
 Adhesive Remover Market | 2026-2036
Adhesive Remover Market Size, Share, and Industry Trends Forecast 2026-2036
Adhesive Remover Market Analysis
Industrial-grade low-VOC specifications are redrawing competitive boundaries in adhesive removers. 3M leverages its materials science heritage to sustain premium positioning in aerospace and electronics cleaning segments. Henkel anchors European supply through its specialty chemicals distribution network. WD-40 Company competes in consumer channels with brand recognition that extends retail shelf presence across North American mass merchants.
Adhesive removers are formulated chemical solutions—typically blends of citrus terpenes, aliphatic hydrocarbons, or soy-based esters designed to dissolve bonding agents without substrate damage—that serve industrial maintenance, vehicle refinishing, and consumer decluttering applications. Solvent-based formulations still dominate volume in heavy industrial cleaning, though gel formats are gaining fastest in automotive applications where vertical surface cling reduces waste and rework. DIY enthusiasts and technicians represent diverging margin pools, with the former driving wipe and spray convenience formats through online retail while the latter sustains higher-margin concentrated supply through wholesale channels.
EPA VOC regulations in the United States, REACH chemical registration requirements in Europe, and state-level air quality rules in California collectively constrain solvent selection and push investment toward bio-based alternatives. OSHA workplace exposure limits further shape industrial product specifications and application protocols. Stakeholders must monitor how tightening chemical hazard classifications in major jurisdictions will redirect R&D spending and reformulation timelines.
Market Dynamics
EPA volatile organic compound regulations are forcing solvent-based adhesive remover manufacturers toward bio-derived ester and terpene formulations, compressing legacy product margins while opening premium positioning for compliant alternatives.
Growth Catalysts
- Automotive refinishing expansion:Collision repair shops in Germany and the United States are specifying professional-grade surface preparation chemicals as OEM aftermarket standards tighten.
- REACH chemical registration:European manufacturers reformulating ahead of hazard classification updates are capturing shelf space from non-compliant imports.
- Citrus terpene extraction scale-up:Brazilian and Florida orange processing waste streams now supply cost-competitive d-limonene feedstock for industrial degreasing blends.
Market Restraints
- Petrochemical feedstock volatility:Aliphatic hydrocarbon prices track naphtha benchmarks, compressing margin stability for solvent-heavy product lines.
- Concentrated supplier geography:Specialty ester production clusters in the Rhine-Ruhr industrial corridor create single-source vulnerability for European formulators.
- Technical performance ceiling:Soy-based alternatives exhibit slower penetration rates on cured epoxy and polyurethane residues versus petroleum solvents.
Strategic Opportunities
- Underpenetrated Indian maintenance sector:BIS certification alignment for industrial cleaning chemicals opens formal sector adoption currently served by unorganized mineral spirit blends.
- EV battery assembly cleaning:Precision residue removal for thermal interface materials in electric vehicle manufacturing represents a specification-driven entry point.
- E-commerce wipe format expansion:Direct-to-technician subscription models bypass traditional wholesale markups in North American independent repair shops.
Industry Challenges
- Reformulation chemist scarcity:Expertise in bio-solvent compatibility with legacy substrate protection standards concentrates among retiring specialists at European specialty chemical firms.
- Cross-jurisdiction labeling complexity:Divergent OSHA hazard communication, CLP classification, and state-level California Proposition 65 warning requirements multiply SKU proliferation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adhesive Remover Market |
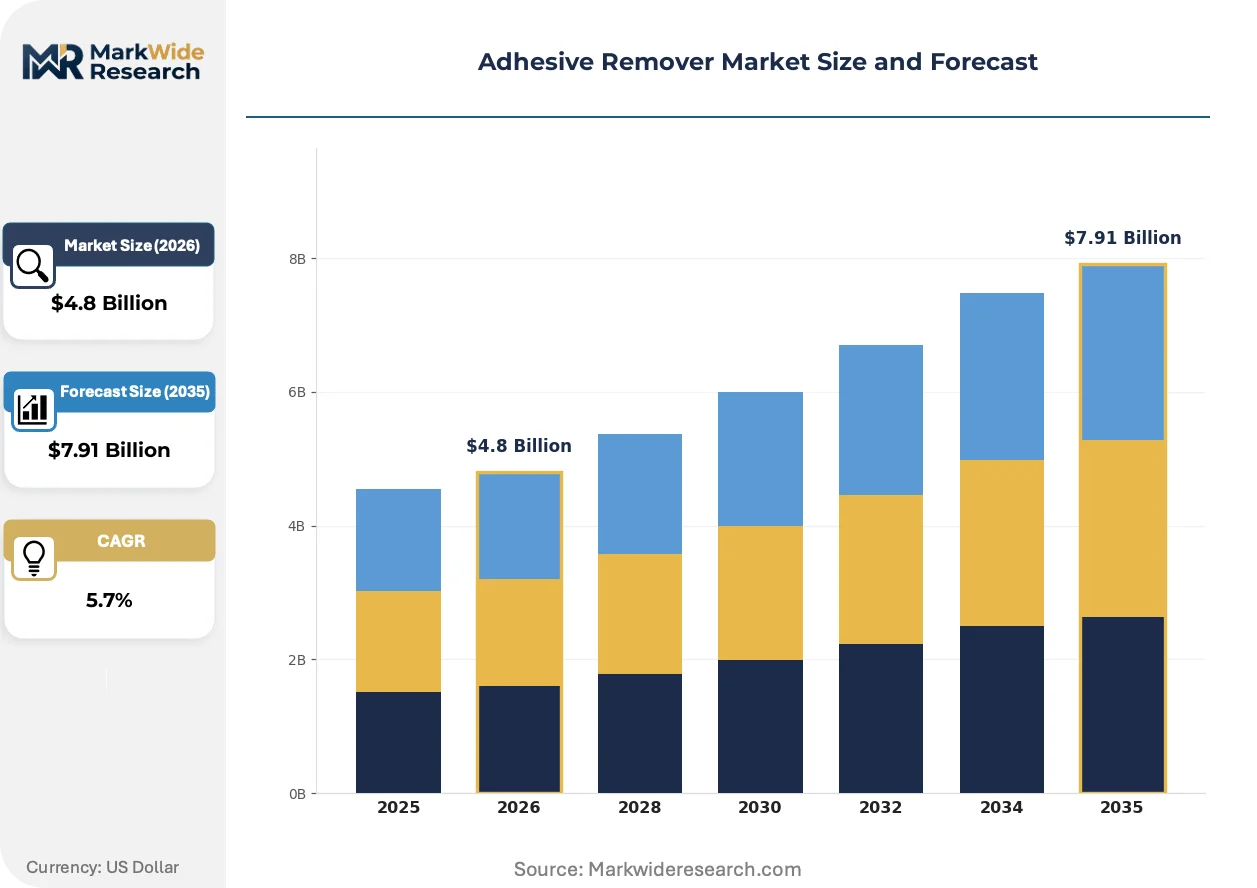
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Gel, Spray, Wipe Application: Industrial Cleaning, Automotive, Home Improvement, Arts & Crafts End User: Manufacturers, Consumers, DIY Enthusiasts, Technicians Distribution Channel: Online Retail, Wholesale, Specialty Stores, Supermarkets |
| Companies Covered | WD-40 Company, Stepan Company, 3M, Diversey, Weiman Products, Henkel, Goo Gone, Klean Strip, CRC Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adhesive Remover Market Emerging Trajectories
Gel-thickened adhesive remover formats are displacing liquid sprays in vertical surface applications, while regulatory pressure on volatile organic compounds accelerates bio-based feedstock integration across industrial and consumer segments.
Water-dispersible citrus terpene microemulsions are bifurcating the automotive refinishing segment. Tier 1 collision repair chains in the United States specify these formulations for EPA compliance. The technology is bifurcating procurement patterns between volume-driven national accounts and cost-focused independent shops.
California Air Resources Board consumer product regulations now mandate maximum reactivity limits for adhesive removers sold through retail channels. Formulators serving mass merchants have condensed product portfolios to CARB-compliant SKUs. Professional automotive channels remain less constrained, preserving solvent performance for certified technician use.
Subscription replenishment models now dominate DIY consumer acquisition through online marketplaces. Mass merchant shelf space for single-unit purchases contracts as direct-to-consumer auto-ship programs capture recurring revenue. This channel rotation is most visible in United States metropolitan markets where same-day delivery infrastructure supports just-in-time restocking.
Adhesive Remover Market Segmentation
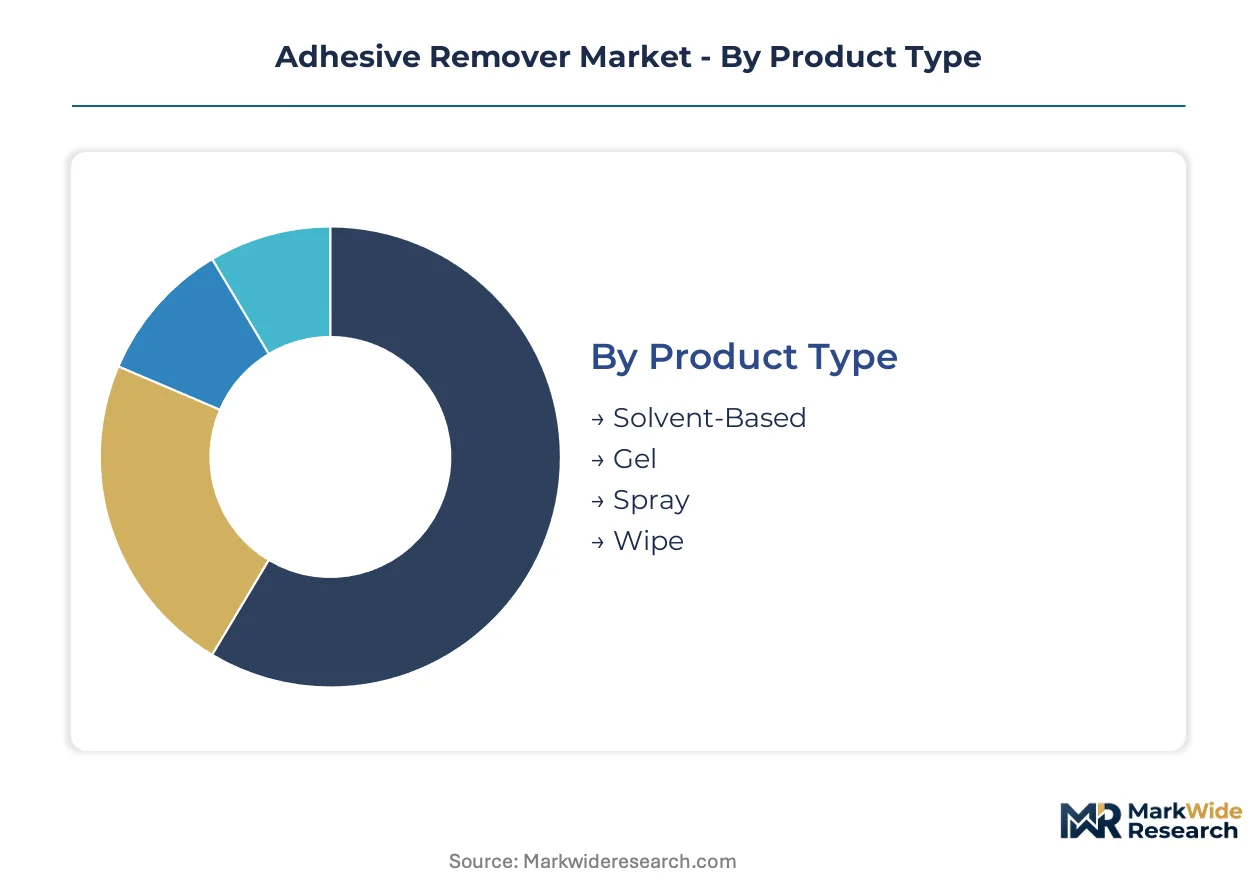
Adhesive remover demand fragments across formulation chemistry, surface application requirements, and procurement channel economics. Segmentation clarity exposes where bio-solvent substitution pressure concentrates versus where petroleum-based performance still commands premium pricing.
Product Type:
Solvent-based formulations face the most acute substitution threat from bio-derived alternatives as EPA VOC limits and REACH hazard classifications tighten across industrial procurement specifications.
- Solvent-Based:Aliphatic hydrocarbon and chlorinated blends deliver fastest penetration on cured epoxy and polyurethane residues. Demand concentrates in German automotive refinishing chains where OEM aftermarket standards still permit solvent performance for certified technician use.
- Gel:Thickened rheology enables vertical surface cling without runoff, cutting material waste in collision repair shops. German and United States automotive refinishing sectors specify gel formats for door panel and pillar work where liquid sprays fail.
- Spray:Aerosol delivery suits broad-area coverage in industrial maintenance settings. OSHA workplace exposure protocols limit spray deployment in confined manufacturing environments.
- Wipe:Pre-saturated substrates target DIY convenience through e-commerce subscription models. CARB reactivity limits constrain formulation options for California retail distribution.
Solvent-based retains volume leadership; gel holds the steepest expansion curve.
Application:
Cost tier stratification separates specification-driven industrial procurement from price-sensitive consumer purchases.
- Industrial Cleaning:Heavy-duty degreasing of manufacturing equipment and tooling demands high-flash-point formulations compliant with OSHA permissible exposure limits. Rhine-Ruhr industrial corridor maintenance contractors specify REACH-registered ester blends for multi-shift operations.
- Automotive:Collision repair surface preparation requires residue-free substrates compatible with OEM refinishing warranties. United States EPA VOC regulations bifurcate procurement between compliant national chains and solvent-dependent independent shops.
- Home Improvement:Flooring and wallpaper removal drives seasonal demand spikes through mass merchant retail. California CARB rules have condensed product portfolios to low-reactivity SKUs in this channel.
- Arts & Crafts:Precision residue removal for delicate materials favors mild citrus terpene formulations. Brazilian d-limonene feedstock cost advantages support margin preservation in this price-sensitive segment.
Industrial cleaning commands highest per-unit pricing; automotive shows the sharpest volume acceleration.
End User:
Customer type determines margin structure and channel access requirements more than formulation chemistry alone.
- Manufacturers:Industrial formulators integrate adhesive removers into production line cleaning protocols with documented SOP compliance. BIS certification requirements in India filter procurement toward organized sector suppliers.
- Consumers:Mass market purchasers prioritize convenience formats and brand recognition over technical specifications. Subscription replenishment models now dominate acquisition in United States metropolitan markets with same-day delivery infrastructure.
- DIY Enthusiasts:Project-focused buyers research substrate compatibility and seek tutorial-validated products through online communities. Wipe and spray formats capture this segment through direct-to-consumer channels.
- Technicians:Certified professionals demand concentrated supply with batch traceability and SDS documentation. Wholesale distribution through jobber networks sustains higher-margin concentrated formats.
Technicians generate premium margin pools; DIY enthusiasts are climbing the fastest in absolute user count.
Distribution Channel:
Channel geography dictates which regulatory frameworks govern product formulation and labeling compliance.
- Online Retail:Direct-to-consumer platforms enable subscription replenishment and bypass traditional wholesale markups. CARB-compliant SKUs dominate listings targeting California addresses.
- Wholesale:Industrial distributors and automotive jobbers supply concentrated formats with technical support. REACH registration documentation gates European market access through this channel.
- Specialty Stores:Paint and body shop suppliers curate professional-grade portfolios with application training. German KBA aftermarket standards influence product selection in automotive-focused outlets.
- Supermarkets:Mass merchant shelf space contracts for single-unit purchases as e-commerce captures recurring revenue. Limited SKU breadth favors wipe formats with broad substrate claims.
Wholesale retains the highest value throughput; online retail is expanding most quickly in transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in adhesive removers favor manufacturing economies with feedstock access and regulatory clarity. Germany and the United States run structural deficits in bio-solvent formulations, sourcing d-limonene from Brazilian and Florida processing clusters. Asian production hubs capture growing intra-regional trade as BIS certification requirements reshape Indian procurement patterns.
United States
Collision repair chains and DIY subscription models drive divergent demand patterns. EPA VOC regulations and California CARB reactivity limits constrain solvent selection for retail channels. Houston and Detroit automotive clusters sustain wholesale demand for concentrated industrial formats with documented SDS compliance.
Germany
KBA aftermarket standards and OEM refinishing warranties enforce premium product specifications in automotive applications. REACH chemical registration requirements filter non-compliant imports from Eastern European suppliers. The Rhine-Ruhr corridor concentrates specialty ester production for multi-shift industrial maintenance contracts.
Brazil
Orange processing waste streams supply cost-competitive d-limonene feedstock for global terpene markets. ANVISA chemical registration procedures lag REACH complexity, preserving formulation flexibility for export-oriented producers. São Paulo state industrial zones blend citrus derivatives for regional degreasing applications.
India
BIS certification alignment opens formal sector procurement currently served by unorganized mineral spirit blends. Central Pollution Control Board air quality directives push refinishing shops toward compliant surface preparation chemicals. Maharashtra and Gujarat manufacturing belts specify REACH-registered imports for precision electronics cleaning.
China
Dual carbon goals and MEE emissions standards accelerate bio-solvent R&D investment in state-owned chemical complexes. Yangtze River Delta electronics manufacturers demand residue-free substrates for semiconductor packaging operations. Guangdong province automotive suppliers integrate adhesive removers into EV battery assembly protocols.
Adhesive Remover Market Vendor Landscape
Listed leaders compete with private specialists across formulation chemistry and channel access dimensions. The vendor base splits between diversified chemical conglomerates with materials science heritage and focused players with single-category depth. Three archetypes dominate: integrated specialty chemical houses with global distribution networks, brand-recognition consumer goods firms with mass retail penetration, and regional formulators with regulatory compliance expertise. Capacity expansion in Brazilian terpene extraction and strategic partnerships for REACH-registered supply dominate competitive maneuvering.
Within the diversified chemical tier, 3M and Henkel occupy positions anchored by materials science capabilities and European distribution infrastructure. WD-40 Company exemplifies brand-driven consumer channel penetration with recognition extending across North American mass merchant retail. Stepan Company represents specialty surfactant and ester chemistry expertise serving industrial formulators with compliant feedstock alternatives.
| Leading Market Players |
|---|
| WD-40 Company |
| Stepan Company |
| 3M |
| Diversey |
| Weiman Products |
| Henkel |
| Goo Gone |
| Klean Strip |
| CRC Industries |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day d-limonene inventory cycles in Brazilian processing facilities concentrate pricing power among Florida and São Paulo terpene extractors, while REACH registration costs in Europe compress margins for non-integrated formulators sourcing from single-corridor ester producers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the adhesive remover market. Price differentiation rests on certification grade—REACH-registered formulations command premiums against non-compliant imports—and volume scale through national collision repair chain contracts. Cost compression in solvent-based tiers is intensifying because Brazilian d-limonene feedstock availability fluctuates with orange harvest cycles. DIY consumers through e-commerce channels exhibit highest price sensitivity, while German automotive OEM aftermarket specifications sustain least-sensitive procurement.
Supply Chain Analysis
Port congestion on Asia-Europe container lanes elevates inbound logistics costs for specialty ester imports into the Rhine-Ruhr corridor. Geographic supply concentrates in Brazil for citrus terpene feedstock, Germany for REACH-registered ester production, and the United States for formulated consumer packaged goods. Raw material dependencies include d-limonene from orange processing waste, aliphatic hydrocarbons from naphtha cracking, and soy-based methyl esters from Midwest agricultural processing. Single-source vulnerability pervades European specialty ester supply. Distribution runs through wholesale jobber networks for technician-grade concentrates and direct-to-consumer platforms for wipe-format replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription replenishment platforms are consolidating technician and DIY buyer relationships into captive ecosystems, with interoperability between inventory management systems and e-commerce auto-ship protocols emerging as the decisive competitive moat.
For Market Incumbents: Fortify backward integration into Brazilian terpene extraction to secure d-limonene supply against harvest volatility. Deepen REACH registration portfolios ahead of hazard classification updates to filter import competition. Channel control through exclusive wholesale jobber relationships in German automotive refinishing clusters defends margin pools against direct-to-consumer entrants.
For New Entrants and Emerging Players: BIS certification fast-track for industrial cleaning chemicals opens formal sector procurement in Indian manufacturing belts currently served by unorganized mineral spirit blends. White-space targets include precision residue removal for EV battery thermal interface materials and subscription wipe formats for North American independent repair shops. Go-to-market leverage runs through direct-to-technician digital platforms bypassing traditional wholesale markups.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because tightening EPA VOC limits and REACH hazard classifications concentrate value in registered formulation expertise. Acquisition targets center on mid-cap European specialty chemical houses with retiring reformulation chemists and documented substrate compatibility libraries. The signal to watch is CARB reactivity rule expansion beyond consumer channels into professional automotive specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Terpene Extraction | Captive d-limonene supply from Brazilian orange processing waste secures feedstock cost stability against harvest volatility. |
| REACH Registration Portfolio Expansion | Documented hazard classifications filter non-compliant Eastern European imports from German automotive aftermarket channels. |
| Gel Format Capacity Addition | Thickened rheology production lines serve German and United States collision repair demand for vertical surface applications. |
| Direct-to-Technician Platform Launch | Subscription auto-ship models bypass wholesale markups in North American independent repair shop procurement. |
| BIS Certification Alignment | Formal sector qualification opens Indian industrial maintenance contracts currently captured by unorganized mineral spirit suppliers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the adhesive remover value chain, including collision repair shop owners, industrial maintenance contractors, specialty chemical procurement managers, Brazilian terpene extraction facility operators, and REACH compliance officers at European formulators. Secondary validation drew from EPA VOC regulation filings, ECHA REACH registration databases, Brazilian orange processing industry reports, and customs trade data on d-limonene and ester chemical flows. Bottom-up segment sizing triangulated against top-down market envelope estimates from chemical industry associations.
Across the analysis window, volume and value outputs reflect segmentation modeling by formulation chemistry, application surface requirements, procurement channel economics, and end-user certification tier. CAGRs were derived from elasticity-adjusted demand projections incorporating feedstock cost trajectories and regulatory phase-in schedules. Industry-specific forecast inputs included Brazilian orange harvest yield correlations with d-limonene pricing and German KBA aftermarket standard revision timelines.
The analysis sits within stated boundaries; outcomes outside sustained EPA and CARB regulatory enforcement, stable Brazilian agricultural output, and continued German OEM aftermarket specification tightening would require recalibration. Forecasts reflect documented assumptions on substitution rates between solvent and bio-based formulations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Fabric Conditioner Market
Cleaning Chemicals
Descaler Market
Cleaning Chemicals
Electrostatic Liquid Cleaner Market
Cleaning Chemicals
Rust Remover Market
Cleaning Chemicals
Sponge and Scouring Pads Market
Cleaning Chemicals
Dust and Emission Control Chemicals for Ore Handling Market
Cleaning Chemicals
Mask Reticle Cleaning Agent Market
Cleaning Chemicals
Southeast Asia Surface Treatment Chemicals Market
Cleaning Chemicals
US Specialty Cleaners Market
Cleaning Chemicals
Efflorescence Remover Market
Cleaning Chemicals
North America Surface Treatment Chemicals Market
Cleaning Chemicals
Industrial Cleaners Market
Cleaning Chemicals
Green Floor Care Chemical Systems for Commercial Facilities Market
Cleaning Chemicals
Chemical Dust Suppressants Market
Cleaning Chemicals
Cleaning Products Market
Cleaning Chemicals
Chlorhexidine Gluconate (CHG) Cloth Market