
 Cleaning Products Market | 2026-2036
Cleaning Products Market Size, Share, and Industry Trends Forecast 2026-2036
Cleaning Products Market Analysis
Janitorial labor shortages across commercial facilities is redrawing distribution priorities for bulk-format concentrates. Procter & Gamble Company leverages its captive supply of surfactant precursors to stabilize input costs. Unilever Plc anchors European shelf presence through refill-station partnerships with supermarket chains. Henkel AG & Company KGaA specializes in enzyme-based formulations that reduce hot-water requirements for industrial laundries.
Cleaning products encompass formulated chemical solutions containing surfactants, builders, solvents, and antimicrobial agents designed to remove soil, grease, and pathogens from surfaces, textiles, and equipment. Manufacturing employs batch processing with controlled pH adjustment and viscosity modification to achieve target performance specifications for specific soil types and application temperatures. Surface cleaners and disinfectants concentrate margin pools in healthcare and food-service channels where efficacy certification commands premium positioning. Laundry detergents in concentrated and eco-friendly formulations are expanding fastest as household buyers trade volume for dosage efficiency and reduced packaging waste.
EPA Safer Choice labeling and EU REACH chemical restrictions are forcing reformulation away from quaternary ammonium compounds and synthetic fragrances in consumer-facing products. FDA oversight of sanitizers used in food-contact applications and OSHA hazard communication standards for industrial cleaners shape compliance costs and liability exposure for manufacturers. Stakeholders must monitor how state-level ingredient disclosure laws in California and New York diverge from federal minimums.
Market Dynamics
Janitorial labor shortages across commercial facilities are forcing distributors to prioritize bulk-format concentrates and automated dispensing systems over ready-to-use packaged goods.
Growth Catalysts
- EPA Safer Choice certification:Formulators achieving this label gain preferred vendor status with healthcare procurement departments in the United States, locking in multi-year supply agreements.
- Enzyme-based cold-water formulations:Industrial laundries in Germany are retrofitting equipment to reduce energy costs, creating pull-through demand for specialized detergents.
- Private-label manufacturing clusters:Concentrated production around Düsseldorf and Rotterdam enables cross-border EU distribution with shortened lead times.
Market Restraints
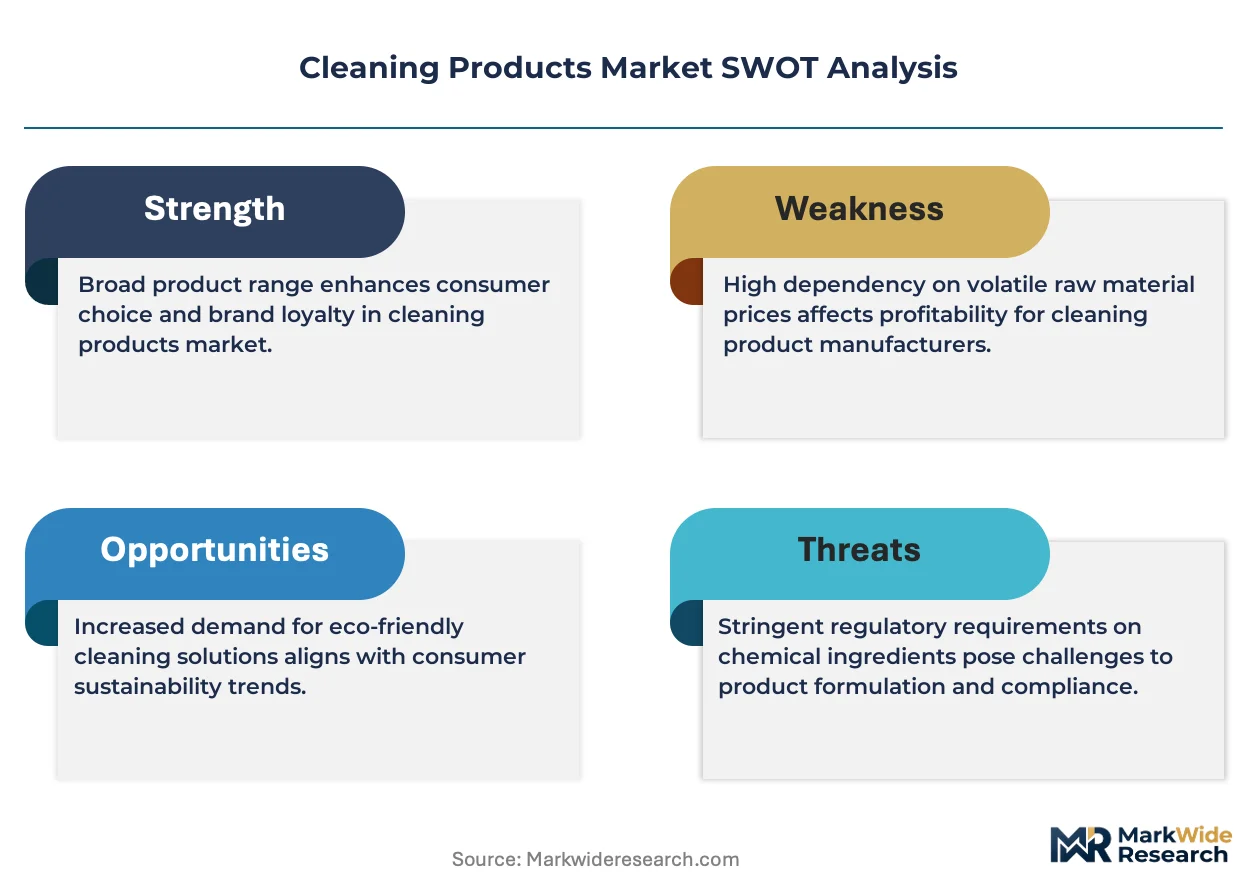
- Palm kernel oil and coconut fatty acid volatility:Surfactant precursor costs swing with Southeast Asian harvest cycles, compressing margin predictability for mid-tier producers.
- Quaternary ammonium compound restrictions:EU REACH limitations on QAC biocides force reformulation of legacy disinfectant lines at substantial R&D expense.
- Concentrated production geography:Overreliance on Rhine-Ruhr chemical corridors creates single-point vulnerability for EU supply continuity.
Strategic Opportunities
- Refill-station retail networks:Supermarket chains in France and Benelux are expanding in-aisle dispensing infrastructure, cutting packaging waste and transportation costs simultaneously.
- Food-contact sanitizer certification:FDA compliance for no-rinse formulations opens institutional kitchen contracts previously held by commodity bleach suppliers.
- Industrial Internet of Things integration:Sensor-enabled dilution control systems in facility management are creating attach-rate opportunities for smart-concentrate cartridges.
Industry Challenges
- Formulation chemist scarcity:Expertise in green-chemistry substitution for phosphates and synthetic fragrances commands premium compensation, constraining mid-cap R&D throughput.
- Multi-jurisdiction disclosure compliance:Divergent ingredient reporting requirements between California SB-258 and New York cleaning product laws force parallel labeling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cleaning Products Market |
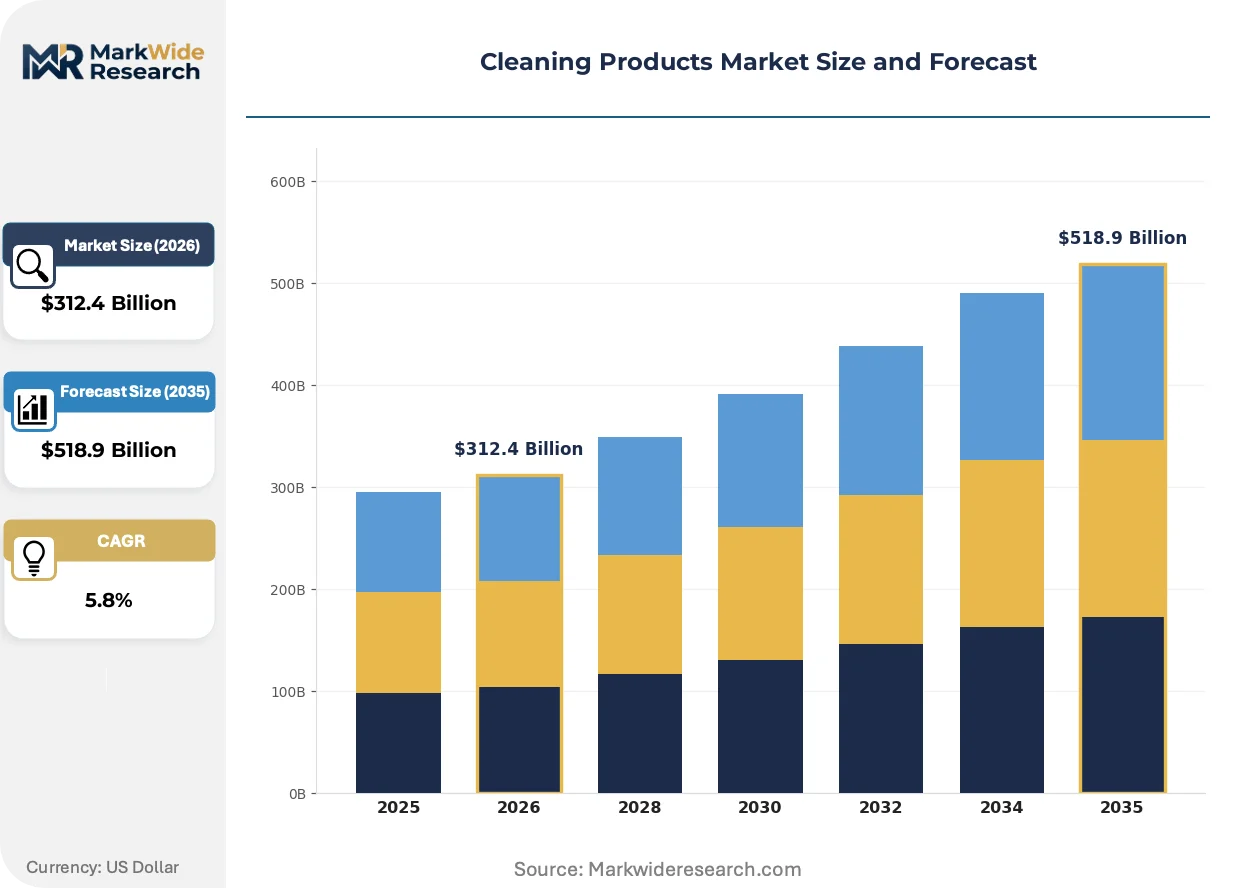
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $518.9 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Cleaners, Laundry Detergents, Dishwashing Liquids, Disinfectants End User: Households, Commercial Facilities, Industrial Sectors, Institutional Settings Formulation Type: Organic, Conventional, Concentrated, Eco-friendly Packaging Type: Bottles, Refill Packs, Tubs, Pouches |
| Companies Covered | Procter & Gamble Company, Unilever Plc, Reckitt Benckiser Group Plc, Henkel AG & Company KGaA, The Clorox Company, S.C. Johnson & Son Inc., Church & Dwight Co. Inc., Colgate-Palmolive Company, Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cleaning Products Market Emerging Trajectories
Active chemistry substitution and dispensing automation are compressing traditional product-form boundaries, while regulatory disclosure mandates reshape competitive transparency.
Enzyme-based cleaning chemistry is bifurcating the industrial laundry segment. Protease and lipase formulations enable effective soil removal below 40°C, cutting thermal energy consumption by facilities operators. Hospitality chains with centralized linen processing are adopting fastest, while smaller commercial laundries face equipment retrofit barriers that concentrate share among capitalized operators.
REACH authorization procedures for biocidal active substances are extending product-registration timelines. ECHA's systematic review of quaternary ammonium compounds and fragrance allergens forces early-phase reformulation investments. Consumer-facing surface cleaners face the steepest compliance burden, driving portfolio simplification toward core SKUs with proven substance dossiers.
Bulk concentrate procurement with metered dispensing is displacing case-good purchasing in commercial channels. Facility management contractors are unbundling chemical supply from equipment service, selecting vendors on cost-per-use metrics rather than unit price. Germany and the Netherlands show the most advanced adoption, where integrated facility services contracts specify dilution-control hardware as standard.
Cleaning Products Market Segmentation
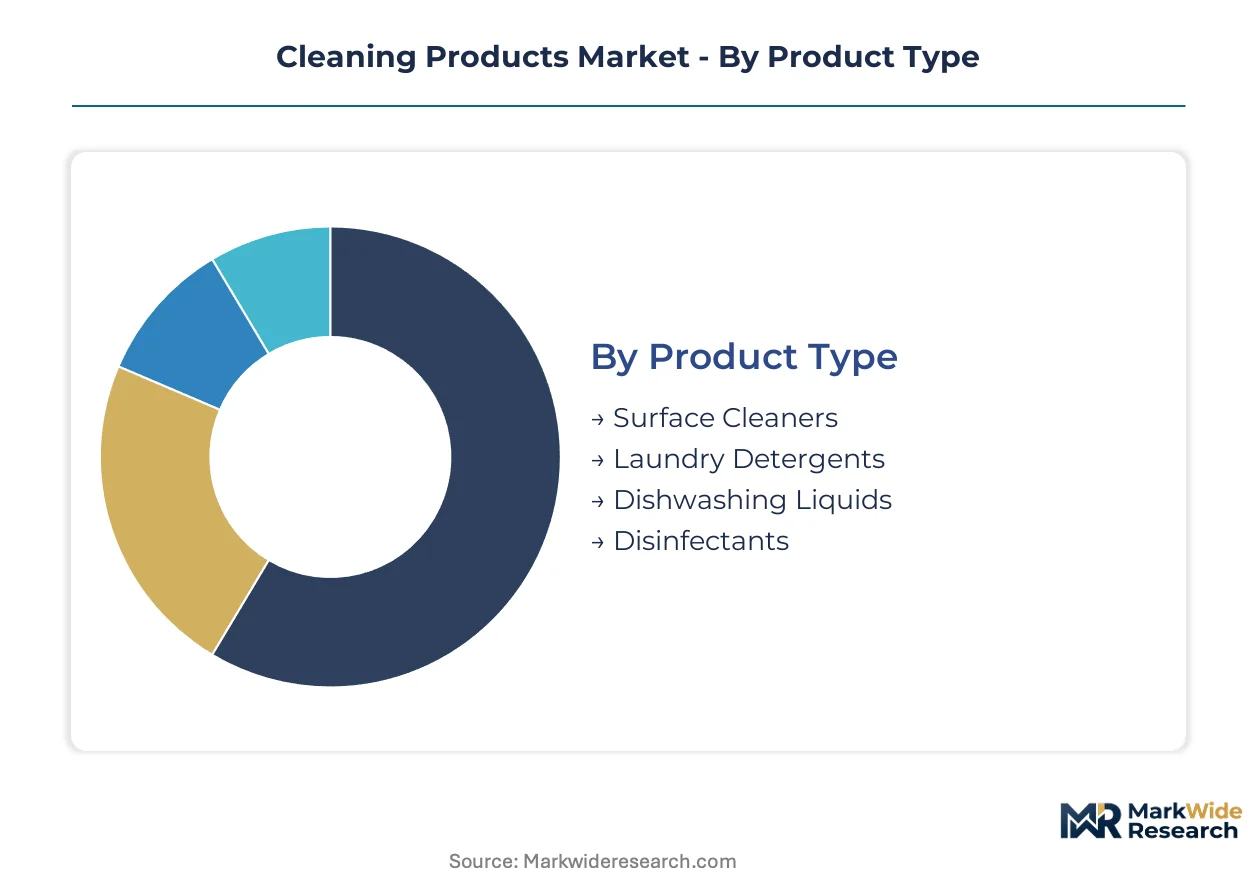
Cleaning products manufacturers configure production lines and pricing architectures around distinct segment boundaries. Product chemistry, packaging format, and end-user compliance requirements each create separate margin profiles that dictate competitive positioning.
Product Type:
Margin pools concentrate in disinfectants and surface cleaners where efficacy certification commands premium positioning, while laundry detergents compete on volume efficiency.
- Surface Cleaners:Formulated with surfactant-builder combinations for soil suspension on hard surfaces. Demand concentrates in healthcare and food-service channels across Germany and the Netherlands where EPA Safer Choice and EU REACH compliance filter vendor pools.
- Laundry Detergents:Enzyme-based and concentrated chemistries reducing water temperature requirements. Hospitality chains in France and Belgium are retrofitting equipment for cold-water processing, pulling specialized formulations from Düsseldorf manufacturing clusters.
- Dishwashing Liquids:Manual and automatic formulations with foam control and rinse-aid compatibility.
- Disinfectants:Quaternary ammonium and alternative biocide systems requiring registration dossiers.
The dominant share belongs to laundry detergents, while disinfectants are closing the gap fastest on institutional procurement premiums.
End User:
Procurement scale and compliance burden separate institutional buyers from household purchasers.
- Households:Individual consumers selecting on unit price, fragrance preference, and shelf visibility. German supermarket refill-station networks and French hypermarket private-label programs are capturing dosage-conscious buyers.
- Commercial Facilities:Facility management contractors with cost-per-use metrics and automated dispensing requirements. Janitorial labor shortages across Netherlands office complexes are accelerating bulk concentrate adoption.
- Industrial Sectors:Heavy soil removal with specialized equipment compatibility.
- Institutional Settings:Hospitals, schools, and government facilities with mandatory disclosure compliance.
Commercial facilities command the highest per-liter margins, though institutional settings are expanding procurement fastest on multi-year supply agreements.
Formulation Type:
Regulatory pressure on active chemistry is fragmenting the conventional segment while concentrating investment in certified alternatives.
- Organic:Plant-derived surfactants and bio-based solvents with third-party certification. Benelux retail chains are slotting organic SKUs adjacent to refill stations, capturing sustainability-motivated household spend.
- Conventional:Petrochemical surfactants and synthetic fragrances facing REACH authorization delays. ECHA review of quaternary ammonium compounds is forcing reformulation timelines that disadvantage legacy product lines.
- Concentrated:Reduced water content with precise dilution protocols.
- Eco-friendly:Phosphate-free and biodegradable claim substantiation.
Conventional formulations retain volume leadership, yet concentrated formats are gaining share fastest on transportation cost reduction.
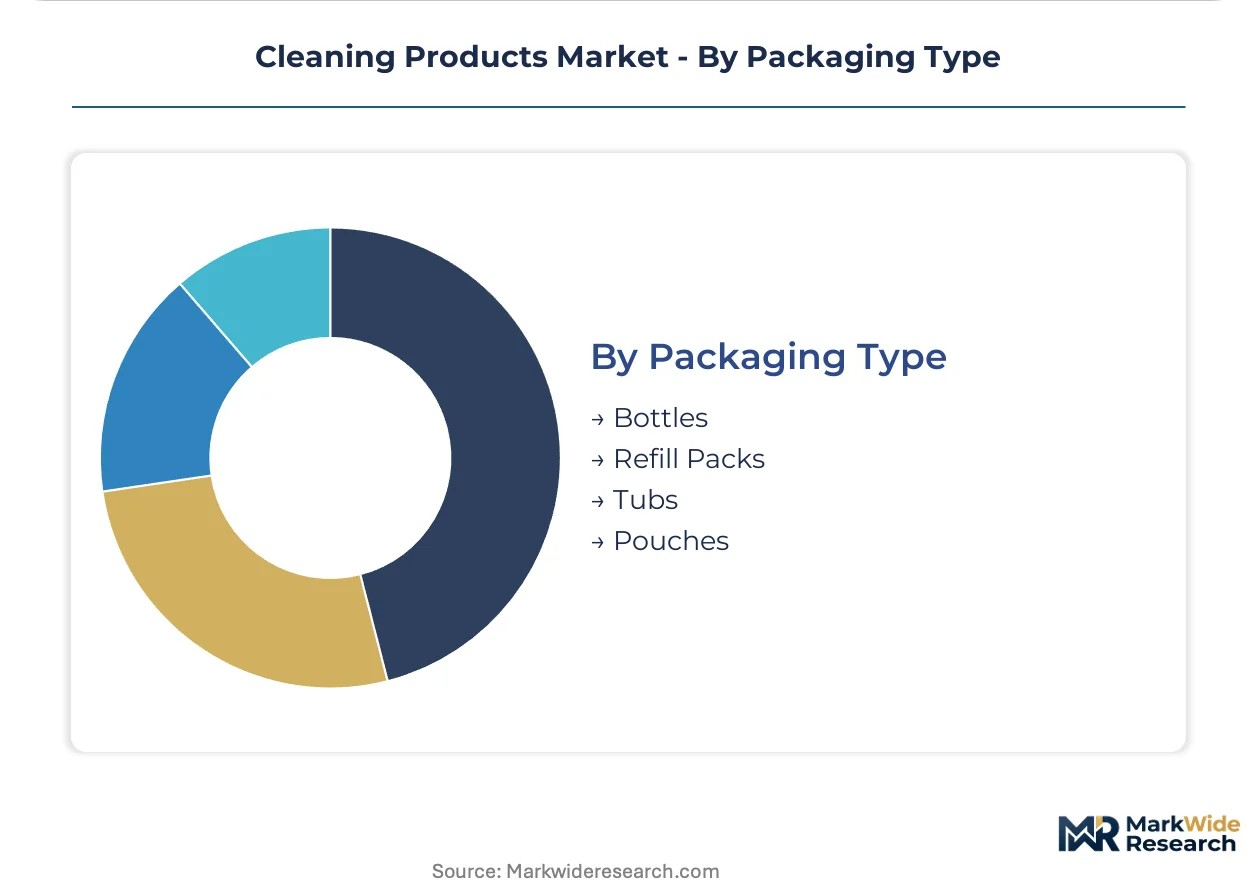
Packaging Type:
Packaging cost structure and reverse logistics requirements determine distribution channel fit.
- Bottles:Standard HDPE and PET containers with trigger-spray or flip-cap closures. German retail maintains bottle dominance for household surface cleaners, though refill-station infrastructure is eroding single-use case volumes.
- Refill Packs:Flexible film reducing per-dose material weight. French supermarket chains are installing in-aisle dispensing systems that bypass primary packaging entirely.
- Tubs:Rigid containers for powder detergents and pastes.
- Pouches:Stand-up flexible packaging for liquid concentrates.
Bottles still anchor household channel revenue, while refill packs are climbing the fastest on commercial facility procurement shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Safer Choice certification anchors procurement decisions in the United States, while EU REACH chemical restrictions reshape formulation standards across Germany, France, and the Netherlands. Private-label manufacturing clusters in the Rhine-Ruhr corridor and Rotterdam port zones concentrate supply capacity for cross-border distribution.
United States
Healthcare procurement departments favor EPA Safer Choice-certified vendors for multi-year supply agreements. FDA oversight of food-contact sanitizers and OSHA hazard communication standards elevate compliance costs for institutional channel entrants. Chicago and Atlanta distribution hubs prioritize bulk concentrate formats addressing janitorial labor shortages in commercial facilities.
Germany
Industrial laundries in North Rhine-Westphalia retrofit equipment for enzyme-based cold-water processing below 40°C. ECHA's systematic review of quaternary ammonium compounds forces early-phase reformulation investments. Düsseldorf manufacturing clusters serve cross-border EU distribution with shortened lead times for concentrated detergents.
France
Supermarket chains in Île-de-France and Provence-Alpes-Côte d'Azur expand in-aisle refill-station infrastructure cutting packaging waste. ANSM monitoring of fragrance allergens influences consumer-facing surface cleaner portfolios. Lyon-based facility management contractors specify automated dilution-control hardware in integrated service contracts.
Netherlands
Rotterdam port zones anchor private-label production for Benelux retail chains slotting organic SKUs adjacent to refill stations. Dutch office complexes accelerate bulk concentrate adoption amid acute janitorial labor shortages. Eindhoven Region chemical processors supply surfactant precursors to mid-tier formulators.
United Kingdom
London procurement offices enforce cost-per-use metrics unbundling chemical supply from equipment service contracts. UK REACH divergence from EU chemical restrictions creates parallel substance dossier requirements. Midlands distribution centers stock concentrated formats for hospitality chains with centralized linen processing.
Cleaning Products Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational consumer goods conglomerates commanding premium shelf space through captive surfactant supply and refill-station partnerships. The mid-cap specialist tier concentrates around enzyme-based formulation expertise and regional private-label manufacturing. Three archetypes dominate: vertically integrated surfactant producers, enzyme-technology specialists, and private-label contract manufacturers. Competitive moves center on backward integration into surfactant precursors and strategic partnerships with supermarket chains for refill infrastructure.
Among US-based conglomerates, Procter & Gamble Company exemplifies the integrated-leader archetype through captive supply chain control. Unilever Plc represents the European partnership model anchoring shelf presence through retail collaboration. Henkel AG & Company KGaA occupies the specialist position with enzyme-based industrial laundry expertise. These three names illustrate how scale, partnership, and technology specialization segment competitive positioning.
| Leading Market Players |
|---|
| Procter & Gamble Company |
| Unilever Plc |
| Reckitt Benckiser Group Plc |
| Henkel AG & Company KGaA |
| The Clorox Company |
| S.C. Johnson & Son Inc. |
| Church & Dwight Co. Inc. |
| Colgate-Palmolive Company |
| Kao Corporation |
| Others |
Supply Flow & Price Mechanics
Enzyme-based surfactant substitution for petroleum-derived quaternary ammonium compounds is redrawing procurement geography toward Southeast Asian oleochemical processors while compressing margin pools for legacy formulators locked into long-term supply contracts.
Pricing Analysis
Long-term offtake agreements with surfactant precursor suppliers anchor pricing stability for integrated leaders, while spot-market exposure punishes mid-tier competitors during palm kernel oil harvest volatility. Three-tier pricing structure across EPA Safer Choice-certified premium, REACH-compliant standard, and private-label economy levels separates healthcare procurement premiums from household unit-price competition. Cost compression in the conventional segment intensifies as ECHA authorization delays strand legacy biocide inventories. Institutional buyers with multi-year contracts exhibit lowest price sensitivity, while German supermarket chains driving refill-station adoption force dosage-efficiency negotiations.
Supply Chain Analysis
Rhine-Ruhr chemical corridor concentration creates single-point vulnerability for EU distribution, with Rotterdam port congestion and Düsseldorf manufacturing cluster dependencies amplifying lead-time risk. Malaysia, Indonesia, and the Philippines supply coconut fatty acid and palm kernel oil feedstocks that surfactant producers in Germany and the Netherlands process into finished chemistries. Tariff exposure on Southeast Asian oleochemical imports threatens margin predictability for non-integrated formulators. Distribution runs through integrated facility services contractors unbundling chemical supply from equipment maintenance, with bulk concentrate metering systems displacing case-good logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Safer Choice certification and EU REACH biocide restrictions constitute a dual regulatory inflection that will consolidate vendor pools and reward early reformulation investment across institutional procurement channels.
For Market Incumbents: Shield margin position by securing captive supply of surfactant precursors through backward integration into Southeast Asian oleochemical processing, while accelerating EPA Safer Choice dossier submissions to lock in healthcare procurement contracts before ECHA quaternary ammonium compound restrictions fully phase in. For New Entrants and Emerging Players: Anchor in French and Benelux refill-station retail networks where supermarket chains seek private-label partners for in-aisle dispensing infrastructure, targeting sustainability-motivated household segments with organic-certified SKUs priced at modest premiums to conventional alternatives. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed enzyme-technology specialists in Germany's Düsseldorf manufacturing corridor that lack capital to scale cold-water formulation capacity for hospitality chain retrofit demand. Monitor ECHA authorization timelines for quaternary ammonium compounds as the inflection signal for portfolio rationalization among legacy disinfectant producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemical Supply | Captive surfactant precursor access insulates margin from Malaysian palm kernel oil harvest volatility. |
| EPA Safer Choice Certification Investment | Preferred vendor status with US healthcare procurement departments locks multi-year supply agreements. |
| Refill-Station Retail Partnership | French supermarket chain collaborations cut packaging waste while capturing sustainability-premium household spend. |
| Enzyme-Based Cold-Water Formulation R&D | Industrial laundry equipment retrofits in Germany pull specialized detergents reducing thermal energy consumption. |
| Automated Dispensing System Integration | Sensor-enabled dilution control in Dutch facility management contracts creates attach-rate for smart-concentrate cartridges. |
Methodological Framework
Initial hypotheses were tested against primary input from plant managers at Düsseldorf manufacturing clusters, procurement leads at German hospitality chains, distribution channel partners in Rotterdam port zones, and technical R&D directors specializing in enzyme formulation. Secondary validation drew from ECHA substance dossiers, EPA Safer Choice certified product listings, customs trade data on Southeast Asian oleochemical imports, and SEC 10-K filings of integrated surfactant producers. Bottom-up volume modeling across formulation types and end-user segments was cross-checked against top-down macroeconomic indicators.
Variance decomposition across product chemistry, packaging format, and geographic regulatory clusters shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory analysis weighted by procurement pattern shifts in institutional versus household channels. Modeled inputs included ECHA authorization timeline scenarios for quaternary ammonium compounds and hospitality chain equipment retrofit adoption curves for cold-water processing.
Decision-makers should treat outputs as directional under assumptions of stable REACH enforcement intensity and continued janitorial labor shortage conditions; material deviation in regulatory stringency or automation adoption rates would warrant model refresh. Practitioners should keep alternative scenarios live as palm kernel oil price volatility and refill-station retail network expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Low-Residue Glass and Stainless-Steel Maintenance Chemicals Market
Cleaning Chemicals
Industrial Cleaning Chemicals Market
Cleaning Chemicals
Air Duct Cleaning Chemicals Market
Cleaning Chemicals
Global Dust Suppression and Control Chemicals Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market
Cleaning Chemicals
Commercial Deodorizers Market
Cleaning Chemicals
Rust Remover Market
Cleaning Chemicals
Cleanroom Consumables Market
Cleaning Chemicals
Purging Compound Market
Cleaning Chemicals
Water Soluble Detergent Pods Market
Cleaning Chemicals
Multifunctional Cleaner Market
Cleaning Chemicals
Floor Wax Market
Cleaning Chemicals
Limestone Cleaner Market
Cleaning Chemicals
Housekeeping Chemicals for Hotels and Resorts Market
Cleaning Chemicals
Europe Mastic Remover Market
Cleaning Chemicals
Pipeline Chemical Cleaners Market