
 Cleaning Chemicals Market | 2026-2036
Cleaning Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Cleaning Chemicals Market Analysis
Healthcare facility procurement is pivoting toward sporicidal and virucidal chemistries as post-pandemic sanitation protocols harden into permanent standards. Ecolab Inc. leverages its institutional service model to embed cleaning protocols directly into hospital operations. Diversey Holdings Ltd. anchors its position through specialized infection prevention bundles for long-term care facilities. Stepan Company differentiates via backward integration into surfactant manufacturing, securing feedstock flexibility for quaternary ammonium compounds.
Cleaning chemicals encompass formulated blends of surfactants, solvents, chelating agents, and active biocides engineered to remove soil, destroy pathogens, or dissolve organic deposits from surfaces and equipment. Industrial degreasers typically operate at pH ranges of 11-13 and incorporate alkaline builders such as sodium hydroxide or potassium silicate to saponify fatty soils in food processing and metal fabrication environments. Surface cleaners maintain the largest revenue pool within product type segmentation due to their universal deployment across residential, commercial, and institutional channels. Disinfectants command premium pricing and faster volume expansion as healthcare and foodservice buyers upgrade to hospital-grade and food-contact-sanitizer chemistries. Liquid formulations dominate formulation type segmentation through ease of dilution control and compatibility with automated dispensing systems, though concentrated powder formats gain traction in industrial laundries seeking reduced shipping mass.
EPA registration requirements under FIFRA govern antimicrobial claims and efficacy testing for products sold in the United States, while REACH and the EU Biocidal Products Regulation mandate exhaustive substance authorization and hazard communication across European markets. OSHA Hazard Communication Standards and GHS-aligned labeling obligations further constrain product composition and worker safety protocols in industrial applications. Stakeholders must monitor pending restrictions on per- and polyfluoroalkyl substances and quaternary ammonium compounds, as these chemistries face simultaneous regulatory pressure in multiple jurisdictions.
Market Dynamics
The cleaning chemicals sector confronts simultaneous pressure from EPA and REACH mandates restricting legacy biocides while healthcare buyers escalate efficacy requirements for sporicidal formulations.
Growth Catalysts
- EPA Safer Choice certification:Federal procurement preferences for labeled products accelerate reformulation investments by institutional suppliers seeking hospital and school contracts.
- Healthcare sanitation protocols:Permanent post-pandemic infection control standards in long-term care and ambulatory surgical centers sustain elevated disinfectant consumption.
- Concentrated powder formats:Industrial laundries adopt reduced-mass shipping to cut freight costs and warehouse footprint.
Market Restraints
- Feedstock volatility:Petrochemical-derived surfactants and solvents expose margins to crude oil and natural gas price swings.
- Authorization bottlenecks:EU Biocidal Products Regulation active-substance approval timelines extend 3-5 years, freezing product launches.
- Per- and polyfluoroalkyl substance restrictions:Pending state-level bans in the US and proposed REACH amendments threaten fluorosurfactant-dependent formulations.
Strategic Opportunities
- India healthcare infrastructure:Hospital accreditation mandates under NABH standards create demand for imported hospital-grade chemistries.
- Electrolyzed water systems:On-site generation technology converges with IoT dispensing to displace shipped concentrates in food processing.
- Green public procurement:EU Green Deal circular-economy criteria direct municipal spending toward bio-based and readily biodegradable alternatives.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in green surfactant synthesis and regulatory dossier preparation concentrates among retiring cohorts.
- Legacy dispensing infrastructure:Automated dilution systems in institutional kitchens and laundries require retrofitting for low-foam, high-concentration chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cleaning Chemicals Market |
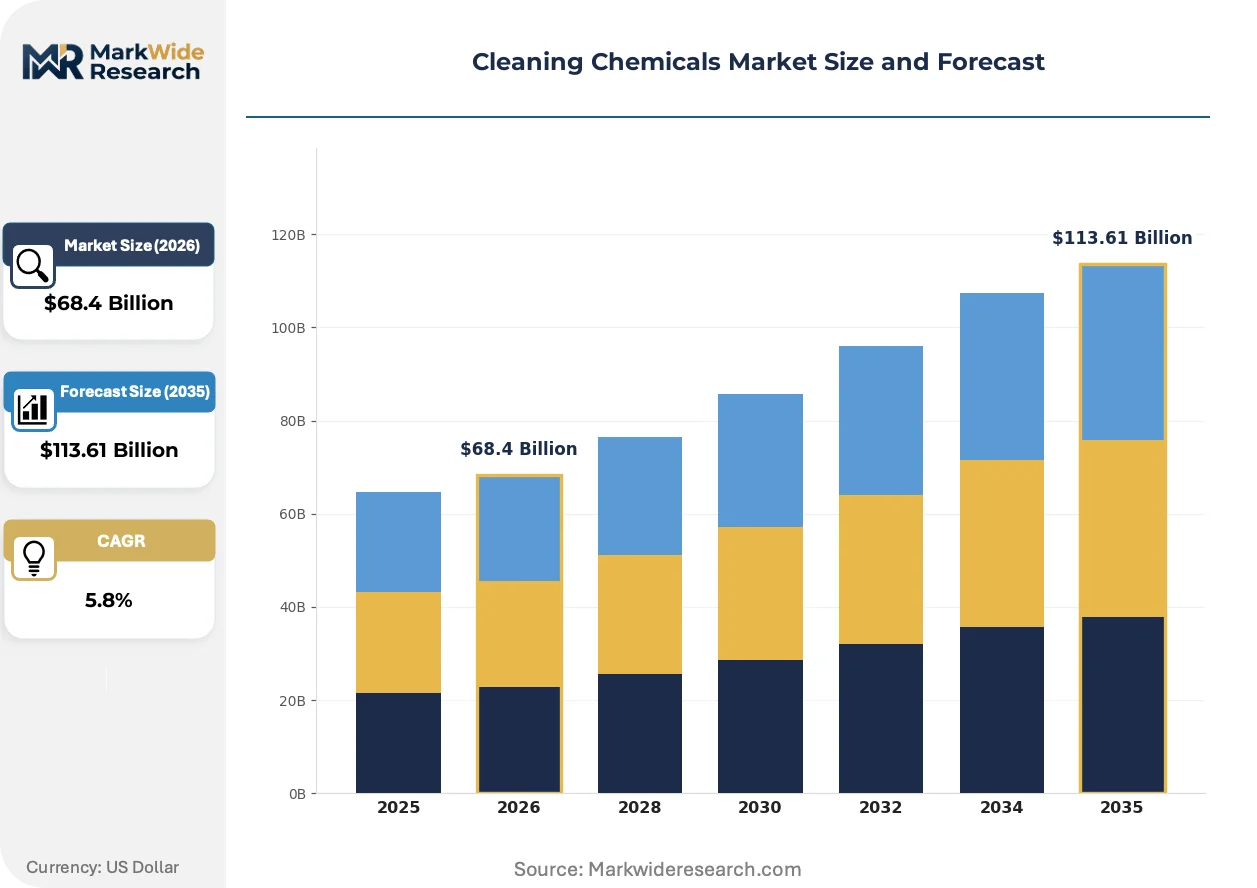
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Cleaners, Disinfectants, Degreasers, Stain Removers End User: Residential, Commercial, Industrial, Healthcare Formulation Type: Liquid, Powder, Gel, Spray Application Area: Kitchens, Bathrooms, Floors, Windows |
| Companies Covered | Ecolab Inc., BASF SE, Dow Inc., Diversey Holdings Ltd., Clariant AG, Procter & Gamble, Zep Inc., Solenis LLC, Stepan Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cleaning Chemicals Market Emerging Trajectories
Formulation science is pivoting toward bio-derived feedstocks and on-site generation systems that compress supply chains and alter competitive economics.
Electrolyzed water technology is decentralizing chemical supply for food processors and healthcare facilities. Sodium hypochlorite and hypochlorous acid generated on-demand from salt, water, and electricity eliminate drum handling, storage, and disposal costs. Large institutional buyers in Germany and Japan are piloting integrated generator-dispenser systems that replace weekly concentrate deliveries with tap-water inputs.
REACH authorization timelines are compressing the viable active-ingredient palette for European disinfectant manufacturers. The European Chemicals Agency's cumulative assessment of quaternary ammonium compounds and aldehydes forces reformulation toward lactic acid, hydrogen peroxide, and peracetic acid blends. Food-contact sanitizer producers face the steepest compliance costs, with dossier preparation consuming 18-24 months of technical resources.
Hospital purchasing cooperatives are consolidating supplier rosters and demanding outcome-based service contracts bundling chemicals, equipment, and compliance documentation. This procurement consolidation squeezes regional distributors and rewards integrated providers capable of delivering EPA-registered efficacy data, staff training, and dispensing hardware as a single contract. The shift is most advanced in the United States, where GPOs control 70% of acute-care facility spending.
Cleaning Chemicals Market Segmentation
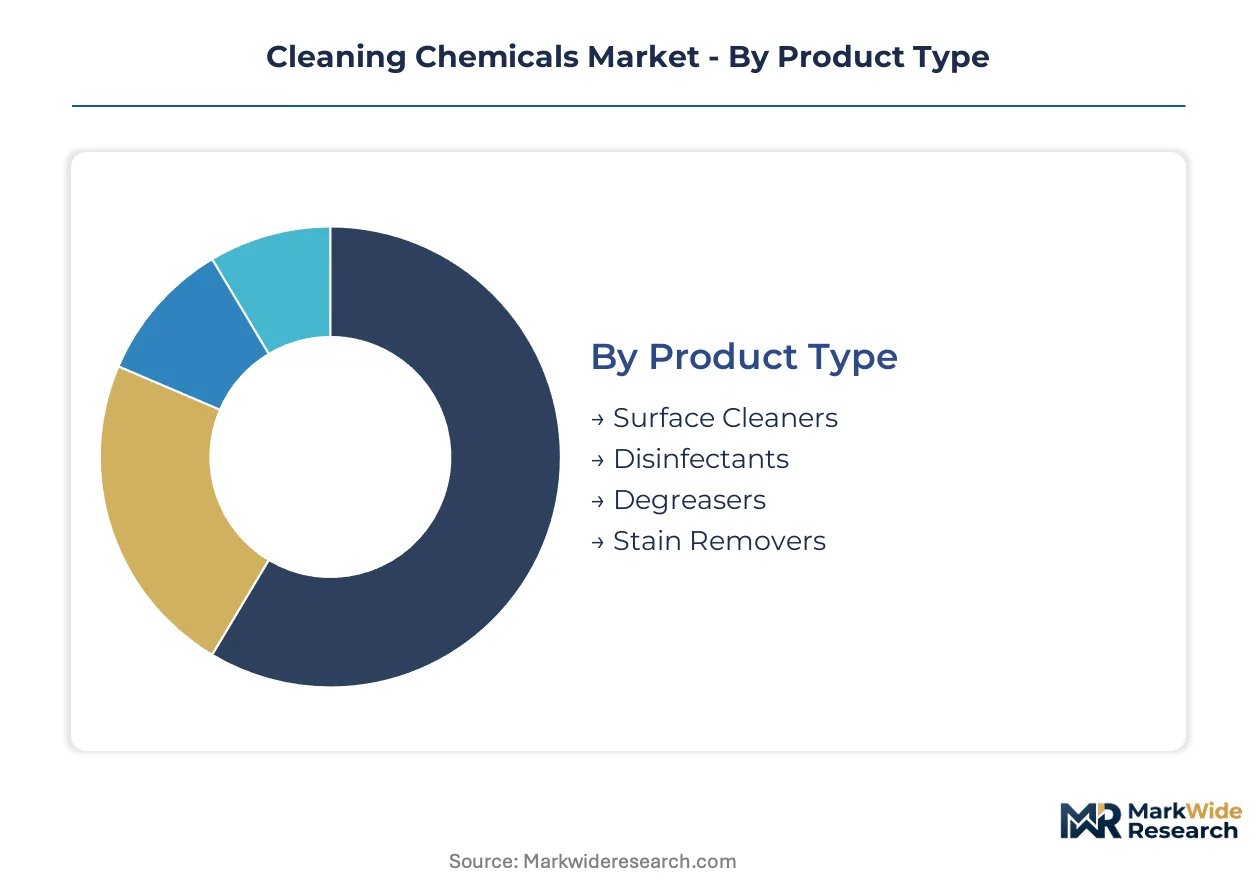
Cleaning chemicals serve divergent performance requirements across hygiene protocols, equipment compatibility, and regulatory jurisdictions. Segmentation reveals where formulation investments concentrate and which chemistries face substitution pressure from bio-based alternatives.
Product Type:
Replacement cycles vary sharply across product types, with healthcare-grade disinfectants refreshing every 12-18 months versus 3-5 year cycles for industrial degreasers in stable process environments.
- Surface Cleaners:Formulated blends of anionic and non-ionic surfactants with pH buffers between 6-9 for substrate compatibility. Demand concentrates in United States commercial facilities where LEED v4.1 and EPA Safer Choice procurement preferences accelerate reformulation toward readily biodegradable surfactant systems.
- Disinfectants:Biocide-active formulations incorporating quaternary ammonium compounds, hydrogen peroxide, or peracetic acid at EPA-registered concentrations. Hospital purchasing cooperatives in Germany and Japan are consolidating supplier rosters around bundled service contracts that embed these chemistries into permanent infection control protocols.
- Degreasers:High-alkaline or solvent-based systems for fatty soil removal in food processing and metal fabrication.
- Stain Removers:Enzyme-active or oxidizing formulations targeting protein and pigment soils in textile and hard surface applications.
Volume placements concentrate in Surface Cleaners; the faster expansion belongs to Disinfectants.
End User:
Cost tiers separate this category, with healthcare and industrial buyers absorbing 3-5x per-unit pricing versus residential channels.
- Residential:Mass-market formulations emphasizing fragrance, packaging convenience, and retail shelf presence over technical performance claims.
- Commercial:Concentrated dilutable systems for facility management contractors operating across hospitality, education, and office sectors.
- Industrial:Process-integrated chemistries for CIP systems, parts washing, and heavy soil removal in manufacturing environments.
- Healthcare:Sporicidal and virucidal formulations governed by Joint Commission accreditation standards and CDC disinfection guidelines in United States acute-care facilities.
Margin concentration sits with Healthcare; Industrial delivers the steepest expansion trajectory as food processing capacity scales in China and India.
Formulation Type:
Application method dictates physical form selection, with automated dispensing infrastructure locking in liquid dominance despite powder's freight advantage.
- Liquid:Pump-dispensed or aerosolized solutions enabling precise dilution control and rapid surface coverage.
- Powder:Reduced-mass shipping formats gaining traction in industrial laundries and institutional kitchens seeking warehouse footprint reduction.
- Gel:Thickened rheology for vertical surface cling and extended contact time in bathroom and kitchen applications.
- Spray:Pre-diluted or propellant-dispensed formats for convenience-oriented residential and light commercial use.
Customer type stratification shows Liquid anchoring institutional procurement; Powder is climbing the fastest as freight costs pressure supply chain redesign.
Application Area:
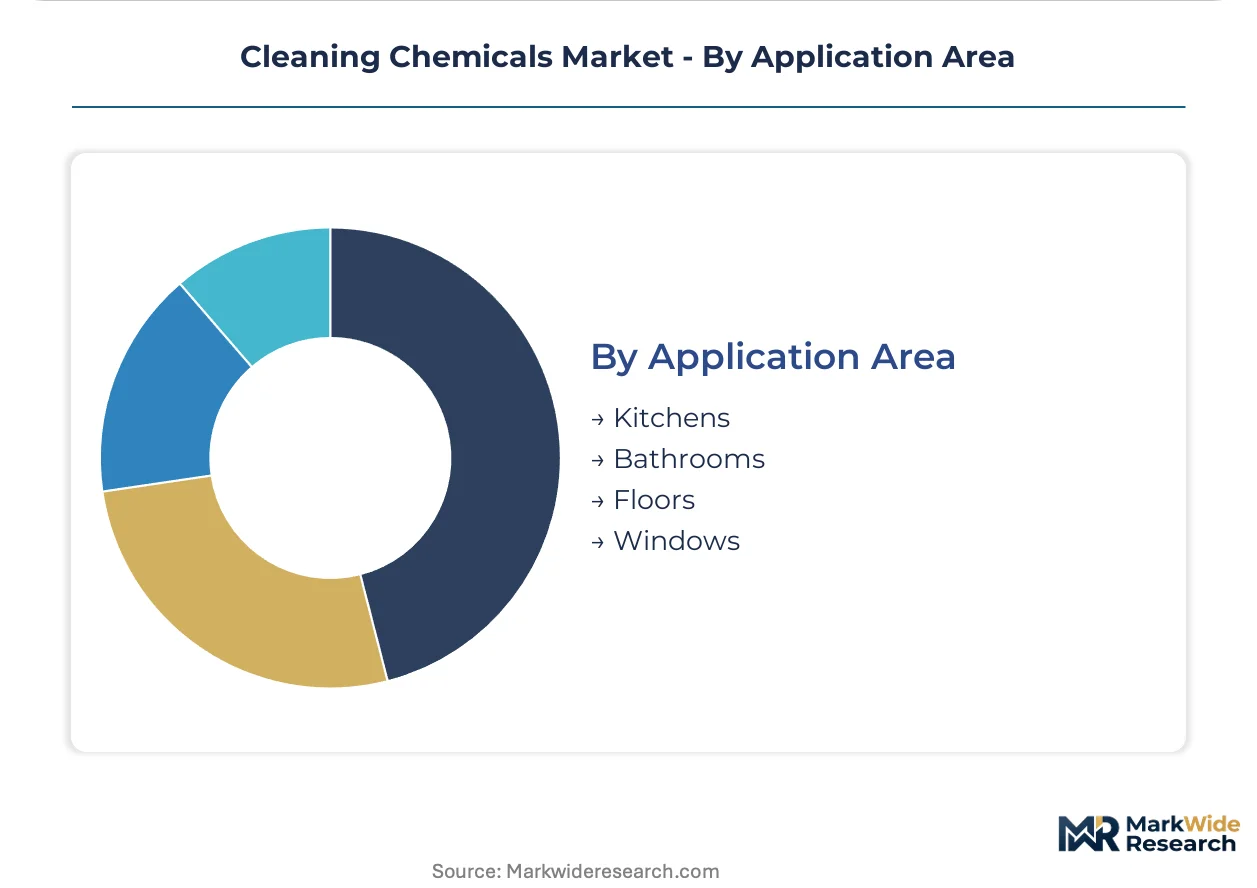
Geography shapes demand intensity, with humid climates accelerating bathroom mold remediation chemistries and high-traffic commercial corridors driving floor care specialization.
- Kitchens:Food-contact sanitizer formulations balancing antimicrobial efficacy with residue limits under FDA and local health department protocols.
- Bathrooms:Acidic and oxidizing chemistries targeting mineral scale, soap scum, and biofilm accumulation on ceramic and metal fixtures.
- Floors:Neutral pH or mildly alkaline cleaners compatible with polymer floor finishes and automated scrubber equipment.
- Windows:Ammonia-free and low-streak surfactant systems for glass and mirror surfaces in commercial high-rise maintenance.
Supply concentration favors Kitchen formulations given food safety regulatory density; Bathrooms are gaining share fastest as hospitality and healthcare construction expands in Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Gujarat and Tamil Nadu accelerate chemical manufacturing concentration through tax holidays and duty exemptions on imported feedstocks. These zones anchor Asia-Pacific supply expansion while EPA-registered producers in the United States defend institutional contracts against reformulation mandates.
United States
Hospital purchasing cooperatives consolidate supplier rosters around bundled service contracts embedding disinfectants, dispensing hardware, and compliance documentation. EPA Safer Choice procurement preferences under federal acquisition regulations accelerate reformulation toward bio-based surfactant systems. Manufacturing clusters in Texas and Louisiana leverage Gulf Coast petrochemical infrastructure for quaternary ammonium compound production.
Germany
Electrolyzed water pilot programs in Bavarian food processing plants displace shipped concentrates with on-site generation from salt and electricity inputs. REACH authorization timelines under ECHA jurisdiction compress the viable active-ingredient palette, forcing migration toward lactic acid and peracetic acid blends. Industrial chemical production concentrates in North Rhine-Westphalia around Leverkusen and Ludwigshafen complexes.
China
Food processing capacity expansion in Shandong and Jiangsu provinces sustains industrial degreaser demand for CIP systems and equipment sanitation. Dual carbon goals under MEE jurisdiction pressure reformulation away from high-energy surfactant synthesis routes. Yangtze River Delta chemical parks in Zhejiang and Jiangsu integrate cleaning chemical output with downstream textile and electronics manufacturing.
India
NABH hospital accreditation mandates create procurement pathways for imported hospital-grade disinfectants in tertiary care facilities across Maharashtra and Karnataka. PLI scheme incentives for specialty chemicals attract greenfield investment in Gujarat's Dahej and Mundra port zones. Mumbai-Pune industrial corridor hosts contract manufacturers serving domestic institutional buyers and export markets.
Japan
Integrated generator-dispenser systems in Kanto region food processors replace weekly concentrate deliveries with tap-water electrolysis. METI efficiency standards for commercial cleaning equipment drive adoption of concentrated powder formats in hospitality and healthcare sectors. Osaka-Kobe chemical complex maintains surfactant production for precision electronics cleaning applications.
Cleaning Chemicals Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with institutional healthcare channels favoring integrated service providers while industrial buyers source through regional distributors. The vendor base organizes around three strategic archetypes: multinational chemical conglomerates with backward integration into surfactant feedstocks, specialized infection prevention bundlers, and regional formulators serving price-sensitive commercial accounts. Consolidation pressure intensifies through hospital GPO procurement consolidation and REACH-driven active-substance authorization costs that freeze smaller competitors from European markets. Capacity expansion and strategic partnerships represent the dominant competitive moves, with electrolyzed water technology licensing emerging as a channel disruption vector.
Among integrated chemical conglomerates, BASF SE and Dow Inc. exemplify the feedstock-integrated archetype through captive surfactant manufacturing and global distribution infrastructure. Ecolab Inc. anchors the institutional service model, embedding cleaning protocols directly into hospital and foodservice operations through outcome-based contracts. These three companies occupy positions that concentrate procurement influence across healthcare and industrial end uses, with Diversey Holdings Ltd. representing the specialized infection prevention bundler archetype focused on long-term care and acute-care facility compliance requirements.
| Leading Market Players |
|---|
| Ecolab Inc. |
| BASF SE |
| Dow Inc. |
| Diversey Holdings Ltd. |
| Clariant AG |
| Procter & Gamble |
| Zep Inc. |
| Solenis LLC |
| Stepan Company |
| Others |
Supply Flow & Price Mechanics
Backward integration into surfactant manufacturing anchors both supply security and pricing power for leading producers, as captive feedstock production insulates margins from petrochemical volatility while enabling premium positioning for EPA-registered formulations in institutional procurement channels.
Pricing Analysis
Short lead-time premiums command pricing power in healthcare procurement, where hospital purchasing cooperatives prioritize same-week delivery of sporicidal disinfectants over spot inventory discounts. Three-tier pricing structure across hospital-grade, commercial-grade, and economy-grade chemistries reflects EPA registration status and efficacy certification levels. Cost compression in industrial degreasers intensifies as food processors in China and India qualify local suppliers. Residential channels exhibit highest price sensitivity, while healthcare buyers absorb premiums for bundled compliance documentation and dispensing hardware.
Supply Chain Analysis
Dual-sourcing requirements from hospital GPOs mandate multi-supplier qualification for quaternary ammonium compounds and peracetic acid blends, forcing distributors to maintain parallel relationships with producers in the United States, Germany, and China. Raw material dependencies center on ethylene oxide derivatives, linear alkylbenzene sulfonates, and bio-based feedstocks such as coconut oil and corn-derived ethanol. Single-source vulnerability concentrates in European REACH-authorized active substances, where ECHA approval timelines freeze alternative supplier onboarding. Distribution runs through regional chemical distributors serving institutional accounts, with direct manufacturer relationships reserved for top-tier healthcare networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrolyzed water on-site generation systems are displacing shipped concentrate models in food processing and healthcare, compressing traditional supply chains and rewriting competitive economics for formulation suppliers.
For Market Incumbents: Deploy outcome-based service contracts bundling chemicals, dispensing hardware, and EPA compliance documentation to lock in hospital GPO relationships against electrolyzed water substitution. Deepen backward integration into bio-based surfactant synthesis to meet EPA Safer Choice procurement preferences while insulating margins from petrochemical feedstock swings. Counter regional distributor erosion by embedding technical service teams directly into long-term care facility operations. For New Entrants and Emerging Players: Launch via electrolyzed water technology licensing agreements targeting mid-size food processors in Germany and Japan seeking to eliminate drum handling costs. Penetrate India's NABH-accredited hospital segment through imported hospital-grade disinfectant partnerships with Mumbai-Pune corridor distributors. White-space concentrates in on-site generation system integration services, where incumbent chemical suppliers lack IoT dispensing expertise. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational chemical conglomerates seeking EPA-registered product portfolios and institutional service capabilities. Five-to-ten-year viability favors targets with captive surfactant production and established GPO contracts. Watch electrolyzed water adoption rates in Kanto region food processors as inflection signal for concentrate displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Surfactants | Captive feedstock production secures EPA Safer Choice certification pathways for institutional contracts. |
| Electrolyzed Water Technology Licensing | On-site generation systems displace shipped concentrates in Bavarian food processing pilot programs. |
| Hospital GPO Service Contract Bundling | Outcome-based agreements embed chemicals, hardware, and compliance documentation into acute-care procurement. |
| REACH-Active Substance Dossier Investment | ECHA authorization timelines compress viable ingredient palettes, freezing smaller competitors from European markets. |
| India Healthcare Infrastructure Partnership | NABH accreditation mandates create procurement pathways for imported hospital-grade chemistries in Maharashtra. |
Methodological Framework
Independent corroboration across plant managers at Gulf Coast quaternary ammonium facilities, procurement leads at German food processors, and distribution channel partners in the Mumbai-Pune corridor underwrites the qualitative findings. Technical R&D directors at surfactant manufacturers provided formulation trend intelligence. Secondary validation drew from EPA registration databases, ECHA authorization lists, customs trade data, and SEC filings from publicly traded chemical conglomerates. Bottom-up volume estimates triangulate with top-down market sizing across product type, end user, and formulation segments.
Rate-of-change decomposition separates volume growth from pricing dynamics across the analysis window. Segmentation modeling incorporates product type, end-use industry, formulation format, and regional production hub. CAGRs derive from trend extrapolation adjusted for regulatory inflection points and technology substitution curves. Forecast inputs include REACH authorization timelines, NABH hospital accreditation rollout pace, and electrolyzed water system adoption rates in institutional foodservice.
Feedstock price volatility, REACH active-substance authorization delays, and electrolyzed water substitution velocity are the dominant revision risks. Deviation in electrolyzed water adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Electrostatic Liquid Cleaner Market
Cleaning Chemicals
Fabric Softener Market
Cleaning Chemicals
Rust Remover Market
Cleaning Chemicals
Home Insecticides Market
Cleaning Chemicals
Firefighting Chemicals Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Commercial Deodorizers Market
Cleaning Chemicals
Aviation Cabin Cleaning Chemical Market
Cleaning Chemicals
Descaler Market
Cleaning Chemicals
Mask Reticle Cleaning Agent Market
Cleaning Chemicals
Biodegradable Spray Tank Line-Cleaning Chemistry Market
Cleaning Chemicals
Green Floor Care Chemical Systems for Commercial Facilities Market
Cleaning Chemicals
North America Metal Cleaning Chemicals Market
Cleaning Chemicals
Latin America Detergent Market
Cleaning Chemicals
Commercial Cleaning Products Market
Cleaning Chemicals
Europe Metal Cleaning Chemicals Market