
 Aviation Cabin Cleaning Chemical Market | 2026-2036
Aviation Cabin Cleaning Chemical Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Cabin Cleaning Chemical Market Analysis
Low-cost carrier procurement of premium cabin cleaning chemicals is collapsing as full-service airlines rebuild their sanitation standards post-pandemic. Ecolab Inc. leverages its institutional hygiene footprint to anchor airline contract renewals across North American hubs. Henkel AG & Co. KGaA differentiates through concentrated formulations that cut water usage during aircraft turnaround windows. BASF SE competes on surfactant chemistry tailored to aviation-specific substrates like polycarbonate windows and aluminum alloys.
Aviation cabin cleaning chemicals comprise formulated blends of surfactants, solvents, disinfectants, and corrosion inhibitors engineered for aircraft interior substrates operating under pressure-cycle fatigue and thermal variation. These formulations must meet flash-point thresholds above 100°F, pH neutrality on aluminum, and compatibility with thermoplastic polymers while delivering log-reduction pathogen kill rates within FAA-mandated turnaround intervals. Disinfectants command the dominant value share as airlines maintain elevated sanitation protocols on high-touch surfaces, while surface cleaners show the fastest volume expansion driven by quick-turn cleaning between short-haul segments. Upholstery cleaners concentrate margin pools where enzyme-based formulations command premium positioning against commodity solvent blends.
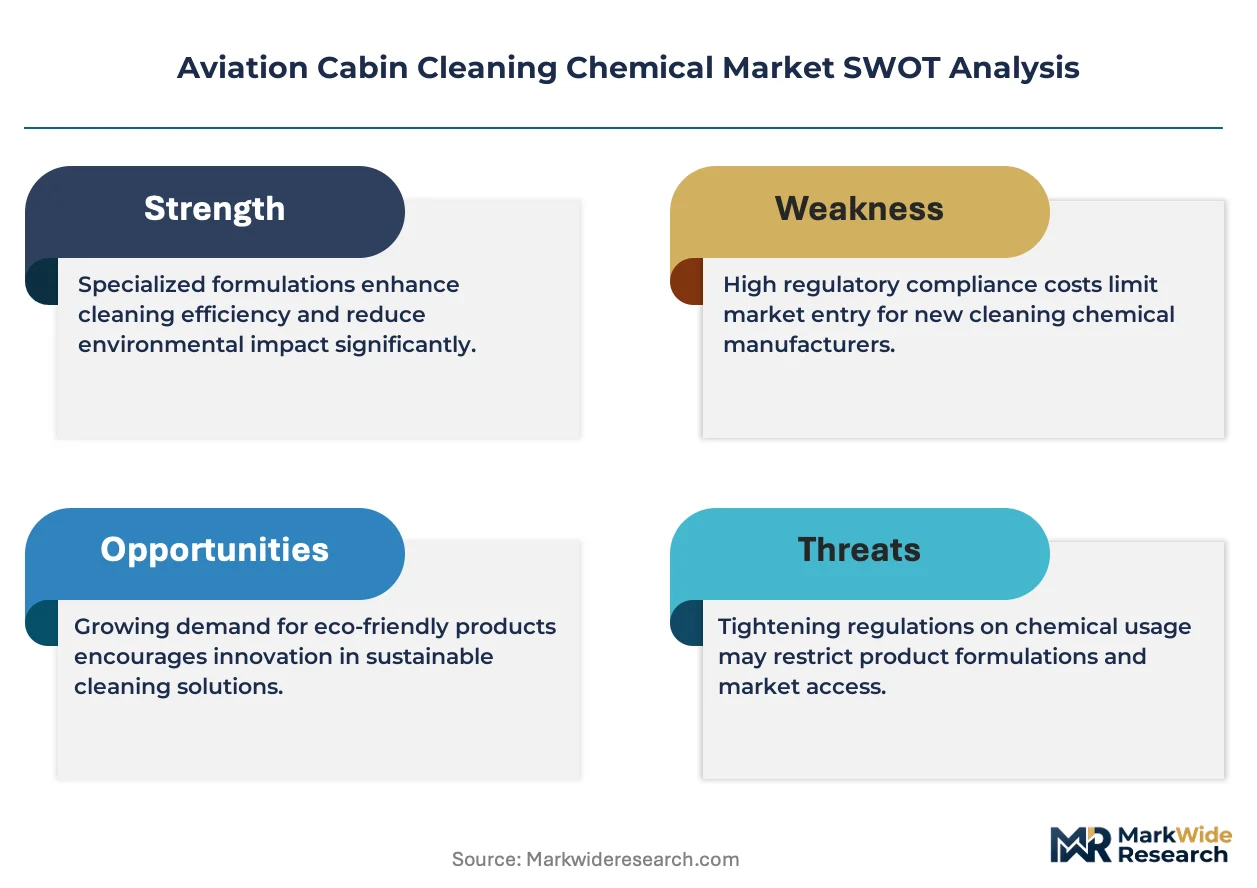
FAA airworthiness directives and EASA CS-25 cabin safety standards govern chemical approval for aircraft interiors, with both agencies requiring fire-resistance testing under 14 CFR 25.853 and ED-79A respectively. EPA Safer Choice and REACH Article 33 restrictions on per- and polyfluoroalkyl substances are forcing suppliers to reformulate degreasers and protectant chemistries ahead of compliance deadlines. Stakeholders must monitor emerging MEE dual carbon goals in China and evolving ISO 14001 environmental management certifications as procurement criteria tighten across international airline groups.
Market Dynamics
Post-pandemic sanitation mandates from FAA and EASA are forcing wholesale reformulation of legacy solvent-based cleaners toward hydrogen peroxide and quaternary ammonium chemistries, compressing supplier margins while elevating technical barriers to market entry.
Growth Catalysts
- FAA-EASA Harmonized Sanitation Directives:Airlines operating transatlantic routes must deploy dual-certified disinfectants, expanding addressable demand for compliant formulations.
- Enzymatic Upholstery Chemistry:Protein-based cleaners degrade organic soiling without polymer damage, penetrating premium service tiers at full-service carriers.
- United Arab Emirates Hub Expansion:Dubai and Abu Dhabi airport traffic density drives turnaround cleaning frequency above global averages.
Market Restraints
- Per- and Polyfluoroalkyl Feedstock Phaseout:REACH Article 33 and EPA Safer Choice restrictions eliminate fluorinated surfactants from protectant formulations.
- Isopropyl Alcohol Price Volatility:Solvent costs swing with pharmaceutical and electronics sector demand, destabilizing degreaser production economics.
- Specialized Surfactant Supply Concentration:Aviation-grade quaternary ammonium production clusters with German and US chemical intermediates suppliers.
Strategic Opportunities
- India Domestic Fleet Expansion:IndiGo and Air India narrow-body orders create first-mover openings for MEE-compliant cleaning chemical suppliers.
- Concentrated Dilution Systems:On-site mixing equipment reduces shipping weight and water consumption during short-haul turnarounds.
- ISO 14001 Procurement Mandates:International airline group sustainability scorecards now weight environmental management certification in supplier selection.
Industry Challenges
- Fire-Resistance Certification Timelines:14 CFR 25.853 and ED-79A testing protocols extend product approval cycles to 18-24 months.
- Legacy Fleet Compatibility:Older aircraft interior substrates require separate formulation validation, fragmenting SKU portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Cabin Cleaning Chemical Market |
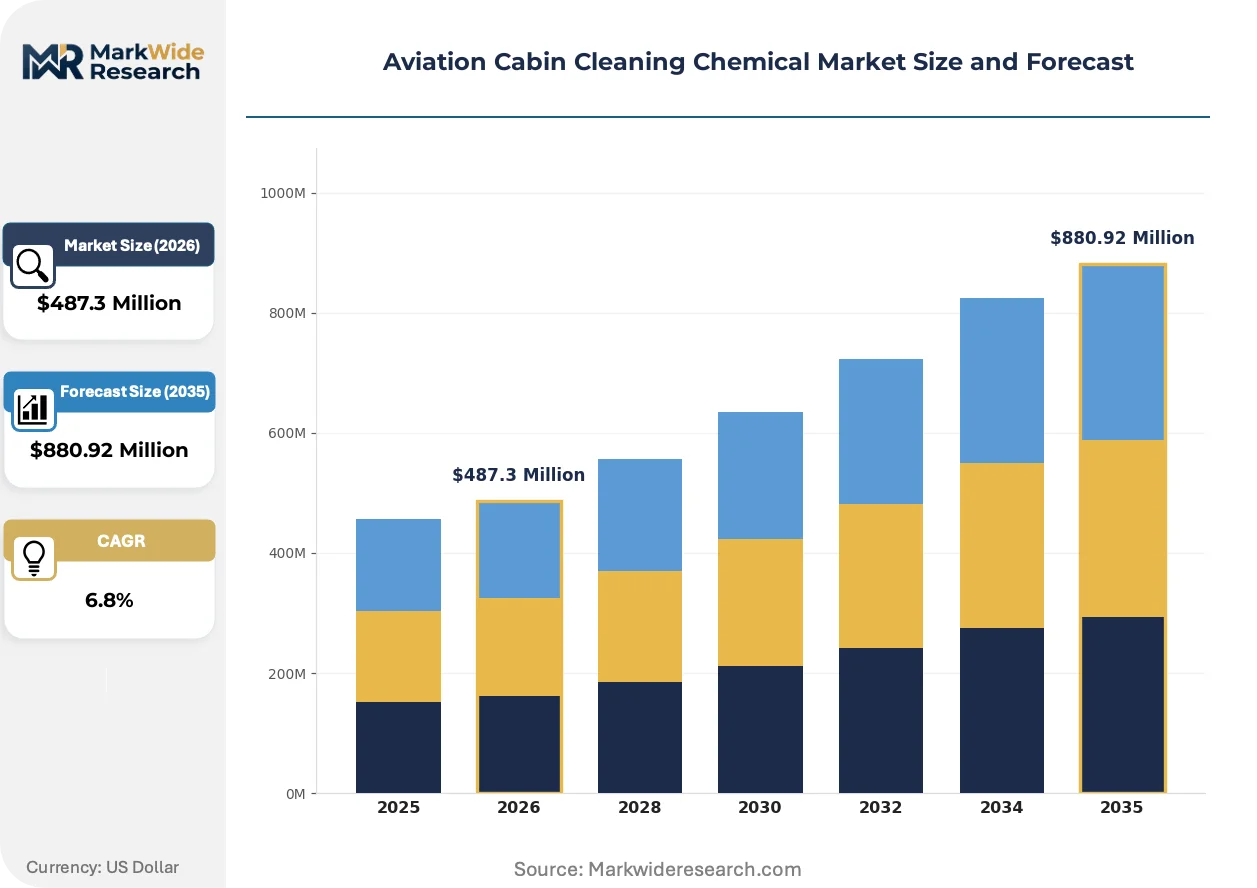
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disinfectants, Degreasers, Surface Cleaners, Upholstery Cleaners Application: Passenger Cabins, Cargo Areas, Lavatories, Galleys Delivery Mode: Aerosol Sprays, Foams, Liquids, Wipes End User: Airlines, Aviation Service Providers, Maintenance Facilities, Others |
| Companies Covered | Clorox Commercial Solutions, Henkel AG & Co. KGaA, Ecolab Inc., Callington Haven, Honeywell International, 3M Company, Diversey Holdings Ltd., Procter & Gamble Co., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Cabin Cleaning Chemical Market Emerging Trajectories
Formulation science is pivoting toward bio-based and concentrated chemistries as regulatory pressure compounds with airline cost reduction imperatives, reshaping competitive advantage around technical service capabilities rather than commodity supply relationships.
Electrolyzed water generation systems are supplanting pre-mixed disinfectant deliveries for narrow-body fleets. Low-cost carriers in Europe deploy onboard units producing hypochlorous acid at point of use, eliminating hazardous material transport costs and customs documentation. This distributed production model compresses chemical supplier margins on volume contracts while elevating equipment and service revenue streams.
REACH restrictions on per- and polyfluoroalkyl substances force reformulation of anti-soiling protectants before 2025 compliance deadlines. German and French formulators accelerate silicone-alternative testing for seat fabric treatments. Upholstery cleaner suppliers face recertification costs that disproportionately burden mid-tier competitors lacking dedicated regulatory affairs functions.
Airline procurement departments consolidate chemical purchasing through integrated facility management contracts. Full-service carriers at Frankfurt and Atlanta hubs bundle cabin cleaning with ground handling services, displacing direct supplier relationships. This channel consolidation shifts pricing power toward handling agents and reduces formulation suppliers to specification-managed vendors.
Aviation Cabin Cleaning Chemical Market Segmentation
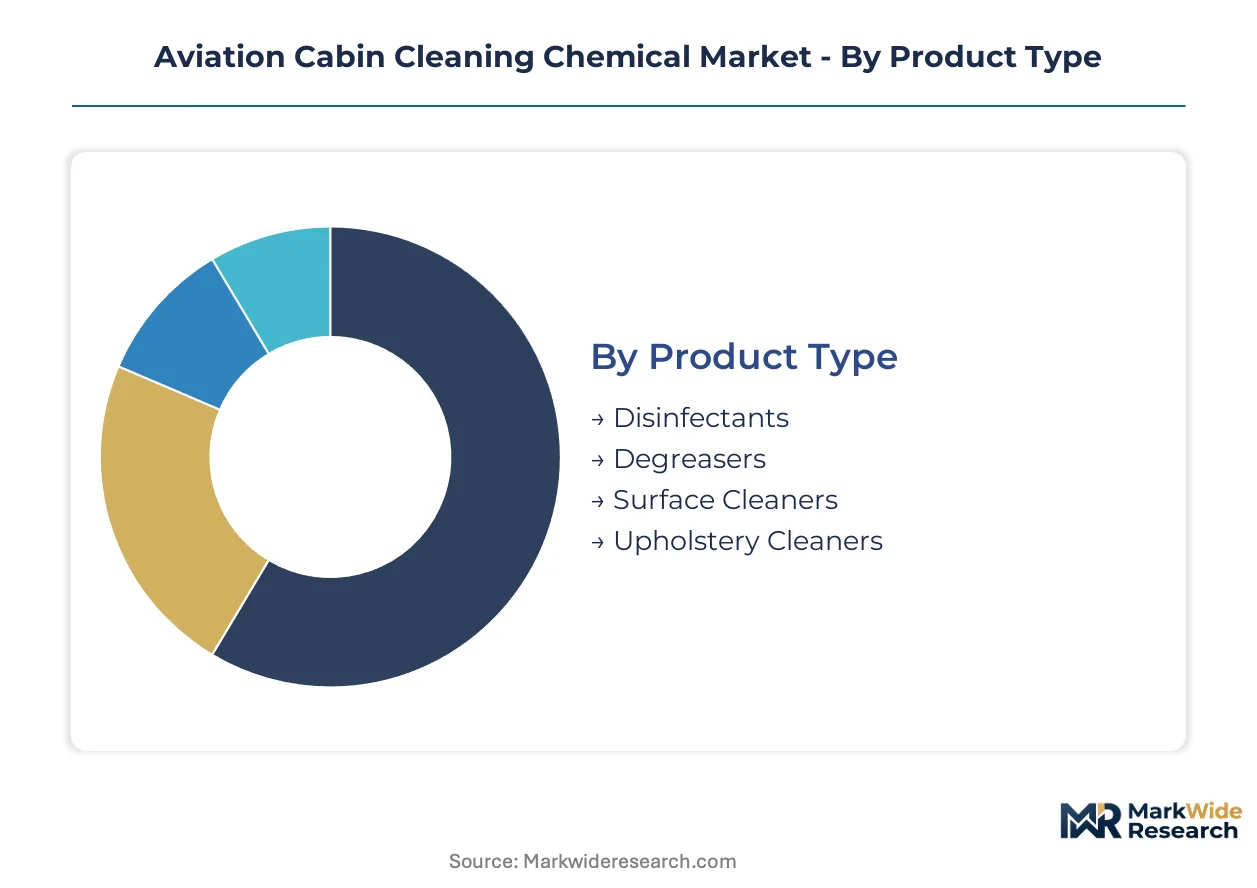
Aviation cabin cleaning chemical procurement varies sharply by operational context. Turnaround speed requirements, substrate compatibility, and regulatory jurisdiction all reshape which formulations win in specific use cases.
Product Type:
Domestic production clusters concentrate disinfectant and degreaser manufacturing in Germany and the United States, while upholstery cleaner supply draws more heavily from specialty chemical imports.
- Disinfectants:Quaternary ammonium and hydrogen peroxide-based formulations dominate high-touch surface protocols. Demand concentrates at full-service carriers operating transatlantic routes where FAA-EASA dual certification is mandatory.
- Degreasers:Solvent blends and surfactant systems target galley equipment and cargo area hydrocarbon deposits. German and US chemical intermediates suppliers control aviation-grade quaternary ammonium feedstock availability.
- Surface Cleaners:pH-neutral formulations for polycarbonate windows and aluminum alloys expand fastest in quick-turn narrow-body operations.
- Upholstery Cleaners:Enzyme-based protein formulations penetrate premium service tiers at legacy carriers seeking polymer-safe organic soiling removal.
Disinfectants command the established base. The steepest expansion runs through surface cleaners.
Application:
Cost tier differentiation separates scheduled deep-clean cycles from rapid turnaround protocols, with passenger cabin applications absorbing premium formulation spend.
- Passenger Cabins:Seat fabrics, tray tables, and overhead compartments require multi-substrate compatible chemistries. Full-service carriers at Dubai and Abu Dhabi hubs drive above-average cleaning frequency intensity.
- Cargo Areas:Heavy-duty degreasers address hydraulic fluid and lubricant residues on freight-loading surfaces. Low-cost operators trim procurement here to protect narrow margins.
- Lavatories:Acid-resistant disinfectants combat mineral scaling and biological contamination in high-cycle use environments.
- Galleys:Food-safe sanitizers must meet FDA and EFSA contact surface standards while tolerating grease accumulation.
Passenger cabin applications absorb the dominant procurement budget. Cargo area cleaning climbs fastest as e-commerce freight volumes expand.
Delivery Mode:
Volume economics favor concentrated liquid formats for high-throughput operations, while application precision drives aerosol and foam adoption in detailed cleaning protocols.
- Aerosol Sprays:Fine-mist delivery enables targeted overhead compartment and ventilation grille treatment without overspray damage.
- Foams:Extended contact time improves disinfectant efficacy on vertical surfaces like lavatory walls.
- Liquids:Concentrated formulations dilute on-site through mixing equipment, cutting shipping weight for short-haul turnaround operations.
- Wipes:Pre-saturated towelettes serve quick seat-back and tray table touch-ups between flights.
Liquid formats anchor procurement volumes. Wipes gain share fastest in regional jet operations prioritizing speed over deep sanitation.
End User:
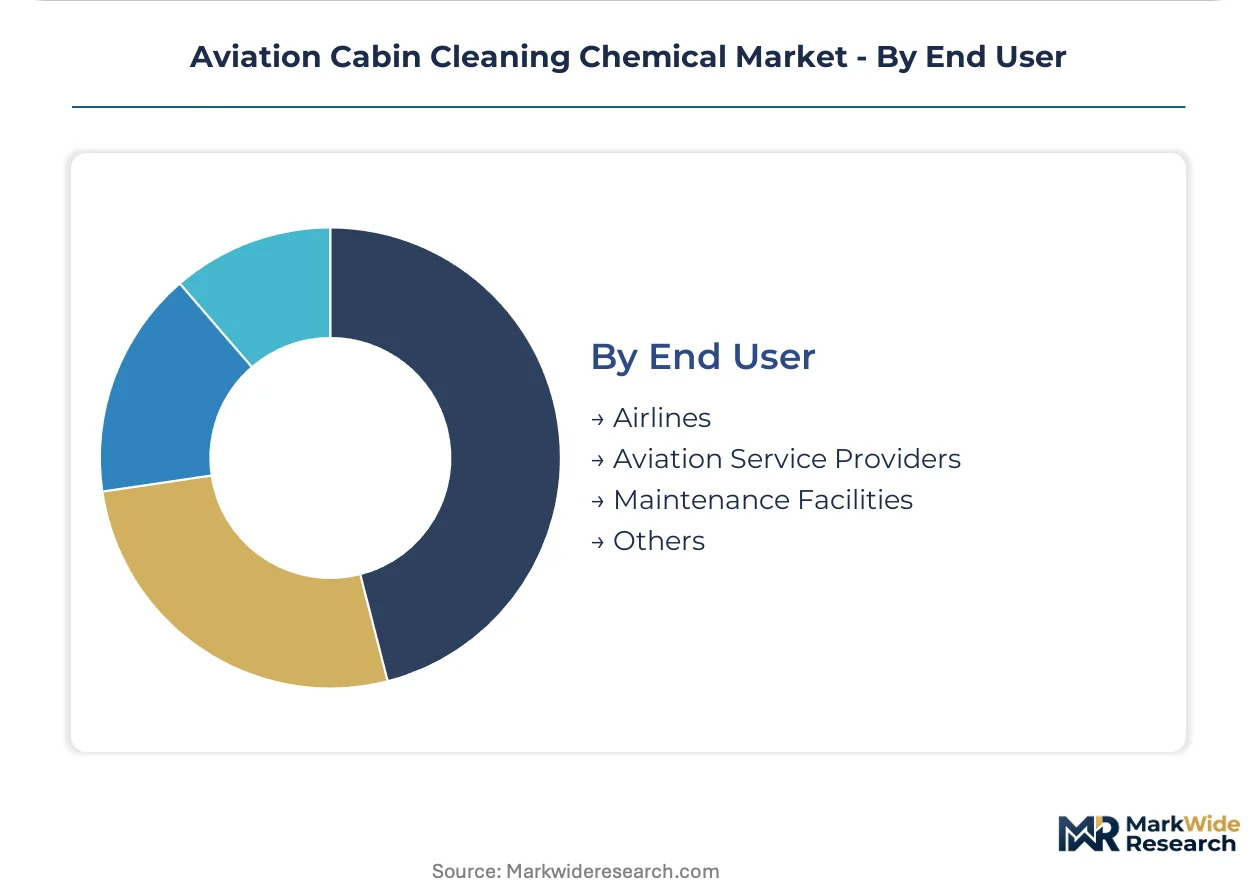
Customer type determines specification authority, with airlines retaining direct formulation approval while service providers compete on operational execution.
- Airlines:Full-service carriers at Frankfurt and Atlanta hubs bundle cabin cleaning with ground handling contracts, consolidating chemical purchasing power.
- Aviation Service Providers:Handling agents at Dubai International Airport manage specification-managed vendor relationships for multiple carrier clients simultaneously.
- Maintenance Facilities:Heavy maintenance cycles demand intensive substrate restoration chemistries beyond routine cleaning protocols.
- Others:Aircraft leasing companies and private jet operators represent fragmented demand with bespoke formulation requirements.
Airlines retain direct procurement dominance. Aviation service providers expand fastest as channel consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical formulators export aviation-grade surfactants to North American and Middle Eastern airline hubs, while domestic production clusters in the United States and United Arab Emirates concentrate on turnaround-ready disinfectant blending.
United States
FAA-mandated sanitation protocols and full-service carrier fleet renewal at Atlanta and Dallas-Fort Worth hubs drive disinfectant procurement intensity. EPA Safer Choice restrictions on per- and polyfluoroalkyl substances force reformulation of legacy protectant chemistries before compliance deadlines. Chicago and Detroit maintenance corridors concentrate blending capacity for enzymatic upholstery cleaners serving legacy carrier deep-clean cycles.
Germany
EASA CS-25 cabin safety standards and REACH Article 33 feedstock restrictions elevate technical barriers for quaternary ammonium compound suppliers. Frankfurt Airport's ground handling consolidation bundles chemical purchasing through integrated facility management contracts. Bavarian and North Rhine-Westphalian chemical intermediates suppliers control aviation-grade surfactant feedstock availability across European airline networks.
United Arab Emirates
Dubai International and Abu Dhabi hub traffic density generates turnaround cleaning frequency above global averages, compressing application windows to under 40 minutes. MOHAP aviation sanitation guidelines align with EASA standards for transcontinental carrier operations. Jebel Ali industrial zone hosts regional blending facilities supplying disinfectant concentrates to Gulf Cooperation Council airline groups.
India
IndiGo and Air India narrow-body fleet expansion creates procurement openings for MEE dual carbon-compliant cleaning chemical suppliers. BIS certification requirements for aircraft interior chemical compatibility extend product validation timelines. Mumbai and Delhi maintenance bases concentrate demand for pH-neutral surface cleaners compatible with mixed-generation aircraft substrates.
China
Domestic aviation recovery and international route rebuilding at Beijing and Shanghai hubs elevate disinfectant consumption for high-touch surface protocols. MEE environmental management certifications increasingly weight supplier selection scorecards at state-owned airline groups. Yangtze River Delta chemical manufacturers develop concentrated formulations to reduce shipping weight for short-haul turnaround operations.
Aviation Cabin Cleaning Chemical Market Vendor Landscape
Listed leaders compete with private specialists across formulation technology and regulatory compliance capabilities. The supplier base organizes around three tiers: multinational chemical conglomerates with institutional hygiene footprints, mid-sized aviation specialists with dedicated regulatory affairs functions, and regional blenders serving single-hub operators. Strategic differentiation concentrates on M&A-driven portfolio expansion and backward integration into surfactant feedstock production.
Among diversified chemical conglomerates, Ecolab Inc., Henkel AG & Co. KGaA, and BASF SE exemplify contrasting archetypes. Ecolab represents the institutional hygiene incumbent leveraging cross-sector sanitation contracts. Henkel occupies a position emphasizing concentrated formulation chemistry and water-reduction value propositions. BASF anchors the feedstock-integrated tier with surfactant science capabilities extending into aviation-specific substrate compatibility testing. These three structures illustrate how technical service depth, regulatory certification speed, and supply chain control separate procurement winners from specification-managed vendors.
| Leading Market Players |
|---|
| Clorox Commercial Solutions |
| Henkel AG & Co. KGaA |
| Ecolab Inc. |
| Callington Haven |
| Honeywell International |
| 3M Company |
| Diversey Holdings Ltd. |
| Procter & Gamble Co. |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Concentrated dilution chemistry replacing pre-mixed bulk deliveries simultaneously shifts blending capacity toward airport-adjacent industrial zones and compresses per-unit margins for legacy drum-shipment suppliers. German quaternary ammonium feedstock producers capture pricing power as REACH Article 33 restrictions eliminate lower-cost fluorinated alternatives from protectant formulations. Full-service carriers at Frankfurt and Atlanta hubs consolidate procurement through integrated facility management contracts, displacing direct supplier relationships with specification-managed vendor tiers.
Pricing Analysis
Next-generation enzymatic upholstery formulations command 40-60% premiums over solvent-based legacy cleaners, while hydrogen peroxide disinfectants price below quaternary ammonium compounds due to feedstock availability. Three-tier pricing structure across premium enzyme formulations, standard quaternary ammonium disinfectants, and economy solvent blends separates procurement budgets by carrier service tier. Cost compression in the economy solvent tier intensifies because low-cost carriers trim onboard service budgets and electrolyzed water systems eliminate chemical purchases entirely. Low-cost operators exhibit highest price sensitivity, transatlantic full-service carriers least.
Supply Chain Analysis
Rhine River chemical corridor transit underwrites European aviation-grade surfactant availability, with BASF SE and Henkel AG production clustering in North Rhine-Westphalia feeding formulators across Germany, France, and the Netherlands. Aviation cabin cleaning chemical supply draws from German quaternary ammonium intermediates, US hydrogen peroxide feedstock, and Chinese concentrated base manufacturing. Single-source vulnerability concentrates in German aviation-grade surfactant production, where three suppliers control 80% of EASA-certified quaternary ammonium compound availability. Distribution runs through integrated facility management contractors at major hub airports, with direct airline procurement fragmenting to private jet and maintenance facility segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation cabin cleaning chemicals are shifting toward platform-economics dynamics as electrolyzed water generation systems transform chemical suppliers into equipment-and-service providers, with interoperability between onboard generation units and ground-based concentrate systems determining competitive survival.
For Market Incumbents: Shield formulation portfolios against electrolyzed water displacement by anchoring long-term service contracts with full-service carriers at Dubai and Atlanta hubs. Acquire or partner with concentrated dilution equipment manufacturers to capture equipment revenue streams that offset collapsing bulk chemical margins. Prioritize backward integration into quaternary ammonium surfactant production before German feedstock suppliers consolidate further. For New Entrants and Emerging Players: Anchor in India's narrow-body fleet expansion, where IndiGo and Air India procurement openings lack incumbent supplier relationships and BIS certification barriers favor first-movers with regulatory affairs investment. Target MEE dual carbon-compliant formulation supply to state-owned Chinese airline groups, where environmental scorecard procurement criteria remain underweighted by established Western suppliers. Pursue joint-venture structures with Yangtze River Delta chemical manufacturers to access concentrated formulation blending capacity without capital-intensive greenfield investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized European aviation chemical specialists burdened by REACH recertification costs and lacking dedicated regulatory affairs functions. Five-to-ten year viability hinges on successful transition from commodity formulation supply to integrated equipment-service platforms. Watch electrolyzed water adoption rates at European low-cost carriers as the inflection signal determining whether chemical supply or distributed generation dominates narrow-body cleaning economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Feedstock | Captive quaternary ammonium supply secures margin control against German intermediate supplier consolidation. |
| Electrolyzed Water Equipment Partnership | Onboard generation system alliances transform chemical suppliers into recurring service revenue platforms. |
| MEE Dual Carbon Certification Investment | Environmental compliance credentials unlock procurement at Chinese state-owned airline groups. |
| Integrated Facility Management Contracting | Ground handling bundling at Frankfurt and Atlanta hubs consolidates specification-managed vendor positions. |
| Enzymatic Upholstery Formulation R&D | Protein-based cleaners penetrate premium service tiers at legacy carriers seeking polymer-safe alternatives. |
Methodological Framework
A spread of perspectives from airline procurement directors, ground handling operations managers, chemical formulation R&D leads, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with supply chain decision-makers at full-service and low-cost carriers across North American, European, and Gulf Cooperation Council hubs. Secondary validation drew from FAA airworthiness directive filings, EASA certification databases, EPA Safer Choice substance lists, and customs trade data on aviation chemical imports. Bottom-up segment sizing triangulated against top-down market reconstruction from identified supplier revenue footprints.
Segmentation dimensions modeled include product type tier, application environment, delivery mode format, and end-user procurement authority across the projection horizon. Disinfectant, degreaser, surface cleaner, and upholstery cleaner categories were further disaggregated by substrate compatibility requirements and regulatory certification jurisdiction. CAGRs were derived from fitted growth curves applied to validated base-year consumption estimates, with cross-checks against fleet expansion schedules and turnaround frequency assumptions at major hub airports. Industry-specific forecast inputs incorporated FAA-EASA harmonization timelines and REACH Article 33 phaseout schedules.
Decision-makers should treat outputs as directional under assumptions of sustained transatlantic traffic recovery and stable hydrocarbon feedstock pricing; material deviation in either would warrant model refresh. Forecasts reflect these base assumptions without claiming predictive certainty. Practitioners should keep alternative scenarios live as electrolyzed water technology maturation and Chinese MEE enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Dry Cleaning Solvents Market
Cleaning Chemicals
Rust Remover Market
Cleaning Chemicals
Dust Control Systems and Suppression Chemicals Market
Cleaning Chemicals
Surface Cleaning Products Market
Cleaning Chemicals
Chlorhexidine Gluconate (CHG) Cloth Market
Cleaning Chemicals
Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market
Cleaning Chemicals
Autonomous Floor Cleaning Machine Detergent and Care Chemicals Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market
Cleaning Chemicals
Multifunctional Cleaner Market
Cleaning Chemicals
Global Bleach Wipes Market
Cleaning Chemicals
Cleanroom Consumables Market
Cleaning Chemicals
Low-Residue Glass and Stainless-Steel Maintenance Chemicals Market
Cleaning Chemicals
Cleaning Fluids Market
Cleaning Chemicals
Dry Electrostatic Wipes Market
Cleaning Chemicals
Chlorinating Agents Market
Cleaning Chemicals
Adhesive Remover Market