
 Industrial and Institutional (Iandi) Cleaning Chemicals Market | 2026-2036
Industrial and Institutional (Iandi) Cleaning Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial and Institutional (Iandi) Cleaning Chemicals Market Foresight
Project finance and operating lease structures for chemical dispensing systems is tilting competitive access toward capital-rich service providers. Ecolab leverages its integrated water-chemistry-service model to anchor long-term institutional contracts. Diversey Holdings sustains geographic density in European healthcare and hospitality channels through direct sales teams. BASF SE competes on surfactant chemistry scale, supplying active ingredients to private-label formulators across multiple industrial verticals.
Industrial and institutional cleaning chemicals comprise formulated blends of surfactants, solvents, chelating agents, and antimicrobial actives engineered to remove soils, destroy pathogens, or dissolve organic residues on hard surfaces, equipment, and facilities. These formulations typically operate within specified pH ranges, concentration dilutions, and contact-time parameters validated against ASTM or EN microbiological test methods. Disinfectants command premium positioning in healthcare and food processing applications where EPA-registered or biocidal-claim compliance determines procurement eligibility. Liquid formulations dominate volume throughput due to compatibility with automated dilution and dispensing infrastructure, though concentrated powder formats retain cost advantages in freight-intensive supply chains.
The EPA regulates antimicrobial efficacy claims and toxicological profiles through FIFRA registration requirements, while OSHA's Hazard Communication Standard governs worker exposure documentation and safety data sheet distribution. The EU Biocidal Products Regulation and REACH chemical restrictions are forcing reformulation cycles, particularly for quaternary ammonium compounds and solvent-based degreasers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as these determinations will reshape raw material availability and compliance costs for stain-removal and specialty cleaning formulations.
Market Dynamics
The EPA's Safer Choice program and REACH restrictions in Europe are forcing simultaneous reformulation of surfactant chemistries and antimicrobial actives, compressing product development cycles while elevating compliance costs for mid-tier formulators.
Growth Catalysts
- Hospital-grade disinfectant mandates:Healthcare facilities in the United States are expanding procurement of EPA-registered sporicidal and virucidal formulations to meet Joint Commission sanitation protocols.
- REACH Article 57 restrictions:European manufacturers are accelerating substitution of quaternary ammonium compounds with bio-based alternatives to maintain biocidal product authorization.
- Automated dilution infrastructure:Food processing plants are installing IoT-enabled chemical dispensing systems that lock in concentrated liquid supply contracts.
Market Restraints
- Petrochemical feedstock volatility:Ethylene oxide and propylene derivatives exhibit price swings that compress surfactant blender margins without forward-contract protection.
- Active ingredient supply concentration:Chinese manufacturers control over 60% of global quaternary ammonium compound precursor output, creating geographic single-source vulnerability.
- Biocidal efficacy validation timelines:EPA FIFRA registration cycles extend 18-24 months for novel antimicrobial actives, freezing formulation innovation pipelines.
Strategic Opportunities
- Per- and polyfluoroalkyl substance replacement:Formulators developing fluorine-free stain repellents for textile and carpet cleaning applications can capture premium positioning ahead of state-level restrictions.
- On-site generation systems:Electrolyzed water and ozone generation equipment creates recurring chemical supply displacement in hospitality and institutional food service channels.
- Green public procurement mandates:EU member state purchasing directives favoring bio-based surfactants open volume pathways for certified sustainable formulations.
Industry Challenges
- Formulation chemist scarcity:Industrial cleaning chemistry expertise concentrates at legacy suppliers, constraining new entrant R&D velocity.
- Legacy dispensing system incompatibility:Concentrated powder and solid tablet formats face adoption friction against installed liquid infrastructure base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial and Institutional (Iandi) Cleaning Chemicals Market |
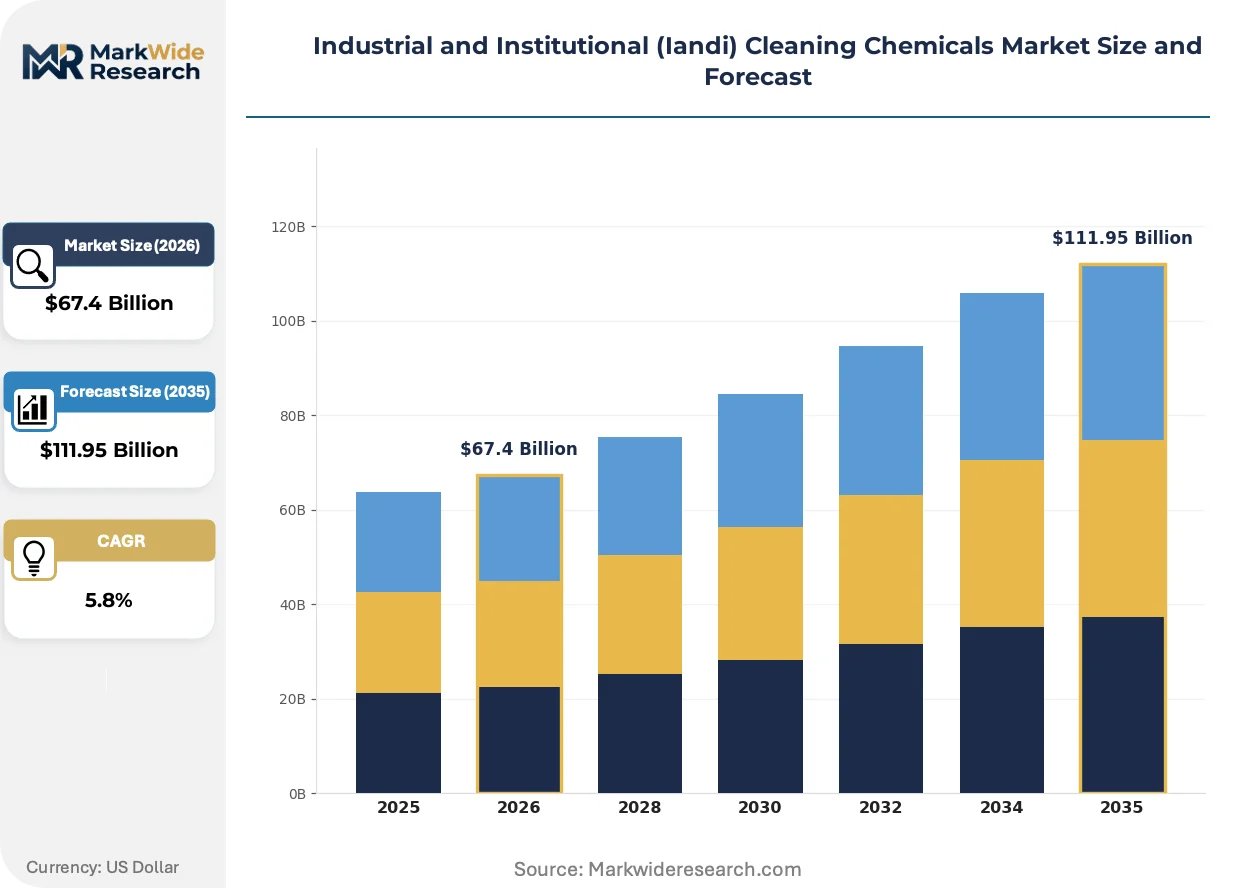
| Market Size in 2026 | $67.4 Billion |
| Market Size in 2035 | $111.95 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Detergents, Disinfectants, Degreasers, Stain Removers Application: Food Processing, Healthcare Facilities, Hospitality, Educational Institutions End User: Manufacturing, Retail, Services, Transportation Formulation: Liquid, Powder, Aerosol, Gel |
| Companies Covered | Ecolab, Procter & Gamble, BASF SE, The Clorox Company, Diversey Holdings, Clariant, Dow, Henkel AG & Co. KGaA, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial and Institutional (Iandi) Cleaning Chemicals Market Shifts & Advancements
Formulation science and delivery mechanisms are converging around sustainability mandates and automation compatibility, with three distinct vectors reshaping competitive positioning.
Enzymatic cleaning systems are collapsing the performance gap between bio-based and solvent-heavy degreasers in food processing and industrial maintenance applications. Meatpacking and dairy processors in Germany and the Netherlands are adopting lipase and protease formulations at scale. This enzymatic transition is collapsing traditional surfactant volume requirements while extending contact-time specifications in equipment cleaning protocols.
REACH restrictions on per- and polyfluoroalkyl substances are accelerating fluorine-free surfactant development across European industrial laundries and hard surface cleaners. The ECHA restriction proposals targeting stain-resistance chemistry are forcing reformulation of specialty carpet and upholstery products. German textile service providers are responding with accelerated supplier qualification programs for silicone and hydrocarbon-based alternatives.
Facility management outsourcing is consolidating chemical procurement authority into integrated service contracts that bundle dispensing equipment, training, and compliance documentation. Third-party facility operators in United States healthcare and education verticals are displacing direct chemical purchasing by in-house maintenance staff. This authority shift is most visible in metropolitan hospital systems where GPO-negotiated contracts now specify chemistry-dispensing-service bundles rather than product-only supply agreements.
Industrial and Institutional (Iandi) Cleaning Chemicals Market Segmentation
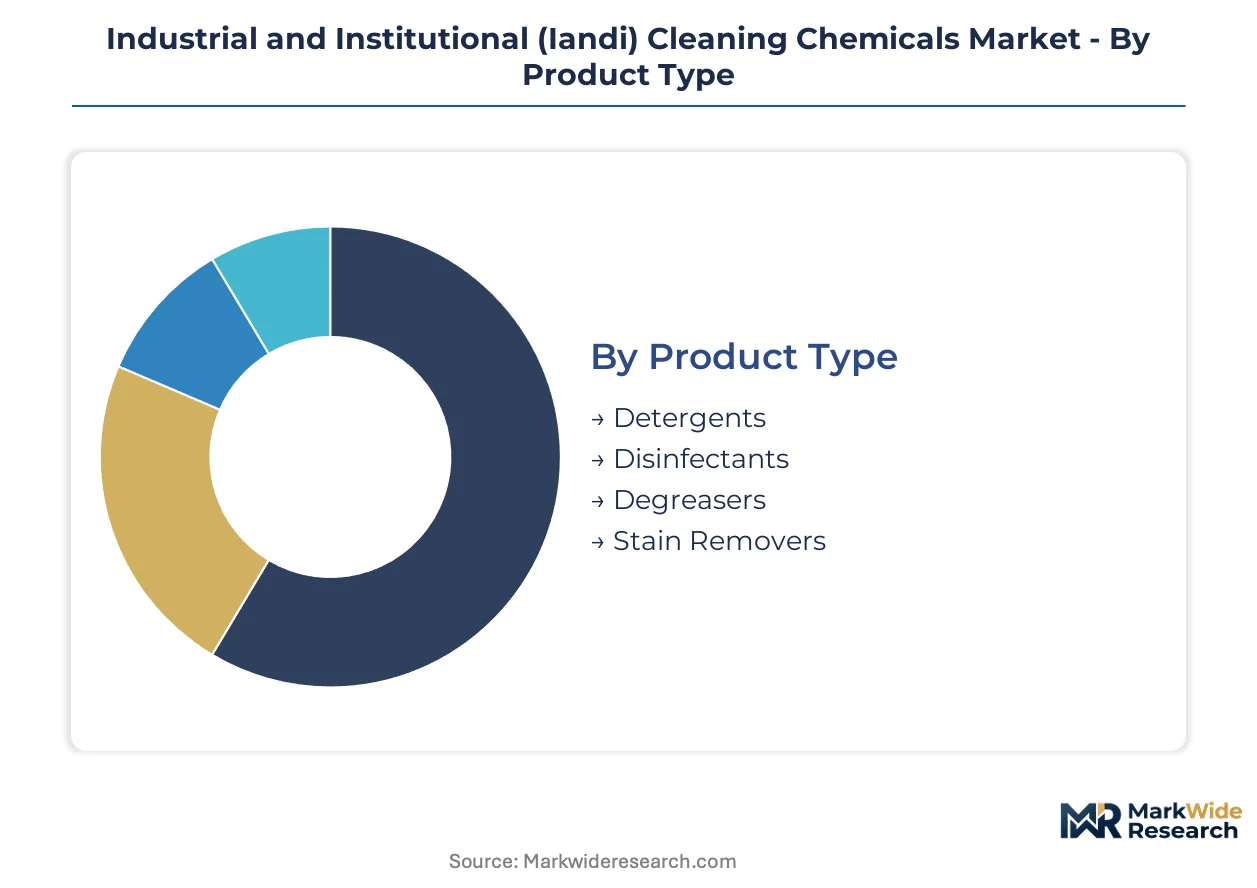
Segmentation in the Iandi cleaning chemicals market determines procurement pathways, formulation requirements, and service intensity. Product type dictates regulatory compliance burden. Application verticals enforce distinct microbiological validation standards. End user classification shapes contract structure and dispensing infrastructure investment. Formulation choice locks in supply chain economics and automation compatibility.
Product Type:
After-sales-service intensity peaks with disinfectants due to EPA FIFRA registration support, efficacy validation documentation, and Joint Commission audit preparation requirements.
- Detergents:Surfactant-based formulations engineered for soil suspension and emulsification across pH-neutral to alkaline ranges. Demand concentrates in United States food processing plants where USDA sanitation protocols mandate documented cleaning verification. Service contracts bundle automated dilution equipment calibration with quarterly surfactant efficacy testing.
- Disinfectants:EPA-registered antimicrobial actives including quaternary ammonium compounds, sodium hypochlorite, and accelerated hydrogen peroxide. Healthcare facilities in Germany enforce sporicidal claims for C. difficile containment, driving hospital-grade procurement with 24-month registration maintenance obligations. Service intensity includes outbreak response protocols and staff training recertification.
- Degreasers:Solvent-heavy or enzymatic formulations targeting petroleum-based and protein soils in industrial maintenance.
- Stain Removers:Specialty surfactant blends with oxidizing or reducing agents for textile and carpet applications.
Detergents hold the largest share; momentum sits with disinfectants as healthcare sanitation mandates tighten across multiple jurisdictions.
Application:
Cost tier stratification separates commodity cleaning from premium validated formulations where regulatory documentation commands price premiums.
- Food Processing:Sanitation chemistry compliant with FDA Food Safety Modernization Act preventive controls and HACCP documentation. Meatpacking operations in the Netherlands adopt enzymatic degreasers to reduce water consumption while maintaining USDA-equivalent export standards. Volume contracts specify lot traceability and allergen control protocols.
- Healthcare Facilities:EPA-registered hospital-grade disinfectants with sporicidal, virucidal, and fungicidal claims validated per ASTM test methods. United States metropolitan hospital systems consolidate procurement through GPO-negotiated bundles including dispensing equipment, compliance software, and infection control consulting. Joint Commission surveys elevate documentation requirements above commodity pricing.
- Hospitality:Guest-facing sanitation with fragrance and residue specifications driving brand differentiation.
- Educational Institutions:Budget-constrained procurement favoring concentrated formats with simplified dilution protocols for custodial staff.
Food processing commands the highest per-site chemical expenditure; healthcare facilities are expanding most quickly as post-pandemic sanitation protocols institutionalize.
End User:
Customer type determines contract structure, with manufacturing favoring multi-year equipment-integrated supply agreements.
- Manufacturing:Industrial maintenance and process equipment cleaning with OSHA Hazard Communication Standard compliance documentation. Automotive assembly plants in China specify low-residue formulations compatible with precision component handling. Contracts bundle chemical supply with wastewater treatment chemistry integration.
- Retail:Store-level sanitation with simplified dispensing and reduced training requirements for high-turnover staff.
- Services:Facility management outsourcing consolidating procurement authority into integrated service contracts.
- Transportation:Fleet maintenance and terminal sanitation with specialized formulations for fuel residue and biological contamination.
Manufacturing holds the largest share; services are climbing the fastest as third-party operators displace direct purchasing across healthcare and education verticals.
Formulation:
Supply concentration in liquid concentrates reflects installed base of automated dilution infrastructure and IoT-enabled dispensing systems.
- Liquid:Pumpable concentrates and ready-to-use solutions compatible with automated dilution controllers and chemical proportioning systems. Food processing plants in the United States deploy IoT-enabled dispensers that lock in supply contracts through equipment financing structures. Freight economics favor local blending operations.
- Powder:Concentrated solid formats with cost advantages in freight-intensive supply chains and extended shelf stability.
- Aerosol:Pressurized delivery for targeted application and reduced overspray in confined mechanical spaces.
- Gel:Cling formulations extending contact time on vertical surfaces and complex equipment geometries.
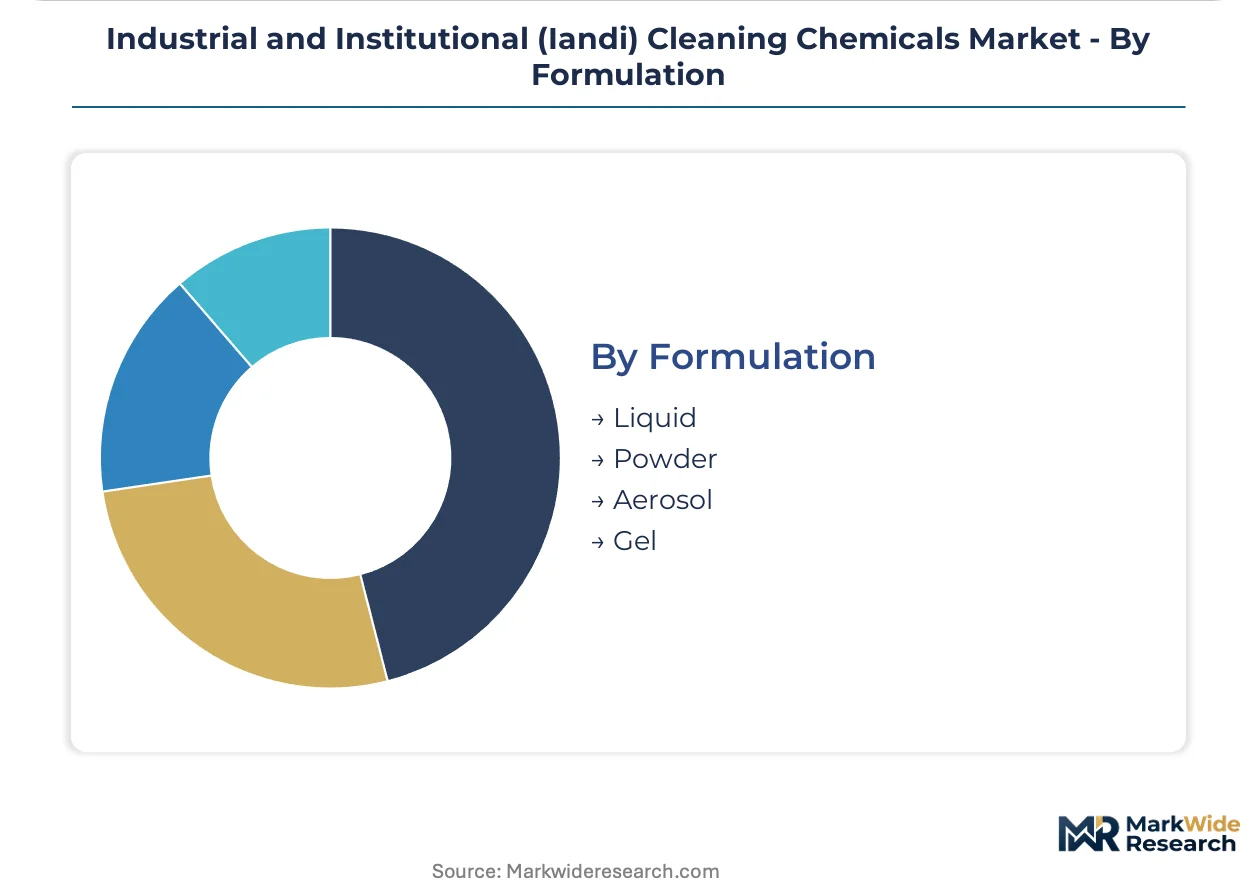
Liquid holds the largest share; powder is gaining share fastest as sustainability mandates elevate concentrated format adoption for reduced packaging and transport emissions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems, food processors, and third-party facility operators drive procurement intensity across concentrated industrial corridors. Buyer archetypes cluster where regulatory enforcement is strictest and automation infrastructure is deepest.
United States
Healthcare GPOs consolidate disinfectant purchasing for metropolitan hospital systems in Chicago, Houston, and Atlanta. EPA FIFRA registration requirements lock out unregistered suppliers from Joint Commission-audited facilities. Meatpacking corridors in Nebraska and Iowa specify USDA-validated sanitation chemistry with automated dilution systems.
Germany
REACH Article 57 restrictions accelerate quaternary ammonium compound substitution in Bavarian dairy processing and North Rhine-Westphalian industrial laundries. ECHA biocidal product authorization timelines compress supplier qualification cycles. Stuttgart automotive clusters specify low-residue maintenance chemistry compatible with precision assembly environments.
China
Food Safety Law enforcement tightens sanitation documentation for Yangtze River Delta processors exporting to EU and US markets. SAMR registration requirements for disinfectant manufacturers concentrate supply among licensed formulators. Shandong Province chemical parks integrate surfactant production with downstream blending operations for domestic institutional channels.
Netherlands
Enzymatic degreaser adoption scales in Rotterdam port logistics and Utrecht food service distribution. EU Green Deal procurement directives favor bio-based surfactants in public institutional contracts. Eindhoven high-tech manufacturing specifies residue-controlled precision cleaning for semiconductor equipment maintenance.
India
FSSAI sanitation mandates expand qualified supplier lists for Maharashtra and Gujarat food processing zones. BIS certification requirements for industrial disinfectants create entry barriers for unregistered imports. Bangalore pharmaceutical manufacturing clusters drive hospital-grade chemistry specification for cleanroom environments.
Industrial and Institutional (Iandi) Cleaning Chemicals Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority. Integrated service providers anchor long-term contracts through equipment financing and compliance documentation bundles. Product-centric formulators compete on surfactant chemistry scale and EPA registration portfolios. Strategic moves concentrate on M&A for geographic density and strategic partnerships for IoT-enabled dispensing infrastructure.
Among integrated service providers, Ecolab and Diversey Holdings occupy positions where water-chemistry-service bundling locks in institutional contracts. BASF SE anchors the active ingredient supply tier, supplying surfactant chemistry to private-label formulators across multiple verticals. These three exemplify the archetype split between channel control, formulation scale, and upstream chemical supply.
| Leading Market Players |
|---|
| Ecolab |
| Procter & Gamble |
| BASF SE |
| The Clorox Company |
| Diversey Holdings |
| Clariant |
| Dow |
| Henkel AG & Co. KGaA |
| 3M |
| Others |
Supply & Pricing Matrix
Shandong Province chemical parks concentrate surfactant precursor capacity that feeds downstream pricing power to liquid concentrate blenders across Asia-Pacific institutional channels. REACH-driven reformulation cycles in Europe and EPA registration maintenance in the United States create divergent cost structures that stratify procurement tiers by compliance burden rather than commodity chemistry alone.
Pricing Analysis
Certification level creates the primary spread between hospital-grade EPA-registered disinfectants and commodity maintenance cleaners. Three-tier pricing structure across premium, standard, and economy levels reflects FIFRA registration status, automated dispensing equipment bundling, and outbreak response service inclusion. Cost compression in mid-tier surfactant blends is intensifying because Chinese quaternary ammonium compound manufacturers face export documentation delays. Food processing plants show least price sensitivity due to HACCP audit failure costs, while educational institutions prioritize concentrated powder formats with minimal service attachment.
Supply Chain Analysis
Export-control scrutiny on dual-use chemical precursors limits flows of ethylene oxide derivatives from Chinese state-owned enterprises to European formulators. Supply concentrates in China, Germany, and the United States for surfactant actives, with Shandong and Bavarian chemical parks anchoring regional blending. Feedstock draws from petrochemical crackers and bio-based fermentation capacity. Single-source vulnerability concentrates in quaternary ammonium compound precursors where three Chinese producers control majority output. Distribution runs through integrated service contracts bundling chemical supply with IoT-enabled dispensing infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated dispensing platform economics are consolidating procurement authority into chemistry-equipment-service bundles that reward ecosystem interoperability over standalone formulation quality. Interoperability between chemical concentrate RFID tagging and facility management software is becoming the lock-in mechanism.
For Market Incumbents: Pre-empt electrolyzed water and ozone generation displacement by embedding predictive maintenance algorithms into existing dispensing infrastructure. Backward integration into bio-based surfactant fermentation capacity insulates margin structures from REACH-driven precursor scarcity. Lock hospital system GPO contracts through Joint Commission audit preparation services that entrench switching costs. For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical manufacturing cleanroom chemistry where BIS certification barriers filter out unregistered imports. Target enzymatic degreaser white space in Netherlands food service distribution where EU Green Deal procurement directives favor bio-based surfactants. Lead with solid tablet concentrate formats that bypass installed liquid infrastructure in freight-intensive emerging markets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors facility management outsourcing consolidators with captive chemical procurement authority. Long-term viability hinges on IoT-enabled dispensing platform penetration rather than formulation patents alone. Acquisition target archetype: regional service providers with dense healthcare GPO relationships and underutilized EPA registration portfolios. Signal to watch: state-level PFAS restriction acceleration forcing fluorine-free reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Surfactants | REACH Article 57 compliance secures biocidal product authorization continuity for European healthcare formulators. |
| IoT-Enabled Dispensing Platform Deployment | Equipment financing structures lock food processing plants into recurring concentrate supply contracts with switching penalties. |
| EPA FIFRA Registration Portfolio Expansion | Hospital-grade sporicidal claims open Joint Commission-audited metropolitan health system procurement channels. |
| Enzymatic Formulation R&D Partnership | Lipase and protease systems reduce water consumption in German meatpacking operations while maintaining USDA-equivalent standards. |
| Facility Management Outsourcing Acquisition | Third-party operators displace direct chemical purchasing across United States education and healthcare verticals. |
Research Methodology
Desk research of EPA FIFRA registration databases, ECHA biocidal product authorization filings, and customs trade flow data preceded structured interviews with chemical plant managers, healthcare procurement directors, and facility management outsourcing executives. Primary fieldwork validated surfactant blender margin structures and automated dispensing equipment financing terms. Secondary sources included SEC 10-K filings of integrated service providers, Cefic chemical industry reports, and GPO contract disclosure documents. Bottom-up volume modeling triangulated against top-down market sizing across product type and application verticals.
Assumptions held fixed include current EPA and REACH regulatory enforcement intensity, petrochemical feedstock availability from existing crackers, and installed base of liquid dispensing infrastructure. The analytical framework modeled demand across the projection horizon by detergent, disinfectant, degreaser, and stain remover categories; food processing, healthcare, hospitality, and education applications; liquid, powder, aerosol, and gel formulation formats; and manufacturing, retail, services, and transportation end users. CAGRs derived from segment-level volume trajectories weighted by regulatory compliance cost pass-through elasticity and automation adoption curves.
Macroeconomic conditions sit as an overlay; deviation in industrial production indices, freight rate volatility, or healthcare capital expenditure cycles would shift the trajectory. Material shifts in EPA FIFRA registration timelines, ECHA restriction scope expansion, or Chinese export license enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Mastic Remover Market
Cleaning Chemicals
Mosquito Repellent Market
Cleaning Chemicals
Low-Foaming Detergent Market
Cleaning Chemicals
Biodegradable Spray Tank Line-Cleaning Chemistry Market
Cleaning Chemicals
Industrial Cleaners Market
Cleaning Chemicals
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market
Cleaning Chemicals
Latin America Detergent Market
Cleaning Chemicals
Descaler Market
Cleaning Chemicals
Chlorinating Agents Market
Cleaning Chemicals
Cleaning Fluids Market
Cleaning Chemicals
Global Antiseptic Products Market
Cleaning Chemicals
Mask Reticle Cleaning Agent Market
Cleaning Chemicals
Global Metal Cleaning Chemicals Market
Cleaning Chemicals
Micellar Cleansing Water Market
Cleaning Chemicals
Cleaning Nozzles Market
Cleaning Chemicals
Southeast Asia Surface Treatment Chemicals Market