
 Chlorinating Agents Market | 2026-2036
Chlorinating Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorinating Agents Market Analysis
Chinese chlor-alkali producers is expanding merchant chlorine capacity to serve downstream chlorinating agent derivatives. Nouryon leverages integrated salt-to-chlorine infrastructure across Northern Europe to sustain cost-advantaged supply positions. Olin Corporation anchors North American bleach and disinfectant supply through its Gulf Coast chlor-alkali network. Evonik Industries AG specializes in high-purity organic chlorine intermediates for European pharmaceutical and agrochemical synthesis.
Chlorinating agents encompass chlorine-derived compounds employed to introduce chlorine atoms into organic substrates or to disinfect water matrices, typically requiring active chlorine concentrations above 5% for effective microbial inactivation. Sodium hypochlorite dominates municipal water treatment volumes due to safer handling profiles versus compressed chlorine gas, though calcium hypochlorite tablets are displacing liquid alternatives in decentralized rural systems across Sub-Saharan Africa and South Asia. Organic chlorine compounds command premium pricing in pharmaceutical intermediate applications where halogenation specificity determines yield economics. Pulp and paper bleaching represents a mature, contracting segment as oxygen-based delignification reduces chlorine dependency in Nordic and Canadian mills.
The EPA regulates maximum residual disinfectant levels under the Safe Drinking Water Act, while the EU BPR restricts biocidal chlorine product formulations containing hazardous impurities. India's BIS certification mandates minimum available chlorine content for commercial hypochlorite products sold to municipal buyers. Stakeholders must monitor evolving DBP regulations that could restrict traditional chlorination in favor of mixed oxidant systems.
Market Dynamics
Merchant chlorine supply concentration along China's coastal chlor-alkali corridor is compressing regional cost curves and forcing derivative producers to secure long-term offtake agreements. This supply-side consolidation interacts with tightening effluent standards across South Asian manufacturing belts to reshape procurement patterns.
Growth Catalysts
- EPA Stage 2 DBP Rule:Tighter chloramine residual limits in US municipal systems are accelerating adoption of precision dosing equipment and alternative oxidant blends.
- Textile effluent mandates:India's CPCB is enforcing zero-liquid-discharge norms across Gujarat and Tamil Nadu industrial clusters, expanding hypochlorite demand for tertiary treatment.
- Decentralized water access:Calcium hypochlorite tablet formats are penetrating rural distribution networks in Kenya, Nigeria, and Bangladesh where liquid logistics fail.
Market Restraints
- Electrolysis energy intensity:Chlor-alkali production remains tethered to volatile natural gas and power tariffs, squeezing margin visibility for merchant chlorine suppliers.
- Disinfection byproduct liability:Trihalomethane formation in surface water treatment is triggering litigation exposure and insurance cost escalation for municipal utilities.
- Oxygen delignification substitution:Nordic and Canadian pulp mills are retiring elemental chlorine bleaching sequences, eroding a historical volume anchor.
Strategic Opportunities
- Indonesia's pharmaceutical corridor:Batam and Banten provinces are attracting API manufacturing investment, creating demand for high-purity organic chlorinating intermediates.
- On-site generation systems:Brine electrolysis units are eliminating transport risk for remote mining camps and offshore platforms in Chilean and Peruvian operations.
- EU BPR biocidal authorization:Streamlined substance approval pathways for active chlorine compounds are lowering regulatory entry barriers for specialty disinfectant formulators.
Industry Challenges
- Halogenation chemist scarcity:European and North American universities are shuttering organochlorine synthesis programs, constraining R&D pipeline staffing for agrochemical innovators.
- Legacy infrastructure retrofit:Converting compressed chlorine gas facilities to hypochlorite or on-site generation requires extended outage windows that utilities struggle to schedule.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorinating Agents Market |
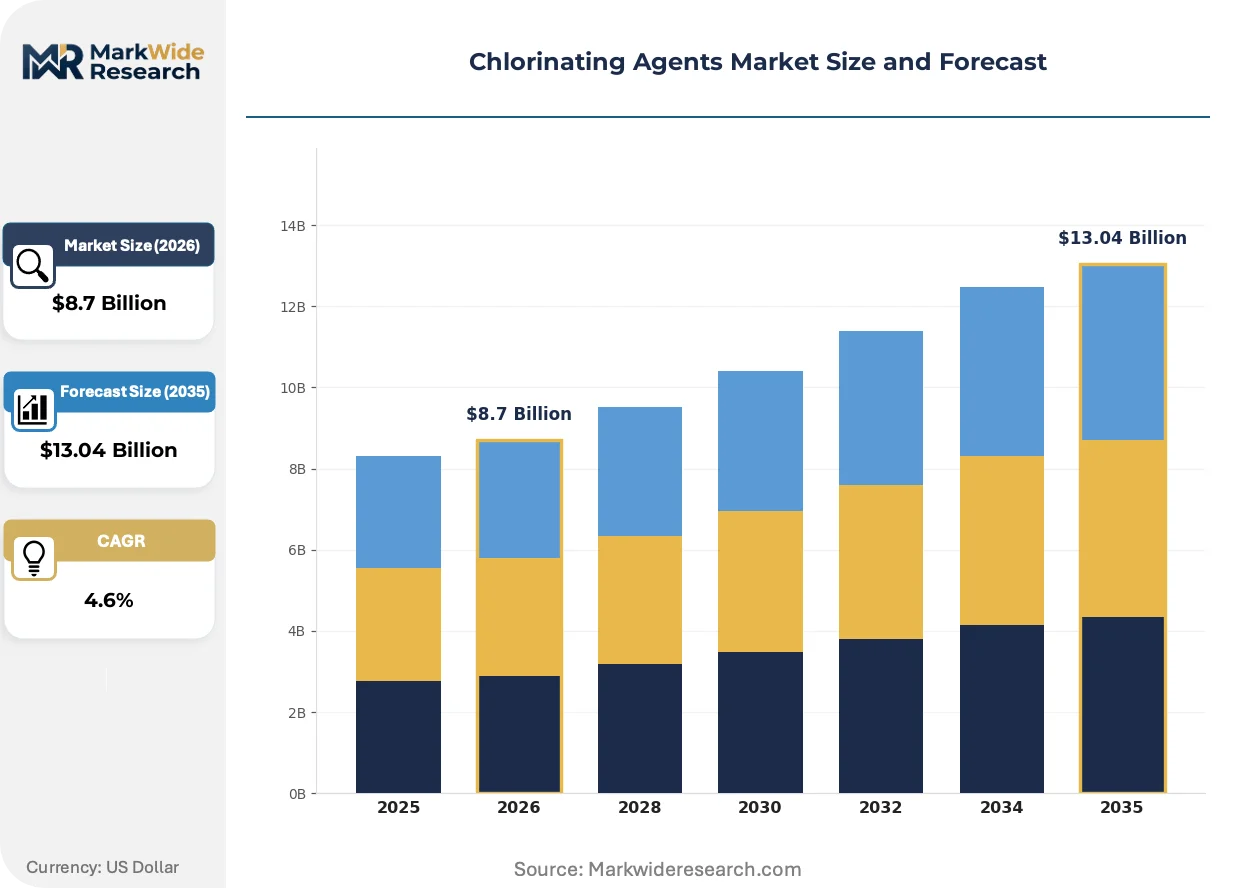
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Hypochlorite, Calcium Hypochlorite, Chlorine Gas, Organic Chlorine Compounds Application: Water Treatment, Wastewater Treatment, Swimming Pools, Pulp & Paper End User: Municipalities, Industrial Plants, Residential Users, Commercial Establishments Form: Liquid, Granular, Gas, Tablet |
| Companies Covered | Nouryon, DIC Corporation, BASF SE, HPL Additives Limited, AGC Chemicals, Olin Corporation, PPG Industries, Inc., Evonik Industries AG, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorinating Agents Market Emerging Trajectories
Electrochemical process intensification and regulatory chemistry are compressing traditional batch chlorination workflows. Three interconnected developments are altering competitive positioning across municipal, industrial, and pharmaceutical end-uses.
Membrane cell electrolysis is expanding into mid-scale hypochlorite production previously served by bulk merchant supply. Water utilities in Australia's Queensland and Western Australia are deploying containerized brine-to-bleach units to eliminate chlorine gas transport through population centers. This distributed architecture is expanding into remote industrial sites where logistics costs previously blocked continuous disinfection.
REACH authorization requirements for persistent organic pollutants are forcing reformulation of chlorinated biocidal products across EU member states. Manufacturers must substitute legacy chlorinated phenols and solvents with biodegradable alternatives or secure costly sunset authorization extensions. The pharmaceutical intermediate segment is responding by shifting halogenation steps to contract manufacturers in Switzerland and the United Kingdom with established substance dossiers.
Performance-based service contracting is displacing commodity chemical procurement in large-scale municipal systems. French and German water operators are bundling chlorine residual guarantees with equipment maintenance, transferring dosing optimization risk to chemical suppliers. This model concentrates in metropolitan utilities with consolidated treatment plant portfolios and real-time monitoring infrastructure.
Chlorinating Agents Market Segmentation
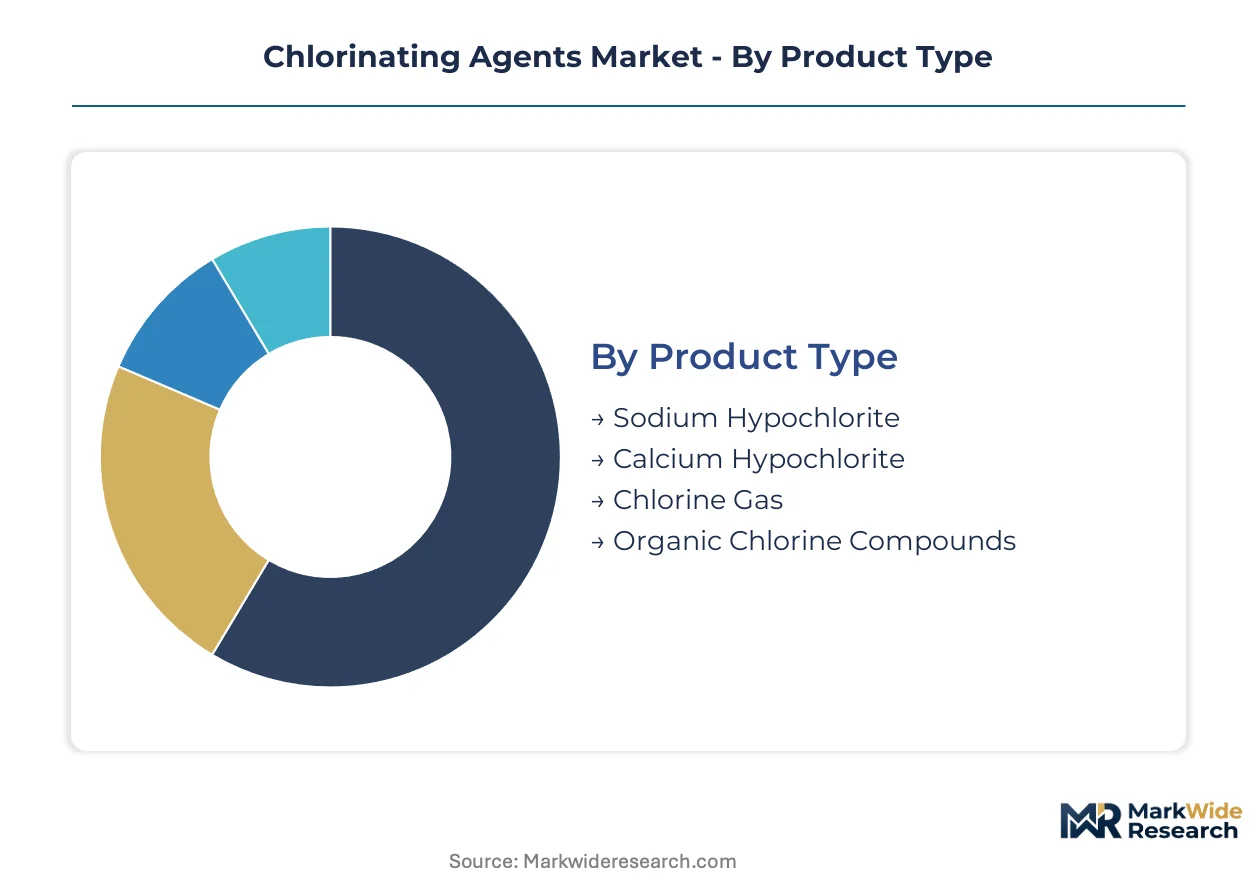
Segmentation in chlorinating agents reveals how supply chain configuration, regulatory constraints, and end-use specifications fragment procurement patterns across municipal, industrial, and consumer channels. Understanding these divides clarifies where margin pools concentrate and where volume growth shifts.
Product Type:
Merchant chlorine supply concentration along coastal chlor-alkali corridors determines cost positioning across derivative categories.
- Sodium Hypochlorite:Aqueous solution typically containing 5-15% available chlorine by weight, stabilized with excess caustic to prevent decomposition. Municipal utilities in the United States favor this format under EPA Stage 2 DBP Rule pressures that discourage chloramine formation. Handling protocols eliminate compressed gas risks.
- Calcium Hypochlorite:Solid granules or tablets with 65-70% available chlorine content, offering superior stability in tropical storage conditions. Kenya, Nigeria, and Bangladesh deploy tablet formats in rural distribution networks where liquid logistics infrastructure fails. Decentralized water access programs drive procurement.
- Chlorine Gas:Compressed elemental chlorine delivered in tonnage cylinders or railcars for large-scale continuous dosing. Legacy municipal installations in Germany and France retain this infrastructure despite conversion pressures.
- Organic Chlorine Compounds:High-purity halogenating reagents including sulfuryl chloride and N-chlorosuccinimide for pharmaceutical intermediate synthesis. Switzerland and United Kingdom contract manufacturers maintain REACH-compliant substance dossiers.
Sodium hypochlorite absorbs the bulk of installed capacity; calcium hypochlorite is expanding most quickly.
Application:
End-use maturity curves diverge sharply, with oxygen-based substitution eroding legacy volume anchors while effluent mandates create new demand pockets.
- Water Treatment:Municipal drinking water disinfection represents the foundational volume driver, governed by maximum residual disinfectant levels under the Safe Drinking Water Act in the United States. Australia's Queensland deploys containerized brine-to-bleach units to eliminate transport risk through population centers.
- Wastewater Treatment:Tertiary disinfection and effluent polishing for industrial discharge compliance. India's CPCB enforces zero-liquid-discharge norms across Gujarat and Tamil Nadu textile clusters, expanding hypochlorite procurement.
- Swimming Pools:Residential and commercial aquatic facility maintenance with stabilized chlorine products. Seasonal demand concentration in Mediterranean climates.
- Pulp & Paper:Bleaching sequences in Nordic and Canadian mills. Oxygen delignification is retiring elemental chlorine stages, contracting this segment.
Water treatment commands the dominant share of chemical throughput; wastewater treatment is climbing the fastest.
End User:
Procurement sophistication and contract structure vary dramatically across customer types, from performance-based service bundling to spot commodity purchasing.
- Municipalities:Consolidated metropolitan utilities with real-time monitoring infrastructure. French and German operators bundle residual guarantees with equipment maintenance, transferring dosing optimization risk to suppliers.
- Industrial Plants:Textile, pharmaceutical, and chemical manufacturing facilities with effluent discharge permits. India's industrial corridor states concentrate demand under tightening CPCB mandates.
- Residential Users:Swimming pool owners and household water treatment adopters. Price-sensitive, brand-loyal purchasing through retail channels.
- Commercial Establishments:Hotels, hospitals, and food processing facilities with hygiene audit requirements. Intermediate volume scale between municipal and residential.
Municipalities anchor procurement volume; industrial plants are gaining share fastest.
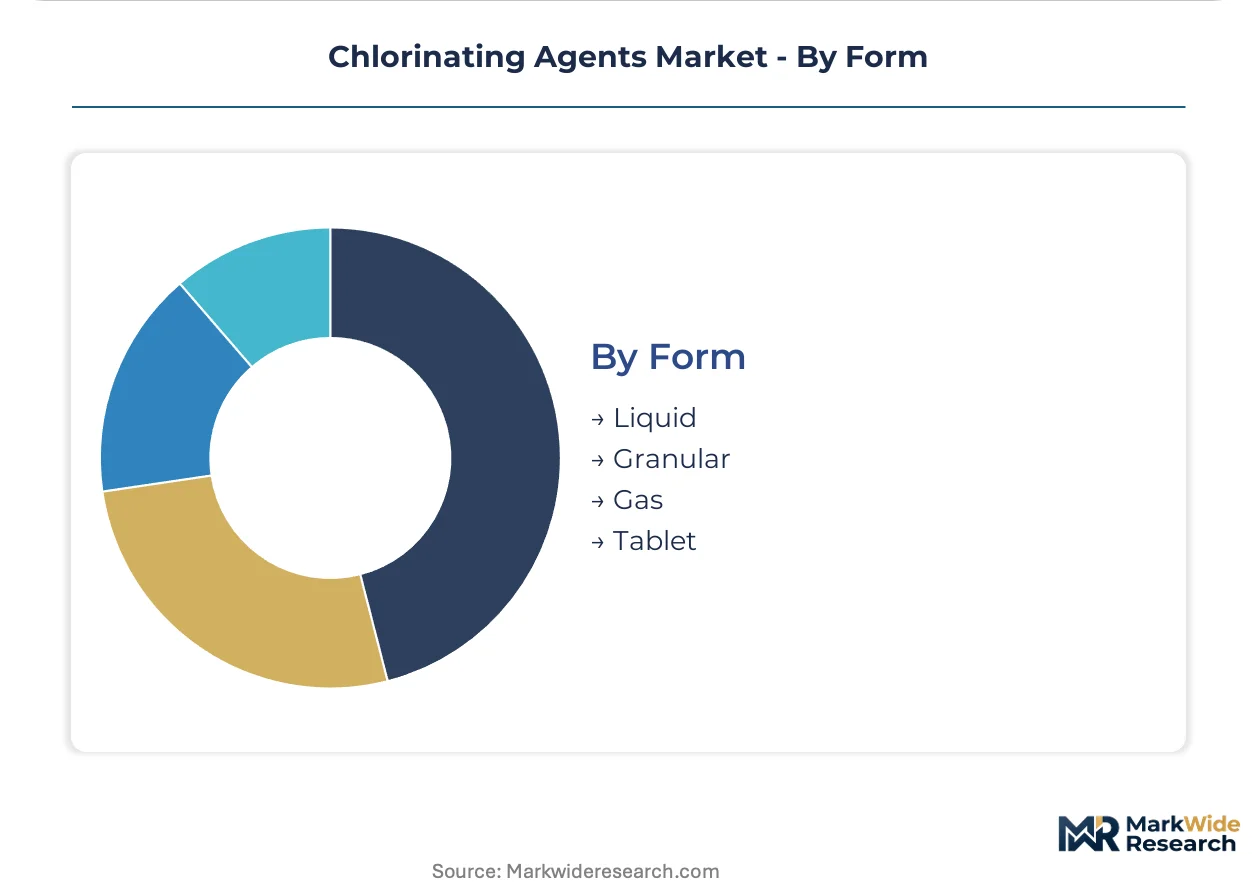
Form:
Physical state dictates logistics economics, safety protocols, and storage depreciation rates across distribution networks.
- Liquid:Bulk tanker and drum deliveries for continuous dosing systems. Dominates municipal and large industrial accounts with established handling infrastructure.
- Granular:Free-flowing calcium hypochlorite for dissolution-fed applications. Intermediate stability between liquid and tablet formats.
- Gas:Compressed chlorine in pressure vessels for high-volume continuous users. Declining share due to security and liability concerns.
- Tablet:Compressed calcium hypochlorite for point-of-use and remote deployment. Kenya, Nigeria, and Bangladesh rural networks favor this format.
Liquid form holds the majority of throughput; tablet form shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Salt deposits along coastal Gujarat and the chlor-alkali corridor of Shandong Province anchor regional supply positioning. Demand trajectories diverge sharply between mature regulatory regimes and emerging industrial clusters.
United States
Municipal utilities confront EPA Stage 2 DBP Rule limits on chloramine residuals. The Safe Drinking Water Act enforcement is accelerating precision dosing equipment procurement. Gulf Coast chlor-alkali infrastructure sustains merchant chlorine supply for downstream bleach and disinfectant manufacturing.
Germany
REACH authorization requirements for persistent organic pollutants are forcing biocidal product reformulation. The ECHA sunset clause deadlines are compressing reformulation timelines. North Rhine-Westphalia's integrated chemical parks maintain halogenation capacity for pharmaceutical intermediate synthesis.
China
Merchant chlorine capacity expansion along the coastal chlor-alkali corridor is compressing regional cost curves. The MEE effluent discharge standards are tightening across the Yangtze River Delta. Shandong Province's salt-to-chlorine infrastructure feeds downstream chlorinating agent derivative production.
India
CPCB zero-liquid-discharge mandates are expanding hypochlorite procurement across Gujarat and Tamil Nadu textile clusters. The BIS certification requirement for minimum available chlorine content is standardizing municipal procurement. Maharashtra's pharmaceutical corridor is attracting API manufacturing investment requiring high-purity organic chlorinating intermediates.
Australia
Containerized brine-to-bleach units are eliminating chlorine gas transport through Queensland population centers. The country's national drinking water regulator is tightening residual disinfectant monitoring protocols. Western Australia's remote mining camps are deploying on-site generation systems to bypass bulk chemical logistics.
Chlorinating Agents Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue electrochemical process intensification and service-based contracting models. The market structure consolidates around integrated chlor-alkali operators with captive salt resources and downstream derivative capacity. Three archetypes dominate: integrated salt-to-chlorine majors, specialty organic halogenation specialists, and regional bleach formulators with distribution density. Competitive moves center on long-term offtake agreements with municipal utilities and backward integration into salt mining assets.
Within the integrated infrastructure tier, Nouryon and Olin Corporation exemplify cost-advantaged positioning through captive supply chains. Specialty organic chlorine intermediates are represented by Evonik Industries AG, which occupies a position in European pharmaceutical and agrochemical synthesis. These three anchors demonstrate how supply chain configuration and regulatory compliance capability separate margin tiers in differentiated applications.
| Leading Market Players |
|---|
| Nouryon |
| DIC Corporation |
| BASF SE |
| HPL Additives Limited |
| AGC Chemicals |
| Olin Corporation |
| PPG Industries, Inc. |
| Evonik Industries AG |
| Dow |
| Others |
Supply Flow & Price Mechanics
Membrane cell electrolysis adoption is compressing production economics for mid-scale hypochlorite while redistributing supply concentration toward coastal chlor-alkali corridors with captive salt access. This technology shift simultaneously erodes legacy merchant chlorine premiums and rewards integrated producers with backward control over brine feedstock.
Pricing Analysis
Service bundling now separates municipal contract winners from commodity suppliers, with residual guarantees and equipment maintenance packages commanding 15-25% premiums over unbundled chemical delivery. Price differentiation rests on REACH dossier completeness for EU biocidal applications and BIS certification tier for Indian municipal tenders. Cost compression in standard-grade sodium hypochlorite is intensifying because Chinese coastal capacity expansion is flooding Asian spot markets. Industrial textile processors in Gujarat and Tamil Nadu exhibit the sharpest price sensitivity, while pharmaceutical API manufacturers in Switzerland and the United Kingdom prioritize halogenation specificity over unit cost.
Supply Chain Analysis
Freight cost differentials of 40-60% between liquid bulk tankers and compressed gas railcars are accelerating format shifts across distribution networks. Supply concentrates in China, India, and Germany, with Shandong Province's salt-to-chlorine infrastructure feeding downstream derivative production. Raw material flows draw from rock salt deposits, caustic soda merchant supply, and electricity contracts tethered to volatile natural gas tariffs. Single-source vulnerability runs through China's coastal chlor-alkali corridor, where MEE effluent enforcement is shuttering marginal capacity. Distribution runs through long-term offtake agreements with municipal utilities, spot procurement by industrial accounts, and tablet-format rural networks in Sub-Saharan Africa and South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated salt-to-chlorine operators as electrolysis energy intensity squeezes standalone merchant chlorine margins and forces weaker players toward acquisition or exit.
For Market Incumbents: To counter oxygen delignification erosion in Nordic and Canadian pulp markets, deepen backward integration into Gujarat and Shandong salt mining assets while securing decade-long municipal offtake agreements in India's CPCB-enforced textile corridors. Anchor defensive positioning through REACH-compliant substance dossiers that emerging competitors cannot replicate before ECHA sunset deadlines. For New Entrants and Emerging Players: Enter via on-site brine electrolysis systems for Chilean and Peruvian remote mining camps, where logistics costs have historically blocked continuous disinfection adoption. Target Indonesia's Batam-Banten pharmaceutical corridor for high-purity organic chlorinating intermediates, leveraging contract manufacturing relationships with established REACH dossier holders. Lead with performance-based residual guarantees rather than commodity chemical positioning. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale electrochemical technology specialists given membrane cell process intensification tailwinds and municipal conversion demand from compressed gas infrastructure. Long-term viability favors producers with captive salt resources and downstream derivative integration across multiple end-use segments. Watch for inflection in India's zero-liquid-discharge enforcement intensity across Gujarat and Tamil Nadu textile clusters as a demand acceleration signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Salt Mining | Gujarat and Shandong brine access secures cost-advantaged chlorine feedstock for derivative production. |
| Long-term Municipal Offtake Agreements | French and German performance-based contracting transfers dosing optimization risk from utilities to suppliers. |
| On-site Brine Electrolysis Deployment | Queensland containerized units eliminate chlorine gas transport liability through population centers. |
| REACH Dossier Investment | EU BPR biocidal authorization lowers regulatory entry barriers for specialty disinfectant formulators. |
| Tablet Format Distribution Expansion | Kenya and Bangladesh rural networks favor calcium hypochlorite tablets where liquid logistics fail. |
Methodological Framework
Multi-period observation of chlor-alkali capacity utilization, merchant chlorine price indices, and municipal procurement contract structures anchored the trend analysis, supplemented by interviews with plant managers at integrated salt-to-chlorine facilities, procurement leads at Indian textile processors, distribution channel partners in Sub-Saharan Africa, and technical R&D directors at European pharmaceutical intermediate specialists. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings by listed chemical producers, and EPA enforcement action databases. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Input-output matrices modeled chlorine derivative demand against salt mining capacity, electrolysis energy costs, and regulatory compliance thresholds across product type, application, end user, and physical form dimensions. CAGRs were derived from segment-level volume trajectories and value-per-unit trends. Forecast inputs incorporated CPCB effluent mandate enforcement timelines, ECHA sunset authorization schedules, and oxygen delignification adoption curves in Nordic and Canadian pulp markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden natural gas price spikes, accelerated DBP regulation in US municipal systems, or unanticipated MEE enforcement waves across China's Yangtze River Delta. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Latin America Detergent Market
Cleaning Chemicals
Housekeeping Chemicals for Hotels and Resorts Market
Cleaning Chemicals
Dry Cleaning Solvents Market
Cleaning Chemicals
Dust and Emission Control Chemicals for Ore Handling Market
Cleaning Chemicals
Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market
Cleaning Chemicals
South Africa Cleaning Products Market
Cleaning Chemicals
Electrostatic Liquid Cleaner Market
Cleaning Chemicals
Sanitizing Agents Market
Cleaning Chemicals
Fabric Conditioner Market
Cleaning Chemicals
Lens Cleaning Product Market
Cleaning Chemicals
Micellar Cleansing Water Market
Cleaning Chemicals
Cleaning Products Market
Cleaning Chemicals
Europe Metal Cleaning Chemicals Market
Cleaning Chemicals
Soap and Detergent Market
Cleaning Chemicals
Global Antiseptic Products Market
Cleaning Chemicals
Cleaning Chemicals Market