
 Soap and Detergent Market | 2026-2036
Soap and Detergent Market Size, Share, and Industry Trends Forecast 2026-2036
Soap and Detergent Market Intelligence
The European Union's regulatory push for biodegradable surfactants and reduced phosphate content is recalibrating product formulation strategies across the industry. Procter & Gamble leverages its significant R&D budget to innovate concentrated liquid detergents that meet these new standards. Unilever sustains a strong market presence through its diverse brand portfolio catering to various price points. Henkel positions itself as a key supplier in the industrial cleaning segment with specialized, high-performance formulations.
Soaps and detergents are chemical compounds or mixtures that act as cleaning agents. Soaps are sodium or potassium salts of fatty acids, while detergents are synthetic surfactants, often derived from petrochemicals, designed to lower the surface tension of water. Their primary function is to emulsify oils and suspend dirt, allowing for removal from surfaces. The market's product landscape shows liquid detergents gaining share from traditional powder detergents due to user convenience. The household end-user segment continues to command the largest volume share globally.
Regulatory frameworks heavily influence ingredient selection and market access. In the United States, the EPA's Safer Choice program certifies products with environmentally friendly ingredients. The EU's REACH regulation governs the use of chemical substances, impacting detergent formulations. In China, GB standards set mandatory requirements for performance and safety. These regulations compel manufacturers to invest in compliant and transparent supply chains. Stakeholders must now balance the performance expectations of consumers with evolving sustainability mandates and cost pressures.
Market Dynamics
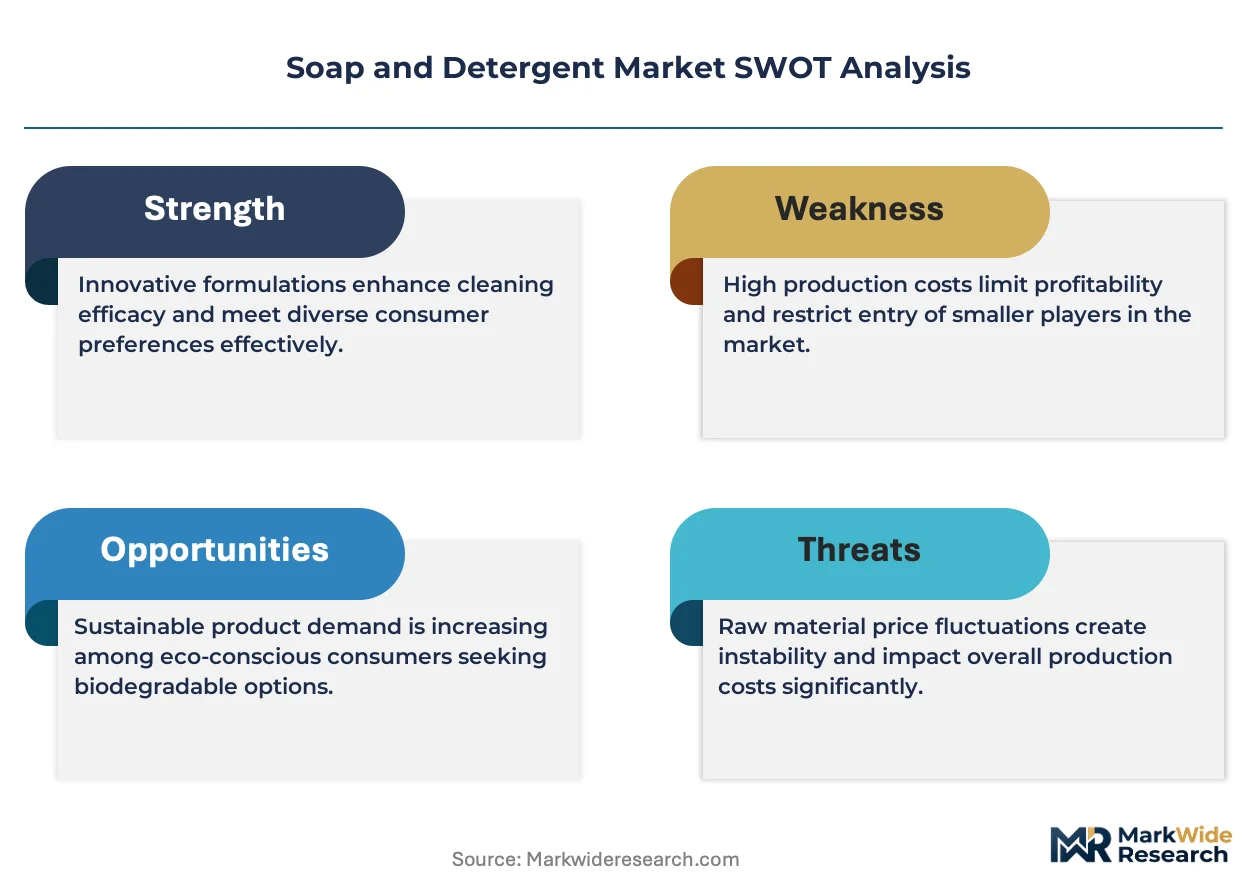
The central dynamic shaping the soap and detergent market is the tension between escalating sustainability mandates and persistent consumer demand for high-performance cleaning at a low cost. This conflict forces manufacturers to innovate within tightening regulatory and raw material constraints, particularly balancing petrochemical-based surfactants with emerging bio-based alternatives.
Growth Catalysts
- Regulatory Mandates:The EU Green Deal and its associated chemical strategies are compelling a shift towards biodegradable surfactants and phosphate-free formulations, creating demand for compliant, next-generation cleaning products across Europe.
- Hygiene Awareness in Emerging Economies:Rising disposable incomes and public health initiatives in countries like India and Brazil are expanding the market for household cleaning products, especially in rapidly urbanizing areas.
- Industrial Sector Expansion:Growth in the hospitality, healthcare, and food service industries requires specialized, high-performance cleaning agents, driving volume in the industrial and institutional (I&I) cleaning segment.
Market Restraints
- Raw Material Volatility:The market's reliance on petrochemical derivatives and oleochemicals, such as palm oil, exposes manufacturers to significant price fluctuations and supply chain disruptions tied to global commodity markets.
- Intense Price Competition:The proliferation of private label brands across major retail channels in North America and Europe exerts constant downward pressure on pricing, squeezing margins for established national brands.
- Water Scarcity Concerns:Increasing water stress in several key regions, including parts of Asia and Africa, creates a structural barrier for traditional water-intensive laundry and cleaning processes, limiting market expansion.
Strategic Opportunities
- Bio-based Formulations:Developing detergents from renewable feedstocks, including advanced enzymes and microbial surfactants, presents an opportunity to meet sustainability goals and capture environmentally conscious consumer segments.
- Penetration in Africa:Sub-Saharan Africa represents a significant long-term opportunity, with low household penetration of manufactured detergents and a growing young, urban population creating a new consumer base.
- Waterless and Solid Formats:Innovation in waterless products, solid detergent sheets, and highly concentrated pods addresses consumer demand for convenience and sustainability, opening a new product category with premium pricing potential.
Industry Challenges
- Supply Chain Reconfiguration:Shifting production from established petrochemical feedstocks to novel bio-based ingredients requires significant capital investment in new infrastructure and supplier qualification, creating operational friction and risk.
- Consumer Habit Inertia:Overcoming long-standing consumer habits, such as overdosing liquid detergents or preferring powder formats, presents a significant marketing and educational challenge for manufacturers launching concentrated or novel formats.
- Greenwashing Scrutiny:Heightened regulatory and consumer vigilance against unsubstantiated environmental claims requires robust, transparent, and verifiable data to support sustainability marketing, increasing compliance and communication costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soap and Detergent Market |
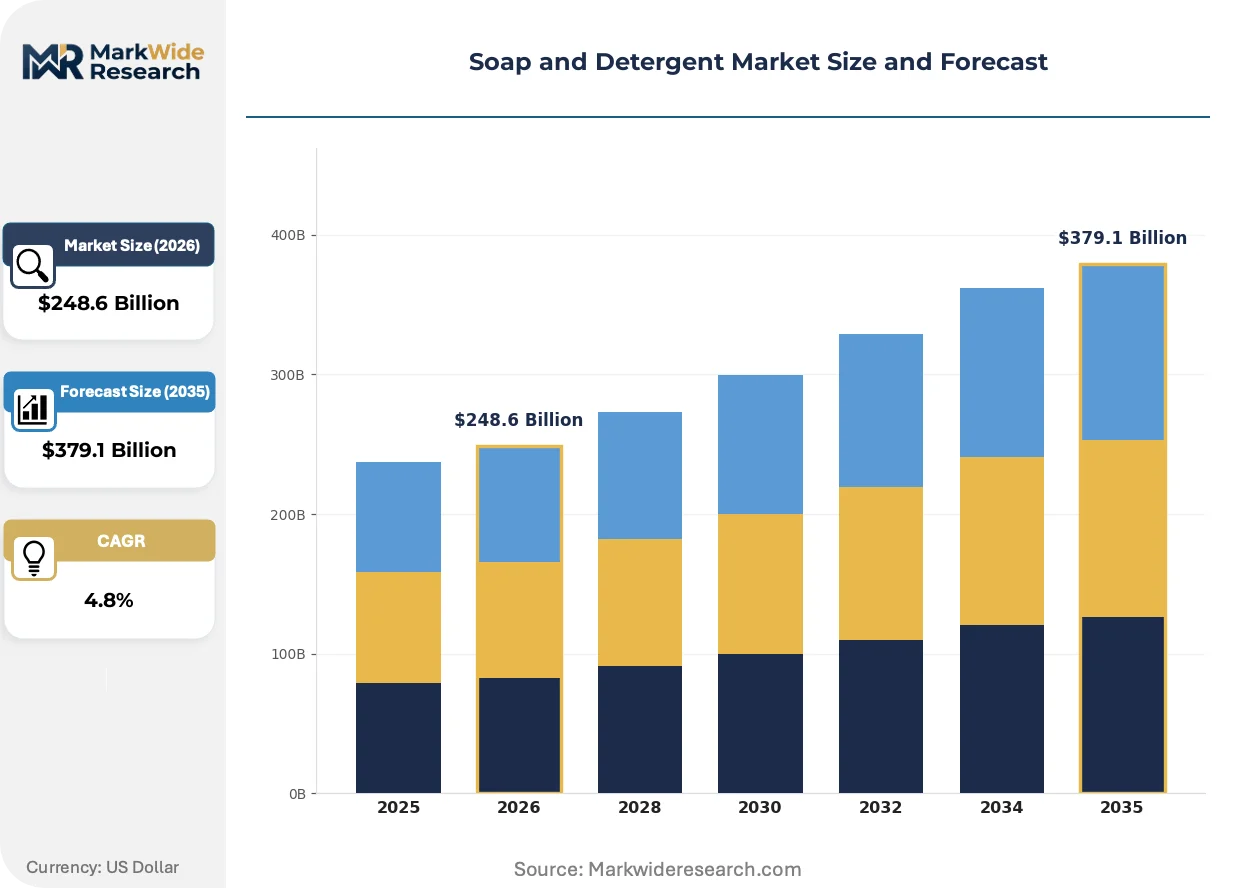
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $379.1 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Soap, Bar Soap, Powder Detergent, Liquid Detergent End User: Household, Industrial, Commercial, Institutional Application: Personal Care, Household Cleaning, Industrial Cleaning, Specialty Cleaning Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale |
| Companies Covered | Church & Dwight, Reckitt, Procter & Gamble, Lion Corporation, Colgate-Palmolive, Unilever, Kao Corporation, Nice Group, Henkel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soap and Detergent Market Strategic Shifts & Innovations
Product development is pivoting toward a circular economy model, where formulation, packaging, and end-of-life are considered holistically. This shift is driven by a confluence of stringent environmental regulations and a growing consumer preference for products with a demonstrably lower ecological footprint.
Biosurfactants, derived from microbial fermentation, offer a renewable and biodegradable alternative to conventional surfactants. The household and personal care segments are steadily adopting these ingredients in premium eco-friendly product lines, particularly in Europe. This technological evolution toward green chemistry is absorbing significant R&D investment that was previously allocated to optimizing petrochemical-based formulations.
In the United States, the EPA's Safer Choice program is influencing formulation decisions beyond mandatory compliance. The voluntary certification provides a clear market signal, prompting manufacturers to remove specific chemicals of concern to gain the label. The household cleaning category is most impacted, with brands leveraging the Safer Choice certification on packaging to appeal to health-conscious consumers.
Refillable packaging systems and direct-to-consumer subscription services for concentrated refills are gaining traction. This model disrupts the traditional retail dominance of single-use plastic containers, particularly for liquid detergents and surface cleaners. This behavioral shift is most prominent among environmentally conscious urban consumers in North America and Western Europe, creating opportunities for new, digitally native brands.
Soap and Detergent Market Segmentation
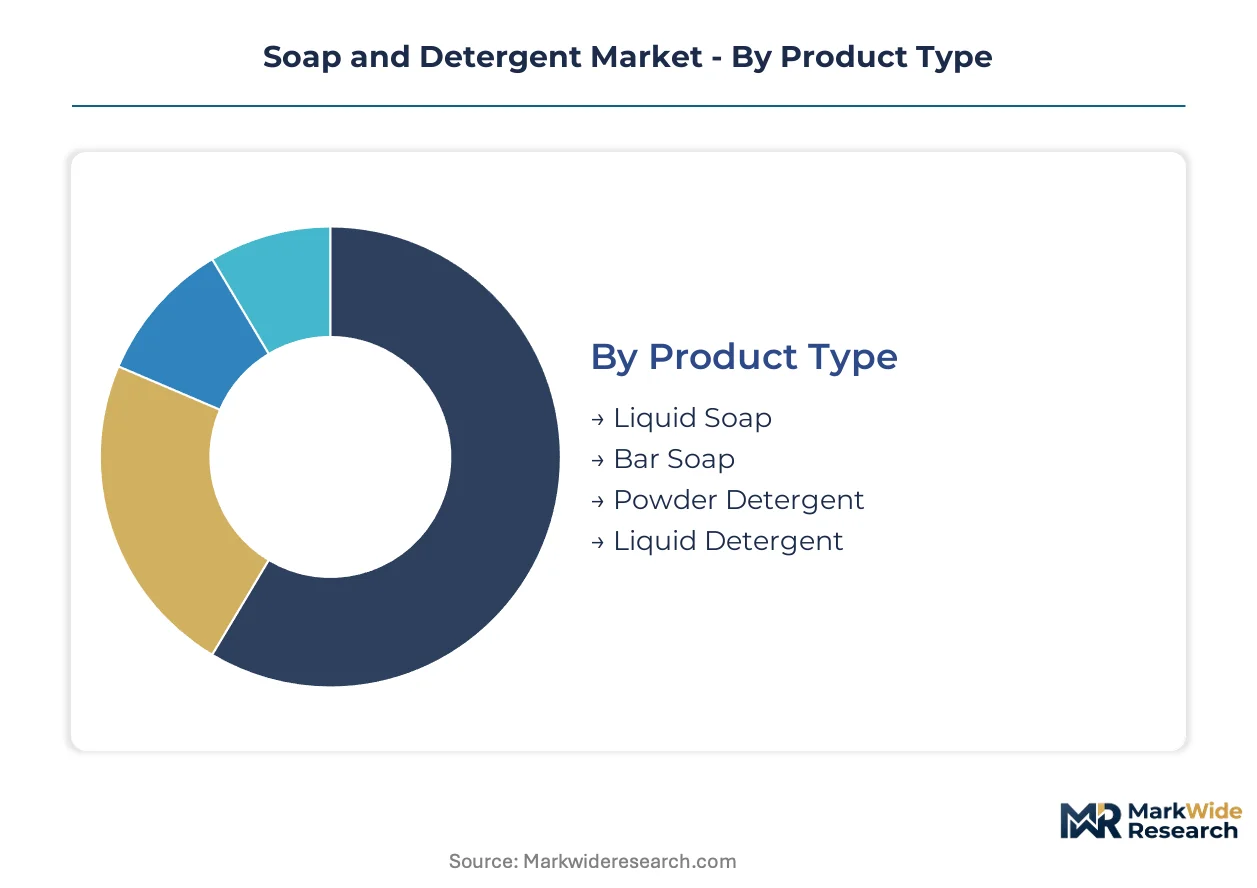
Understanding the varied segments within the soap and detergent market is crucial for strategic planning, revealing diverse consumer needs and operational landscapes. Manufacturers must tailor product formulations and distribution strategies to address specific demands across different user groups and product formats. This granular analysis illuminates distinct growth pockets and competitive dynamics for market participants.
Product Type:
The product type segment delineates between high-volume, cost-effective cleaning agents and premium, specialized formulations.
- Liquid Detergent:These synthetic surfactant solutions offer enhanced solubility and precise dosing, often incorporating advanced enzymes for stain removal. Demand is concentrating in North America and Western Europe, driven by consumer preference for convenience and performance in laundry applications.
- Powder Detergent:Composed of granular cleaning agents, these formulations provide strong cleaning power and are cost-effective, particularly in hard water regions. Significant volume demand originates from emerging economies like India and Brazil, supported by lower price points and traditional washing habits.
- Liquid Soap:These aqueous solutions for personal hygiene often contain emollients, gaining traction in public and commercial facilities for handwashing.
- Bar Soap:Solid soap formats, typically sodium or potassium salts of fatty acids, maintain a strong presence in household personal care, especially in cost-sensitive markets.
Mature deployment sits with Bar Soap. Newer deployment is concentrated in Liquid Detergent.
End User:
End-user categories define the specific environments and scale of cleaning operations, ranging from individual households to large industrial complexes.
- Household:This segment encompasses products for domestic cleaning, including laundry, dishwashing, and surface care, directly purchased by consumers. Demand is expanding in urbanization zones across India and China, reflecting rising hygiene standards and disposable incomes.
- Industrial:Formulations for large-scale manufacturing, processing, and heavy-duty cleaning applications require specialized chemical properties and high performance. Growth in this segment is driven by stringent sanitation requirements in food processing and automotive industries within Germany and the United States.
- Commercial:This segment serves businesses such as hotels, restaurants, and offices, requiring effective and often concentrated cleaning solutions for daily maintenance.
- Institutional:Products for hospitals, schools, and governmental facilities prioritize disinfection and safety, adhering to specific public health regulations in countries like the UK.
The household segment commands the largest volume share. Industrial applications represent the fastest-growing trajectory.
Application:
The application segment differentiates products by their intended cleaning purpose, each demanding specific performance characteristics and ingredient profiles.
- Household Cleaning:This broad application covers laundry, dishwashing, and general surface cleaning within residential settings, focusing on efficacy and user safety. Consumer demand in France and Canada prioritizes eco-friendly and hypoallergenic formulations for family use.
- Industrial Cleaning:Products designed for heavy-duty cleaning in factories, workshops, and large-scale facilities require robust formulations to remove tough grime and contaminants. Regulatory compliance, such as EU REACH standards, heavily influences product development for this segment in Germany.
- Personal Care:This application includes soaps and body washes for individual hygiene, focusing on skin compatibility and sensory attributes.
- Specialty Cleaning:These niche applications address specific cleaning challenges, such as medical instrument sterilization or electronics cleaning, demanding highly targeted chemical solutions.
Household cleaning maintains the largest market share. Specialty cleaning applications are climbing the fastest.
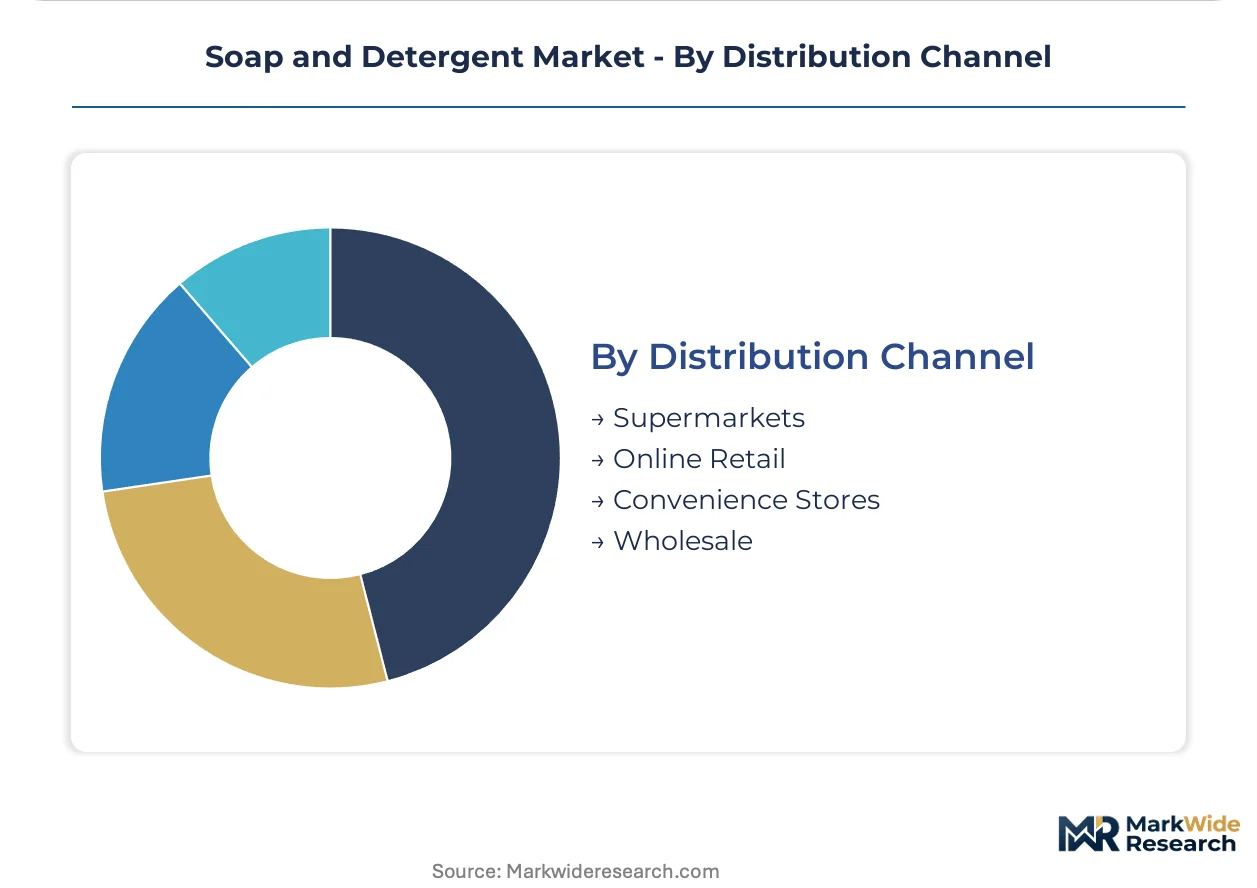
Distribution Channel:
Distribution channels dictate how soap and detergent products reach end-users, influencing market access and pricing strategies.
- Supermarkets:These large-format retail outlets remain the primary channel for household cleaning products, offering extensive product ranges and competitive pricing. Consumer purchasing in the United States and the United Kingdom heavily relies on supermarket promotions and brand visibility.
- Online Retail:E-commerce platforms provide convenience and a wider selection, increasingly capturing market share, particularly for concentrated and subscription-based products. This channel is expanding quickly in urban centers across China and Germany, driven by digital adoption.
- Convenience Stores:These smaller retail formats cater to immediate needs and impulse purchases, offering a limited selection of essential soap and detergent items.
- Wholesale:This channel supplies bulk quantities to commercial and institutional buyers, often providing specialized products and services to businesses in Brazil.
Supermarkets continue to dominate volume sales. Online retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The market for soaps and detergents sees significant activity in regions like the Yangtze River Delta, where manufacturing hubs drive both production and consumption. Key demand centers across the globe influence product innovation and distribution strategies. These diverse geographies reflect distinct consumer preferences and regulatory environments.
United States
Consumer preference for liquid detergents and eco-friendly options drives demand in the United States. The EPA's Safer Choice program heavily influences formulation decisions for household cleaning products. Companies in the Los Angeles metropolitan area are focusing on sustainable packaging and refill systems for urban consumers.
Germany
Industrial cleaning applications and a strong emphasis on sustainability characterize the German market. The EU REACH regulation mandates stringent chemical substance requirements for detergent formulations. Manufacturers in the Rhine-Ruhr region are investing in bio-based surfactants to meet environmental standards.
India
Rising hygiene awareness and rapid urbanization fuel substantial demand for household cleaning products in India. BIS standards ensure product quality and safety for a vast consumer base. The Mumbai metropolitan area experiences high volume sales of powder detergents due to cost-effectiveness and traditional habits.
China
The expansion of online retail channels and a focus on product performance shape the Chinese market. GB standards set mandatory requirements for detergent safety and efficacy. The Guangzhou-Shenzhen corridor is a hub for e-commerce distribution, driving sales of concentrated and liquid formats.
Brazil
High hygiene awareness and traditional washing habits sustain a large demand for powder detergents in Brazil. ANVISA regulations guide the safety and efficacy of personal care and household cleaning products. Companies in São Paulo state are expanding wholesale distribution to commercial and institutional buyers.
Soap and Detergent Market Key Industry Players
Premium-margin players sit above commodity-margin players across product innovation and brand positioning within the soap and detergent market. The industry exhibits a tiered structure, with global conglomerates dominating premium segments through advanced formulations and marketing. Numerous regional players compete on price and local distribution, particularly in emerging economies. Strategic archetypes include diversified consumer goods giants, specialized industrial chemical suppliers, and agile direct-to-consumer brands. Dominant competitive moves involve portfolio diversification into bio-based formulations and strategic partnerships for supply chain resilience.
Within the diversified consumer goods giant archetype, Procter & Gamble and Unilever occupy positions as global leaders, leveraging extensive brand portfolios across household and personal care segments. These organizations demonstrate broad market penetration, catering to various price points and consumer preferences worldwide. Henkel, a German-based company, exemplifies a specialized industrial chemical supplier, focusing on high-performance formulations for institutional clients and industrial applications. These companies collectively anchor significant market share, navigating both persistent consumer demand and evolving sustainability mandates across diverse geographies.
| Leading Market Players |
|---|
| Church & Dwight |
| Reckitt |
| Procter & Gamble |
| Lion Corporation |
| Colgate-Palmolive |
| Unilever |
| Kao Corporation |
| Nice Group |
| Henkel |
| Others |
Cost & Logistics Intelligence
Premium eco-friendly formulations represent a significant tier divergence, influencing both pricing and supply chain structures in the soap and detergent market. These products command higher prices due to specialized ingredients and certifications, contrasting sharply with cost-driven commodity segments.
Pricing Analysis
Outcome-based pricing for specialized industrial cleaning agents anchors their market value, reflecting efficacy in meeting stringent sanitation requirements. Pricing stratifies across premium, standard, and economy tiers, driven by factors such as EPA Safer Choice certification and established brand premium. Downward pricing pressure stems from the proliferation of private label brands across Europe and North America. The household segment remains highly price-sensitive, while industrial buyers prioritize performance for critical applications.
Supply Chain Analysis
Refillable packaging systems, alongside concentrated formats, are reshaping reverse logistics flows by reducing single-use plastic waste. The supply chain for soap and detergent draws from key manufacturing hubs in China and oleochemical producers in Malaysia. Raw material dependencies include petrochemical derivatives and palm oil, exposing manufacturers to significant commodity price volatility. Distribution runs through supermarkets for household products and specialized wholesale channels for industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soap and detergent market increasingly functions as a cost-of-compliance story, where stringent regulations create significant barriers. The EU Green Deal, with its mandates for biodegradable surfactants, establishes a moat for manufacturers capable of meeting these advanced standards.
For Market Incumbents: Anchor significant R&D budgets into advanced bio-based formulations, particularly microbial surfactants, to preempt future regulatory shifts. Consolidate market share by acquiring smaller innovators specializing in green chemistry to counter the threat of novel ingredient suppliers. Invest in EPA Safer Choice and EU REACH certifications to reinforce product trust and maintain brand premium. This strategy defends against margin pressure from non-compliant alternatives. For New Entrants and Emerging Players: E-commerce platforms offer a viable channel partner type for new brands to enter the market. Target underpenetrated household segments in Sub-Saharan Africa with cost-effective, high-performance powder detergents. Develop innovative waterless or solid formats, leveraging direct-to-consumer subscription models to build customer loyalty. This approach bypasses traditional retail dominance and appeals to environmentally conscious urban consumers. For Investors and Strategic Acquirers: Re-rating potential sits with agile, specialized bio-chemistry firms given escalating sustainability mandates and consumer demand for eco-friendly products. Long-term viability favors companies with strong intellectual property in microbial surfactants or robust distribution networks in rapidly urbanizing emerging economies like India. Target acquisition profiles include innovators in waterless formats and regional players with strong local market penetration. Monitor the cost parity of bio-based ingredients with traditional petrochemicals as a key inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Transition to Bio-based Production | This initiative reduces reliance on petrochemicals, aligning with EU Green Deal mandates. |
| Launch Waterless Detergent Formats | These products address water scarcity concerns and cater to convenience-seeking urban consumers. |
| Expand Online Retail Distribution | This strategy capitalizes on digital adoption in China and Germany for concentrated products. |
| Invest in EPA Safer Choice Certification | This certification provides a clear market signal, appealing to health-conscious US consumers. |
| Secure Long-term Enzyme Supply Agreements | Such agreements mitigate raw material volatility for advanced, high-performance formulations. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with R&D directors, procurement leads at major manufacturers, brand managers, and retail buyers provided qualitative insights. This approach combined bottom-up market sizing with top-down validation, ensuring comprehensive data triangulation. Company annual reports and EU REACH documentation also served as critical secondary sources.
Market granularity was modeled across product type, end-user, application, and distribution channel segments. Volume and value projections reflect a triangulated approach, integrating historical growth trends with projected market dynamics throughout the forecast period. Compound Annual Growth Rates were derived from a synthesis of supply-side capacity expansions and demand-side adoption rates. Key forecast inputs included raw material price forecasts.
Several conditions sit outside the modeled scope, including major geopolitical events and unforeseen technological breakthroughs. Forecasts reflect assumptions regarding stable economic conditions and current regulatory frameworks. Practitioners should monitor bio-based ingredient cost fluctuations and new regulatory proposals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Efflorescence Remover Market
Cleaning Chemicals
Global Bleach Wipes Market
Cleaning Chemicals
Aviation Cabin Cleaning Chemical Market
Cleaning Chemicals
Mosquito Repellent Market
Cleaning Chemicals
Chemical Dust Suppressants Market
Cleaning Chemicals
Industrial Cleaning Chemicals Market
Cleaning Chemicals
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market
Cleaning Chemicals
Deck Brightener Market
Cleaning Chemicals
Autonomous Floor Cleaning Machine Detergent and Care Chemicals Market
Cleaning Chemicals
Dust and Emission Control Chemicals for Ore Handling Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Dry Electrostatic Wipes Market
Cleaning Chemicals
Biodegradable Spray Tank Line-Cleaning Chemistry Market
Cleaning Chemicals
Commercial Cleaning Products Market
Cleaning Chemicals
Surface Cleaning Products Market
Cleaning Chemicals
Low-VOC Cleaning Chemicals for Enclosed Workspaces Market