
 Dust Suppressant Market | 2026-2036
Dust Suppressant Market Size, Share, and Industry Trends Forecast 2026-2036
Dust Suppressant Market Foresight
Mining operations is realigning the largest share of dust suppressant procurement as surface extraction expands in arid zones. Cargill Incorporated leverages its agricultural input supply chain to cross-sell organic suppressant formulations into adjacent mining territories. Borregaard AS sustains technology leadership in lignin-based binders derived from wood processing byproducts. Hexion Inc. specializes in resin-modified emulsions that anchor longer-duration surface stability on haul roads.
Dust suppressants comprise liquid, granular, chemical, and organic formulations engineered to agglomerate fine particulate matter and prevent airborne dispersion from disturbed surfaces; typical specifications include application rates of 0.5 to 2.0 liters per square meter and curing times under 24 hours for traffic-ready surfaces. Liquid suppressants dominate current volume due to compatibility with existing spray equipment across construction and mining fleets. Chemical suppressants command premium positioning where polymer-modified durability exceeds 90 days between reapplications. Organic suppressants are gaining fastest in agricultural fields where residue restrictions limit synthetic inputs.
The EPA enforces National Ambient Air Quality Standards for PM10 and PM2.5 that directly mandate fugitive dust control plans at major construction and mining sites, while OSHA's silica exposure limits for construction workers drive specification of high-performance suppressants on demolition and earthwork projects. Australia's state environmental protection agencies in Western Australia and Queensland impose site-specific dust management conditions that exceed federal baselines for major resource projects. Stakeholders must monitor evolving polymer registration requirements and biodegradability certifications that will determine product access across North American and Asia-Pacific mining contracts.
Market Dynamics
Surface mining expansion across arid extraction zones is intensifying procurement of polymer-modified liquid formulations as haul road stabilization becomes a compliance-critical operational function. EPA enforcement of National Ambient Air Quality Standards for PM10 and PM2.5 is forcing extraction operators to upgrade fugitive dust control plans with longer-duration chemical binders.
Growth Catalysts
- OSHA Silica Exposure Limits:Construction and demolition contractors face mandated respirable crystalline silica controls, driving specification of high-performance suppressants on earthwork and demolition sites.
- Australia Iron Ore Belt Expansion:Western Australia and Queensland resource projects operate under state environmental protection agency conditions that exceed federal baselines, creating sustained demand for premium formulations.
- Polymer-Modified Emulsion Technology:Resin-enhanced liquid suppressants deliver 90-plus day surface durability, reducing reapplication frequency and labor costs for remote mining operations.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic polymer binders depend on ethylene and propylene derivatives, exposing formulators to crude oil price swings that compress margin stability.
- Biodegradability Certification Delays:Registration timelines for organic suppressants under EPA Safer Choice and EU REACH biodegradability protocols extend market entry by 18-24 months.
- Lignin Supply Concentration:Wood processing byproduct availability clusters in Nordic and North American pulp regions, creating geographic supply vulnerability for bio-based binder producers.
Strategic Opportunities
- India Infrastructure Build-Out:National highway expansion and smart city earthworks generate unmet demand for dust control solutions compatible with monsoon climate cycles.
- Precision Application Equipment:Integration of GPS-guided spray systems with variable-rate suppressant dosing enables outcome-based contracting models for large-scale mining fleets.
- Agricultural Residue Restrictions:EU Farm-to-Fork Strategy limits synthetic chemical inputs on arable land, opening premium positioning for certified organic suppressant formulations.
Industry Challenges
- Polymer Chemist Talent Scarcity:Formulation expertise in long-chain polymer stabilization and emulsion chemistry concentrates at specialty chemical firms, constraining R&D expansion at regional suppliers.
- Legacy Equipment Compatibility:Existing mining fleet spray infrastructure requires retrofitting for high-viscosity emulsion delivery, complicating technology transitions at operating sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dust Suppressant Market |
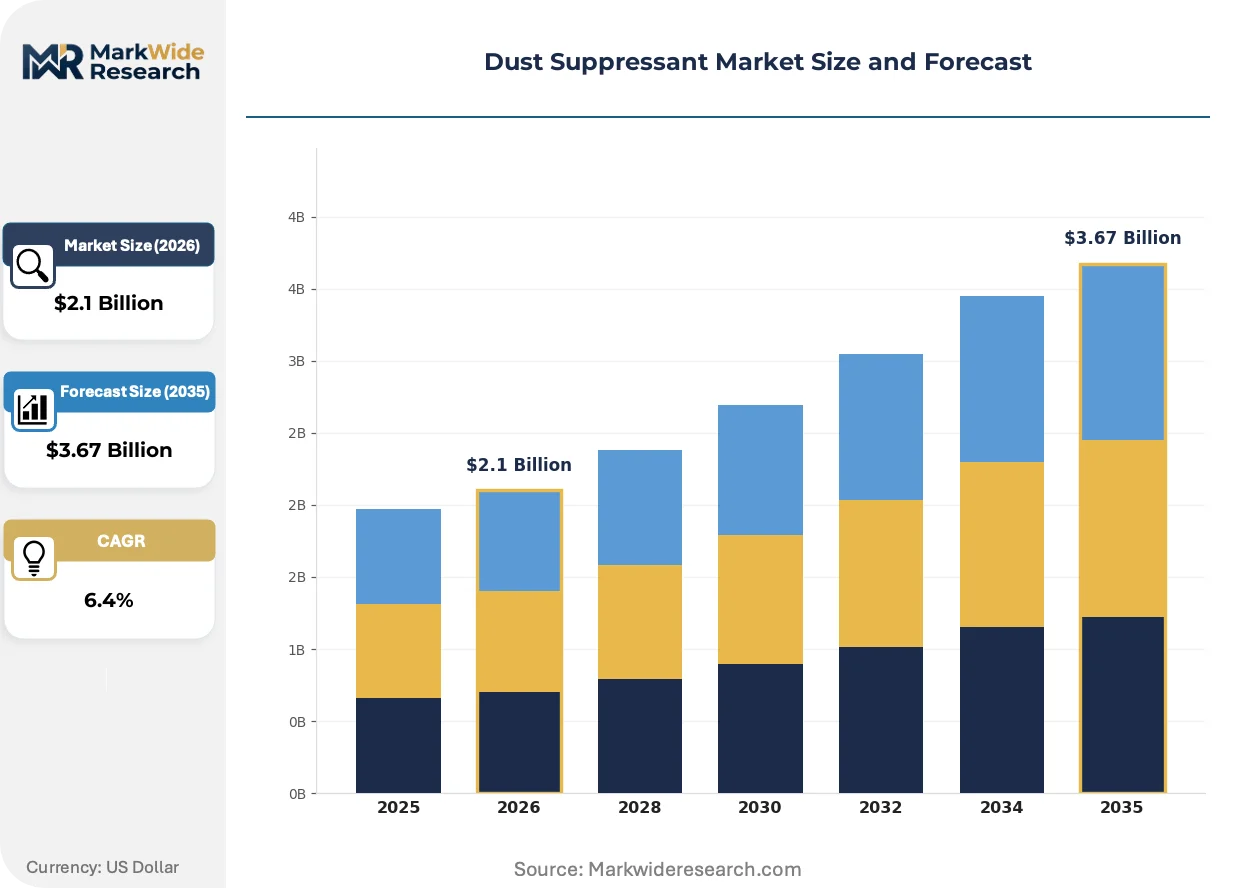
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Suppressants, Granular Suppressants, Chemical Suppressants, Organic Suppressants Application: Construction Sites, Mining Operations, Agricultural Fields, Road Maintenance Distribution Channel: Direct Sales, Distributors, Online Retail, Specialty Stores End User: Contractors, Environmental Agencies, Agricultural Producers, Industrial Users |
| Companies Covered | Borregaard AS, Cargill Incorporated, Ecolab Inc., Midwest Industrial Supply Inc., Soilworks LLC, BASF, Hexion Inc., Quaker Chemical Corporation, Dust-A-Side, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dust Suppressant Market Shifts & Advancements
Formulation chemistry is pivoting toward bio-derived binders and precision application systems as extraction operators seek to reconcile performance durability with environmental certification requirements. The competitive landscape is fragmenting between petrochemical majors, pulp-derived specialty players, and agricultural input cross-sellers.
Lignin-based suppressant technology is overtaking synthetic polymer formulations in agricultural-adjacent mining territories where residue restrictions limit chemical inputs. Australian iron ore producers in the Pilbara region are piloting Borregaard-derived binders at 40 percent of new surface treatment contracts. This shift is compressing addressable volume for conventional acrylic emulsion suppliers while expanding the certified-organic product tier.
EPA enforcement of updated National Ambient Air Quality Standards is mandating real-time PM10 monitoring integration with automated suppressant application systems at major construction and mining sites. Industrial operators must now demonstrate continuous compliance rather than periodic inspection readiness. Surface extraction projects in Arizona, Nevada, and Utah are deploying sensor-networked spray systems that trigger dosing based on wind speed and particulate detection thresholds.
Long-term service contracting is displacing spot procurement of suppressant chemicals across North American mining operations. Major extraction firms are unbundling chemical supply from application services, awarding multi-year performance contracts to integrated service providers. This restructuring concentrates purchasing authority at corporate procurement functions rather than site-level operations managers, favoring suppliers with national distribution networks and certified application technician pools.
Dust Suppressant Market Segmentation
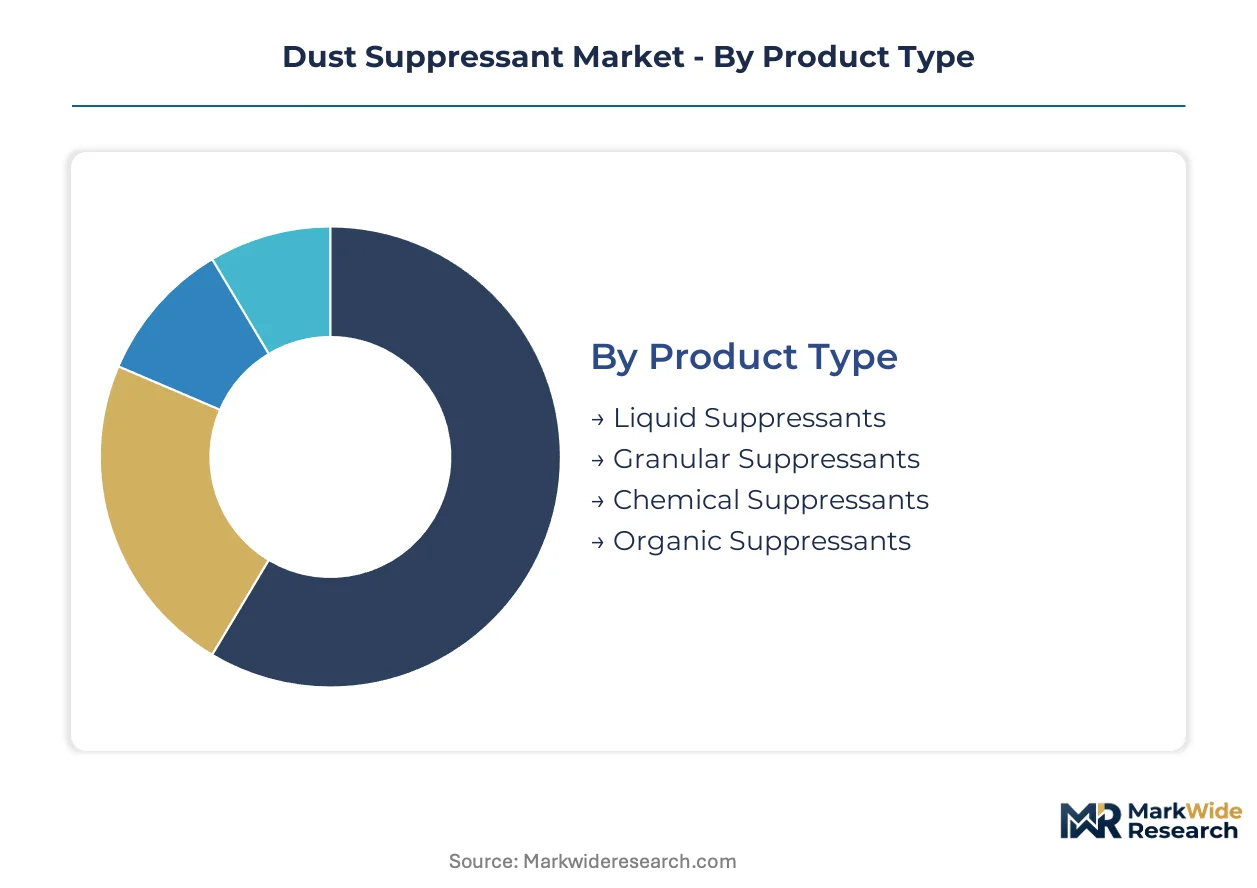
Dust suppressant procurement splits sharply between standalone spray applications and integrated surface treatment systems. Mining operators and construction contractors select formulations based on equipment compatibility, reapplication frequency, and compliance documentation requirements. Each segmentation dimension reveals distinct margin structures and supplier concentration patterns.
Product Type:
Liquid suppressants integrate directly into existing fleet spray infrastructure, while granular and chemical formulations demand specialized application equipment or surface preparation protocols.
- Liquid Suppressants:Water-based emulsions and polymer solutions deploy through standard spray trucks and water carts without retrofit. Mining haul roads in Western Australia and Queensland specify these formulations for rapid traffic-ready curing under 24 hours. EPA PM10 enforcement is accelerating procurement of longer-duration polymer-modified liquids that extend reapplication intervals beyond 90 days.
- Chemical Suppressants:Synthetic polymer binders including acrylic and resin-modified emulsions deliver extended surface stability exceeding 90 days between treatments. Surface extraction operators in Arizona, Nevada, and Utah specify these for remote sites where labor costs dominate total cost of ownership. Petrochemical feedstock volatility compresses margin stability for formulators dependent on ethylene and propylene derivatives.
- Granular Suppressants:Solid particulate binders spread via conventional grading equipment for unpaved road stabilization and stockpile capping.
- Organic Suppressants:Lignin-based and plant-derived formulations from wood processing byproducts serve agricultural-adjacent mining territories with residue restrictions.
Liquid suppressants lead volumes today; organic suppressants are gaining share fastest.
Application:
Cost tiering separates compliance-mandated mining applications from discretionary construction and agricultural deployments.
- Mining Operations:Surface extraction sites in arid zones require continuous haul road stabilization and stockpile capping under strict particulate matter enforcement. Western Australia iron ore producers and Queensland coal operators face state environmental protection agency conditions exceeding federal baselines. Real-time PM10 monitoring integration with automated spray systems is becoming mandatory at major extraction sites.
- Construction Sites:Earthwork, demolition, and infrastructure projects specify suppressants to meet OSHA respirable crystalline silica exposure limits for workers. Contractors on highway expansion and smart city earthworks in India generate unmet demand for formulations compatible with monsoon climate cycles. High-performance suppressants command premium positioning where silica control plans are inspection-critical.
- Agricultural Fields:EU Farm-to-Fork Strategy limits on synthetic chemical inputs drive specification of certified organic formulations for tillage and harvest dust control.
- Road Maintenance:Municipal and county unpaved road programs balance performance duration against material cost in budget-constrained procurement.
Mining operations anchor revenue concentration; construction sites are expanding most quickly.
Distribution Channel:
Customer scale determines channel selection, with enterprise mining fleets bypassing intermediaries while smaller contractors rely on distributor networks.
- Direct Sales:Major extraction firms unbundle chemical supply from application services, awarding multi-year performance contracts to integrated service providers. Corporate procurement functions concentrate purchasing authority, favoring suppliers with national distribution networks and certified technician pools. Long-term service contracting is displacing spot procurement across North American mining operations.
- Distributors:Regional chemical and construction supply houses serve mid-tier contractors and municipal road maintenance programs with inventory proximity and technical support.
- Online Retail:Agricultural producers and small-scale contractors access standardized formulations through digital procurement platforms.
- Specialty Stores:Localized outlets cater to equipment owners requiring immediate availability of consumable suppressant products.
Direct sales dominate mining sector value; distributors retain construction and agricultural volume leadership.
End User:
Maturity differentiation separates specification-driven environmental compliance from price-sensitive operational procurement.
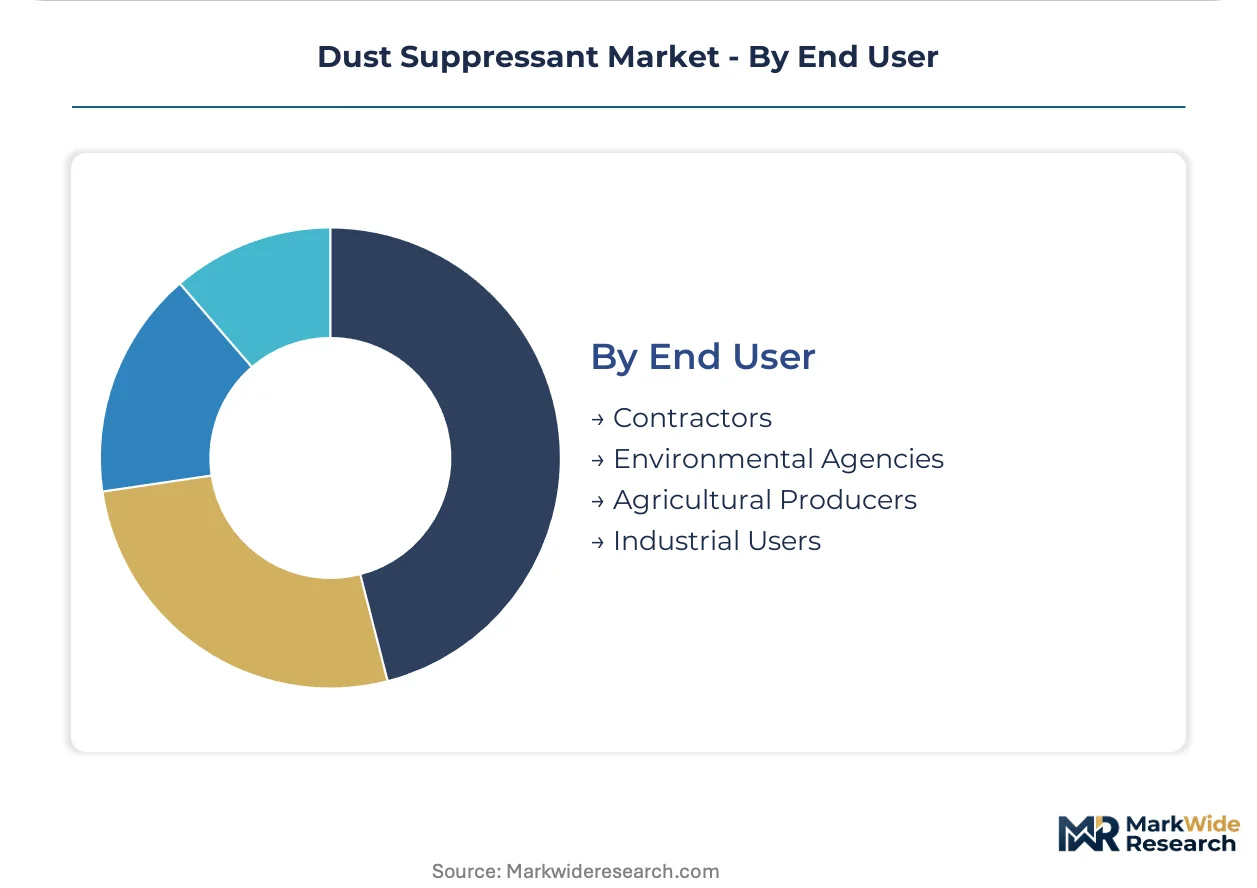
- Contractors:Construction and earthwork firms specify suppressants to satisfy OSHA silica exposure mandates and client environmental requirements. Demolition contractors face mandated respirable crystalline silica controls driving high-performance suppressant specification. GPS-guided spray systems with variable-rate dosing enable outcome-based contracting models for large-scale fleets.
- Environmental Agencies:Regulatory bodies enforce National Ambient Air Quality Standards and state-level conditions that dictate suppressant performance specifications at permitted sites.
- Agricultural Producers:Arable land operators select organic formulations where residue restrictions limit synthetic inputs under EU and emerging market regulations.
- Industrial Users:Manufacturing and logistics facilities with exposed material handling surfaces deploy suppressants for worker safety and neighbor relations management.
Contractors represent the largest addressable base; environmental agencies are driving steepest specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting dust suppressant procurement toward jurisdictions with stringent but codified compliance frameworks, where the cost of non-compliance exceeds premium formulation premiums. Australia and the United States concentrate demand where EPA and state-level enforcement creates predictable procurement obligations. Emerging markets capture volume through infrastructure scale rather than environmental mandate density.
Australia
Western Australia iron ore producers and Queensland coal operators anchor regional procurement under state environmental protection agency conditions exceeding federal baselines. The Pilbara region deploys lignin-derived binders at 40 percent of new surface treatment contracts as residue restrictions intensify. Real-time PM10 monitoring integration with automated spray systems is becoming mandatory at major extraction sites across the mineral-rich northwest.
United States
Surface extraction projects in Arizona, Nevada, and Utah specify polymer-modified emulsions for remote haul road stabilization under EPA National Ambient Air Quality Standards. OSHA silica exposure limits for construction workers drive high-performance suppressant specification on demolition and earthwork projects. Corporate procurement functions concentrate purchasing authority through multi-year performance contracts favoring suppliers with national distribution networks.
China
Mining operations in Inner Mongolia and Shanxi Province face escalating dust compliance obligations under MEE particulate matter enforcement. National highway expansion and smart city earthworks generate demand for formulations compatible with seasonal precipitation cycles. Domestic formulators leverage captive petrochemical feedstock access to compress pricing on synthetic polymer binders.
India
National highway expansion under the Ministry of Road Transport and Highways generates unmet demand for dust control solutions compatible with monsoon climate cycles. BIS certification requirements for construction chemicals create entry barriers for unformulated imports. Earthwork contractors in Maharashtra and Karnataka specify suppressants to satisfy client environmental requirements on infrastructure megaprojects.
Brazil
Iron ore extraction in Minas Gerais and Pará states operates under evolving state environmental agency conditions for surface mining dust management. Agricultural residue restrictions in the Cerrado biome drive specification of certified organic formulations for tillage dust control. ANVISA registration timelines for imported chemical inputs extend market entry for foreign specialty formulators.
Dust Suppressant Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with mining procurement concentrating authority at corporate functions while construction retains distributor-mediated fragmentation. Three archetypes dominate: petrochemical majors with captive polymer supply, pulp-derived specialty players leveraging lignin byproduct access, and agricultural input cross-sellers exploiting existing field service infrastructure. Consolidation pressure concentrates among mid-tier formulators lacking backward integration into feedstock supply. Strategic moves center on multi-year performance contracting and certified application technician pool expansion.
Among Nordic-origin specialty chemical players, Borregaard AS exemplifies the pulp-derived binder archetype through lignin technology leverage. Cargill Incorporated occupies a position bridging agricultural input distribution with adjacent mining territory penetration. Hexion Inc. represents the resin-modified emulsion specialization for extended-duration surface stability applications. These three anchors illustrate how feedstock origin and application expertise stratify competitive positioning across compliance-driven procurement segments.
| Leading Market Players |
|---|
| Borregaard AS |
| Cargill Incorporated |
| Ecolab Inc. |
| Midwest Industrial Supply Inc. |
| Soilworks LLC |
| BASF |
| Hexion Inc. |
| Quaker Chemical Corporation |
| Dust-A-Side |
| Others |
Supply & Pricing Matrix
EPA Safer Choice certification gates both qualified supply and premium-tier pricing access, as mining operators in Western Australia and Queensland refuse unregistered formulations regardless of performance claims. This regulatory filter concentrates pricing power among incumbent specialists with completed biodegradability protocols, while compressing margins for synthetic polymer suppliers exposed to ethylene derivative volatility.
Pricing Analysis
Distributor margin layers absorb 15-25 points before product reaches mid-tier contractors, while direct-to-mining-fleet contracts eliminate intermediaries entirely. Three-tier pricing structure across premium polymer-modified, standard water-based, and economy lignin formulations separates 90-day durability specifications from 30-day reapplication cycles. Pricing pressure stems from petrochemical feedstock swings that compress margin stability for acrylic emulsion suppliers. Construction contractors exhibit highest price sensitivity due to discretionary procurement authority, whereas corporate mining procurement functions prioritize total cost of ownership over unit price.
Supply Chain Analysis
Single-source vulnerability sits with Nordic pulp regions for lignin-derived binders, as Borregaard's wood processing byproduct network lacks geographic redundancy. Feedstock supply draws from Norway, Sweden, and Finland for bio-based formulations, while synthetic polymer production rests on Gulf Coast petrochemical corridors in the United States and Rotterdam-Antwerp hubs in Europe. Tariff exposure on imported specialty chemicals threatens formulators serving Australian mining contracts. Distribution runs through integrated service providers with certified application technician pools for mining sector volume, while regional chemical distributors retain construction and agricultural channel leadership.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, justified by the shift toward 90-day polymer-modified durability specifications that disqualify commodity-grade suppliers from major extraction contracts.
For Market Incumbents: Deploy multi-year performance contracting to lock in corporate procurement functions before application-service unbundling completes. Backward integration into captive lignin supply or resin-modified emulsion feedstock secures margin stability against petrochemical volatility. Certification investment in EPA Safer Choice and EU REACH biodegradability protocols defends positioning against emerging bio-based entrants from agricultural input cross-sellers.
For New Entrants and Emerging Players: Begin with precision application equipment integration for GPS-guided spray systems, where outcome-based contracting models remain underdeveloped in Indian highway expansion and Brazilian iron ore territories. Target construction site silica compliance as the most penetrable segment, where OSHA enforcement creates specification urgency without incumbent loyalty. Partner with regional equipment distributors for fleet retrofit compatibility rather than competing on formulation chemistry alone.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier formulators lacking backward integration because corporate procurement consolidation favors suppliers with national distribution networks and certified technician pools. Long-term viability hinges on bio-derived binder technology access as residue restrictions expand beyond agricultural-adjacent mining territories. Watch lignin supply contract renewals in Nordic pulp regions as the inflection indicator for bio-based tier pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lignin Feedstock | Captures margin from Nordic pulp byproducts before competitor contract renewals in Norway and Sweden. |
| Multi-Year Performance Contracting | Locks corporate mining procurement functions before site-level authority dissolves entirely. |
| Precision Application Equipment Integration | Enables GPS-guided variable-rate dosing for outcome-based contracts with Australian iron ore fleets. |
| EPA Safer Choice Certification Investment | Qualifies formulations for Western Australia state environmental protection agency conditions exceeding federal baselines. |
| Certified Technician Pool Expansion | Supports direct sales channel dominance as integrated service providers consolidate mining sector purchasing authority. |
Research Methodology
Multiple input streams — executive interviews with mining procurement directors, formulation chemists at specialty chemical firms, and construction site safety officers — were reconciled against secondary validation from EPA enforcement records, state environmental protection agency permit databases, and customs trade data for lignin derivative imports. Bottom-up triangulation across product-type shipment volumes and top-down reconciliation against end-use application spend produced convergent estimates. Primary fieldwork captured procurement authority shifts from site-level operations managers to corporate functions.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry tier, application equipment compatibility, reapplication frequency specification, and regional regulatory enforcement intensity. CAGRs were derived from slope analysis of historical procurement patterns extrapolated against compliance mandate acceleration curves. Industry-specific forecast inputs incorporated polymer registration timeline delays and monsoon climate cycle compatibility requirements for South Asian infrastructure deployment.
Several conditions sit outside the modeled scope, including abrupt petrochemical price shocks beyond historical volatility bands and unilateral regulatory recognition reciprocity failures between EPA Safer Choice and EU REACH protocols. Forecasts reflect documented assumptions about enforcement continuity and feedstock supply stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Micellar Cleansing Water Market
Cleaning Chemicals
Global Cleaner and Degreaser Aftermarket Market
Cleaning Chemicals
Cleaning Nozzles Market
Cleaning Chemicals
North America Metal Cleaning Chemicals Market
Cleaning Chemicals
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market
Cleaning Chemicals
Dishwashing Liquid Market
Cleaning Chemicals
Cleaning Chemicals Market
Cleaning Chemicals
Fabric Softener Market
Cleaning Chemicals
Sanitizing Agents Market
Cleaning Chemicals
Eco-Label Certified Cleaning Chemicals for Professional Users Market
Cleaning Chemicals
Low-VOC Cleaning Chemicals for Enclosed Workspaces Market
Cleaning Chemicals
Instrument Cleaners and Detergents Market
Cleaning Chemicals
Low-Residue Glass and Stainless-Steel Maintenance Chemicals Market
Cleaning Chemicals
Coating Removal System Market
Cleaning Chemicals
Drain Opener Chemicals Market
Cleaning Chemicals
Mask Reticle Cleaning Agent Market