
 Cleaning Nozzles Market | 2026-2036
Cleaning Nozzles Market Size, Share, and Industry Trends Forecast 2026-2036
Cleaning Nozzles Market Outlook
German precision engineering clusters is decoupling from low-cost Asian supply for high-pressure wash applications. Spraying Systems Co. leverages its Chicago-based R&D campus to dominate spray characterization protocols for food safety clients. Lechler GmbH anchors European demand through captive stainless steel foundry operations in Metzingen. Kärcher Group extends its retail channel control into professional nozzle aftermarket services across Central Europe.
Cleaning nozzles are precision-engineered orifices machined to deliver controlled spray patterns at defined pressures, typically operating between 15 bar and 250 bar depending on jet geometry and material grade, with stainless steel variants offering corrosion resistance for caustic chemical environments. Their primary purpose is to direct cleaning media—water, solvent, or foam—onto targeted surfaces with minimal waste and maximal shear force for contaminant removal. Spray nozzles command the largest installed base across industrial cleaning lines where continuous-duty cycles drive replacement demand. Stainless steel material grades capture premium margin pools due to FDA and EFSA compatibility requirements in dairy and beverage processing equipment. Multi-function nozzles represent the fastest-growing product configuration as OEMs consolidate attachment inventories for automated wash skids.
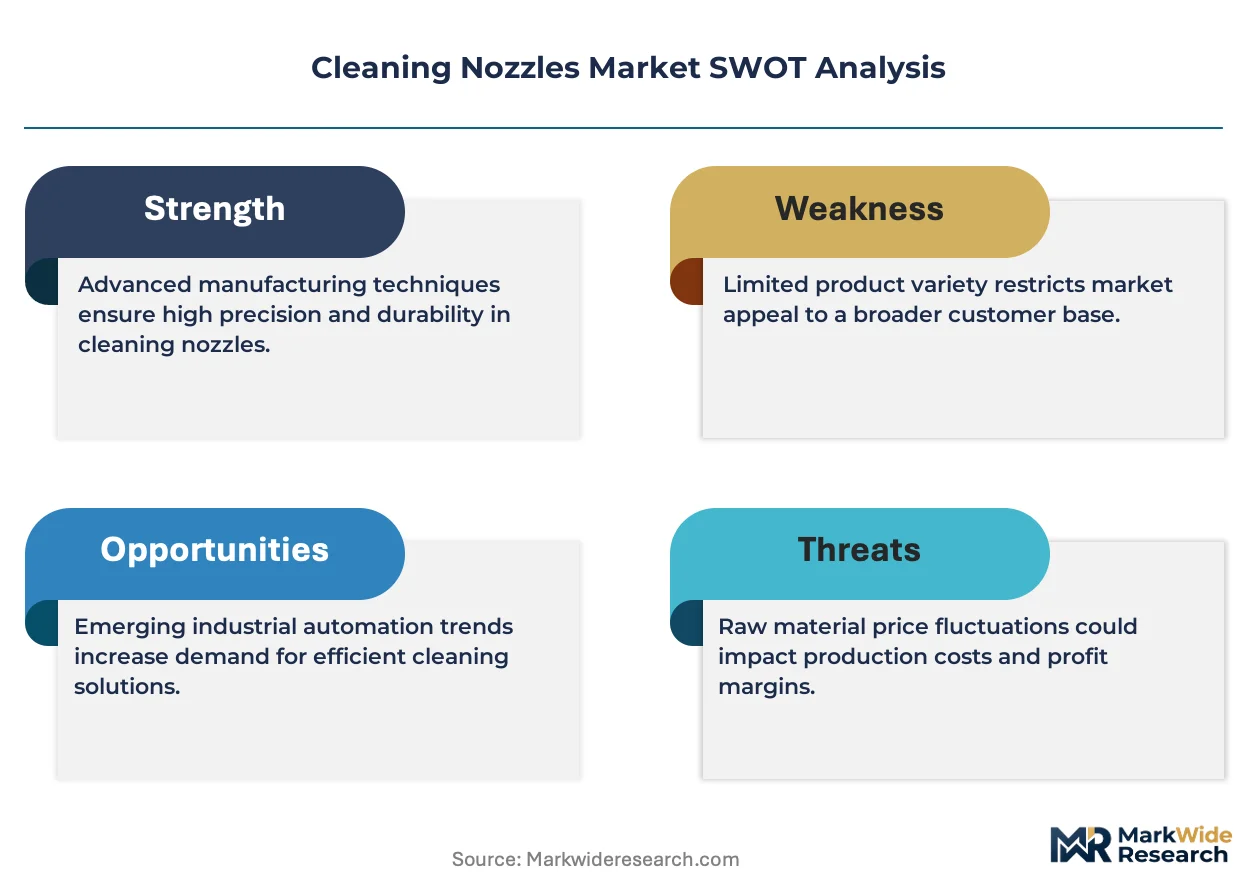
EPA effluent guidelines constrain wastewater chemistry from industrial cleaning operations, pushing end-users toward precision nozzles that reduce chemical consumption and water volumes. FDA Food Safety Modernization Act preventive controls mandate hygienic design standards for clean-in-place systems, directly specifying 316L stainless steel nozzle construction with Ra 0.8 surface finishes or smoother. ISO 9001 quality system certification has become a baseline market access requirement for nozzle suppliers serving multinational OEMs. Stakeholders must monitor how REACH substance restrictions on nickel alloys reshape material substitution roadmaps and whether EU Green Deal water efficiency targets accelerate payback calculations for premium nozzle upgrades.
Market Dynamics
Stainless steel foundry capacity concentration in Southern Germany is reshaping supply security for precision-engineered cleaning nozzles, as captive vertical integration becomes the dominant competitive moat amid REACH substance scrutiny on nickel alloy formulations.
Growth Catalysts
- REACH compliance deadlines:ECHA substance restrictions on chrome-nickel alloys are accelerating stainless steel grade transitions in food processing equipment, forcing replacement cycles for legacy brass nozzle inventories across European dairy operations.
- Clean-in-place automation:Dairy and beverage OEMs in Bavaria are specifying 316L construction with Ra 0.8 surface finishes to satisfy FDA Food Safety Modernization Act preventive controls for hygienic design validation.
- Water stress geography:Municipal water pricing in Stuttgart industrial zones is compressing payback periods for precision nozzles that reduce cleaning media volumes by 15-30% versus conventional spray geometries.
Market Restraints
- Nickel alloy feedstock volatility:LME nickel price swings since 2022 are compressing margin pools for nozzle suppliers without captive foundry operations or long-term offtake agreements with Swedish or Finnish stainless producers.
- Precision machining bottleneck:Five-axis CNC capacity for micro-orifice drilling below 0.5mm diameter concentrates in Stuttgart-Tübingen industrial clusters, creating single-source dependency for high-pressure wash system OEMs.
- Caustic chemical compatibility limits:Sodium hydroxide concentrations above 5% in CIP protocols degrade 304-grade stainless within 18-month replacement cycles, forcing premature upgrades to premium 316L variants.
Strategic Opportunities
- EU Green Deal water efficiency targets:Industrial facility retrofits in Baden-Württemberg must achieve 20% process water reduction by 2030, creating specification pull for multi-function nozzles that consolidate attachment inventories on automated wash skids.
- Aftermarket service unbundling:Kärcher Group's professional channel control across Central Europe demonstrates how nozzle replacement subscription models can capture recurring revenue from food safety audit-driven maintenance schedules.
- Pharmaceutical bioreactor cleaning:Single-use bioprocessing equipment growth in Basel-Rhine pharmaceutical clusters is creating demand for validated spray patterns that eliminate cross-contamination risk in multi-product facilities.
Industry Challenges
- Surface finish certification timelines:Third-party validation of Ra 0.4 micron finishes for pharmaceutical applications requires 12-16 week laboratory protocols, delaying OEM qualification schedules and compressing supplier cash conversion cycles.
- Legacy system integration friction:Retrofitting precision nozzles onto 1990s-era wash skids without programmable logic controller upgrades forces custom adapter fabrication, inflating project engineering costs by 40-60%.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cleaning Nozzles Market |
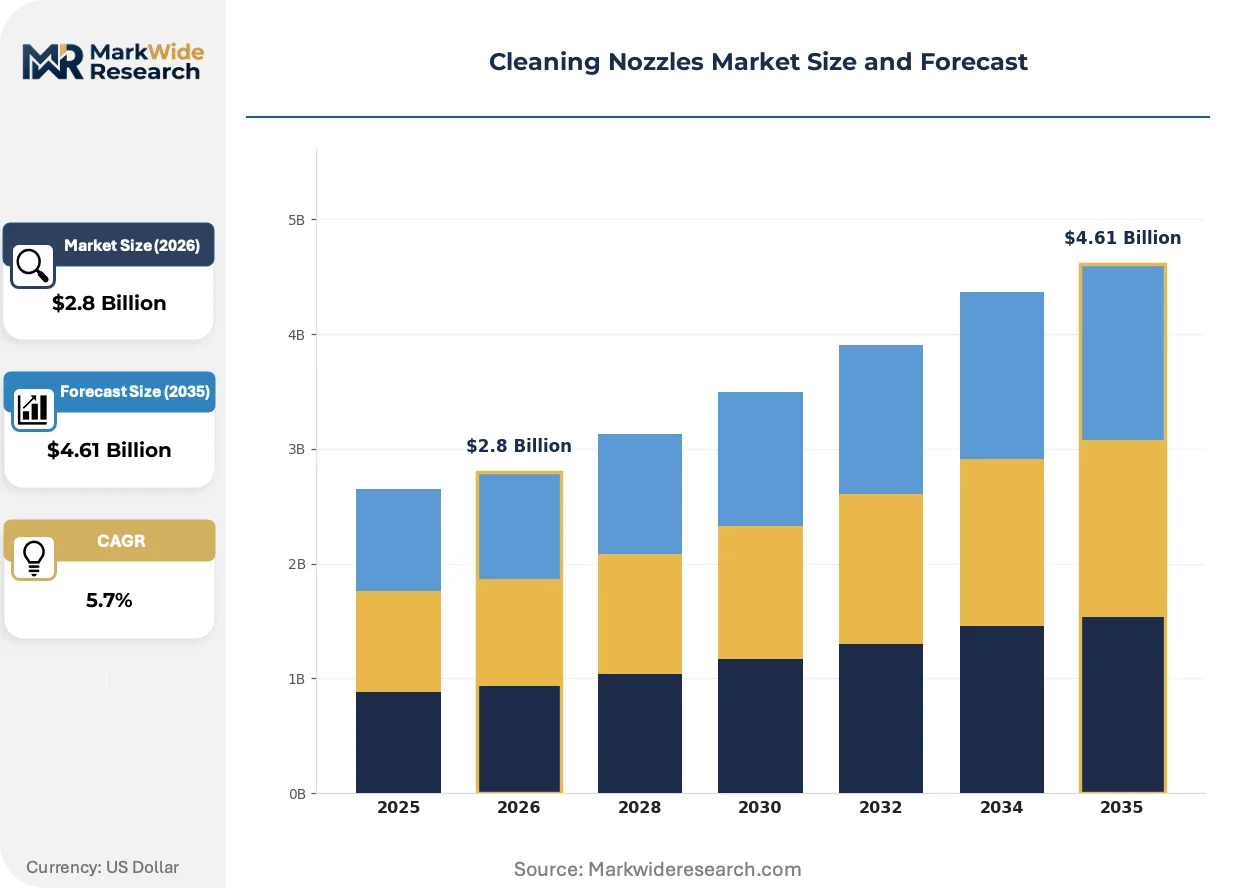
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray Nozzles, Foam Nozzles, Jet Nozzles, Multi-Function Nozzles Material: Plastic, Stainless Steel, Brass, Rubber Application: Industrial Cleaning, Automotive Cleaning, Residential Cleaning, Commercial Cleaning Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | Nilfisk Group, Kärcher Group, Graco Inc, Spraying Systems Co., Lechler GmbH, Alfa Laval, BETE, Delavan, Düsen-Schlick GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cleaning Nozzles Market Strategic Shifts
Nozzle architecture is fragmenting into configurable sub-assemblies as OEMs demand consolidated spare part inventories, while regulatory surface finish specifications tighten and water stress economics rewrite procurement criteria for cleaning media delivery systems.
Computational fluid dynamics-optimized orifice geometries are modularizing spray characterization protocols for food safety clients. Spraying Systems Co.'s Chicago R&D campus validates droplet size distributions across 15-250 bar operating envelopes. Dairy processors in Wisconsin and Bavaria now specify CFD-verified patterns to minimize water carryover into pasteurization zones, compressing validation cycles from 18 months to 6 months.
EPA effluent guidelines for industrial cleaning wastewater are mandating precision nozzle retrofits to reduce chemical oxygen demand in discharged streams. Metal finishing operations in Michigan and Ohio face NPDES permit limits on phosphate discharge, pushing specification shifts toward nozzles that achieve equivalent shear force at 30% lower detergent concentrations. ECHA parallel restrictions on nonylphenol ethoxylate surfactants amplify this chemistry-minimization trajectory across Atlantic supply chains.
Aftermarket procurement is consolidating through authorized service networks rather than distributor spot-buying. Food processing maintenance managers in Stuttgart industrial zones now contract fixed-price nozzle replacement programs tied to hygiene audit calendars, displacing transactional MRO purchasing. This contractual shift concentrates volume with OEM-captive service divisions and compresses independent distributor margins across Central European markets.
Cleaning Nozzles Market Segmentation
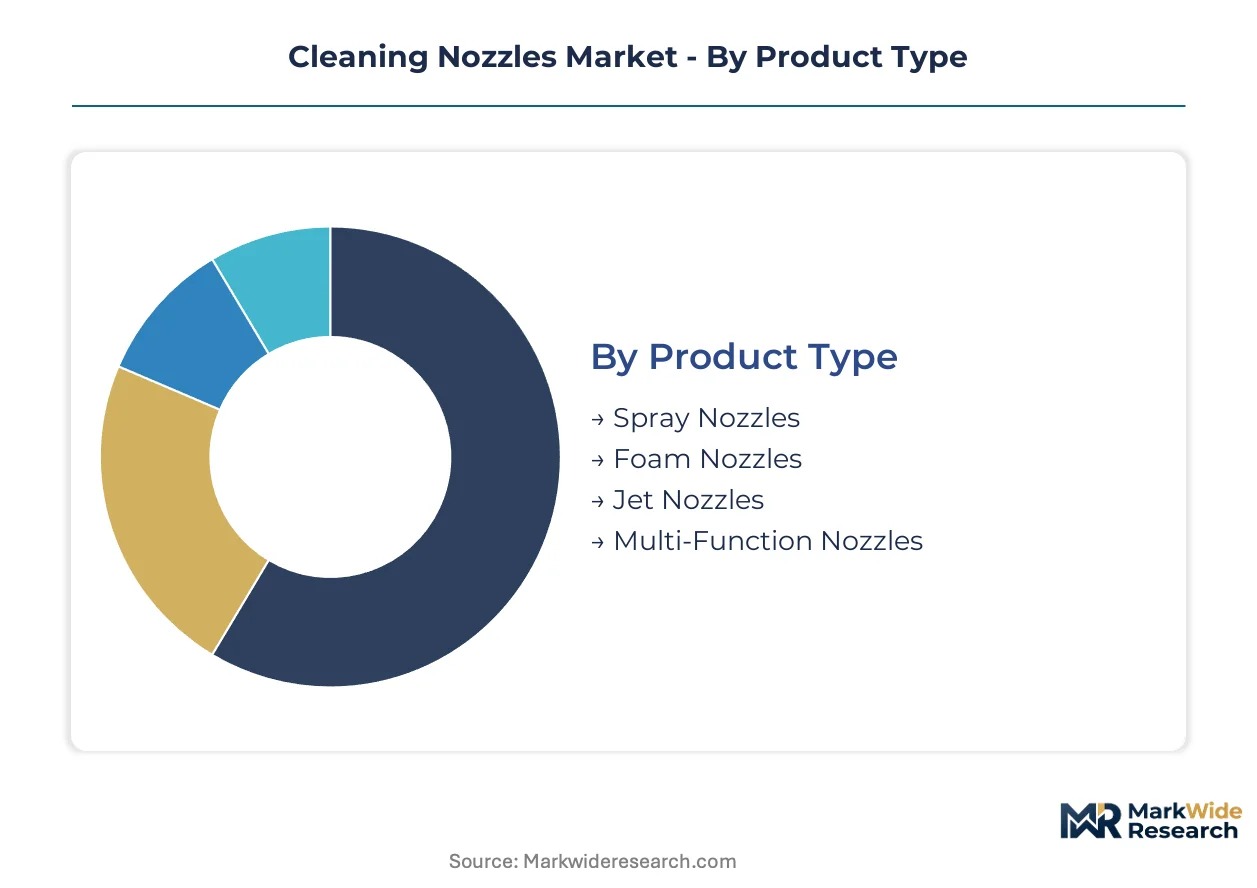
Cleaning nozzle procurement patterns diverge sharply between precision-engineered industrial specifications and commoditized consumer-grade replacements. Segmentation reveals how material certification requirements and automation intensity reshape margin pools across end-use categories.
Product Type:
Volume deployments concentrate in standardized spray geometries, while premium engineering margins attach to configurable architectures that consolidate attachment inventories.
- Spray Nozzles:These precision-machined orifices deliver controlled droplet distributions across 15-250 bar operating envelopes. Dairy processors in Bavaria specify CFD-validated patterns to minimize water carryover into pasteurization zones, compressing validation cycles from 18 months to 6 months.
- Multi-Function Nozzles:Modular sub-assemblies consolidate spare part inventories for automated wash skids. OEMs in Stuttgart-Tübingen clusters specify these configurations to reduce maintenance complexity in clean-in-place systems serving pharmaceutical bioreactor cleaning applications.
- Foam Nozzles:Specialized geometries generate stable air-liquid emulsions for heavy-soil applications in automotive pre-treatment lines.
- Jet Nozzles:Concentrated high-pressure streams serve precision deburring and surface preparation in metal finishing operations.
Mature deployment sits with spray nozzles. Newer deployment is concentrated in multi-function nozzles.
Material:
REACH compliance deadlines are forcing grade transitions that separate FDA-validated stainless inventories from legacy brass installations in European food processing.
- Stainless Steel:316L and 304 grades dominate industrial specifications requiring Ra 0.8 surface finishes or smoother for hygienic design validation. Captive foundry operations in Southern Germany anchor supply security for precision-engineered variants amid nickel alloy feedstock volatility.
- Plastic:Polypropylene and PVDF formulations serve caustic chemical environments below 60°C operating temperatures. Residential and light commercial applications in water-stressed geographies specify these variants for cost-sensitive replacement cycles.
- Brass:Legacy installations in European dairy operations face accelerated replacement timelines due to ECHA substance restrictions on chrome-nickel alloy alternatives.
- Rubber:Elastomeric seals and gaskets complement rigid nozzle bodies in vibration-prone wash skid installations.
Established specification dominance belongs to stainless steel. Material substitution momentum is building fastest in plastic formulations.
Application:
Automation intensity and regulatory audit frequency determine whether procurement flows through OEM-captive service networks or transactional distributor channels.
- Industrial Cleaning:Continuous-duty cycles in food processing plants drive replacement demand tied to hygiene audit calendars. Fixed-price subscription models are displacing spot-buying across Stuttgart industrial zones.
- Automotive Cleaning:Paint shop pre-treatment lines and final assembly wash stations specify precision nozzles to achieve phosphate discharge limits under NPDES permits in Michigan and Ohio manufacturing clusters.
- Commercial Cleaning:Facility management contractors in municipal water pricing zones prioritize precision geometries that reduce cleaning media volumes by 15-30%.
- Residential Cleaning:Price-sensitive replacement cycles concentrate in retail channel distribution with minimal specification complexity.
Contractual service integration is deepest in industrial cleaning. Volume expansion is steepest in commercial cleaning retrofit programs.
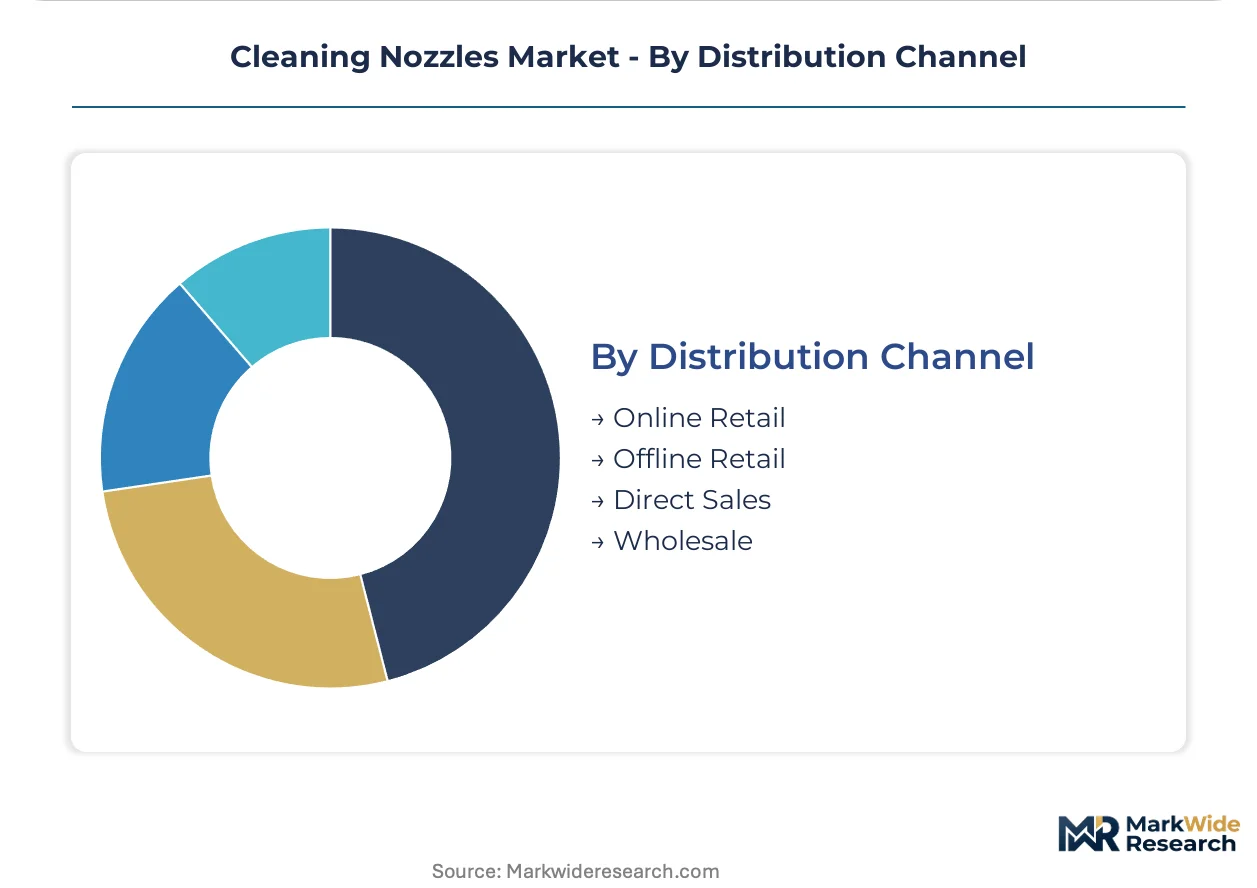
Distribution Channel:
Channel control patterns reflect whether end-users prioritize technical specification support or procurement cost minimization.
- Direct Sales:OEM-captive service divisions capture recurring revenue through nozzle replacement programs tied to food safety validation schedules. Lechler GmbH anchors European demand through captive foundry operations with direct technical specification support.
- Offline Retail:Authorized distributor networks serve maintenance managers requiring immediate availability for unplanned replacement cycles in continuous-process manufacturing.
- Wholesale:Volume aggregators supply MRO procurement for multi-site facility operators with standardized wash system configurations.
- Online Retail:E-commerce platforms capture price-sensitive spot purchases for standardized geometries with minimal technical consultation requirements.
Service bundling maturity is highest in direct sales. Digital procurement penetration is advancing fastest in online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel foundry capacity in Southern Germany anchors precision-engineered nozzle supply chains. REACH substance scrutiny on nickel alloy formulations is redrawing procurement geography across industrial cleaning markets.
Germany
Precision engineering clusters in Stuttgart-Tübingen and Metzingen concentrate five-axis CNC capacity for micro-orifice drilling below 0.5mm diameter. ECHA substance restrictions on chrome-nickel alloys are accelerating grade transitions in Bavarian dairy operations. Lechler GmbH's captive foundry operations in Baden-Württemberg secure supply security for 316L stainless variants.
United States
Dairy processors in Wisconsin specify CFD-validated spray patterns to minimize water carryover into pasteurization zones. EPA effluent guidelines for industrial cleaning wastewater mandate precision nozzle retrofits to reduce chemical oxygen demand. Metal finishing operations in Michigan and Ohio face NPDES permit limits on phosphate discharge.
China
Automotive pre-treatment lines in Yangtze River Delta manufacturing zones drive demand for high-pressure jet geometries. MEE wastewater discharge standards are tightening permissible chemical concentrations in industrial effluent. Zhengzhou and Shanghai industrial clusters are scaling domestic stainless machining capacity for wash system OEMs.
India
Food processing expansion in Maharashtra and Gujarat is creating specification pull for hygienic design validation under FSSAI safety protocols. BIS quality certification requirements are filtering supplier access for multinational OEM procurement. Dairy cooperative modernization in Karnataka and Tamil Nadu is accelerating automated clean-in-place system deployment.
Switzerland
Pharmaceutical bioprocessing growth in Basel-Rhine clusters demands validated spray patterns for single-use equipment cleaning. Swissmedic regulatory frameworks mandate surface finish documentation for multi-product facility cross-contamination prevention. Precision component suppliers in Zurich and Geneva cantons are specializing in Ra 0.4 micron finish certification.
Cleaning Nozzles Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue configurable sub-assembly architectures for automated wash skids. The vendor base stratifies across captive foundry operators, precision machining specialists, and retail channel controllers. Three archetypes dominate: vertically integrated European manufacturers with in-house stainless production, North American engineering houses with CFD-validated spray characterization, and diversified cleaning equipment conglomerates extending aftermarket services. Competitive moves concentrate on strategic partnerships for five-axis CNC capacity access and geographic expansion through authorized service network unbundling.
Among Germany-based precision fabricators, Lechler GmbH and Düsen-Schlick GmbH exemplify the captive foundry archetype with upstream control over stainless steel supply chains. Spraying Systems Co. represents the engineering-intensive North American model, leveraging R&D campus infrastructure for spray characterization protocol development. Kärcher Group occupies a position at the diversified equipment end, extending retail channel dominance into professional nozzle aftermarket subscription services across Central European markets.
| Leading Market Players |
|---|
| Nilfisk Group |
| Kärcher Group |
| Graco Inc |
| Spraying Systems Co. |
| Lechler GmbH |
| Alfa Laval |
| BETE |
| Delavan |
| Düsen-Schlick GmbH |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between Ra 0.8 surface finish 316L stainless and legacy brass inventories splits both pricing power and supply chain sourcing patterns across European dairy and pharmaceutical cleaning equipment. Premium FDA-validated nozzles command bundled service contracts through OEM-captive channels, while commodity brass replacements face spot-market pricing pressure amid REACH-mandated obsolescence.
Pricing Analysis
Warranty and validation-bundling separates OEM-captive subscription models from unbundled distributor spot purchases in this market. Three-tier pricing structure across premium, standard, and economy levels reflects surface finish certification, with Ra 0.4 micron pharmaceutical-grade variants capturing highest margins and 304-grade industrial specifications facing cost compression from nickel alloy feedstock volatility. Price erosion runs through legacy brass inventories as ECHA substance restrictions accelerate replacement cycles. Residential and light commercial buyers exhibit highest price sensitivity, while pharmaceutical bioprocessing facilities prioritize validation documentation over unit cost.
Supply Chain Analysis
Surface finish certification and third-party Ra validation protocols gate supplier access to pharmaceutical and dairy OEM qualification schedules. Manufacturing concentration centers on Germany, Sweden, and Finland for stainless steel foundry and five-axis CNC machining capacity. Raw material dependencies include LME-traded nickel, chrome alloy feedstock, and precision carbide drilling consumables. Single-source vulnerability concentrates in Stuttgart-Tübingen micro-orifice machining clusters below 0.5mm diameter. Distribution runs through authorized service networks for industrial specifications and retail channels for consumer-grade replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive stainless foundry operations and five-axis CNC capacity determine competitive survival. Players are pursuing upstream control over precision machining assets to secure supply security amid nickel alloy feedstock volatility.
For Market Incumbents: Acquire five-axis CNC machining capacity in Southern Germany to eliminate single-source dependency for micro-orifice drilling below 0.5mm diameter. Secure long-term offtake agreements with Swedish or Finnish stainless producers to insulate margin pools from LME nickel price swings. Defend against emerging Asian machining competitors by deepening FDA validation documentation and Ra surface finish certification capabilities. For New Entrants and Emerging Players: Launch via online retail platforms targeting price-sensitive residential and light commercial segments with polypropylene and PVDF formulations below 60°C operating temperatures. Target pharmaceutical bioreactor cleaning applications in Basel-Rhine clusters where single-use equipment growth outpaces incumbent capacity expansion. Pursue white-space in Indian dairy cooperative modernization programs requiring FSSAI-compliant hygienic design validation. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified cleaning equipment conglomerates seeking aftermarket service network expansion. Long-term viability favors vertically integrated fabricators with captive foundry operations and validated pharmaceutical surface finish capabilities. Monitor ECHA substance restriction timelines as inflection indicator for accelerated replacement cycle velocity across European food processing installed base.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Acquisition | Secures 316L stainless supply security amid REACH nickel alloy scrutiny. |
| Five-Axis CNC Capacity Expansion | Eliminates single-source dependency for micro-orifice precision drilling. |
| Subscription Service Unbundling | Captures recurring revenue from food safety audit-driven replacement schedules. |
| Pharmaceutical Validation Investment | Enables Ra 0.4 micron finish certification for bioreactor cleaning applications. |
| Authorized Service Network Expansion | Consolidates aftermarket procurement away from distributor spot-buying. |
Study Parameters
Trade association filings, customs and import-export databases, and SEC 10-K regulatory disclosures formed the secondary backbone for market sizing and competitive landscape mapping. Primary interviews with maintenance directors at dairy processing facilities, OEM procurement teams for automated wash systems, aftermarket service heads, and precision machining specialists combined with secondary validation to triangulate demand patterns. Bottom-up unit economics and top-down industry value chain analysis converged on segment-level estimates.
Historical trendline analysis across installed base replacement cycles, automation adoption curves, and regulatory compliance deadlines informed projection frameworks. Segmentation dimensions modeled include product type, material grade, surface finish certification tier, application automation intensity, and distribution channel structure. CAGRs derived from regression analysis against water stress economics, REACH implementation timelines, and clean-in-place system deployment rates. Forecast inputs incorporated stainless steel foundry capacity utilization and five-axis CNC bottleneck severity indices.
REACH substance restriction acceleration, LME nickel price volatility spikes, and pharmaceutical OEM qualification timeline extensions are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding regulatory implementation schedules and replacement cycle elasticity. A model refresh is warranted upon material change in ECHA substance restriction enforcement intensity or stainless steel feedstock contract pricing structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Fabric Softener Market
Cleaning Chemicals
Industrial Degreaser Market
Cleaning Chemicals
Biodegradable Spray Tank Line-Cleaning Chemistry Market
Cleaning Chemicals
Global Metal Cleaning Chemicals Market
Cleaning Chemicals
Commercial Cleaning Products Market
Cleaning Chemicals
Industrial Cleaners Market
Cleaning Chemicals
Latin America Detergent Market
Cleaning Chemicals
Global Dust Suppression and Control Chemicals Market
Cleaning Chemicals
Housekeeping Chemicals for Hotels and Resorts Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market
Cleaning Chemicals
Mosquito Repellent Market
Cleaning Chemicals
Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market
Cleaning Chemicals
Adhesive Remover Market
Cleaning Chemicals
Soap and Detergent Market
Cleaning Chemicals
Document Cleaning Powder Market
Cleaning Chemicals
Liquid Detergent Market