
 North America Emission Monitoring System Market | 2026-2036
North America Emission Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Emission Monitoring System Market Insights
Utility buyers are collapsing historical procurement timelines for emission monitoring infrastructure as EPA compliance deadlines compress installation windows. Emerson Electric Co. leverages its DeltaV distributed control platform to anchor integrated monitoring contracts across Midwest power plants. ABB Ltd. competes through its AC500 PLC architecture paired with gas analyzer modules. Thermo Fisher Scientific specializes in mass spectrometry detection for trace-level mercury quantification in coal-fired stack gas.
An emission monitoring system comprises gas analyzers, data acquisition hardware, and regulatory reporting software engineered to quantify pollutant concentrations in industrial exhaust streams, typically measuring SO2, NOx, CO, CO2, and particulate matter at detection thresholds below 1 ppm. Infrared sensors dominate the technology segment due to proven reliability in high-temperature flue gas environments and lower total cost of ownership versus acoustic alternatives. Software offerings represent the fastest-expanding revenue pool as utilities migrate from on-premise data loggers to cloud-native compliance dashboards with automated EPA reporting. Integrated solutions command premium positioning by bundling hardware, calibration services, and regulatory submission workflows into single-contract structures.
The EPA enforces Continuous Emission Monitoring System requirements under 40 CFR Part 75, mandating hourly data reporting from fossil fuel combustion sources. The FAA coordinates with EPA on aircraft engine emission certification under ICAO Annex 16 equivalence, while NHTSA tailpipe standards indirectly shape portable analyzer demand for automotive testing laboratories. Stakeholders must monitor pending revisions to MATS compliance timelines and emerging state-level carbon intensity rules that could redefine sensor calibration protocols and data retention requirements.
Market Dynamics
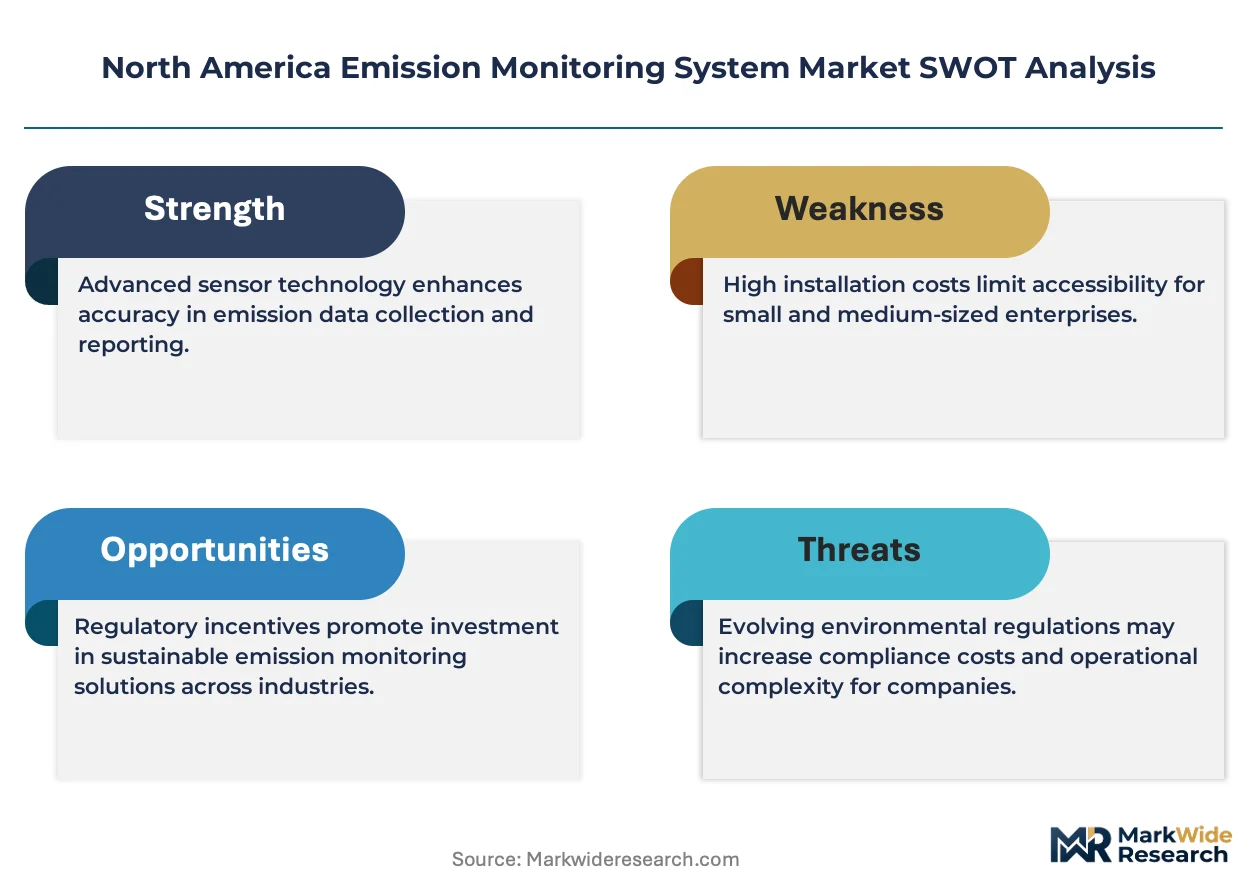
Utility procurement cycles for emission monitoring hardware are compressing from 18-month windows to 90-day sprints as EPA Mercury and Air Toxics Standards enforcement intensifies across coal-fired and natural gas generation fleets.
Growth Catalysts
- MATS Compliance Deadlines:EPA enforcement under 40 CFR Part 75 is forcing power utilities to retrofit continuous emission monitoring systems ahead of scheduled plant assessments, pulling forward capital deployment timelines.
- Texas Refinery Cluster Density:The Gulf Coast petrochemical corridor hosts the continent's highest concentration of FCCU and coker units, generating concentrated demand for multi-pollutant stack analyzers.
- Cloud-Native Software Migration:Utilities are abandoning on-premise data loggers for automated EPA reporting platforms, expanding recurring service contract revenue pools.
Market Restraints
- Specialized Sensor Supply Concentration:Infrared detector manufacturing concentrates among German and Japanese component suppliers, exposing North American integrators to 12-16 week lead time volatility.
- High-Temperature Probe Degradation:Ceramic sampling probes in coal-fired flue gas environments require quarterly replacement, elevating total cost of ownership above acoustic alternatives.
- State-Level Carbon Intensity Rule Fragmentation:California's cap-and-trade protocols impose calibration standards incompatible with Texas ERCOT reporting requirements, forcing dual certification investments.
Strategic Opportunities
- Mexican Power Sector Liberalization:CENACE grid reforms are opening independent power producer contracts requiring CEMS installation for natural gas combined-cycle plants in Baja California and Nuevo León.
- Aviation Engine Test Cell Expansion:FAA-EPA coordination under ICAO Annex 16 equivalence is driving demand for portable FTIR analyzers at GE Aerospace and Pratt & Whitney validation facilities.
- Edge Computing Convergence:On-stack AI inference chips are enabling real-time anomaly detection without cloud latency, creating hardware-software bundled service models.
Industry Challenges
- Cross-Trained Technician Scarcity:Field engineers must simultaneously certify on EPA protocol gas calibration, PLC programming, and cybersecurity hardening, extending hiring cycles to 4-6 months.
- Legacy DCS Integration Friction:1990s-era distributed control systems at Midwest coal plants lack OPC-UA connectivity, requiring expensive protocol gateway hardware for modern analyzer integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Emission Monitoring System Market |
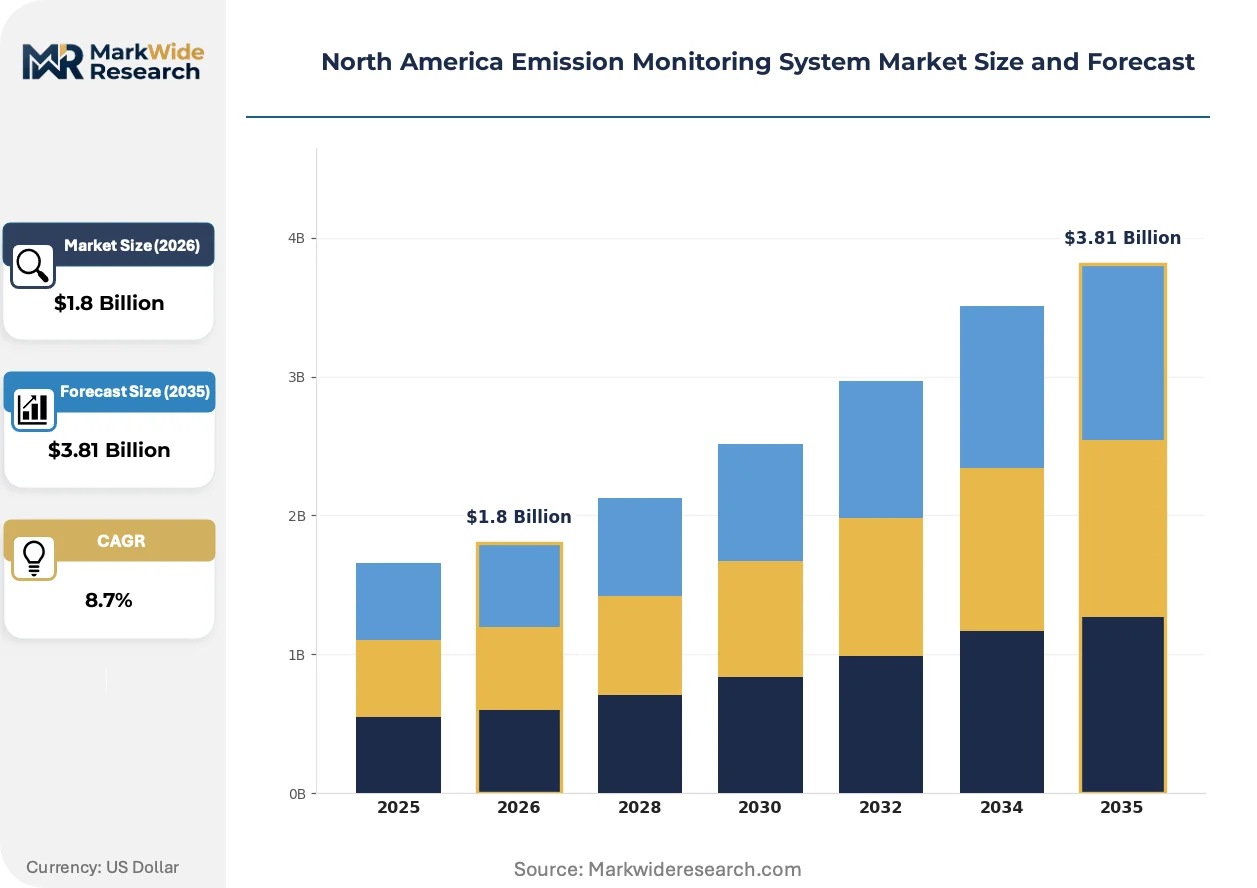
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Chemical Sensors, Optical Sensors, Acoustic Sensors, Infrared Sensors End User: Manufacturing, Oil & Gas, Utilities, Transportation Offering: Hardware, Software, Services, Integrated Solutions Installation: Permanent, Portable, Remote Monitoring, Centralized Systems |
| Companies Covered | ABB Ltd., AMETEK, Inc., Emerson Electric Co., Siemens AG, Thermo Fisher Scientific, GE Vernova, Rockwell Automation, Teledyne Technologies Incorporated, SICK AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Emission Monitoring System Market Trends and Innovations
Digital twin architectures and predictive calibration algorithms are compressing maintenance intervals while EPA reporting automation is eliminating manual data transcription errors across utility compliance workflows.
Tunable diode laser absorption spectroscopy is decomposing the historical dominance of extractive sampling systems in high-particulate flue gas applications. Southwestern coal utilities are deploying TDLAS for in-situ ammonia slip monitoring at SCR outlets, eliminating heated sample line maintenance. This technology is decomposing the installed base of chilled-mirror hygrometers and conventional IR benches.
EPA's pending revisions to MATS compliance timelines under 40 CFR Part 63 are tightening mercury monitoring frequency requirements for lignite-burning units. The industrial consequence is accelerated replacement of cold-vapor atomic absorption systems with higher-sensitivity mass spectrometry detection. Texas and North Dakota lignite operators are pre-positioning analyzer upgrades ahead of anticipated 2025-2026 rule finalization.
Utility engineering departments are consolidating vendor relationships from multi-supplier hardware-procurement models to single-source integrated monitoring contracts. Equipment distributors with calibration service capabilities are displacing traditional manufacturer-direct sales channels. This consolidation is most visible among municipal power authorities in the Upper Midwest seeking bundled hardware-service-regulatory submission packages.
North America Emission Monitoring System Market Segmentation
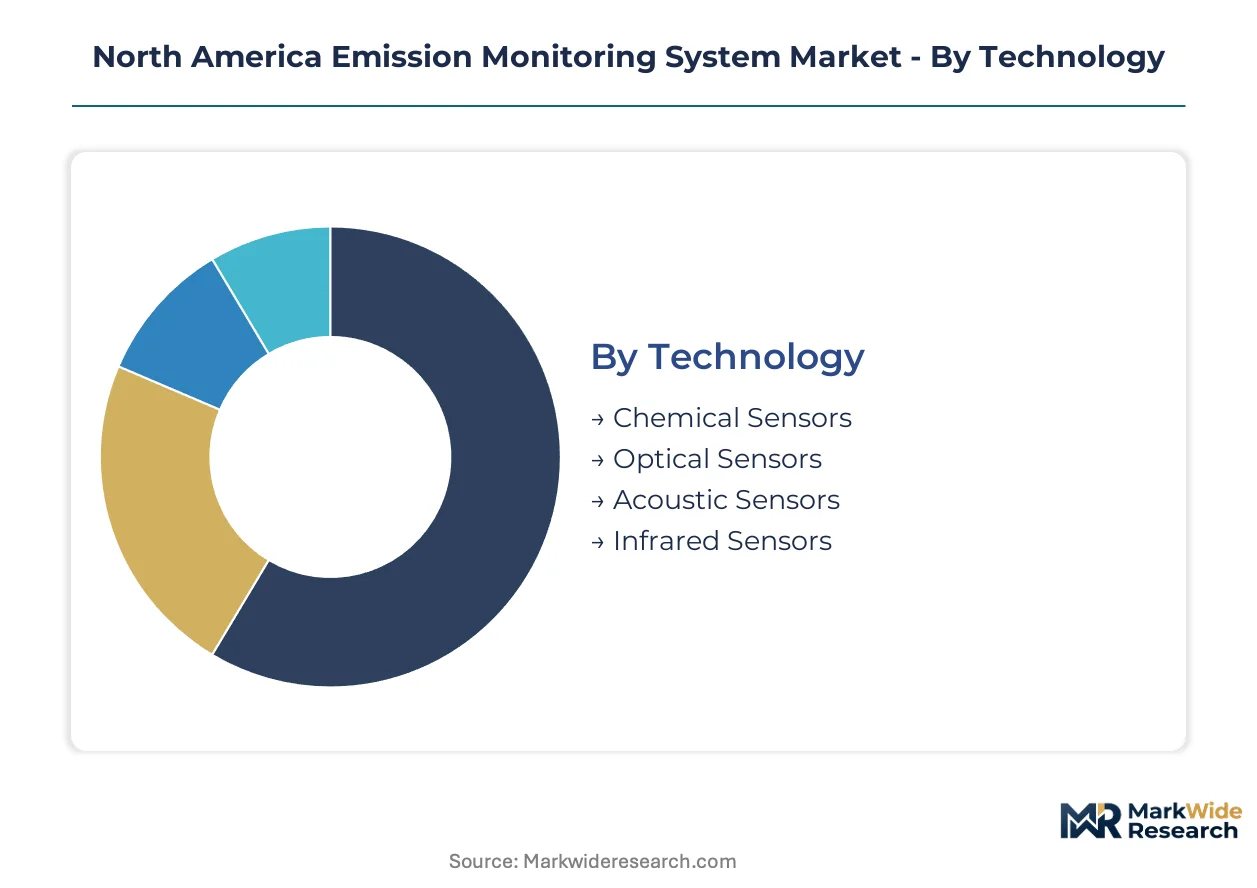
Emission monitoring procurement patterns diverge sharply across technology generations and customer sophistication tiers. Vendor pricing power concentrates where hardware-software integration creates switching costs for regulated utilities facing EPA enforcement timelines.
Technology:
Margin pools concentrate in sensor platforms that minimize calibration frequency while maintaining sub-ppm detection thresholds for MATS compliance.
- Infrared Sensors:Non-dispersive infrared benches measure CO, CO2, and SO2 through gas-specific absorption bands at 4.26 µm and 7.3 µm wavelengths. Texas Gulf Coast refineries specify these for FCCU regenerator stacks where thermal stability exceeds 200°C, though ceramic probe degradation elevates replacement costs versus acoustic alternatives.
- Optical Sensors:Tunable diode laser absorption spectroscopy enables in-situ ammonia slip quantification at SCR outlets without heated sample lines. Southwestern coal utilities are deploying TDLAS to eliminate chilled-mirror hygrometer maintenance, decomposing historical extractive sampling dominance.
- Chemical Sensors:Electrochemical cells provide cost-effective NOx detection for smaller combustion sources below 250 MMBtu/hr thermal input.
- Acoustic Sensors:Ultrasonic time-of-flight analyzers measure flue gas velocity and particulate loading in high-dust environments.
Infrared sensors hold installed capacity across coal-fired baseload fleets. Optical sensors are rotating up the share rankings as utilities prioritize reduced maintenance intervals.
End User:
Customer concentration follows regulatory enforcement intensity rather than absolute facility counts.
- Utilities:Coal and natural gas power generators face 40 CFR Part 75 mandates for hourly SO2, NOx, and CO2 reporting. Midwest municipal authorities are consolidating procurement around single-source integrated contracts bundling hardware, calibration services, and EPA submission workflows.
- Oil & Gas:Refinery FCCU and coker units require multi-pollutant stack monitoring for benzene, 1,3-butadiene, and hydrogen sulfide under refinery MACT standards. The Gulf Coast petrochemical corridor generates concentrated analyzer demand where process heaters and flares exceed 100 tons per year hazardous air pollutant thresholds.
- Manufacturing:Cement kilns and steel minimills deploy portable FTIR analyzers for periodic compliance demonstrations.
- Transportation:Aircraft engine test cells at GE Aerospace and Pratt & Whitney facilities require ICAO Annex 16 equivalence certification.
Utilities anchor capital deployment volumes. Oil & gas is climbing fastest as refinery MACT enforcement tightens.
Offering:
Recurring revenue intensity escalates from discrete hardware sales toward subscription-based compliance automation.
- Software:Cloud-native EPA reporting platforms automate data validation, missing data substitution, and electronic submission under 40 CFR Part 75. Utilities are abandoning on-premise data loggers for these solutions, expanding annual contract value per installation.
- Integrated Solutions:Single-contract structures bundle gas analyzers, data acquisition hardware, calibration gas supply, and regulatory submission services. Equipment distributors with field service capabilities are displacing manufacturer-direct channels among Upper Midwest municipal power authorities.
- Hardware:Gas analyzers, sample conditioning systems, and data acquisition equipment constitute upfront capital expenditure.
- Services:Protocol gas calibration, quarterly maintenance, and certification auditing support ongoing compliance.
Hardware commands upfront procurement budgets. Software is expanding most quickly as utilities migrate compliance workflows to cloud infrastructure.
Installation:
Deployment architecture tradeoffs reflect facility permanence and regulatory scrutiny levels.
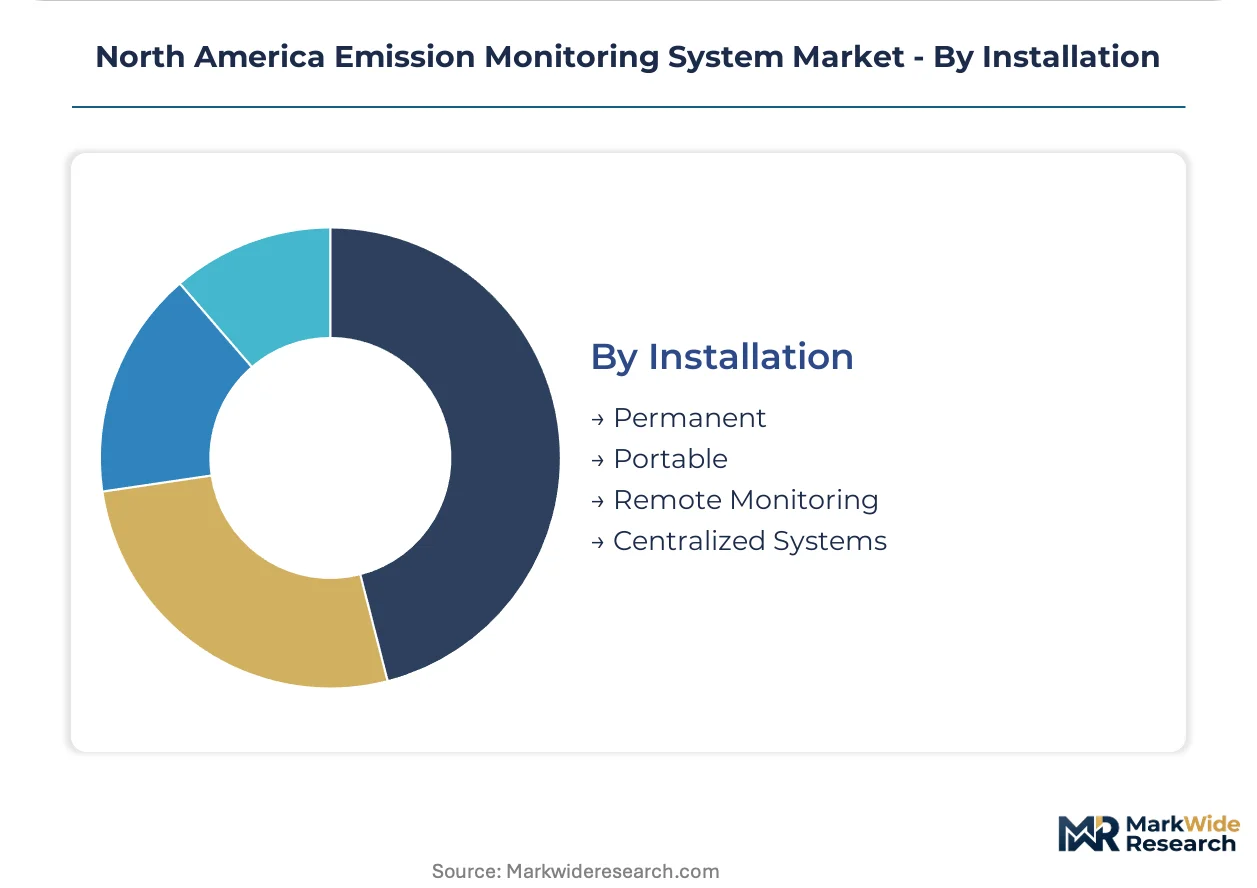
- Permanent:Continuous emission monitoring systems with heated sample lines and shelter-mounted analyzers serve baseload power plants and large refineries. These installations require 90-day procurement sprints as EPA compliance deadlines compress.
- Portable:Handheld FTIR and electrochemical analyzers enable spot-checking at automotive testing laboratories and smaller manufacturing sources.
- Remote Monitoring:Cellular-enabled data loggers transmit hourly averages to central compliance dashboards without on-site personnel.
- Centralized Systems:Multi-stack monitoring networks consolidate sampling and analysis for large industrial complexes.
Permanent installations dominate capital allocation. Portable units are gaining traction as state-level carbon intensity rules fragment calibration requirements across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports analyzer components and calibration gases to United States utilities under EPA-driven procurement contracts. Mexico receives integrated monitoring systems from Texas-based distributors serving CENACE-regulated power projects.
United States
EPA enforcement under 40 CFR Part 75 drives utility retrofit cycles across coal and natural gas fleets. The Mercury and Air Toxics Standards compress installation windows to 90-day procurement sprints. Texas Gulf Coast refineries and California power authorities host the densest concentrations of multi-pollutant stack monitoring infrastructure.
Canada
Alberta oil sands operators deploy continuous emission monitoring for SAGD facility stack compliance under provincial environmental protection acts. Environment and Climate Change Canada coordinates with EPA on cross-border air quality monitoring protocols. Ontario power generators concentrate analyzer demand around Lake Erie industrial corridors.
Mexico
CENACE grid liberalization mandates CEMS installation for independent power producers in Baja California and Nuevo León. SEMARNAT emission standards for natural gas combined-cycle plants align with EPA technical specifications. Monterrey industrial parks attract bundled hardware-service contracts from cross-border equipment distributors.
North America Emission Monitoring System Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with process automation heritage. Market structure concentrates around vertically integrated suppliers controlling hardware manufacturing, software platforms, and field service networks. Two strategic archetypes dominate: control system vendors bundling emission monitoring into distributed control platforms, and analytical instrument specialists focusing on detection sensitivity for trace-level compliance. Competitive moves center on single-source contract consolidation and predictive maintenance service expansion.
Among diversified automation conglomerates, ABB Ltd., Emerson Electric Co., and Siemens AG represent the integrated-platform archetype. These Swiss, American, and German entities occupy positions where distributed control system penetration creates captive pathways for emission monitoring hardware attachment. Thermo Fisher Scientific exemplifies the analytical-specialist tier, anchoring mass spectrometry detection capabilities for mercury quantification requirements. The competitive terrain rewards vendors combining EPA reporting software with calibration service infrastructure.
| Leading Market Players |
|---|
| ABB Ltd. |
| AMETEK, Inc. |
| Emerson Electric Co. |
| Siemens AG |
| Thermo Fisher Scientific |
| GE Vernova |
| Rockwell Automation |
| Teledyne Technologies Incorporated |
| SICK AG |
| Others |
Pricing and Supply Chain Analysis
Tunable diode laser absorption spectroscopy displacement of extractive sampling systems simultaneously redraws component sourcing maps and compresses maintenance-contract pricing across Southwestern coal utility fleets. This technology substitution shifts procurement gravity from heated sample line fabricators toward semiconductor laser diode suppliers, altering vendor bargaining positions and service revenue structures.
Pricing Analysis
Next-generation optical sensor platforms command 40-60% premiums over conventional infrared benches, though total cost of ownership advantages from eliminated probe maintenance erode that gap across multi-year contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by detection sensitivity thresholds and EPA certification tier. Pricing pressure stems from Mexican power sector liberalization drawing Texas-based distributors into cross-border bundled contracts with compressed margins. Municipal power authorities in the Upper Midwest exhibit highest price sensitivity due to constrained capital budgets, while Gulf Coast refineries prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Germany and Japan anchor infrared detector manufacturing, feeding North American integrators with ceramic substrate and thermopile components. German component houses supply tunable laser diodes for next-generation optical platforms, while Japanese fabs dominate pyroelectric detector output. Supply chain risk centers on 12-16 week lead time volatility from single-source semiconductor laser suppliers. Distribution runs through equipment distributors with calibration service capabilities, displacing manufacturer-direct channels among consolidated utility procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America emission monitoring system market rewards vendors controlling scarce cross-trained technician pools capable of simultaneous EPA protocol certification, PLC programming, and cybersecurity hardening. This capability bottleneck constrains expansion velocity and anchors competitive differentiation.
For Market Incumbents: Secure calibration service infrastructure in Texas and California corridor markets to defend against distributor-led channel displacement. Consolidate field engineer certification programs to narrow hiring cycles from 4-6 months toward industry-leading 8-12 week onboarding. Backward integration into semiconductor laser diode sourcing mitigates German and Japanese supplier concentration risk. For New Entrants and Emerging Players: Anchor in Mexican CENACE-regulated power projects where bundled hardware-service contracts lack established incumbent relationships. Target independent power producers in Baja California and Nuevo León with EPA-aligned SEMARNAT compliance packages. Go-to-market leverage rests on cross-border logistics capabilities and Spanish-language field service teams. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed analytical instrument specialists holding mass spectrometry detection capabilities for pending MATS mercury monitoring upgrades. Long-term viability hinges on software recurring revenue ratios above 35% of contract value. Signal to watch: EPA finalization of 40 CFR Part 63 revisions accelerating cold-vapor atomic absorption system replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Calibration Algorithm Development | Reduces field service dispatch frequency for Midwest coal plant operators under EPA Part 75 mandates. |
| Single-Source Integrated Contract Consolidation | Captures multi-year recurring revenue pools from municipal power authorities abandoning multi-vendor procurement. |
| Cross-Border Service Infrastructure Buildout | Positions Texas-based distributors for CENACE-mandated CEMS installations across Mexican IPP projects. |
| Edge Computing Hardware-Software Bundling | Creates differentiated service models through on-stack AI inference chips enabling real-time anomaly detection. |
| TDLAS Platform Commercialization | Eliminates heated sample line maintenance costs for Southwestern utilities monitoring SCR ammonia slip. |
Research Methodology
Operator-level perspectives from utility engineering directors, refinery environmental compliance officers, CEMS field service technicians, and equipment distribution channel managers anchored the qualitative base. Primary interview findings triangulated against EPA enforcement action databases, FERC generation capacity filings, EIA power plant emissions data, and SEC 10-K disclosures from publicly traded automation conglomerates. Bottom-up installation counts across coal, natural gas, and refinery stacks converged with top-down market sizing derived from capital expenditure patterns across the analysis window.
Sensitivity analysis tested forecast outputs against varying MATS compliance timeline assumptions and Mexican power sector liberalization velocity scenarios. Segmentation modeling spanned technology generation, end-user regulatory intensity, offering type, and installation architecture across the projection horizon. CAGRs derived from unit deployment trajectories weighted by average contract values, with specific inputs including EPA enforcement staffing levels and state-level carbon intensity rule proliferation rates.
Material uncertainties — pending 40 CFR Part 63 mercury monitoring revisions, semiconductor laser diode supply disruptions, and cross-border trade policy shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and technology substitution curves. Recalibration cycles align with material shifts in EPA rulemaking timelines and CENACE grid reform implementation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Environmental Test Equipment Market
Environmental Monitoring
Asia-Pacific Cloud Seeding Market
Environmental Monitoring
South America Air Quality Monitoring Market
Environmental Monitoring
US Cloud Seeding Market
Environmental Monitoring
Water Testing Market
Environmental Monitoring
Pollution Monitoring Equipment Market
Environmental Monitoring
End-Of-Pipe Air Pollution Control Equipment Market
Environmental Monitoring
Global Environmental Sensor Market
Environmental Monitoring
Weather Modification Equipment Market
Environmental Monitoring
Environment Monitoring Devices Market
Environmental Monitoring
Ecotoxicological Studies Market
Environmental Monitoring
Environmental Monitoring (Surface Water) Market
Environmental Monitoring
Global on-Line Total Organic Carbon (TOC) Analyzer Market
Environmental Monitoring
Continuous Emission Monitoring Systems (CEMS) Market
Environmental Monitoring
Air Quality Monitoring Equipment Market
Environmental Monitoring
United States Erosion Sediment Control Market