
 Canada Cloud Seeding Market | 2026-2036
Canada Cloud Seeding Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Cloud Seeding Market Insights
Market Context
Multi-source contracting for silver iodide generators and aircraft services is restructuring procurement across provincial cloud seeding programs. North American Weather Consultants leverages its long-standing relationships with Alberta's agricultural agencies to sustain recurring revenue streams. Weather Modification, Inc. competes through specialized ice nuclei delivery systems that dominate western Canadian hail suppression contracts. Snowy Hydro Limited anchors its position by transferring Australian alpine expertise into North American cold-cloud operations.
Technical and Segment Dynamics
Canada cloud seeding deploys hygroscopic and glaciogenic agents—primarily silver iodide and potassium chloride—via aircraft-mounted flares or ground-based generators to induce or enhance precipitation from supercooled cloud systems. The process requires precise atmospheric monitoring, with operations typically conducted at altitudes between 4,000 and 8,000 meters where cloud temperatures range from -5°C to -20°C. Aircraft-based technology leads deployment spending due to the vast territorial coverage required across Prairie provinces, while drone-based systems represent the fastest-growing segment as Transport Canada develops beyond-visual-line-of-sight frameworks for unmanned atmospheric operations. Water Resource Management end users command the largest procurement budgets, though Drought Mitigation solutions concentrate margin pools through multi-year provincial emergency funding mechanisms.
Regulatory Environment and Outlook
Environment and Climate Change Canada oversees weather modification licensing under the Environmental Protection Act, while Transport Canada regulates aircraft and drone operations through CARs Part VI and emerging RPAS standards. Health Canada's PMRA evaluates silver iodide ecotoxicology under pesticide registration frameworks, creating compliance layers that shape product formulation choices. Stakeholders must monitor how provincial climate adaptation strategies rebalance funding between reactive drought response and proactive precipitation enhancement programs.
Market Dynamics
Transport Canada's beyond-visual-line-of-sight drone regulations are compressing operational timelines for Prairie cloud seeding contracts, forcing operators to restructure crew deployment and aircraft-generator hybrid models.
Growth Catalysts
- Alberta Emergency Drought Funding:Provincial multi-year appropriations for precipitation enhancement programs lock in recurring revenue streams for aircraft service providers.
- Silver Iodide Generator Modernization:Ground-based hygroscopic delivery systems are displacing legacy acetone burners in Saskatchewan's agricultural zones.
- Environment and Climate Change Canada Licensing Framework:Streamlined Environmental Protection Act permitting for weather modification activities accelerates contract activation timelines.
Market Restraints
- Silver Iodide Supply Concentration:Domestic refining capacity for cloud seeding-grade silver iodide concentrates in single-source jurisdictions, exposing procurement to metal price volatility.
- PMRA Ecotoxicology Review Cycles:Health Canada's pesticide registration frameworks impose multi-year evaluation windows on novel nucleating agents.
- Aircraft Maintenance Cost Escalation:Turboprop fleet availability constraints in western Canada inflate hourly operating rates for cloud seeding missions.
Strategic Opportunities
- Manitoba Underpenetration:The province's Red River Valley lacks established hail suppression programs, presenting first-mover positioning for ice nuclei service contracts.
- Drone-Aircraft Hybrid Operations:Transport Canada's RPAS standards enable unmanned systems to augment manned seeding missions in restricted airspace corridors.
- Indigenous Water Rights Partnerships:First Nations co-management agreements for watershed stewardship create novel procurement channels outside provincial tender processes.
Industry Challenges
- Atmospheric Physics Talent Scarcity:Cloud microphysics specialists with operational meteorology experience command premium compensation, constraining program scale-up.
- Multi-Jurisdictional Compliance Burden:Operators must simultaneously satisfy Environment and Climate Change Canada licensing, Transport Canada aviation rules, and PMRA chemical handling protocols.
- Legacy Generator Integration:Ground-based silver iodide installations from the 1990s require retrofitting to meet current PMRA discharge monitoring standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Cloud Seeding Market |
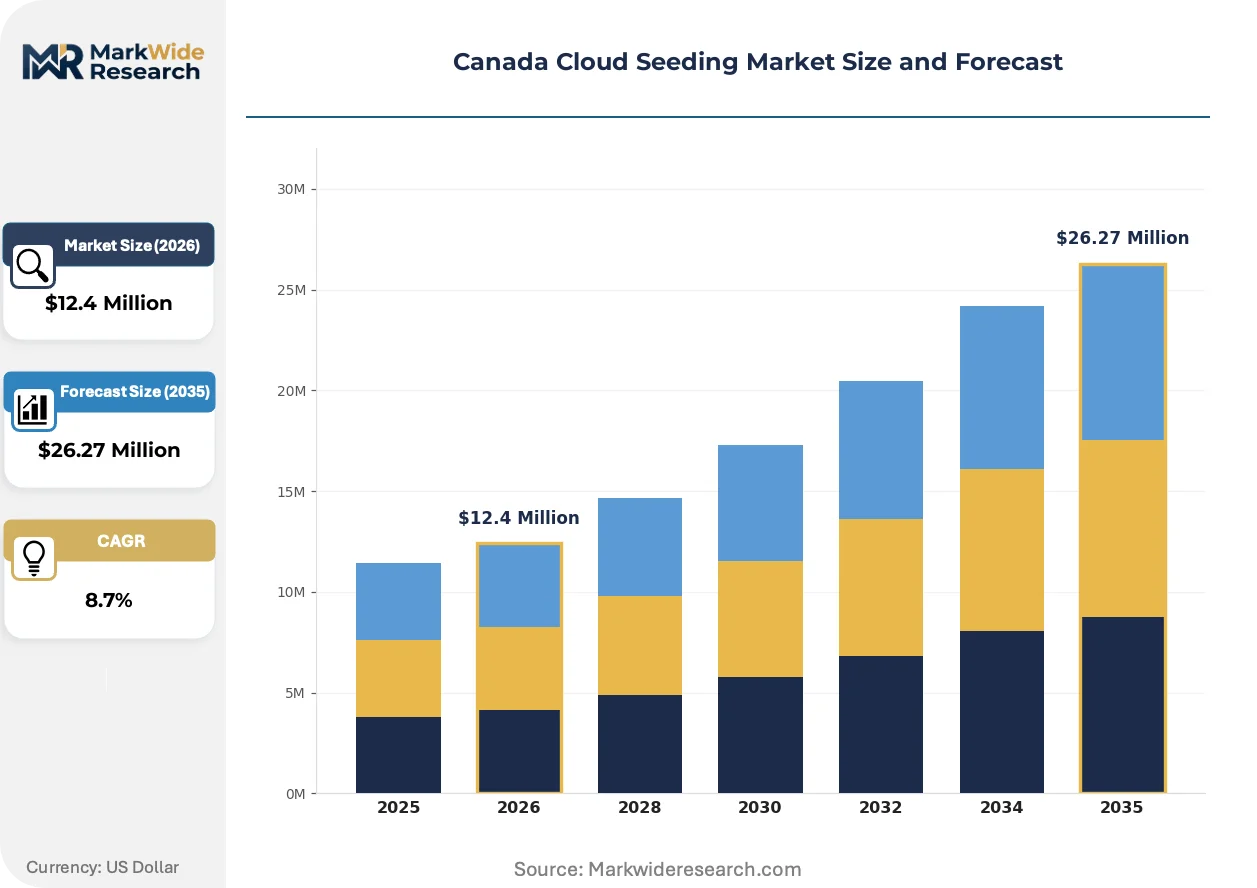
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $26.27 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ground-based, Aircraft-based, Rocket-based, Drone-based End User: Agriculture, Water Resource Management, Government Agencies, Research Institutions Deployment: Onshore, Remote, Urban, Rural Solution: Weather Modification, Climate Control, Drought Mitigation, Precipitation Enhancement |
| Companies Covered | North American Weather Consultants, Snowy Hydro Limited, Weather Modification, Inc., Ice Crystal Engineering, WeatherTec Services, Inc., Alberta Hail Suppression Project, Aquila Air Traffic Management Services, Western Weather Consultants, Weather Modification International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Cloud Seeding Market Trends and Innovations
Digital atmospheric sensing and unmanned platform integration are compressing the decision-to-action cycle for cloud seeding operations across the Prairie Provinces.
Drone-mounted hygroscopic flares are converging with ground-based silver iodide generator networks to create layered precipitation enhancement architectures. Alberta's agricultural water authorities are piloting these hybrid systems in the Palliser Triangle. The convergence is compressing capital requirements for new market entrants while fragmenting service contracts across multiple technology providers.
Environment and Climate Change Canada's revised Environmental Protection Act guidance on weather modification licensing tightens public notification and downstream monitoring obligations. The industrial consequence elevates compliance documentation costs for multi-provincial operators. Saskatchewan's drought mitigation programs are responding by centralizing contracting through single-province procurement vehicles to streamline regulatory alignment.
Provincial water authorities are unbundling aircraft service contracts from chemical supply agreements, fragmenting vendor relationships that previously ran through integrated operators. This procurement restructuring disrupts long-standing sole-source arrangements in Alberta's agricultural districts. The shift is most visible in Saskatchewan, where separate RFPs for silver iodide flares and flight hours have attracted specialized chemical manufacturers without aviation assets.
Canada Cloud Seeding Market Segmentation
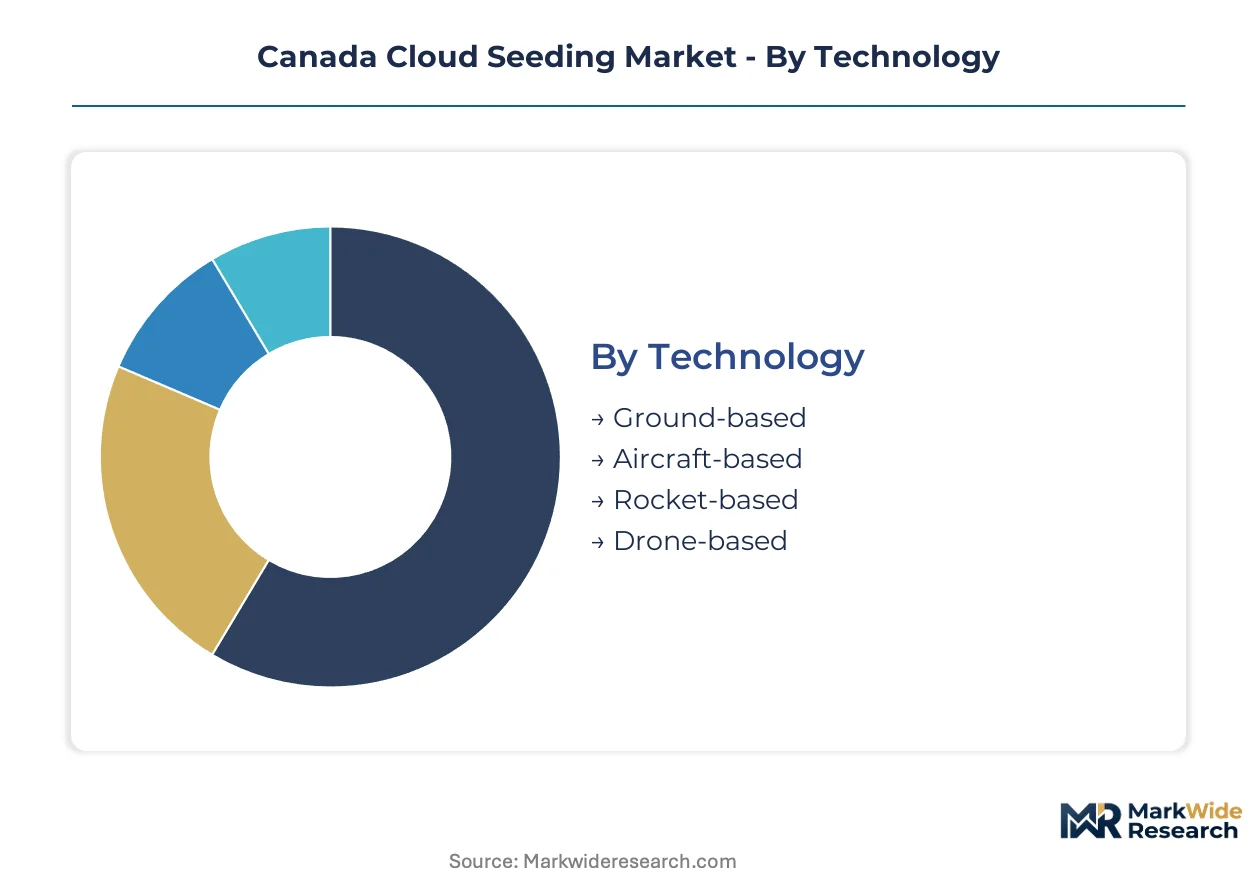
Cloud seeding procurement in Canada fragments across operational platforms, institutional buyers, geographic contexts, and atmospheric objectives. Understanding these divides reveals where capital concentrates and where regulatory friction shapes vendor selection.
Technology:
Standalone systems operate independently with dedicated infrastructure, while embedded technologies integrate into broader meteorological or aviation networks.
- Aircraft-based:Manned turboprop platforms deploy silver iodide flares at 4,000-8,000 meter altitudes across Prairie Provinces. Alberta's agricultural water authorities anchor demand through multi-year service contracts covering vast territorial footprints.
- Drone-based:Unmanned systems equipped with hygroscopic payload delivery operate under emerging Transport Canada beyond-visual-line-of-sight frameworks. Saskatchewan's drought mitigation programs are piloting these units in restricted airspace corridors where manned aircraft face operational constraints.
- Ground-based:Fixed-position silver iodide generators and acetone burners installed at elevation points in agricultural zones. These systems require minimal aviation coordination but depend on favorable wind patterns for nuclei dispersion.
- Rocket-based:Artillery-launched seeding charges deployed for hail suppression in localized storm cells. Limited adoption in Canada due to airspace restrictions and safety protocols around populated areas.
Aircraft-based technology leads volumes today; drone-based systems are expanding most quickly.
End User:
Procurement authority concentrates in public institutions with statutory water management mandates, while private demand remains nascent.
- Water Resource Management:Provincial water authorities in Alberta and Saskatchewan command the largest procurement budgets through statutory drought response mandates. These entities structure multi-year appropriations that lock in recurring revenue for service providers.
- Government Agencies:Environment and Climate Change Canada licensing requirements shape operational parameters for all seeding activities. Federal and provincial emergency management departments fund reactive precipitation enhancement during declared drought conditions.
- Agriculture:Commodity boards and irrigation districts in the Palliser Triangle purchase hail suppression and moisture enhancement services. Farm-level demand concentrates in high-value crop zones where yield protection justifies per-hectare service fees.
- Research Institutions:Universities and atmospheric science centers operate seeding equipment for cloud microphysics studies. Funding derives from federal research grants rather than operational service contracts.
Water Resource Management dominates procurement value; Government Agencies show the steepest expansion trajectory during emergency funding cycles.
Deployment:
Geographic context determines infrastructure requirements, with remote operations demanding autonomous systems and urban proximity triggering stricter safety protocols.
- Rural:Agricultural districts across Alberta and Saskatchewan host the majority of active seeding operations. Ground-based generator networks and aircraft staging facilities concentrate in these zones with minimal population density constraints.
- Remote:Northern watersheds and forest fire suppression zones require extended-range aircraft and satellite-linked monitoring. Indigenous co-management agreements for watershed stewardship are opening novel procurement channels in these areas.
- Onshore:Standard territorial operations within provincial boundaries under established regulatory frameworks. Most commercial contracts operate under this classification with clear jurisdictional authority.
- Urban:Peri-urban hail suppression around Calgary and Edmonton faces stricter Transport Canada airspace coordination. Limited active programs due to population density and liability considerations.
Rural deployment anchors operational hours; Remote deployment is climbing the fastest through Indigenous partnership structures.
Solution:
Service offerings range from reactive emergency response to proactive atmospheric management, with funding mechanisms and contract durations varying accordingly.
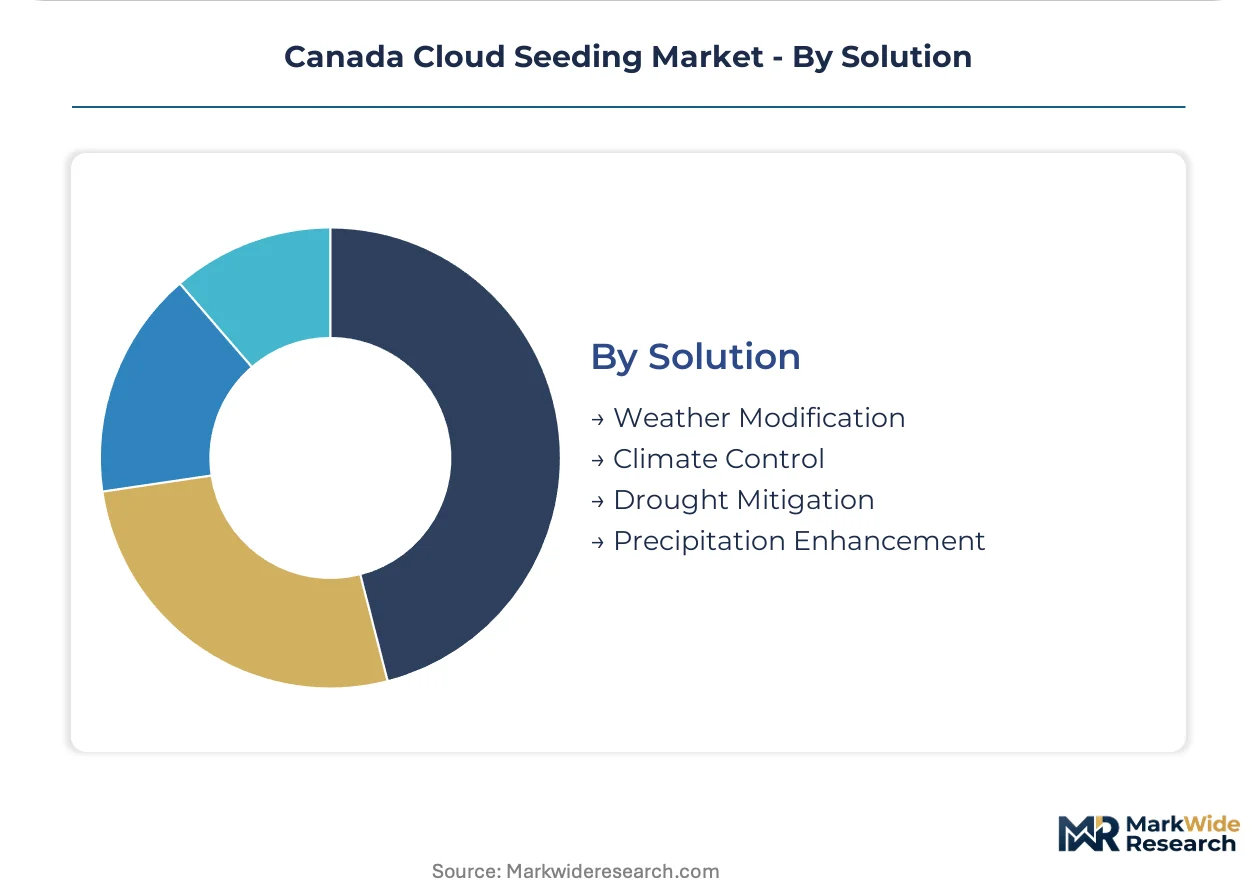
- Drought Mitigation:Emergency precipitation enhancement activated during declared water shortage conditions. Provincial multi-year appropriations in Alberta and Saskatchewan concentrate margin pools through guaranteed funding mechanisms.
- Precipitation Enhancement:Proactive cold-cloud seeding to increase snowpack and reservoir inflows. Alberta's agricultural water authorities structure these as recurring seasonal contracts with performance monitoring requirements.
- Weather Modification:Broad-category licensing under Environment and Climate Change Canada frameworks encompassing hail suppression, fog dispersal, and moisture enhancement. Regulatory compliance costs elevate barriers for multi-provincial operators.
- Climate Control:Long-term atmospheric intervention programs with multi-decade monitoring horizons. Theoretical positioning in Canada with limited active deployment due to scientific uncertainty and funding constraints.
Drought Mitigation commands the largest share of government procurement; Precipitation Enhancement is gaining share fastest as provinces shift from reactive to proactive water security strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Prairie Provinces anchor cloud seeding demand through provincial drought mitigation programs and agricultural water security mandates.
Alberta
Provincial water authorities command the largest procurement budgets through multi-year appropriations for precipitation enhancement. Environment and Climate Change Canada's Environmental Protection Act licensing requirements shape operational parameters for all seeding activities. The Palliser Triangle agricultural districts host extensive aircraft-based operations targeting hail suppression and moisture enhancement.
Saskatchewan
Agricultural commodity boards and irrigation districts purchase hail suppression services across drought-prone agricultural zones. Health Canada's PMRA evaluates silver iodide ecotoxicology under pesticide registration frameworks, creating compliance layers for chemical handling. Ground-based generator networks concentrate in the southern grain belt where favorable wind patterns support nuclei dispersion.
Manitoba
The Red River Valley lacks established hail suppression programs, presenting positioning opportunities for ice nuclei service contracts. Transport Canada regulates aircraft operations through CARs Part VI, with emerging RPAS standards enabling unmanned system deployment. Indigenous co-management agreements for watershed stewardship are opening novel procurement channels in northern watersheds.
British Columbia
Forest fire suppression zones and alpine watersheds require extended-range aircraft for atmospheric intervention. Federal emergency management departments fund reactive precipitation enhancement during declared drought conditions. The province's mountainous terrain drives demand for specialized cold-cloud seeding expertise transferred from international alpine operations.
Canada Cloud Seeding Market Competitive Landscape
Global majors compete with regional champions across aviation service delivery and chemical supply chains. The vendor base concentrates around integrated operators with long-standing provincial relationships and specialized nucleating agent manufacturers. Three archetypes dominate: full-service aviation contractors, chemical specialists with flare manufacturing capabilities, and hybrid drone-aircraft operators. Strategic moves center on unbundling previously integrated contracts and forming Indigenous partnership structures for watershed co-management.
Within the full-service aviation tier, North American Weather Consultants and Weather Modification, Inc. exemplify operators with sustained provincial relationships. Snowy Hydro Limited represents the international alpine expertise transfer archetype. These entities occupy positions shaped by Environment and Climate Change Canada licensing history and Transport Canada aviation certification frameworks.
| Leading Market Players |
|---|
| North American Weather Consultants |
| Snowy Hydro Limited |
| Weather Modification, Inc. |
| Ice Crystal Engineering |
| WeatherTec Services, Inc. |
| Alberta Hail Suppression Project |
| Aquila Air Traffic Management Services |
| Western Weather Consultants |
| Weather Modification International |
| Others |
Pricing and Supply Chain Analysis
Provincial water authorities in Alberta and Saskatchewan anchor procurement through multi-year drought mitigation appropriations, locking in contract-based long-term offtake pricing that insulates service providers from spot-market volatility. Silver iodide generator modernization programs and Transport Canada aviation certification requirements fragment vendor relationships across specialized chemical manufacturers and aircraft operators.
Pricing Analysis
Silver iodide feedstock costs pass directly into flare and generator pricing through commodity-linked contract structures. Pricing stratifies across premium, standard, and economy tiers based on Transport Canada CARs Part VI certification level and after-sales atmospheric monitoring bundling. Cost compression in standard-tier aircraft services is intensifying because turboprop fleet availability constraints in western Canada inflate hourly operating rates. Agricultural commodity boards exhibit highest price sensitivity due to per-hectare service fee structures, while provincial water authorities with statutory mandates show lowest sensitivity.
Supply Chain Analysis
Regional distribution for silver iodide flares runs through Calgary and Saskatoon staging facilities serving Prairie agricultural zones. Supply concentrates in the United States for cloud seeding-grade silver iodide refining, with secondary sourcing from Australian alpine expertise transfer networks. Raw material dependencies include silver bullion, potassium chloride, and acetone-based carrier solutions. Single-source vulnerability in domestic silver iodide refining exposes procurement to metal price volatility. Distribution feeds from manufacturer-direct to provincial procurement vehicles with minimal intermediary layering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada cloud seeding represents a late-cycle quality story as provincial climate adaptation strategies shift from reactive emergency response toward proactive precipitation enhancement specifications.
For Market Incumbents: Acquire drone-aircraft hybrid operational capabilities to counter emerging unmanned system specialists. Secure Indigenous co-management agreements for northern watershed stewardship contracts before provincial tender processes fragment further. Backward integration into silver iodide flare manufacturing reduces exposure to single-source chemical supply concentration. For New Entrants and Emerging Players: Launch via Manitoba Red River Valley hail suppression contracts where established programs remain absent. Target Saskatchewan ground-based generator retrofit opportunities displacing legacy acetone burners. Pursue drone-based service contracts under emerging Transport Canada beyond-visual-line-of-sight frameworks as the most penetrable entry vector. For Investors and Strategic Acquirers: Integrated aviation-chemical service providers are the most active acquirer in this space as contract unbundling fragments vendor relationships. The five-to-ten year viability window favors operators with Environment and Climate Change Canada licensing history and Transport Canada certification depth. Monitor Alberta and Saskatchewan provincial budget appropriations for drought mitigation as the inflection signal indicating procurement acceleration or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Drone-Aircraft Hybrid Operations | Transport Canada RPAS standards enable unmanned augmentation of manned seeding missions in restricted corridors. |
| Indigenous Water Rights Partnerships | First Nations co-management agreements create procurement channels outside provincial tender processes. |
| Silver Iodide Generator Modernization | Ground-based hygroscopic systems displace legacy acetone burners in Saskatchewan agricultural zones. |
| Provincial Contract Unbundling | Separate RFPs for chemical supply and flight hours fragment previously integrated vendor relationships. |
| Atmospheric Physics Talent Acquisition | Cloud microphysics specialists with operational meteorology experience command premium compensation. |
Research Methodology
Direct dialogue with provincial water authority procurement officers, aircraft service operators, atmospheric monitoring specialists, and Indigenous watershed co-management coordinators grounded the qualitative foundation. Secondary validation drew from Environment and Climate Change Canada licensing databases, Transport Canada CARs Part VI regulatory filings, Health Canada PMRA pesticide registration records, and provincial budget appropriation documents. Bottom-up contract value aggregation and top-down provincial spending analysis were triangulated to establish market sizing.
Segmented outputs across the analysis window reflect technology platform splits, end-user institutional categories, geographic deployment contexts, and atmospheric solution types. CAGRs were derived from historical appropriation trajectories and projected provincial climate adaptation funding shifts. Forecast inputs incorporated Transport Canada RPAS regulatory development timelines and silver iodide supply concentration risk factors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PMRA ecotoxicology review delays or abrupt provincial budget reallocation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Smart Water Monitoring Market
Environmental Monitoring
Environment Monitoring Devices Market
Environmental Monitoring
Carbon Monoxide Analyzers Market
Environmental Monitoring
Middle East and Africa Air Quality Monitoring Market
Environmental Monitoring
Latin America Cloud Seeding Market
Environmental Monitoring
Environmental Hazard Monitoring (EHM) Software Market
Environmental Monitoring
LAMEA Emission Monitoring System Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
South America Air Quality Monitoring Market
Environmental Monitoring
Real-Time Flood Monitoring and Warning System Market
Environmental Monitoring
Water Quality Monitoring Equipment Market
Environmental Monitoring
Europe Air Quality Monitoring Market
Environmental Monitoring
Emission Monitoring Systems Market
Environmental Monitoring
United States Erosion Sediment Control Market
Environmental Monitoring
Environmental Technology Market
Environmental Monitoring
Environmental Radiation Monitor Market