
 Global Cloud Seeding Equipment Market | 2026-2036
Global Cloud Seeding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Seeding Equipment Market Foresight
The capital-intensity divergence between aircraft-mounted system providers and ground-based launcher manufacturers is bifurcating competitive dynamics across the sector. Weather Modification Inc. leverages its long-standing operational footprint across North American drought corridors to sustain recurring government contracts. Cloud Technologies GmbH anchors European demand through specialized silver iodide generator engineering that meets stringent ECHA chemical handling protocols. Ice Crystal Engineering LLC differentiates via compact, portable disperser units designed for rapid-deployment alpine environments.
Cloud seeding equipment encompasses ground-based and airborne systems engineered to introduce ice nucleating agents—primarily silver iodide with crystal lattice structures matching ice—into supercooled cloud formations to induce precipitation. Generators dominate current procurement volumes due to lower per-unit capital requirements and established maintenance networks, while electronic seeding technologies represent the fastest-expanding technology category as operators seek alternatives to chemical payloads. Aircraft-mounted systems command premium positioning given integration complexity with aviation safety standards, whereas drought mitigation applications generate the most consistent government funding streams across semi-arid jurisdictions.
The EPA governs silver iodide discharge thresholds under the Clean Water Act, while the FAA mandates airworthiness certification for all airborne dispersal apparatus, creating dual compliance pathways that shape product development cycles. China's MEE enforces emission-linked weather modification permits that restrict operational windows in high-pollution zones, directly constraining equipment utilization rates. Stakeholders must monitor evolving aerosol toxicity classifications from ECHA and emerging state-level water-rights litigation that could restrict seeding operations in contested river basins.
Market Dynamics
Electronic seeding technologies are compressing capital requirements for new market entrants while fragmenting procurement authority across municipal water districts and provincial environmental agencies rather than central governments.
Growth Catalysts
- China's dual carbon goals:Provincial weather modification bureaus in Sichuan and Gansu are expanding fleet procurement to meet emission-linked precipitation targets under MEE permits.
- Colorado River Basin litigation:Interstate water compacts are forcing Arizona, Nevada, and Utah to invest in augmentation programs, creating sustained equipment demand from state procurement offices.
- Silver iodide generator engineering:Portable ground-based units are penetrating alpine hydroelectric catchments in Australia's Snowy Mountains where aircraft access remains seasonally restricted.
Market Restraints
- Silver iodide cost volatility:Photographic industry demand for silver halide compounds creates competing offtake pressure on refined iodine supply chains.
- Aviation safety certification:FAA airworthiness mandates for airborne dispersal apparatus extend product development cycles by 18-24 months and concentrate design authority among established aerospace integrators.
- Electronic seeding technical immaturity:Laser and acoustic nucleation systems demonstrate inconsistent efficacy across varying cloud temperatures and humidity profiles, limiting operational deployment.
Strategic Opportunities
- Saudi Arabia's cloud seeding expansion:The Kingdom's National Center for Meteorology is tendering for ground-based generator networks to secure water independence targets by 2030.
- ECHA chemical handling protocol convergence:REACH-aligned silver iodide handling standards are creating exportable compliance frameworks that reduce market entry friction for European equipment manufacturers.
- Drone-mounted dispersal systems:Unmanned aerial platforms below 55 pounds are evading crewed aircraft certification requirements while penetrating terrain-blocked watersheds in the Himalayas and Andes.
Industry Challenges
- Atmospheric physics modeling expertise:Operational success depends on rare cross-training in meteorology, aviation logistics, and chemical engineering that universities are not producing at replacement rates.
- State-level water-rights litigation:Downstream riparian claimants in contested basins are filing injunctions that freeze seeding permits mid-season, stranding capital deployment and crew contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Seeding Equipment Market |
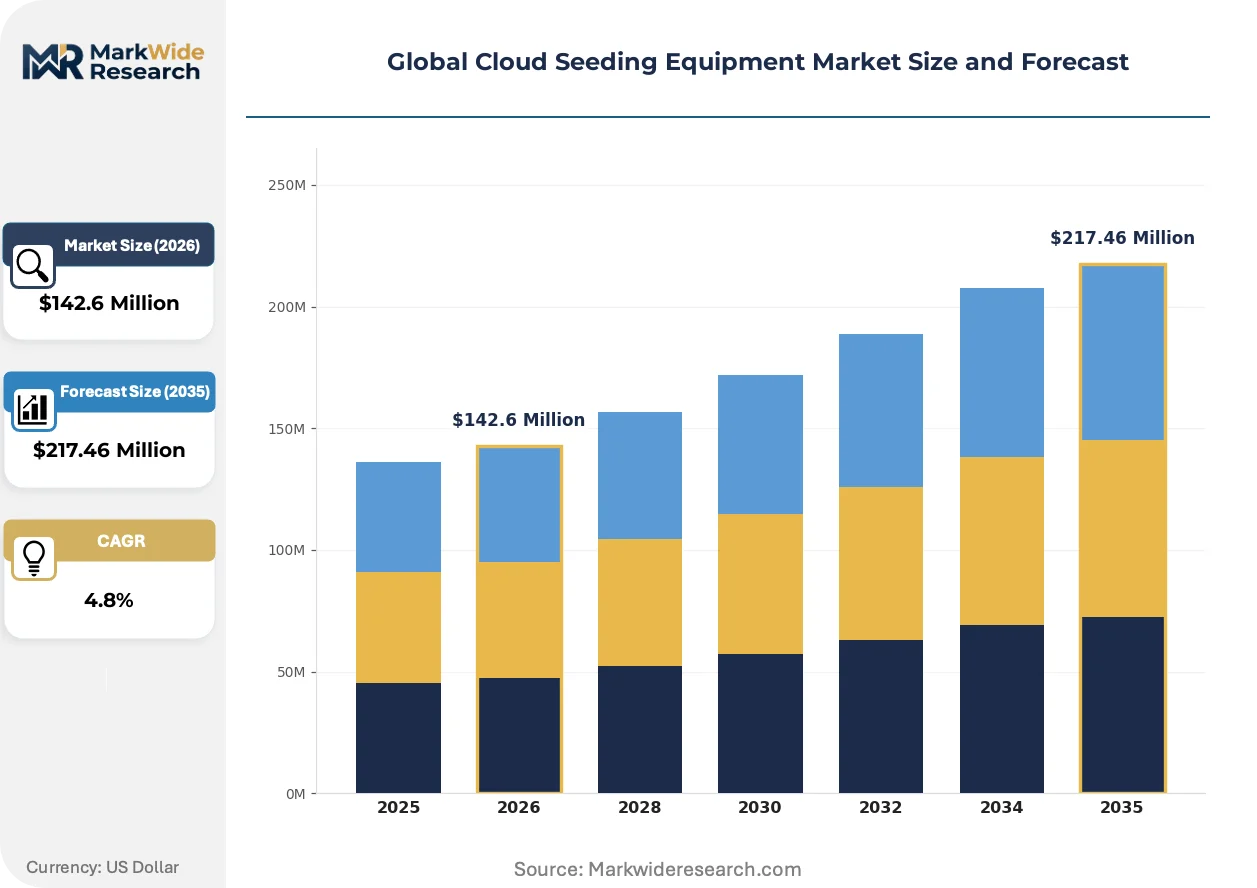
| Market Size in 2026 | $142.6 Million |
| Market Size in 2035 | $217.46 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generators, Dispersers, Aircraft-Mounted Systems, Ground-Based Launchers, Detonation Devices Technology: Silver Iodide, Dry Ice Pellets, Hygroscopic Flares, Liquid Propellant, Electronic Seeding Application: Agricultural Enhancement, Drought Mitigation, Hydropower Support, Air Quality Improvement, Snowpack Augmentation End User: Government Agencies, Research Institutes, Energy Producers, Environmental Organizations, Defense Departments |
| Companies Covered | Ice Crystal Engineering LLC, Mettech S.p.A., Weather Modification Inc., 3D S.A., Cloud Technologies GmbH, North American Weather Consultants Inc., Snowy Hydro Limited, American Elements Inc., RHS Consulting Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Seeding Equipment Market Shifts & Advancements
Equipment form factors and operational protocols are diverging sharply between established chemical-based systems and emerging electronic alternatives, with procurement criteria shifting from precipitation volume guarantees toward environmental traceability metrics.
Portable ground-based silver iodide generators are miniaturizing to under 15 kilograms for single-operator transport into alpine terrain. Hydroelectric utilities in New Zealand and Norway are adopting these units for rapid deployment to specific catchment elevations. The technology is miniaturizing maintenance requirements and enabling precision targeting that reduces chemical payload volumes by 40% compared to legacy fixed installations.
ECHA's evolving aerosol toxicity classifications under REACH are compelling manufacturers to document silver iodide deposition rates in soil and runoff. German and Swiss regulators are now requiring quarterly environmental monitoring reports as a condition of operational permits. Alpine equipment suppliers are responding by integrating real-time atmospheric sampling sensors that transmit particulate data directly to environmental compliance dashboards.
Water district procurement committees are unbundling equipment purchase from flight-hour service contracts that previously locked buyers into single-vendor relationships. California's Department of Water Resources and Australia's Bureau of Meteorology are now soliciting separate bids for generator hardware, silver iodide supply, and piloted aircraft dispatch. This disintermediation is most advanced in jurisdictions with mature public procurement transparency laws, where contract segmentation reduces single-source dependency risks.
Global Cloud Seeding Equipment Market Segmentation
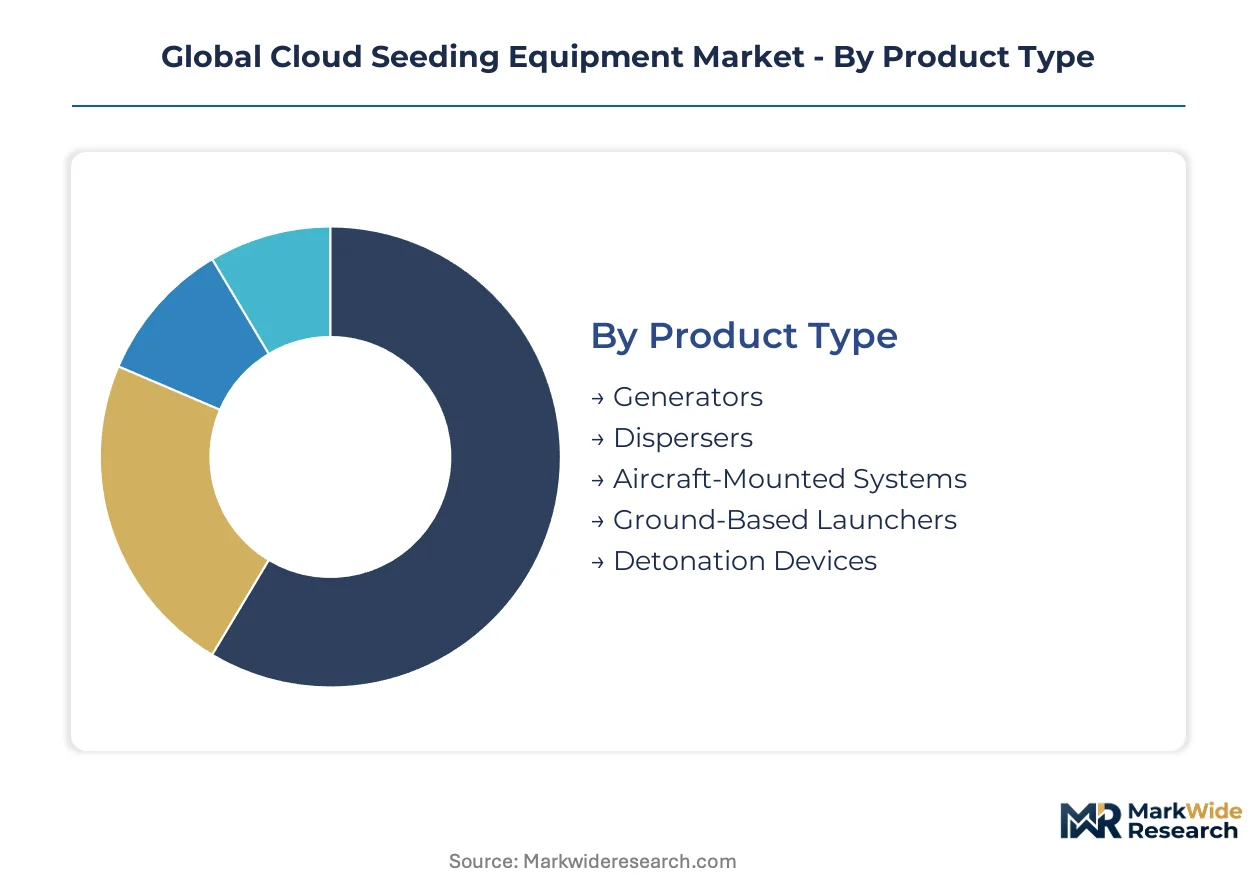
Equipment procurement patterns diverge sharply between capital-intensive airborne platforms and deployable ground-based units, with technology selection driven by regulatory constraints and operational geography. End-user budgeting authority concentrates in government water resource departments and hydroelectric utilities, creating concentrated demand pools that favor established equipment categories.
Product Type:
Margin pools concentrate in aircraft-mounted systems where FAA airworthiness certification creates defendable pricing power for qualified integrators.
- Generators:Portable ground-based units burn silver iodide acetone solutions to release nucleating aerosols into updraft zones. Australia's Snowy Mountains hydroelectric catchments and Colorado River Basin states are expanding procurement of sub-15-kilogram single-operator models that reduce payload volumes by 40% compared to fixed installations.
- Aircraft-Mounted Systems:These integrate dispersal apparatus with aviation safety standards, requiring 18-24 month FAA certification cycles that concentrate design authority among established aerospace suppliers. Water-stressed agricultural regions in the western United States are expanding fleet procurement to meet interstate compact obligations.
- Dispersers:Compact units for rapid-deployment alpine environments.
- Ground-Based Launchers:Fixed installations for sustained operations in accessible terrain.
- Detonation Devices:Specialized systems for targeted atmospheric intervention.
The dominant share belongs to Generators, while Aircraft-Mounted Systems is closing the gap fastest.
Technology:
Procurement committees are unbundling equipment purchase from chemical supply contracts, fragmenting vendor relationships across hardware and consumable categories.
- Silver Iodide:The established standard with crystal lattice structures matching ice for nucleation efficacy. China's Sichuan and Gansu provincial bureaus are expanding procurement under MEE emission-linked precipitation targets, though photographic industry demand for silver halide compounds creates competing offtake pressure on refined iodine supply chains.
- Electronic Seeding:Laser and acoustic nucleation systems that compress capital requirements for new market entrants. Municipal water districts are piloting these technologies despite inconsistent efficacy across varying cloud temperatures and humidity profiles that limit operational deployment.
- Dry Ice Pellets:Solid carbon dioxide for rapid temperature reduction in supercooled clouds.
- Hygroscopic Flares:Salt-based particles for warm-cloud precipitation induction.
- Liquid Propellant:Pressurized delivery systems for controlled agent dispersion.
Silver Iodide retains the largest installed base, though Electronic Seeding is gaining share fastest among municipal procurement offices.
Application:
Funding consistency varies by application, with drought mitigation generating the most reliable government appropriations across semi-arid jurisdictions.
- Drought Mitigation:Sustained equipment demand from state procurement offices in Arizona, Nevada, and Utah responding to Colorado River Basin litigation and interstate water compact pressures. These programs command multi-year budget allocations with lower cancellation risk than experimental applications.
- Hydropower Support:Alpine catchment operations in New Zealand and Norway where rapid-deployment portable generators enable precision targeting at specific elevations. Quarterly environmental monitoring reports are now required under ECHA-aligned standards.
- Agricultural Enhancement:Seasonal operations in water-stressed farming regions.
- Air Quality Improvement:Emerging application constrained by atmospheric modeling uncertainty.
- Snowpack Augmentation:Winter-focused operations with narrow operational windows.
Drought Mitigation holds the largest revenue share, while Hydropower Support is expanding most quickly.
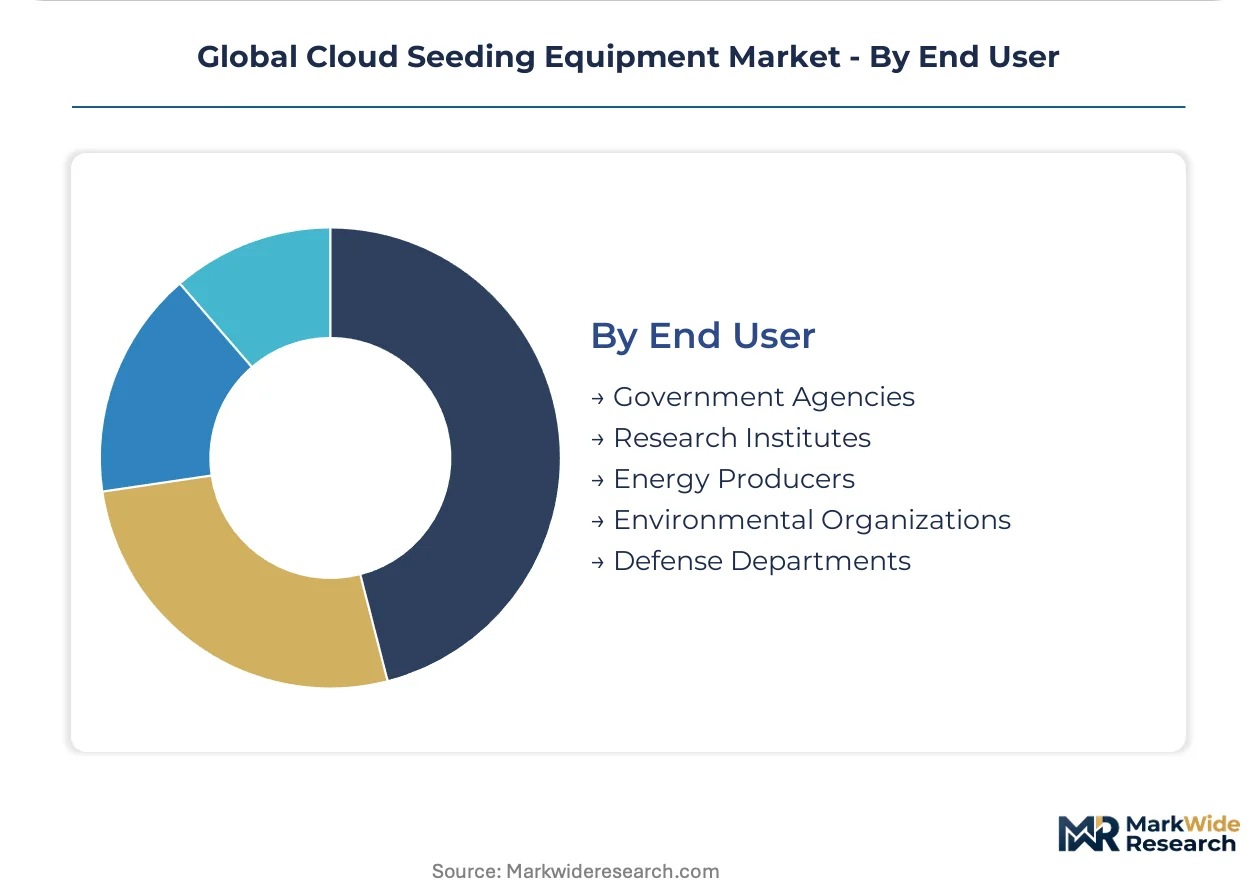
End User:
Procurement authority is fragmenting from central governments toward municipal water districts and provincial environmental agencies with localized budget control.
- Government Agencies:State water resource departments and national meteorological bureaus with sustained capital budgets for multi-year equipment programs. California's Department of Water Resources and Australia's Bureau of Meteorology are segmenting bids for hardware, chemical supply, and aircraft dispatch to reduce single-source dependency.
- Energy Producers:Hydroelectric utilities adopting portable ground-based units for catchment-specific deployment. These operators prioritize precision targeting capabilities that minimize chemical payload volumes and compliance reporting burdens.
- Research Institutes:Limited procurement volumes focused on experimental validation.
- Environmental Organizations:Constrained funding for operational deployment.
- Defense Departments:Specialized applications with restricted procurement transparency.
Government Agencies dominate procurement volume, while Energy Producers are climbing the fastest as alpine utilities expand operational autonomy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in FAA-certified US aerospace integrators, while Chinese provincial bureaus compress margins through bulk procurement of ground-based generators under MEE emission-linked permits.
United States
Colorado River Basin states drive sustained demand as interstate water compels Arizona, Nevada, and Utah to expand augmentation programs. FAA airworthiness mandates for airborne dispersal apparatus extend certification cycles by 18-24 months, concentrating design authority among established aerospace suppliers. California's Department of Water Resources segments procurement across hardware, chemical supply, and aircraft dispatch to reduce vendor lock-in.
China
Sichuan and Gansu provincial weather modification bureaus are expanding fleet procurement to meet dual carbon precipitation targets. MEE enforces emission-linked operational permits that restrict seeding windows in high-pollution zones, directly constraining equipment utilization rates. The Yangtze River Delta hosts manufacturing clusters for silver iodide generator components serving domestic and export markets.
Australia
Snowy Mountains hydroelectric catchments prioritize portable ground-based units under 15 kilograms for rapid deployment to specific elevations. The Bureau of Meteorology unbundles equipment purchase from flight-hour service contracts, fragmenting procurement authority across municipal water districts. Alpine utilities in New South Wales and Victoria adopt precision targeting capabilities that reduce chemical payload volumes by 40%.
Saudi Arabia
The National Center for Meteorology is tendering for ground-based generator networks to secure water independence targets by 2030. SFDA-aligned chemical handling protocols shape silver iodide import and storage requirements for operational permits. Riyadh-based procurement offices prioritize equipment with real-time atmospheric sampling sensors for compliance dashboard integration.
Germany
ECHA's evolving REACH aerosol toxicity classifications compel manufacturers to document silver iodide deposition rates in soil and runoff. German and Swiss regulators now require quarterly environmental monitoring reports as a condition of operational permits. Bavarian alpine equipment suppliers integrate sensors transmitting particulate data directly to environmental compliance dashboards.
Global Cloud Seeding Equipment Market Competitive Landscape
Concentration sits with established aerospace integrators holding FAA airworthiness certification, while portable generator specialists fragment the ground-based tier. The vendor base spans three strategic archetypes: certified aircraft-mounted system providers, ECHA-compliant European engineering houses, and compact alpine deployment specialists. Competitive moves center on unbundling service contracts from hardware sales and integrating real-time environmental monitoring for compliance automation.
Among North American operators, Weather Modification Inc. and North American Weather Consultants Inc. exemplify the government-contract archetype with sustained recurring revenue from drought corridor programs. European engineering credibility anchors Cloud Technologies GmbH within the chemical-handling compliance tier. Ice Crystal Engineering LLC occupies the rapid-deployment specialist position for terrain-blocked watersheds where aircraft access remains seasonally restricted.
| Leading Market Players |
|---|
| Ice Crystal Engineering LLC |
| Mettech S.p.A. |
| Weather Modification Inc. |
| 3D S.A. |
| Cloud Technologies GmbH |
| North American Weather Consultants Inc. |
| Snowy Hydro Limited |
| American Elements Inc. |
| RHS Consulting Inc. |
| Others |
Supply & Pricing Matrix
Take-or-pay silver iodide supply contracts lock in multi-year offtake commitments between Australian hydroelectric utilities and Japanese chemical processors, anchoring price visibility while constraining operational flexibility during demand surges. California's unbundled procurement mandates fragment these arrangements, forcing equipment vendors to absorb spot-market volatility in refined iodine.
Pricing Analysis
Configured-to-order pricing for FAA-certified aircraft-mounted systems commands spreads exceeding standard ground-based generator pricing by factors tied to certification tier and integration complexity. Three-tier pricing structure across premium, standard, and economy levels segments on aviation safety classification, volume scale, and after-sales service bundling. Pricing pressure stems from Chinese provincial bureaus compressing margins through bulk generator procurement under MEE emission-linked permits. Municipal water districts exhibit highest price sensitivity due to fragmented budget authority, while national meteorological bureaus prioritize certification compliance over unit cost.
Supply Chain Analysis
China and Japan anchor silver iodide refining capacity, with the Yangtze River Delta hosting specialized generator component manufacturing clusters. Germany and Switzerland concentrate precision engineering for atmospheric sampling sensors and compliance-integrated dispersal units. The supply chain draws from photographic industry demand for silver halide compounds, refined iodine from Chilean caliche deposits, and acetone carrier solvents from petrochemical complexes. Single-source vulnerability concentrates in FAA-certified aerospace integrators controlling airworthiness design authority. Distribution runs through government procurement offices, hydroelectric utility engineering departments, and provincial weather modification bureaus with segmented tender processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Environmental compliance-as-a-service layers expand faster than hardware sales, as ECHA-aligned monitoring mandates and MEE emission-linked permits force recurring data transmission and reporting subscriptions.
For Market Incumbents: Consolidate around FAA certification moats by acquiring specialized aerospace engineering talent pools and backward integration into silver iodide acetone solution blending. Electronic seeding entrants threaten chemical payload incumbents with capital-light deployment models; defend through vertical integration into real-time atmospheric sensor manufacturing and compliance dashboard software. For New Entrants and Emerging Players: Aftermarket calibration and maintenance service gaps in portable alpine generator deployments offer white-space entry points where incumbents under-serve rapid-deployment hydroelectric utilities. Drone-mounted dispersal systems below 55 pounds evade crewed aircraft certification requirements in Himalayan and Andes watersheds. Pursue direct contracting with municipal water districts in Colorado River Basin states where procurement unbundling fragments incumbent relationships. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors ECHA-compliant European engineering houses with REACH-aligned chemical handling documentation. Long-term viability hinges on environmental traceability capabilities outpacing hardware commoditization. Target acquisition profiles center on compact portable generator specialists with integrated sensor technology. The signal to watch is state-level water-rights litigation freezing seeding permits mid-season, which would strand capital deployment and compress equipment utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Environmental Compliance Integration | ECHA-aligned sensor integration enables REACH documentation automation for German and Swiss alpine operators. |
| Drone Platform Certification Bypass | Unmanned aerial systems below 55 pounds penetrate terrain-blocked Himalayan and Andes watersheds without FAA crewed aircraft mandates. |
| Silver Iodide Supply Backward Integration | In-house acetone solution blending insulates against photographic industry offtake competition for refined iodine. |
| Procurement Unbundling Response | Separate hardware, chemical, and dispatch bidding aligns with California Department of Water Resources transparency mandates. |
| Real-Time Atmospheric Monitoring | Particulate data transmission to compliance dashboards satisfies quarterly ECHA reporting requirements for operational permits. |
Research Methodology
The analysis maps aircraft-mounted systems, ground-based generators, electronic seeding technologies, and drone dispersal platforms, each validated through meteorological bureau procurement officers, hydroelectric utility engineering directors, aerospace certification specialists, and silver iodide chemical supply managers. Primary interviews with FAA compliance consultants and MEE permit administrators cross-check against EPA Clean Water Act filings, ECHA REACH substance registrations, Australian Bureau of Meteorology tender databases, and Saudi National Center for Meteorology procurement notices. Bottom-up equipment shipment tracking and top-down government appropriation analysis triangulate market sizing.
Consistency checks validate model outputs against external benchmarks including utility capital expenditure disclosures, provincial weather modification budget allocations, and aerospace integrator order backlogs. Segmentation dimensions span equipment form factor, nucleation technology type, application end-use, and end-user procurement authority tier across the projection horizon. CAGRs derive from equipment replacement cycles, regulatory permit expansion rates, and interstate water compact litigation timelines. Forecast inputs incorporate alpine terrain accessibility constraints and seasonal operational window restrictions.
Forecasts assume regulatory continuity in FAA airworthiness mandates, ECHA aerosol toxicity classifications, and MEE emission-linked operational permits; material policy shifts would require re-modeling. Specific risks include state-level water-rights injunctions freezing seeding permits, silver iodide supply disruption from photographic industry demand spikes, and electronic seeding efficacy validation failures that could redirect procurement toward chemical systems. Recalibration cycles align with material shifts in interstate water compact negotiations and ECHA REACH substance review schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
North America Emission Monitoring System Market
Environmental Monitoring
Pollution Monitoring Equipment Market
Environmental Monitoring
Water Quality Analyzer Market
Environmental Monitoring
Cloud Seeding System Market
Environmental Monitoring
LAMEA Emission Monitoring System Market
Environmental Monitoring
Green Mining Market
Environmental Monitoring
Asia Pacific Air Quality Monitoring Market
Environmental Monitoring
Latin America Cloud Seeding Market
Environmental Monitoring
Environmental Technology Market
Environmental Monitoring
Global Environmental Remediation Market
Environmental Monitoring
Radon Gas Test Kits Market
Environmental Monitoring
Water Testing Market
Environmental Monitoring
Water Quality Monitoring Systems Market
Environmental Monitoring
Asia-Pacific Cloud Seeding Market
Environmental Monitoring
Smart Water Monitoring Market