
 Global Resource Circulation Equipment Market | 2026-2036
Global Resource Circulation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Resource Circulation Equipment Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) is pivoting the market's cost-of-entry calculus by mandating detailed circular economy disclosures. This regulatory pressure benefits established engineering firms. Kawasaki Heavy Industries Ltd. leverages its extensive manufacturing capabilities for large-scale waste processing systems. Vecoplan AG specializes in high-torque shredders for difficult materials, while Metso differentiates through its comprehensive portfolio of crushing and screening technologies for mineral recycling.
Resource circulation equipment encompasses a range of machinery designed to sort, process, and reclaim valuable materials from waste streams. These systems, such as optical sorters and hydraulic balers, are specified by parameters like throughput capacity in tons per hour and final material purity. Within equipment types, shredders and conveyors form the foundational infrastructure for most facilities. The waste management application remains the largest segment, but e-waste processing and scrap metal recovery represent the fastest-growing areas for advanced technology deployment.
Regulatory frameworks create the primary demand signals, with the US EPA setting landfill diversion targets and China's GB standards defining acceptable recycled material quality. Concurrently, the EU’s CE marking dictates mandatory safety and operational standards for all equipment sold in the region. For equipment manufacturers, navigating this fragmented regulatory landscape to achieve compliance without sacrificing performance is the central strategic challenge.
Market Dynamics
The market's structural momentum originates from a global regulatory pivot towards circularity. Mandates like the European Union's Circular Economy Action Plan and China's GB standards are creating non-negotiable demand for equipment capable of producing high-purity recycled feedstock.
Growth Catalysts
- Mandatory Recycling Targets:The European Union's Circular Economy Action Plan enforces progressively higher recycling and material recovery rates, directly stimulating investment in advanced sorting, shredding, and processing systems to meet legal obligations.
- E-Waste Proliferation:The expansion of the e-waste processing sector requires specialized equipment, such as high-precision optical sorters and gentle shredders, to reclaim valuable metals and plastics from complex electronic assemblies without degradation.
- National Quality Standards:China's GB standards for imported recyclables impose strict purity thresholds. This policy compels waste exporters and domestic processors to deploy superior sorting technology to ensure their materials meet market access requirements.
Market Restraints
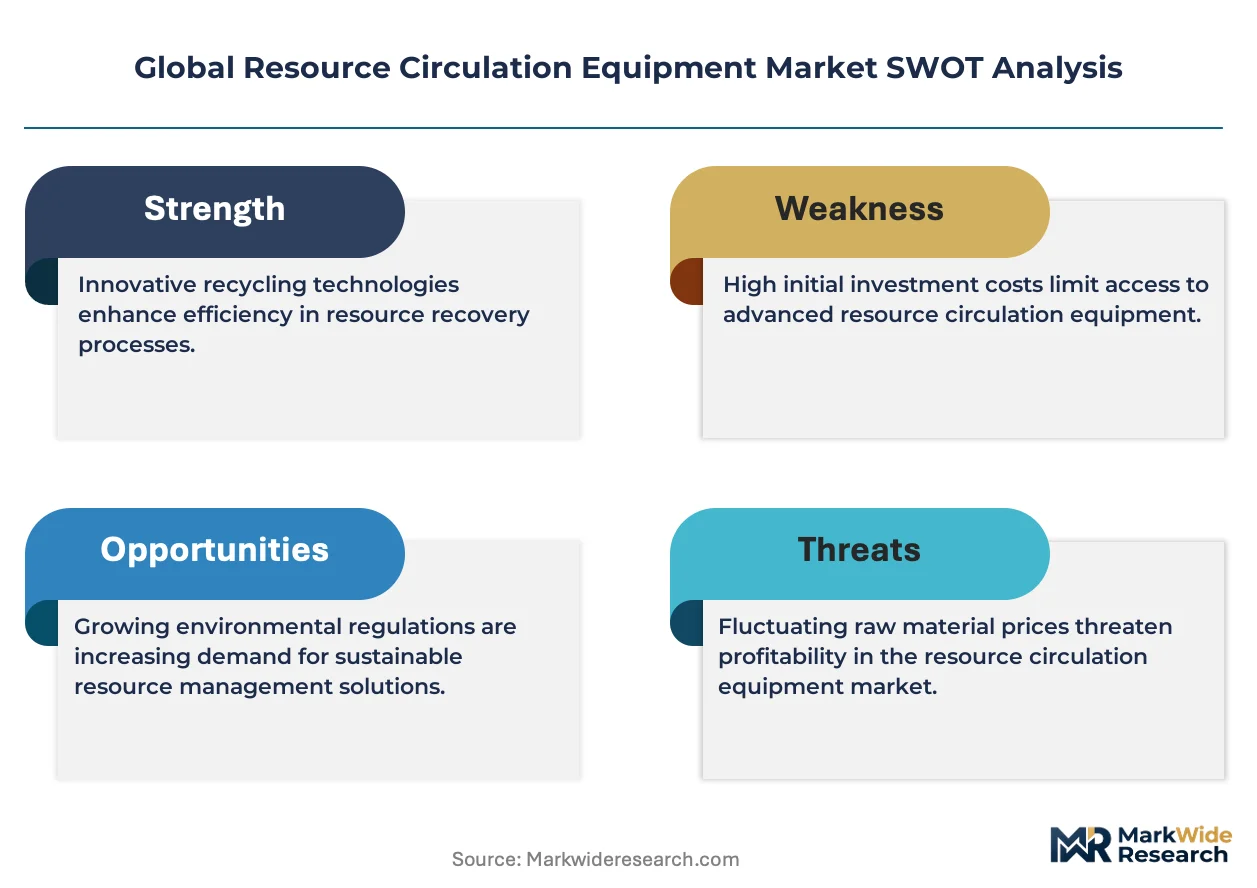
- High Capital Expenditure:The significant upfront investment required for large-scale systems, including high-capacity shredders and automated sorting lines, presents a substantial barrier to entry for smaller waste management operators and municipalities.
- Feedstock Inconsistency:The variable and often contaminated nature of municipal and industrial waste streams challenges equipment performance, leading to lower throughput, reduced final purity, and increased maintenance downtime for processing machinery.
- Regulatory Fragmentation:Navigating disparate international standards, such as the EU's CE marking for safety and the US EPA's landfill diversion goals, complicates equipment design and certification, increasing compliance costs for manufacturers selling globally.
Strategic Opportunities
- Emerging Market Formalization:Nations in Southeast Asia and Latin America are beginning to implement formal waste management frameworks, creating new markets for foundational resource circulation equipment like balers and conveyors.
- Construction and Demolition Waste:The recovery of aggregates, metals, and wood from construction and demolition debris represents an underdeveloped application for heavy-duty crushing, screening, and sorting equipment.
- AI-Powered Sorting:Integrating artificial intelligence and machine learning with optical sorting systems enables the identification and separation of materials with greater speed and accuracy, unlocking higher value from mixed waste streams.
Industry Challenges
- Technician Skill Gaps:A shortage of trained personnel capable of operating, maintaining, and repairing increasingly complex and automated resource circulation systems constrains facility uptime and operational efficiency.
- Legacy System Integration:Integrating new, high-performance equipment, such as advanced optical sorters, into existing facilities with older conveyor and processing infrastructure creates significant engineering and operational hurdles.
- Energy Consumption:The high energy demand of heavy machinery like industrial shredders and large-scale screening plants exposes operators to volatile electricity prices and adds significant operational cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Resource Circulation Equipment Market |
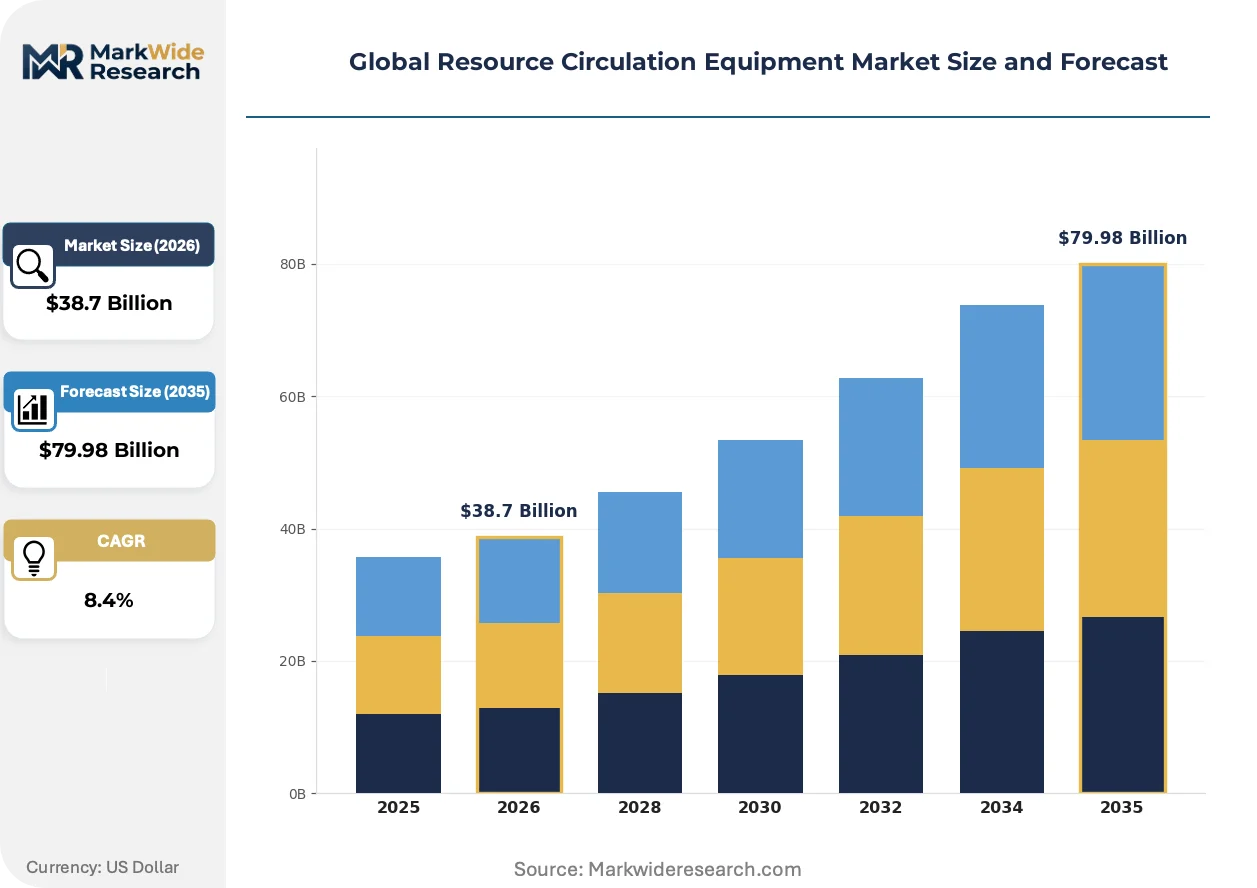
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Shredders, Conveyors, Balers, Crushers, Screening Machines, Compactors Technology: Mechanical, Hydraulic, Pneumatic, Electromechanical, Magnetic Separation, Optical Sorting Application: Waste Management, Circular Economy, E-Waste Processing, Construction Debris Recycling, Agricultural Residue Handling, Scrap Metal Recovery End User: Recycling Facilities, Manufacturing Plants, Waste Collection Services, Environmental Consultancies, Municipal Corporations |
| Companies Covered | Kawasaki Heavy Industries Ltd., Vecoplan AG, Metso, Foster Wheeler, Wolf Material Handling Systems, ThermoSelect SA, Komptech GmBH, ECO Green Equipment, Veolia Environnement, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Resource Circulation Equipment Market Strategic Shifts & Innovations
Technological evolution is defined by the pursuit of higher purity outputs and greater operational efficiency. Intelligent automation and data connectivity are transforming standalone machines into integrated systems that provide verifiable proof of circularity for regulatory and commercial stakeholders.
High-torque, direct-drive systems provide superior energy efficiency and control for processing challenging materials. The scrap metal and e-waste recovery sectors are rapidly adopting this configuration for industrial shredders. This technological shift is electrifying the shredder segment, displacing legacy hydraulic-driven machines and improving facility uptime through reduced maintenance requirements.
The European Union's Corporate Sustainability Reporting Directive (CSRD) creates new data-driven procurement criteria. It compels large corporations to disclose detailed metrics on waste generation, material reuse, and recycling performance. The e-waste processing segment is most affected, as companies now require equipment with integrated sensors and software to track and validate material flows for compliance.
A transition from one-time capital sales to long-term service and leasing agreements is altering buyer behavior. This model disrupts traditional equipment distribution by bundling maintenance, software upgrades, and performance guarantees into a single operational expense. The trend is most pronounced in North America and Europe, where it helps facility operators manage technology risk and align costs with processing volumes.
Global Resource Circulation Equipment Market Segmentation
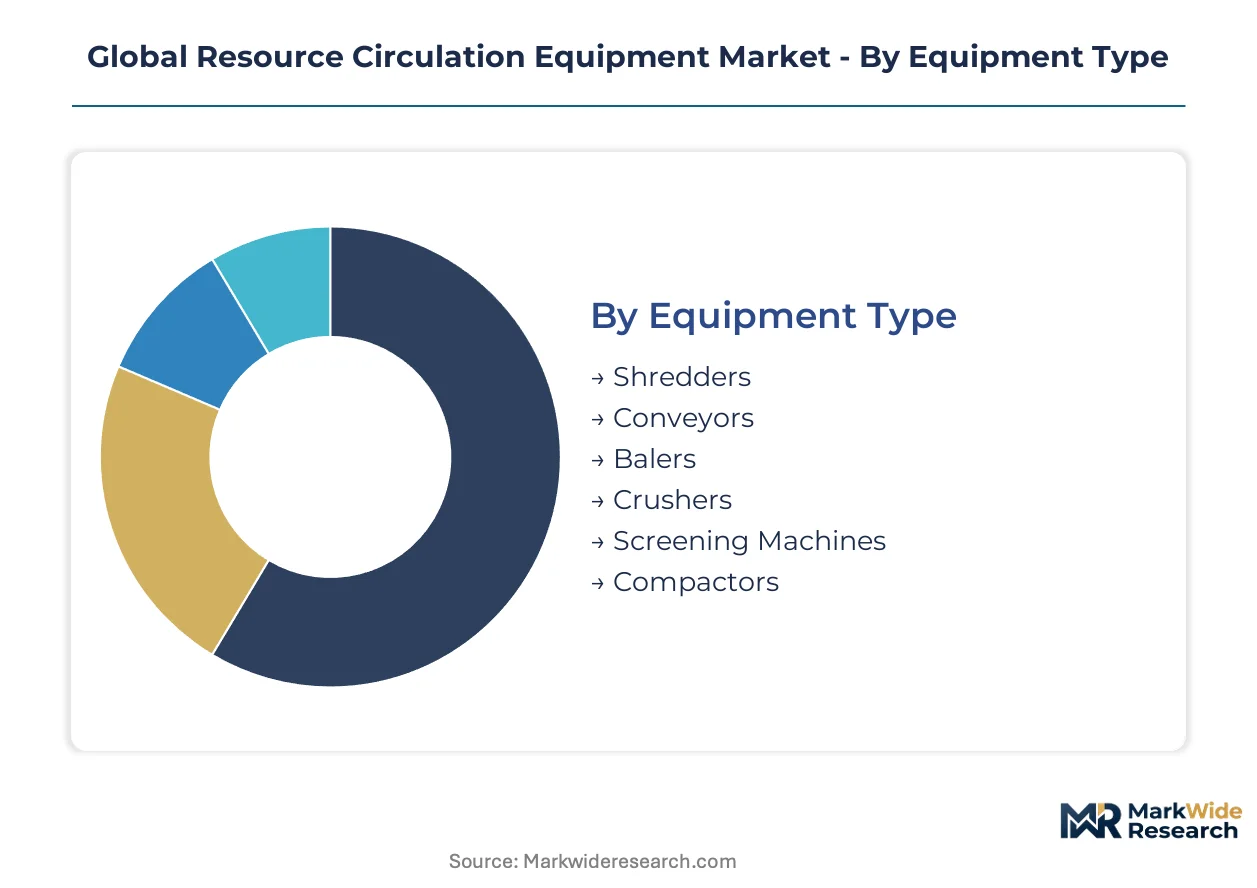
The Global Resource Circulation Equipment Market segmentation highlights the distinct needs and operational parameters driving technology adoption. This analysis underscores how varying material streams, processing objectives, and end-user requirements shape demand for specialized machinery. Understanding these segments is crucial for manufacturers to align product development with specific industry challenges and opportunities.
Equipment Type:
Buyers differentiate equipment choices based on material type, processing volume, and desired output purity.
- Shredders:High-torque, direct-drive systems effectively break down bulky and difficult materials like e-waste and industrial scrap. Demand is concentrating in industrial economies like Germany for e-waste processing due to stringent regulatory mandates.
- Conveyors:Modular and robust systems transport materials efficiently between various processing stages within a facility. China's industrial sector requires high-capacity conveyors for large-scale recycling operations to manage high volumes.
- Balers:Hydraulic balers compress recyclable materials such as paper, plastics, and metals for efficient storage and transport.
- Crushers:Heavy-duty crushing equipment reduces construction and demolition debris into reusable aggregates and other fractions.
- Screening Machines:Mechanical screening machines separate mixed materials by size, ensuring consistent particle distribution for downstream processes.
- Compactors:Compacting equipment reduces the volume of general waste for more economical transport and disposal.
Conveyors lead volumes today; Shredders are gaining share fastest.
Technology:
Technology selection reflects the precision required for material separation and the overall operational efficiency desired.
- Optical Sorting:Advanced sensor-based systems identify and separate materials based on color, shape, and composition with high accuracy. E-waste processing benefits from this precision to recover valuable metals from complex assemblies.
- Electromechanical:Direct-drive systems provide energy-efficient power transmission for heavy machinery, displacing legacy hydraulic systems. North America and Europe adopt these for shredders to reduce maintenance and energy costs.
- Mechanical:Robust mechanical systems provide basic material handling, size reduction, and separation functions.
- Hydraulic:Fluid power systems drive heavy machinery for crushing, baling, and compacting operations.
- Pneumatic:Air-based systems transport lightweight materials and separate lighter fractions from heavier ones.
- Magnetic Separation:Magnetic separators extract ferrous metals from mixed waste streams, improving material purity.
Efficiency gains are often realized through Electromechanical technologies, while Optical Sorting drives material purity.
Application:
Applications are segmented by the waste stream processed and the specific material recovery objectives.
- E-Waste Processing:Specialized systems reclaim precious metals, plastics, and glass from discarded electronic devices. Regulatory pressure from the EU's CSRD mandates detailed disclosures, driving demand for traceable processes.
- Scrap Metal Recovery:Equipment extracts various ferrous and non-ferrous metals from industrial and consumer scrap. China's GB standards for imported recyclables compel advanced processing for purity.
- Waste Management:Foundational equipment handles municipal solid waste for landfill diversion or basic recycling.
- Circular Economy:Integrated systems support closed-loop material flows across various industrial sectors.
- Construction Debris Recycling:Heavy-duty machinery processes concrete, wood, and metal from demolition sites for reuse.
- Agricultural Residue Handling:Equipment converts crop residues into biomass or other valuable resources.
Waste Management remains the broadest application, but E-Waste Processing shows the steepest expansion trajectory.
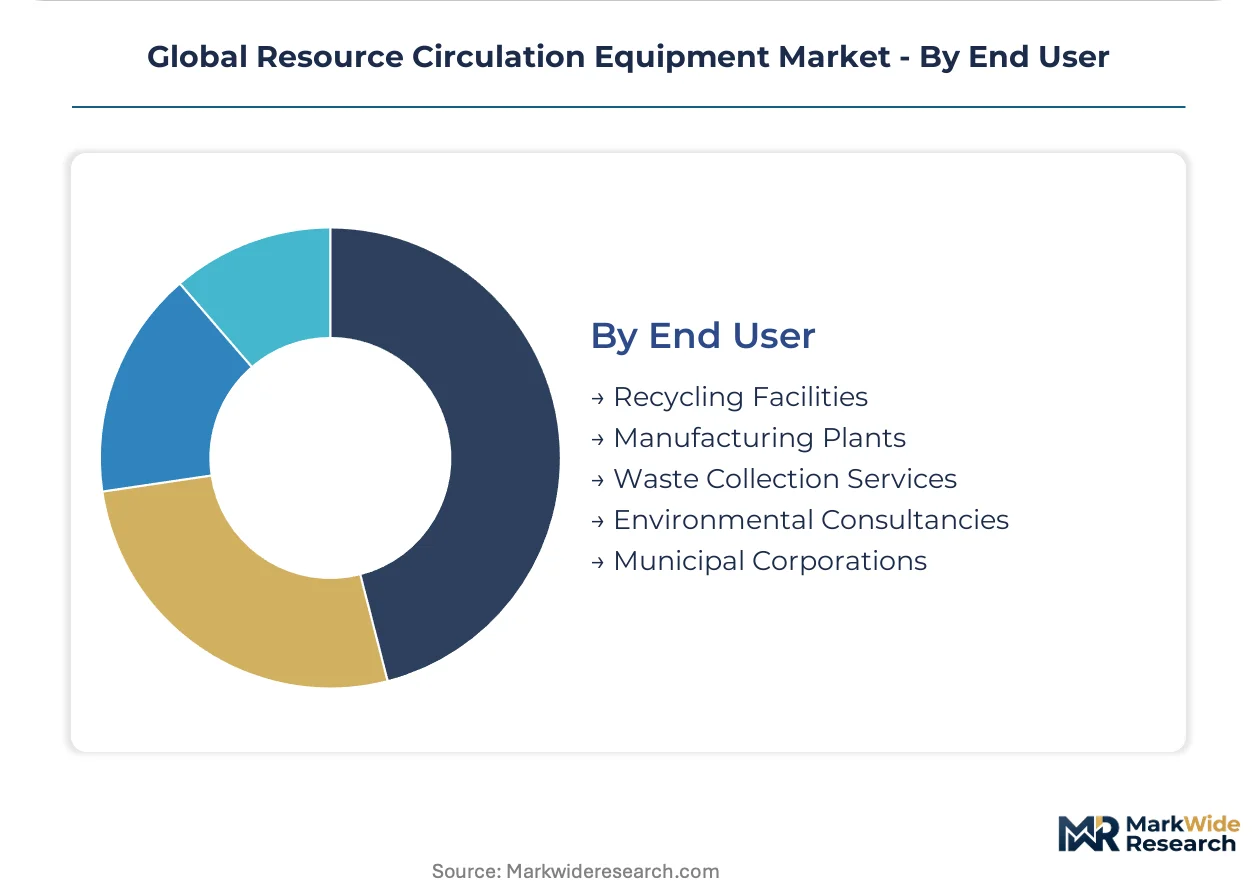
End User:
End-users are differentiated by their operational scale, investment capacity, and specific regulatory compliance needs.
- Recycling Facilities:Large-scale operations deploy comprehensive systems for sorting, shredding, and baling diverse waste streams. These facilities require high throughput capacity and material purity.
- Manufacturing Plants:Companies integrate resource circulation equipment to process internal waste streams and reintroduce materials into production. This reduces raw material costs and supports corporate sustainability goals.
- Waste Collection Services:These entities utilize compactors and balers for efficient waste handling before transfer to processing centers.
- Environmental Consultancies:Firms advise on equipment selection and system integration for compliance and operational efficiency.
- Municipal Corporations:Local governments invest in equipment to manage public waste, aiming for landfill diversion targets set by entities like the US EPA.
Recycling Facilities form the largest customer base, while Manufacturing Plants are increasingly adopting in-house solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The resource circulation equipment industry first scaled in industrialized nations, driven by early environmental regulations and the need for efficient waste processing. These foundational efforts established initial markets for sorting and shredding technologies. Modern demand now spans diverse geographies, influenced by evolving circular economy mandates.
Germany
Stringent environmental regulations and high industrial waste generation drive demand for advanced resource circulation equipment. The EU's Circular Economy Action Plan directly stimulates investment in sophisticated sorting and shredding systems. Industrial hubs like Bavaria and North Rhine-Westphalia are concentrating R&D for high-torque direct-drive shredders.
China
Rapid industrialization and urban growth generate immense waste volumes, requiring large-scale recycling infrastructure. China's GB standards for imported recyclables mandate high purity thresholds, compelling investment in superior sorting technology. The Yangtze River Delta region is a focal point for high-capacity conveyor system deployment in recycling facilities.
United States
Growing pressure for landfill diversion targets and increasing e-waste volumes stimulate demand for processing technologies. The US EPA sets ambitious landfill diversion goals, encouraging investment in efficient balers and compactors. California and other coastal states are leading in adopting AI-powered optical sorters for municipal solid waste.
France
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates detailed circular economy disclosures, influencing equipment procurement. France's national policies align with EU directives, promoting material recovery from various waste streams. The Grand Est region, with its industrial base, sees investment in advanced crushing equipment for construction debris.
India
Emerging formal waste management frameworks and rising urban waste generation create new opportunities for foundational equipment. India's Swachh Bharat Abhiyan (Clean India Mission) promotes better waste collection and processing infrastructure. Major metropolitan areas like Mumbai and Delhi are developing modern waste-to-resource facilities.
Global Resource Circulation Equipment Market Key Industry Players
The competitive structure tilts toward established engineering firms and specialized technology providers. This market exhibits a tiered landscape, with large industrial conglomerates competing alongside nimble innovators. Strategic archetypes include comprehensive system integrators, niche component specialists, and regional service providers. Companies are pursuing geographic expansion into emerging markets and investing in technology licensing to broaden their capabilities.
Specialists in heavy industrial machinery, Kawasaki Heavy Industries Ltd. exemplifies a large-scale engineering firm providing comprehensive waste processing systems. German-based Vecoplan AG occupies a position as a leader in high-torque shredder technology, catering to difficult material streams. Metso, a Finnish industrial company, anchors the segment for comprehensive crushing and screening technologies, particularly for mineral recycling applications. These entities represent distinct approaches to resource circulation equipment, from broad industrial solutions to highly specialized processing units, reflecting the diverse needs of the global market.
| Leading Market Players |
|---|
| Kawasaki Heavy Industries Ltd. |
| Vecoplan AG |
| Metso |
| Foster Wheeler |
| Wolf Material Handling Systems |
| ThermoSelect SA |
| Komptech GmBH |
| ECO Green Equipment |
| Veolia Environnement |
| Others |
Cost & Logistics Intelligence
Vertical integration by major equipment manufacturers like Kawasaki Heavy Industries anchors both their supply position and pricing power for complex resource circulation systems. This strategic choice allows them to control critical component supply and maintain higher margins on large-scale projects.
Pricing Analysis
A hybrid capital sales and service-based model is emerging, disrupting traditional equipment distribution. Pricing differentiation stems from customization for specialized applications like e-waste processing and comprehensive after-sales service bundles. Pricing pressure stems from the high capital expenditure required, particularly for smaller operators and municipalities. Smaller waste management operators are most price-sensitive, often seeking more flexible leasing arrangements to manage costs.
Supply Chain Analysis
Specialized component supply for resource circulation equipment rests on industrial manufacturing hubs in Germany for high-torque shredder components and China for high-capacity conveyor systems. The supply chain draws from global sources for steel, specialized alloys, and advanced electronic sensors. Regulatory fragmentation across regions presents a significant structural risk, increasing compliance costs for manufacturers. Equipment distribution is transitioning from one-time capital sales to long-term service and leasing agreements, particularly in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the European Union's Circular Economy Action Plan directly stimulating investment and technology adoption.
For Market Incumbents: Cement market leadership by leveraging extensive manufacturing capabilities and investing heavily in AI-powered sorting technologies. Focus R&D on electromechanical systems for superior energy efficiency and reduced maintenance, counteracting the threat from niche technology entrants. Pursue strategic technology licensing to broaden product portfolios and maintain a competitive edge in advanced processing. Reinforce channel control by offering comprehensive service and leasing agreements, especially in mature markets.
For New Entrants and Emerging Players: Capture white-space opportunities in nascent markets like Southeast Asia by providing foundational resource circulation equipment. Target the construction and demolition waste segment with heavy-duty crushing and screening solutions, an underdeveloped application area. A go-to-market angle focusing on specialized, cost-effective AI-powered optical sorters for e-waste processing offers a pathway to penetrate the fastest-growing application segment. Offer flexible financing models to overcome high capital expenditure barriers for smaller operators.
For Investors and Strategic Acquirers: Roll-up economics work for specialized technology providers because structural fragmentation allows for consolidation of advanced capabilities. The long-term viability of this market is secured by the global regulatory pivot towards circularity. Target archetype firms include those with strong intellectual property in AI-powered sorting or electromechanical systems, along with regional service providers. The formalization of waste management frameworks in emerging economies is a key signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Integration in Sorting Systems | Enhances material purity and processing speed, meeting stringent regulatory quality standards like China's GB standards. |
| Expansion into Construction & Demolition Waste | Unlocks a large, underdeveloped market for heavy-duty crushing and screening equipment, supporting material recovery goals. |
| Development of Electromechanical Shredders | Improves energy efficiency and reduces maintenance for processing challenging materials, displacing legacy hydraulic systems. |
| Offering Service & Leasing Models | Addresses high capital expenditure barriers for operators, aligning costs with processing volumes and managing technology risk. |
| Geographic Expansion into Emerging Markets | Capitalizes on the formalization of waste management frameworks in regions like Southeast Asia and Latin America. |
Research Approach
Coverage spans Europe, Asia, and North America, with primary inputs from each region informing the analysis of resource circulation equipment. This involved engaging with plant managers at recycling facilities, procurement leads at manufacturing plants, and regulatory compliance specialists. Secondary validation drew from EU environmental directives, US EPA reports, China's GB standards, and industry association publications, all triangulated with bottom-up and top-down data approaches.
Market granularity was modeled across equipment type, technology, application, end-user, and regional regulatory environment over the projection horizon. Compound annual growth rates were derived from historical trends, market growth drivers, and expert projections, with e-waste generation rates and national recycling targets serving as key forecast inputs. This comprehensive framework ensures a robust understanding of market dynamics.
Policy shifts, raw material price volatility, and technological breakthroughs are the dominant revision risks for this market. Forecasts reflect assumptions regarding regulatory enforcement and industrial investment cycles. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Water Treatment As a Service Market
Environment & Sustainability
Borehole Yield Testing Market
Environment & Sustainability
Wood Recycling Market
Environment & Sustainability
Carbon Footprint Management Market
Environment & Sustainability
Global Environmental Sensor Market
Environment & Sustainability
Global SCADA in Water and Wastewater Management Market
Environment & Sustainability
Carbon Verification Market
Environment & Sustainability
Global Temperature Management Market
Environment & Sustainability
Carbon Credit Market
Environment & Sustainability
Wheeled Bins Market
Environment & Sustainability
Sewage Pump Market
Environment & Sustainability
Asia-Pacific Indoor Air Purification Market
Environment & Sustainability
Sustainable Palm Oil Market
Environment & Sustainability
Green Emissions Analyzers Market
Environment & Sustainability
Asia Pacific Biochar Market
Environment & Sustainability
Environment Testing Services Market