
 Global Metal Detectable Tags and Labels Market | 2026-2036
Global Metal Detectable Tags and Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal Detectable Tags and Labels Market Intelligence
A shift from single-source procurement to multi-vendor strategies is pivoting how large food processors manage their supply chains for traceability components. Brady Corporation leverages its extensive distribution network to serve multinational clients seeking standardized solutions across different geographies. In contrast, specialist firms like Detectamet Ltd. and Alan Northrop Ltd Label Printers compete on customized product development for specific industrial applications.
Metal detectable tags and labels are identification products embedded with a metallic foil or film layer, typically aluminum, allowing detection by industrial systems. Their primary purpose is to prevent accidental contamination in sectors like food processing and pharmaceutical manufacturing by flagging any detached label fragments. Within product types, metal detectable films are seeing rapid uptake in automated packaging lines. Polypropylene continues to be a preferred material choice for its balance of durability and cost in harsh industrial settings.
Compliance with food safety standards is a major market determinant, with regulations from the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) setting baseline requirements. Global quality management systems like ISO 22000 also drive adoption for traceability and risk mitigation purposes. The key decision for end-users now revolves around balancing implementation costs against the escalating financial and reputational risks associated with product recalls.
Market Dynamics
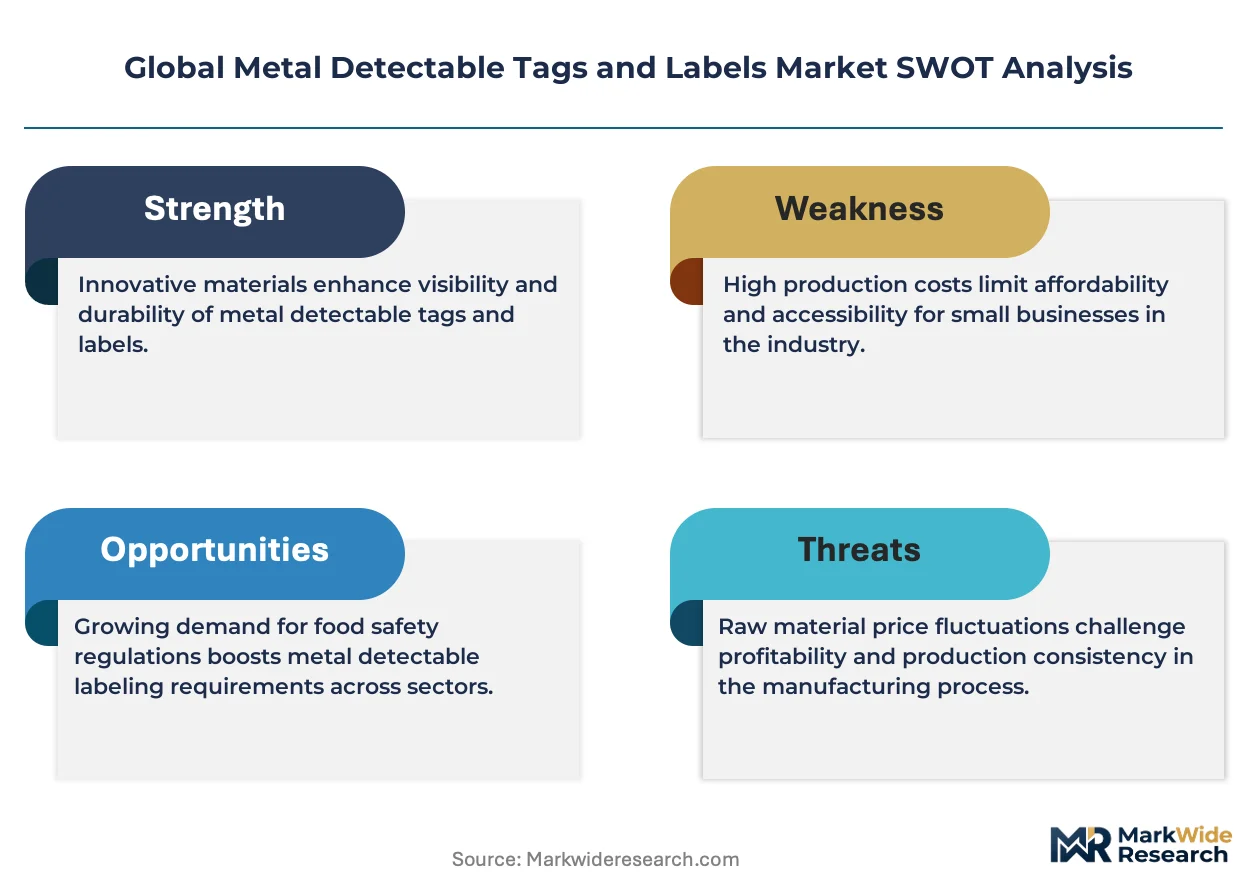
The intensification of global food safety standards is the central force shaping the market. Mandates from regulators like the U.S. Food and Drug Administration and the European Food Safety Authority create a non-negotiable demand floor for contaminant prevention technologies.
Growth Catalysts
- Regulatory Enforcement:The FDA's Food Safety Modernization Act (FSMA) in the United States compels food processors to implement preventative controls, directly stimulating demand for foreign object detection and traceability tools like detectable tags.
- Pharmaceutical Sector Expansion:Pharmaceutical manufacturing's zero-tolerance policy for contamination drives adoption to safeguard product integrity and comply with stringent quality management systems, preventing cross-contamination from packaging materials during production.
- Global Quality Standards:Adoption of ISO 22000 by food exporters, particularly in industrial centers like Germany, necessitates robust traceability systems, making metal detectable labels a key component for risk mitigation and market access.
Market Restraints
- Implementation Costs:The high capital expenditure required for industrial metal detection systems, in addition to the tags themselves, presents a significant barrier for small and medium-sized enterprises in the food processing industry.
- Technical Limitations:Detection sensitivity can be compromised by certain product characteristics, such as high moisture or salt content in foods, which can interfere with detector signals and potentially lead to false negatives.
- Input Material Price Volatility:Fluctuations in the global price of aluminum, the primary material used for the detectable foil layer, create cost instability and margin pressure for tag and label manufacturers.
Strategic Opportunities
- Application in Cosmetics Manufacturing:Expanding into the cosmetics and personal care sector offers a new growth vector, as manufacturers seek to prevent contamination from plastic or paper fragments in high-value formulations.
- Dual-Function Technology Integration:There is a clear opportunity for products that combine metal detectability with digital traceability technologies like RFID or QR codes, offering end-users a single solution for both safety and supply chain visibility.
- Emerging Market Penetration:Targeting the growing food processing industries in countries like Brazil and Mexico, where food safety regulations are becoming more stringent, provides a significant avenue for market expansion.
Industry Challenges
- Integration with Legacy Systems:End-users face difficulties integrating modern, high-sensitivity metal detection equipment and corresponding tag workflows into older, established production lines without causing significant downtime or process bottlenecks.
- Calibration and Standardization:A lack of universal standards for detector calibration and tag sensitivity across different equipment manufacturers complicates procurement and can lead to inconsistent performance for multinational food processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal Detectable Tags and Labels Market |
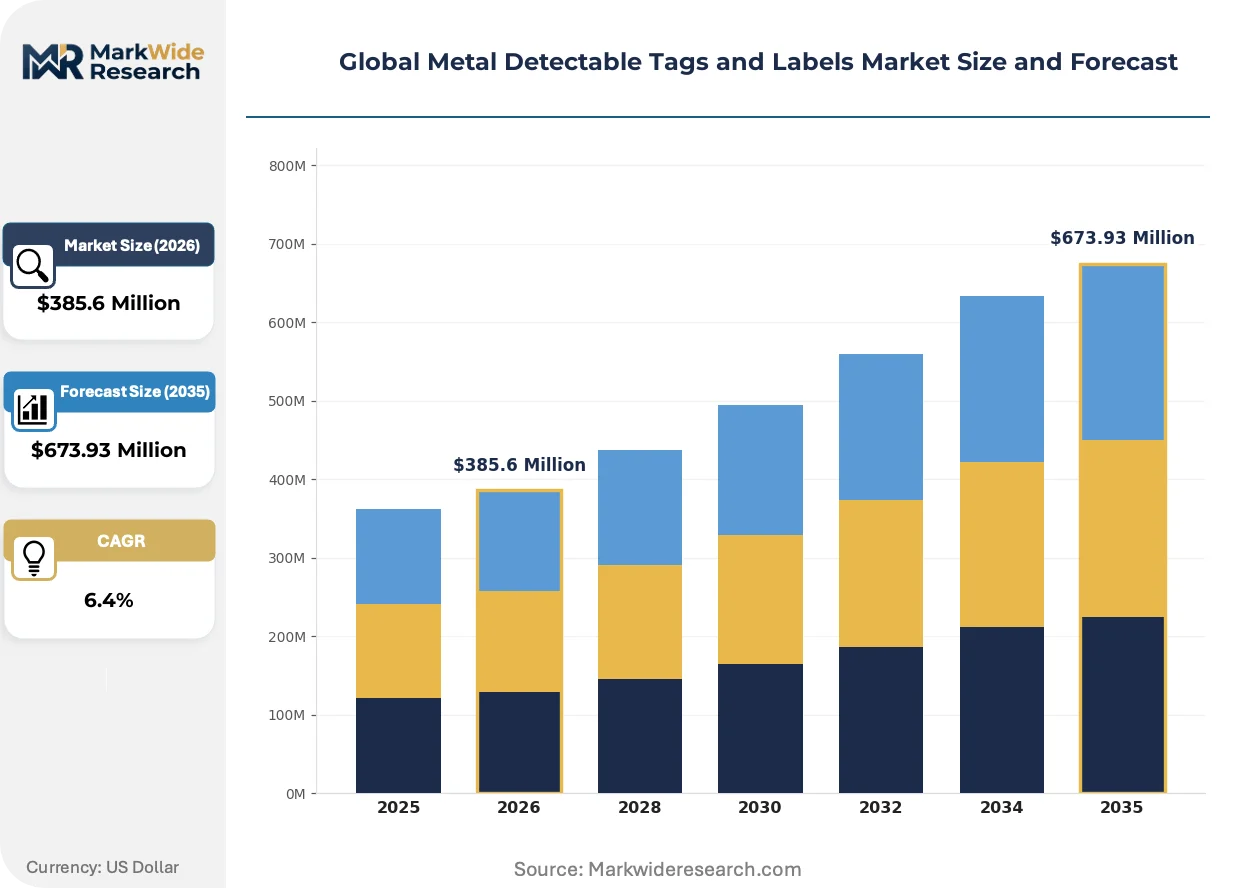
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Detectable Tags, Metal Detectable Labels, Metal Detectable Films, Metal Detectable Strips, Metal Detectable Tape Material: Polypropylene, Polyethylene, BOPP, PVC, PET, Acrylic Application: Food Processing, Pharmaceutical Manufacturing, Packaging Inspection, Textile Production, Electronics Assembly End User: Food Processing Plants, Pharmaceutical Companies, Packaging Services, Textile Manufacturers, Electronics Producers |
| Companies Covered | Detectamet Ltd., Brady Corporation, Alan Northrop Ltd Label Printers, Lara Marketing Labels, Bluepoint Tags & Labels Ltd, Dura-ID Solutions Limited, Shanghai BHii Instrument Co., Ltd., PMG Equipments group, Chemstar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal Detectable Tags and Labels Market Strategic Shifts & Innovations
Material science advancements are converging with digital traceability demands, pushing the market beyond simple contamination flagging. Innovations focus on enhancing detection reliability in challenging environments and embedding more data into the physical tag itself for comprehensive supply chain control.
Metal detectable films, designed for direct integration into automated packaging equipment, provide a seamless solution for high-speed production lines. Food processors are the primary adopters, particularly in applications using form-fill-seal machinery for products like snacks or powders. This integrated film format is overtaking the use of discrete, manually applied labels in high-volume settings, boosting operational efficiency.
European Food Safety Authority (EFSA) regulations concerning food contact materials are becoming more stringent, impacting tag composition. These rules mandate rigorous assessment of all components, including substrates, adhesives, and inks, to ensure they do not migrate into food products. This affects all manufacturers supplying the EU market, forcing investment in compliance testing and formulation adjustments with approved materials.
A notable behavioral shift involves large food processors diversifying their supplier base for traceability components. This pivot away from single-source dependencies toward a multi-vendor strategy aims to mitigate risk and improve access to specialized innovations. This trend is most prominent among multinational corporations in the United States and Germany, who balance global contracts with regional specialists for customized applications.
Global Metal Detectable Tags and Labels Market Segmentation

Understanding the segmentation of the global metal detectable tags and labels market reveals how diverse industry needs drive product development and material selection. This granular view helps identify where compliance requirements intersect with operational efficiency, guiding strategic investments across the value chain.
Product Type:
The market for metal detectable tags and labels exhibits a clear split between high-volume, standardized products and specialized, application-specific solutions. This differentiation influences procurement strategies for end-users balancing cost and performance.
- Metal Detectable Films:These products are thin, flexible materials embedded with metallic elements, designed for direct integration into automated packaging lines. Demand is concentrating in food processing plants across the United States and Germany, driven by the need for seamless foreign object detection in high-speed production.
- Metal Detectable Labels:These adhesive-backed identification items contain a metallic layer, ensuring detection if they detach from packaging. Food and pharmaceutical manufacturers utilize these labels extensively for product traceability and contamination control, especially where manual application is still prevalent.
- Metal Detectable Tags:Robust and often reusable, these tags are used for tracking assets or materials in harsh industrial environments.
- Metal Detectable Strips:Narrow, elongated metallic components are often integrated into specific packaging designs for enhanced detection capability.
- Metal Detectable Tape:This adhesive tape contains metallic particles, offering a flexible solution for sealing or bundling items while maintaining detectability.
Mature deployment sits with Metal Detectable Labels. Newer deployment is concentrated in Metal Detectable Films.
Material:
Material choices for metal detectable tags and labels are primarily dictated by the specific environmental conditions and regulatory requirements of the end-use application. Durability, chemical resistance, and cost efficiency are critical selection criteria.
- Polypropylene:This versatile polymer offers an excellent balance of durability, chemical resistance, and cost-effectiveness, making it a preferred material for labels in harsh food processing environments. Its widespread use in packaging makes it suitable for integration into existing systems.
- PET:Polyethylene terephthalate provides superior strength, clarity, and temperature resistance, often selected for high-performance applications in pharmaceutical manufacturing. The material's stability ensures label integrity under stringent sterilization processes.
- Polyethylene:A flexible and cost-effective material, polyethylene is used for various detectable labels and films where moderate durability is sufficient.
- BOPP:Biaxially-oriented polypropylene offers enhanced tensile strength and clarity, suitable for applications requiring durable and visually appealing labels.
- PVC:Polyvinyl chloride provides good chemical resistance and printability, though its use is becoming more regulated in certain food contact applications.
- Acrylic:Often used as an adhesive component, acrylic offers strong bonding properties and good resistance to environmental factors.
Polypropylene materials are seeing the steepest expansion trajectory. PET materials maintain a strong position in high-specification uses.
Application:
The application landscape for metal detectable tags and labels is heavily influenced by stringent safety regulations and the imperative to prevent product contamination across sensitive industries. Each sector presents unique demands for detection reliability.
- Food Processing:This sector represents the largest application area, driven by the FDA's Food Safety Modernization Act and EFSA regulations mandating robust foreign object detection. The primary goal is to prevent metallic contaminants from reaching consumers, safeguarding public health and brand reputation.
- Pharmaceutical Manufacturing:Pharmaceutical companies employ these labels to ensure product integrity and compliance with strict quality management systems, preventing packaging material cross-contamination. Zero-tolerance policies for foreign objects drive continuous innovation in detection sensitivity.
- Packaging Inspection:This application involves using detectable elements to ensure the integrity and closure of packaging, particularly in automated lines.
- Textile Production:Metal detectable components help identify and remove foreign metallic objects that might contaminate textile products during manufacturing.
- Electronics Assembly:In this application, detectable materials prevent tiny metallic fragments from damaging sensitive electronic components or causing product failures.
Food Processing applications command the largest market share. Pharmaceutical Manufacturing applications are expanding quickly.
End User:
The end-user base for metal detectable tags and labels is concentrated in industries where product safety, regulatory compliance, and brand protection are paramount. Procurement decisions often balance initial investment against the long-term costs of potential recalls.
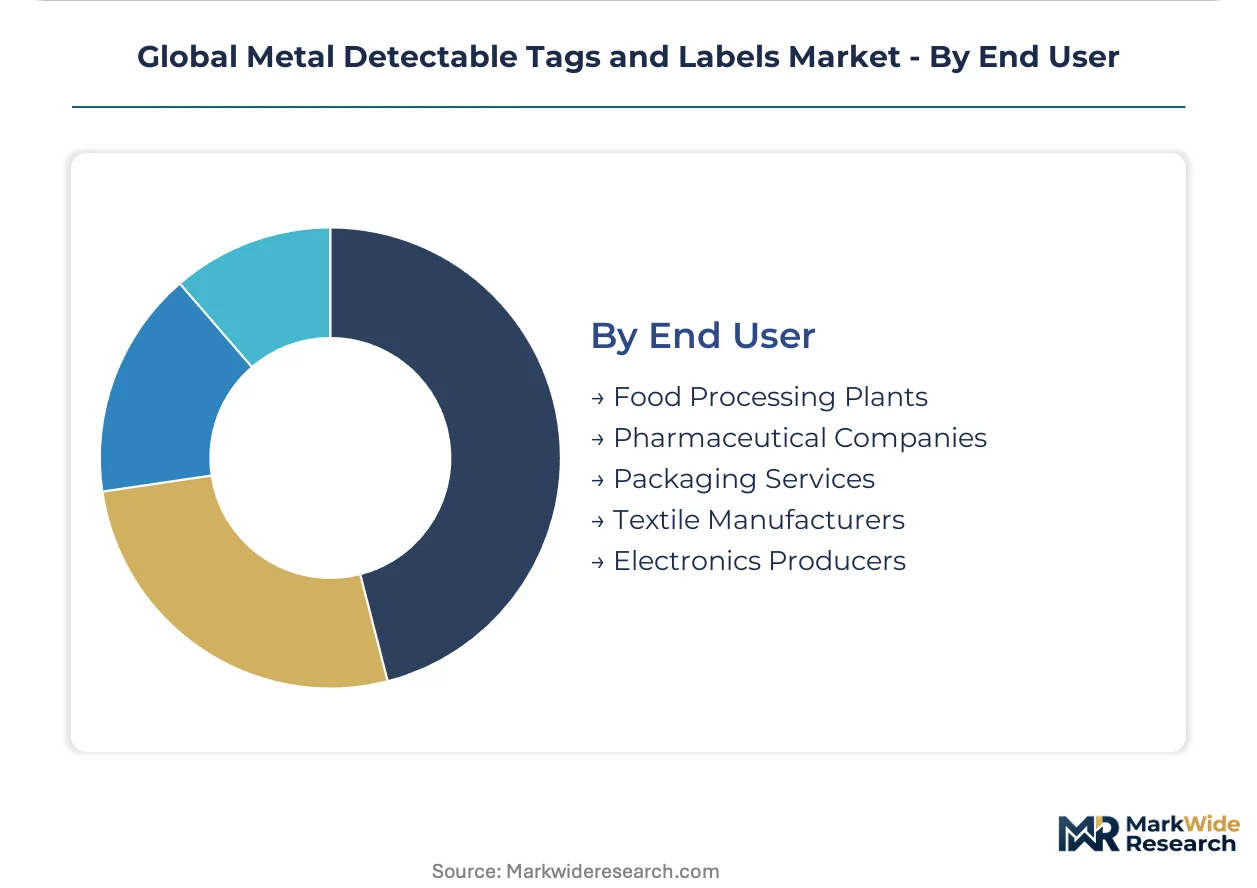
- Food Processing Plants:These facilities are primary end-users, requiring detectable tags and labels for compliance with food safety regulations and to prevent costly product recalls. Demand is particularly high in established food production centers like the United States and Germany.
- Pharmaceutical Companies:Driven by stringent quality control and patient safety requirements, pharmaceutical manufacturers integrate detectable materials into their packaging and production processes. This ensures product purity and adherence to global quality standards.
- Packaging Services:Companies providing packaging solutions to various industries use detectable materials to enhance the safety and traceability of their offerings.
- Textile Manufacturers:These producers utilize detectable tags and labels to manage contamination risks during the production of fabrics and garments.
- Electronics Producers:Manufacturers in the electronics sector employ detectable solutions to prevent foreign object contamination in sensitive assembly environments.
Food Processing Plants represent the largest consumer segment. Pharmaceutical Companies are demonstrating notable growth in adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for metal detectable tags and labels concentrates in regions with stringent food safety regulations and expanding pharmaceutical manufacturing. Food processing plants and pharmaceutical companies drive this demand, seeking enhanced traceability and foreign object detection solutions. Compliance with global quality standards further reinforces market growth in these established and emerging centers.
United States
Demand for metal detectable tags in the United States stems from its vast food processing and pharmaceutical industries. The FDA's Food Safety Modernization Act (FSMA) compels food processors to implement preventative controls, boosting foreign object detection tool adoption. Food production hubs across the Midwest and California actively integrate these solutions to ensure product safety.
Germany
Germany's strong emphasis on food safety and advanced manufacturing fuels demand for detectable tags. European Food Safety Authority (EFSA) regulations concerning food contact materials necessitate rigorous assessment of tag components. Industrial centers like Bavaria and North Rhine-Westphalia see high adoption, especially among food exporters adhering to ISO 22000.
Brazil
Brazil's growing food processing industry generates increasing demand for contaminant prevention technologies. ANVISA, the national health surveillance agency, is progressively tightening food safety standards, pushing manufacturers towards better traceability. The São Paulo region, a major agricultural and industrial hub, is a key area for deploying these safety components.
Mexico
Mexico's expanding food and beverage sector requires metal detectable solutions to meet domestic and export market requirements. The country's food safety regulations are becoming more stringent, aligning with international standards to facilitate trade. Manufacturing clusters in states like Nuevo León implement detectable tags to enhance product integrity for both local consumption and exports.
United Kingdom
The United Kingdom's pharmaceutical manufacturing sector and sophisticated food industry create steady demand for metal detectable tags. UK food safety agencies enforce strict guidelines, mirroring many EFSA requirements for product purity. Pharmaceutical production facilities in regions like the Southeast of England prioritize these materials for compliance with stringent quality management systems.
Global Metal Detectable Tags and Labels Market Key Industry Players
Geographic expansion dominates the current landscape, as market players seek to serve multinational clients and comply with varied regional regulations. The market for metal detectable tags and labels exhibits a tiered structure, with a mix of large, established players and niche specialists. Strategic archetypes include global solution providers leveraging extensive distribution networks and specialized product developers focusing on custom applications. Dominant competitive moves involve portfolio diversification to offer both standardized and bespoke solutions, alongside strategic partnerships to penetrate new markets.
Within the global solution provider archetype, Brady Corporation occupies a position leveraging its extensive distribution network to serve multinational clients. This approach enables the company to offer standardized solutions across different geographies. Specialist firms such as Detectamet Ltd., a UK-based entity, exemplify the customized product development approach for specific industrial applications. Alan Northrop Ltd Label Printers, another UK-based specialist, further reinforces the niche for bespoke industrial labeling solutions, contrasting with the broader, standardized offerings of larger entities. These specialized players cater to unique requirements within the market.
| Leading Market Players |
|---|
| Detectamet Ltd. |
| Brady Corporation |
| Alan Northrop Ltd Label Printers |
| Lara Marketing Labels |
| Bluepoint Tags & Labels Ltd |
| Dura-ID Solutions Limited |
| Shanghai BHii Instrument Co., Ltd. |
| PMG Equipments group |
| Chemstar |
| Others |
Cost & Logistics Intelligence
Specialized manufacturing expertise in Germany and the United States, particularly for high-specification detectable tags, contributes to higher pricing tiers for advanced solutions. Labor-cost differentials influence the overall cost structure, with standard products often sourced from regions with lower manufacturing overheads.
Pricing Analysis
Warranty and integration support services are frequently bundled with high-performance metal detectable systems, influencing the overall cost proposition. The dominant pricing model remains per-unit transactional, though long-term contracts are common for large multinational clients seeking consistent supply. Price differentiation stems from the product's certification level, such as FDA or EFSA compliance, and the degree of customization required for specific industrial applications. Pricing pressure originates from the volatility of aluminum, a key input material, and intensified competition from multi-vendor strategies. Small and medium-sized enterprises exhibit the highest price sensitivity due to significant implementation costs, while large pharmaceutical companies prioritize performance and regulatory compliance.
Supply Chain Analysis
Regional distribution centers and a hub-and-spoke model characterize the downstream distribution of metal detectable tags and labels. Geographic supply concentration for specialized products is notable in Germany and the United Kingdom, home to several specialist firms, while broader manufacturing capabilities are found in countries like China and the United States. The supply chain depends heavily on raw materials such as aluminum for the metallic layer, and polypropylene and PET for the base materials. Input material price volatility, particularly for aluminum, presents a structural risk to manufacturer margins. Distribution runs through a combination of direct sales channels for major clients and extensive distributor networks for wider market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is currently in a technology-transition phase, with advanced metal detectable films gradually replacing discrete, manually applied labels in high-speed production environments.
For Market Incumbents:Cement existing client relationships by offering comprehensive, integrated solutions that combine detectable tags with system calibration and maintenance support. Diversify product portfolios to include dual-function technologies, such as those integrating RFID or QR codes, to address evolving traceability demands. A named threat to incumbent market share comes from technical limitations in detecting certain product characteristics, necessitating continuous R&D investment in advanced material science and sensor technologies.
For New Entrants and Emerging Players:Capture market share by developing highly customized and niche solutions for specific industrial applications, particularly in sectors like cosmetics manufacturing. Penetrate emerging markets suchs as Brazil and Mexico, where food safety regulations are becoming more stringent but existing solutions may be less established or cost-prohibitive. A strong go-to-market angle involves offering cost-effective, compliant products tailored to the operational scales of small and medium-sized enterprises in these regions.
For Investors and Strategic Acquirers:Re-rating potential sits with specialist firms possessing strong material science intellectual property given intensifying regulatory demands and the need for advanced detection reliability. The long-term viability of this market, extending beyond a five-year window, is underpinned by non-negotiable food and pharmaceutical safety regulations. Acquisition targets should include mid-sized firms with proven dual-function technology or strong capabilities in specific high-growth material segments like polypropylene films. A specific signal to watch as an inflection indicator is increased venture capital funding in digital traceability startups that can integrate with physical detection.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Dual-Function RFID/Metal Detectable Tags | Offers end-users integrated safety and supply chain visibility solutions. |
| Strategic Partnership: With industrial automation providers | Streamlines integration of detectable films into high-speed packaging lines. |
| Capacity Expansion: In polypropylene film manufacturing | Addresses growing demand for cost-effective and durable detectable materials. |
| Acquisition of Specialist Firm: Focused on pharmaceutical applications | Bolsters expertise in high-specification, compliant material solutions. |
| Green Manufacturing Transition: For adhesive and substrate materials | Ensures compliance with evolving European Food Safety Authority regulations. |
Research Approach
U.S. Food and Drug Administration reports, European Food Safety Authority guidelines, and ISO 22000 standards formed the secondary backbone of this market analysis. This was complemented by primary interviews with industry stakeholders, including food safety managers, procurement directors, R&D engineers, and regulatory compliance officers across key geographies. The study employed a rigorous bottom-up and top-down triangulation approach to validate market size and growth projections against multiple data points.
A bottom-up analytical lens was applied to segment the market by product type, material, application, and end-user, with a further breakdown by geographic region. Each segment's compound annual growth rate (CAGR) was derived from historical trends, projected regulatory changes, and anticipated technological advancements across the modeling period. Industry-specific forecast inputs included regulatory enforcement timelines and anticipated raw material price fluctuations over the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unforeseen regulatory shifts and raw material supply disruptions. The forecasts reflect assumptions regarding sustained regulatory pressure and continued technological innovation in detection capabilities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Global Cryogenic Label Market
Labels
Hang Tags Market
Labels
Freshness Indicator Label Market
Labels
Linerless Labels Market
Labels
Europe Self Adhesives Label Market
Labels
Direct Thermal Linerless Labels Market
Labels
HAZMAT Labels Market
Labels
Extended Text Labels Market
Labels
Repositionable Labels Market
Labels
Stand Alone Label Applicator Market
Labels
Barcode Label Market
Labels
Global Label Adhesive Market
Labels
Industrial Label Printers Market
Labels
Foil Labels Market
Labels
Hot Melt Glue Labeler Market
Labels
Global Waterproof Labels Market