
 Beverage Cans Market | 2026-2036
Beverage Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Cans Market Intelligence
Aluminum's displacement of plastic and glass packaging for beverages is expanding the addressable market for can manufacturers. Ball Corporation leverages its extensive manufacturing footprint to serve major beverage brands across multiple continents. Crown Holdings, Inc. competes on innovation in can shaping and advanced printing technologies. Ardagh Group S.A. specializes in both aluminum and steel can formats to cater to diverse beverage categories, from beer to ready-to-drink cocktails.
Beverage cans are rigid containers, predominantly manufactured from aluminum using a two-piece drawn and wall-ironed (DWI) process. Their primary function is to provide a hermetically sealed, light-proof, and durable package for preserving carbonated and non-carbonated liquids. Aluminum represents the dominant material choice due to its lightweight properties and high recycling rates. While carbonated drinks remain a core application, demand for smaller can sizes like 250 ml is increasing for products such as energy drinks and ready-to-drink tea.
Regulations from bodies like the US FDA and the European Food Safety Authority (EFSA) govern food-contact materials and internal coating safety. In parallel, national recycling mandates and sustainability frameworks, including China's GB standards for packaging, influence material selection and can design. Strategic decisions for can makers will center on securing recycled aluminum supply and investing in production lines that accommodate new beverage categories.
Market Dynamics
A structural shift from plastic and glass to aluminum, driven by sustainability mandates like the EU Green Deal, is fundamentally expanding the market for beverage cans. This material substitution defines the current competitive landscape and investment priorities for manufacturers globally.
Growth Catalysts
- Sustainability Mandates:The EU Green Deal's circular economy goals favor aluminum's high recyclability over plastics, accelerating material substitution.
- New Beverage Categories:Ready-to-drink cocktails, hard seltzers, and cold brew coffee create new, high-volume applications for cans.
- Material Innovation:Lighter-gauge aluminum alloys reduce material costs and the carbon footprint of transportation.
Market Restraints
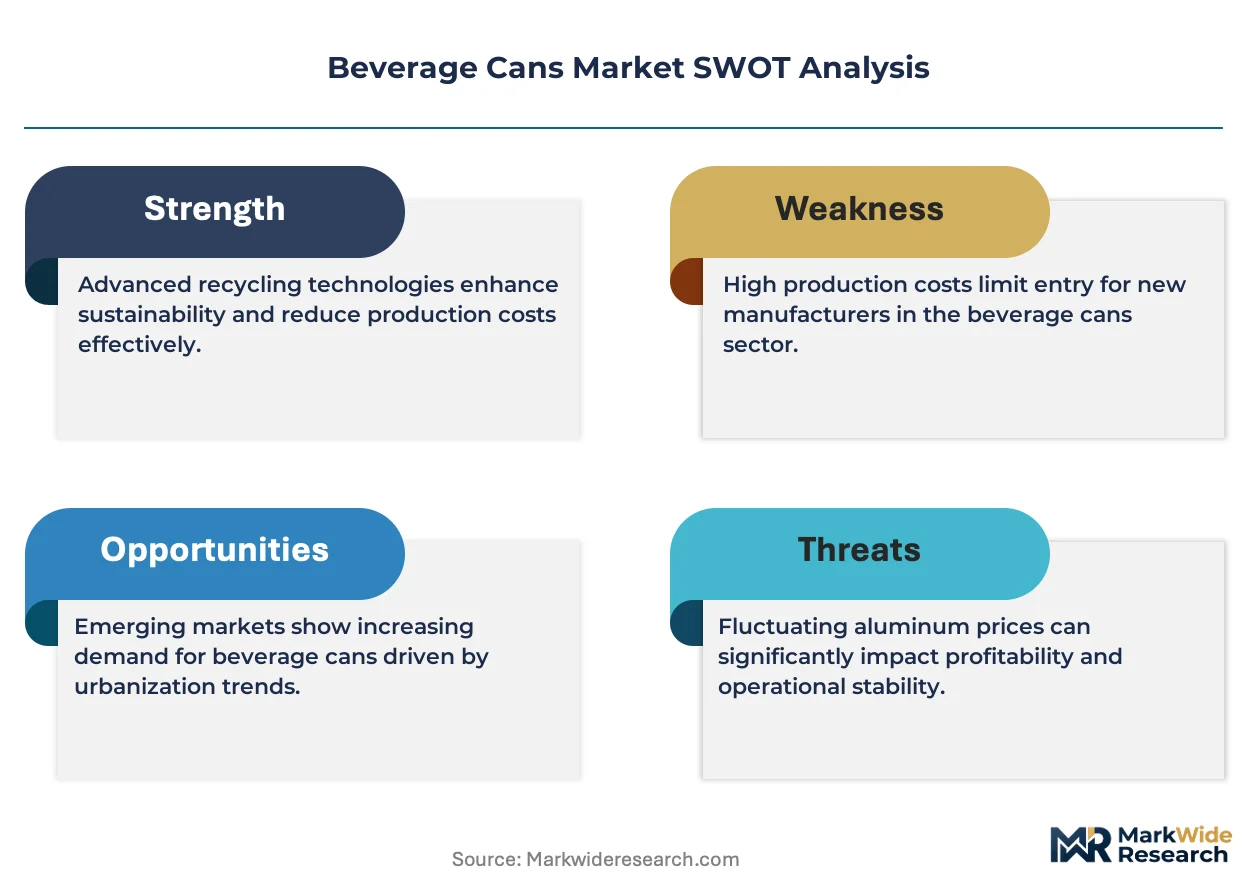
- Input Price Volatility:Fluctuations in primary aluminum pricing on the London Metal Exchange directly impact can manufacturing costs and margin stability.
- Supply Chain Concentration:Heavy reliance on a few countries for bauxite mining and alumina refining creates geopolitical supply risks.
- Substitution from PET:In non-carbonated segments, polyethylene terephthalate (PET) bottles remain a strong competitor due to lower initial costs.
Strategic Opportunities
- Untapped Geographies:Markets with low per-capita can consumption, such as India and Southeast Asia, offer substantial volume growth potential.
- Product Format Expansion:Canned wine and functional waters are transitioning from niche segments to mainstream consumer products.
- Smart Packaging Integration:Incorporating QR codes or NFC tags enables direct consumer engagement and supply chain traceability.
Industry Challenges
- Capital Expenditure Intensity:Adding new production lines for diverse can sizes and shapes requires significant upfront capital investment.
- Recycled Content Sourcing:Securing sufficient, high-quality post-consumer scrap is a critical operational hurdle for meeting circularity goals.
- Regulatory Divergence:Navigating different food-contact safety standards for internal coatings from bodies like the FDA and EFSA complicates global distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Cans Market |
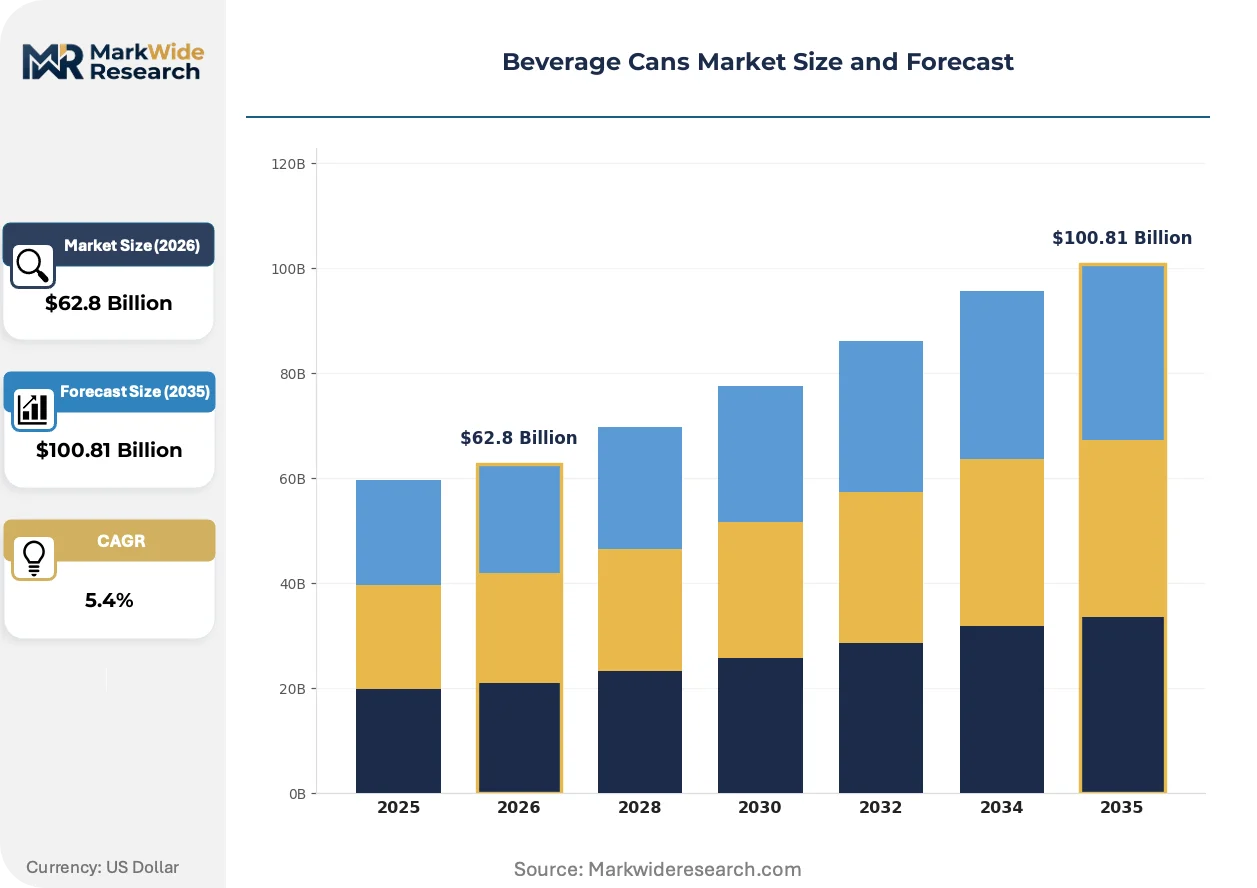
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $100.81 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Steel, Tinplate, Plastic, Composite Can Size: 250 ml, 330 ml, 500 ml, 750 ml, 1 Liter Application: Carbonated Drinks, Juices & Nectars, Energy Drinks, Ready-to-Drink Tea, Bottled Water End User Industry: Food & Beverage Manufacturers, Event Catering, Hospitality Services, Retail Chains, Vending Operators |
| Companies Covered | Ball Corporation, Crown Holdings, Inc., Ardagh Group S.A., CANPACK Group, Silgan Containers LLC, CPMC Holdings Limited, Orora Packaging Solutions, Envases Group, Kian Joo Can Factory Berhad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Cans Market Strategic Shifts & Innovations
Innovation in the beverage can market responds to the dual pressures of sustainability and product diversification. This forces advancements in manufacturing, material science, and surface decoration to meet new brand requirements.
Digital printing technology allows for direct-to-can graphics without plates, a process adopted by craft beverage producers for limited editions. This capability is rewriting the economics of can decoration, enabling cost-effective short runs that were previously unfeasible with traditional offset lithography.
State-level Extended Producer Responsibility (EPR) laws in the United States, such as those in Oregon, are altering packaging economics. These regulations assign end-of-life recycling costs to producers, which directly incentivizes brands to choose aluminum cans to minimize their financial liability under these new frameworks.
A consumer-led preference for portion control is creating demand for smaller, non-standard can sizes. This movement disrupts the focus on standard 12 oz formats, pushing for more 250 ml and 150 ml slim can production. The energy drink and RTD coffee segments in North America show the highest adoption.
Beverage Cans Market Segmentation
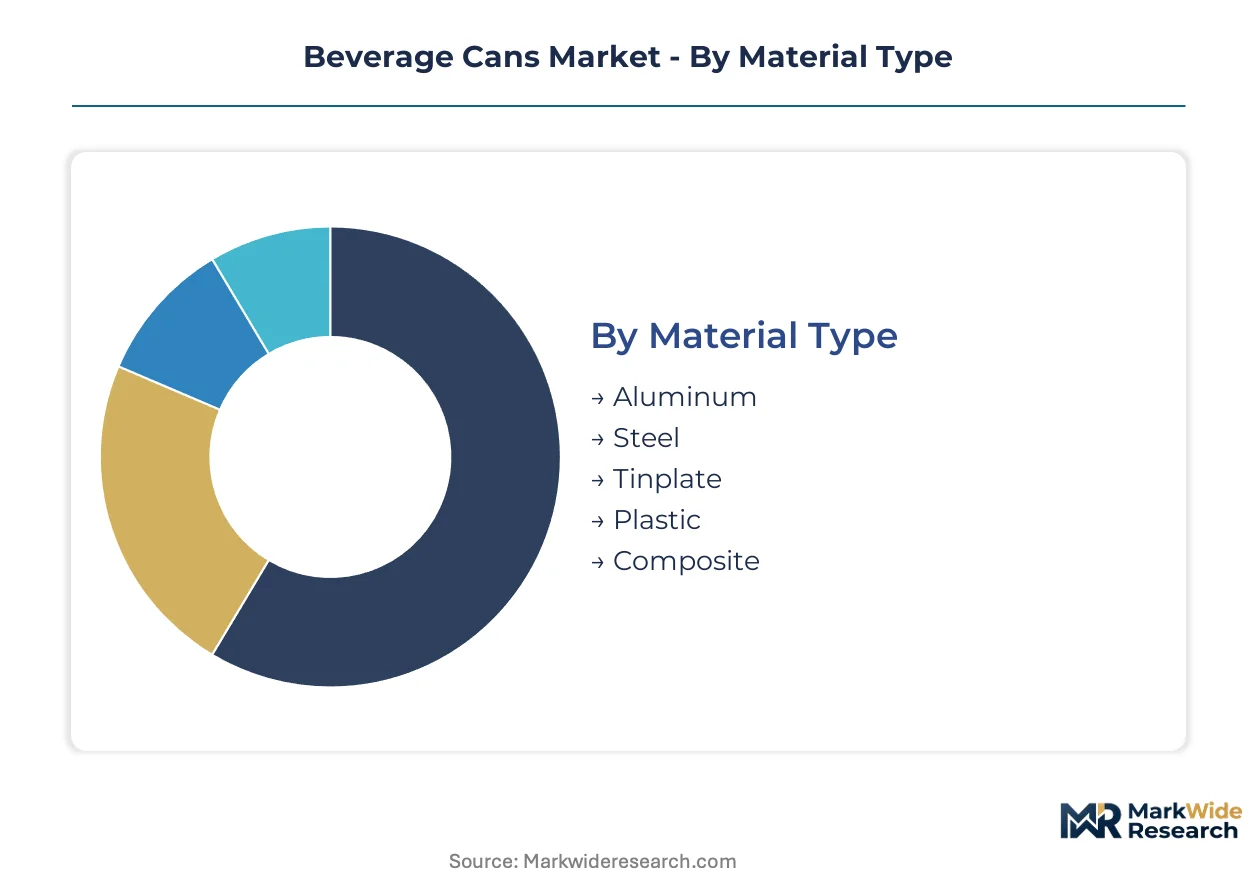
The beverage cans market segmentation provides a granular view of material preferences, size demands, application trends, and key end-user industries. Understanding these distinct segments allows manufacturers to align production capabilities with evolving consumer preferences and regulatory shifts. This detailed analysis highlights areas of both established demand and emerging growth opportunities.
Material Type:
The material type segmentation reveals a clear distinction between high-volume, infinitely recyclable options and more specialized, niche material solutions. Aluminum dominates the premium and standard segments due to its lightweight properties and recycling infrastructure.
- Aluminum:Aluminum cans are manufactured using a two-piece drawn and wall-ironed process, providing excellent barrier properties. Demand concentrates in high-consumption markets like the United States, driven by sustainability mandates such as the EU Green Deal.
- Steel:Steel cans offer robust structural integrity, often used for larger formats or specific product preservation needs in established markets. Their demand remains consistent in traditional segments like some carbonated beverages in Europe.
- Tinplate:Tinplate cans offer corrosion resistance for specific food and beverage applications.
- Plastic:Plastic containers offer cost advantages for specific non-carbonated segments.
- Composite:Composite cans combine multiple layers for enhanced barrier properties in specialty beverages.
Today's leader: Aluminum. Tomorrow's challenger: Steel.
Can Size:
Can size segmentation directly reflects evolving consumer consumption patterns and product innovation across various beverage categories. Smaller formats cater to portion control and convenience, while larger sizes serve multi-serve and value-oriented markets.
- 250 ml:This smaller format is growing significantly for energy drinks and RTD coffee in North America, aligning with consumer preferences for portion control. Its compact size reduces material usage and transportation costs.
- 330 ml:The 330 ml can remains a standard for carbonated soft drinks and beer across many global markets. Demand for this size is stable in mature beverage markets like Germany.
- 500 ml:The 500 ml can serves larger single-serve portions for sports drinks and some beer.
- 750 ml:The 750 ml can is adopted for wine and craft beer, offering a multi-serve alternative.
- 1 Liter:The 1 Liter can targets bulk consumption, prevalent in markets needing family-sized formats.
The 250 ml format represents the fastest-growing trajectory, driven by new beverage categories and consumer preference for convenience.
Application:
The application segmentation highlights the diverse end-uses for beverage cans, ranging from established, high-volume segments to rapidly emerging product categories. This distribution influences material selection and can design requirements.
- Carbonated Drinks:This remains a core application, leveraging aluminum's ability to maintain carbonation and provide a light-proof barrier. Demand for carbonated soft drinks is robust in markets like the United States.
- Energy Drinks:Energy drinks are a significant growth driver for smaller can formats, benefiting from aluminum's quick chilling properties. The segment shows strong expansion in North America and parts of Asia.
- Juices & Nectars:Juices and nectars utilize cans for extended shelf life, especially for single-serve portions.
- Ready-to-Drink Tea:Ready-to-drink tea in cans offers convenience, gaining traction in health-conscious segments across Europe.
- Bottled Water:Canned bottled water is an emerging segment, capitalizing on aluminum's sustainability.
Carbonated Drinks command the highest volume, while Energy Drinks drive the most innovation in packaging formats.
End User Industry:
End user industry segmentation clarifies the primary channels through which beverage cans reach consumers, impacting distribution strategies and packaging requirements. This includes both direct manufacturing and various retail and service sectors.
- Food & Beverage Manufacturers:These entities are primary buyers, integrating cans directly into production lines for various product lines. Their procurement decisions heavily influence can specifications globally.
- Retail Chains:Retail chains are critical distribution points, stocking canned beverages for direct consumer purchase. Large supermarket chains in Germany and France drive significant can volume.
- Event Catering:Event catering requires convenient, durable, single-serve canned beverages for functions.
- Hospitality Services:Hospitality services offer canned beverages for in-room dining, valuing presentation and storage.
- Vending Operators:Vending operators rely on standardized can sizes for automated dispensing and on-the-go consumption.
Food & Beverage Manufacturers contribute the largest value, while Retail Chains represent the most dynamic distribution channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States market for beverage cans demonstrates significant consumption volumes, driven by high demand for energy drinks and convenience-oriented formats. This market dynamism reflects broader shifts towards sustainable packaging solutions across various beverage categories. Manufacturers strategically position production to serve these concentrated consumer bases and emerging segments efficiently.
United States
High consumption of carbonated drinks and energy beverages drives demand for aluminum cans in the United States. US FDA regulations govern food-contact materials, ensuring product safety and compliance for internal coatings. California beverage producers are rapidly adopting aluminum cans, leveraging their high recyclability for new product launches.
Germany
Germany maintains stable demand for 330 ml cans, serving its mature carbonated soft drink and beer markets. The EU Green Deal's circular economy goals favor aluminum, influencing packaging choices across the country. Bavaria's craft beer industry increasingly utilizes aluminum for diverse product lines, emphasizing sustainability and portability.
China
China's market for beverage cans is expanding due to national recycling mandates and a growing preference for canned ready-to-drink beverages. China's GB standards for packaging significantly influence material selection and can design. Yangtze River Delta manufacturers are investing in advanced printing technologies for cans, catering to brand differentiation.
India
India presents substantial volume growth potential, characterized by low per-capita can consumption and an expanding middle class. The Bureau of Indian Standards (BIS) promotes packaging quality and material specifications within the country. Bengaluru's emerging beverage startups are exploring smaller can formats, targeting urban consumers with innovative products.
Beverage Cans Market Key Industry Players
Global majors compete with regional champions across manufacturing footprint and innovation capabilities within the beverage cans market. The industry exhibits consolidation among top-tier producers but remains fragmented at regional and national levels. Strategic archetypes include large-scale integrated manufacturers, specialized regional suppliers, and innovation-focused niche players. Companies pursue capacity expansion, strategic partnerships, and portfolio diversification to secure market share.
Within the global integrated manufacturers tier, Ball Corporation and Crown Holdings, Inc. exemplify extensive production networks and advanced material science expertise. Ball Corporation leverages its broad manufacturing footprint to serve major beverage brands across multiple continents. Crown Holdings, Inc. competes on innovation in can shaping and advanced printing technologies, offering specialized solutions. Ardagh Group S.A. occupies a position as a diversified packaging specialist, offering both aluminum and steel can formats to cater to diverse beverage categories. These entities collectively anchor the market's supply side, leveraging scale and established relationships across continents.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings, Inc. |
| Ardagh Group S.A. |
| CANPACK Group |
| Silgan Containers LLC |
| CPMC Holdings Limited |
| Orora Packaging Solutions |
| Envases Group |
| Kian Joo Can Factory Berhad |
Cost & Logistics Intelligence
Primary aluminum pricing directly influences manufacturing costs for beverage can producers, impacting downstream pricing across all can formats.
Pricing Analysis
Input cost fluctuations, particularly in primary aluminum, directly translate into variable pricing for beverage can manufacturers. Contract-based long-term offtake agreements dominate for large beverage brands, while smaller producers use more commodity spot pricing. Volume scale provides significant price advantages, alongside customization levels for advanced printing technologies. Pricing pressure stems from the volatility of aluminum on the London Metal Exchange. Food & Beverage Manufacturers exhibit high price sensitivity for standard formats, while craft beverage producers accept higher costs for digital printing.
Supply Chain Analysis
Food-contact material certifications from bodies like the US FDA and EFSA gate market access for can suppliers globally. Supply of primary aluminum concentrates heavily in countries like China and Australia for bauxite mining and alumina refining. The supply chain depends on bauxite, alumina, and specialized internal coatings. Geopolitical supply risks arise from heavy reliance on a few countries for upstream materials. Distribution runs directly through Food & Beverage Manufacturers, who integrate cans into their production lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The beverage can market presents a geographic-arbitrage play, as lower production costs in Southeast Asia offer a significant differential compared to Western European markets.
For Market Incumbents: Deepen strategic partnerships with recycled aluminum suppliers to mitigate input price volatility. Incumbents must also invest in flexible production lines accommodating diverse can sizes, addressing the threat from plastic and glass in some segments. Capacity addition in untapped geographies like India and Southeast Asia strengthens market position against regional challengers. This proactive investment defends against margin pressure driven by primary aluminum price swings.
For New Entrants and Emerging Players: Begin with niche segments like craft beverages and functional drinks, targeting demand for smaller 250 ml can formats. Untapped geographies such as India and Southeast Asia offer substantial volume growth potential due to low per-capita consumption. A go-to-market angle leveraging advanced digital printing for cost-effective short runs provides differentiation against established players. Focus on sustainability messaging around aluminum's recyclability to attract environmentally conscious brands.
For Investors and Strategic Acquirers: Roll-up economics work for regional can manufacturers because local production optimizes logistics costs for beverage brands. The long-term viability of the beverage can market is underpinned by global sustainability mandates favoring aluminum over other materials. Acquisition targets should include specialized regional suppliers with advanced printing capabilities or strong recycled content sourcing networks. A signal to watch is the acceleration of state-level Extended Producer Responsibility (EPR) laws in new US states, which directly incentivizes aluminum adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Increases market share in high-growth regions like India with expanding middle-class consumption. |
| Recycled Aluminum Supply Agreements | Secures critical input material, stabilizing manufacturing costs for can producers. |
| Investment in Digital Printing | Enables cost-effective short runs for craft beverage producers, expanding addressable market segments. |
| Development of Smaller Can Formats | Caters to consumer demand for portion control in energy drinks and RTD coffee segments. |
| Strategic Partnerships with Beverage Brands | Ensures long-term volume commitments for can manufacturers, reinforcing market stability. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing the analysis. This involved combining in-depth primary interviews with packaging engineers, procurement leads at Food & Beverage Manufacturers, and sustainability officers. Secondary validation drew from SEC 10-K filings of major can producers, industry association reports, and national recycling statistics. A rigorous bottom-up and top-down triangulation process ensured data accuracy and forecast reliability.
Rate-of-change decomposition underpinned the analytical framework, assessing market evolution across the analysis window. The model incorporated segmentation by material type, can size, application, end-user industry, and regional regulatory environment. Compound Annual Growth Rates were derived from comprehensive volume and value projections, informed by historical trends. Key industry-specific forecast inputs included per-capita beverage consumption trends and evolving recycled content mandates.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events impacting raw material supply chains. Forecasts reflect assumptions regarding stable regulatory environments and gradual material science advancements. Rapid, disruptive material science breakthroughs or sudden shifts in global trade policies represent key risk factors. A model refresh is warranted upon material change in global primary aluminum pricing or major new sustainability legislation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Europe Soft Drinks Packaging Market
Beverage Packaging
Slip Cover Cans Market
Beverage Packaging
Beverage Crates Market
Beverage Packaging
Disposable Tea Flask Market
Beverage Packaging
Self-Chilling Can Market
Beverage Packaging
Biotainer Market
Beverage Packaging
Indonesia Plastic Bottles Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
US Beverage Packaging Market
Beverage Packaging
Juice Packaging Market
Beverage Packaging
Beverage Packaging Machine Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Can Sleeves Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Water Bottle Racks Market
Beverage Packaging
Soft Drinks Packaging Market