
 GCC Labeling Market | 2026-2036
GCC Labeling Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Labeling Market Insights
Expatriate print technician availability in the GCC is unwinding as visa policy tightening and nationalization quotas raise labor costs for converters. Avery Dennison Corporation anchors the premium pressure-sensitive segment through its Jeddah distribution hub and local slitting operations. CCL Industries Inc. dominates pharmaceutical and healthcare labeling with specialized serialization-compliant capacity serving Saudi Arabia's PMDA-aligned regulatory environment. Sigma Middle East Label Industries LLC leverages proximity to Dubai's logistics free zones to sustain rapid-turnaround supply for FMCG brands.
GCC labeling encompasses adhesive-backed substrates, shrink sleeves, and in-mold decorations applied to consumer and industrial packaging, typically manufactured through flexographic or digital rotary processes with print resolutions ranging from 120 to 175 lines per inch for barcode scannability and brand reproduction. Film labels lead value contribution due to moisture resistance requirements in the region's high-temperature supply chains, while digital printing represents the fastest-expanding technology segment as pharmaceutical and cosmetics brands reduce minimum order quantities and versioning costs. Paper labels retain volume dominance in food and beverage applications where cost sensitivity and single-use disposal predominate.
SFDA serialization mandates in Saudi Arabia and MOHAP traceability requirements in the UAE are reshaping pharmaceutical label specifications toward integrated RFID and two-dimensional barcode formats. The Emirates Authority for Standardization and Metrology enforces halal certification labeling protocols that govern ink composition and substrate compliance for food exports. Stakeholders must monitor evolving Gulf Cooperation Council technical regulations for unified packaging standards and assess digital press investments against flexographic retrofit economics as run lengths continue fragmenting across personal care and nutraceutical launches.
Market Dynamics
Pharmaceutical serialization mandates across Saudi Arabia and the UAE are compressing procurement cycles and forcing converters to retool for integrated track-and-trace capabilities. This regulatory pressure is accelerating capital deployment toward digital printing and RFID-enabled label architectures.
Growth Catalysts
- SFDA Serialization Mandates:Saudi Arabia's pharmaceutical traceability requirements are compelling domestic and multinational drug manufacturers to upgrade labeling infrastructure for compliance deadlines.
- Digital Rotary Press Adoption:Short-run cosmetics and nutraceutical launches in Dubai's free zones are pulling demand toward variable-data printing that eliminates plate costs and reduces versioning minimums.
- Food Processing Cluster Expansion:The Riyadh-Jeddah corridor's concentration of dairy and beverage packaging facilities is generating sustained bulk procurement of moisture-resistant film labels.
Market Restraints
- Expatriate Technician Scarcity:Saudi nationalization quotas and UAE visa tightening are raising wage costs for skilled flexographic press operators and prepress specialists.
- Petrochemical Feedstock Volatility:Polypropylene and polyethylene substrate prices track regional oil benchmarks, squeezing converter margins on fixed-price annual contracts.
- Halal Certification Complexity:Emirates Authority for Standardization and Metrology protocols governing ink composition and substrate compliance create formulation lock-in and extend qualification timelines for food export labels.
Strategic Opportunities
- Kuwait and Oman Penetration:Underdeveloped domestic label manufacturing capacity in these markets creates import substitution potential for Saudi and UAE converters with excess digital press capacity.
- RFID-Barcode Convergence:Pharmaceutical and luxury goods segments are piloting dual-technology labels combining EPC Gen 2 inlays with serialized 2D barcodes for omnichannel authentication.
- Free Zone Proximity Models:Dubai South and Jebel Ali logistics corridors enable rapid-turnaround supply contracts with FMCG brands requiring 48-hour replenishment cycles.
Industry Challenges
- Serialization Data Architecture:Pharmaceutical converters must integrate SAP ATTP and TraceLink cloud platforms with legacy ERP systems, requiring specialized IT integration talent scarce in the GCC.
- Digital Press Capex Recovery: HP Indigo and Xeikon equipment investments face payback pressure as pharmaceutical run lengths fragment below 10,000-unit thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Labeling Market |
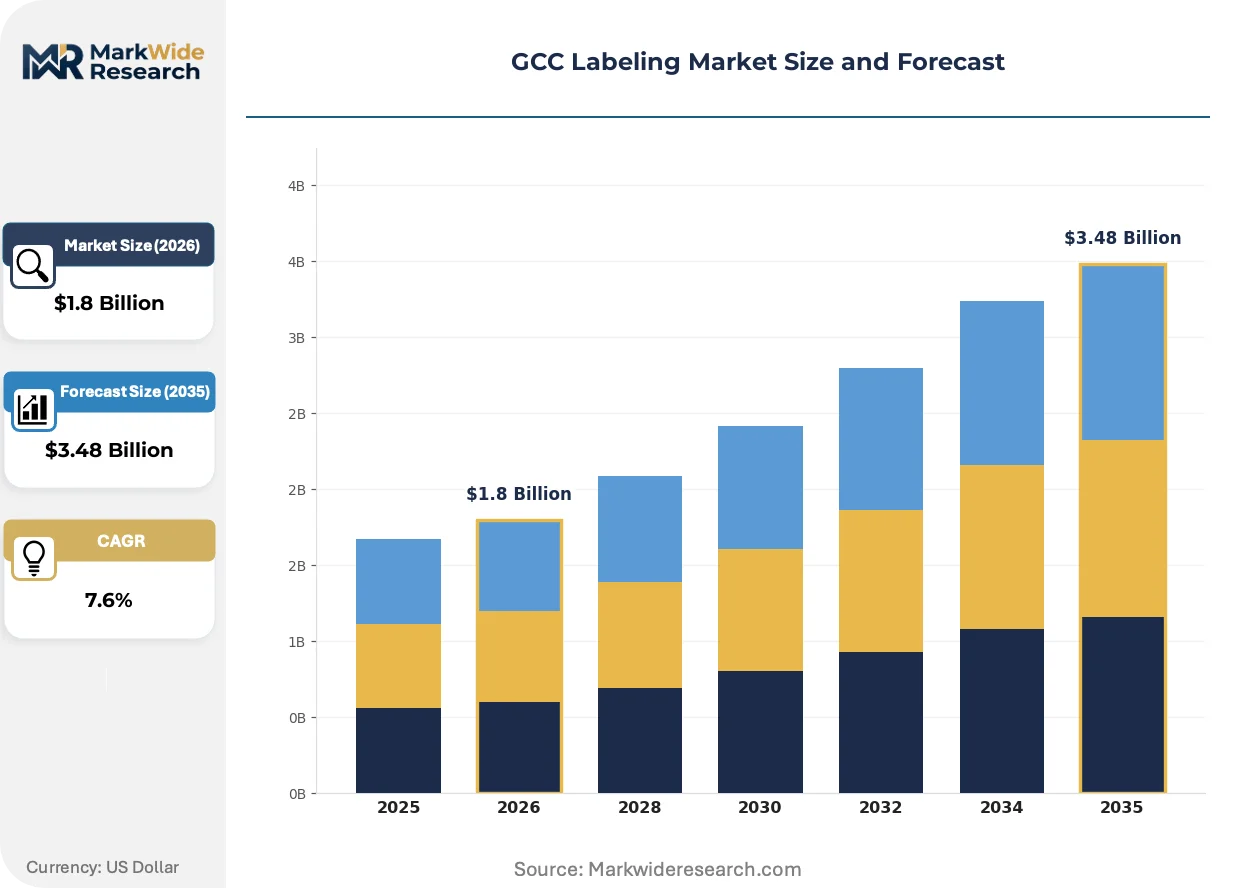
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Synthetic, Paper, Film, Foil Application: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products End User: Manufacturers, Retailers, Distributors, End Consumers Technology: Flexography, Digital Printing, Gravure, Offset |
| Companies Covered | Huhtamaki OYJ, Avery Dennison Corporation, CCL Industries Inc., Honeywell International Inc., Brady Corporation, Mondi Group, Taghleef Industries Inc., Sigma Middle East Label Industries LLC, 3M Company, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Labeling Market Trends and Innovations
Label production workflows across the GCC are pivoting from high-volume flexographic efficiency toward digital agility that matches pharmaceutical and cosmetics versioning requirements. This structural reorientation is compressing traditional equipment depreciation cycles and reshaping converter specialization.
Digital inkjet and toner-based rotary presses are displacing conventional flexography in short-run pharmaceutical and personal care packaging workflows. Saudi and UAE-based converters serving multinational cosmetics brands are retiring solvent-based flexo lines in favor of water-based digital systems that eliminate plate inventory and enable same-day artwork changes. This technology shift is compressing minimum order quantities from 50,000 units toward 5,000-unit thresholds.
SFDA serialization mandates and MOHAP traceability requirements are mandating integrated 2D Data Matrix and human-readable lot codes on all pharmaceutical primary packaging. These regulations are forcing label specifications toward multi-layer constructions with tamper-evident features and covert authentication elements. Saudi manufacturers are responding by qualifying specialized serialization-compliant substrates from European suppliers.
FMCG procurement patterns are fragmenting as multinational brands localize production in Saudi Arabia's King Abdullah Economic City and Dubai Industrial City. This geographic demand rotation is shortening supply chain radii and privileging converters with slitting and distribution hubs adjacent to these manufacturing clusters. Traditional Beirut and European import channels are losing share to domestic GCC supply.
GCC Labeling Market Segmentation
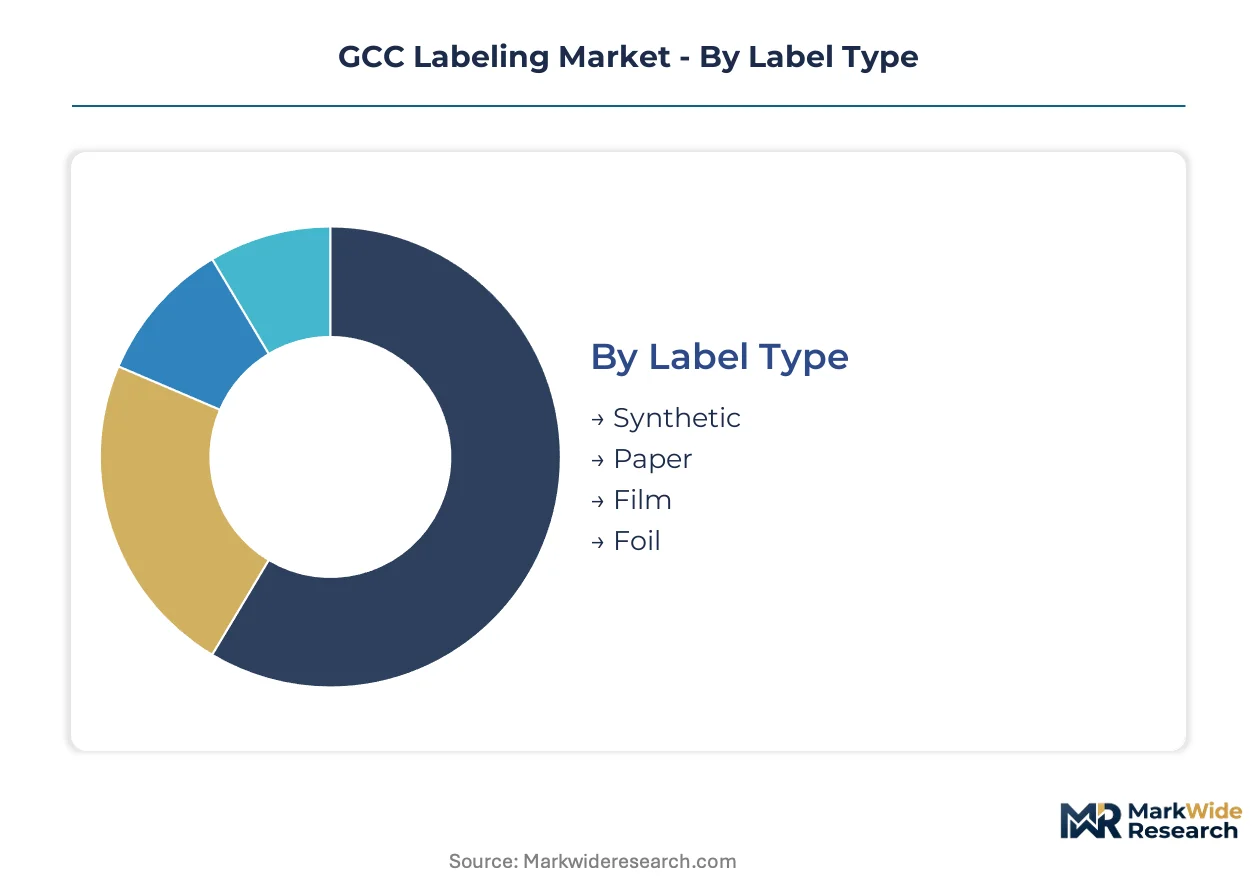
Segmentation in the GCC labeling market reveals how substrate choices, application requirements, and technology investments map to divergent margin structures across Saudi Arabia and the UAE. Understanding these splits enables converters to align capital deployment with the highest-return pockets in a market reshaped by pharmaceutical serialization and food export compliance.
Label Type:
Margin pools concentrate in synthetic and film substrates where moisture resistance commands pricing premiums in the region's high-temperature supply chains.
- Film:Polypropylene and polyethylene constructions deliver barcode scannability and dimensional stability across dairy, beverage, and pharmaceutical packaging. Demand clusters in Saudi Arabia's Riyadh-Jeddah corridor where food processing facilities require moisture-resistant labels for refrigerated distribution. SFDA serialization mandates are pushing film specifications toward multi-layer constructions with tamper-evident features.
- Synthetic:Polymer-based substrates combine durability with print receptivity for variable-data applications in cosmetics and nutraceutical versioning. UAE-based converters serving Dubai's free zone brands are rotating capacity toward synthetic stocks that eliminate plate inventory and enable same-day artwork changes. Premium pricing reflects qualification complexity under Emirates Authority for Standardization and Metrology halal protocols.
- Paper:Cellulose-based labels retain volume dominance in cost-sensitive food and beverage applications where single-use disposal predominates. Saudi dairy processors specify paper for short-shelf-life products.
- Foil:Metallized substrates serve premium cosmetics and pharmaceutical authentication with covert security elements. Limited domestic slitting capacity in the GCC creates import dependency.
Film holds installed capacity. Synthetic is rotating up the share rankings.
Application:
Application segmentation tracks regulatory intensity and procurement cycle length, with pharmaceutical serialization creating the steepest technology barriers to entry.
- Pharmaceuticals:Primary and secondary packaging labels integrate 2D Data Matrix codes, human-readable lot numbers, and RFID inlays for SFDA and MOHAP traceability compliance. Saudi manufacturers are qualifying European-sourced serialization-compliant substrates. Capital requirements for digital presses and cloud-based ERP integration (SAP ATTP, TraceLink) filter the converter base.
- Food & Beverage:Labels for dairy, bottled water, and processed foods dominate unit volume across the GCC, with moisture-resistant film specifications prevalent in Saudi Arabia's King Abdullah Economic City cluster. Halal certification ink and substrate protocols extend qualification timelines for export-bound production.
- Cosmetics:Personal care brands in Dubai's free zones are fragmenting run lengths below 10,000 units, pulling demand toward digital rotary presses with water-based systems. Variable-data capabilities enable regional versioning for multinational portfolios.
- Household Products:Detergent and cleaning chemical labels prioritize chemical resistance and cost minimization. Standard flexographic workflows predominate.
Food & Beverage maintains volume leadership. Pharmaceuticals is climbing the fastest on value contribution.
End User:
End user segmentation reflects supply chain position and technical specification authority, with manufacturers capturing the deepest converter relationships.
- Manufacturers:Food processors, pharmaceutical producers, and cosmetics formulators in Saudi Arabia and the UAE specify label substrates, adhesives, and print technologies directly. Procurement contracts span 12-24 month horizons with volume commitments. King Abdullah Economic City and Dubai Industrial City clusters concentrate specification authority.
- Distributors:Third-party logistics providers and regional trading houses procure standardized labels for repackaging and private-label assembly. Demand concentrates in Jebel Ali and Dubai South free zones.
- Retailers:Hypermarket and pharmacy chains specify shelf-ready labeling for private-label product lines. Short replenishment cycles favor converters with 48-hour turnaround capabilities.
- End Consumers:Direct procurement is negligible, though smartphone-enabled authentication features on pharmaceutical and luxury labels create downstream engagement data.
Manufacturers control specification authority. Retailers are gaining procurement influence through private-label expansion.
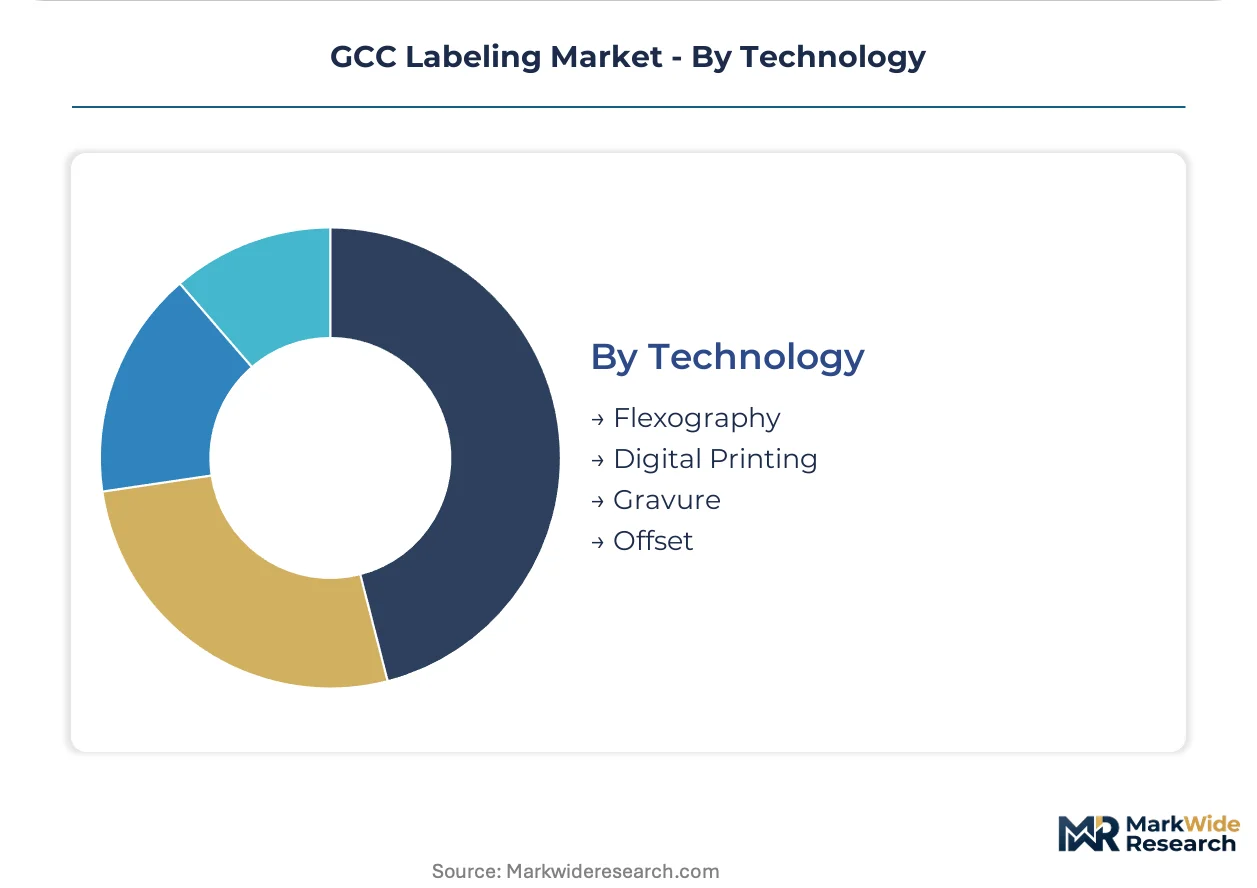
Technology:
Technology segmentation captures the displacement of conventional flexography by digital systems as run lengths fragment and versioning requirements intensify.
- Digital Printing:Toner-based and inkjet rotary presses eliminate plate costs and enable variable-data serialization for pharmaceutical compliance. HP Indigo and Xeikon equipment deployments face payback pressure below 10,000-unit thresholds. Cosmetics and nutraceutical launches in Dubai's free zones are the primary demand pull.
- Flexography:Solvent-based and water-based flexo lines retain efficiency in high-volume food and beverage applications with stable artwork. Saudi nationalization quotas and expatriate technician scarcity are raising operating costs.
- Gravure:High-volume, high-quality reproduction for premium cosmetics and export-oriented food packaging. Limited GCC installed base creates reliance on European and Asian supply.
- Offset:Sheet-fed and web offset serve folding carton and label applications with long run lengths and precise color matching. Declining share in primary label markets.
Flexography retains volume throughput. Digital Printing is expanding most quickly on capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Saudi Arabia's Riyadh-Jeddah corridor where pharmaceutical serialization and food processing clusters command premium label specifications, while UAE converters leverage Dubai's logistics free zones for rapid-turnaround contracts at compressed margins.
Saudi Arabia
Pharmaceutical serialization mandates from SFDA are accelerating demand for track-and-trace labels with integrated RFID and 2D Data Matrix formats. The regulator's traceability deadlines are compelling domestic drug manufacturers to upgrade labeling infrastructure. King Abdullah Economic City anchors this demand concentration with dairy and beverage packaging facilities procuring moisture-resistant film labels at scale.
United Arab Emirates
MOHAP traceability requirements are reshaping pharmaceutical label specifications toward multi-layer constructions with tamper-evident features. Dubai's cosmetics and nutraceutical brands in Jebel Ali free zones are fragmenting run lengths below 10,000 units, pulling capacity toward digital rotary presses. Sigma Middle East Label Industries LLC leverages proximity to these logistics corridors for 48-hour replenishment cycles.
Kuwait
Underdeveloped domestic label manufacturing capacity creates import substitution potential for Saudi and UAE converters with excess digital press capability. The country's national pharmaceutical regulator is aligning with Gulf Cooperation Council unified packaging standards. Food processing clusters around Kuwait City are generating procurement of pressure-sensitive labels for regional export.
Oman
Limited local converter base positions the market for cross-border supply from Saudi Arabia's Eastern Province. The sultanate's standardization authority is adopting GCC technical regulations for halal certification labeling protocols. Industrial zones around Sohar and Salalah are attracting FMCG distribution hubs requiring standardized label supply.
Qatar
Pharmaceutical and luxury goods segments are piloting dual-technology labels combining RFID inlays with serialized barcodes for omnichannel authentication. The national health regulator is implementing traceability requirements aligned with Saudi SFDA frameworks. Doha's logistics infrastructure supports rapid-turnaround supply for high-value product authentication labels.
GCC Labeling Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with multinational material science corporations commanding premium pressure-sensitive segments through specialized substrate formulations while regional converters compete on turnaround velocity and regulatory proximity. The market structure tilts toward consolidation at the substrate and adhesive layer, with fragmentation persisting in slitting, distribution, and short-run digital finishing. Three archetypes dominate: integrated material suppliers with captive resin and film production, regional converters leveraging free zone logistics for rapid replenishment, and pharmaceutical specialists with serialization-compliant infrastructure and cloud-based ERP integration. Competitive intensity centers on M&A activity targeting digital press capacity and strategic partnerships with pharmaceutical manufacturers facing compliance deadlines.
Among the integrated material suppliers, Avery Dennison Corporation exemplifies the premium substrate archetype through its Jeddah distribution hub and local slitting operations. CCL Industries Inc. occupies a position within the pharmaceutical-specialist tier, anchoring serialization-compliant capacity serving Saudi Arabia's regulatory environment. Sigma Middle East Label Industries LLC represents the regional converter archetype, sitting within Dubai's logistics free zones to sustain rapid-turnaround supply for FMCG brands.
| Leading Market Players |
|---|
| Huhtamaki OYJ |
| Avery Dennison Corporation |
| CCL Industries Inc. |
| Honeywell International Inc. |
| Brady Corporation |
| Mondi Group |
| Taghleef Industries Inc. |
| Sigma Middle East Label Industries LLC |
| 3M Company |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Saudi pharmaceutical manufacturers and European substrate suppliers lock in polypropylene film access while capping price volatility exposure across multi-year procurement horizons. These arrangements concentrate purchasing power among serialization-compliant converters serving SFDA-mandated track-and-trace requirements.
Pricing Analysis
The customization-premium spread in GCC labeling widens substantially between standard flexographic paper labels and digitally printed serialization-compliant film constructions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under Emirates Authority for Standardization and Metrology halal protocols and volume scale commitments from King Abdullah Economic City clusters. Cost compression in standard paper tiers is intensifying because petrochemical feedstock volatility squeezes converter margins on fixed-price annual contracts. Food and beverage processors demonstrate highest price sensitivity due to single-use disposal economics, while pharmaceutical manufacturers accept premium positioning for compliance-critical RFID-enabled architectures.
Supply Chain Analysis
Strategic stockpile preferences dominate pharmaceutical labeling workflows as SFDA serialization deadlines compel manufacturers to maintain buffer inventories of qualified European-sourced substrates. Geographic supply concentration centers on Germany, Italy, and China for specialized serialization films and tamper-evident adhesives. Raw material dependencies draw from regional polypropylene resin production, imported pressure-sensitive adhesives, and halal-certified ink formulations. Single-source vulnerability runs through European substrate qualification pathways that extend lead times for new converter entrants. Distribution runs through Jeddah and Dubai slitting hubs that serve Riyadh-Jeddah corridor and Dubai Industrial City manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC labeling demand follows cyclical recovery patterns tied to pharmaceutical serialization compliance waves, with Saudi Arabia and UAE regulatory deadlines creating concentrated investment windows for track-and-trace infrastructure.
For Market Incumbents: Secure serialization-compliant substrate partnerships ahead of Gulf Cooperation Council unified packaging standard implementation, locking in qualification pathways that emerging competitors cannot replicate within compliance deadlines. Defend margin position through backward integration into adhesive formulation and captive slitting capacity in Riyadh-Jeddah corridor logistics zones. Prioritize SAP ATTP and TraceLink cloud platform integration talent acquisition to address IT integration scarcity constraining pharmaceutical converter expansion. For New Entrants and Emerging Players: Differentiate on rapid-turnaround digital finishing capabilities targeting cosmetics and nutraceutical launches in Dubai's free zones where run lengths fragment below 10,000-unit thresholds. Target Kuwait and Oman import substitution opportunities where underdeveloped domestic manufacturing capacity creates supply gaps for Saudi and UAE converters with excess digital press capability. Pursue 48-hour replenishment contracts with FMCG brands in Dubai South and Jebel Ali logistics corridors as primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a compliance-driven investment phase that favors pharmaceutical-specialist converters with serialization infrastructure and cloud-based ERP integration capabilities. Long-term viability centers on acquisition of digital press capacity and regulatory proximity assets serving SFDA and MOHAP traceability mandates. Target acquisition profile encompasses regional converters with Jeddah or Dubai distribution hub positioning and existing halal certification qualification timelines. Watch for Gulf Cooperation Council technical regulation harmonization announcements as inflection indicator for cross-border supply consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Infrastructure Deployment | HP Indigo and Xeikon press investments enable SFDA-compliant 2D Data Matrix and RFID integration for pharmaceutical track-and-trace mandates. |
| Halal Certification Qualification | Emirates Authority for Standardization and Metrology protocol compliance unlocks food export label procurement from Saudi Arabia's King Abdullah Economic City clusters. |
| Free Zone Proximity Expansion | Dubai South and Jebel Ali adjacent slitting operations capture 48-hour replenishment contracts from FMCG brands with fragmented run lengths. |
| Backward Integration into Adhesive Formulation | In-house pressure-sensitive adhesive production reduces petrochemical feedstock volatility exposure and accelerates halal certification timelines. |
| Cloud-Based ERP Integration | SAP ATTP and TraceLink platform deployment addresses pharmaceutical manufacturer compliance requirements and filters non-specialized competitors. |
Research Methodology
The analysis maps pressure-sensitive labels, shrink sleeves, in-mold decorations, and digital printing technology segments, each validated through converter operations directors, pharmaceutical packaging procurement managers, and flexographic press technicians. Primary interviews with SFDA regulatory affairs specialists and Emirates Authority for Standardization and Metrology compliance officers combined with secondary validation from customs trade data, SEC filings of listed material suppliers, and Gulf Cooperation Council technical regulation databases. Bottom-up demand modeling from pharmaceutical, food processing, and cosmetics manufacturing clusters triangulated against top-down substrate consumption estimates from regional polypropylene resin distributors.
Consistency checks validated volume and value outputs against external benchmarks including installed digital press capacity disclosures and pharmaceutical serialization compliance deadline progressions across the analysis window. Segmentation dimensions encompassed label type, application, end user, and technology with regional regulatory cluster differentiation. CAGRs derived from trend extrapolation of digital printing adoption rates and pharmaceutical serialization infrastructure deployment curves, cross-referenced with expatriate technician availability constraints and petrochemical feedstock price trajectory assumptions.
Forecasts assume regulatory continuity in Saudi SFDA and UAE MOHAP traceability regimes; material policy shifts would require re-modeling of pharmaceutical label demand timing and digital press payback calculations. Revision becomes warranted when Gulf Cooperation Council unified packaging standard implementation timelines or visa policy nationalization quotas cross thresholds that alter converter capacity expansion feasibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Future-Proof Pharma Labels Market
Labels
Time Temperature Indicator Labels Market
Labels
Extended Text Labels Market
Labels
Oxygen Indicator Labels Market
Labels
Global Resealable Packaging Labels Market
Labels
Stand Alone Label Applicator Market
Labels
Wet Glue Labeling Machines Market
Labels
Wire Marking Labels Market
Labels
Freezer Label Market
Labels
Syringe Labels Market
Labels
Global Security Labels Market
Labels
High Gloss Labels Market
Labels
Multi-Part Labels Market
Labels
Roll-fed Wraparound Label Substrates Market
Labels
Domed Labels Market
Labels
United States Print Label Market