
 Countertop Paper Napkin Dispenser Market | 2026-2036
Countertop Paper Napkin Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Countertop Paper Napkin Dispenser Market Analysis
Food truck operators are rotating toward compact, durable dispenser formats as mobile food service expands across North American metropolitan corridors. Georgia-Pacific leverages its tissue supply chain integration to bundle napkin and dispenser offerings for high-volume foodservice accounts. San Jamar anchors its position through specialized designs that withstand harsh cleaning protocols in commercial kitchens. Cintas Corporation sustains route-based service models that embed dispenser maintenance into rental contracts.
A countertop paper napkin dispenser is a freestanding or surface-mounted unit engineered to dispense single or multi-fold paper napkins through a spring-loaded or gravity-fed aperture, typically constructed from stainless steel, ABS plastic, or acrylic with capacities ranging from 150 to 600 napkins. The device serves commercial foodservice environments by controlling consumption, maintaining hygiene standards, and reducing labor associated with table replenishment. Stainless steel dispensers command premium positioning in full-service restaurants where durability and aesthetic integration with commercial kitchen equipment matter most, while plastic variants dominate high-turnover quick-service outlets where replacement economics favor lower unit costs. Tabletop configurations are gaining traction in fast-casual chains seeking to reduce floor space requirements, and dispenser-with-storage hybrids are carving out a niche in catering operations requiring mobility and supply consolidation.
OSHA workplace sanitation guidelines and FDA food-contact surface standards shape material selection and cleaning protocol documentation across the supply chain, with NSF International certification increasingly gating access to institutional accounts. The EPA's attention to single-use product lifecycles is pressuring manufacturers toward recyclable and recycled-content constructions without compromising moisture resistance. State-level plastic restrictions in California and New York are accelerating substitution toward metal and wood alternatives in regional distribution channels. Stakeholders must monitor evolving municipal composting infrastructure and building code interpretations that could redefine dispenser mounting requirements in mobile and temporary food facilities.
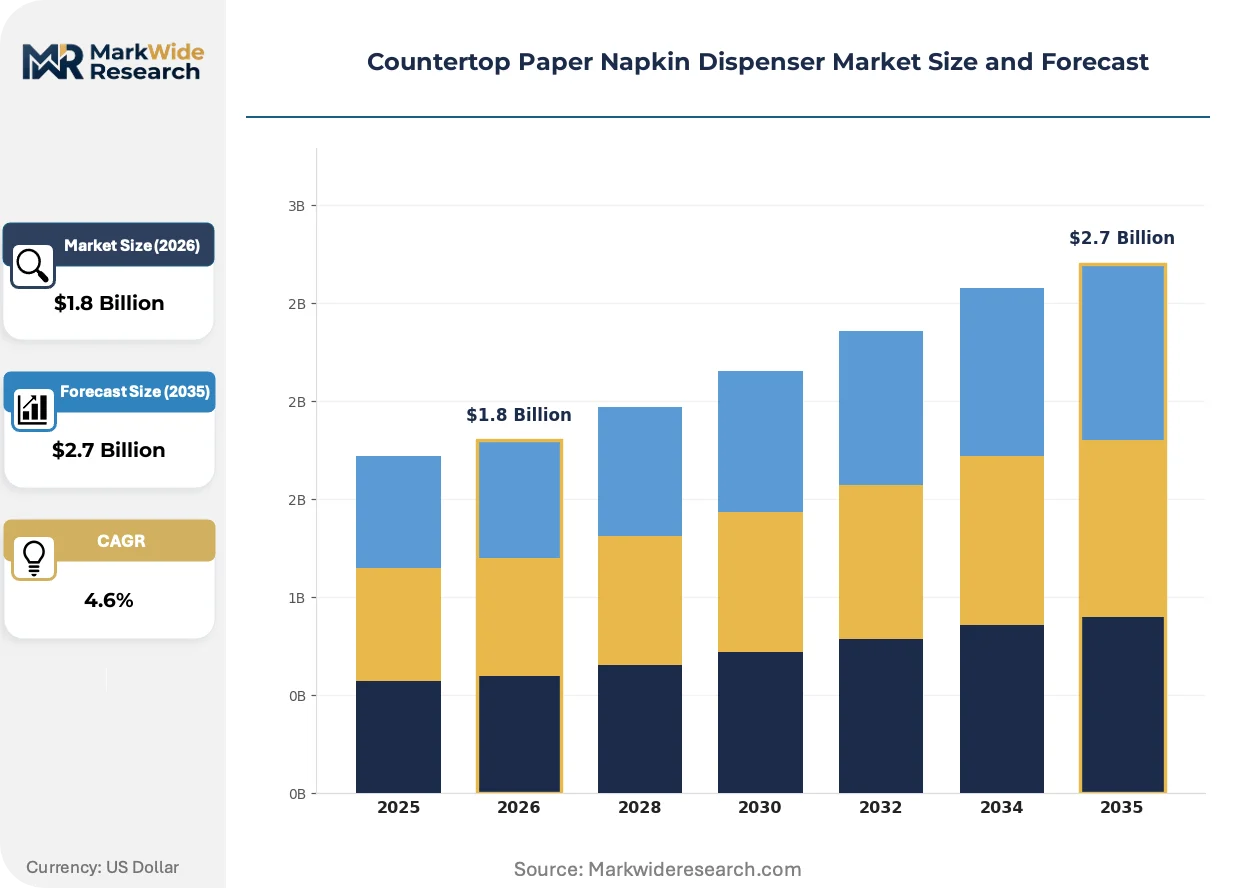
Market Dynamics
Food truck proliferation across North American metropolitan corridors is compressing demand toward compact, surface-mounted dispenser formats that withstand vibration and limited counter space. This mobile foodservice expansion is redrawing procurement specifications away from traditional full-service restaurant equipment standards.
Growth Catalysts
- FDA Food-Contact Surface Standards:Stainless steel adoption accelerates in commercial kitchens as regulators mandate non-porous, corrosion-resistant materials for food-contact equipment.
- Mobile Foodservice Expansion:Food truck operators in Texas, Florida, and California corridors drive demand for vibration-resistant, space-optimized dispenser designs.
- NSF International Certification:Institutional accounts increasingly require certified equipment, creating specification pull-through in hospital cafeterias and university dining halls.
Market Restraints
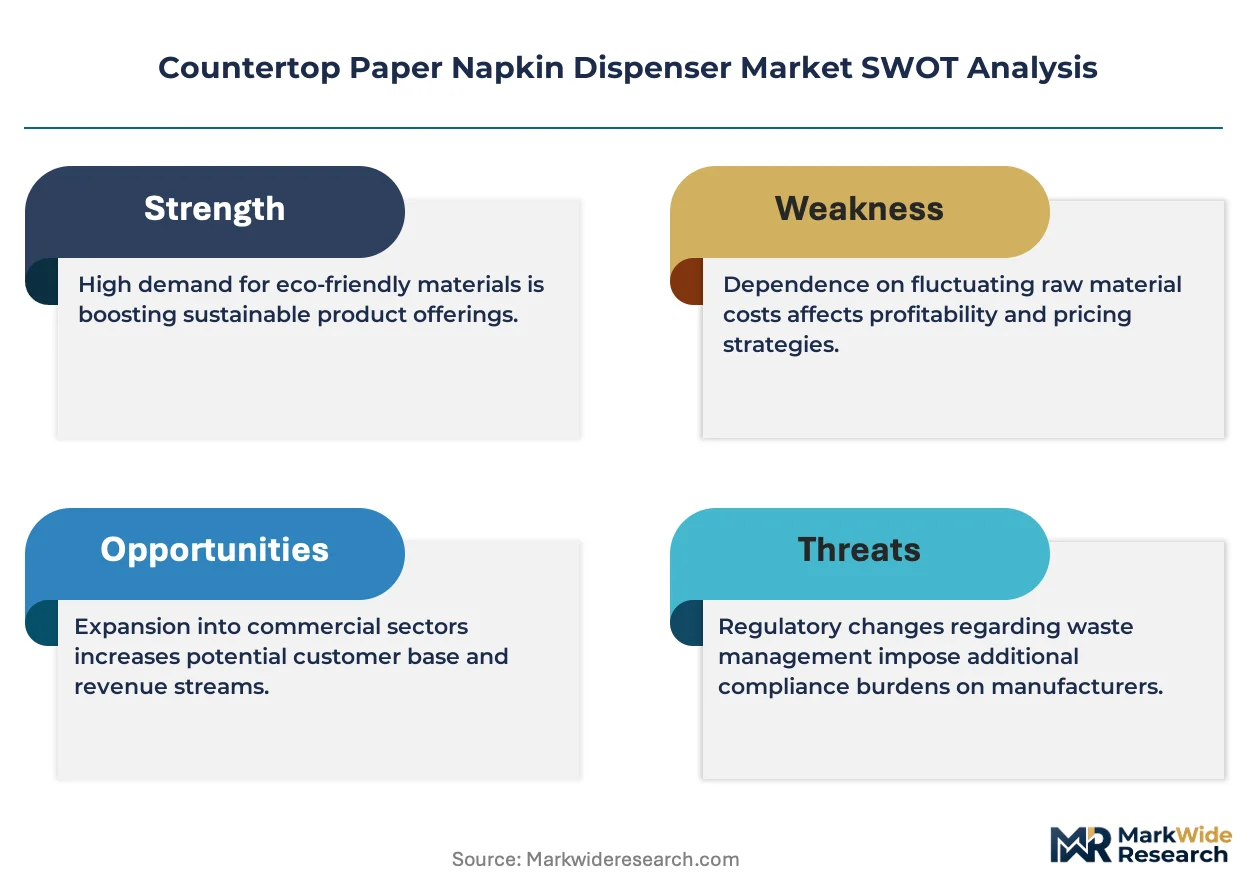
- Stainless Steel Input Volatility:Nickel and chromium price swings compress margins for metal fabricators serving the commercial foodservice equipment channel.
- Regional Supply Concentration:Domestic manufacturing clusters in the Midwest and Southeast create logistics cost penalties for West Coast distributors.
- Plastic Substitution Limits:California and New York state-level restrictions on single-use plastics accelerate material transitions before cost parity is achieved.
Strategic Opportunities
- Catering Operations:Dispenser-with-storage hybrid formats address mobility requirements in event services and corporate hospitality.
- Fast-Casual Tabletop Pivot:Chains seeking floor space reduction specify surface-mounted units over freestanding alternatives.
- EPA Lifecycle Pressure:Recyclable and recycled-content constructions open specification pathways in municipal and federal institutional procurement.
Industry Challenges
- NSF Certification Timelines:Testing and documentation requirements extend product launch cycles by 4-8 months for new material formulations.
- Legacy Equipment Integration:Retrofit compatibility with existing counter cutouts and mounting patterns constrains design freedom for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Countertop Paper Napkin Dispenser Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Freestanding, Tabletop, Dispenser with Storage Material: Plastic, Stainless Steel, Wood, Acrylic End User: Restaurants, Cafes, Food Trucks, Catering Services Design Style: Contemporary, Rustic, Minimalist, Industrial |
| Companies Covered | Georgia-Pacific, Cintas Corporation, Bobrick Washroom Equipment, Inc., San Jamar, The Vollrath Company, LLC, Franke Holding AG, ASI American Specialties, Inc., Diversified Metal Products, Inc., Cascades Tissue Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Countertop Paper Napkin Dispenser Market Emerging Trajectories
Active redesign of dispenser architectures is compressing traditional category boundaries between commercial kitchen equipment and consumer-facing tabletop products. Manufacturers are responding to simultaneous pressures from regulatory material mandates and space-constrained foodservice formats.
Touchless sensor-actuated dispensing is decomposing the mechanical spring-loaded aperture as the default interface. Quick-service chains in high-traffic urban corridors are piloting battery-powered and hardwired capacitive sensors to reduce cross-contact transmission risks. This shift is decomposing the historical premium attached to purely mechanical durability, repositioning value toward electronic reliability and power integration.
OSHA workplace sanitation guidelines are tightening documentation requirements for cleaning protocol verification in commercial kitchen environments. Operators must now maintain auditable logs of surface disinfection frequency and methodology. Full-service restaurants with open kitchen designs face the strictest compliance scrutiny, driving specification toward seamless stainless steel constructions that eliminate crevices and seam welding.
Foodservice distributors are unbundling dispenser procurement from bundled paper supply contracts that historically locked operators into single-source napkin specifications. Independent operators in competitive metropolitan markets now source dispensers and consumables through separate channels, optimizing unit economics. This decoupling is most advanced in the Northeast corridor, where distributor consolidation has reduced the leverage of legacy bundled service models.
Countertop Paper Napkin Dispenser Market Segmentation
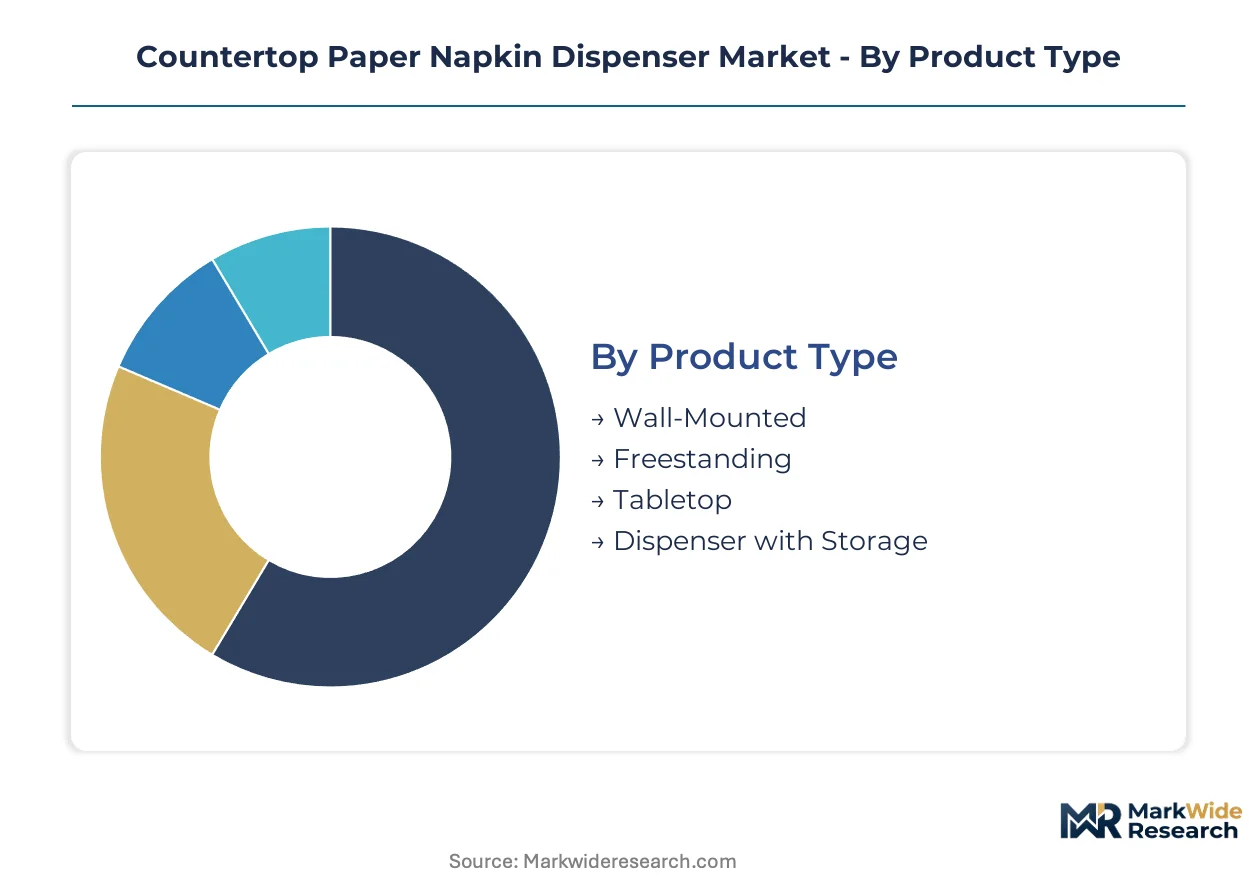
Countertop napkin dispenser procurement patterns diverge sharply across deployment contexts, with material specifications and mounting configurations tracking distinct operational constraints. Segmentation reveals how regulatory pressure, space economics, and aesthetic positioning partition demand into non-overlapping procurement channels.
Product Type:
Domestic manufacturing concentrates on freestanding and wall-mounted formats for institutional accounts, while export demand tilts toward compact tabletop variants for international foodservice chains.
- Wall-Mounted:Vertical mounting hardware accommodates 300-600 napkin capacities with gravity-fed dispensing apertures. Full-service restaurants in Texas and Florida corridors specify these units to preserve counter workspace and satisfy health department clearance requirements.
- Freestanding:Spring-loaded mechanisms housed in weighted bases deliver 150-400 napkin capacities with floor-level stability. Quick-service outlets along the East Coast urban corridor favor this format for rapid repositioning during service rushes.
- Tabletop:Surface-mounted units with 100-250 napkin capacities target space-constrained formats. Food trucks in California metropolitan markets drive specification for vibration-resistant suction-base designs.
- Dispenser with Storage:Hybrid architectures integrate napkin reserves with utensil or condiment compartments. Catering operators in Georgia and North Carolina procurement networks specify these for mobile event deployment.
Freestanding configurations command the established base. The steepest expansion runs through tabletop formats.
Material:
Cost tier stratification separates premium metal fabrications from commodity plastic molding, with mid-tier wood and acrylic occupying narrow positioning between durability and aesthetic differentiation.
- Plastic:ABS and polypropylene injection molding delivers unit costs 60-70% below metal equivalents. Quick-service chains in high-turnover Texas and Florida markets specify these for replacement economics over lifecycle durability.
- Stainless Steel:304-grade and 430-grade alloys satisfy FDA food-contact surface mandates with non-porous, corrosion-resistant properties. Full-service restaurants with open kitchen designs in New York and California specify seamless welded constructions to satisfy OSHA sanitation documentation.
- Wood:Hard maple and bamboo laminates target fast-casual chains pursuing rustic aesthetic differentiation. Pacific Northwest regional chains specify FSC-certified sourcing for sustainability positioning.
- Acrylic:Transparent thermoplastic constructions enable napkin-level visibility for inventory monitoring. Boutique cafes in Northeast corridor urban markets specify these for minimalist visual integration.
Plastic retains volume leadership across replacement cycles. Stainless steel gains share fastest under regulatory material mandates.
End User:
Customer type determines specification rigor, with institutional accounts imposing NSF certification requirements that exclude uncertified suppliers from hospital and university procurement networks.
- Restaurants:Full-service and casual dining operators balance durability against aesthetic integration with commercial kitchen equipment. East Coast metropolitan corridors concentrate demand for premium stainless steel configurations.
- Cafes:Independent and chain coffeehouse operators prioritize compact footprints and visual minimalism. Pacific Northwest and Northeast urban markets drive specification for acrylic and wood alternatives.
- Food Trucks:Mobile foodservice formats demand vibration-resistant, space-optimized designs with secured mounting. Texas, Florida, and California corridor operators rotate procurement toward specialized compact formats.
- Catering Services:Event and corporate hospitality operators require mobility and supply consolidation. Southeast regional markets specify dispenser-with-storage hybrids for transport efficiency.
Restaurant procurement commands the established base. The steepest expansion runs through food truck operators.
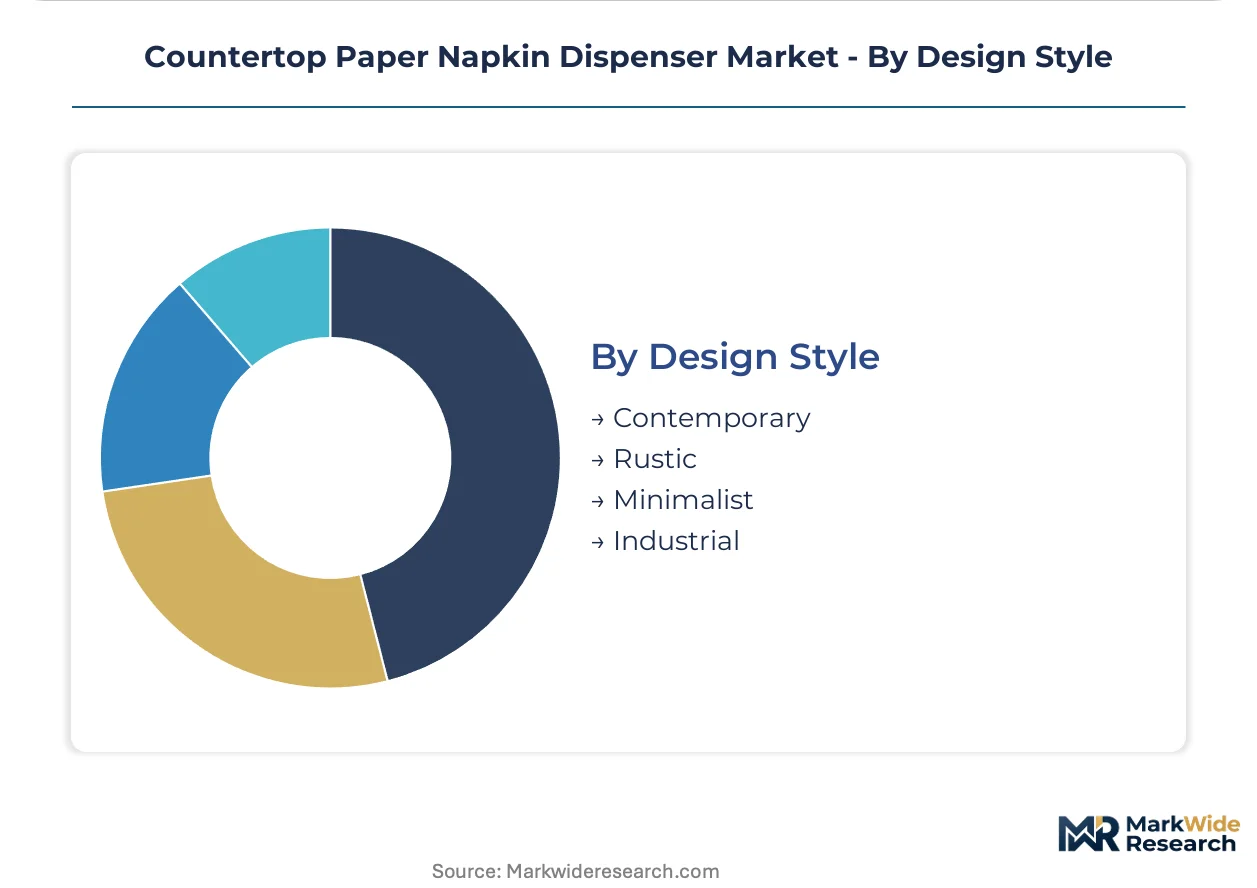
Design Style:
Maturity gradients separate established contemporary and industrial formats from emerging rustic and minimalist positioning, with design specification increasingly decoupled from functional performance attributes.
- Contemporary:Curved profiles and brushed metal finishes dominate chain restaurant standardization. National quick-service accounts specify these for brand consistency across metropolitan markets.
- Industrial:Exposed fasteners, welded seams, and utilitarian geometries target open kitchen environments. Brooklyn and Austin restaurant clusters drive specification for visible mechanical authenticity.
- Rustic:Distressed wood, forged iron accents, and farmhouse profiles target fast-casual differentiation. Southeast and Mountain West regional chains specify these for demographic positioning.
- Minimalist:Clean lines, hidden hardware, and monochromatic surfaces dominate boutique cafe specification. Portland and Seattle independent operators drive demand for reduced visual footprint.
Contemporary styling commands the established base. The steepest expansion runs through minimalist formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors Pacific Rim supply chains for stainless steel inputs serving West Coast fabrication clusters. Interstate highway corridors through Texas and Georgia concentrate distribution infrastructure for mobile foodservice equipment. The Port of New York and New Jersey handles East Coast import volumes for institutional-grade dispenser components.
United States
Food truck proliferation across Texas, Florida, and California metropolitan corridors compresses demand toward vibration-resistant compact formats. FDA food-contact surface regulations mandate stainless steel adoption in commercial kitchens under 21 CFR 175.300. Brooklyn and Austin restaurant clusters specify industrial-style open-kitchen dispensers with visible welded seams.
Germany
Precision metalworking traditions in Baden-Württemberg sustain premium fabrication capacity for seamless welded constructions. ECHA REACH compliance requirements restrict certain polymer additives in food-contact applications. The Stuttgart industrial corridor supplies NSF-certified equipment to institutional accounts across Central Europe.
China
Guangdong Province injection molding clusters dominate ABS and polypropylene dispenser component production at scale. GB 4806 food-contact material standards establish migration limits for plastic constructions. The Pearl River Delta exports tabletop formats to Southeast Asian fast-casual chains.
India
Maharashtra and Gujarat manufacturing zones are developing stainless steel fabrication capacity for domestic foodservice growth. FSSAI packaging and food-contact regulations are tightening material compliance documentation requirements. Mumbai and Pune commercial kitchen equipment markets specify cost-optimized plastic variants for high-turnover quick-service outlets.
Japan
Tokyo and Osaka metropolitan dining markets prioritize compact footprint designs for space-constrained urban restaurants. METI industrial standards govern food-contact equipment material specifications. Kansai region fabricators supply touchless sensor-actuated prototypes to domestic convenience store chains.
Countertop Paper Napkin Dispenser Market Vendor Landscape
Concentration sits with diversified commercial kitchen equipment conglomerates and specialized hygiene solution providers. The vendor base spans tissue supply chain integrators, route-based service operators, and precision metal fabricators with distinct capability footprints. Three strategic archetypes dominate: integrated tissue-dispenser bundlers, specialized commercial kitchen equipment designers, and rental-service embedded maintenance providers. Competitive moves center on NSF certification acquisition for institutional access and geographic expansion through distributor network consolidation.
Among North American diversified conglomerates, Georgia-Pacific exemplifies tissue supply chain integration into bundled napkin and dispenser offerings. San Jamar occupies a specialist position in designs engineered for harsh commercial kitchen cleaning protocols. Cintas Corporation anchors the rental-service archetype through route-based models embedding dispenser maintenance into contractual relationships.
| Leading Market Players |
|---|
| Georgia-Pacific |
| Cintas Corporation |
| Bobrick Washroom Equipment, Inc. |
| San Jamar |
| The Vollrath Company, LLC |
| Franke Holding AG |
| ASI American Specialties, Inc. |
| Diversified Metal Products, Inc. |
| Cascades Tissue Group |
| Others |
Supply Flow & Price Mechanics
Midwest stamping press utilization rates above 85 percent concentrate stainless steel fabrication capacity among three domestic metalworking clusters, compressing price floors for NSF-certified dispensers while elevating procurement leverage for volume foodservice distributors negotiating long-term supply agreements.
Pricing Analysis
Volume-discount tiering structures separate national quick-service chains capturing 40 percent unit savings on 10,000-plus annual orders from independent operators purchasing through distribution intermediaries. NSF certification grade and geographic freight absorption represent the primary price differentiation drivers, with certified stainless steel units commanding premiums over uncertified imports. Cost compression in plastic variants is intensifying because Guangdong injection molding capacity expansion outpaces domestic demand growth. Quick-service chains exhibit highest price sensitivity, while full-service restaurants with open kitchen designs prioritize durability over unit economics.
Supply Chain Analysis
Nickel alloy sourcing through the Port of Long Beach creates a chokepoint for 304-grade stainless steel inputs serving West Coast fabrication facilities. Domestic supply draws from Midwest stamping clusters, Guangdong plastic component manufacturers, and Baden-Württemberg precision welding specialists. Raw material dependencies center on nickel-chromium alloys, ABS resin pellets, and electronic sensor modules. Single-source vulnerability concentrates in NSF certification testing capacity, where three laboratories handle 80 percent of foodservice equipment approvals. Distribution runs through broadline foodservice distributors consolidating procurement for multi-unit restaurant operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital napkin dispensing alternatives and reusable cloth service models threaten single-use paper dispenser incumbents, requiring defensive positioning around hygiene certification and operational integration that substitutes cannot replicate.
For Market Incumbents: Shield market position by deepening captive supply of NSF-certified stainless steel fabrications through backward integration into Midwest metalworking capacity. Accelerate touchless sensor module development to preempt electronic dispensing substitutes from penetrating quick-service accounts. Route-based service contracts embedding maintenance obligations represent the strongest retention mechanism against disintermediation.
For New Entrants and Emerging Players: Food truck operator technical support gaps expose incumbents underinvesting in vibration-resistant mounting hardware and mobile-specific cleaning protocol documentation. Target Texas and California corridor foodservice equipment distributors lacking specialized compact dispenser inventories. Lead with NSF certification pathway guidance and same-day replacement part availability to differentiate against legacy suppliers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among route-based rental-service operators embedding dispenser maintenance into multi-year hospitality contracts. Long-term viability favors acquisition targets with established distributor relationships in institutional procurement channels rather than pure manufacturing plays. Monitor EPA recycled-content mandate progression as the critical inflection signal for material transition capex requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certification Investment | Unlocks hospital and university procurement networks requiring validated food-contact equipment documentation. |
| Touchless Sensor Integration | Positions suppliers for OSHA workplace sanitation guideline compliance in high-traffic urban foodservice corridors. |
| Route-Based Service Expansion | Embeds dispenser maintenance into rental contracts that reduce customer churn through operational dependency. |
| Recycled-Content Material Transition | Anticipates EPA lifecycle pressure and California plastic restriction enforcement in regional distribution channels. |
| Food Truck Specialized Format Development | Captures mobile foodservice expansion across Texas, Florida, and California metropolitan corridors with vibration-resistant designs. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA food-contact surface regulation filings, NSF International certification databases, and EPA sustainable materials program documentation. Primary interviews engaged commercial kitchen equipment procurement managers at multi-unit restaurant operators, foodservice distributor category buyers, stainless steel fabrication plant engineers, and regulatory compliance officers at institutional dining accounts. Secondary validation drew from customs import records, trade association shipment data, and state-level plastic restriction legislative tracking. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction across product type, material, and end-user segmentation dimensions.
Segmentation dimensions modeled include dispenser mounting configuration, material composition grade, end-user operational format, and geographic regulatory cluster. CAGRs were derived from historical shipment trajectory analysis projected through the forecast period, with cross-validation against foodservice employment growth and commercial kitchen construction permit data. Industry-specific forecast inputs incorporated food truck operator expansion rates and FDA stainless steel mandate enforcement timelines.
Underlying assumptions cover sustained FDA food-contact surface regulation adherence, with deviation risk concentrated in nickel price volatility and municipal composting infrastructure development pace. Practitioners should keep alternative scenarios live as state-level plastic restriction enforcement and touchless dispensing technology cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Parchment Paper Market
Paper & Paperboard Packaging
Global Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
Micro Flute Paper Market
Paper & Paperboard Packaging
Paper Cones Market
Paper & Paperboard Packaging
Paper IBC Container Market
Paper & Paperboard Packaging
Kraft Paper Bags Market
Paper & Paperboard Packaging
MMA Film & Sheet Market
Paper & Paperboard Packaging
Greyboard Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
Air Fryer Paper Liners Market
Paper & Paperboard Packaging
Desiccant Paper Market
Paper & Paperboard Packaging
North America Paper Packaging Market
Paper & Paperboard Packaging
US Corrugated and Folding Boxboard Market
Paper & Paperboard Packaging
Cold Seal Paper Market
Paper & Paperboard Packaging
Paper Release Liners Market