
 Parchment Paper Market | 2026-2036
Parchment Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Parchment Paper Market Outlook
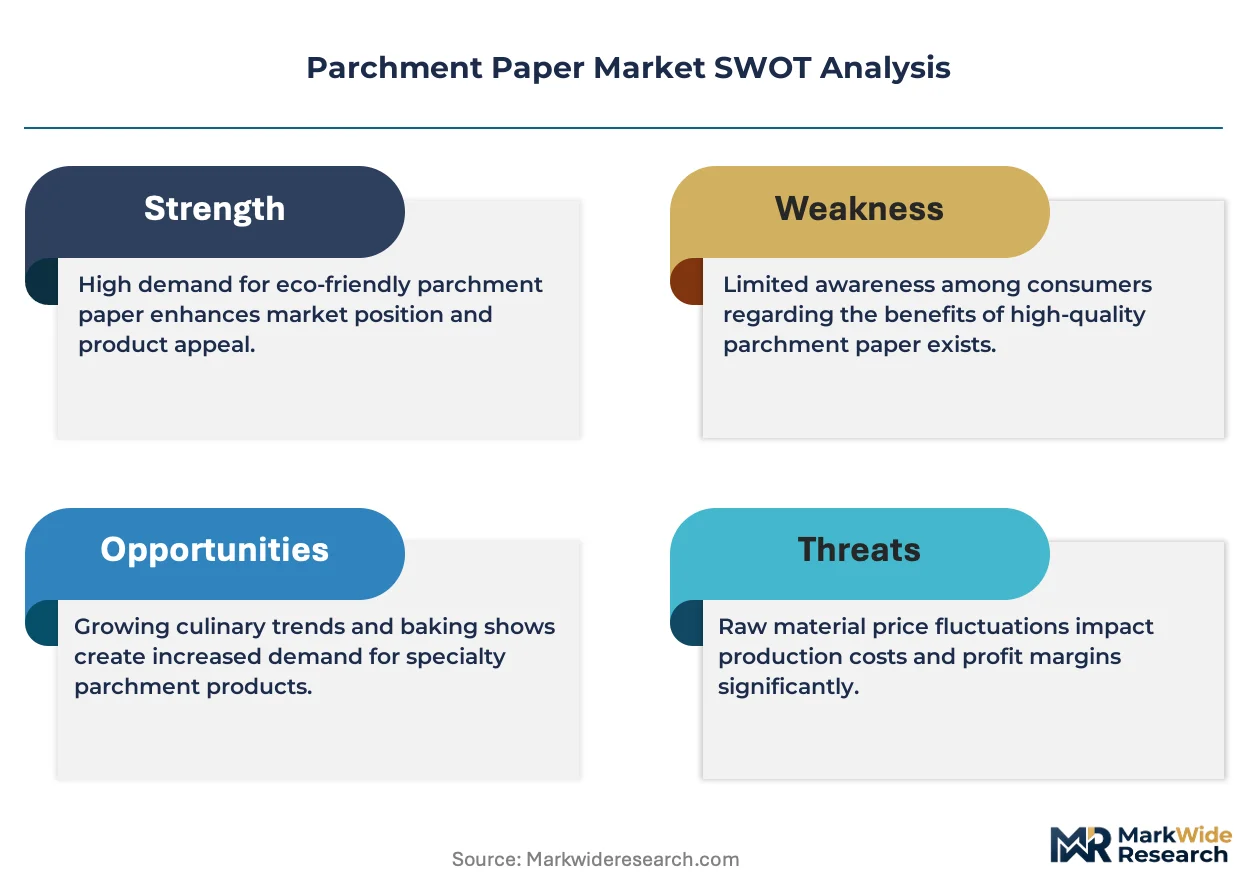
The EU Green Deal is shifting procurement criteria across European food packaging supply chains, compelling converters to certify products against compostability benchmarks. Mondi Group leverages integrated pulp-to-paper operations to secure fiber traceability for premium baking paper grades. Nordic Paper anchors its competitive position through specialized greaseproof manufacturing at Swedish mills with certified renewable energy inputs. Ahlstrom-Munksjö differentiates via R&D intensity in fluorochemical-free barrier coatings for industrial end users.
Parchment paper is a cellulose-based sheet, typically 40–60 gsm, rendered non-stick through silicone or quilon coating and resistant to temperatures exceeding 220°C; its primary commercial purpose is to prevent food adhesion during baking while enabling clean release without additional fats. Baking paper occupies the largest volume share among product types due to universal household and food service penetration, while greaseproof paper captures concentrated margin pools in industrial confectionery and chocolate molding where oil resistance specifications are stringent. The heavyweight thickness segment sustains above-average growth as commercial bakeries automate high-throughput lines requiring dimensional stability under mechanical stress.
The EU F-Gas Regulation and REACH compliance frameworks govern silicone coating chemistries and restrict perfluorinated substances in food-contact materials, directly elevating R&D costs for European producers while creating market access barriers for uncertified imports. The US FDA maintains separate food-contact notification requirements that shape export documentation burdens for Asian manufacturers targeting North American buyers. Stakeholders must monitor evolving compostability certification schemes across multiple jurisdictions to anticipate which coating platforms will retain commercial viability.
Market Dynamics
The EU Green Deal's packaging waste directives are compressing silicone-coated parchment volumes while accelerating converter investment in compostable barrier chemistries and certified renewable fiber sourcing.
Growth Catalysts
- Industrial bakery automation:High-throughput lines in Germany and France require precision-release papers that withstand mechanical stress above 200°C without tearing or curling.
- EU F-Gas Regulation:Restrictions on fluorinated coating precursors are pulling converters toward quilon and plant-based silicone alternatives that maintain food-contact compliance.
- Compostability certification:DIN CERTCO and TÜV Austria OK compost HOME labels are opening institutional procurement channels for certified greaseproof grades in Nordic institutional food service.
Market Restraints
- Pulp cost volatility:Bleached kraft pulp prices swing with Nordic and Brazilian softwood supply disruptions, squeezing converter margins on standard baking paper grades.
- Coating chemical concentration:Silicone emulsion supply clusters in Germany and the US Midwest, creating single-source vulnerability for European converters lacking backward integration.
- Perfluorinated substance legacy:Residual PFAS contamination in recycled fiber streams blocks circular economy claims and triggers REACH enforcement actions.
Strategic Opportunities
- Swiss precision confectionery:Chocolate molding and praline production demand ultra-smooth greaseproof surfaces that command 40-60% price premiums over standard baking grades.
- Digital print compatibility:Inkjet-ready barrier coatings enable short-run branded parchment for artisan bakeries and direct-to-consumer meal kits.
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets by 2030 will disqualify multi-layer laminates, expanding addressable market for single-material cellulose solutions.
Industry Challenges
- Fluorochemical-free R&D timelines:Reformulating oil-repellent coatings without PFAS or heavy quilon metal complexes requires 18-24 month validation cycles against EFSA migration limits.
- Renewable energy certification:Mass balance accounting for Scope 3 emissions in pulp sourcing demands specialized sustainability audit capabilities most mid-tier converters lack in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parchment Paper Market |
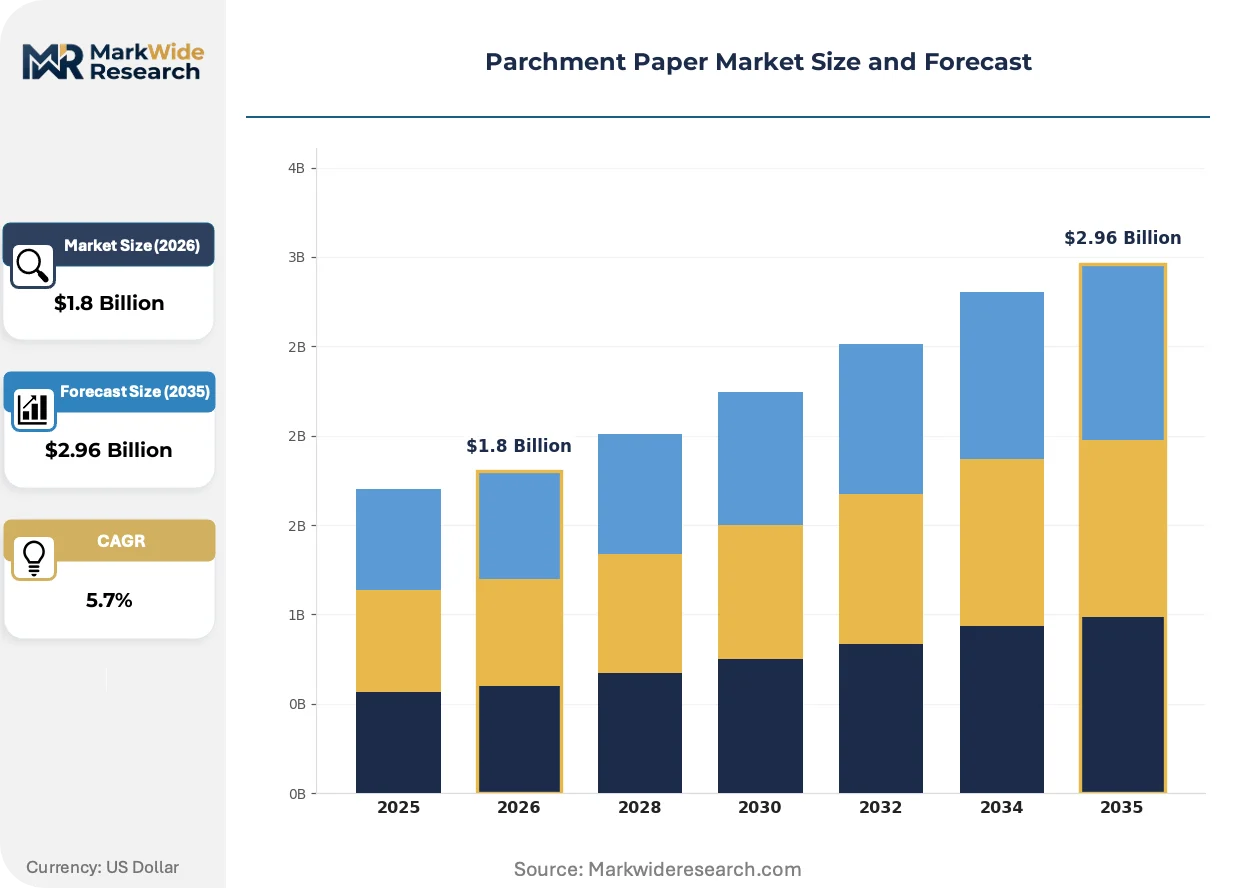
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baking Paper, Cooking Paper, Wrapping Paper, Greaseproof Paper Thickness: Lightweight, Medium Weight, Heavyweight, Extra Heavyweight End User: Household, Food Service, Bakery, Industrial Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Mondi Group, Delfort Group, Georgia-Pacific, Pudumjee Paper Products, JK Paper, Ahlstrom-Munksjö, Reynolds Consumer Products, International Paper Company, Nordic Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parchment Paper Market Strategic Shifts
Coating chemistry substitution and fiber traceability systems are restructuring how parchment paper is specified, priced, and procured across European food manufacturing.
Plasma-enhanced barrier deposition is electrifying the competitive landscape for premium greaseproof grades. This dry-process technology deposits nanometer-scale ceramic layers onto cellulose substrates without liquid silicone baths. Industrial chocolate manufacturers in Belgium and Switzerland are piloting these papers for high-definition mold release. The technology is electrifying R&D allocation away from conventional emulsion coating lines toward capital-intensive vacuum deposition equipment.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing coating reformulation across European converter facilities. The 2023 PFAS restriction proposal covers over 10,000 substances, eliminating long-chain fluorochemicals from food-contact papers entirely. German industrial bakers now require written PFAS-free declarations from suppliers, shifting specification power toward integrated pulp-to-paper producers with in-house analytical capabilities.
Direct mill-to-bakery procurement contracts are displacing traditional distributor intermediaries in Northern European markets. Large industrial bakery groups in Denmark and the Netherlands now negotiate annual volume agreements with Nordic Paper and Mondi Group directly, bypassing regional paper merchants. This consolidation concentrates pricing leverage among buyers with certified renewable energy requirements and consolidated SKU portfolios.
Parchment Paper Market Segmentation
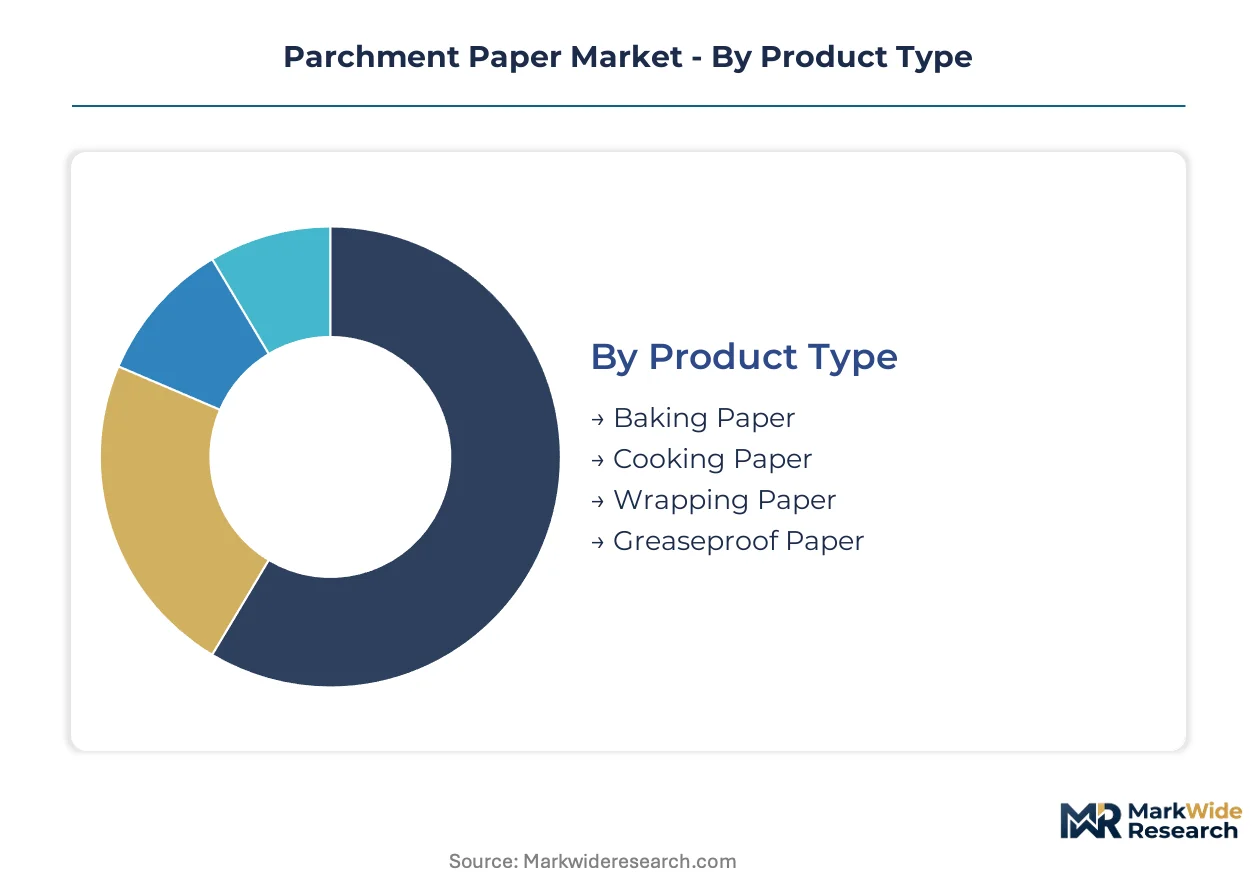
Parchment paper procurement splits sharply between commodity-grade household rolls and specification-driven industrial contracts. Coating chemistry, thickness calibration, and release performance separate price tiers more than brand identity. Understanding these fault lines exposes where margin pools concentrate and where volume commoditization threatens returns.
Product Type:
Volume dominance sits with universal baking applications, while premium extraction concentrates in specialized greaseproof formulations for precision manufacturing.
- Baking Paper:Silicone or quilon-coated cellulose sheets rated for sustained temperatures above 220°C serve household ovens and commercial bakeries alike. German industrial bakeries now specify certified PFAS-free grades under REACH Annex XVII pressure, compressing volumes for legacy silicone-coated imports while expanding addressable market for quilon alternatives.
- Greaseproof Paper:Dense, uncoated or lightly treated cellulose engineered for oil resistance without release coatings commands 40-60% price premiums in Swiss chocolate molding and Belgian praline production. Swissmedic food-contact compliance and EFSA migration limit certifications gate entry for uncertified converters.
- Cooking Paper:Shorter-dimension sheets optimized for stovetop steaming and en papillote preparations occupy mid-tier pricing between commodity baking rolls and industrial greaseproof grades.
- Wrapping Paper:Uncoated or minimally treated sheets for sandwich and deli packaging face accelerating substitution from compostable bio-films under EU Packaging and Packaging Waste Regulation recyclability mandates.
Today's leader: Baking Paper. Tomorrow's challenger: Greaseproof Paper.
Thickness:
Mechanical stress tolerance and dimensional stability under thermal load separate industrial specifications from consumer-grade convenience.
- Heavyweight:50-60 gsm construction withstands automated high-throughput line tension in French and German industrial bakeries without tearing or edge curling. Robotic handling systems and continuous belt ovens impose minimum stiffness thresholds that lightweight grades fail.
- Lightweight:35-45 gsm rolls dominate household retail channels where cost-per-meter sensitivity outweighs durability requirements. Nordic supermarkets now stock DIN CERTCO-certified compostable lightweight grades for home bakers seeking OK compost HOME labeling.
- Medium Weight:45-50 gsm bridges artisan bakery and small commercial kitchen demand, balancing release performance against per-unit cost constraints.
- Extra Heavyweight:60+ gsm specialty grades for extreme temperature applications and repeated reuse cycles in professional confectionery tempering command niche premium positioning.
Heavyweight specifications are climbing fastest as automation spreads; Lightweight retains volume dominance in retail.
End User:
Procurement sophistication and specification power concentrate in industrial bakery groups, while fragmented household demand sustains commodity throughput.
- Industrial:Large-scale confectionery manufacturers and automated bakery groups negotiate direct mill contracts with Nordic Paper and Mondi Group, bypassing distributors to secure certified renewable energy documentation and PFAS-free declarations. Danish industrial bakery consolidation has compressed supplier counts to three approved vendors per production site.
- Food Service:Institutional caterers and restaurant chains in the Netherlands now require TÜV Austria OK compost HOME certification for greaseproof grades used in pre-portioned meal assembly.
- Bakery:Independent artisan bakers and small commercial operations purchase through specialty paper merchants, mixing standard baking paper with short-run digitally printed branded parchment for customer-facing presentation.
- Household:Supermarket and online retail channels move standardized roll formats with minimal differentiation beyond price positioning and occasional seasonal branding.
Industrial buyers wield pricing leverage through consolidated volumes; Food Service channels are gaining specification influence via compostability mandates.
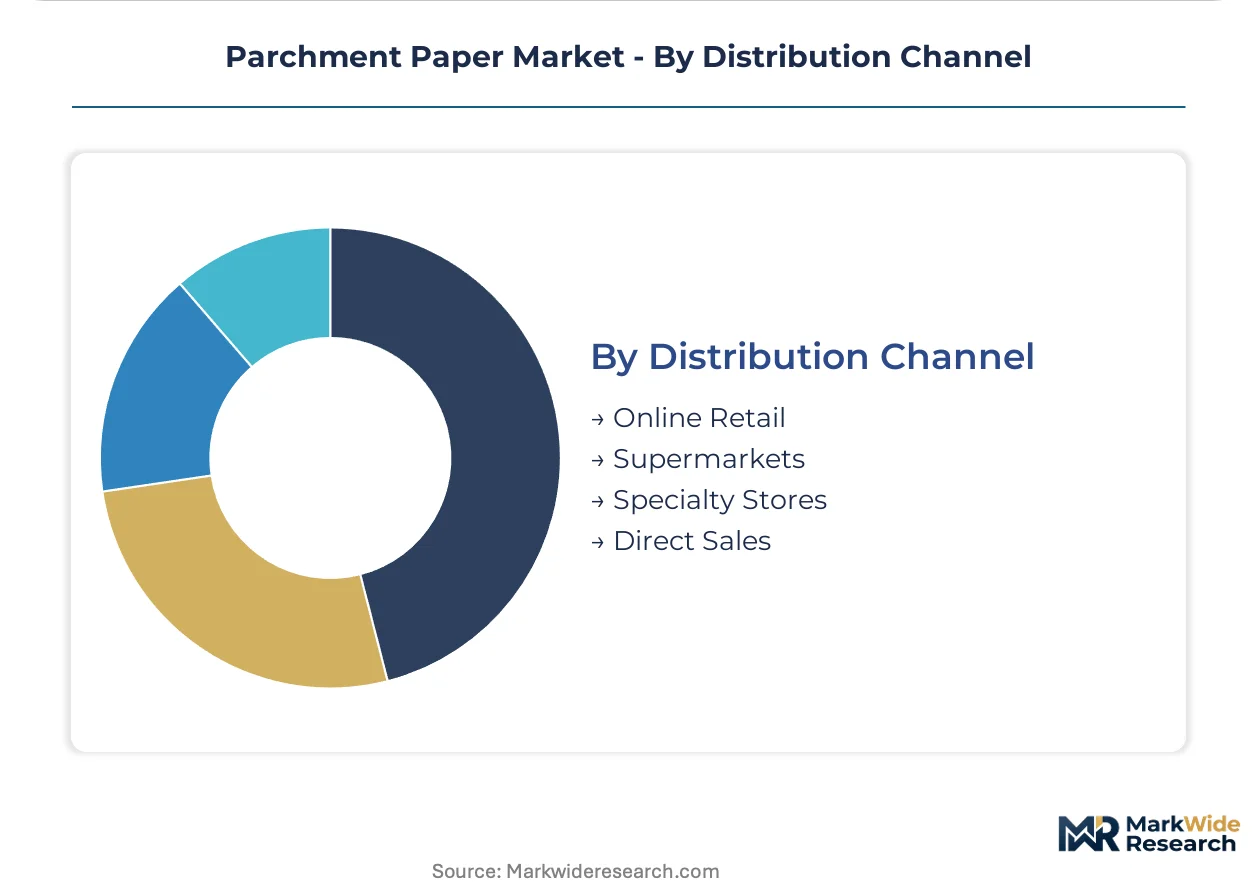
Distribution Channel:
Channel structure reflects buyer scale and technical support requirements, with direct procurement displacing intermediaries for large accounts.
- Direct Sales:Annual volume agreements between Nordic industrial bakery groups and integrated pulp-to-paper producers concentrate pricing power among buyers with renewable energy certification requirements and consolidated SKU portfolios. Mass balance accounting for Scope 3 emissions demands specialized sustainability audit capabilities that direct relationships facilitate.
- Online Retail:E-commerce platforms serve fragmented household demand and small artisan bakeries seeking specialty grades unavailable through mass retail, with inkjet-ready barrier coatings enabling short-run branded parchment for direct-to-consumer meal kit producers.
- Supermarkets:Mass retail channels move lightweight and medium-weight baking paper in standardized roll counts, with private-label penetration highest in Germany and lowest in Switzerland.
- Specialty Stores:Restaurant supply and bakery equipment distributors maintain inventory of heavyweight industrial grades and greaseproof specifications for customers lacking direct mill access.
Direct Sales commands margin retention for producers; Online Retail is expanding fastest as digital procurement penetrates mid-tier food service accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parchment paper production originated in European specialty paper mills during the 19th century, with Nordic and Alpine regions developing the bleached kraft and greaseproof expertise that underpins today's industrial standards. Modern demand patterns reflect this heritage while incorporating automation-driven specifications from industrial baking clusters worldwide.
Germany
Industrial bakery automation in Bavaria and North Rhine-Westphalia drives specification-heavy procurement of heavyweight greaseproof grades. The EU F-Gas Regulation and REACH Annex XVII compliance requirements force converters to source PFAS-free coating chemistries. The Stuttgart precision confectionery corridor demands Swissmedic-certified papers for chocolate molding applications.
United States
Food service chains and institutional caterers in the Midwest and Southeast generate volume demand for compostable baking paper formats. FDA food-contact notification requirements create documentation barriers for uncertified imports. Georgia-Pacific and International Paper anchor domestic supply from Southern pulp mills with integrated coating operations.
Sweden
Renewable energy-certified mills in Värmland and Västernorrland supply premium greaseproof grades to Nordic institutional food service. DIN CERTCO and TÜV Austria OK compost HOME certifications gate entry to Danish and Dutch procurement channels. Nordic Paper's specialized manufacturing concentrates in this region.
Switzerland
Chocolate manufacturers in Vevey and Buchs command 40-60% price premiums for ultra-smooth greaseproof surfaces in praline production. Swissmedic food-contact compliance and EFSA migration limit certifications exclude uncertified competitors. The country's precision confectionery sector sets performance benchmarks adopted across Alpine Europe.
India
JK Paper and Pudumjee Paper Products serve domestic bakery and food service expansion from Maharashtra and West Bengal manufacturing bases. FSSAI food-contact material regulations govern silicone coating approvals for local production. Mumbai and Bangalore industrial bakery clusters are adopting European-style automation specifications.
Parchment Paper Market Competitive Environment
Capital-heavy integrated pulp-to-paper producers compete with asset-light specialty converters for specification influence in procurement channels. The market structure concentrates around Nordic and Central European mill operators with captive fiber supply, while Asian and North American players compete on volume throughput for standardized grades. Three archetypes dominate: integrated forest products groups with traceable fiber chains, specialty paper converters with coating expertise, and diversified packaging conglomerates with food service distribution access. Competitive moves center on backward integration into renewable energy-certified pulp sourcing and direct mill-to-bakery procurement contracts that displace distributor intermediaries.
Among integrated European producers, Mondi Group exemplifies the fiber-traceability archetype through its pulp-to-paper operations, while Nordic Paper anchors the specialized greaseproof manufacturing position from Swedish mill assets. Ahlstrom-Munksjö occupies the R&D-intensive tier focused on fluorochemical-free barrier coatings. These three represent distinct competitive vectors—traceability, specialization, and innovation—that structure procurement segmentation across industrial bakery and precision confectionery end users.
| Leading Market Players |
|---|
| Mondi Group |
| Delfort Group |
| Georgia-Pacific |
| Pudumjee Paper Products |
| JK Paper |
| Ahlstrom-Munksjö |
| Reynolds Consumer Products |
| International Paper Company |
| Nordic Paper |
| Others |
Value Chain & Pricing Dynamics
Plasma-enhanced barrier deposition technology is simultaneously elevating capital requirements for premium greaseproof grades and concentrating supply among integrated pulp-to-paper producers with vacuum deposition capabilities. This dry-process coating method pulls R&D investment away from conventional silicone emulsion lines, reshaping which converters can compete for Swiss chocolate molding and Belgian praline specifications.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs parchment paper procurement, with PFAS-free certification and renewable energy documentation commanding 40-60% premiums in industrial segments. Price differentiation rests on coating chemistry validation and fiber traceability systems rather than brand equity. Cost compression in standard baking grades intensifies as Asian imports pressure European converter margins, while household retail channels exhibit highest price sensitivity and precision confectionery buyers show lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from German industrial bakery groups now mandate qualified suppliers in Sweden, Finland, and Germany to mitigate single-source vulnerability during Nordic pulp disruptions. Raw material dependencies center on bleached kraft pulp, silicone emulsion chemistries, and quilon metal complexes. Distribution runs through direct mill-to-bakery contracts for large accounts, with specialty merchants serving fragmented artisan segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The parchment paper market reads as a late-cycle quality story where automation-driven specifications and REACH Annex XVII compliance are concentrating procurement power among certified producers. Demand is pivoting toward PFAS-free greaseproof grades that command sustained margin premiums.
For Market Incumbents: Anticipate plasma-enhanced barrier deposition technology obsoleting conventional coating lines by securing vacuum deposition equipment partnerships or licensing arrangements. Prioritize backward integration into renewable energy-certified pulp sourcing to defend specification influence against integrated competitors with captive fiber supply.
For New Entrants and Emerging Players: E-commerce platforms serving artisan bakeries and direct-to-consumer meal kit producers represent the most penetrable channel, bypassing distributor intermediaries that incumbents dominate. Target inkjet-ready barrier coating formulations for short-run branded parchment, leveraging digital print compatibility as a wedge against mass-market rolls.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier specialty converters lacking in-house PFAS analytical capabilities or renewable energy certification infrastructure. The long-term viability window favors integrated pulp-to-paper producers with traceable fiber chains. Watch for DIN CERTCO and TÜV Austria OK compost HOME certification mandates expanding beyond Nordic institutional food service as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Coating Reformulation | REACH Annex XVII compliance opens German industrial bakery procurement to certified converters. |
| Renewable Energy Certification | Mass balance accounting for Scope 3 emissions secures direct contracts with Danish bakery groups. |
| Plasma Barrier Deposition Investment | Vacuum deposition equipment access qualifies producers for Swiss chocolate molding specifications. |
| Direct Mill-to-Bakery Contracts | Bypassing distributors concentrates pricing leverage among large industrial buyers. |
| Compostability Certification Program | DIN CERTCO and TÜV Austria labels unlock Dutch institutional catering channels. |
Study Parameters
Direct dialogue with coating chemists, industrial bakery procurement directors, specialty paper merchants, and sustainability audit specialists grounded this analysis in operational realities. Primary interview insights were cross-referenced against customs trade data, ECHA regulatory filings, FSC chain-of-custody documentation, and SEC filings from integrated forest products groups. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Bottom-up demand modeling tracked coating chemistry substitution, thickness specifications, and end-user procurement sophistication across the projection horizon. Segmentation dimensions included product type, thickness grade, coating platform, and buyer scale tier. CAGR derivation incorporated pulp cost trajectories, automation penetration curves in European industrial baking, and compostability certification adoption rates as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for plasma-enhanced barrier deposition would alter the outlook if dry-process equipment costs fall faster than projected. Deviation in EU F-Gas Regulation enforcement intensity or Nordic pulp supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Cold Seal Paper Market
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Composite Paper Cans Market
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
Tea Filter Paper Market
Paper & Paperboard Packaging
Kraft Envelopes Market
Paper & Paperboard Packaging
Paperboard Mailer Market
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
Paperboard Clamshell Boxes Market
Paper & Paperboard Packaging
Global Cooking and Baking Papers Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
North America Paper Packaging Market
Paper & Paperboard Packaging
Paper Cones Market
Paper & Paperboard Packaging
Pre-Impregnated Paper Market
Paper & Paperboard Packaging
Kraftliner Market
Paper & Paperboard Packaging
Paper Canisters Market