
 Global Folding Boxboards Market | 2026-2036
Global Folding Boxboards Market Size, Share, and Industry Trends Forecast 2026-2036
Global Folding Boxboards Market Analysis
Plastic is restructuring folding boxboard economics as brand owners across Europe and North America substitute PET and PVC blister packs with fiber-based cartons for premium positioning. Stora Enso leverages its integrated Nordic pulp-to-board chain to supply bleached grades with certified traceability. Metsa Board Group anchors its competitive stance through lightweighting R&D that reduces grammage without sacrificing stiffness. Mayr-Melnhof Karton dominates Central European converting through backward integration into sheeting and printing operations.
Folding boxboard denotes a multi-ply paperboard product engineered from virgin or recycled fibers, typically ranging from 200 to 500 grams per square meter, manufactured through a layered forming process that positions coarse mechanical pulp in the center between finer bleached chemical pulp surfaces to achieve optimal stiffness-to-weight ratios for creasing and die-cutting operations. Its primary commercial purpose centers on high-graphic packaging applications where structural integrity, print fidelity, and consumer tactile experience converge. Bleached board commands premium placement in cosmetics and pharmaceutical cartons where whiteness underpins color reproduction. Lightweight board is gaining fastest in electronics packaging as manufacturers downsize shipping volumes to reduce freight costs. Coated board occupies the deepest margin pool where specialty barrier coatings enable direct food contact without additional film lamination.
The EU Green Deal and REACH chemical restrictions are tightening specifications for coatings and inks used on folding boxboard destined for food contact applications, while FDA food-contact substance notifications govern parallel requirements in the United States. Japan's METI has introduced recycled-content labeling mandates that create competitive differentiation for suppliers with verified fiber sourcing. Stakeholders must monitor how diverging recyclability certifications between European and Asian markets reshape sourcing decisions for multinational brand owners operating dual supply chains.
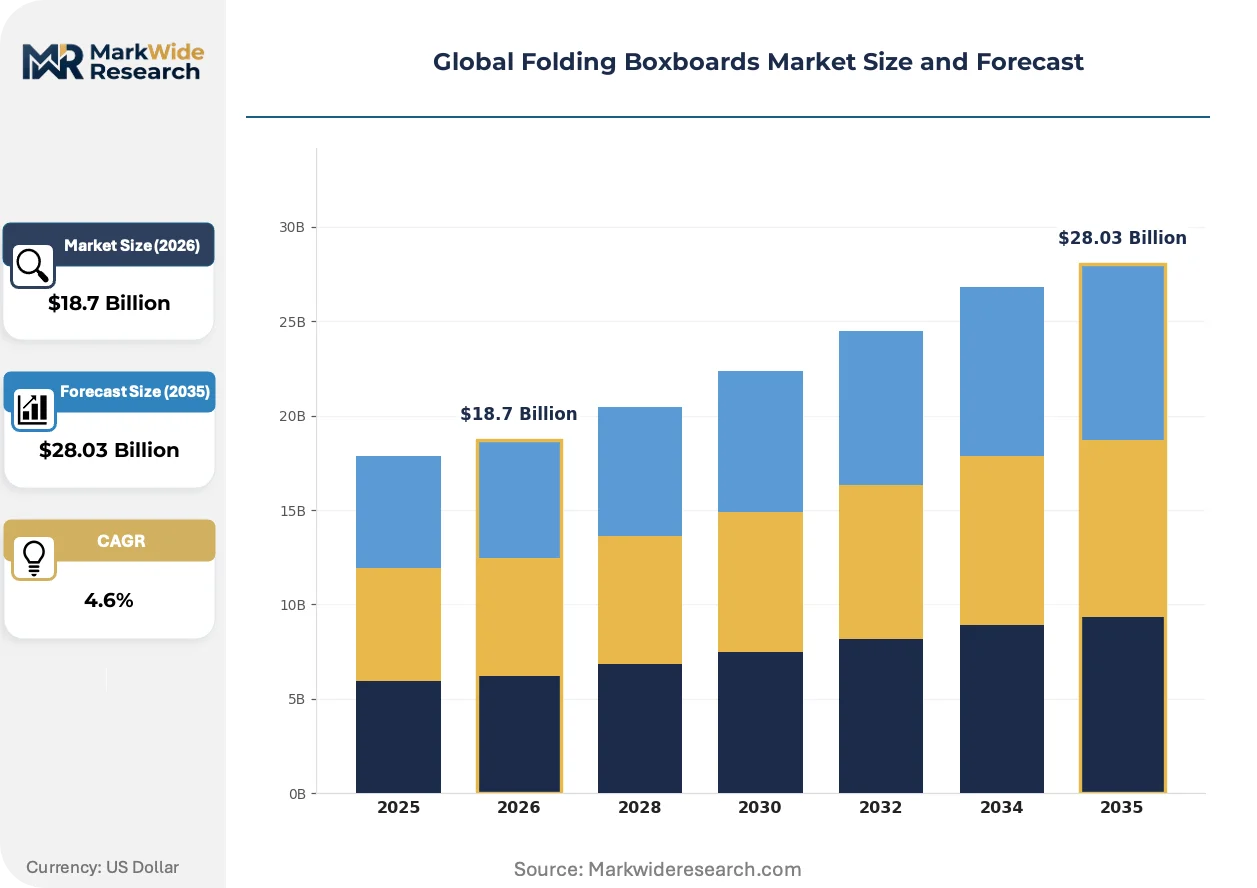
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing plastic substitution timelines, forcing brand owners to requalify fiber-based cartons for blister-pack applications faster than converter capacity can expand.
Growth Catalysts
- REACH chemical restrictions:The EU Green Deal tightens coating specifications for food-contact folding boxboard, accelerating R&D investment in mineral-oil-free barrier technologies.
- Pharmaceutical serialization:Track-and-trace mandates across European and North American markets drive demand for high-stiffness cartons that withstand laser coding and tamper-evident features.
- Vietnam converting cluster expansion:FMCG multinationals localize procurement in Southeast Asian hubs, creating pull for bleached grades with certified chain-of-custody documentation.
Market Restraints
- Pulp cost volatility:Nordic softwood pulp prices swing with energy market disruptions, compressing margins for non-integrated converters dependent on spot-market fiber.
- Barrier coating technical limits:Current water-based coatings fail grease resistance tests above 72 hours, restricting direct-food applications in ready-meal segments.
- Recycled fiber contamination:Post-consumer mixed-paper streams contain adhesive residues that degrade print fidelity, limiting circular-content claims in premium cosmetics packaging.
Strategic Opportunities
- Indonesia domestic market:Halal certification requirements for food packaging create localized demand for virgin-fiber boxboard with verified supply-chain documentation.
- Digital print convergence:Inkjet web presses paired with lightweight board grades enable short-run personalization for direct-to-consumer beauty brands.
- Japan METI labeling mandates:Recycled-content disclosure rules differentiate suppliers with verified fiber sourcing, creating premium positioning for certified producers.
Industry Challenges
- Die-cutting precision gap:Converters face acute shortages of technicians trained to maintain registration tolerances below 0.3mm on high-speed folder-gluer lines.
- Dual-certification burden:Brand owners operating EU and US supply chains must reconcile divergent recyclability standards, extending qualification timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Folding Boxboards Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unbleached Board, Bleached Board, Coated Board, Lightweight Board End User: Food & Beverage, Personal Care, Pharmaceuticals, Electronics Thickness: Thin, Medium, Thick, Extra Thick Application: Packaging, Display, Transportation, Industrial Use |
| Companies Covered | Mayr-Melnhof Karton, Stora Enso, Metsa Board Group, International Paper Company, ITC Limited, SAPPI Limited, Iggesund Paperboard, Nippon Paper Industries, JK Paper Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Folding Boxboards Market Emerging Trajectories
Lightweighting R&D and digital print integration are compressing traditional board-converter relationships while regulatory fragmentation forces parallel qualification tracks across jurisdictions.
Structural fiber engineering is modularizing how board grades match end-use performance requirements. Advanced forming technologies position tailored fiber mixes in discrete plies, allowing cosmetics brands to specify surface whiteness independently from center-layer stiffness. Electronics manufacturers adopt these configurable grades to downsize shipping cube without sacrificing protection.
REACH chemical restrictions are tightening specifications for mineral oil saturated hydrocarbons in food-contact coatings. The EU Green Deal mandates accelerate substitution timelines for conventional polyethylene extrusion barriers. Suppliers with validated bio-based coating chemistries capture preferential placement in ready-meal and dairy segments where direct food contact is required.
Brand-owner procurement teams consolidate supplier panels around integrated pulp-to-board producers capable of single-source certification. Direct contracting with Nordic mills displaces multi-tier distributor relationships in premium cosmetics and pharmaceutical segments. This concentration is most visible in German and French markets where sustainability scorecard weighting favors traceable fiber sourcing.
Global Folding Boxboards Market Segmentation
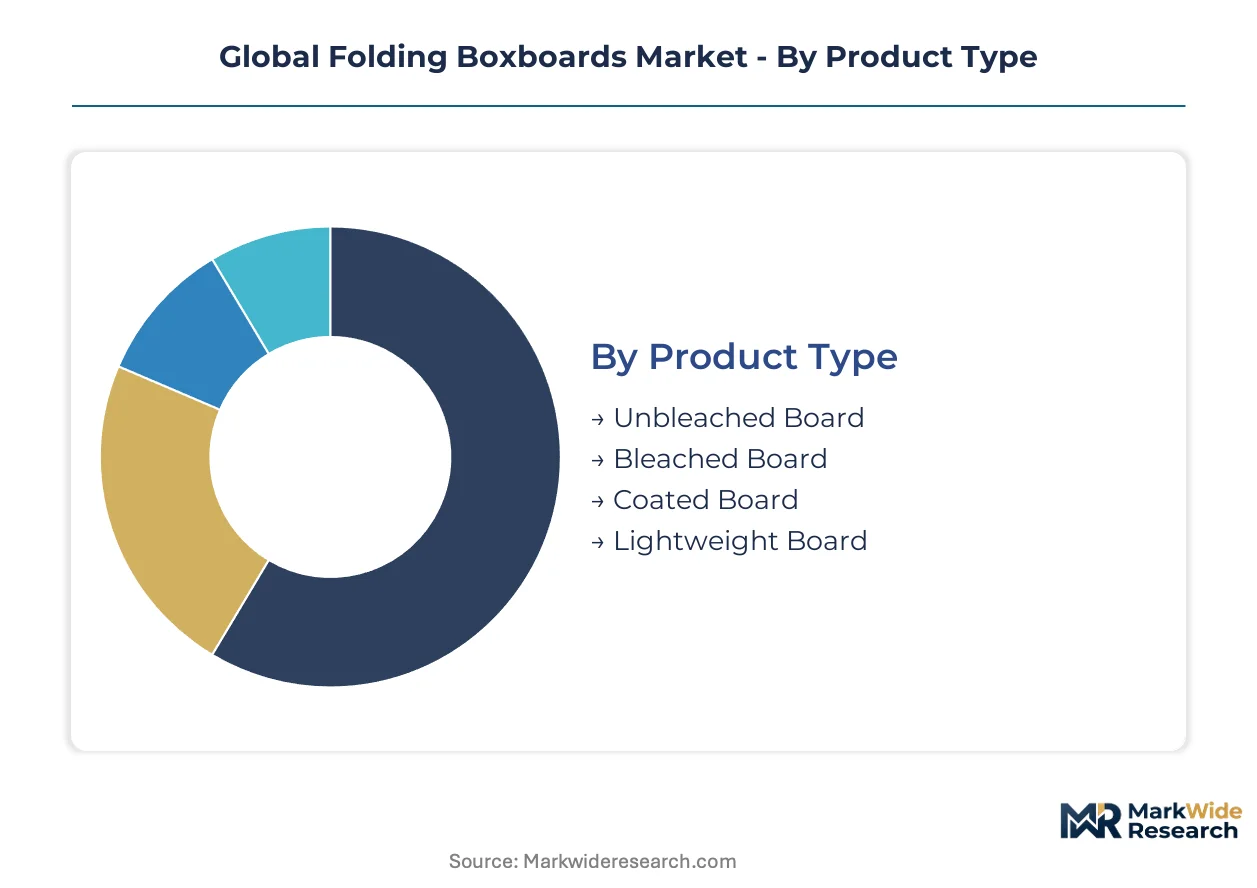
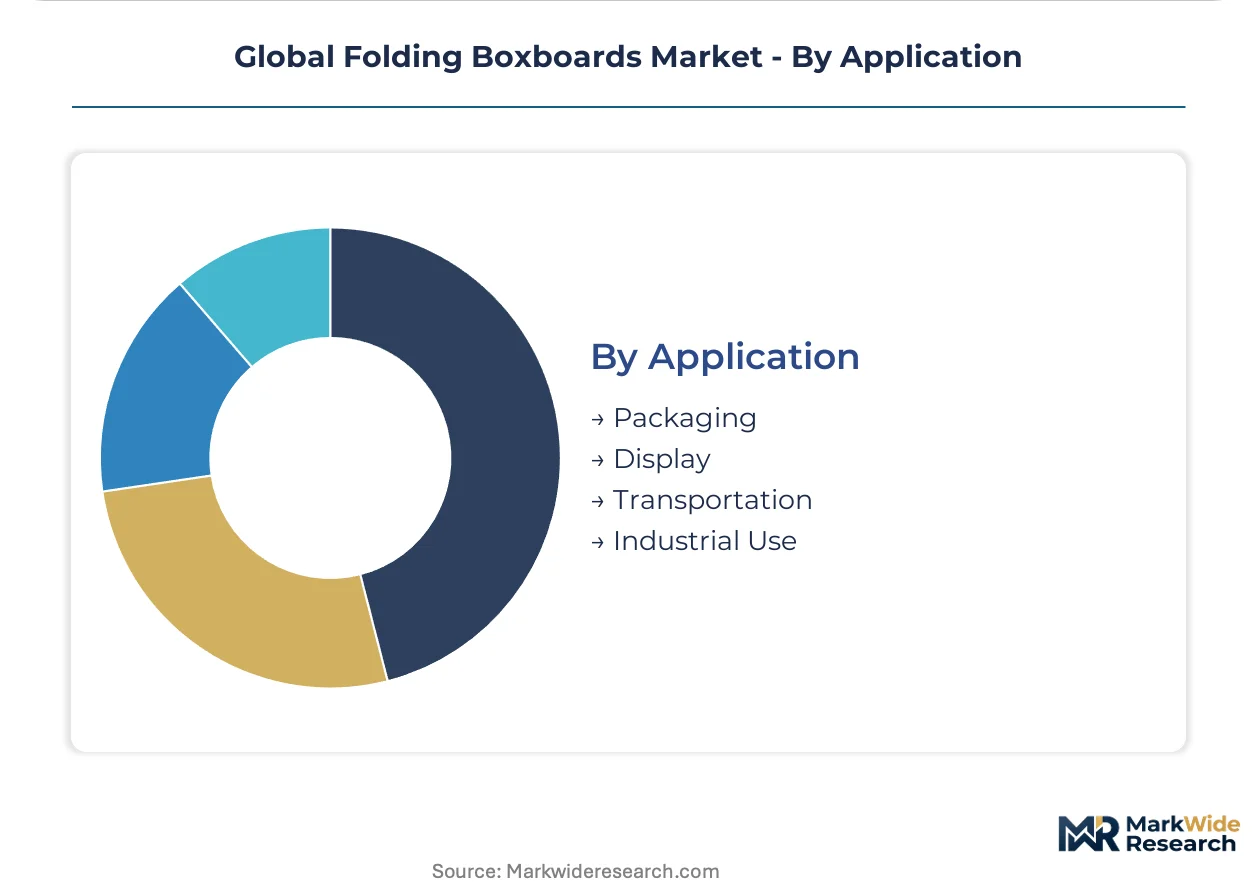
Folding boxboard segmentation reflects divergent technical requirements across end-use applications. Brand owners select grades based on stiffness-to-weight ratios, surface printability, and regulatory compliance thresholds for direct food contact.
Product Type:
Upgrade cycles in premium packaging are compressing as cosmetics and pharmaceutical brands requalify fiber-based alternatives to displace plastic blister packs.
- Bleached Board:Manufactured from virgin chemical pulp with brightness levels exceeding 80 ISO, this grade delivers superior color reproduction for high-graphic cartons. Demand concentrates in German and French cosmetics markets where ECHA REACH compliance mandates mineral-oil-free surface treatments.
- Coated Board:Specialty barrier coatings—polyethylene extrusion or aqueous dispersions—enable direct food contact without secondary film lamination. Japanese ready-meal producers specify these grades to satisfy METI recycled-content labeling mandates while maintaining grease resistance.
- Unbleached Board:Retains natural lignin content for cost-sensitive industrial applications where whiteness is secondary to structural rigidity.
- Lightweight Board:Sub-250 gsm engineered grades reduce shipping cube for electronics manufacturers downsizing e-commerce packaging.
Bleached board sits at the top of the volume ranking, with coated board climbing the fastest as food-contact barrier technologies mature.
End User:
Cost tier differentiation separates commodity converters from integrated suppliers capable of certified chain-of-custody documentation.
- Food & Beverage:Dairy and ready-meal segments require FDA-compliant coatings in US supply chains and EFSA-authorized barriers in EU markets. Vietnam-based converters are localizing procurement for ASEAN halal certification requirements.
- Personal Care:Premium cosmetics brands in Italy and Spain specify high-stiffness grades for rigid secondary packaging that replaces PVC blister formats.
- Pharmaceuticals:Serialization mandates across European markets drive demand for cartons with laser-code retention and tamper-evident fiber structures.
- Electronics:Smartphone and accessory manufacturers adopt lightweight grades to reduce freight density in air-shipped direct-to-consumer channels.
Food & beverage commands the deepest volume pool, though personal care is gaining share fastest through plastic substitution programs.
Thickness:
Application-specific performance requirements dictate grammage selection across converting operations.
- Medium:250-350 gsm range balances stiffness and creasability for standard folding cartons in FMCG applications.
- Thick:350-450 gsm grades provide structural integrity for retail display boxes and premium gift packaging.
- Thin:Sub-250 gsm specifications serve cost-optimized secondary wrapping where protection requirements are minimal.
- Extra Thick:Above-450 gsm boards support heavy-duty industrial applications and point-of-sale displays requiring load-bearing capacity.
Medium thickness dominates converter throughput, with thick grades expanding most quickly in cosmetics rigid-box applications.
Application:
Customer-type procurement patterns are consolidating around integrated pulp-to-board suppliers with single-source certification capabilities.
- Packaging:Primary and secondary carton applications span food, cosmetics, and pharmaceutical segments with divergent barrier specifications.
- Display:Retail-ready shelf packaging requires high print fidelity and structural rigidity for vertical merchandising.
- Transportation:Protective interlayers and dividers utilize unbleached grades for cost-efficient dunnage.
- Industrial Use:Patterned board and specialty laminates serve manufacturing processes outside consumer packaging.
Packaging absorbs the majority of folding boxboard volume, while display applications are climbing fastest through retail-ready format adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Nordic pulp-to-board corridor anchors capacity concentration, while converting demand disperses toward Southeast Asian manufacturing clusters and North American pharmaceutical packaging hubs.
Germany
Pharmaceutical serialization mandates and cosmetics rigid-box conversion drive specification upgrades for high-stiffness grades. ECHA REACH restrictions on mineral oil saturated hydrocarbons accelerate coating requalification timelines. The Rhine-Ruhr converting belt concentrates sheeting and printing operations serving French and Benelux brand owners.
United States
FDA food-contact substance notifications govern barrier coating approvals for dairy and ready-meal applications. Electronics manufacturers specify sub-250 gsm lightweight grades to reduce air-freight density in direct-to-consumer channels. The Chicago-Milwaukee corridor houses specialized die-cutting operations for pharmaceutical tamper-evident cartons.
Vietnam
FMCG multinationals localize procurement for ASEAN distribution networks, creating pull for bleached grades with FSC chain-of-custody documentation. Halal certification requirements for food packaging differentiate virgin-fiber suppliers with verified supply-chain transparency. Ho Chi Minh City converting parks expand sheeting capacity to serve Indonesian and Thai brand owners.
Japan
METI recycled-content labeling mandates create competitive differentiation for suppliers with verified fiber sourcing. Ready-meal producers specify coated board grades that satisfy grease-resistance thresholds while meeting disclosure rules. The Kanto region concentrates high-graphic carton printing for premium cosmetics brands.
Indonesia
Domestic halal certification requirements for food packaging create localized demand for virgin-fiber boxboard with supply-chain traceability. Japanese and Korean electronics manufacturers adopt lightweight grades for regional distribution. Jakarta-Bogor converting clusters expand to capture ASEAN procurement localization.
Global Folding Boxboards Market Vendor Landscape
Backward integration into captive pulp supply dominates the current landscape as converters defend margin positions against Nordic spot-market volatility. The supplier base concentrates around integrated pulp-to-board producers capable of single-source certification, with tiered differentiation separating commodity traders from sustainability-scorecard leaders. Three archetypes define positioning: Nordic integrated mills with certified fiber chains, Asian converters with regional halal certification capabilities, and North American distributors serving pharmaceutical qualification tracks. M&A activity and lightweighting R&D partnerships represent the dominant competitive vectors.
Among Nordic integrated producers, Stora Enso and Metsa Board Group exemplify the certified-traceability archetype through captive softwood pulp operations. Mayr-Melnhof Karton occupies a position within the European converting tier, anchoring Central European sheeting and printing integration. These three names represent distinct strategic postures: fiber-security dominance, lightweighting technology leadership, and downstream converting scale.
| Leading Market Players |
|---|
| Mayr-Melnhof Karton |
| Stora Enso |
| Metsa Board Group |
| International Paper Company |
| ITC Limited |
| SAPPI Limited |
| Iggesund Paperboard |
| Nippon Paper Industries |
| JK Paper Ltd |
| Others |
Supply Flow & Price Mechanics
Captive pulp-to-board integration anchors both supply security and pricing power for Nordic producers serving EU cosmetics and pharmaceutical markets. This structural choice insulates integrated mills from spot-market volatility while forcing non-integrated converters to absorb fiber cost swings or cede share.
Pricing Analysis
Nordic softwood pulp cost pass-through dominates contract negotiations, with bleached board grades tracking fiber indices on quarterly resets. Pricing stratifies across premium, standard, and economy tiers based on certification grade and chain-of-custody documentation depth. Cost compression in standard grades is intensifying as Vietnamese converters expand sheeting capacity for ASEAN procurement localization. Commodity converters show highest price sensitivity, while premium cosmetics brands accept sustained premiums for ECHA REACH-compliant mineral-oil-free surface treatments.
Supply Chain Analysis
Indonesia's halal certification requirements and Vietnam's domestic-content preferences for FMCG procurement are reshaping sourcing patterns across Southeast Asian converting hubs. Supply concentrates in Finland, Sweden, and Indonesia, with Nordic mills feeding bleached grades to European pharmaceutical markets and Indonesian integrated producers serving ASEAN food packaging. The chain draws from certified softwood pulp, aqueous barrier coatings, and halal-compliant adhesives. Single-source vulnerability runs through Nordic energy-intensive pulp operations exposed to electricity market disruptions. Distribution runs through mill-direct contracting displacing multi-tier distributor relationships in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU regulatory compliance costs for mineral-oil-free coatings create margin premiums unavailable to Asian producers serving less stringent domestic markets.
For Market Incumbents: Anticipate accelerating plastic substitution timelines in German and French cosmetics markets by securing ECHA REACH pre-certification for barrier coating chemistries before mandatory phase-outs. Prioritize backward integration into captive pulp supply to defend margin positions against Nordic spot-market volatility that threatens non-integrated converters.
For New Entrants and Emerging Players: Begin with Indonesia's halal-certified food packaging segment where domestic-content rules and supply-chain traceability requirements create protected demand pools. Target Vietnamese converting parks expanding to serve Thai and Indonesian brand owners with FSC chain-of-custody documentation capabilities that multinational procurement teams now require.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale Southeast Asian converters because procurement localization by FMCG multinationals is fragmenting brand-owner supplier panels into regional clusters rather than global mandates. Watch for inflection when Japanese METI labeling mandates expand disclosure requirements to imported packaging, triggering qualification urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting R&D Partnership | Metsa Board Group's gramnage reduction programs enable electronics manufacturers to downsize air-freight cube. |
| Halal Certification Investment | Indonesian mills with verified supply-chain documentation capture protected demand from domestic food producers. |
| Digital Print Integration | Inkjet web press adoption by Vietnamese converters enables short-run personalization for direct-to-consumer beauty brands. |
| Backward Integration into Pulp | Stora Enso's captive Nordic softwood operations insulate margins from energy-market-driven fiber cost volatility. |
| Barrier Coating Substitution | Bio-based aqueous dispacements replacing polyethylene extrusion satisfy EU Green Deal mandates for ready-meal applications. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down pulp-to-board capacity tracking forms the analytical core of this study. Primary interviews with procurement directors at FMCG multinationals, technical directors at Nordic integrated mills, converting plant managers in Vietnam and Indonesia, and regulatory affairs specialists at ECHA and METI combined with secondary validation. Secondary sources include EU Packaging and Packaging Waste Regulation implementation documents, FDA food-contact substance notification databases, FSC chain-of-custody certification registries, and customs trade data for pulp and board flows. Triangulation across these inputs ensures volume and value estimates reflect operational reality rather than modeled abstraction.
Input-output matrices map fiber supply through converting capacity to end-use demand across the projection horizon. Segmentation dimensions include product type, end-user industry, thickness specification, and geographic regulatory cluster. CAGRs derive from trend extrapolation of plastic substitution rates, lightweighting adoption curves, and regional procurement localization patterns. Industry-specific forecast inputs incorporate pharmaceutical serialization mandate compliance timelines and halal certification penetration rates in ASEAN markets.
Caveats apply where pulp cost volatility, regulatory fragmentation between EU and US food-contact standards, or barrier coating technical failures could materially shift the outlook. Forecasts reflect assumptions about substitution elasticity and certification adoption speed. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Global Multi Depth Corrugated Boxes Market
Paper & Paperboard Packaging
Hanging Box Market
Paper & Paperboard Packaging
Wrapping Paper Market
Paper & Paperboard Packaging
Mottled Test Liner Market
Paper & Paperboard Packaging
Germany Honeycomb Paper Market
Paper & Paperboard Packaging
Greyboard Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Clear Envelopes and Mailing Supplies Market
Paper & Paperboard Packaging
EMEA Corrugated Board Packaging Market
Paper & Paperboard Packaging
Macerated Paper Padded Mailers Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
Secondary Paper and Paperboard Luxury Packaging Market
Paper & Paperboard Packaging
SCK Paper Market
Paper & Paperboard Packaging
Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Paperboard Mailer Market
Paper & Paperboard Packaging
Impregnated Paper Market