
 HVAC Services Market | 2026-2036
HVAC Services Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Services Market Outlook
Preventive maintenance subscriptions is expanding as the dominant revenue layer in HVAC services, shifting one-time repair calls into recurring annual contracts. Carrier Global Corporation leverages its building automation heritage to bundle sensor monitoring with technician dispatch. Johnson Controls International PLC anchors its service portfolio through long-term performance contracts tied to energy savings guarantees. Daikin Industries Limited differentiates through VRF system expertise and specialized technician certification programs.
HVAC services encompass the installation, commissioning, upkeep, and restoration of climate control systems operating across refrigerant cycles, combustion processes, and hydronic distribution networks with rated capacities from residential split systems below five tons to industrial chilled water plants exceeding 500 tons. The primary purpose is sustaining thermal comfort, indoor air quality, and process cooling within built environments while minimizing energy consumption and refrigerant leakage. Installation and replacement services capture the largest revenue share due to equipment obsolescence cycles and efficiency upgrade incentives, while maintenance contracts generate the most predictable margin pools through recurring billing and consumables attachment. Smart thermostat integration within the technology segment is expanding fastest as building operators demand remote diagnostics and automated fault detection.
The US Environmental Protection Agency enforces refrigerant phase-down schedules under the AIM Act that compel service providers to certify technicians and retrofit equipment for lower-GWP alternatives. The European Union's F-Gas Regulation and Energy Performance of Buildings Directive collectively mandate regular system inspection intervals and efficiency benchmarking that expand mandatory service scopes. Stakeholders must monitor how refrigerant transition timelines reshape technician training investments and equipment replacement scheduling across their service territories.
Market Dynamics
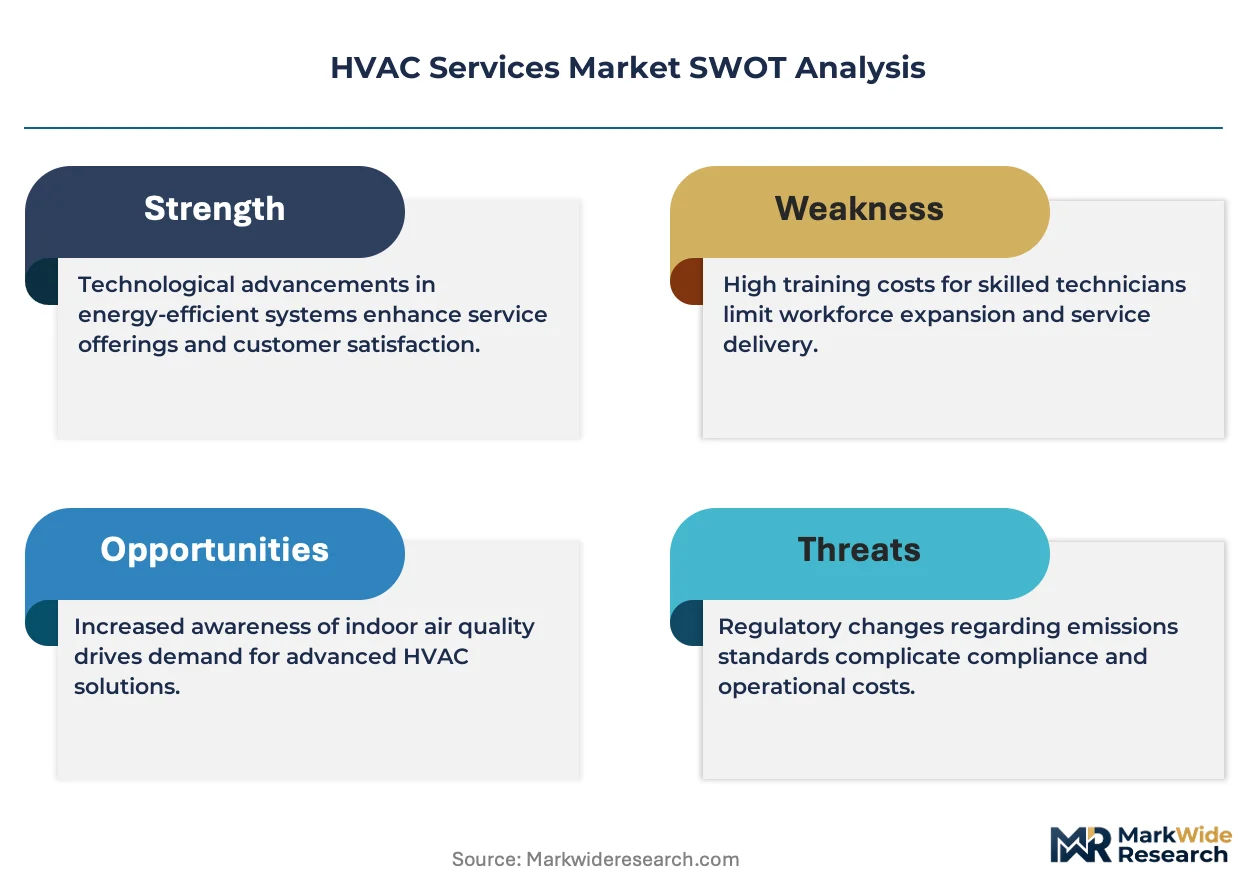
The refrigerant transition mandated by the US EPA's AIM Act and the EU's F-Gas Regulation is forcing simultaneous technician retraining, equipment retrofitting, and service contract restructuring across HVAC service portfolios. This regulatory compression is consolidating service provider capabilities around low-GWP refrigerant expertise.
Growth Catalysts
- Building Efficiency Mandates:The US Department of Energy's efficiency standards are accelerating heat pump conversions in commercial retrofits across North America, expanding long-term service contract scopes.
- Germany's Renovation Programs:Federal building renovation subsidies are concentrating demand for system replacements and integrated maintenance packages in the German market.
- Smart Building Integration:Sensor-enabled predictive maintenance is shifting reactive repair calls into recurring revenue streams for service providers with building automation capabilities.
Market Restraints
- Refrigerant Supply Concentration:Limited domestic production of lower-GWP alternatives creates input cost volatility and availability constraints for US service providers during transition periods.
- Technical Limitation:VRF system complexity requires specialized technician certification that restricts service capacity expansion in high-density urban markets.
- Regulatory Friction:The EU's Energy Performance of Buildings Directive imposes inspection interval mandates that increase compliance overhead without proportional revenue recovery mechanisms.
Strategic Opportunities
- Underpenetrated Geography:India's commercial building stock lacks systematic HVAC maintenance protocols, creating white space for subscription-based service models in Mumbai and Bangalore.
- Technology Convergence:Integration of IoT diagnostics with automated fault detection is enabling remote service triage that reduces truck-roll costs and technician dispatch frequency.
- Regulatory Tailwind:The US Inflation Reduction Act's efficiency tax credits are subsidizing heat pump installations that lock in 15-20 year service relationships for qualifying contractors.
Industry Challenges
- Technician Certification Compression:The EPA's Section 608 certification requirements for low-GWP refrigerants must scale across thousands of technicians before mandated phase-down deadlines.
- Legacy System Integration:Hydronic distribution networks in older commercial buildings resist seamless integration with modern heat pump technologies, requiring custom engineering on each retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Services Market |
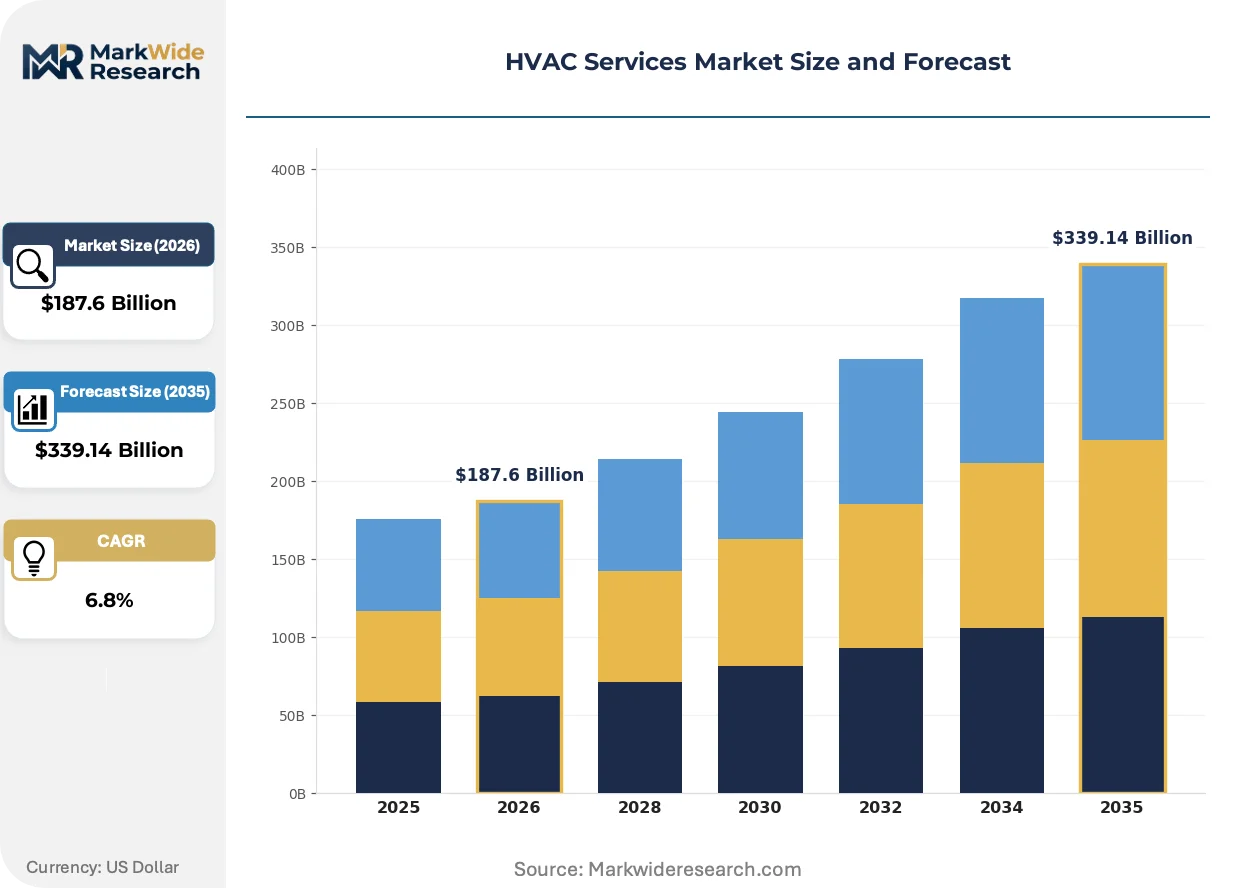
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $339.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Installation, Maintenance, Repair, Replacement System Type: Central Air, Ductless Mini-Split, Heat Pump, Radiant Heating End User: Residential, Commercial, Industrial, Educational Technology: Smart Thermostats, Energy Recovery Ventilators, Variable Refrigerant Flow, Hydronic Systems |
| Companies Covered | Daikin Industries Limited, Carrier Global Corporation, Johnson Controls International PLC, Trane Technologies plc, Lennox International Inc., Honeywell International Inc., Mitsubishi Electric Corporation, LG Electronics Inc., EMCOR Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Services Market Strategic Shifts
Digital service platforms are restructuring how HVAC maintenance is procured, delivered, and priced. The convergence of remote monitoring, automated dispatch, and performance-based contracting is compressing traditional service hierarchies.
Variable refrigerant flow technology is consolidating market share in mid-rise commercial applications where zoned climate control commands premium pricing. Property managers in mixed-use developments are specifying VRF systems for tenant billing granularity. This technology is consolidating installer margins by demanding specialized certification that filters out generalist competitors.
The EU's F-Gas Regulation is tightening refrigerant quota allocations that cascade into mandatory leak detection requirements for systems above specific charge thresholds. Service providers must deploy certified detection equipment and document inspection intervals. Industrial process cooling installations in Germany and France are absorbing the highest compliance costs through expanded maintenance scopes.
Facility managers are unbundling equipment procurement from long-term service agreements, separating capital expenditure decisions from operational vendor selection. This disintermediation is compressing OEM service attach rates while expanding independent service contractor opportunities. The pattern is most visible in US healthcare and education verticals where procurement departments now mandate competitive service bidding post-installation.
HVAC Services Market Segmentation
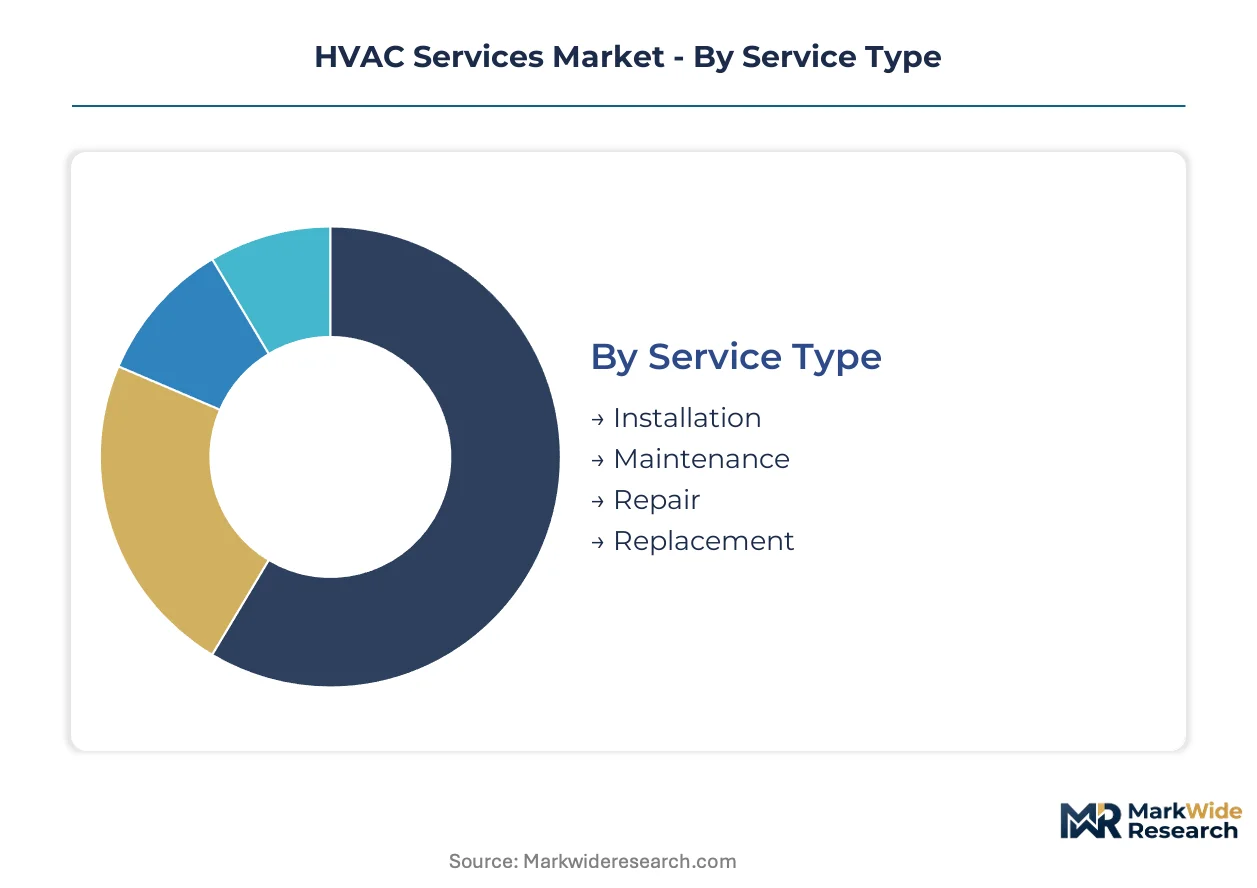
HVAC service providers structure portfolios across equipment lifecycle stages and building archetypes. Segmentation reveals where recurring revenue concentrates versus project-based work, guiding technician specialization and contract pricing.
Service Type:
Installation commands the highest per-transaction value but suffers from cyclical demand. Maintenance contracts deliver the steadiest margin pools through subscription billing and consumables attachment.
- Installation:New system deployment and original equipment commissioning for greenfield construction and major renovation projects. Demand concentrates in Germany's federal building renovation programs, where subsidy thresholds require certified contractor participation for rebate eligibility.
- Maintenance:Scheduled preventive service including filter replacement, coil cleaning, refrigerant level verification, and component inspection intervals. Commercial building retrofits across the United States are expanding long-term service contract scopes as the Department of Energy efficiency mandates accelerate equipment refresh cycles.
- Repair:Reactive breakdown response and component-level restoration of failed subsystems. Emergency dispatch premiums compress margins during peak seasonal demand.
- Replacement:End-of-life equipment removal and successor system integration. The US Inflation Reduction Act efficiency tax credits are subsidizing heat pump conversions that lock in extended service relationships.
Mature deployment sits with Maintenance. Newer deployment is concentrated in Replacement as refrigerant phase-down deadlines force accelerated equipment refresh.
System Type:
Application context determines technology selection—centralized distribution suits large floorplates while zoned systems serve heterogeneous tenant needs.
- Central Air:Ducted forced-air distribution through centralized air handling units with perimeter compressor staging. Remains dominant in US residential suburban construction and legacy commercial stock requiring uniform conditioning.
- Ductless Mini-Split:Refrigerant-line-connected indoor evaporator units paired with outdoor condensers, eliminating ductwork infrastructure. Retrofit penetration is climbing the fastest in high-density urban markets where historic building envelopes resist duct installation.
- Heat Pump:Reversible vapor-compression systems providing both heating and cooling through refrigerant cycle reversal. US Department of Energy efficiency standards are accelerating conversions across North American commercial retrofits.
- Radiant Heating:Hydronic or electric thermal distribution through floor, wall, or ceiling surfaces. European residential new construction favors this technology for thermal comfort consistency.
Volume leadership belongs to Central Air. Technology transition is accelerating fastest in Heat Pump as regulatory mandates displace combustion heating.
End User:
Customer archetypes diverge sharply in procurement sophistication, contract duration preferences, and compliance requirements.
- Residential:Single-family and multi-family dwelling climate control services. Homeowners prioritize upfront cost minimization over lifecycle service bundling.
- Commercial:Office, retail, hospitality, and mixed-use property climate management. Facility managers in US healthcare and education verticals now mandate competitive service bidding post-installation.
- Industrial:Process cooling, manufacturing environment control, and critical infrastructure thermal management. Requires 24/7 response guarantees and specialized refrigerant handling protocols.
- Educational:K-12 and higher education campus building stock with seasonal occupancy patterns. Deferred maintenance backlogs create replacement demand concentration.
Contract maturity is highest in Commercial. Procurement transformation is reshaping fastest in Educational as public sector competitive bidding mandates expand.
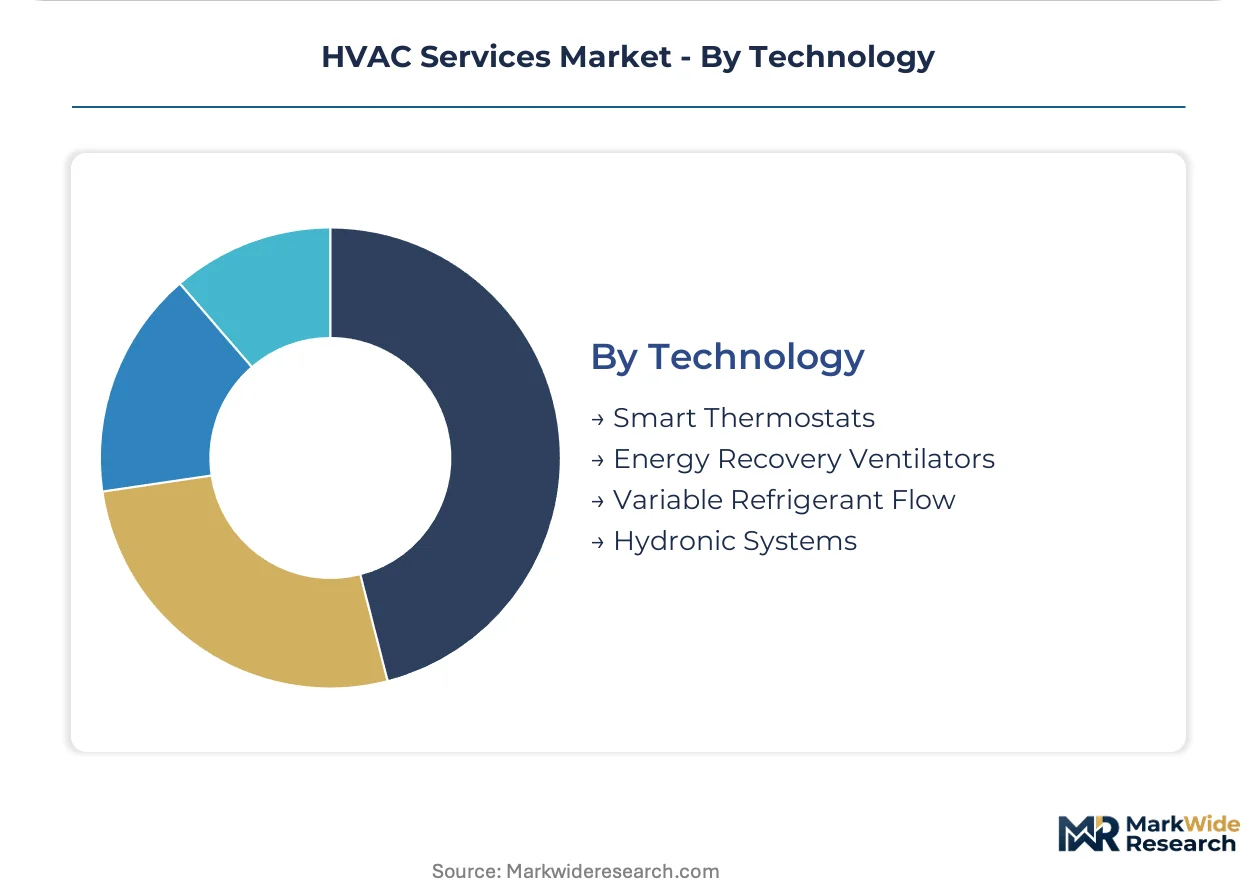
Technology:
Intelligence layer integration is restructuring service delivery economics and customer value propositions.
- Smart Thermostats:Networked environmental controls with occupancy sensing, learning algorithms, and remote accessibility. Building operators demand automated fault detection capabilities that reduce truck-roll frequency.
- Energy Recovery Ventilators:Heat and moisture exchange between exhaust and intake air streams to reduce conditioning load. Mandated in jurisdictions with stringent ventilation efficiency codes.
- Variable Refrigerant Flow:Refrigerant-based zoned climate control with modular compressor staging and individual evaporator metering. Property managers in mixed-use developments specify VRF for tenant billing granularity.
- Hydronic Systems:Water or glycol-based thermal distribution through boilers, chillers, and circulating pumps. Legacy commercial building integration with modern heat pump technologies requires custom engineering on each retrofit.
Installed base concentration remains with Hydronic Systems. Capability investment is concentrating fastest in Variable Refrigerant Flow as specialized certification filters out generalist competitors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing concentrates in Japan, the United States, and Germany, while service revenue generation disperses across retrofit-intensive markets in North America and Europe where building stock age drives replacement demand.
United States
Commercial building retrofits and federal efficiency mandates are accelerating heat pump conversions across the country. The Department of Energy's appliance standards and the Inflation Reduction Act's tax credits are restructuring contractor incentives. Service contract expansion concentrates in Texas and Florida where cooling-degree-day intensity sustains year-round maintenance demand.
Germany
Federal building renovation subsidies are concentrating system replacement demand and integrated maintenance package procurement. The F-Gas Regulation and Energy Performance of Buildings Directive mandate inspection intervals that expand compulsory service scopes. Industrial process cooling installations in the Ruhr region and Bavaria absorb elevated compliance costs through broadened maintenance contracts.
Japan
VRF technology adoption in dense urban commercial developments drives specialized technician demand. METI efficiency standards and refrigerant transition timelines compress service provider capability requirements. Tokyo and Osaka metropolitan areas concentrate high-rise building service contracts where zoned climate control commands premium pricing.
India
Commercial building stock lacks systematic HVAC maintenance protocols, creating white space for subscription-based service models. Bureau of Indian Standards equipment certification and state-level energy conservation building codes are formalizing service requirements. Mumbai and Bangalore clusters see emerging demand for predictive maintenance platforms as facility management sophistication advances.
Canada
Cold-climate heat pump deployment is expanding service contract scopes in provinces with aggressive electrification targets. Natural Resources Canada efficiency programs and provincial rebate structures are accelerating equipment refresh cycles. Ontario and British Columbia urban centers concentrate demand for hydronic-heat pump integration expertise in older commercial building retrofits.
HVAC Services Market Competitive Environment
Capital-heavy producers compete with asset-light designers as diversified industrial conglomerates anchor the market structure alongside specialized climate-control pure-plays. The vendor base stratifies across three tiers: integrated building automation providers, equipment OEMs with captive service networks, and independent regional contractors. Consolidation pressure intensifies as refrigerant certification requirements and smart building integration demands filter out generalist competitors. Strategic moves center on technician training platform acquisitions and remote diagnostics capability licensing.
Within the integrated building automation tier, Carrier Global Corporation and Johnson Controls International PLC exemplify archetypes that bundle sensor infrastructure with service dispatch networks. Daikin Industries Limited anchors the specialized equipment-manufacturer segment where VRF system expertise creates certification barriers that protect service margins.
| Leading Market Players |
|---|
| Daikin Industries Limited |
| Carrier Global Corporation |
| Johnson Controls International PLC |
| Trane Technologies plc |
| Lennox International Inc. |
| Honeywell International Inc. |
| Mitsubishi Electric Corporation |
| LG Electronics Inc. |
| EMCOR Group Inc. |
| Others |
Value Chain & Pricing Dynamics
US commercial facility managers in healthcare and education verticals now mandate competitive service bidding post-installation, compressing OEM service attach rates and anchoring market-wide pricing around project-based transactional models. This procurement sophistication concentrates pricing power with independent regional contractors who undercut bundled service premiums.
Pricing Analysis
Margin tightening in maintenance subscriptions reflects EPA Section 608 certification bottlenecks that restrict technician supply and elevate labor premiums. Three-tier pricing structure across certified-premium, standard-licensed, and economy-generalist levels segments buyer willingness-to-pay. Cost-down pressure on installation services accelerates because refrigerant phase-down deadlines compress equipment replacement windows. Residential homeowners exhibit highest price sensitivity; industrial process cooling operators accept premium pricing for 24/7 response guarantees.
Supply Chain Analysis
Direct-to-contractor distribution channels handle equipment and consumables flow, bypassing traditional wholesale intermediaries in mature North American markets. Manufacturing concentrates in Japan, the United States, and Germany for compressors and control systems; lower-GWP refrigerant production clusters in China and the European Union. Component sourcing draws from copper tubing mills in Chile, electronic control suppliers in South Korea, and specialty steel foundries in India. Single-source vulnerability in lower-GWP refrigerant supply creates input cost volatility during transition periods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HVAC services is consolidating around refrigerant expertise and smart building integration capabilities, with EPA certification mandates and F-Gas Regulation compliance costs forcing generalist competitors toward exit or acquisition.
For Market Incumbents: Anticipate technician certification compression by acquiring training platforms that scale low-GWP refrigerant credentials ahead of mandated phase-down deadlines. Deepen backward integration into sensor hardware to protect service margins against disintermediation from independent contractors. Carrier Global Corporation and Johnson Controls International PLC exemplify the bundled automation-service model that independent competitors cannot replicate without capital investment. For New Entrants and Emerging Players: Enter via predictive maintenance platforms in India's commercial building clusters, where systematic HVAC service protocols remain underdeveloped and facility management sophistication is advancing fastest. Target Mumbai and Bangalore for subscription-based service models that leapfrog legacy reactive repair relationships. Partner with local equipment distributors to secure initial contract flow without captive installation networks. For Investors and Strategic Acquirers: The window for entry favors regional contractors with EPA Section 608 certification scale and established relationships in commercial retrofit verticals. Acquisition targets should demonstrate technician training infrastructure and recurring revenue concentration above project-based work. Watch refrigerant quota allocation announcements under the EU F-Gas Regulation as inflection indicators for compliance cost acceleration and forced consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Platform Acquisition | EPA Section 608 mandates for low-GWP refrigerants compress training timelines and credential scarcity. |
| Remote Diagnostics Capability Licensing | IoT-enabled fault detection reduces truck-roll costs and deepens recurring revenue attachment. |
| Heat Pump Installation Capacity Expansion | US Inflation Reduction Act tax credits subsidize conversions that lock in 15-20 year service relationships. |
| VRF System Specialist Certification Investment | Specialized credentials filter out generalist competitors in high-density urban commercial markets. |
| Predictive Maintenance Platform Launch | Sensor-enabled monitoring shifts reactive repair calls into subscription billing with consumables attachment. |
Study Parameters
Independent corroboration across primary interviews with HVAC service contractors, facility management executives, and OEM service network directors, combined with secondary validation through EPA regulatory filings, DOE efficiency standard publications, and EU F-Gas Regulation implementation reports, underwrites the qualitative findings. Bottom-up technician capacity estimates and top-down service revenue triangulation anchor market sizing across the analysis window.
Historical reference periods anchored the forecast framework to equipment replacement cycles and regulatory compliance deadlines. Segmentation modeling incorporated service type, system technology, end-user vertical, and regional regulatory cluster dimensions. CAGRs derived from equipment obsolescence timelines, subsidy program durations, and refrigerant phase-down schedules. Forecast inputs included cooling-degree-day intensity variations and building stock age distributions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated refrigerant transition timelines or subsidy program suspension. Periodic stress-testing of base assumptions is recommended, particularly regarding technician certification throughput and lower-GWP refrigerant supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Centrifugal Chillers Market
HVAC Equipment
South Korea HVAC Market
HVAC Equipment
Industrial Insulation Testers Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
Europe Heat Exchanger Market
HVAC Equipment
Centrifugal Blower Market
HVAC Equipment
Air-Cooled Heat Exchangers Market
HVAC Equipment
North America Bus HVAC Market
HVAC Equipment
Commercial Refrigeration Compressor Market
HVAC Equipment
Radiant Heating and Cooling Systems Market
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
Louver Dampers Market
HVAC Equipment
South America Screw Compressor Market
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
Compressor Controllers Market
HVAC Equipment
Linear Slot Diffuser Market