
 France Commercial HVAC Market | 2026-2036
France Commercial HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
France Commercial HVAC Market Insights
Equipment procurement through French engineering-procurement-construction consortiums is tilting toward turnkey performance-contracting arrangements. Carrier Corporation leverages its chiller service infrastructure to anchor long-term maintenance revenue in Lyon and Marseille commercial zones. Daikin Airconditioning France dominates ductless and VRF specification channels through direct contractor training academies. Johnson Controls International PLC competes on building automation integration, positioning its Metasys platform as the control layer for multi-site retail portfolios.
France Commercial HVAC encompasses climate control systems engineered to regulate temperature, humidity, and air quality within non-residential structures, typically operating between 50 kW and 5 MW cooling capacity depending on building scale and occupancy density. These systems employ vapor-compression or absorption refrigeration cycles, hydronic heat distribution, and electronically commutated fan arrays to maintain ASHRAE-compliant indoor environments across variable external loads. Heat Pumps now command the fastest expansion trajectory among product types, as French commercial developers substitute gas-fired boilers ahead of RE2020 environmental regulation enforcement. Smart HVAC technology concentrates margin pools through subscription-based energy analytics, while Rooftop Units retain volume dominance in peripheral retail and logistics parks where first-cost sensitivity persists.
France's Ministry of Ecological Transition enforces the F-Gas Regulation through quota-based HFC phase-downs, compelling OEMs to redesign compressor architectures for R-32 and R-454B refrigerants. ANSM and CNIL oversight intersects where connected HVAC systems process occupancy data, creating dual compliance obligations for cybersecurity and health-data handling. RE2020 thermal regulation thresholds for new commercial construction are tightening envelope-performance requirements, effectively mandating higher-efficiency equipment selection. Stakeholders must monitor refrigerant supply chain readiness and local installer certification capacity as the next regulatory compression cycle approaches.
Market Dynamics
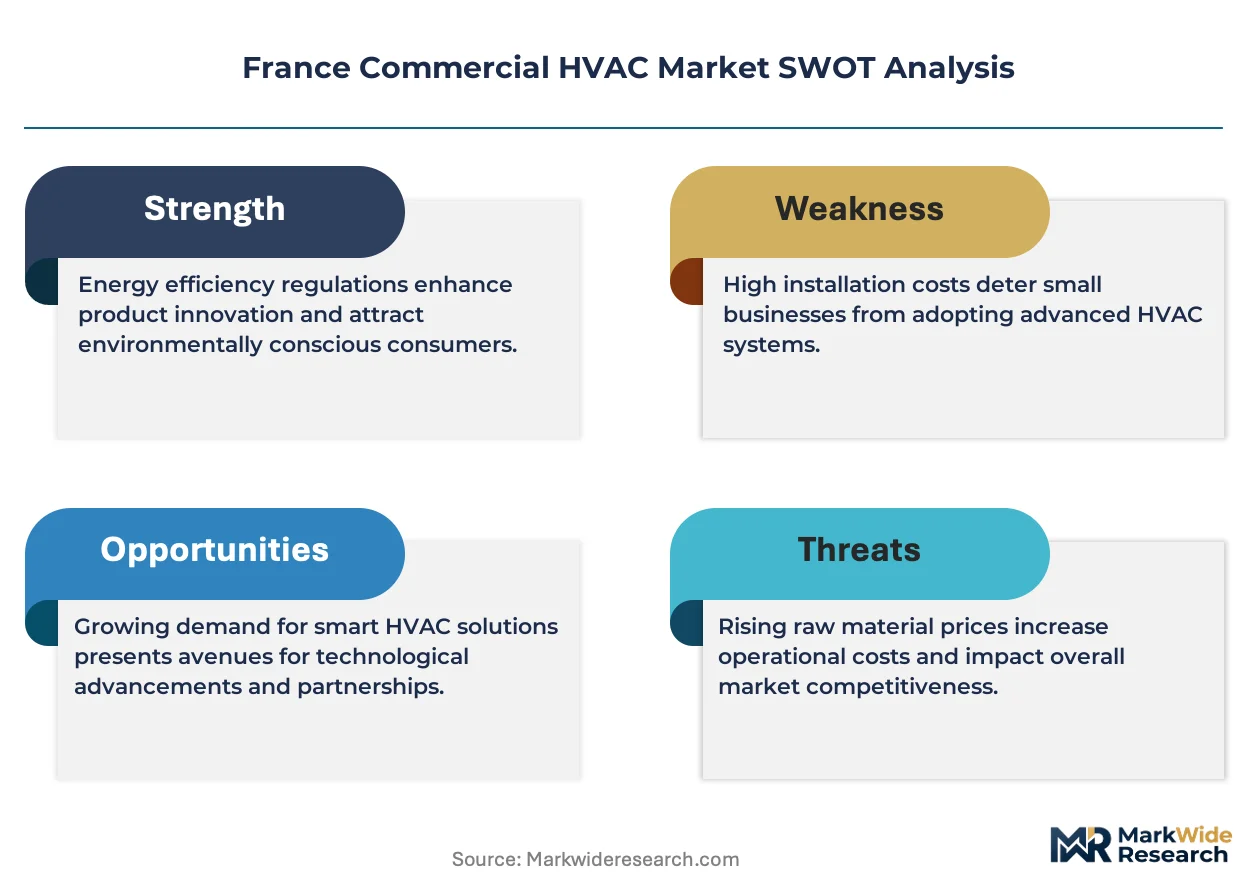
The French commercial HVAC sector faces structural pressure from the F-Gas Regulation's quota-based HFC phase-down, which is forcing wholesale refrigerant platform transitions across installed chiller bases and new construction specifications simultaneously.
Growth Catalysts
- RE2020 Thermal Regulation:New commercial construction mandates higher envelope-performance thresholds, compelling developers to specify heat pumps over gas-fired boilers in office and retail developments.
- Grand Paris Express Ancillary Development:Station-adjacent commercial real estate across Île-de-France is generating concentrated demand for integrated climate control infrastructure.
- R-32 and R-454B Refrigerant Migration:OEM compressor redesigns for lower-GWP platforms are opening specification windows for equipment refresh cycles in aging hospitality and healthcare facilities.
Market Restraints
- Copper and Aluminum Input Volatility:Heat exchanger and coil manufacturing faces margin compression from base metal price swings, particularly affecting rooftop unit producers serving cost-sensitive logistics park developers.
- Installer Certification Bottleneck:F-Gas Regulation compliance requires certified technician pools that remain underdeveloped in Provence-Alpes-Côte d'Azur and Auvergne-Rhône-Alpes secondary markets.
- Legacy Chiller Asset Stranding:High-GWP refrigerant equipment faces accelerated obsolescence risk as quota reductions tighten supply and service part availability for R-410A and R-134a systems.
Strategic Opportunities
- Smart HVAC Subscription Analytics:Energy management platforms offering predictive maintenance and demand-response integration are capturing recurring revenue streams from multi-site retail and hotel portfolios.
- Occitanie and Nouvelle-Aquitaine Commercial Expansion:Underpenetrated secondary urban corridors outside Paris present first-mover advantages for VRF and ductless specification in mid-scale office developments.
- EU Green Deal Heat Pump Acceleration:National subsidy harmonization under Recovery and Resilience Facility funding is redirecting public and institutional procurement toward electrified heating infrastructure.
Industry Challenges
- Refrigerant Supply Chain Reconfiguration:Quota allocation mechanisms are creating procurement uncertainty for contractors managing multi-year project pipelines across mixed-use developments.
- Cybersecurity and Health Data Compliance:Connected HVAC systems processing occupancy and air quality metrics face overlapping ANSM health-data and CNIL privacy obligations that complicate platform architecture.
- Legacy Building Automation Integration:Retrofit projects in Parisian office stock require protocol bridging between new equipment and existing BACnet or proprietary control networks, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Commercial HVAC Market |
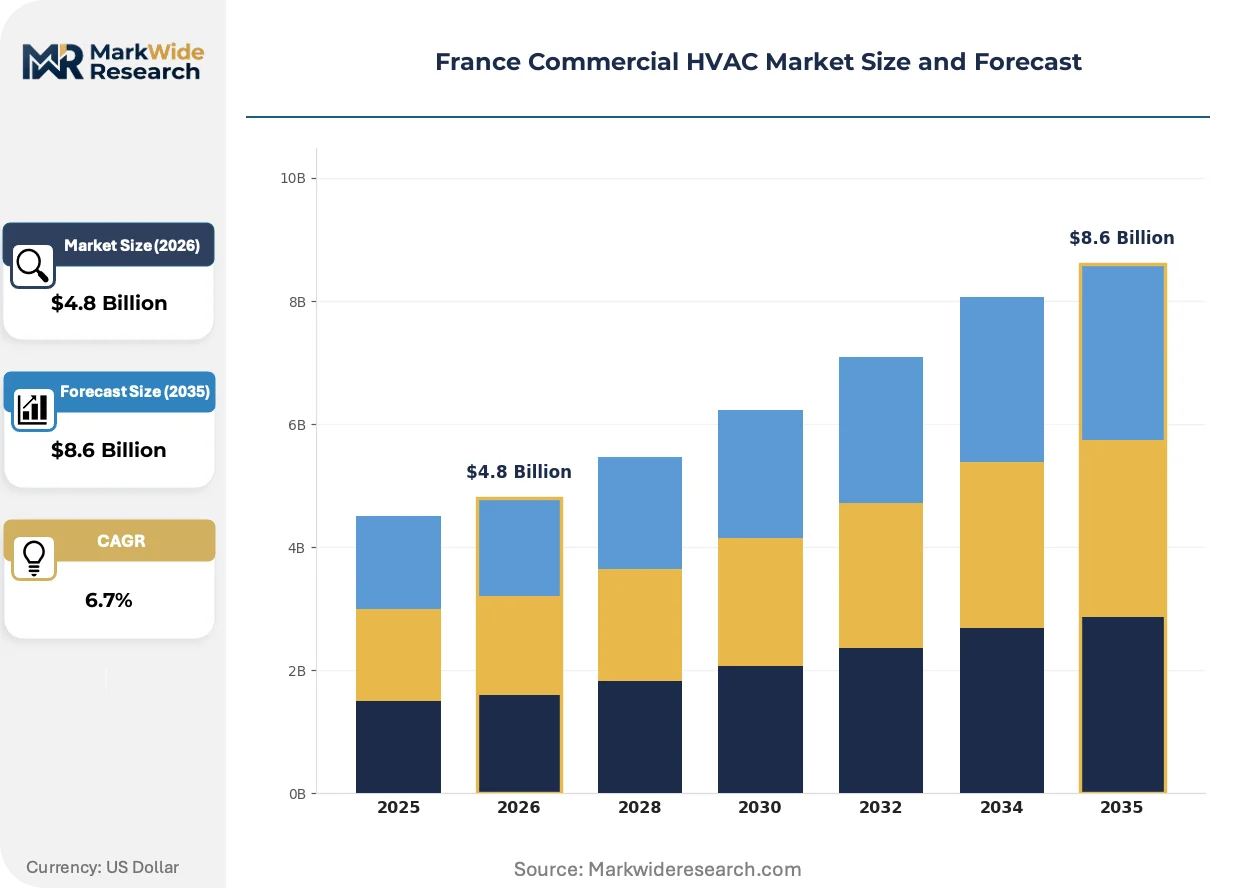
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Air Handling Units, Heat Pumps, Rooftop Units Application: Office Buildings, Retail Stores, Educational Institutions, Hospitality Technology: Variable Refrigerant Flow, Hydronic Systems, Ductless Systems, Smart HVAC End User: Commercial Buildings, Healthcare Facilities, Manufacturing Plants, Data Centers |
| Companies Covered | Carrier Corporation, Johnson Controls International PLC, Trane Technologies PLC, Daikin Airconditioning France, Robert Bosch GmbH, Systemair AB, FlaktGroup Inc., LG Electronics Inc., BDR Thermea Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Commercial HVAC Market Trends and Innovations
Equipment specification behavior is pivoting toward integrated performance contracting, with technology migration and regulatory compression operating as twin accelerants of vendor strategy and buyer procurement criteria.
Vapor-compression chiller technology is migrating from high-GWP refrigerant platforms to R-32 and R-454B architectures. Hospitality operators in Provence-Alpes-Côte d'Azur are adopting these systems at compressed refresh cycles to preempt F-Gas Regulation compliance deadlines. This migration is compressing incumbent OEM service revenue models while opening specification windows for integrated heat pump platforms.
The EU Green Deal's RE2020 enforcement is tightening thermal performance thresholds for new commercial construction. French developers face mandatory efficiency coefficients that effectively prohibit gas-fired boiler specification in favor of electrified heat pump infrastructure. Multi-site retail and office portfolios in Île-de-France are responding with bundled energy-performance contracting that transfers operational risk to HVAC vendors.
Engineering-procurement-construction consortiums are unbundling traditional equipment supply from long-term maintenance obligations. Turnkey performance contracts now dominate specification channels for Lyon and Marseille commercial zones, displacing discrete equipment procurement. This behavioral shift concentrates margin capture with vendors offering predictive analytics and guaranteed efficiency outcomes.
France Commercial HVAC Market Segmentation
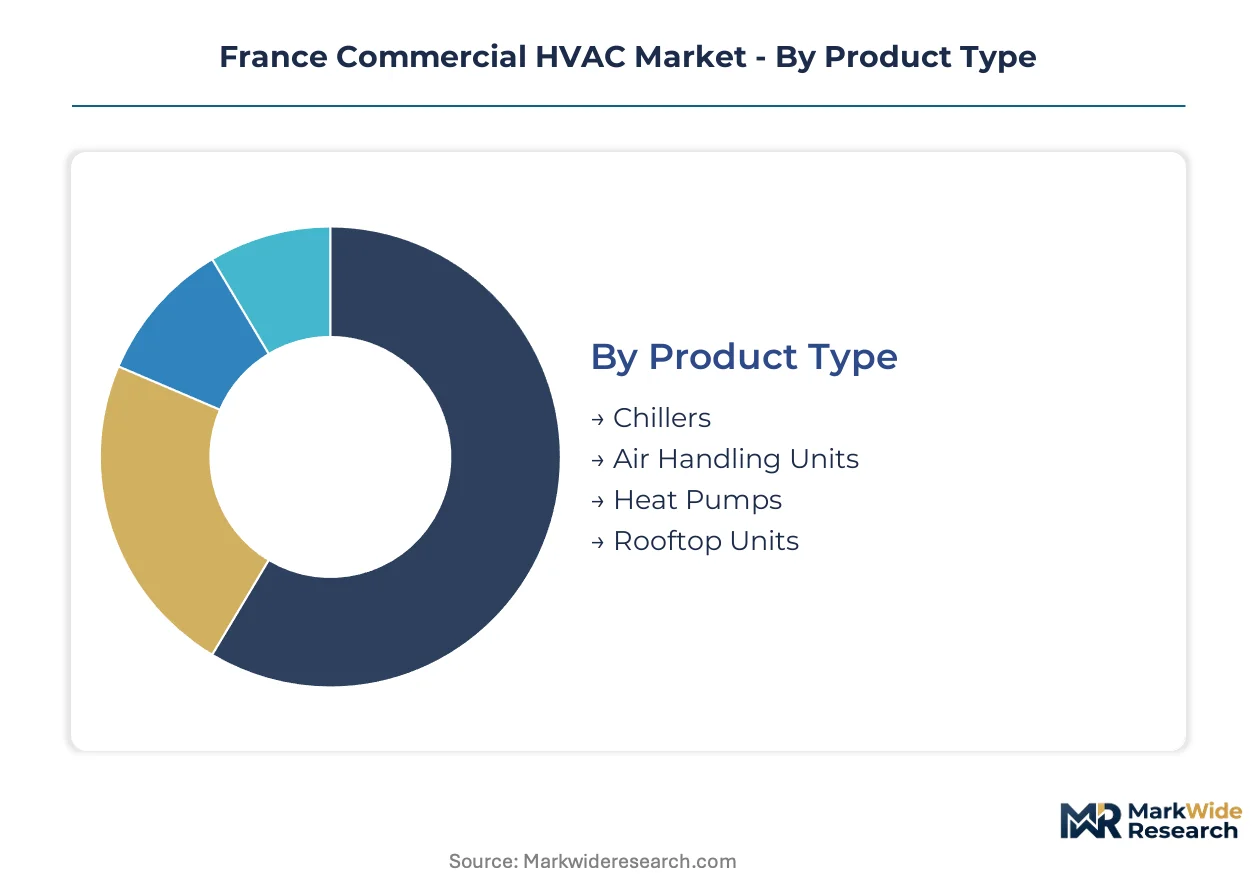
Segmentation in the France Commercial HVAC Market reveals how regulatory pressure and building typology reshape procurement patterns. Equipment categories, application contexts, and technology platforms each concentrate demand in distinct corridors of the Île-de-France and regional urban centers.
Product Type:
Equipment selection across French commercial developments spans cooling-centric infrastructure through integrated heating platforms, with regulatory phase-downs redirecting specification behavior.
- Chillers:Centralized vapor-compression systems engineered for 200 kW to 5 MW cooling loads in large office and hospitality complexes. Provence-Alpes-Côte d'Azur hotel operators are accelerating replacement cycles to preempt F-Gas Regulation compliance deadlines for high-GWP refrigerant retirement.
- Air Handling Units:Modular ventilation assemblies integrating filtration, heating, and cooling coils for ducted distribution networks. Parisian office retrofits concentrate demand where Grand Paris Express ancillary developments require ASHRAE-compliant indoor air quality infrastructure.
- Heat Pumps:Electrified heating and cooling platforms substituting gas-fired boilers under RE2020 thermal regulation enforcement.
- Rooftop Units:Self-contained packaged systems dominating peripheral retail and logistics park installations where first-cost sensitivity persists.
The dominant share belongs to Chillers, while Heat Pumps are closing the gap fastest.
Application:
Building typology determines capacity requirements, control sophistication, and maintenance contract structures across French commercial zones.
- Office Buildings:Climate control systems serving 50 kW to 2 MW loads with zone-level temperature management and occupancy-based ventilation. Île-de-France corridor developments concentrate specification volume where RE2020 mandates electrified heating infrastructure in new construction.
- Retail Stores:Distributed HVAC assets requiring rapid commissioning and standardized maintenance protocols across multi-site portfolios. Lyon and Marseille commercial zones show concentrated demand for turnkey performance-contracting arrangements that transfer operational risk to vendors.
- Educational Institutions:Public sector procurement subject to EU Green Deal subsidy harmonization and extended equipment lifecycle requirements.
- Hospitality:Guest comfort-critical systems with 24/7 reliability demands and rapid refresh cycles in premium coastal markets.
Office Buildings command the largest installed base, though Hospitality is expanding most quickly as coastal operators confront accelerated obsolescence risk.
Technology:
Control architecture and distribution methodology differentiate margin capture and installation complexity across French contractor networks.
- Variable Refrigerant Flow:Refrigerant-based zoning systems enabling individual temperature control without ductwork infrastructure. Daikin Airconditioning France dominates specification channels through direct contractor training academies in secondary urban corridors.
- Hydronic Systems:Water-based heat distribution networks integrating with low-temperature heat pump outputs under RE2020 efficiency thresholds. New commercial construction in Île-de-France mandates these configurations for regulatory compliance.
- Ductless Systems:Compact split configurations serving small-format retail and historic building retrofits with spatial constraints.
- Smart HVAC:Connected platforms offering predictive maintenance, demand-response integration, and subscription-based energy analytics.
Variable Refrigerant Flow holds the greatest specification share, while Smart HVAC is gaining share fastest through recurring revenue capture.
End User:
Operational criticality and regulatory exposure shape procurement sophistication across French commercial and institutional sectors.
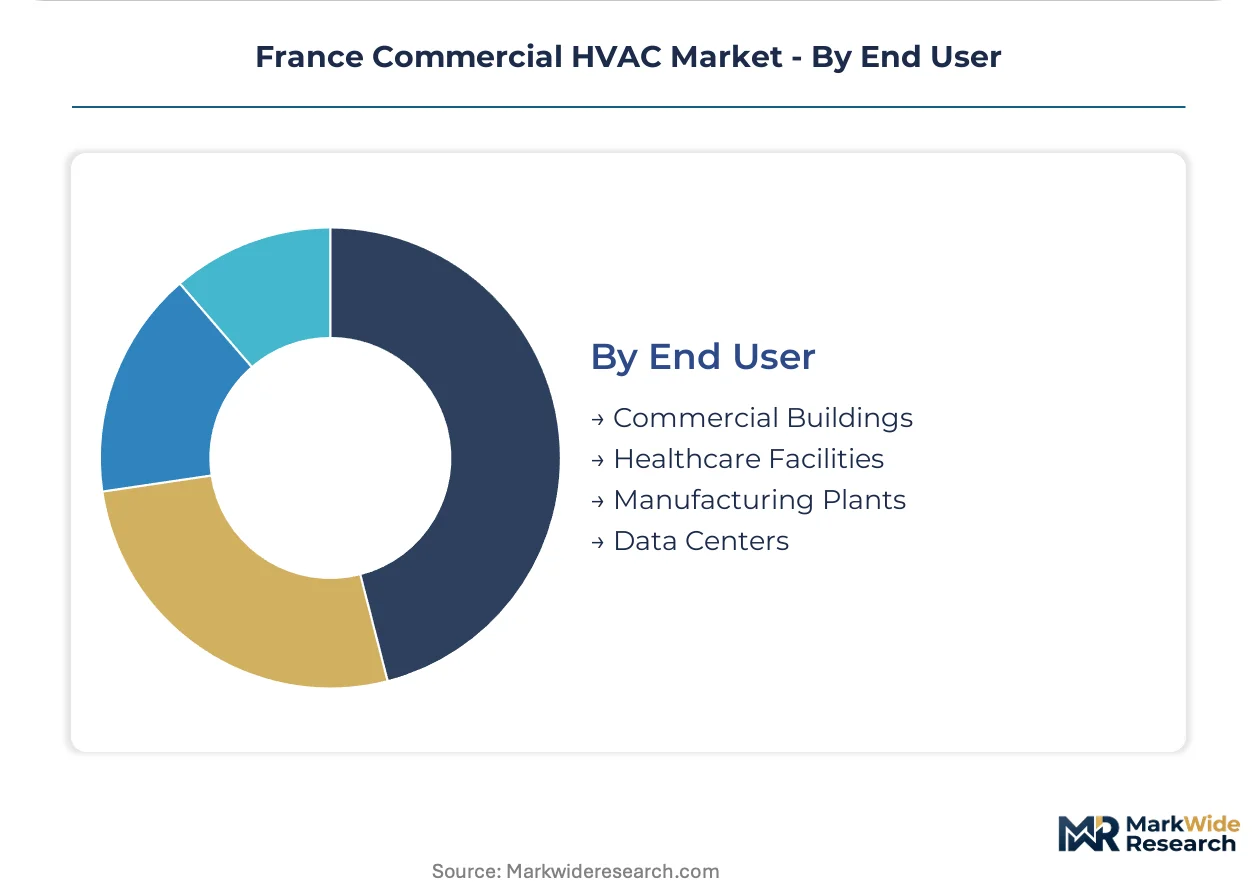
- Commercial Buildings:General office and mixed-use developments where energy-performance contracting transfers operational risk to HVAC vendors. Engineering-procurement-construction consortiums in Lyon and Marseille commercial zones favor turnkey arrangements.
- Healthcare Facilities:Infection control-critical environments requiring HEPA filtration, pressure differential management, and continuous environmental monitoring. ANSM oversight intersects with CNIL obligations where connected systems process occupancy and air quality data.
- Manufacturing Plants:Process cooling and comfort conditioning with heavy electrical loads and extended runtime requirements.
- Data Centers:Precision cooling infrastructure with 24/7 reliability demands and escalating power density challenges.
Commercial Buildings represent the largest addressable base, though Healthcare Facilities are climbing the fastest as regulatory compliance complexity deepens vendor stickiness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France commands pricing power over Provence-Alpes-Côte d'Azur due to concentrated Grand Paris Express ancillary development and tighter RE2020 enforcement timelines. Secondary corridors in Auvergne-Rhône-Alpes and Nouvelle-Aquitaine face installer certification bottlenecks that compress margin capture. Regional demand fragmentation shapes specification behavior across five distinct commercial HVAC corridors.
Île-de-France
Grand Paris Express station-adjacent commercial real estate generates concentrated demand for integrated climate control infrastructure. ANSM and CNIL oversight intersects where connected HVAC systems process occupancy data in healthcare and office developments. Parisian office stock retrofits dominate installation pipelines, with engineering-procurement-construction consortiums favoring turnkey performance-contracting arrangements.
Auvergne-Rhône-Alpes
Lyon commercial zones show concentrated demand for bundled energy-performance contracting that transfers operational risk to HVAC vendors. F-Gas Regulation compliance requires certified technician pools that remain underdeveloped in this secondary market. Carrier Corporation leverages its chiller service infrastructure to anchor long-term maintenance revenue across the corridor.
Provence-Alpes-Côte d'Azur
Hospitality sector operators are upgrading aging chiller infrastructure ahead of France's tightened F-Gas Regulation compliance deadlines. RE2020 thermal regulation thresholds tighten envelope-performance requirements for new coastal commercial construction. Daikin Airconditioning France dominates ductless and VRF specification channels through direct contractor training academies in Marseille and Nice.
Nouvelle-Aquitaine
Underpenetrated secondary urban corridors present first-mover advantages for VRF and ductless specification in mid-scale office developments. EU Green Deal heat pump acceleration redirects public and institutional procurement toward electrified heating infrastructure. Bordeaux and Toulouse commercial zones show emerging demand for smart HVAC subscription analytics platforms.
Occitanie
Mid-scale office developments in Montpellier and Toulouse generate specification volume for heat pump platforms substituting gas-fired boilers. Recovery and Resilience Facility funding harmonizes national subsidy structures for commercial electrification projects. Regional installer networks remain underdeveloped relative to F-Gas Regulation certification requirements.
France Commercial HVAC Market Competitive Landscape
Integrated solution providers and component specialists split the market along the axis of control-system sophistication versus equipment manufacturing scale. The vendor base concentrates around three strategic archetypes: full-stack building automation integrators, refrigerant-platform OEMs with captive distribution, and regional service-anchored contractors. Consolidation pressure intensifies as performance-contracting arrangements displace discrete equipment procurement. Dominant competitive moves include backward integration into predictive analytics software and geographic expansion through certified installer network acquisition.
Within the full-stack integration tier, Carrier Corporation and Johnson Controls International PLC exemplify archetypes combining equipment supply with long-term operational risk transfer. Daikin Airconditioning France occupies a position representing refrigerant-platform specialists with captive contractor development infrastructure. These three anchors illustrate how vendor strategy diverges between automation-layer control and compressor-technology specification dominance.
| Leading Market Players |
|---|
| Carrier Corporation |
| Johnson Controls International PLC |
| Trane Technologies PLC |
| Daikin Airconditioning France |
| Robert Bosch GmbH |
| Systemair AB |
| FlaktGroup Inc. |
| LG Electronics Inc. |
| BDR Thermea Group |
| Others |
Pricing and Supply Chain Analysis
Chinese compressor manufacturing concentration feeds directly into margin capture by OEMs with captive service networks across French commercial zones. Copper and aluminum coil pricing volatility from Chilean and Australian mining output reshapes procurement economics for rooftop unit producers serving cost-sensitive logistics developers.
Pricing Analysis
Configured-to-order chiller specifications command 25-40% premiums over standard rooftop unit pricing in French commercial developments. Price differentiation rests on F-Gas Regulation certification tiers and after-sales service bundling rather than raw equipment performance. Cost compression in economy-tier packaged units is intensifying because logistics park developers prioritize first-cost minimization over lifecycle efficiency. Healthcare and data center buyers exhibit lowest price sensitivity due to operational criticality mandates.
Supply Chain Analysis
EU export-control restrictions on fluorinated gas technologies limit refrigerant platform transfers to French OEM assembly operations. Manufacturing concentration in China, Germany, and Japan supplies compressor architectures and electronic expansion valves to French system integrators. Raw material dependencies on Chilean copper, Chinese rare earth magnets, and German precision bearings create tariff-exposure vulnerabilities. Distribution runs through engineering-procurement-construction consortiums that bundle equipment procurement with long-term maintenance obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France Commercial HVAC Market is recovering from cyclical compression as RE2020 thermal regulation enforcement triggers replacement demand across Parisian office stock.
For Market Incumbents: Build installer certification moats by acquiring training academy networks in Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur secondary markets. Consolidate service infrastructure to preempt F-Gas Regulation compliance bottlenecks that threaten incumbent revenue models. Channel control through direct contractor relationships represents the critical defensive lever against refrigerant-platform specialists. For New Entrants and Emerging Players: Nouvelle-Aquitaine and Occitanie commercial corridors offer underpenetrated specification windows for mid-scale office heat pump deployments. Target hospitality sector refresh cycles in coastal Provence-Alpes-Côte d'Azur markets where aging chiller infrastructure faces accelerated obsolescence. Go-to-market positioning through EU Green Deal subsidy harmonization unlocks public sector procurement channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional service contractors holding F-Gas Regulation certification capacity in underserved French corridors. Five-to-ten year viability hinges on regulatory compression sustaining equipment refresh momentum. Acquisition targets should demonstrate captive installer development infrastructure and predictive analytics platform deployment. Monitor refrigerant quota allocation mechanics as the inflection signal for margin expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Installer Certification Network Acquisition | F-Gas Regulation compliance bottlenecks in secondary markets create scarcity value for certified technician pools. |
| Predictive Analytics Platform Development | Smart HVAC subscription revenue captures recurring margin from multi-site retail and hospitality portfolios. |
| Refrigerant Platform Redesign | R-32 and R-454B compressor architectures open specification windows as high-GWP equipment faces obsolescence. |
| Performance Contracting Arrangement Expansion | Turnkey energy-performance contracts transfer operational risk and deepen vendor stickiness in Lyon and Marseille zones. |
| Secondary Market Geographic Expansion | Underpenetrated Nouvelle-Aquitaine and Occitanie corridors offer first-mover advantages for VRF and ductless specification. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with HVAC contractors, facilities managers at multi-site retail portfolios, engineering-procurement-construction consortium procurement leads, and OEM regional sales directors. Secondary validation drew from ANSM regulatory filings, CNIL data protection guidance, EU F-Gas Regulation quota publications, and French Ministry of Ecological Transition RE2020 technical documentation. Bottom-up equipment shipment analysis and top-down construction pipeline valuation were triangulated to establish market sizing.
Calibration against historical equipment replacement cycles and regulatory compliance deadline clustering anchored projection modeling across the analysis window. Segmentation dimensions included product type, building application, control technology platform, and regional construction pipeline density. CAGRs were derived from regression analysis linking regulatory enforcement timelines to equipment refresh elasticity, with heat pump substitution rates and smart HVAC penetration curves as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by refrigerant-platform specialists or accelerated subsidy harmonization beyond Recovery and Resilience Facility baselines would shift outcomes. Material shifts in F-Gas Regulation quota allocation mechanics or copper price volatility sustained beyond historical bands would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Asia-Pacific Compressor Market
HVAC Equipment
US Residential Heat Pump Market
HVAC Equipment
US HVAC Field Device Market
HVAC Equipment
Industrial Refrigeration Equipment Market
HVAC Equipment
Automatic Ducting Machine Market
HVAC Equipment
Asia-Pacific Heating Equipment Market
HVAC Equipment
Commercial Water Heater Market
HVAC Equipment
Global Fan Coil Unit Market
HVAC Equipment
US HVAC Systems Market
HVAC Equipment
HVAC Louvers Market
HVAC Equipment
HVAC Fan and Evaporator Coil Market
HVAC Equipment
Global Modular Chillers Market
HVAC Equipment
HVAC Centrifugal Compressors Market
HVAC Equipment
US HVAC Services Market
HVAC Equipment
North America Air Conditioning Equipment Market
HVAC Equipment
Centrifugal Chillers Market