
 Wall Covering Products Market | 2026-2036
Wall Covering Products Market Size, Share, and Industry Trends Forecast 2026-2036
Wall Covering Products Market Outlook
Skilled wallpaper installer availability is unwinding as a bottleneck across mature markets, prompting manufacturers to engineer simpler application systems. York Wallcoverings leverages peel-and-stick technology to capture DIY renovation spend. Graham & Brown anchors European supply through in-house design studios that control pattern-to-production cycles. Asian Paints Ltd. dominates South Asian distribution by sustaining dense dealer networks in secondary cities.
Wall covering products encompass decorative and protective surfacing materials applied to interior vertical structures, typically ranging in thickness from 0.2 mm for lightweight papers to 2.5 mm for heavy vinyl substrates, engineered to conceal substrate imperfections while managing indoor air quality through breathable or sealed surface properties. Vinyl products lead volume due to washability and cost efficiency in commercial settings, while fabric segments command premium positioning in hospitality specifications where acoustic performance and tactile finish differentiate room categories. Peel-and-stick installation methods are expanding fastest among residential renovators seeking to bypass professional labor costs, whereas traditional paste-applied papers retain share in heritage restoration and luxury residential applications.
FDA oversight of antimicrobial claims in healthcare-adjacent wall coverings, EPA VOC emission standards under TSCA Title VI, and EU REACH restrictions on phthalate plasticizers collectively constrain formulation choices and elevate compliance costs for cross-border suppliers. California's Department of Public Health Section 01350 and Germany's AgBB scheme further fragment certification requirements, forcing manufacturers to maintain multiple test protocols. Stakeholders must monitor evolving state-level chemical disclosure mandates and decide whether to regionalize production or absorb centralized certification overhead.
Market Dynamics
DIY installation systems are compressing demand for skilled labor across residential renovation, forcing manufacturers to redesign substrates for non-professional application while preserving commercial-grade durability standards.
Growth Catalysts
- EU Green Deal renovation targets:Binding building retrofit mandates across member states are redirecting procurement toward low-VOC substrates and recyclable vinyl alternatives.
- Peel-and-stick adhesives:Pressure-sensitive backing technologies are eliminating paste-mixing complexity and expanding addressable demand among time-constrained residential renovators.
- China tier-one hospitality fit-outs:Premium fabric wall covering specifications are concentrating in Shanghai and Beijing commercial developments where acoustic performance differentiates property valuations.
Market Restraints
- Phthalate plasticizer restrictions:EU REACH and US TSCA Title VI compliance are fragmenting formulation protocols and elevating cross-border certification overhead for vinyl substrate producers.
- Specialized installer scarcity:Master paperhanger apprenticeship programs have contracted across Germany and the United Kingdom, creating bottleneck risk for heritage restoration and luxury residential segments.
- Petrochemical feedstock volatility:PVC resin and plasticizer input costs oscillate with crude oil indices, compressing margin predictability for volume vinyl producers.
Strategic Opportunities
- Antimicrobial healthcare specifications:FDA-regiated surface claims in acute care and senior living facilities are opening premium positioning for copper-ion and silver-embedded substrates.
- Digital print-on-demand:Web-to-wall customization platforms are collapsing minimum order quantities and enabling designer-direct distribution models.
- India secondary city distribution:Dense dealer network expansion into Pune, Ahmedabad, and Kochi is capturing first-mover advantage in underpenetrated residential renovation markets.
Industry Challenges
- Multi-jurisdiction certification timelines:California Section 01350, Germany AgBB, and France VOC labeling schemes require parallel testing protocols that extend product launch cycles.
- Legacy paste-applied inventory rationalization:Traditional wallpaper stockkeeping units face obsolescence risk as retail shelf space reallocates to self-adhesive formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wall Covering Products Market |
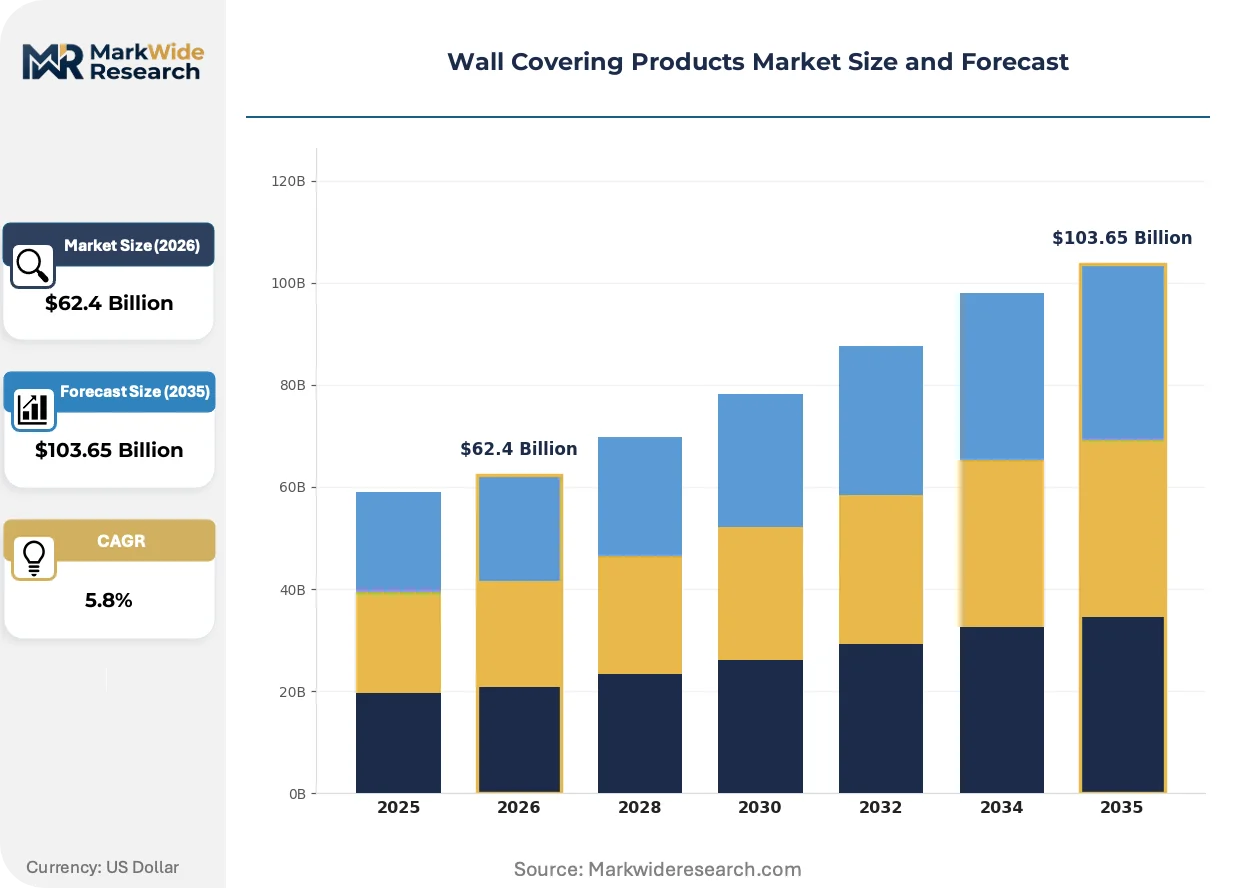
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $103.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
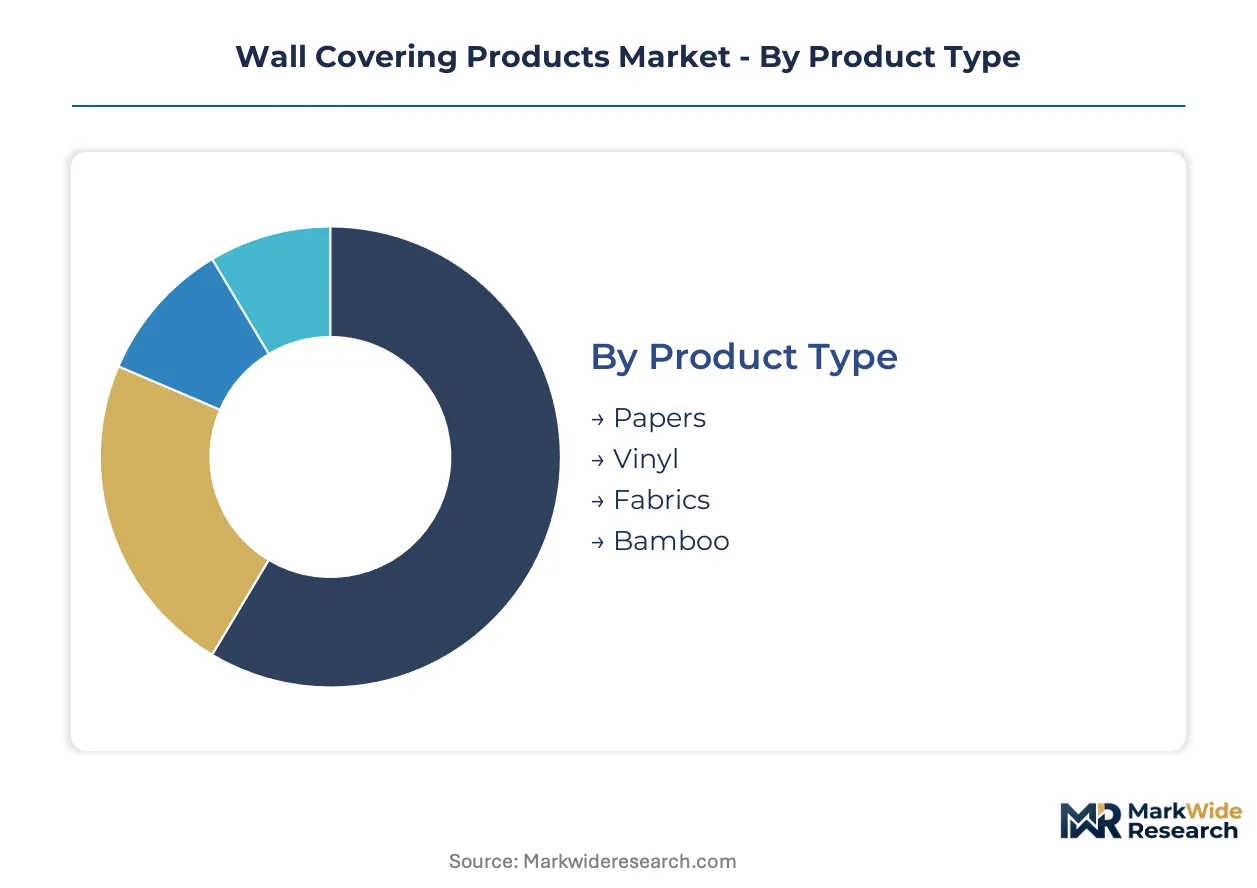
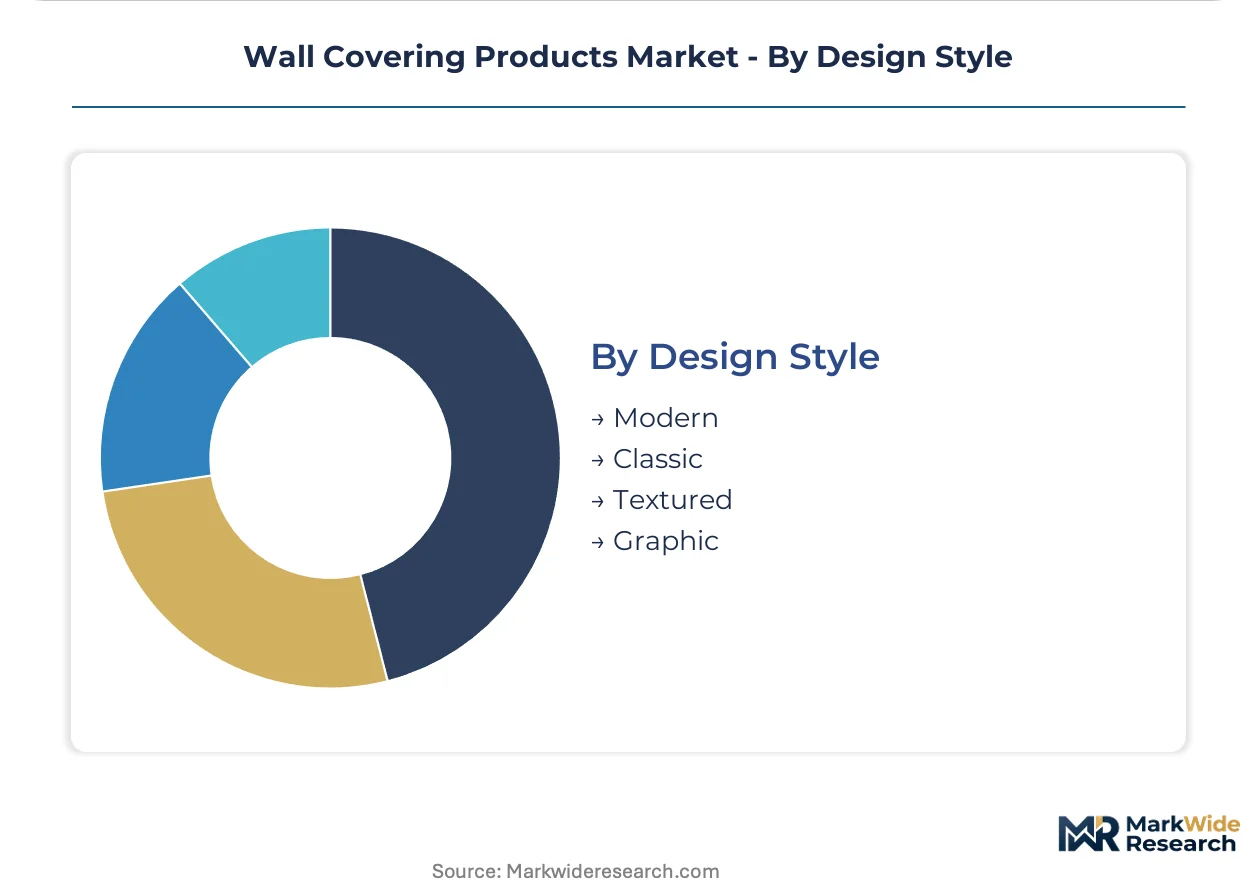
| Segmentation | Product Type: Papers, Vinyl, Fabrics, Bamboo Application: Residential, Commercial, Industrial, Hospitality Installation Method: Peel & Stick, Traditional, Adhesive, Pre-Pasted Design Style: Modern, Classic, Textured, Graphic |
| Companies Covered | F. Schumacher & Co., Crossville Inc., Sherwin-Williams Company, A.S. Création Tapeten AG, Asian Paints Ltd., York Wallcoverings, Benjamin Moore & Co., Graham & Brown, Brewster Home Fashions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wall Covering Products Market Strategic Shifts
Material science advances and installation simplification are converging to collapse the boundary between professional-grade performance and consumer-accessible application methods.
Peel-and-stick vinyl substrates with repositionable acrylic adhesives are supplanting traditional paste-applied papers in North American residential renovation. Home improvement retailers report self-adhesive SKUs expanding shelf allocation as DIY buyers prioritize speed over permanence. This shift is compressing demand for professional installation services while elevating substrate engineering requirements for clean removability.
EU REACH Annex XVII restrictions on phthalate plasticizers are forcing vinyl compound reformulation across European manufacturing. Producers are migrating to bio-based plasticizers and non-PVC alternatives including thermoplastic polyolefin substrates. Healthcare and education end-uses face the steepest compliance burden, with specifications now requiring full material disclosure to meet France's VOC emission labeling mandate.
Direct-to-consumer sampling programs are displacing traditional distributor showrooms for residential pattern selection. Millennial and Gen-Z buyers in the United States and United Kingdom now expect augmented reality visualization tools before committing to bulk orders. Hospitality procurement teams remain anchored to physical memo sampling, creating a bifurcated channel structure that manufacturers must serve through parallel fulfillment systems.
Wall Covering Products Market Segmentation
Wall covering procurement splits sharply between domestic renovation cycles and export-led hospitality specifications. Manufacturers engineer substrate formulations differently for these divergent demand channels.
Product Type:
Vinyl and fabric segments serve distinct geographic markets, with vinyl dominating domestic residential replacement cycles and fabrics capturing export-driven luxury hospitality fit-outs.
- Vinyl:PVC-based substrates with calendered or cast construction deliver washability and abrasion resistance for high-traffic commercial interiors. Demand concentrates in North American residential renovation where peel-and-stick formats bypass installer scarcity. REACH phthalate restrictions are forcing compound reformulation across European supply.
- Fabrics:Woven textile backings bonded to paper or non-woven carriers provide acoustic absorption and tactile warmth. Specifications cluster in China's tier-one cities where Shanghai and Beijing hospitality developers prioritize room-category differentiation. Premium positioning sustains margin despite longer lead times.
- Papers:Cellulose-based wall coverings with printed or embossed surfaces serve heritage restoration and budget residential segments.
- Bamboo:Grass-fiber substrates offer renewable positioning for eco-conscious commercial specifications in Japan and South Korea.
Vinyl commands the established base. The steepest expansion runs through fabrics.
Application:
Cost tier separation drives specification divergence, with premium acoustic and antimicrobial features concentrating in healthcare-adjacent commercial use.
- Residential:DIY-accessible formats dominate replacement demand as homeowners bypass professional labor. Peel-and-stick vinyl and pre-pasted papers capture renovation spend across US and UK markets. Digital sampling platforms are collapsing traditional distributor showroom dependence.
- Commercial:Washable vinyl and antimicrobial substrates serve education, healthcare, and corporate fit-outs where durability standards exceed residential thresholds. FDA-regulated surface claims open premium positioning for copper-ion embedded specifications in acute care facilities.
- Hospitality:Fabric wall coverings with custom pattern capabilities differentiate luxury property valuations. Procurement teams in Dubai, Singapore, and London maintain physical memo sampling requirements despite digital adoption elsewhere.
- Industrial:Heavy-gauge vinyl and reinforced substrates protect substrates in manufacturing and warehouse environments.
Residential absorbs the volume base. Hospitality delivers the margin expansion.
Installation Method:
Application complexity separates professional-dependent systems from consumer-accessible formats reshaping distribution economics.
- Peel & Stick:Pressure-sensitive acrylic adhesives enable repositioning and clean removability. Home improvement retailers in the United States and United Kingdom are reallocating shelf space toward these SKUs as DIY buyers prioritize speed. Substrate engineering now targets clean removal without substrate damage.
- Traditional:Paste-applied papers requiring skilled preparation retain position in heritage restoration and luxury residential where permanence and alignment precision matter. Master paperhanger apprenticeship contraction in Germany and the United Kingdom creates bottleneck risk.
- Adhesive:Site-mixed or ready-mixed paste systems serve commercial contractors with established installation crews.
- Pre-Pasted:Water-activated adhesives on paper backings bridge DIY accessibility with traditional material aesthetics.
Traditional methods anchor the skilled-labor segment. Peel-and-stick formats are climbing the fastest.
Design Style:
Customer type bifurcation separates specification-driven commercial procurement from emotionally-driven residential selection.
- Modern:Clean lines and minimal pattern repetition align with contemporary architecture in Scandinavian and East Asian markets. Digital print capabilities enable customization at reduced minimum order quantities.
- Textured:Three-dimensional surface treatments including grasscloth, silk, and embossed vinyl provide tactile differentiation for hospitality and luxury residential. Specifications concentrate in Dubai and Mumbai high-end developments.
- Classic:Damask, toile, and heritage patterns serve restoration and traditional residential aesthetics.
- Graphic:Bold-scale prints and mural formats leverage digital production for statement installations.
Classic patterns hold the replacement base. Textured treatments are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wall covering consumption patterns diverge sharply between geographies. Residential renovators in the United States favor self-adhesive vinyl formats, while European procurement teams prioritize low-emission certifications, and Chinese hospitality developers drive premium fabric specifications.
United States
DIY renovation cycles and peel-and-stick uptake dominate residential demand. EPA TSCA Title VI regulates formaldehyde emissions from composite wood substrates used in wall covering backings. Home improvement retailers in the Southeast and Southwest are reallocating shelf space toward self-adhesive SKUs as installer scarcity persists.
Germany
Heritage restoration and EU Green Deal building retrofit mandates sustain paste-applied paper demand. AgBB scheme compliance for VOC emissions creates certification overhead for imported vinyl substrates. Industrial clusters in North Rhine-Westphalia host compound reformulation facilities adapting to REACH Annex XVII phthalate restrictions.
China
Tier-one city hospitality fit-outs in Shanghai and Beijing concentrate premium fabric wall covering procurement. NMPA oversight of antimicrobial surface claims applies to healthcare-adjacent specifications. Yangtze River Delta manufacturing bases supply both domestic commercial projects and export-led luxury developments.
India
Secondary city residential renovation in Pune, Ahmedabad, and Kochi drives volume expansion. BIS standards for interior finishes create compliance benchmarks for imported substrates. Dense dealer networks in Maharashtra and Gujarat capture first-mover advantage in underpenetrated markets.
United Kingdom
Digital sampling platforms and augmented reality tools reshape residential pattern selection. HSE workplace exposure limits influence adhesive formulation choices for commercial installers. London and Southeast England hospitality procurement maintains physical memo sampling requirements despite digital adoption elsewhere.
Wall Covering Products Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the former controlling pattern-to-production cycles and the latter dominating regional distribution niches. The market structure rewards design studio capabilities in Europe and dense dealer networks in South Asia. Three archetypes prevail: vertically integrated manufacturers with in-house design control, regional distributors with localized logistics, and digital-native platforms collapsing traditional sampling economics. Competitive moves center on substrate reformulation for regulatory compliance and direct-to-consumer channel expansion.
Among European specialists, A.S. Création Tapeten AG and Graham & Brown exemplify the design-integrated archetype through controlled pattern-to-production workflows. York Wallcoverings represents North American adaptation to installer scarcity via peel-and-stick engineering. Asian Paints Ltd. anchors South Asian distribution density through secondary city dealer networks.
| Leading Market Players |
|---|
| F. Schumacher & Co. |
| Crossville Inc. |
| Sherwin-Williams Company |
| A.S. Création Tapeten AG |
| Asian Paints Ltd. |
| York Wallcoverings |
| Benjamin Moore & Co. |
| Graham & Brown |
| Brewster Home Fashions |
| Others |
Value Chain & Pricing Dynamics
Bio-based plasticizer substitution for phthalate-laden PVC compounds simultaneously redistributes manufacturing toward North Rhine-Westphalia reformulation clusters and compresses margin structures for volume vinyl producers unable to pass compliance costs downstream.
Pricing Analysis
Long-term offtake contracts with hospitality developers anchor premium fabric pricing, while spot-market transactions dominate residential vinyl procurement. Three-tier pricing structure across premium acoustic fabrics, standard commercial vinyl, and economy paper grades reflects certification grade and volume scale differentiation. Pricing pressure stems from petrochemical feedstock volatility that erodes margin predictability for PVC resin-dependent producers. Residential renovators exhibit highest price sensitivity, whereas healthcare procurement teams absorb premium antimicrobial specifications with minimal elasticity.
Supply Chain Analysis
Strategic stockpile preferences concentrate among European manufacturers hedging against REACH Annex XVII compliance timelines, while North American retailers favor just-in-time replenishment of fast-turning peel-and-stick SKUs. Raw material sourcing draws from Yangtze River Delta PVC resin production, German plasticizer compounding facilities, and Italian textile weaving centers. Single-source vulnerability runs through concentrated acrylic adhesive supply for pressure-sensitive backings. Distribution runs through home improvement retail chains in the United States, dense dealer networks in India, and specification-driven contract channels in Gulf hospitality markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among large-format home improvement retailers and hospitality procurement consortia, compressing supplier margins and elevating channel control as the decisive competitive variable.
For Market Incumbents: Shield market position by accelerating in-house bio-based plasticizer compounding to capture REACH compliance premiums before reformulation costs fully transmit downstream. Anchor channel control through exclusive SKU development with Home Depot and Lowe's, while investing in digital sampling infrastructure to bypass traditional distributor economics. Vertical integration into adhesive backing production mitigates single-source vulnerability.
For New Entrants and Emerging Players: EU Green Deal certification fast-track offers entry pathway for low-VOC substrate specialists lacking legacy phthalate inventory burdens. White-space concentration sits in India's secondary city dealer networks where Asian Paints Ltd. has not yet achieved saturation density. Direct-to-consumer augmented reality sampling platforms collapse traditional showroom capital requirements.
For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors vertically integrated design studios with captive pattern-to-production workflows. Long-term viability hinges on controlling formulation IP as compliance costs stratify the supplier base. Acquisition targets should exhibit established AgBB or Section 01350 certification pipelines. The signal to watch is master paperhanger apprenticeship program expansion or contraction as indicator of traditional segment recovery or terminal decline.
| Strategic Initiative | Industry Significance |
|---|---|
| Peel-and-Stick Substrate Engineering | Captures DIY renovation spend bypassing installer scarcity in North American residential markets. |
| REACH-Compliant Compound Reformulation | Preserves European market access as AgBB and France VOC labeling tighten emission standards. |
| Digital Print-on-Demand Platform Launch | Collapses minimum order quantities and enables designer-direct distribution in hospitality specification. |
| Secondary City Dealer Network Expansion | Captures first-mover advantage in underpenetrated Indian markets beyond Maharashtra and Gujarat saturation. |
| Antimicrobial Surface Certification Investment | Opens premium positioning in FDA-regulated acute care and senior living facility specifications. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with wall covering manufacturers, hospitality procurement directors, home improvement retail category managers, and master paperhanger trade associations; and secondary validation through EPA TSCA Title VI filings, EU ECHA REACH registrations, customs trade databases for PVC resin and textile imports, and SEC 10-K disclosures from listed building materials companies. Bottom-up demand modeling across installation methods and application segments triangulated against top-down macroeconomic drivers.
The projection horizon spans the full analysis window with segmentation across product type, application, installation method, and design style dimensions. CAGRs were derived from historical shipment data and forward-looking regulatory implementation timelines. Forecast inputs incorporated EU Green Deal building retrofit mandates, tier-one Chinese hospitality development pipelines, and petrochemical feedstock price trajectory assumptions.
Decision-makers should treat outputs as directional under sustained regulatory enforcement and stable raw material supply assumptions; material deviation would warrant model refresh. Revision becomes warranted when phthalate restriction implementation accelerates or when master paperhanger labor availability crosses critical thresholds affecting heritage restoration segment viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Middle East Revolving Doors Market
Homecare and Decor
Wall Art Market
Homecare and Decor
Corner Pads Market
Homecare and Decor
Flush Door Market
Homecare and Decor
India Wallpapers Market
Homecare and Decor
Fragrant Drawer Liners Market
Homecare and Decor
United States Decorative Laminates Market
Homecare and Decor
Revolving Doors Market
Homecare and Decor
Europe Decorative Laminates Market
Homecare and Decor
India Furniture Hardware Market
Homecare and Decor
Door Stopper Market
Homecare and Decor
Bifold Door Market
Homecare and Decor
Online Home Decor Market
Homecare and Decor
Europe Mattress Market
Homecare and Decor
Balcony Accessories Market
Homecare and Decor
Wall Clock Market