
 India Furniture Hardware Market | 2026-2036
India Furniture Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
India Furniture Hardware Market Insights
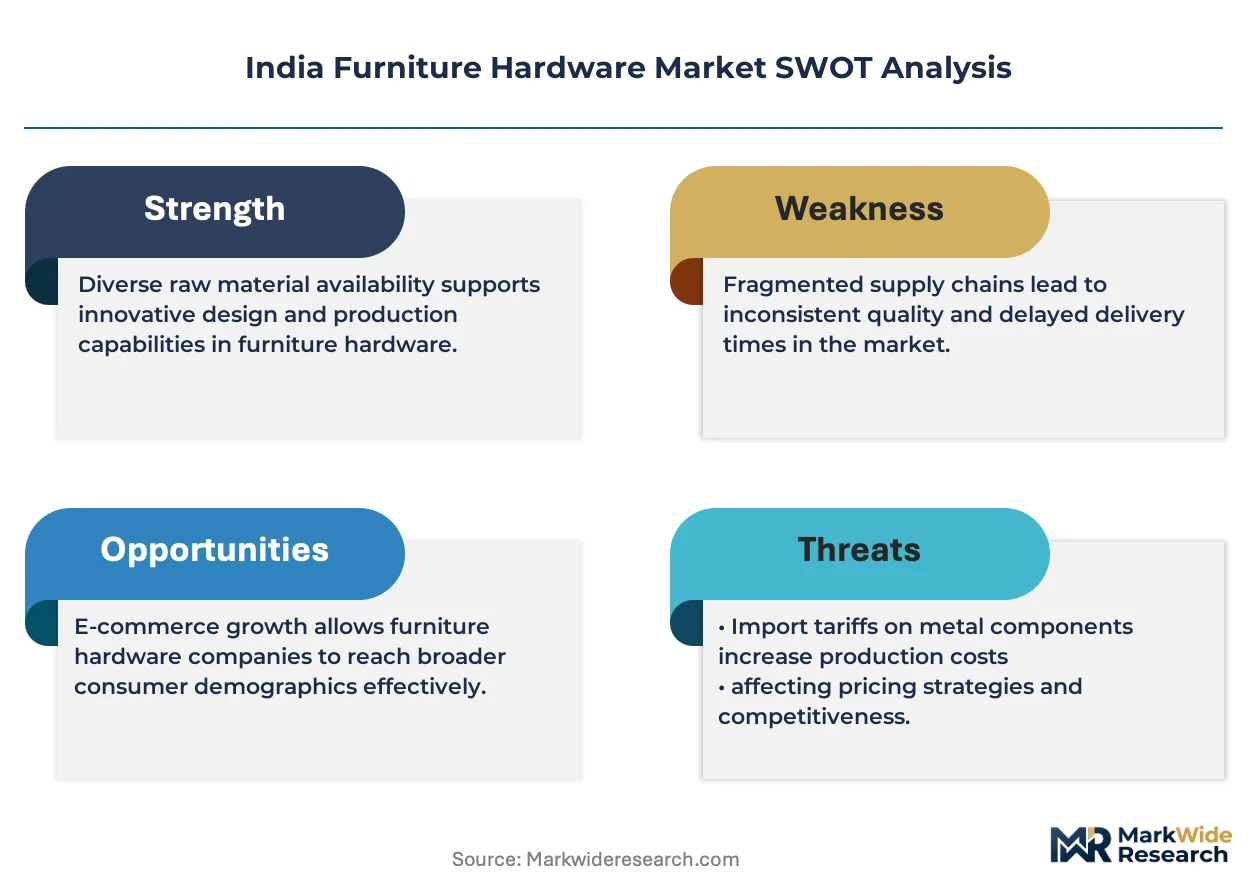
BIS IS 9000 certification for furniture fittings is bifurcating the competitive landscape between organized and unorganized manufacturers. Hettich India Pvt. Ltd leverages its German engineering pedigree to dominate premium channel access in metropolitan markets. Häfele India Pvt. Ltd. sustains R&D intensity through its Bangalore technical center, specializing in soft-close hinge systems. Godrej Locks & Architectural Fittings & Systems anchors mass-market penetration through its established distribution network across tier-2 and tier-3 cities.
Furniture hardware encompasses mechanical and electromechanical components including hinges, drawer slides, locks, and latches fabricated from cold-rolled steel, zinc alloys, and engineering polymers, designed to enable motion control, security, and ergonomic access in cabinetry and seating systems. The residential application segment leads volume absorption as urban apartment dwellers prioritize space-optimized storage solutions. Steel material grades command the largest share of raw material offtake due to cost efficiency and load-bearing performance, while aluminum gains traction in premium hospitality fit-outs where corrosion resistance and finish aesthetics justify higher unit economics.
BIS mandates under the Compulsory Registration Scheme govern furniture hardware quality parameters, while the CDSCO regulates antimicrobial coating claims on institutional-grade fittings. State-level municipal building codes in Maharashtra, Karnataka, and Telangana increasingly specify fire-rated hardware for commercial high-rises, redirecting procurement toward certified suppliers. Stakeholders must monitor evolving PLI scheme eligibility for precision metal components and assess backward integration into zinc die-casting capacity as import substitution pressures intensify.
Market Dynamics
BIS IS 9000 certification mandates are compressing competitive margins for unorganized manufacturers while creating procurement preference tiers among institutional buyers across Maharashtra, Gujarat, and Karnataka.
Growth Catalysts
- Residential modular kitchen expansion:Urban apartment construction in Mumbai, Bengaluru, and Delhi NCR corridors is absorbing volume for soft-close hinges and tandem box systems as space-optimized storage becomes standard.
- CDSCO antimicrobial coating claims:Institutional-grade hardware for healthcare and educational facilities now carries verified antimicrobial specifications, opening premium procurement channels.
- PLI scheme eligibility for precision metal components:Domestic manufacturers are qualifying for production-linked incentives on zinc die-cast and cold-rolled steel fabrication, reducing import dependency.
Market Restraints
- Zinc alloy price volatility:Die-cast hardware producers face margin compression from fluctuating zinc ingot costs, with limited pass-through power against large-format retailers.
- Import concentration for high-grade polymers:Engineering plastics for silent-motion drawer systems remain concentrated in East Asian supply chains, exposing lead time risks.
- Fire-rated hardware technical limitations:Current domestic testing infrastructure cannot certify beyond 90-minute fire ratings, constraining high-rise commercial participation.
Strategic Opportunities
- Tier-2 and tier-3 city underpenetration:Pune, Ahmedabad, and Hyderabad retail corridors show insufficient organized hardware distribution relative to residential construction permits.
- Smart furniture convergence:Electromechanical locking systems integrating with home automation protocols represent unclaimed white space in premium residential projects.
- Maharashtra municipal fire code expansion:State-level mandates for certified hardware in commercial buildings above 15 stories are redirecting specification authority toward BIS-registered suppliers.
Industry Challenges
- Tool and die skill scarcity:Precision stamping and progressive die operations lack trained operators in the Nagpur and Rajkot manufacturing clusters.
- BIS certification timeline compression:Laboratory queue times for IS 9000 testing extend beyond six months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Furniture Hardware Market |
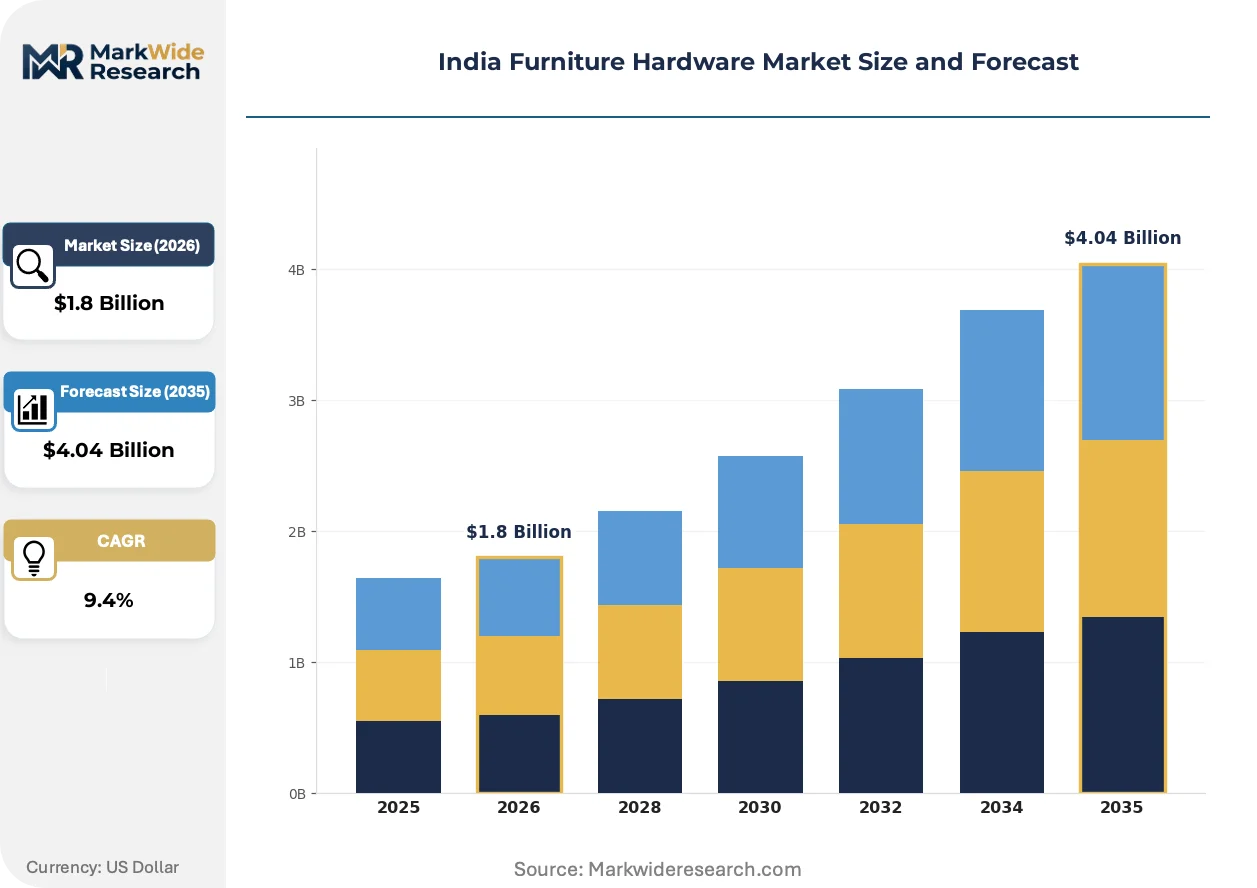
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hinges, Locks, Drawer Slides, Latches Material: Steel, Aluminum, Plastic, Brass Application: Residential, Commercial, Institutional, Hospitality Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Hettich India Pvt. Ltd, Häfele India Pvt. Ltd., Godrej Locks & Architectural Fittings & Systems, Ebco Pvt. Ltd., Ozone Overseas Pvt. Ltd., Olive World, Greenply Industries, Supreme Hardware, Star Hardware, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Furniture Hardware Market Trends and Innovations
Hardware functionality is migrating from mechanical reliability toward integrated motion control and connected access systems, with material science and regulatory compliance as parallel innovation vectors.
Concealed hinge systems with three-dimensional adjustment capabilities are miniaturizing cabinet door hardware footprints while maintaining load ratings. Premium residential developers in Gurugram and Noida are specifying these for seamless aesthetic integration. The technology is compressing visible hardware surface area by over half compared to traditional butt hinges.
BIS Compulsory Registration Scheme phase-ins are tightening quality documentation requirements for all furniture fittings sold in India. Manufacturers must now maintain batch traceability records and third-party audit compliance. Small-scale producers in Moradabad and Aligarh are consolidating or exiting as certification costs mount.
Project developers are unbundling hardware specification from general contractor procurement, creating direct relationships with certified suppliers. Large residential developers in Mumbai now maintain approved vendor lists with pre-negotiated rates. This pattern is most visible in build-to-rent apartment complexes where lifecycle cost calculations override first-cost minimization.
India Furniture Hardware Market Segmentation
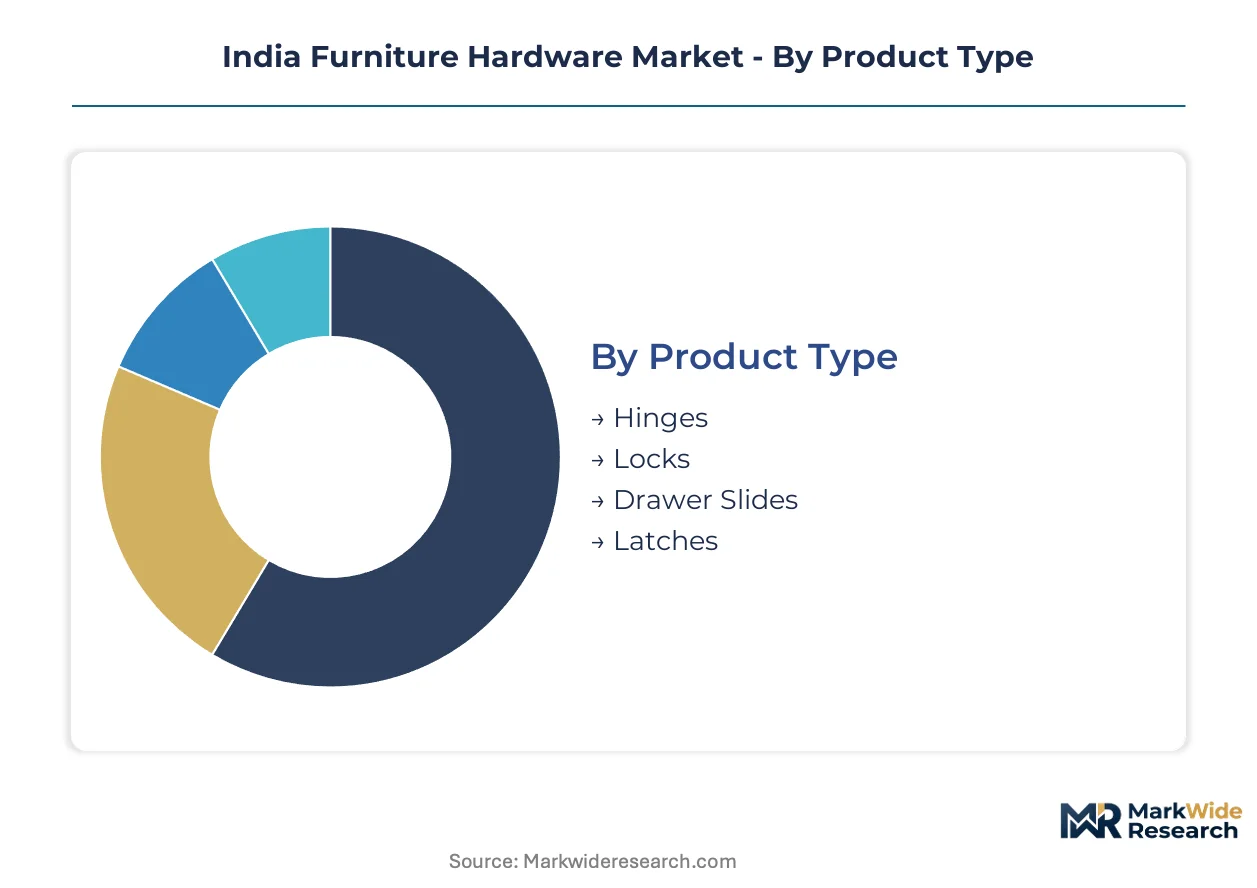
Segmentation in the India furniture hardware market reveals how specification authority and procurement power concentrate across distinct buyer types and material grades. Understanding these divisions exposes where margin pools form and which channels absorb volume at scale.
Product Type:
Channel mix varies sharply by hardware category, with hinges and drawer slides flowing through organized retail while locks and latches concentrate in wholesale distribution to contractors.
- Hinges:Mechanical assemblies fabricated from cold-rolled steel with zinc plating, enabling door articulation through pivot or concealed mounting configurations. Demand clusters in Mumbai and Bengaluru residential towers where soft-close specifications are becoming standard in modular kitchens.
- Drawer Slides:Tandem box and undermount systems fabricated from galvanized steel with polymer glide elements, supporting dynamic load ratings. Pune and Hyderabad furniture manufacturers are specifying these for space-optimized storage in compact urban apartments.
- Locks:Cylindrical and mortise mechanisms for security applications across residential and commercial entry points.
- Latches:Spring-loaded and magnetic closure devices for cabinet doors and access panels in high-traffic institutional settings.
Hinges dominate installed base. Drawer slides are where expansion concentrates.
Material:
Cost tier stratification separates commodity-grade steel from premium aluminum and brass, with plastic gaining traction in budget hospitality fit-outs where replacement cycles are shorter.
- Steel:Cold-rolled and galvanized grades form the backbone of mass-market hardware production, offering strength-to-cost ratios that satisfy BIS IS 9000 structural requirements. Maharashtra and Gujarat fabricators consume the majority of domestic steel hardware offtake for residential cabinetry.
- Aluminum:Extruded and die-cast grades deliver corrosion resistance and finish consistency for premium commercial and hospitality applications. Bengaluru hotel developers specify these for coastal properties where salt exposure degrades ferrous alternatives.
- Plastic:Engineering polymers and glass-filled nylon reduce weight and noise in drawer systems and decorative hardware.
- Brass:Cast and forged grades serve decorative and antimicrobial applications in heritage restoration and healthcare facilities.
Steel commands volume leadership. Aluminum is climbing the fastest on value metrics.
Application:
Customer type determines specification complexity, with institutional buyers demanding certified fire-rated hardware while residential developers prioritize cost-engineered solutions through direct supplier relationships.
- Residential:Single-family homes, apartments, and villas requiring space-optimized storage hardware. Delhi NCR corridor developers are unbundling hardware procurement from general contracting, creating direct vendor relationships for lifecycle cost optimization.
- Commercial:Offices, retail spaces, and mixed-use developments with high-cycle durability requirements. Maharashtra municipal codes now mandate certified hardware for buildings exceeding 15 stories, redirecting procurement toward BIS-registered suppliers.
- Institutional:Healthcare and educational facilities with antimicrobial and accessibility specifications governed by CDSCO coating claims.
- Hospitality:Hotels and serviced apartments where aesthetic finish and corrosion resistance justify premium material selection.
Residential absorbs the greatest unit volume. Commercial is where certification requirements are tightening fastest.
Distribution Channel:
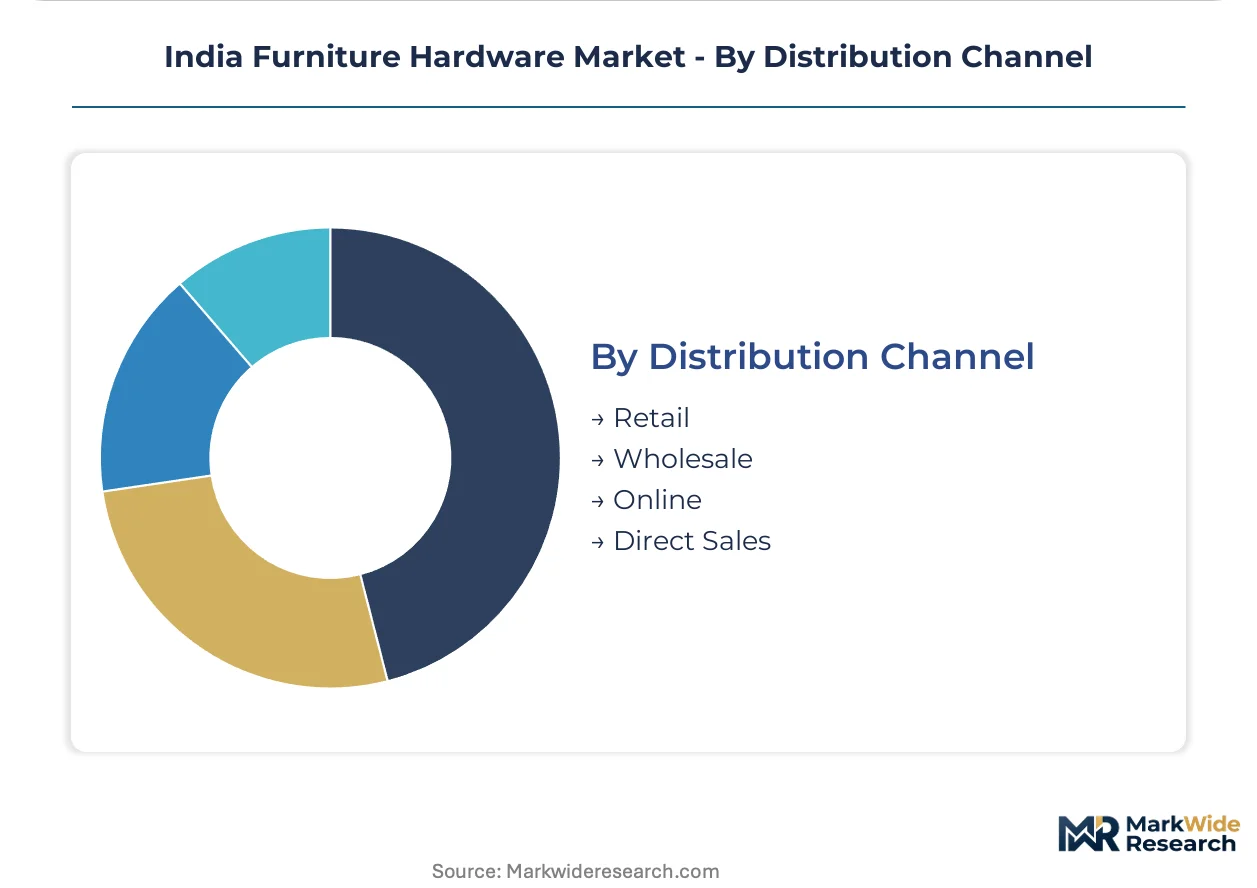
Volume concentration runs through wholesale networks serving tier-2 and tier-3 cities, while metropolitan markets show accelerating online penetration for replacement and upgrade purchases.
- Retail:Organized home improvement chains and specialty hardware stores with certified product displays. Ahmedabad and Chennai retail corridors are expanding organized hardware sections as residential construction permits rise.
- Wholesale:Distributor networks supplying contractors and furniture manufacturers with volume pricing and project-specific logistics. Rajkot and Moradabad wholesale hubs remain critical for unbranded hardware offtake despite BIS consolidation pressures.
- Online:E-commerce platforms capturing replacement demand and small-project specifications in metropolitan markets.
- Direct Sales:Manufacturer relationships with large developers and hospitality chains for new construction and renovation projects.
Wholesale maintains the deepest reach. Online is gaining share fastest in replacement segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives for precision metal components are redistributing manufacturing capacity across Indian states, with state-level BIS enforcement tightening procurement standards in commercial construction corridors.
Maharashtra
Mumbai residential towers and Pune furniture manufacturing clusters absorb the largest volume of soft-close hinges and tandem box systems. State municipal building codes mandate certified fire-rated hardware for structures exceeding fifteen stories. The Nashik-Rajkot industrial corridor hosts die-casting facilities serving organized retail channels.
Gujarat
Ahmedabad's modular kitchen fabricators and Surat's hospitality fit-out specialists drive demand for corrosion-resistant aluminum hardware. BIS IS 9000 certification timelines compress margins for Moradabad-sourced suppliers attempting market entry. The Gandhinagar tooling cluster faces acute shortages of progressive die operators.
Karnataka
Bengaluru's build-to-rent apartment developers unbundle hardware procurement from general contracting, creating direct supplier relationships. CDSCO antimicrobial coating claims govern institutional procurement for healthcare and educational facilities. The Peenya industrial estate concentrates precision stamping capacity for export-oriented OEMs.
Delhi NCR
Gurugram and Noida premium residential developers specify concealed hinge systems with three-dimensional adjustment capabilities. State-level fire safety regulations redirect commercial high-rise procurement toward BIS-registered suppliers. The Faridabad hardware wholesale hub serves tier-2 and tier-3 distribution networks across North India.
Telangana
Hyderabad's expanding retail corridor shows insufficient organized hardware distribution relative to residential construction permit growth. Municipal building codes increasingly specify certified hardware for commercial developments. The Jeedimetla industrial area hosts zinc die-casting operations supplying mass-market cabinetry manufacturers.
India Furniture Hardware Market Competitive Landscape
Player mix skews toward organized multinational subsidiaries with premium channel access, tier-1 domestic conglomerates with mass-market distribution depth, and regional fabricators facing consolidation pressure from BIS compliance costs. Strategic archetypes separate engineering-led premium specialists, scale-driven volume manufacturers, and unbranded commodity producers. Dominant competitive moves include backward integration into zinc die-casting capacity and direct developer relationship cultivation bypassing traditional wholesale channels.
Among Germany-based engineering specialists, Hettich India Pvt. Ltd and Häfele India Pvt. Ltd occupy positions exemplifying premium-tier positioning through metropolitan retail access and technical center investments. Godrej Locks & Architectural Fittings & Systems anchors the domestic conglomerate archetype with established tier-2 and tier-3 distribution networks. These three represent the structural divide between import-dependent premium positioning and mass-market penetration strategies.
| Leading Market Players |
|---|
| Hettich India Pvt. Ltd |
| Häfele India Pvt. Ltd. |
| Godrej Locks & Architectural Fittings & Systems |
| Ebco Pvt. Ltd. |
| Ozone Overseas Pvt. Ltd. |
| Olive World |
| Greenply Industries |
| Supreme Hardware |
| Star Hardware |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for zinc die-cast components concentrate procurement leverage with Maharashtra-based fabricators while compressing margins for Moradabad suppliers lacking BIS certification. This lead-time band feeds directly into pricing power stratification across organized retail versus wholesale channels.
Pricing Analysis
Cost-plus contracts with London Metal Exchange zinc indexation dominate long-term supply agreements between die-casters and hardware assemblers. Price differentiation rests on BIS IS 9000 certification grade and volume scale, with certified suppliers commanding premium positioning against unbranded competitors. Pricing pressure intensifies in the mass-market steel hinge segment as Godrej's distribution depth forces margin compression on regional players. Large-format retailers show lowest price sensitivity due to lifecycle cost frameworks, while tier-3 contractor channels remain highly elastic.
Supply Chain Analysis
China and South Korea anchor engineering polymer production for silent-motion drawer systems, while domestic Maharashtra and Gujarat clusters handle zinc die-casting and cold-rolled steel stamping. Raw material dependencies center on zinc ingots, cold-rolled steel coils, and glass-filled nylon compounds. Single-source vulnerability concentrates in high-grade polymer imports from East Asian suppliers. Distribution runs through Rajkot and Moradabad wholesale hubs serving tier-2 and tier-3 furniture manufacturers, with direct sales channels gaining share among Mumbai and Bengaluru developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through direct procurement unbundling by Delhi NCR and Bengaluru residential developers, fragmenting traditional wholesale channel control. Large developers now maintain approved vendor lists with pre-negotiated lifecycle terms.
For Market Incumbents: Consolidate backward integration into captive zinc die-casting capacity in Nashik and Rajkot to offset ingot price volatility. Deepen BIS certification moats through third-party audit investments, recognizing that six-month laboratory queue times now delay competitor product launches. Lock in direct developer relationships in Maharashtra and Karnataka before municipal fire code mandates fully redirect procurement authority. For New Entrants and Emerging Players: Anchor in Hyderabad's underpenetrated retail corridor where organized hardware distribution lags residential construction permit growth. Target smart furniture convergence for electromechanical locking systems in Gurugram premium projects, where home automation protocol integration remains unclaimed white space. Pursue project-specific direct sales rather than wholesale channel buildout to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned Moradabad and Aligarh fabricators facing BIS compliance cost pressures. Long-term viability favors precision stamping specialists with Nagpur or Rajkot facility footprints and existing OEM relationships. Watch for PLI scheme eligibility announcements on precision metal components as the inflection signal for domestic capacity investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Die-Casting | Captive ingot processing in Nashik-Rajkot corridor insulates margin from LME volatility. |
| BIS IS 9000 Certification Investment | Third-party audit compliance creates six-month queue barrier against unorganized competitors. |
| Direct Developer Relationship Cultivation | Bypassing wholesale channels captures lifecycle pricing power in Mumbai and Bengaluru towers. |
| Smart Lock Electromechanical Development | Home automation protocol integration opens premium residential specification in Gurugram and Noida. |
| Tier-2/Tier-3 Distribution Expansion | Pune, Ahmedabad, and Hyderabad retail corridors show construction-permit-to-distribution mismatch. |
Research Methodology
A spread of perspectives from furniture manufacturer procurement heads, organized retail category managers, BIS certification laboratory directors, zinc die-casting plant engineers, and municipal building code enforcement officers converged on the working assumptions. Secondary validation drew from BIS compulsory registration databases, CDSCO antimicrobial coating filings, Maharashtra and Karnataka municipal building code amendments, and PLI scheme precision component eligibility notifications. Bottom-up demand modeling from residential construction permit data triangulated against top-down hardware absorption estimates across the analysis window.
Segmentation dimensions modeled include product type, material grade, application category, and distribution channel across the projection horizon. CAGRs were derived from regression analysis on historical absorption patterns and forward projection of regulatory mandate phase-ins. Industry-specific forecast inputs incorporated BIS certification timeline compression effects and PLI scheme capacity addition assumptions for domestic zinc die-casting.
Material uncertainties — zinc price volatility, polymer import lead time disruptions, and municipal fire code enforcement variance — sit outside the modeled envelope. Forecasts reflect documented assumptions on certification adoption curves and developer procurement unbundling velocity. Recalibration cycles align with material shifts in PLI scheme notifications and state-level building code amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
MDF Decorative Overlays Market
Homecare and Decor
Japan Sustainable Home Decor Market
Homecare and Decor
Composite Doors and Windows Market
Homecare and Decor
Mattresses and Accessories Market
Homecare and Decor
United States Decorative Laminates Market
Homecare and Decor
Asia-Pacific Decor Paper Market
Homecare and Decor
Global Decorative Panels Market
Homecare and Decor
New Zealand Window Covering Market
Homecare and Decor
Saudi Arabia Interior Design Market
Homecare and Decor
US Mattress Bases Market
Homecare and Decor
Europe Mattress Market
Homecare and Decor
Wall Clock Market
Homecare and Decor
Middle East and Africa Christmas Tree Market
Homecare and Decor
Door Stopper Market
Homecare and Decor
Builders and Cabinet Hardware Market
Homecare and Decor
Stained Glass Market