
 Revolving Doors Market | 2026-2036
Revolving Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Revolving Doors Market Analysis
Integration of sensor-driven automation and low-energy drive systems is tilting revolving door engineering toward intelligent building ecosystems. ASSA ABLOY leverages its access control heritage to embed biometric compatibility into entrance solutions. dormakaba Group anchors European specifications with heavy R&D allocation to fire-rated revolving systems. Boon Edam dominates premium airport installations through custom wing configurations and climate-optimized airlocks.
Revolving doors are electromechanical entrance systems comprising radially arranged wings rotating within a cylindrical enclosure, typically engineered with 2.1 to 3.6 meter diameters and brush-sealed perimeter gaps to minimize air infiltration. Their primary commercial purpose is to reduce HVAC load while maintaining continuous pedestrian flow in high-traffic structures. Automatic revolving doors command the largest installed base among product types, though security revolving doors with interlocking tailgate detection represent the fastest-expanding margin pool. Aluminum and glass material combinations lead specification sheets for commercial buildings and airports, while stainless steel persists in retrofit applications where durability outweighs aesthetic refresh.
CE marking under the EU Construction Products Regulation governs structural safety and energy performance for revolving doors sold across Europe, while ECHA REACH compliance restricts hazardous substances in surface coatings and drive system lubricants. The EU Green Deal's building renovation targets directly expand retrofit installation demand by mandating thermal performance upgrades in existing commercial stock. Stakeholders must weigh sensor interoperability standards against cybersecurity exposure as building automation networks converge.
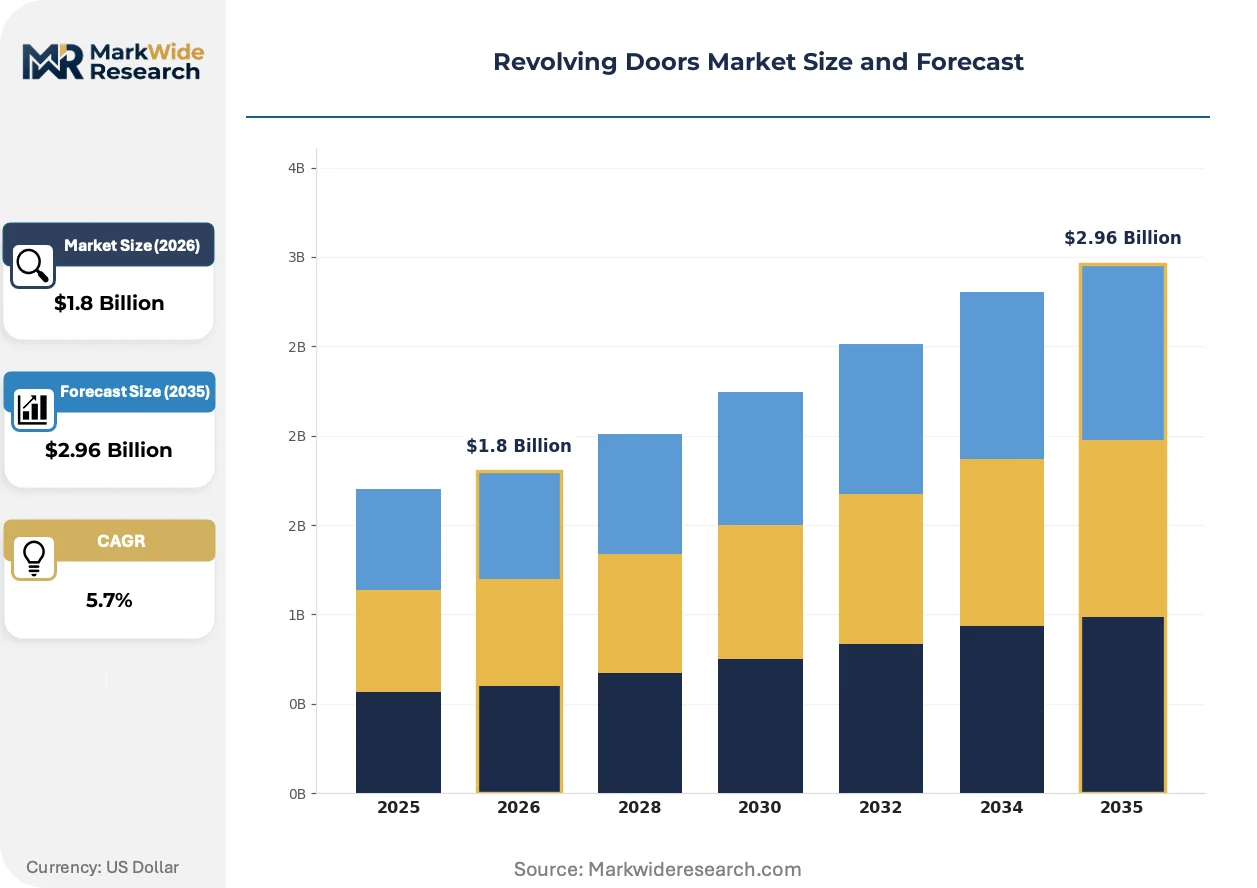
Market Dynamics
The EU Green Deal's building renovation wave is compressing specification cycles as developers in Germany, France, and the United Kingdom race to meet tightening thermal performance mandates through entrance system retrofits.
Growth Catalysts
- Airport infrastructure modernization:Climate-controlled passenger terminals in Frankfurt, Paris, and London demand high-throughput entrance solutions that seal against HVAC loss during peak traffic periods.
- REACH compliance-driven material substitution:ECHA restrictions on hazardous coatings and lubricants accelerate adoption of water-based surface treatments and bio-derived drive system fluids.
- Sensor fusion architecture:Biometric access modules and presence detection arrays integrate revolving doors into building automation networks, creating specification pull from intelligent building developers.
Market Restraints
- Aluminum price volatility:Wing frame and canopy fabrication depends on primary aluminum ingot costs that fluctuate with LME trading patterns and smelter energy surcharges.
- Drive system supplier concentration:Precision gearmotor production clusters in southern Germany and northern Italy, creating lead time vulnerability for non-European door assemblers.
- Manual door substitution:Low-traffic retail and small office buildings specify sliding or swing alternatives where capital constraints outweigh energy recovery benefits.
Strategic Opportunities
- Fire-rated revolving system expansion:Dormakaba Group and ASSA ABLOY R&D allocations target certified smoke containment solutions for high-rise atrium applications under evolving EU construction safety codes.
- Service contract unbundling:Predictive maintenance subscriptions using vibration and current-draw analytics create recurring revenue streams separate from hardware procurement.
- Netherlands and Belgium retrofit penetration:Older commercial stock in Rotterdam, Amsterdam, and Brussels remains underconverted relative to German thermal upgrade rates, leaving specification white space.
Industry Challenges
- Cybersecurity certification complexity:Network-connected automatic doors must demonstrate IEC 62443 compliance for building automation integration, extending commissioning timelines.
- Skilled installation technician scarcity:Precision alignment of 3.6-meter diameter wings with brush-sealed perimeter gaps requires certified mechanics whose training pipelines lag demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Revolving Doors Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Revolving Doors, Automatic Revolving Doors, Security Revolving Doors, Bi-parting Revolving Doors Material: Glass, Aluminum, Stainless Steel, Wood Use Case: Commercial Buildings, Airports, Hotels, Retail Outlets Installation Type: New Construction, Retrofit, Upgrades, Custom Installations |
| Companies Covered | GEZE, Horton Automatics, ASSA ABLOY, TORMAX USA, Stanley Access Technologies, dormakaba Group, KONE, Manusa, Boon Edam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Revolving Doors Market Emerging Trajectories
Digital twin architectures and predictive maintenance algorithms are compressing service response times while sensor density transforms entrance systems from passive hardware into data collection nodes.
LiDAR-based presence detection is virtualizing the safety perimeter around revolving door wings. Airport terminal operators in Frankfurt and Charles de Gaulle specify these arrays to eliminate mechanical safety edges and reduce maintenance callouts. The technology is virtualizing traditional electromechanical limit switches and enabling centimeter-precision passenger flow analytics.
CE marking under the EU Construction Products Regulation now requires documented energy performance testing for revolving doors sold across member states. Manufacturers must submit thermal transmittance calculations and air infiltration rates to notified bodies before market placement. German specification engineers increasingly filter supplier shortlists by published U-value certificates, compressing competitive differentiation around documented thermal metrics.
Specification authority is migrating from general contractors to specialized facade consultants who bundle entrance systems with curtain wall packages. London and Paris development projects now see revolving doors specified through envelope performance guarantees rather than standalone procurement. This concentration of buying power favors suppliers with integrated climate modeling capabilities and certified installation networks.
Revolving Doors Market Segmentation
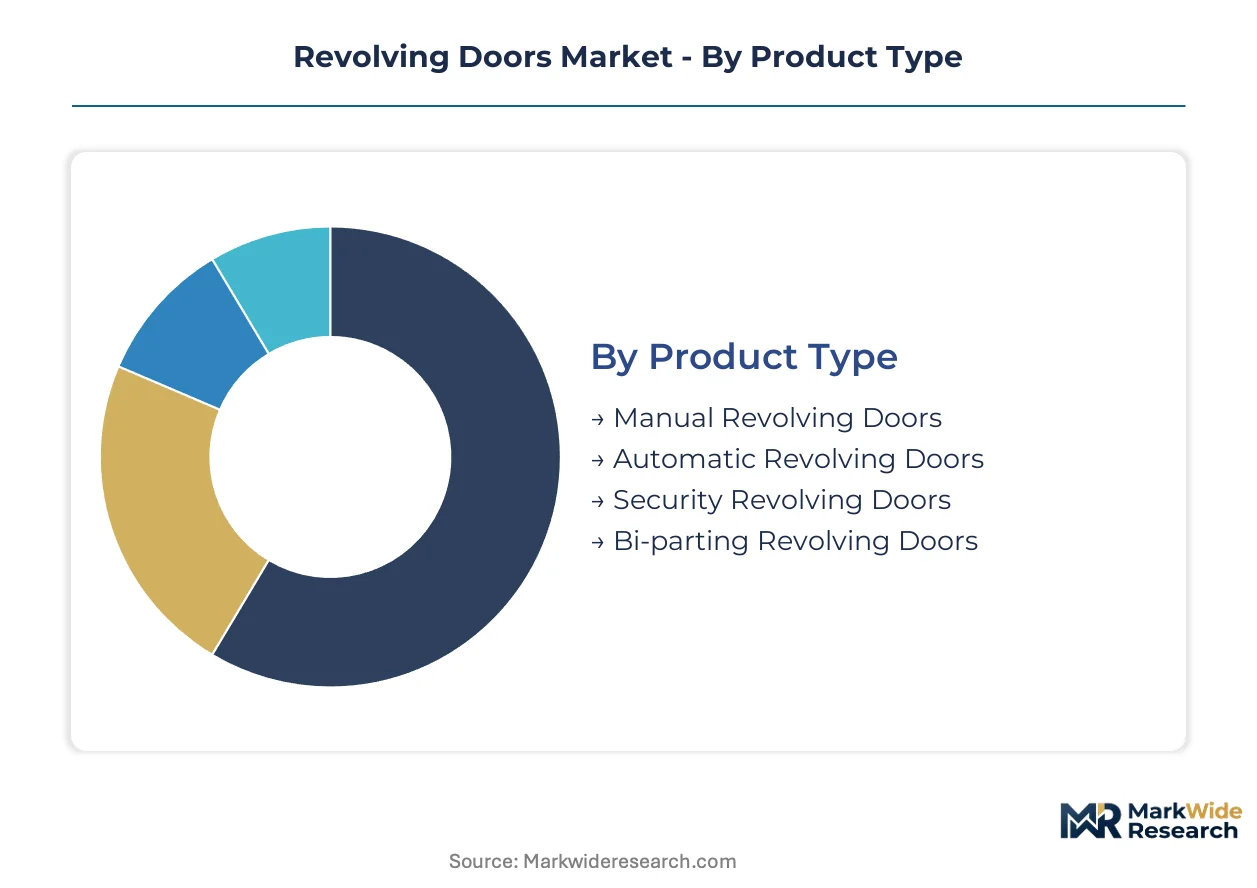
Segmentation in the revolving doors market determines specification authority, installation complexity, and long-term service revenue. Product architecture and material selection drive initial capital outlay, while use case and installation type shape aftermarket attachment rates and lifecycle economics.
Product Type:
After-sales service intensity varies dramatically across automation levels, with sensor arrays and drive systems demanding scheduled maintenance contracts that automatic and security variants monetize most effectively.
- Automatic Revolving Doors:These systems integrate brushless DC motors, programmable logic controllers, and infrared presence detection arrays. Demand concentrates in Frankfurt, Paris, and London airport terminals where climate control and passenger throughput requirements intersect under EU Green Deal thermal mandates. Service contracts typically cover 10-15 year lifecycles with predictive maintenance modules.
- Security Revolving Doors:Interlocking tailgate detection, biometric access modules, and anti-piggybacking sensors define these specifications. Banking headquarters in Frankfurt and government facilities across Germany specify these systems where access control integration outweighs pure energy efficiency. The segment commands premium pricing through certified cybersecurity compliance under IEC 62443.
- Manual Revolving Doors:Mechanical bearings and passive brush seals without motorized drive systems. Small office buildings and heritage structures in Belgium and the Netherlands specify these where capital constraints limit automation investment.
- Bi-parting Revolving Doors:Collapsible wing configurations enabling emergency egress compliance. High-rise atrium applications in London and Paris require these for fire safety certification under evolving EU construction codes.
Automatic revolving doors hold the largest share; momentum sits with security revolving doors.
Material:
Material selection maps directly to facade aesthetic requirements and corrosion exposure, with coastal and high-traffic applications imposing divergent durability specifications.
- Aluminum:Extruded wing frames and canopy structures with anodized or powder-coated finishes dominate commercial building specifications. German developers favor aluminum-glass combinations for thermal break performance documented under CE marking energy performance testing. Price volatility in LME-traded primary ingot creates procurement hedging complexity.
- Glass:Laminated safety glass with low-E coatings enables maximum transparency and thermal transmittance compliance. Premium hotel lobbies in Paris and London specify these for daylighting optimization alongside HVAC load reduction.
- Stainless Steel:AISI 316 grade persists in Rotterdam and Hamburg port-adjacent installations where salt corrosion resistance outweighs aesthetic refresh cycles.
- Wood:Engineered timber veneers with fire-retardant treatment serve heritage building retrofits in Brussels and Amsterdam where regulatory preservation mandates apply.
Aluminum leads specification volume; glass is expanding most quickly in premium commercial applications.
Use Case:
End-use concentration determines traffic load specifications, warranty terms, and the economic viability of sensor fusion investments.
- Airports:24-hour operational profiles with 3,000+ daily passenger cycles demand heavy-duty drive systems and LiDAR-based presence detection. Frankfurt and Charles de Gaulle terminal upgrades specify climate-optimized airlocks with documented U-value certificates.
- Commercial Buildings:Corporate headquarters and Class A office towers in London's Canary Wharf and Frankfurt's Bankenviertel bundle revolving doors with curtain wall performance guarantees.
- Hotels:Luxury hospitality properties in Paris prioritize aesthetic customization and biometric integration for VIP access management.
- Retail Outlets:High-street flagship stores in Berlin and Milan specify compact 2.1-meter diameter units where footprint constraints limit wing span.
Commercial buildings anchor installed base; airports show the steepest expansion trajectory.
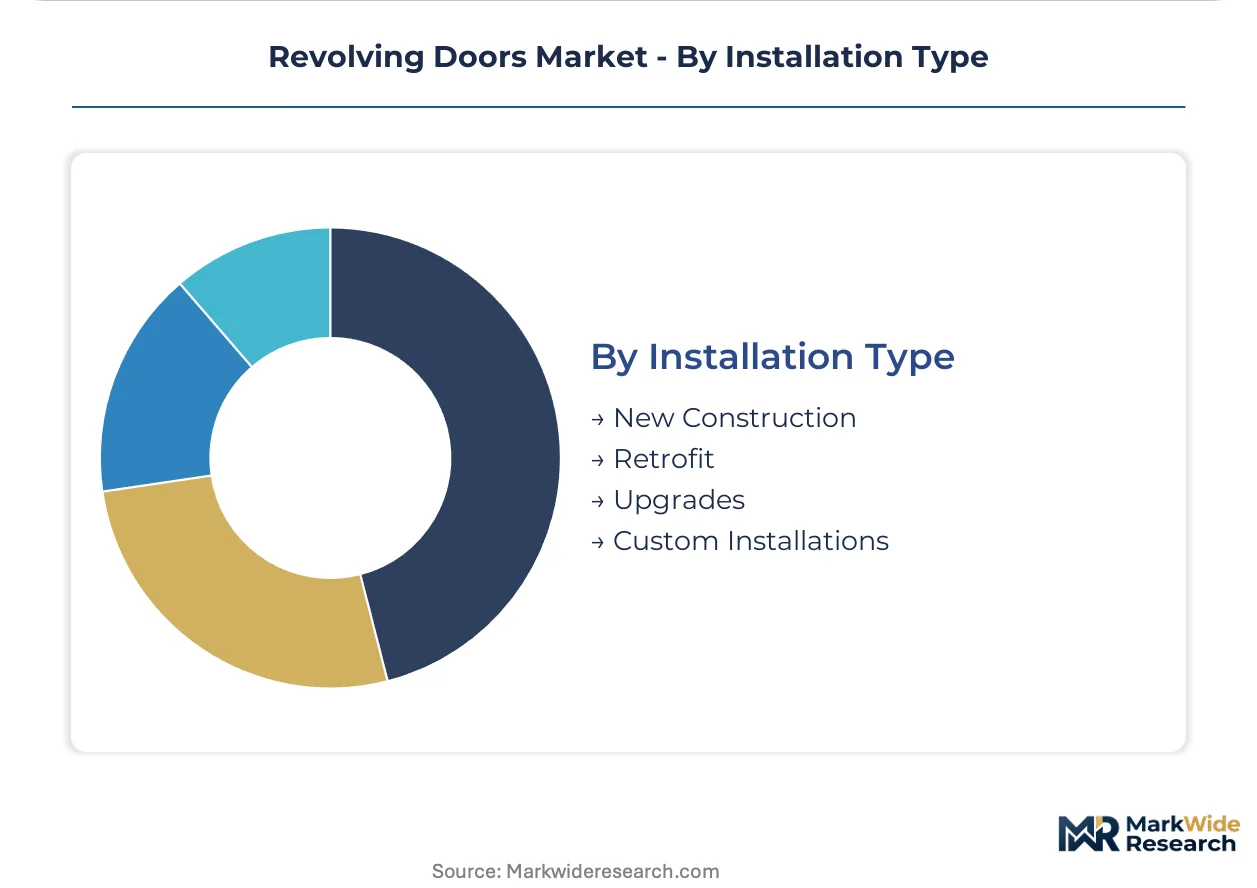
Installation Type:
Installation category shapes project timeline risk, margin structure, and the competitive positioning of certified installation networks versus product-only suppliers.
- Retrofit:Existing commercial stock in Rotterdam, Amsterdam, and Brussels drives demand as EU Green Deal renovation targets mandate thermal performance upgrades. Precision alignment with existing structural openings requires skilled technician deployment.
- New Construction:Greenfield developments in London and Paris specify revolving doors through facade consultant packages with envelope performance guarantees.
- Upgrades:Drive system modernization and sensor retrofit programs extend asset lifecycles without full replacement. Predictive maintenance subscriptions attach most effectively here.
- Custom Installations:Non-standard diameters, bespoke wing configurations, and heritage facade matching serve museum and landmark building projects.
Retrofit captures the fastest-growing demand pool; new construction maintains volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European revolving door manufacturers maintain a structural export surplus, shipping precision-engineered drive systems and climate-optimized airlocks to Middle Eastern airport terminals and Asian commercial developments. Import dependency concentrates in raw aluminum ingot and specialized gearmotor components from German and Italian supplier clusters.
Germany
Frankfurt and Munich airport authorities specify automatic revolving doors with documented U-value certificates under EU Green Deal thermal mandates. ECHA REACH compliance drives substitution of hazardous coatings with water-based surface treatments across Bavarian and North Rhine-Westphalian fabrication facilities. The Bankenviertel district anchors corporate headquarters demand where facade consultants bundle entrance systems with curtain wall performance guarantees.
United Kingdom
London's Canary Wharf and City of London developments prioritize climate-controlled entrance solutions as building renovation targets tighten under national net-zero commitments. CE marking under the EU Construction Products Regulation governs structural safety for cross-channel suppliers serving British commercial stock. Heathrow and Gatwick terminal upgrades specify LiDAR-based presence detection arrays to eliminate mechanical safety edges.
France
Charles de Gaulle and Orly airport infrastructure programs drive procurement of high-throughput revolving systems with brush-sealed perimeter gaps. The country's national construction safety regulator enforces evolving fire-rated revolving system standards for high-rise atrium applications. Paris luxury hospitality properties in the 8th and 16th arrondissements specify biometric integration for VIP access management alongside aesthetic customization.
Netherlands
Rotterdam and Amsterdam commercial stock remains underconverted relative to German thermal upgrade rates, creating specification white space for retrofit installation networks. The Dutch building code implements EU Green Deal renovation targets through mandatory energy performance certificates for existing commercial entrances. Eindhoven's high-tech manufacturing corridor supplies sensor arrays and programmable logic controllers to door assemblers across the Benelux region.
Belgium
Brussels heritage building retrofits specify engineered timber veneers with fire-retardant treatment where regulatory preservation mandates apply. The country's central location positions it as a distribution hub for German and French-manufactured drive systems serving northern European markets. Antwerp port-adjacent installations favor stainless steel configurations where salt corrosion resistance outweighs aesthetic refresh cycles.
Revolving Doors Market Vendor Landscape
On the supply side, the industry is consolidating around integrated entrance solution providers with certified installation networks and documented thermal performance testing capabilities. Three strategic archetypes dominate: full-system manufacturers with automation heritage, security-focused specialists with biometric integration capabilities, and regional fabricators serving retrofit markets through price-competitive manual configurations. Competitive moves concentrate on M&A activity targeting predictive maintenance platforms and strategic partnerships with facade consultants for envelope performance bundling.
Among European-integrated entrance specialists, dormakaba Group and Boon Edam exemplify the full-system archetype with fire-rated and climate-optimized product lines respectively. ASSA ABLOY occupies a position bridging automation heritage with biometric access control integration. These three entities anchor the premium specification tier where CE marking documentation and certified installation networks determine competitive viability.
| Leading Market Players |
|---|
| GEZE |
| Horton Automatics |
| ASSA ABLOY |
| TORMAX USA |
| Stanley Access Technologies |
| dormakaba Group |
| KONE |
| Manusa |
| Boon Edam |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor's container rate volatility feeds directly into landed cost differentials for aluminum ingot and precision gearmotors, compressing margin buffers for door assemblers outside southern Germany while amplifying price differentiation between certified installation networks and product-only suppliers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with CE marking documentation and predictive maintenance bundling as the primary price differentiation drivers. Cost compression in the economy tier is intensifying because manual door substitution erodes specification authority in low-traffic retail segments. Airport terminal operators show the least price sensitivity, prioritizing U-value certification and LiDAR integration over capital outlay.
Supply Chain Analysis
Extended payment terms from Bavarian gearmotor suppliers and supply-chain finance facilities at Italian smelter clusters shape working capital requirements for door fabricators. Manufacturing concentrates in Germany, Italy, and the Netherlands, with raw material dependencies centering on LME-traded primary aluminum, laminated safety glass, and brushless DC drive components. Single-source vulnerability in precision gearmotor production creates lead time risk. Distribution runs through facade consultant networks and certified installer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sliding and swing door systems pose a direct substitution threat as capital-constrained developers in small office and retail segments bypass energy recovery benefits. Incumbents must defend specification authority through integrated climate modeling and envelope performance guarantees.
For Market Incumbents: Entrench position by deepening backward integration into sensor array production and predictive maintenance platforms. Prioritize certification investment for fire-rated revolving systems under evolving EU construction safety codes. Counter manual door substitution through service contract unbundling that monetizes lifecycle value beyond hardware procurement.
For New Entrants and Emerging Players: Mid-market commercial buildings in Rotterdam, Amsterdam, and Brussels represent the most penetrable entry point given underconversion relative to German thermal upgrade rates. Heritage building retrofits requiring engineered timber veneers and regulatory preservation compliance offer specification white space. Pursue go-to-market partnerships with regional facade consultants lacking certified installation networks.
For Investors and Strategic Acquirers: EU Green Deal building renovation targets reshaping the acquisition landscape toward retrofit installation networks with predictive maintenance capabilities. Long-term viability hinges on exposure to mandated thermal performance upgrades across existing commercial stock. Target specialists with documented U-value testing infrastructure and CE marking authority. Watch for inflection in ECHA REACH enforcement accelerating water-based coating substitution.
| Strategic Initiative | Industry Significance |
|---|---|
| Fire-Rated System Certification | EU construction safety code evolution creates first-mover advantage for smoke containment solutions. |
| Predictive Maintenance Platform Acquisition | Vibration and current-draw analytics transform service revenue from hardware attachment to recurring subscriptions. |
| Sensor Array Backward Integration | In-house production of LiDAR and presence detection modules reduces dependency on Eindhoven supplier clusters. |
| Facade Consultant Partnership | Envelope performance bundling concentrates buying power with suppliers offering integrated climate modeling. |
| Netherlands-Belgium Retrofit Expansion | Rotterdam and Brussels commercial stock underconversion relative to German rates leaves specification white space. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with revolving door manufacturers, facade consultants, airport procurement officers, and certified installation technicians; and secondary validation through EU Construction Products Regulation filings, ECHA REACH substance restriction databases, airport infrastructure tender documents, and aluminum trade flow records. Bottom-up segment sizing triangulated against top-down construction expenditure forecasts across the analysis window.
Forecast inputs considered product automation level, material specification tier, end-use traffic intensity, and installation type across the projection horizon. CAGRs derived from segment-level build-ups incorporating EU Green Deal renovation target compliance rates, airport infrastructure program pipelines, and REACH-driven material substitution timelines. Energy performance certificate mandates and thermal transmittance testing requirements shaped demand elasticity assumptions.
Macroeconomic conditions sit as an overlay; deviation in aluminum LME pricing, container freight rates, or construction investment cycles would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Balcony Accessories Market
Homecare and Decor
Plantation Shutters Market
Homecare and Decor
Removable Wallpaper Market
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
Asia-Pacific Sustainable Home Decor Market
Homecare and Decor
Global Decorative Panels Market
Homecare and Decor
Wall Art Market
Homecare and Decor
Global Wallpaper Market
Homecare and Decor
Europe Mattress Market
Homecare and Decor
US Mattress Bases Market
Homecare and Decor
China Sustainable Home Decor Market
Homecare and Decor
India Home Furnishing Market
Homecare and Decor
USA Bed Pillow Market
Homecare and Decor
Mattress Topper Market
Homecare and Decor
US Wallpaper Market
Homecare and Decor
ASEAN UPVC Doors and Windows Market