
 Europe Decorative Laminates Market | 2026-2036
Europe Decorative Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Decorative Laminates Market Intelligence
Melamine-faced chipboard is expanding its share against traditional veneered panels in European furniture production, driven by cost consistency and shorter lead times. FunderMax GmbH leverages its Austrian manufacturing base to sustain premium-positioned exterior-grade laminate supply across Alpine markets. Kronospan Holdings Limited anchors Central European volume through integrated particleboard and decorative paper operations. Wilsonart International competes on specification depth in commercial interiors across the UK and Nordic markets.
Europe decorative laminates are multi-layered thermosetting resin-impregnated sheets, typically composed of kraft paper cores and decorative printed layers cured under heat and pressure, engineered for abrasion-resistant surface finishing in interior applications. High-Pressure Laminates dominate technical performance segments where impact resistance and chemical durability command margin premiums, while Low-Pressure Laminates capture volume in standard furniture and cabinetry production through cost-optimized direct-lamination processes. The Residential end user segment channels steady replacement demand through renovation cycles, whereas Commercial application in hospitality and healthcare settings imposes stricter fire-rating and hygiene specifications that filter supplier eligibility.
REACH compliance and the EU Green Deal's carbon-border adjustment mechanisms are tightening disclosure requirements on formaldehyde emissions and recycled content across laminate supply chains. ECHA's classification of certain phenolic resin precursors is pressuring reformulation timelines, while CE marking under the Construction Products Regulation governs market access for wall-paneling and flooring-grade laminates. Stakeholders must monitor evolving eco-design criteria and embedded-carbon accounting rules to secure specification positions in public procurement frameworks.
Market Dynamics
The EU Green Deal's embodied carbon accounting rules are redirecting specification decisions across European construction and furniture supply chains, forcing laminate producers to reengineer core board formulations and decorative paper sourcing to maintain procurement eligibility in public and commercial tenders.
Growth Catalysts
- Residential renovation cycles:Germany, France, and Italy are channeling steady replacement demand for premium surfacing solutions as housing stock ages and energy-efficiency retrofits accelerate interior upgrades.
- REACH compliance mandates:ECHA's tightening formaldehyde emission thresholds are filtering out lower-grade suppliers and consolidating specification share among certified producers with validated low-emission resin systems.
- FSC-certified decorative papers:OEM procurement standards in Central European furniture manufacturing are prioritizing chain-of-custody documentation, pulling volume toward integrated producers with captive paper mills.
Market Restraints
- Phenolic resin precursor volatility:ECHA's classification of certain phenolic compounds is pressuring reformulation timelines and raw material substitution costs for thermosetting laminate production.
- Central European supply concentration:Particleboard and decorative paper capacity clusters in Austria, Germany, and Poland create geographic dependency risk for just-in-time furniture manufacturing.
- Natural veneer substitution threat:Solid wood and engineered veneer panels retain preference in ultra-premium residential segments where tactile authenticity commands specification premiums.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden, Norway, and Denmark present white space for exterior-grade laminate systems in cladding applications where moisture resistance and color stability are valued.
- Healthcare hygiene specifications:Antimicrobial surface treatments and seamless jointing systems are opening specification pathways in hospital and clinic renovation programs across France and Italy.
- Digital print-to-laminate convergence:Direct-to-substrate inkjet decoration technologies are enabling short-run customization for boutique hospitality and retail interior projects.
Industry Challenges
- CE marking timeline compression:Construction Products Regulation testing and certification for wall-paneling and flooring-grade laminates is extending time-to-market for new product introductions.
- Recycled-content core board integration:Balancing post-consumer wood fiber supply quality with mechanical performance standards is complicating production consistency in high-volume furniture applications.
- Resin chemistry skill scarcity:Formulation expertise for low-emission thermosetting systems is concentrating among senior technical staff nearing retirement in Central European manufacturing centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Decorative Laminates Market |
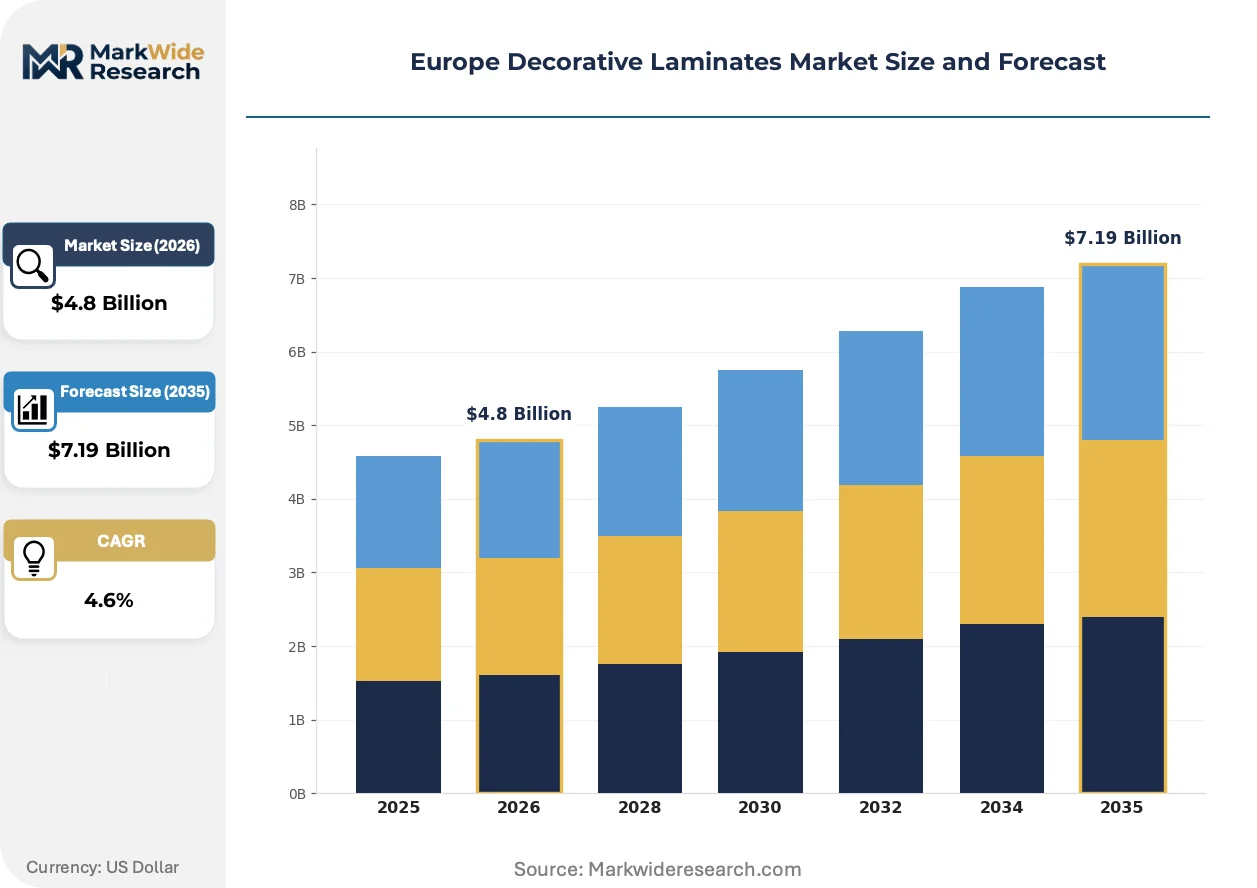
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Pressure Laminates, Low-Pressure Laminates, Backed Laminates, Wood Based Laminates Application: Furniture, Flooring, Wall Paneling, Cabinetry End User: Residential, Commercial, Institutional, Industrial Distribution Channel: Direct Sales, Online Retail, Distributors, Contractors |
| Companies Covered | Formica Group, FunderMax GmbH, Swiss Krono, Kronospan Holdings Limited, Wilsonart International, Abet Laminati SpA, Arpa Industriale, Windmoller GmbH, Panolam Industries International Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Decorative Laminates Market Strategic Shifts & Innovations
Digital decoration technologies and circular material flows are compressing traditional production cycles and redefining competitive differentiation in European decorative laminates. Three forces are actively reshaping how value is created and captured.
Digital inkjet printing directly onto core substrates is rewriting the economics of short-run decorative surface production. Boutique furniture manufacturers and custom hospitality interior specialists are adopting print-to-laminate workflows to compress sample-to-production lead times from weeks to days. This capability is enabling mass-customization at scale and compressing minimum order quantities for regional laminate converters.
EU Green Deal carbon-border adjustment mechanisms are tightening disclosure requirements on embedded emissions across laminate supply chains. CE marking under the Construction Products Regulation now requires documented life-cycle carbon data for wall-paneling and flooring-grade products entering public procurement frameworks. German and French specification teams are prioritizing suppliers with third-party verified Environmental Product Declarations.
Specification decisions in commercial interiors are migrating from generalist distributors to direct OEM collaboration models. Large furniture manufacturers in Italy and Germany are consolidating supplier relationships around integrated producers capable of co-developing surface aesthetics and performance grades. This channel consolidation is visible most acutely in contract hospitality and healthcare verticals where batch consistency and fire-rating documentation are non-negotiable.
Europe Decorative Laminates Market Segmentation
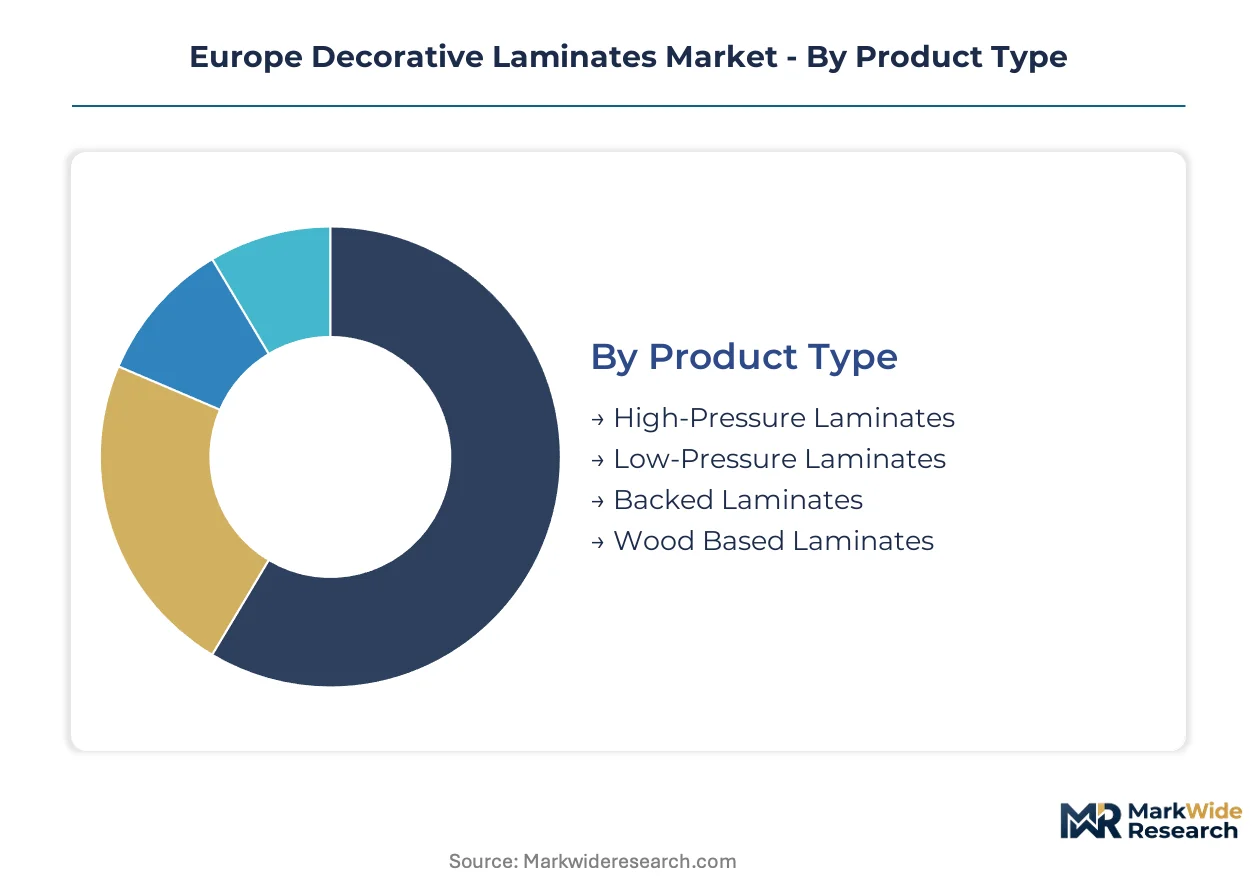
Segmentation in Europe's decorative laminates market reveals how specification requirements diverge across pressure-class, end-use durability demands, and procurement channel preferences. Upgrade cycles in furniture manufacturing and commercial interiors create distinct volume patterns that reward producers with aligned product portfolios.
Product Type:
Replacement-driven specification decisions in European furniture and interior construction favor laminate systems that balance surface performance with core board compatibility during renovation timelines.
- High-Pressure Laminates:Multi-layer kraft paper cores saturated with thermosetting phenolic resins, compressed under elevated heat and pressure to achieve density above 1.35 g/cm³. German healthcare and hospitality specification teams prioritize these grades for reception desks and wall cladding where impact resistance and chemical durability command procurement premiums.
- Low-Pressure Laminates:Single decorative paper layer bonded directly to particleboard or MDF substrates through short-cycle lamination, eliminating the separate pressing stage. French and Italian furniture OEMs channel volume here for standard cabinetry and residential case goods where cost consistency outweighs extreme durability requirements.
- Backed Laminates:Pressure-sensitive adhesive or thermal-bond backing layers enable field installation without specialized equipment. These systems serve UK and Nordic renovation contractors executing rapid commercial interior refreshes.
- Wood Based Laminates:Thin wood veneer faces bonded to composite cores, bridging the aesthetic gap between synthetic surfaces and solid timber. Austrian and Swiss premium residential markets specify these for visible furniture components requiring tactile authenticity.
Low-Pressure Laminates sit at the top of the volume ranking, with Backed Laminates climbing the fastest as retrofit activity accelerates across Northern Europe.
Application:
Cost tier differentiation separates specification pathways, with premium surfacing investments concentrating in visible, high-touch surfaces while economy grades serve concealed structural components.
- Furniture:Horizontal and vertical surface finishing for case goods, tables, and seating frames. Germany's furniture manufacturing belt in North Rhine-Westphalia and Bavaria consumes the majority share, driven by OEM procurement standards prioritizing FSC-certified decorative papers and batch-to-batch color consistency.
- Flooring:Wear-layer applications requiring enhanced abrasion resistance and slip ratings. Italian and Spanish specification teams in hospitality and retail verticals drive demand here, with CE marking under the Construction Products Regulation governing market access for public installations.
- Wall Paneling:Vertical surfacing for interior partitions and feature walls. French healthcare renovation programs impose strict fire-rating documentation that filters supplier eligibility toward integrated producers with captive testing capabilities.
- Cabinetry:Kitchen, bath, and storage system surfacing where moisture resistance and thermal cycling durability matter. Polish and Czech manufacturers serving Western European markets concentrate procurement in mid-pressure laminate grades optimized for automated edgebanding lines.
Furniture commands the largest installed base, though Flooring is expanding most quickly as commercial refurbishment cycles compress across Southern Europe.
End User:
Customer type determines performance specification intensity, with institutional and commercial buyers imposing certification burdens that residential purchasers rarely enforce.
- Residential:Owner-occupied and rental property interior upgrades. Aging housing stock across Germany, France, and Italy generates steady replacement demand, with energy-efficiency retrofits frequently triggering coordinated kitchen and bath renovations.
- Commercial:Hospitality, retail, and office environments where durability and aesthetic refresh cycles compete. Contract furniture manufacturers in Milan and High Point Europe specify laminate systems with documented antimicrobial performance and seamless jointing for high-traffic reception and dining areas.
- Institutional:Healthcare, education, and government facilities subject to public procurement frameworks. REACH compliance and EU Green Deal embodied carbon thresholds redirect specification decisions toward suppliers with third-party verified Environmental Product Declarations.
- Industrial:Workstation, laboratory, and cleanroom surfacing where chemical resistance and static control matter. Benelux and Scandinavian pharmaceutical manufacturing clusters specify specialized grades with conductive core layers.
Residential maintains the deepest volume foundation, while Institutional procurement is gaining share fastest as Green Deal compliance reshapes public tender eligibility.
Distribution Channel:
Supply concentration in Central European manufacturing clusters shapes how laminate products reach specification teams and installation contractors.
- Direct Sales:Manufacturer-to-OEM relationships for large furniture producers with dedicated procurement teams. Italian and German contract hospitality manufacturers consolidate supplier relationships around integrated producers capable of co-developing surface aesthetics.
- Online Retail:Digital platforms serving small-batch custom fabricators and renovation contractors. UK and Nordic boutique interior specialists leverage these channels for rapid sample-to-production workflows.
- Distributors:Regional inventory holders bridging mill production and local fabrication. Austrian and Polish distribution networks concentrate particleboard and decorative paper capacity to serve just-in-time furniture manufacturing.
- Contractors:Installation firms purchasing surfacing materials as part of turnkey interior packages. French and Spanish general contractors in commercial renovation verticals prefer bundled procurement to compress project timelines.
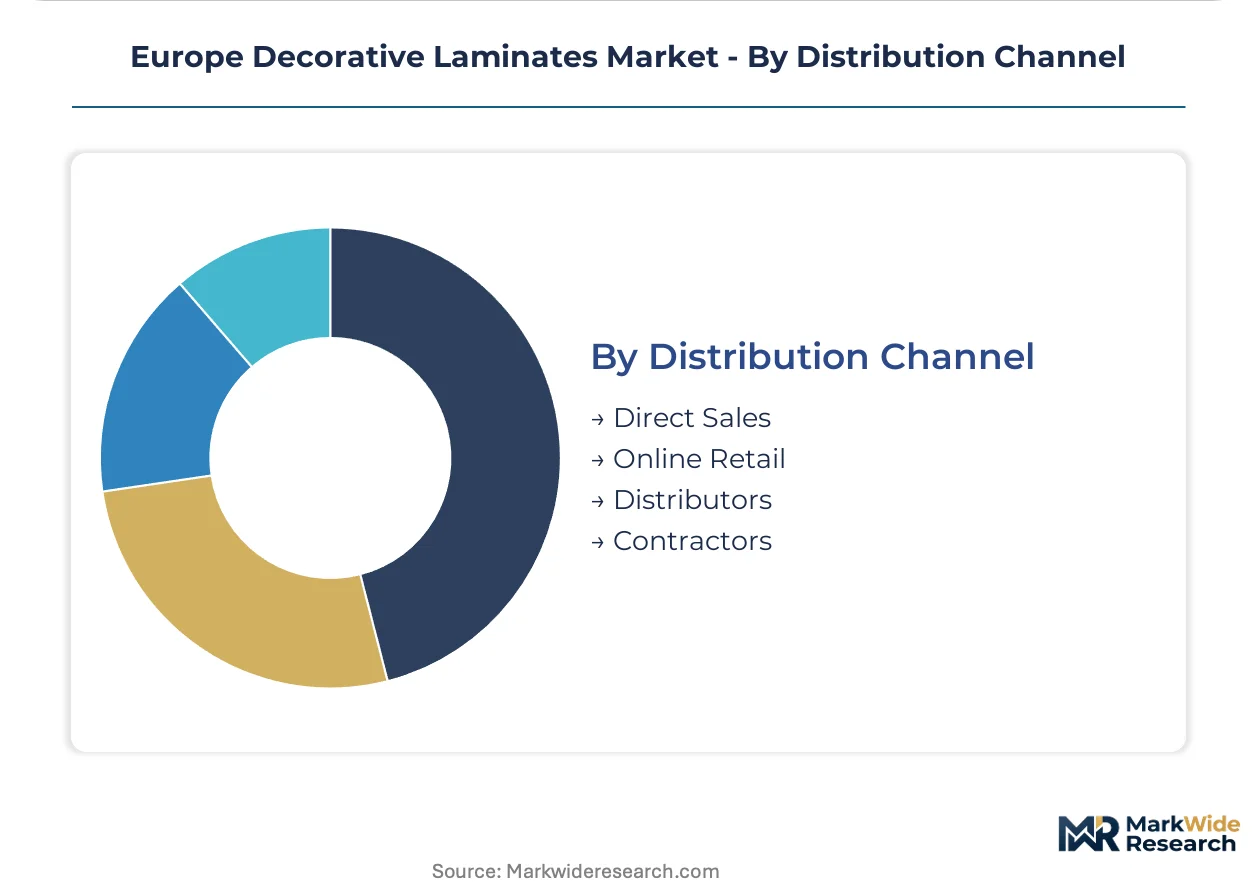
Direct Sales retains the largest transaction value, with Online Retail advancing fastest as digital print-to-laminate technologies enable mass-customization at reduced minimum order quantities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Rhine-Westphalia's furniture manufacturing belt anchors European decorative laminates demand, with Germany consuming the largest regional share. Specification teams across the continent prioritize REACH-compliant low-emission systems as the EU Green Deal tightens embodied carbon thresholds. Production capacity clusters along the Alpine arc and Central European plain, creating distinct procurement zones for premium and volume-grade laminates.
Germany
OEM procurement standards in Bavaria and North Rhine-Westphalia prioritize FSC-certified decorative papers and recycled-content core boards. ECHA's formaldehyde emission thresholds filter supplier eligibility toward integrated producers with validated resin systems. The Stuttgart furniture cluster drives specification volume for high-pressure laminates in contract hospitality interiors.
France
Healthcare renovation programs in Île-de-France impose strict fire-rating documentation that concentrates procurement among certified suppliers. CE marking under the Construction Products Regulation governs wall-paneling market access for public installations. Lyon and Marseille manufacturing zones channel mid-pressure laminate demand for automated cabinetry production lines.
Italy
Milan's contract furniture manufacturers consolidate supplier relationships around co-development capabilities for surface aesthetics. The EU Green Deal's carbon-border adjustment mechanisms redirect tender decisions toward suppliers with third-party verified Environmental Product Declarations. Emilia-Romagna's woodworking districts sustain steady replacement demand through residential kitchen and bath renovation cycles.
United Kingdom
London commercial interior specialists leverage digital print-to-laminate workflows to compress sample-to-production lead times. Specification depth in Nordic-influenced design segments rewards suppliers with documented antimicrobial performance and seamless jointing systems. Manchester and Birmingham distribution hubs bridge Central European mill production and regional fabrication networks.
Poland
Particleboard and decorative paper capacity in Lower Silesia and Greater Poland serves just-in-time furniture manufacturing for Western European markets. Polish manufacturers optimize mid-pressure laminate grades for automated edgebanding lines serving German and French OEMs. The country's central logistics position attracts distribution investment from integrated European producers.
Europe Decorative Laminates Market Key Industry Players
Global majors compete with regional champions across specification depth and supply chain integration, producing a tiered structure where scale-driven volume producers coexist with premium-positioned specialists. The vendor base separates into three archetypes: integrated resin-to-laminate manufacturers with captive paper mills, regional converters serving niche specification channels, and distribution-heavy players optimizing logistics reach. Consolidation pressure concentrates among mid-tier converters lacking backward integration into core board or decorative paper production. Dominant competitive moves include strategic partnerships with furniture OEMs for co-developed surface collections and geographic expansion into underpenetrated Nordic cladding markets.
Within the integrated-manufacturer tier, Kronospan Holdings Limited and FunderMax GmbH exemplify divergent geographic and positioning strategies. Kronospan anchors Central European volume through particleboard and decorative paper operations concentrated in Austria and Poland. FunderMax leverages its Austrian manufacturing base to sustain premium exterior-grade laminate supply across Alpine markets. Wilsonart International occupies a position focused on specification depth in UK and Nordic commercial interiors. Swiss Krono represents the scale-driven archetype with broad European distribution coverage.
| Leading Market Players |
|---|
| Formica Group |
| FunderMax GmbH |
| Swiss Krono |
| Kronospan Holdings Limited |
| Wilsonart International |
| Abet Laminati SpA |
| Arpa Industriale |
| Windmoller GmbH |
| Panolam Industries International Inc |
| Others |
Cost & Logistics Intelligence
German and Italian furniture OEMs dominate procurement volume and enforce contract-based long-term offtake agreements that compress margin variability for laminate converters. This buyer concentration rewards integrated producers with captive resin and paper operations while squeezing standalone converters on price and payment terms.
Pricing Analysis
Phenolic resin and kraft paper input-cost pass-through clauses dominate supply agreements, with quarterly adjustments tethering laminate prices to petrochemical indices and pulp futures. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with FSC-certified decorative papers commanding measurable premiums. Cost compression in standard-grade furniture laminates is intensifying because Polish and Czech converters are expanding automated press capacity. Residential renovation contractors exhibit the highest price sensitivity, while healthcare specification teams prioritize emission compliance over unit cost.
Supply Chain Analysis
Post-consumer wood fiber collection and reprocessing flows are gaining scale in Germany and Austria as EU circular economy mandates tighten disposal restrictions on construction debris. Manufacturing gravity centers on Austria, Germany, and Poland, where particleboard and decorative paper capacity clusters serve just-in-time furniture production. The network draws from phenolic resin precursors sourced through Benelux petrochemical hubs and decorative paper from Scandinavian pulp mills. Single-source vulnerability concentrates in melamine-formaldehyde resin supply, where two Central European producers control majority share. Distribution runs through regional inventory holders in North Rhine-Westphalia and Lombardy bridging mill output and fabrication networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's decorative laminates market functions as a stable compounder anchored by replacement-driven renovation cycles in aging housing stock across Germany, France, and Italy.
For Market Incumbents: Hedge against natural veneer substitution in ultra-premium residential segments by deepening co-development relationships with Milan and Stuttgart contract furniture manufacturers. Prioritize REACH-compliant resin system investments to maintain specification eligibility as ECHA tightens formaldehyde emission thresholds. Secure backward integration into post-consumer wood fiber sorting and cleaning to stabilize recycled-content core board quality. For New Entrants and Emerging Players: Begin with digital print-to-laminate service models targeting UK and Nordic boutique hospitality interior specialists seeking compressed sample-to-production timelines. The most penetrable white space sits in Swedish and Norwegian exterior-grade cladding applications where moisture-resistant laminate systems remain underdistributed. Establish direct online retail channels to bypass incumbent distributor relationships and capture small-batch custom fabrication demand. For Investors and Strategic Acquirers: European furniture OEMs are the most active acquirer in this space, consolidating supplier relationships to secure batch consistency and fire-rating documentation for contract hospitality and healthcare verticals. Long-term viability rests on embedded carbon accounting capabilities as EU Green Deal procurement rules harden. Watch for ECHA reclassification of additional phenolic compounds as the critical inflection signal that could accelerate consolidation among non-integrated converters lacking reformulation resources.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Decorative Paper Mills | Captive FSC-certified supply secures procurement eligibility with German and Italian OEMs. |
| Digital Print-to-Laminate Capability Investment | Short-run customization captures boutique hospitality specification share from incumbent converters. |
| Third-Party Verified Environmental Product Declaration | Documented life-cycle carbon data unlocks public tender access under EU Green Deal frameworks. |
| Antimicrobial Surface Treatment Development | Hygiene performance specifications open hospital and clinic renovation pathways in France and Italy. |
| Nordic Distribution Partnership Expansion | Exterior-grade laminate penetration in Sweden and Norway addresses underpenetrated cladding demand. |
Research Approach
Direct dialogue with plant managers at Central European laminate presses, procurement leads at German and Italian furniture OEMs, distribution channel partners in Austria and Poland, and technical R&D directors at resin suppliers grounded the qualitative foundation. Secondary validation drew from ECHA regulatory filings, EU Construction Products Regulation documentation, customs and trade data on particleboard and decorative paper flows, and SEC filings from publicly listed building materials companies. Bottom-up volume estimates by product type and application were cross-checked against top-down macroeconomic indicators and construction activity indices.
Segmented projections across pressure class, end-use durability tier, and procurement channel preference informed the analytical framework over the projection horizon. CAGRs were derived from trend extrapolation of replacement cycle intensity, regulatory compliance cost trajectories, and OEM procurement standard evolution. Key forecast inputs included housing stock age profiles by country, energy-efficiency retrofit program budgets, and ECHA substance evaluation timelines.
Several conditions sit outside the modeled scope, including abrupt phenolic resin precursor reclassification, major trade policy shifts affecting Central European particleboard exports, and technological disruption from solid-surface composite alternatives. Forecasts reflect assumptions about steady regulatory implementation timelines and continued EU Green Deal procurement rule expansion. Practitioners should monitor ECHA substance evaluation announcements, carbon-border adjustment mechanism implementation schedules, and Nordic cladding specification standard development for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Curtains and Window Blinds Market
Homecare and Decor
Mattress Pads Market
Homecare and Decor
Bamboo Panels Market
Homecare and Decor
India Furniture Hardware Market
Homecare and Decor
China Sustainable Home Decor Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
Wall Covering and Wall Decor Market
Homecare and Decor
Middle East Revolving Doors Market
Homecare and Decor
US Bamboos Market
Homecare and Decor
Wall Decor Market
Homecare and Decor
Terracotta Pots Market
Homecare and Decor
USA Bed Pillow Market
Homecare and Decor
Interior Design Services Market
Homecare and Decor
Global Wallpaper Market
Homecare and Decor
MDF Decorative Overlays Market
Homecare and Decor
Gas Fire Table Market