
 Fragrant Drawer Liners Market | 2026-2036
Fragrant Drawer Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Fragrant Drawer Liners Market Foresight
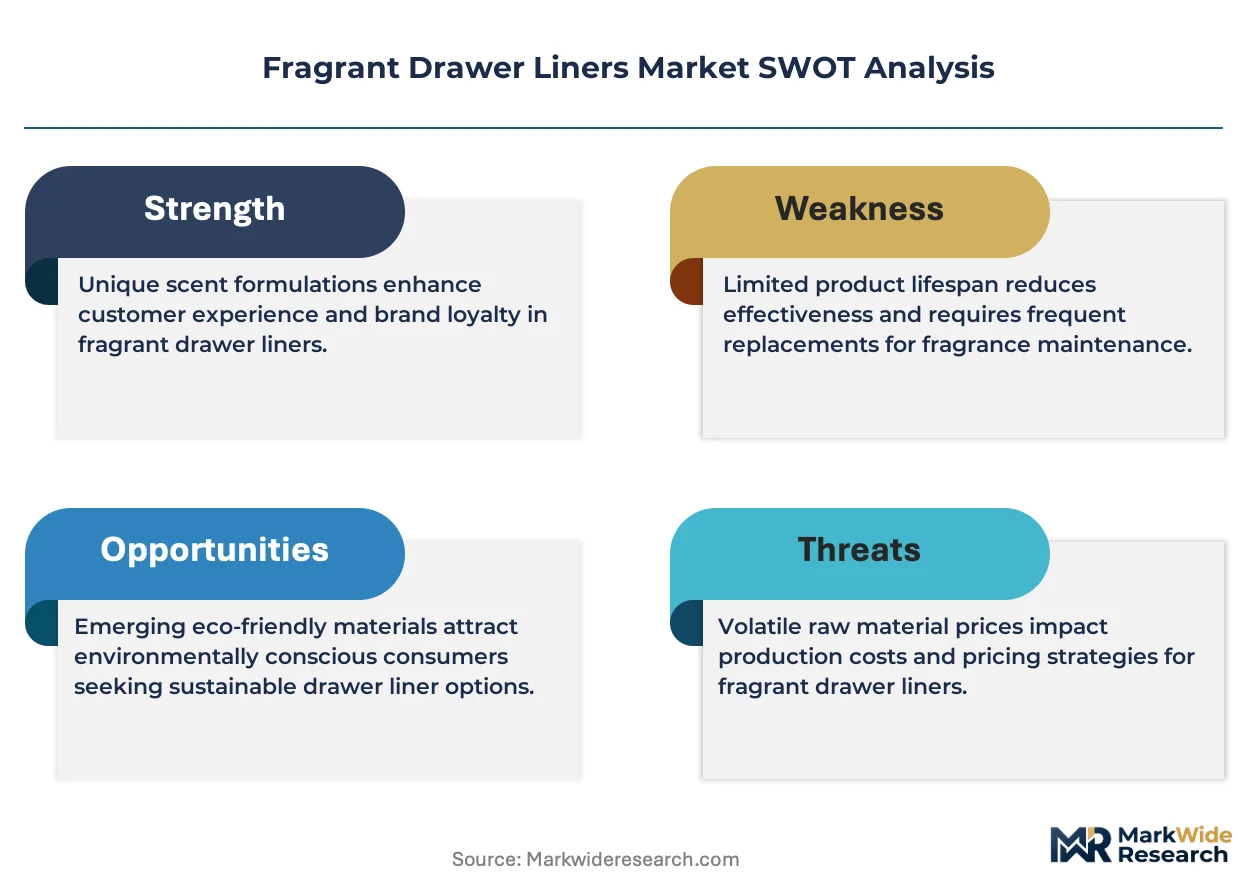
Premium scent concentration is bifurcating the competitive landscape into artisan-grade and mass-market tiers. Crabtree & Evelyn leverages its heritage fragrance library to sustain pricing power in specialty retail channels. Michel Design Works anchors its position through coordinated pattern-and-scent collections that dominate gift-shop distribution. IKEA competes on volume scale with flat-pack compatible roll formats that occupy big-box home organization aisles.
Fragrant drawer liners are paper or nonwoven substrates impregnated with microencapsulated essential oils or synthetic fragrance compounds, typically 0.3–0.8 millimeters thick, designed to release scent while protecting stored textiles from mustiness and insect damage. Cedarwood formulations lead material type demand among heritage-conscious consumers seeking natural moth deterrents, while lavender-infused variants represent the fastest-growing segment as sleep-hygiene trends expand from bedding into closet environments. Roll packaging controls the volume channel through cost-efficient continuous formats, yet boxed sets capture margin pools in boutique and hospitality procurement where presentation drives purchase decisions.
REACH compliance in Europe governs fragrance allergen disclosure and restricts certain synthetic musks, compelling reformulation across export-oriented suppliers. The EPA's Safer Choice program in the United States shapes consumer perception of plant-derived versus petrochemical scent carriers. Stakeholders must monitor evolving fragrance disclosure mandates and substrate sustainability certifications to secure shelf placement in regulated retail environments.
Market Dynamics
California's Safer Consumer Products regulations are forcing reformulation across North American supply chains, bifurcating manufacturers between heritage synthetic carriers and emergent plant-based substrates that command boutique retail placement.
Growth Catalysts
- REACH fragrance allergen disclosure:European compliance mandates are accelerating transparency investments that differentiate premium suppliers in export markets.
- Heritage homeware retailers:United Kingdom interior design studios are driving artisanal format adoption through coordinated scent-and-pattern curation.
- Microencapsulation technology:Essential oil stabilization advances are extending scent release duration from weeks to months in cedarwood formulations.
Market Restraints
- Recycled paper substrate volatility:Post-consumer fiber sourcing concentrates in Nordic pulp mills, exposing cost structures to energy-driven input swings.
- Synthetic musk restrictions:REACH Annex XVII limitations on nitro musks are eliminating fragrance families without drop-in botanical replacements.
- Flat-pack roll commoditization:Big-box volume formats compress margin pools and crowd shelf space from differentiated boxed sets.
Strategic Opportunities
- Hospitality procurement channels:Boutique hotel amenity programs represent underpenetrated volume for presentation-driven boxed liner sets.
- Sleep-hygiene vertical expansion:Lavender-infused variants are migrating from bedding into closet environments, opening new end-use positioning.
- EPA Safer Choice certification:Plant-derived carrier recognition is creating preference pull among wellness-focused consumer segments.
Industry Challenges
- Fragrance chemist talent scarcity:Microencapsulation formulation expertise concentrates in legacy personal care suppliers, constraining in-house capability builds.
- Multi-jurisdiction compliance timelines:Simultaneous California SCP and REACH dossier preparation extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fragrant Drawer Liners Market |
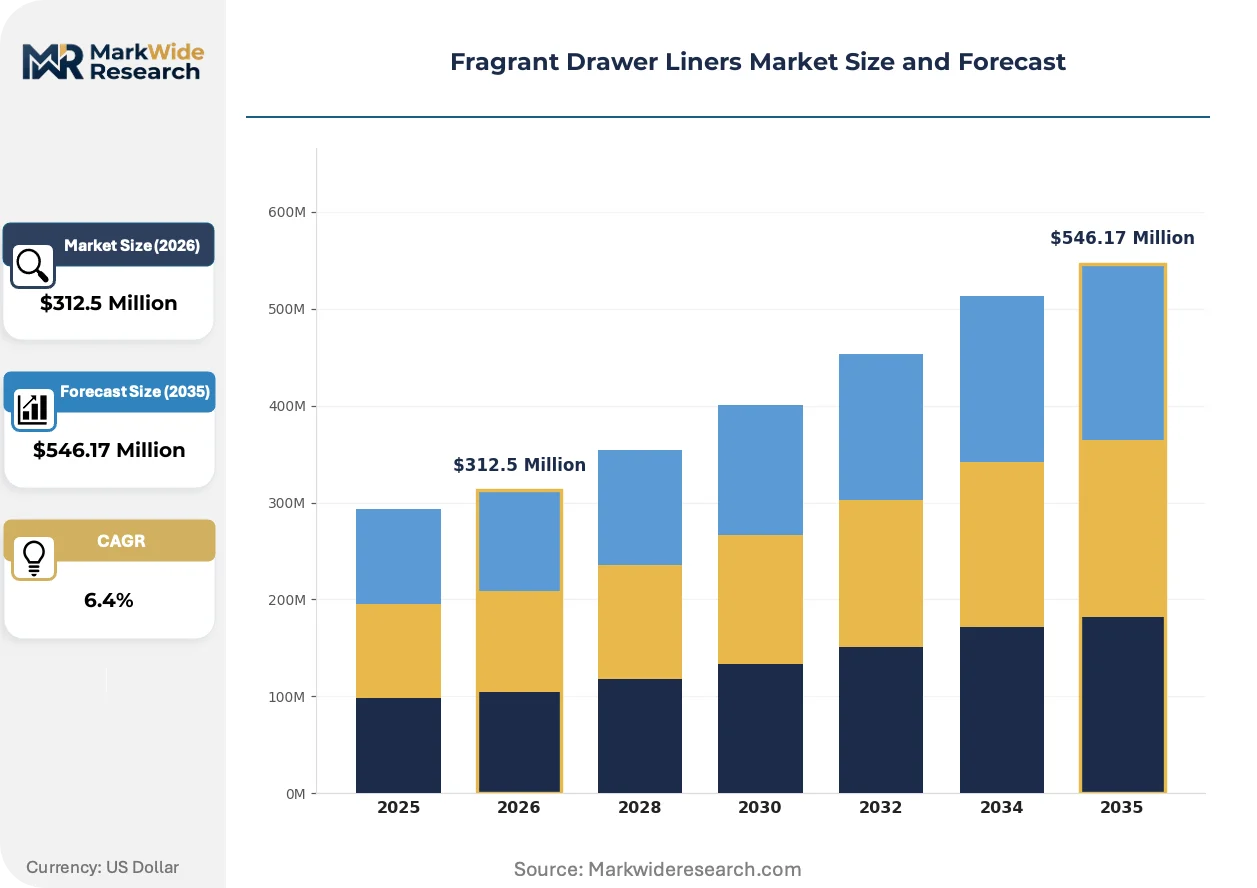
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cedarwood, Lavender-Infused, Jasmine Scented, Vanilla Essence, Rose Petal, Chamomile Application: Wardrobes, Kitchen Drawers, Office Cabinets, Bathroom Storage, Shoe Organizers, Linen Closets End User: Households, Boutique Stores, Interior Designers, Hospitality Units, Craft Workshops Packaging Type: Rolls, Pre-Cut Sheets, Sachets, Boxed Sets, Refill Packs |
| Companies Covered | Crabtree & Evelyn, Michel Design Works, Orlandi, Scentennials, Cala Industries, Conimar Group LLC, Gorilla Grip, IKEA, Print Fragrancing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fragrant Drawer Liners Market Shifts & Advancements
Active reformulation is reshaping substrate chemistry and scent delivery architectures. Three developments are compressing legacy competitive advantages while opening white space for certified-sustainable entrants.
Biodegradable nonwoven substrates impregnated with algae-derived fixatives are decomposing the traditional paper-versus-synthetic dichotomy. Boutique hospitality buyers in Scandinavia are piloting these formats for guest room amenities. The technology is decomposing incumbent advantages in moisture resistance and shelf stability that previously favored petrochemical binders.
REACH Annex XVII updates on fragrance allergens are compelling granular ingredient disclosure across EU export supply chains. Reputable suppliers are reformulating legacy synthetic musks ahead of enforcement timelines. Premium boxed-set manufacturers in the United Kingdom are responding fastest, leveraging transparency as a positioning wedge against mass-market competitors.
Closet wellness curation is displacing purely functional textile protection as the primary purchase trigger. Interior design studios in London and Manchester are specifying coordinated scent-and-pattern collections for residential projects. This behavioral pivot is most visible in heritage homeware retail channels where presentation and provenance command price premiums over utilitarian roll formats.
Fragrant Drawer Liners Market Segmentation
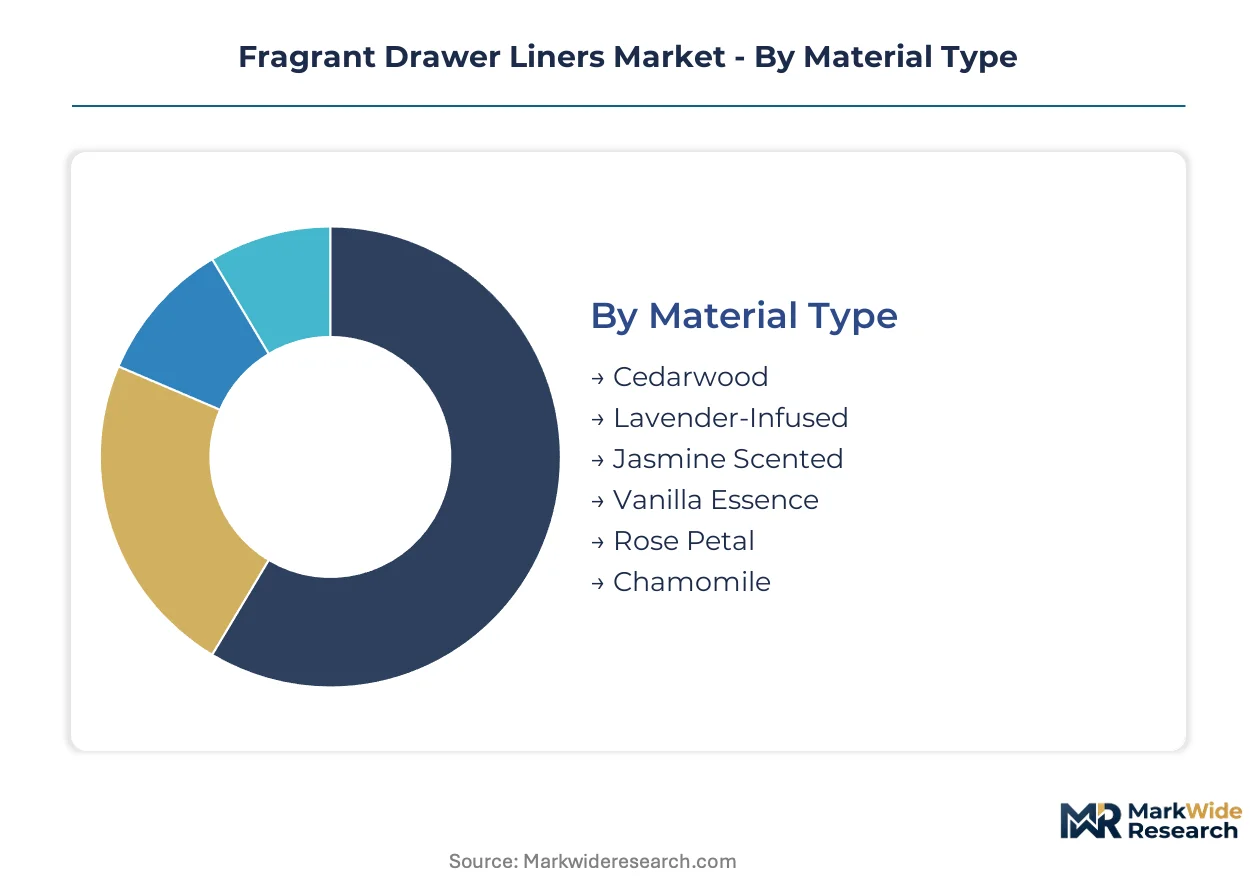
Segmentation in the Fragrant Drawer Liners Market reveals how substrate chemistry, scent profiles, and packaging formats align with distinct procurement channels. Manufacturers optimize formulation and presentation to capture divergent margin pools across mass retail, boutique hospitality, and artisan craft segments.
Material Type:
Cedarwood formulations dominate domestic North American demand through heritage positioning as natural moth deterrents, while lavender-infused variants lead export growth into European sleep-hygiene markets.
- Cedarwood:Paper substrates impregnated with cedar oil extracts at 0.5-0.8mm thickness provide textile protection against moth larvae. Demand concentrates in California and Pacific Northwest households where Safer Consumer Products regulations favor plant-based carriers over synthetic alternatives.
- Lavender-Infused:Microencapsulated essential oil formulations release scent over 60-90 day cycles. United Kingdom interior design studios specify these for residential closet wellness projects, with Manchester and London showrooms driving specification rates.
- Jasmine Scented:Synthetic and natural blend formulations target gift-shop channels in Southeast Asian export markets.
- Vanilla Essence:Warm-profile scents dominate hospitality amenity procurement for boutique hotel guest rooms.
- Rose Petal:Premium boxed-set positioning in heritage homeware retail channels.
- Chamomile:Calming-profile variants expanding into nursery and children's storage applications.
Cedarwood holds the largest share; momentum sits with lavender-infused formats as sleep-hygiene positioning expands beyond bedding into closet environments.
Application:
Cost tier segmentation separates premium specification-driven placements from volume retail formats, with hospitality and residential design channels commanding 3-4x unit economics over mass-market kitchen drawer applications.
- Wardrobes:Full-height liner installations at 0.6-0.8mm thickness protect seasonal garments from moisture and insect damage. United Kingdom heritage retailers coordinate scent-and-pattern collections for this application, with interior design studios in London specifying artisanal boxed sets for residential projects.
- Kitchen Drawers:Food-safe formulations at 0.3-0.5mm thickness line utensil and cutlery storage. Flat-pack roll formats dominate this volume channel through IKEA and big-box home organization aisles where price compression limits margin expansion.
- Office Cabinets:Neutral scent profiles for professional environments.
- Bathroom Storage:Moisture-resistant nonwoven substrates for high-humidity environments.
- Shoe Organizers:Cedarwood-dominant formats leveraging natural odor absorption.
- Linen Closets:Coordinated scent layering with bedroom textiles.
Wardrobes generate the highest revenue per square meter installed; linen closets are climbing the fastest as closet wellness curation displaces purely functional protection.
End User:
Customer type segmentation determines packaging format and scent complexity, with hospitality procurement requiring presentation-driven boxed sets while craft workshops prioritize unbranded bulk sachets for artisan product incorporation.
- Households:Individual consumers purchase through retail and direct channels, with subscription refill models emerging for cedarwood and lavender segments. California households show elevated preference for EPA Safer Choice certified plant-derived carriers.
- Boutique Stores:Curated assortments of artisanal boxed sets drive margin pools. United Kingdom homeware retailers in heritage districts specify coordinated pattern-and-scent collections that command price premiums over utilitarian formats.
- Interior Designers:Specification-grade procurement for residential and commercial projects.
- Hospitality Units:Boutique hotel amenity programs represent underpenetrated volume for presentation-driven presentation formats.
- Craft Workshops:Bulk unbranded sourcing for artisan product integration.
Households constitute the volume base; hospitality units show the steepest expansion trajectory as boutique hotel differentiation intensifies.
Packaging Type:
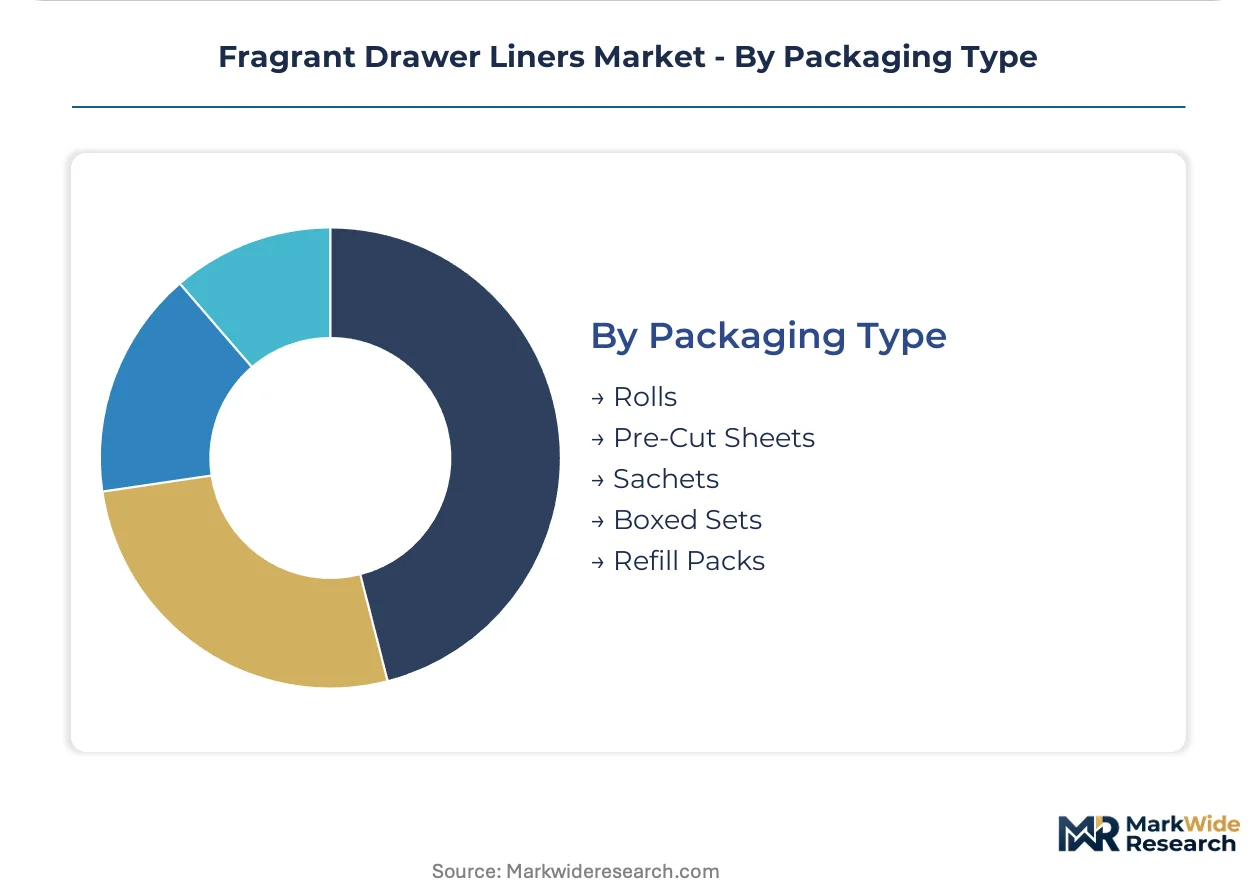
Supply concentration in Nordic pulp mills for recycled paper substrates favors continuous roll formats, while margin accretion concentrates in boxed sets where presentation engineering justifies premium positioning.
- Rolls:Continuous 5-10 meter formats at 300-600mm widths enable cost-efficient coverage of variable drawer dimensions. Flat-pack compatibility drives placement in IKEA and big-box channels, though shelf space compression crowds differentiated alternatives.
- Boxed Sets:Pre-coordinated scent-and-pattern collections in rigid presentation packaging. United Kingdom heritage retailers and hospitality procurement channels favor these formats where unboxing experience influences repurchase intent.
- Pre-Cut Sheets:Standardized dimensions for common drawer sizes.
- Sachets:Small-format portable scent for travel and gift applications.
- Refill Packs:Subscription-compatible formats for established installed bases.
Rolls dominate unit volume; boxed sets are gaining share fastest as closet wellness curation elevates presentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. United Kingdom buyers absorb premium positioning for artisanal formats, while United States mass-market channels compress margins through flat-pack commoditization.
United States
California households drive plant-derived carrier preference through EPA Safer Choice certification pull. The state's Safer Consumer Products regulations force reformulation toward recycled paper substrates. Los Angeles boutique retailers curate scent-and-pattern collections for closet wellness positioning.
United Kingdom
Heritage homeware retailers in London and Manchester command 3-4x unit economics over mass-market alternatives through coordinated curation. REACH fragrance allergen disclosure mandates accelerate transparency investments among export-oriented suppliers. Interior design studios specify artisanal boxed sets for residential wardrobe installations.
Germany
Scandinavian pulp mill supply concentration exposes German converters to energy-driven input volatility for recycled paper substrates. ECHA enforcement of REACH Annex XVII synthetic musk restrictions eliminates legacy fragrance families without botanical replacements. Hamburg hospitality procurement channels pilot algae-derived biodegradable nonwoven formats.
France
Boutique hotel amenity programs in Paris represent underpenetrated volume for presentation-driven boxed liner sets. ANSM fragrance disclosure requirements align with broader EU transparency mandates. Provence lavender supply chains anchor regional positioning for sleep-hygiene variants.
Japan
Metro Tokyo households demonstrate elevated willingness-to-pay for microencapsulated essential oil formulations with extended release cycles. METI sustainability guidelines shape substrate chemistry preferences toward biodegradable alternatives. Osaka-based retailers coordinate seasonal scent rotations with textile protection functionality.
Fragrant Drawer Liners Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, producing a bifurcated structure. Premium positioning concentrates around heritage fragrance libraries and coordinated pattern-and-scent curation, while volume scale dominates through flat-pack compatible manufacturing. Three archetypes define competitive terrain: artisan-grade heritage houses, mass-market scale operators, and specialty hospitality suppliers. Dominant competitive moves include strategic partnerships with interior design studios and portfolio diversification into sleep-hygiene adjacent categories.
Within the heritage fragrance tier, Crabtree & Evelyn and Michel Design Works exemplify positioning built on provenance and coordinated aesthetic systems. IKEA anchors the scale-driven vector through roll-format cost engineering. These three occupy distinct margin pools without direct confrontation, each representing a non-substitutable archetype for procurement channel segmentation.
| Leading Market Players |
|---|
| Crabtree & Evelyn |
| Michel Design Works |
| Orlandi |
| Scentennials |
| Cala Industries |
| Conimar Group LLC |
| Gorilla Grip |
| IKEA |
| Print Fragrancing |
| Others |
Supply & Pricing Matrix
Sixty-day inventory cycles for microencapsulated essential oil formulations concentrate cost leverage among Nordic pulp mill suppliers, compressing margin pools for recycled paper substrate converters while amplifying pricing power for heritage fragrance houses with captive scent libraries.
Pricing Analysis
Refill pack subscriptions and hospitality replenishment contracts drive lifetime value capture beyond initial boxed-set purchases. Pricing stratifies across premium artisanal collections, standard boutique retail formats, and economy flat-pack rolls. Cost compression in mass-market channels intensifies as IKEA and big-box operators crowd shelf space with undifferentiated continuous formats. Household consumers in California and Pacific Northwest markets show lowest price sensitivity for EPA Safer Choice certified plant-derived carriers, while kitchen drawer applications face acute margin pressure.
Supply Chain Analysis
Container availability constraints on Baltic Sea routes elevate inbound logistics costs for Swedish and Finnish post-consumer fiber shipments. Raw material sourcing draws from Nordic pulp mills, Provence lavender cooperatives, and Pacific Northwest cedar oil distillers. Single-source vulnerability concentrates in microencapsulation formulation expertise held by legacy personal care chemical suppliers. Distribution runs through heritage homeware retailers in London and Manchester, boutique hospitality procurement channels in Paris and Hamburg, and flat-pack big-box networks across North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity intensifies as closet wellness curation splinters demand into scent-specific micro-segments, creating niches for certified-sustainable entrants between heritage fragrance houses and mass-market scale operators.
For Market Incumbents: Compound heritage fragrance library advantages through exclusive pattern-and-scent coordination contracts with United Kingdom interior design studios. Defend against algae-derived biodegradable substrate disruption by securing early pilot placement with Scandinavian hospitality buyers. Prioritize in-house microencapsulation capability builds to reduce dependency on legacy personal care chemical suppliers.
For New Entrants and Emerging Players: EPA Safer Choice certification fast-tracks market entry into California household segments where regulatory pull creates preference premiums. White space concentrates in boutique hotel amenity programs across Paris and Tokyo, where presentation-driven boxed sets remain underpenetrated. Launch through direct partnerships with Manchester and London heritage homeware retailers to bypass crowded mass-market shelf competition.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified home fragrance conglomerates with undermonetized drawer liner assets. Five-to-ten year viability hinges on regulatory compliance infrastructure transferability across REACH and California SCP jurisdictions. Monitor ECHA enforcement timelines on synthetic musk restrictions as inflection indicator for botanical replacement formulation valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Fragrance Library Licensing | Crabtree & Evelyn's scent archive creates exclusive pattern coordination moats against mass-market competitors. |
| Algae-Derived Substrate Pilot Programs | Scandinavian hospitality buyers test biodegradable nonwoven formats that decompose incumbent petrochemical binder advantages. |
| REACH Annex XVII Pre-Compliance Reformulation | United Kingdom boxed-set manufacturers leverage transparency investments as positioning wedge against synthetic musk-dependent rivals. |
| Interior Design Studio Specification Partnerships | London and Manchester showrooms drive artisanal format adoption through coordinated scent-and-pattern curation for residential projects. |
| Subscription Refill Model Deployment | Cedarwood and lavender segments capture recurring revenue from California households with elevated EPA Safer Choice certification preference. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with fragrance chemists, heritage homeware retail buyers, hospitality procurement managers, and California regulatory affairs specialists; and secondary validation through ECHA REACH dossier filings, EPA Safer Choice certified product registries, United Kingdom customs import records, and Nordic pulp mill production disclosures. Bottom-up unit economics triangulated against top-down category spend estimates.
Across the projection horizon, the analytical framework modeled material type segmentation by substrate chemistry and scent profile, packaging format differentiation by procurement channel, and geographic regulatory cluster alignment. CAGRs derived from historical volume trajectories adjusted for enforcement timeline impacts on synthetic musk formulations and microencapsulation technology diffusion curves.
Underlying assumptions cover sustained California SCP and REACH Annex XVII enforcement stringency, with deviation risk concentrated in energy-driven input volatility for recycled paper substrates and fragrance chemist talent scarcity constraining formulation pipeline expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Soundproof Curtains Market
Homecare and Decor
Global Homeware Market
Homecare and Decor
Global Wallpaper Market
Homecare and Decor
United States Home Decor Market
Homecare and Decor
India Sustainable Home Decor Market
Homecare and Decor
Composite Doors and Windows Market
Homecare and Decor
Soundproof Door Market
Homecare and Decor
Window Blinds Market
Homecare and Decor
Rift Sawn Lumber Market
Homecare and Decor
North America Sustainable Home Decor Market
Homecare and Decor
Home Decor and Accessories Market
Homecare and Decor
Europe Commercial Blinds and Shades Market
Homecare and Decor
Stained Glass Market
Homecare and Decor
Hearth Market
Homecare and Decor
France Steam Rooms Market
Homecare and Decor
Decorations and Inclusions Market