
 Wall Covering Market | 2026-2036
Wall Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Wall Covering Market Intelligence
Aftermarket service revenue from wall covering maintenance and refurbishment is tilting toward premium substrate providers. Saint-Gobain leverages its building materials ecosystem to anchor large-format commercial projects across Europe. York Wallcoverings sustains artisan manufacturing heritage while competing in the designer residential segment. A.S. Création Tapeten AG specializes in digitally printed custom collections that dominate mid-market European distribution.
Wall coverings comprise surface-applied materials including paper-backed vinyl with weight ratings from 13 to 25 ounces per linear yard, non-woven substrates bonded with fiberglass or cellulose pulp, and engineered wood panels with fire-retardant Class A ratings, serving primarily to protect structural surfaces while enabling aesthetic customization and acoustic control in built environments. Vinyl wall coverings occupy the largest share of commercial specification due to scrubbability and infection-control protocols, while fabric substrates represent the fastest-growing category as biophilic design principles penetrate corporate interiors. Wood panels retain premium positioning in hospitality lobbies where natural material specifications command higher installed-value margins.
EPA regulations on volatile organic compound emissions constrain solvent-based adhesive formulations and printing processes in the United States, while REACH restrictions on phthalate plasticizers redirect European vinyl formulation toward bio-based plasticizer alternatives. ECHA substance-of-very-high-concern listings accelerate substitution of certain flame retardants in textile wall coverings. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment supply chain standardization and create region-specific product line requirements.
Market Dynamics
Antimicrobial vinyl formulations are redefining commercial specifications as hospitality and healthcare renovation cycles compress replacement timelines and elevate performance requirements for infection-resistant surfaces.
Growth Catalysts
- EPA VOC emission standards:Stricter limits on solvent-based adhesives and printing processes in the United States are accelerating water-based formulation adoption across domestic manufacturing facilities.
- Hospitality renovation cycles:Hotel and resort refurbishment programs are expanding specification of scrubbable antimicrobial wallcoverings to meet elevated hygiene protocols in guest-facing spaces.
- Cellulose pulp bonding:Non-woven substrate manufacturing is displacing traditional paper backing in high-traffic commercial installations due to superior dimensional stability and seam performance.
Market Restraints
- Phthalate plasticizer substitution costs:REACH restrictions on conventional plasticizers in European vinyl formulations are forcing reformulation investments that compress margin structures for regional producers.
- Flame retardant substance listings:ECHA substance-of-very-high-concern designations are accelerating phase-outs of halogenated retardants in textile wall coverings before certified alternatives achieve scale.
- Raw material concentration:Specialized non-woven substrate supply concentrates among German and Italian producers, creating vulnerability to energy cost volatility and logistics disruption.
Strategic Opportunities
- Biophilic design penetration:Corporate interior specifications are elevating fabric and engineered wood substrates as natural material alternatives to synthetic surfaces in wellness-focused workplace environments.
- Digital print customization:Mid-market distribution channels are absorbing short-run custom collections that reduce inventory risk and enable rapid response to designer color cycles.
- Acoustic control integration:Healthcare and education construction is specifying wallcoverings with integrated sound-absorption ratings as multi-functional building envelope solutions.
Industry Challenges
- Cross-jurisdictional compliance:Divergent EPA and REACH chemical restrictions are fragmenting product line standardization and forcing region-specific inventory management.
- Installation skill specialization:Large-format vinyl and fabric application demands certified installer networks that lag behind material innovation in several construction markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wall Covering Market |
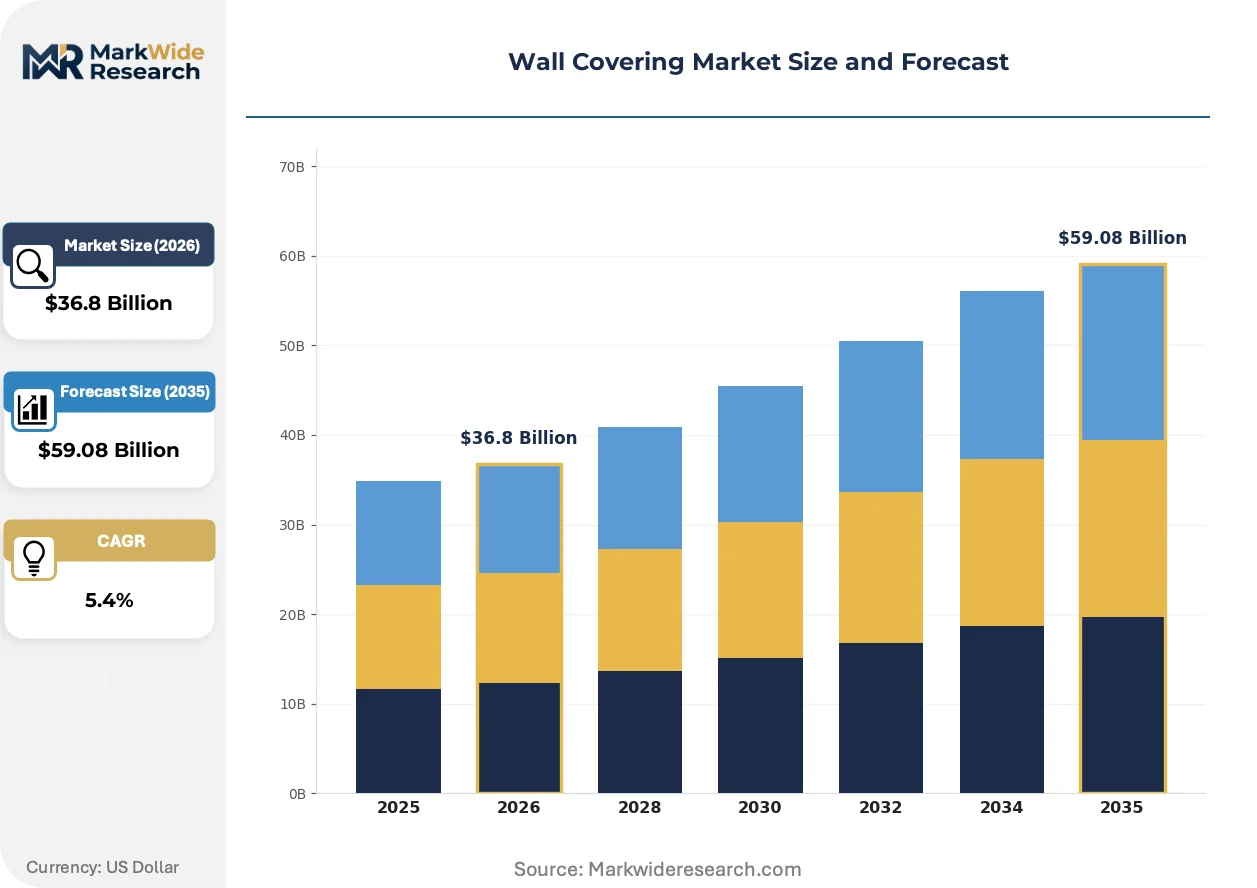
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $59.08 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Papers, Vinyl, Fabrics, Wood Panels Application: Residential, Commercial, Industrial, Hospitality Material: Plastic, Textile, Wood, Metal Distribution Channel: Online Retail, Specialty Stores, Home Improvement, Direct Sales |
| Companies Covered | Saint-Gobain, Asian Paints Ltd., York Wallcoverings, Brewster Home Fashions, F. Schumacher & Co., A.S. Création Tapeten AG, Ahlstrom, Sherwin-Williams, Cole & Son Wallpapers Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wall Covering Market Strategic Shifts & Innovations
Material science convergence with digital manufacturing is compressing production timelines and enabling mass customization that challenges traditional batch-based supply models.
Fiberglass-reinforced non-woven substrates are hybridizing with cellulose pulp bonding to create dimensionally stable backings that accommodate digital printing at production speeds while maintaining commercial-grade scrubbability. Hospitality and corporate buyers are specifying these hybrid constructions for high-traffic corridors and public assembly spaces. The technology is hybridizing supply chain structures by collapsing the distinction between stock and custom production runs.
REACH compliance deadlines are forcing systematic substitution of phthalate plasticizers with bio-based alternatives across European vinyl formulation. Manufacturers serving EU distribution channels are reformulating product lines to maintain market access while managing performance equivalence risks. Textile wall covering segments face accelerated flame retardant substitution timelines as ECHA listings expand, with German and French specification teams driving compliance verification requirements.
Specification decisions are migrating from general contractors to interior design firms with direct material sourcing authority, compressing traditional distribution markups and elevating brand recognition requirements. Designer residential and boutique commercial projects are bypassing wholesale channels for manufacturer-direct relationships. This channel compression is most visible in United States and United Kingdom metropolitan construction markets where design-build integration is advancing fastest.
Wall Covering Market Segmentation
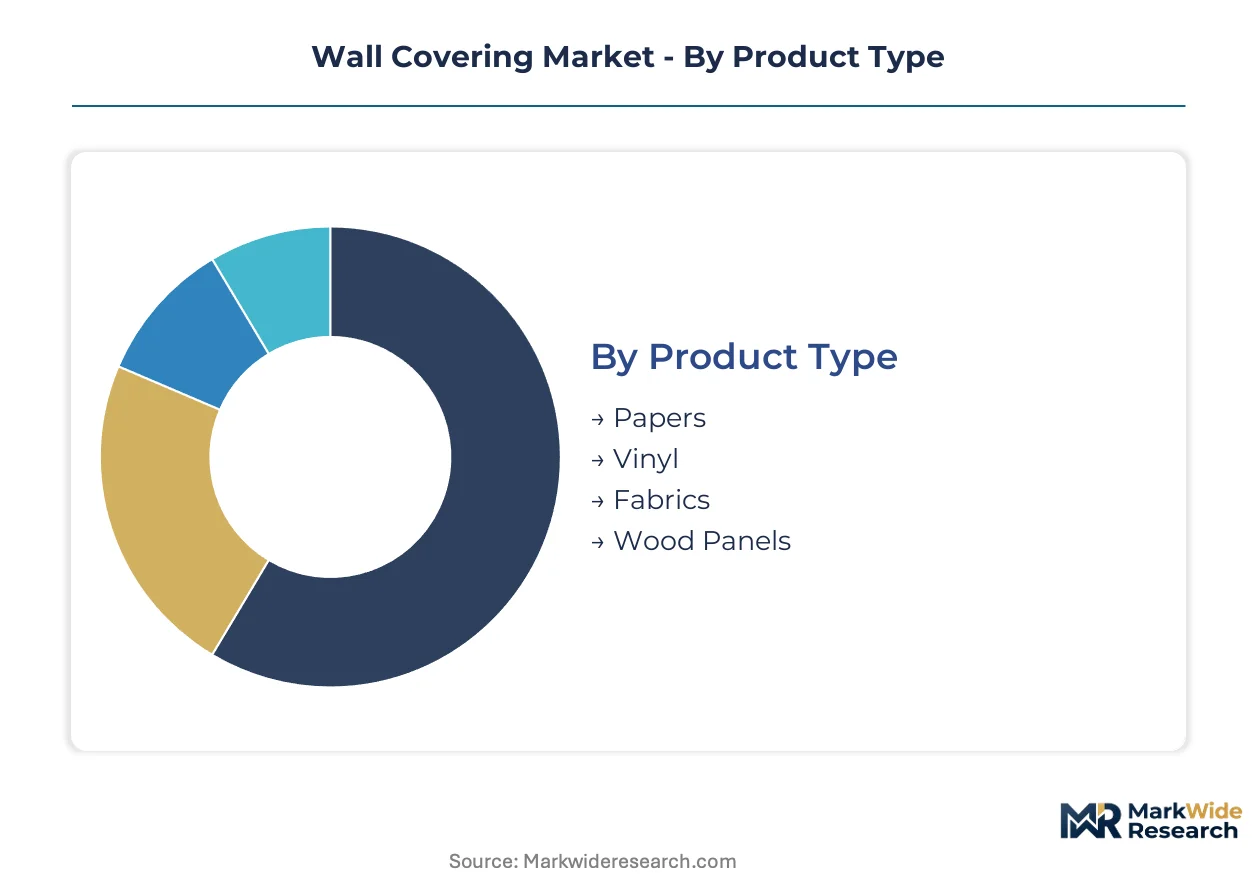
Wall covering segmentation reveals how material specifications diverge across infection-control protocols, acoustic requirements, and aesthetic customization demands. Commercial buyers prioritize scrubbability and antimicrobial performance, while residential channels emphasize design flexibility and installation accessibility.
Product Type:
Vinyl and fabric substrates span the widest use-case spectrum from hospital corridors to boutique hotel lobbies, with material selection driven by traffic intensity and hygiene mandates.
- Vinyl:Paper-backed constructions with 13-25 ounce per linear yard weight ratings deliver commercial-grade scrubbability and antimicrobial surface treatments. Hospitality renovation cycles in the United States and Germany are compressing replacement timelines for infection-resistant specifications.
- Fabrics:Woven and non-woven textile substrates bonded with fiberglass or cellulose pulp enable acoustic absorption ratings and biophilic design integration. Corporate interior specifications across China and Germany are elevating natural material alternatives to synthetic surfaces in wellness-focused workplace environments.
- Papers:Traditional cellulose-based wallcoverings occupy residential and light commercial niches where cost sensitivity outweighs durability requirements.
- Wood Panels:Engineered constructions with Class A fire-retardant ratings command premium positioning in hospitality lobbies where natural material specifications drive higher installed-value margins.
The dominant share belongs to vinyl, while fabric is closing the gap fastest.
Application:
Cost tier stratification separates specification authority between owner-operated facilities and third-party managed properties.
- Commercial:Office buildings, healthcare facilities, and educational institutions specify multi-functional wallcoverings integrating acoustic control with infection-resistant surfaces. EPA VOC emission standards in the United States are constraining solvent-based adhesive formulations across domestic manufacturing.
- Hospitality:Hotels and resorts mandate scrubbable antimicrobial wallcoverings with compressed replacement cycles driven by elevated guest-facing hygiene protocols. REACH compliance deadlines across Europe are forcing systematic substitution of phthalate plasticizers in vinyl formulations serving EU distribution channels.
- Residential:Designer and mass-market segments diverge on customization depth, with direct-to-manufacturer relationships bypassing wholesale channels in United States and United Kingdom metropolitan markets.
- Industrial:Manufacturing and warehouse environments prioritize chemical resistance and impact durability over aesthetic considerations.
Commercial applications generate the highest volume, with hospitality expanding most quickly.
Material:
Supply concentration among German and Italian non-woven substrate producers creates vulnerability to energy cost volatility and logistics disruption.
- Plastic:PVC and bio-based polymer formulations dominate vinyl wall covering production, with REACH restrictions on conventional plasticizers forcing reformulation investments that compress margin structures for European regional producers.
- Textile:Natural and synthetic fiber constructions face accelerated flame retardant substitution timelines as ECHA substance-of-very-high-concern listings expand, with German and French specification teams driving compliance verification requirements.
- Wood:Engineered panel systems with fire-retardant treatments retain premium positioning where natural material authenticity commands specification premiums.
- Metal:Specialized architectural applications in high-traffic public assembly spaces utilize metallic substrates for impact resistance and distinctive surface finishes.
Plastic retains the dominant share, though textile is gaining share fastest.
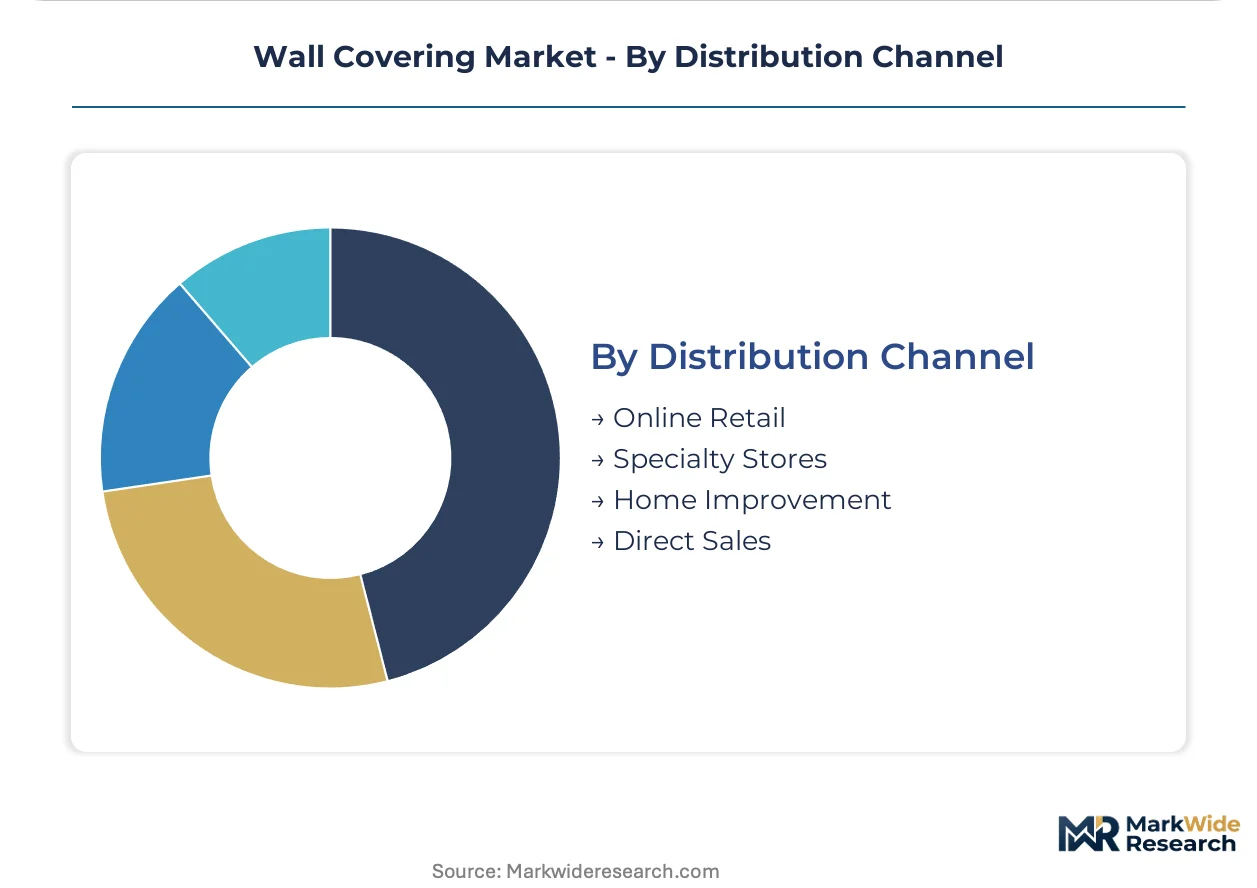
Distribution Channel:
Channel compression is elevating manufacturer-direct relationships while compressing traditional distribution markups in design-build integrated markets.
- Direct Sales:Interior design firms with direct material sourcing authority are bypassing wholesale channels for manufacturer relationships, compressing traditional markups in United States and United Kingdom metropolitan construction markets.
- Specialty Stores:Curated product assortments serve designer residential and boutique commercial projects with high-touch specification support and sample logistics.
- Home Improvement:Mass-market retail channels dominate residential replacement and renovation volume with standardized product ranges and installation accessory bundling.
- Online Retail:Digital platforms are absorbing short-run custom collections that reduce inventory risk and enable rapid response to designer color cycles across mid-market distribution.
Direct sales commands the dominant share, while online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: hospitality renovation cycles dominate specification in the United States, while REACH-driven material reformulation reshapes European procurement, and China's commercial construction rebound concentrates demand in tier-one urban clusters.
United States
Hotel and resort refurbishment programs drive antimicrobial vinyl specification for infection-resistant guest-facing surfaces. EPA VOC emission standards constrain solvent-based adhesive formulations across domestic manufacturing facilities. Chicago and Miami hospitality corridors anchor large-format commercial installations.
Germany
Healthcare and education construction specifies multi-functional wallcoverings integrating acoustic control with scrubbability. ECHA substance-of-very-high-concern listings accelerate halogenated flame retardant phase-outs in textile segments. The Rhine-Ruhr industrial belt concentrates non-woven substrate production vulnerable to energy cost volatility.
China
Corporate interior specifications elevate fabric substrates as biophilic design penetrates wellness-focused workplaces. National GB standards on indoor air quality tighten formaldehyde emission limits for construction materials. Shanghai and Beijing commercial districts absorb premium engineered wood panel systems for hospitality lobbies.
United Kingdom
Design-build integration compresses traditional distribution markups as interior firms bypass wholesale channels for manufacturer-direct relationships. Building Regulations Part B fire safety standards elevate Class A fire-retardant specifications in public assembly spaces. London metropolitan construction markets lead channel compression trends.
France
Boutique hotel and luxury residential projects mandate natural material authenticity commanding premium installed-value margins. ANSM and environmental agency oversight tightens chemical substance reporting for imported wallcovering materials. The Île-de-France region concentrates specification authority among design firms with direct sourcing relationships.
Wall Covering Market Key Industry Players
Capability concentration sits with specialized substrate innovators; scale advantage sits with diversified building materials conglomerates. The vendor base organizes around three tiers: integrated building materials ecosystems, digitally-enabled custom collection specialists, and artisan heritage manufacturers. Dominant competitive moves include strategic partnerships between substrate producers and design firms, plus portfolio diversification into acoustic-integrated multi-functional systems.
Within the diversified materials tier, Saint-Gobain anchors large-format commercial projects across European distribution channels. York Wallcoverings occupies a position exemplifying artisan heritage manufacturing heritage while competing in designer residential segments. A.S. Création Tapeten AG represents digitally-enabled custom collection specialists dominating mid-market European distribution through short-run production capabilities.
| Leading Market Players |
|---|
| Saint-Gobain |
| Asian Paints Ltd. |
| York Wallcoverings |
| Brewster Home Fashions |
| F. Schumacher & Co. |
| A.S. Création Tapeten AG |
| Ahlstrom |
| Sherwin-Williams |
| Cole & Son Wallpapers Ltd |
| Others |
Cost & Logistics Intelligence
The Rhine-Ruhr industrial belt concentrates non-woven substrate production capacity, and this geographic clustering hands German manufacturers outsized leverage in negotiating resin and pulp supply contracts that cascade into vinyl wallcovering pricing tiers across European distribution channels.
Pricing Analysis
Long-term offtake agreements dominate procurement between hospitality chains and antimicrobial vinyl suppliers, insulating volume buyers from spot volatility in PVC resin markets while project-based spot purchasing persists in boutique commercial segments. Price differentiation rests on scrubbability certification tiers and fire-retardant Class A ratings, with premium engineered wood panels commanding substantial margins in hospitality lobbies. Cost compression in mid-market vinyl runs through REACH-driven plasticizer reformulation expenses that European producers struggle to pass through. Mass-market residential channels exhibit acute price sensitivity, whereas corporate wellness-focused buyers prioritize biophilic fabric specifications over unit economics.
Supply Chain Analysis
Contract manufacturing concentration sits with specialized non-woven converters in Germany, Italy, and China, where fiberglass-reinforced cellulose pulp bonding capacity feeds digital printing operations serving custom collection demand. Raw material dependencies center on PVC resin, bio-based plasticizer alternatives, and halogen-free flame retardant compounds. Single-source vulnerability concentrates in German substrate producers exposed to natural gas cost spikes. Distribution runs through specification-driven channels where interior design firms increasingly bypass wholesale intermediaries for manufacturer-direct relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among design-build integrated firms in United States and United Kingdom metropolitan markets, fragmenting traditional distribution markups and elevating direct procurement leverage over substrate specification decisions.
For Market Incumbents: Entrench antimicrobial performance leadership through backward integration into bio-based plasticizer supply chains, insulating margin structures from REACH compliance cost spikes while locking hospitality chains into multi-year renovation cycle contracts. Expand certified installer networks in Chicago and Miami corridors to capture large-format application value that material innovation currently outpaces. For New Entrants and Emerging Players: Establish a beachhead in acoustic-integrated fabric wallcoverings for healthcare and education construction, where biophilic design penetration outstrips incumbent R&D pipelines and specification authority sits with design firms receptive to manufacturer-direct relationships. Target mid-market European distribution through short-run digital print capabilities that reduce inventory risk versus batch-based competitors. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because substrate specialization and regulatory compliance burdens favor scaled operators with reformulation expertise and design firm channel control. Acquisition targets should demonstrate REACH-compliant vinyl portfolios or fiberglass-non-woven hybrid production capabilities. Watch ECHA substance-of-very-high-concern listing velocity as a signal for accelerated flame retardant substitution timelines that could strand non-compliant inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Plasticizers | REACH compliance deadlines in Europe force systematic substitution away from phthalate formulations. |
| Digital Print Customization Capabilities | Short-run production collapses stock-versus-custom distinctions and compresses designer color cycle response times. |
| Acoustic-Integrated Product Development | Healthcare and education construction specifies multi-functional wallcoverings merging sound absorption with infection resistance. |
| Certified Installer Network Expansion | Large-format vinyl and fabric application demands specialized skills that lag material innovation in several construction markets. |
| Design Firm Direct Relationship Programs | Channel compression in United States and United Kingdom metropolitan markets elevates manufacturer brand recognition requirements. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with wallcovering plant managers, procurement leads at hospitality chains, interior design firm specification directors, and distribution channel partners; and secondary validation through customs and trade data, EPA VOC emission filings, ECHA substance registrations, and SEC disclosures from building materials conglomerates. Bottom-up volume modeling triangulated against top-down construction spending forecasts across commercial, hospitality, and residential end-uses.
Forecast inputs incorporated product type segmentation across vinyl, fabric, paper, and wood panel substrates; application splits between commercial, hospitality, residential, and industrial channels; material-grade tiers reflecting fire-retardant certification levels; and distribution channel dynamics spanning direct sales, specialty retail, home improvement, and online platforms. CAGRs were derived from regression analysis against commercial construction indices and hospitality renovation cycle frequencies, with antimicrobial performance premiumization and biophilic design penetration treated as demand elasticity modifiers.
Sensitivities concentrate around ECHA substance listing expansions, EPA emission standard tightening trajectories, and energy cost volatility in German substrate production clusters. Forecasts embed assumptions regarding REACH compliance timeline adherence and hospitality hygiene protocol permanence. Quarterly review of regulatory filing velocities, hospitality capital expenditure announcements, and design firm procurement pattern shifts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Smart Vase Market
Homecare and Decor
India Sustainable Home Decor Market
Homecare and Decor
India Wallpapers Market
Homecare and Decor
Terracotta Pots Market
Homecare and Decor
India Furniture Hardware Market
Homecare and Decor
India Home Furnishing Market
Homecare and Decor
Builders and Cabinet Hardware Market
Homecare and Decor
Home Decor Market
Homecare and Decor
Asia-Pacific Decorative Laminates Market
Homecare and Decor
United States Wall Covering and Wall Decor Market
Homecare and Decor
Wall Covering Products Market
Homecare and Decor
Soundproof Curtains Market
Homecare and Decor
Door Stopper Market
Homecare and Decor
Mattresses and Accessories Market
Homecare and Decor
Pillow Cases Market
Homecare and Decor
New Zealand Window Covering Market