
 Corner Pads Market | 2026-2036
Corner Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Corner Pads Market Outlook
A capital-intensity divergence between integrated paperboard conglomerates and specialized foam fabricators is unwinding competitive stability in corner pad supply. Smurfit Kappa Group leverages its captive pulp supply and corrugation network to anchor cost positions in paper-based edge protection. Sonoco sustains R&D intensity across molded fiber and expanded polystyrene alternatives, competing on custom-engineered geometries for appliance OEMs. Packaging Corporation of America controls regional distribution density, extending same-day fulfillment capabilities to Midwest furniture manufacturers.
Corner pads are protective cushioning elements installed at vertex points of rectangular objects to absorb impact energy during handling, transit, and storage; they typically measure 25–100 mm in edge length and are manufactured through die-cutting, injection molding, or thermoforming processes depending on substrate. Foam corner pads dominate electronics and furniture applications where low-density polyethylene and polyurethane formulations deliver calibrated compression resistance, while gel segments are gaining traction in high-value automotive glass shipping due to reusable, non-marking surface contact properties. Plastic corner pads retain cost leadership in high-volume industrial logistics, though margin pools are shifting toward self-adhesive installation formats that reduce labor at packing stations.
The EPA regulates volatile organic compound emissions from foam curing operations under Clean Air Act standards, while OSHA mandates ergonomic load-handling protocols that indirectly elevate demand for lighter protective packaging materials. REACH restrictions on certain phthalate plasticizers and the EU Green Deal packaging recyclability targets are reshaping material qualification processes for exporters serving European electronics and automotive end users. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to internalize recycling infrastructure or partner with specialized reverse logistics operators.
Market Dynamics
EU Packaging and Packaging Waste Regulation recyclability mandates are forcing converters to requalify material portfolios, compressing lead times for bio-based corner pad formulations while electronics OEMs accelerate protective packaging standardization.
Growth Catalysts
- REACH phthalate restrictions:Electronics exporters serving European automotive glass manufacturers are switching to non-plasticizer foam formulations, expanding addressable demand for compliant corner pad suppliers.
- Automotive OEM protective packaging standardization:Third-party logistics providers in Germany are mandating unified corner pad specifications across inbound glass and electronics shipments, consolidating specification volumes.
- Gel pad reusability:High-value automotive glass shippers are adopting gel-based corner pads for non-marking surface contact properties, creating pull-through demand for durable cushioning formats.
Market Restraints
- Petrochemical input volatility:Low-density polyethylene and polyurethane foam feedstock costs swing with crude oil indices, compressing converter margins during price spike periods.
- Pulp supply concentration:Integrated paperboard conglomerates control captive pulp networks, limiting independent molded fiber corner pad producers' cost competitiveness at scale.
- Expanded polystyrene substitution threat:Lightweight molded pulp alternatives are capturing share in appliance shipping, pressuring EPS corner pad pricing power in furniture logistics.
Strategic Opportunities
- India electronics manufacturing clusters:PLI scheme incentives for semiconductor and mobile device production are expanding protective packaging demand in Noida and Sri City industrial corridors.
- Self-adhesive installation formats:Labor reduction at packing stations is driving specification shifts toward peel-and-stick corner pads in high-volume e-commerce fulfillment centers.
- EU Green Deal packaging targets:Extended producer responsibility frameworks are creating first-mover advantages for converters with certified recyclable or compostable corner pad portfolios.
Industry Challenges
- Bio-based material certification timelines:Industrial compostability validation under EN 13432 requires 12-18 month testing cycles, delaying new product commercialization for sustainability-focused converters.
- Multi-substrate production integration:Foam fabricators adding molded fiber lines face thermoforming-to-pulp molding equipment incompatibility, complicating capital deployment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corner Pads Market |
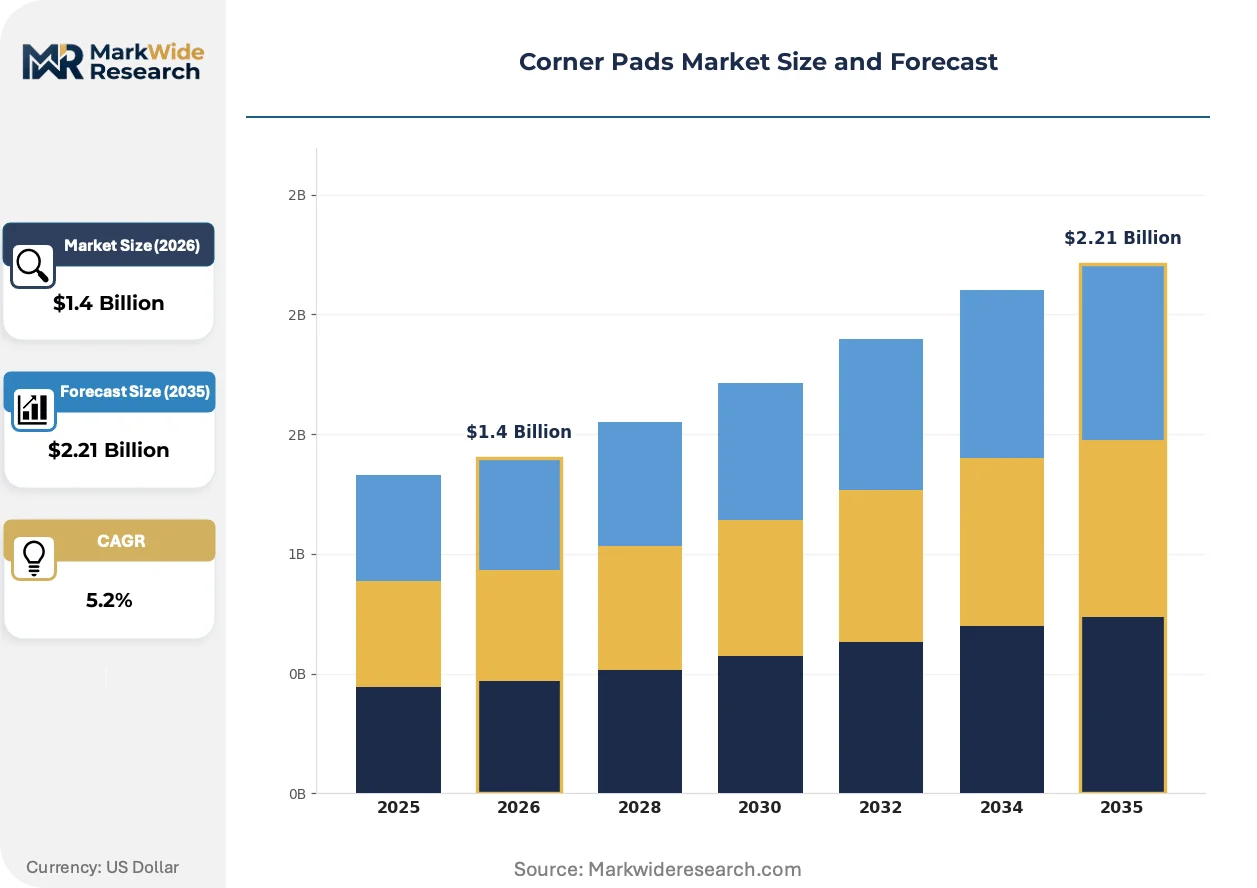
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Rubber, Plastic, Gel Application: Furniture, Electronics, Shipping, Automotive Installation: Self-Adhesive, Mechanical, Embedded, Removable End User: Residential, Commercial, Industrial, Institutional |
| Companies Covered | Smurfit Kappa Group, Sonoco, Packaging Corporation of America, ImpactSafe Solutions, CornerGuard Technologies, ProtectiveEdge Inc., ImpactGuard Industries, SafeCorner Innovations, IPS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corner Pads Market Strategic Shifts
Material science advances and installation format evolution are reconfiguring competitive advantage in protective cushioning, with sustainability credentials and labor efficiency emerging as primary specification drivers across electronics and automotive logistics.
Polyurethane foam formulations with bio-based polyol content are decomposing the virgin petroleum dependency of traditional corner pads. Electronics contract manufacturers in Taiwan and South Korea are qualifying these hybrid foams for smartphone and tablet shipments. The technology is decomposing cost premiums between sustainable and conventional formulations, compressing margin structures for pure-petroleum foam specialists.
REACH restrictions on phthalate plasticizers are accelerating non-toxic foam curing process adoption across European supply chains. German automotive glass logistics providers now require full material disclosure documentation for inbound protective packaging. Molded fiber and gel pad categories are capturing specification share previously held by plasticized foam in premium shipping applications.
Specification consolidation among third-party logistics providers is compressing supplier diversity in furniture and appliance shipping. Midwest US manufacturers now source corner pads through centralized procurement platforms rather than regional converter relationships. This concentration is most visible in Germany, where automotive OEM packaging engineering teams are reducing approved supplier lists from twelve to four qualified converters.
Corner Pads Market Segmentation
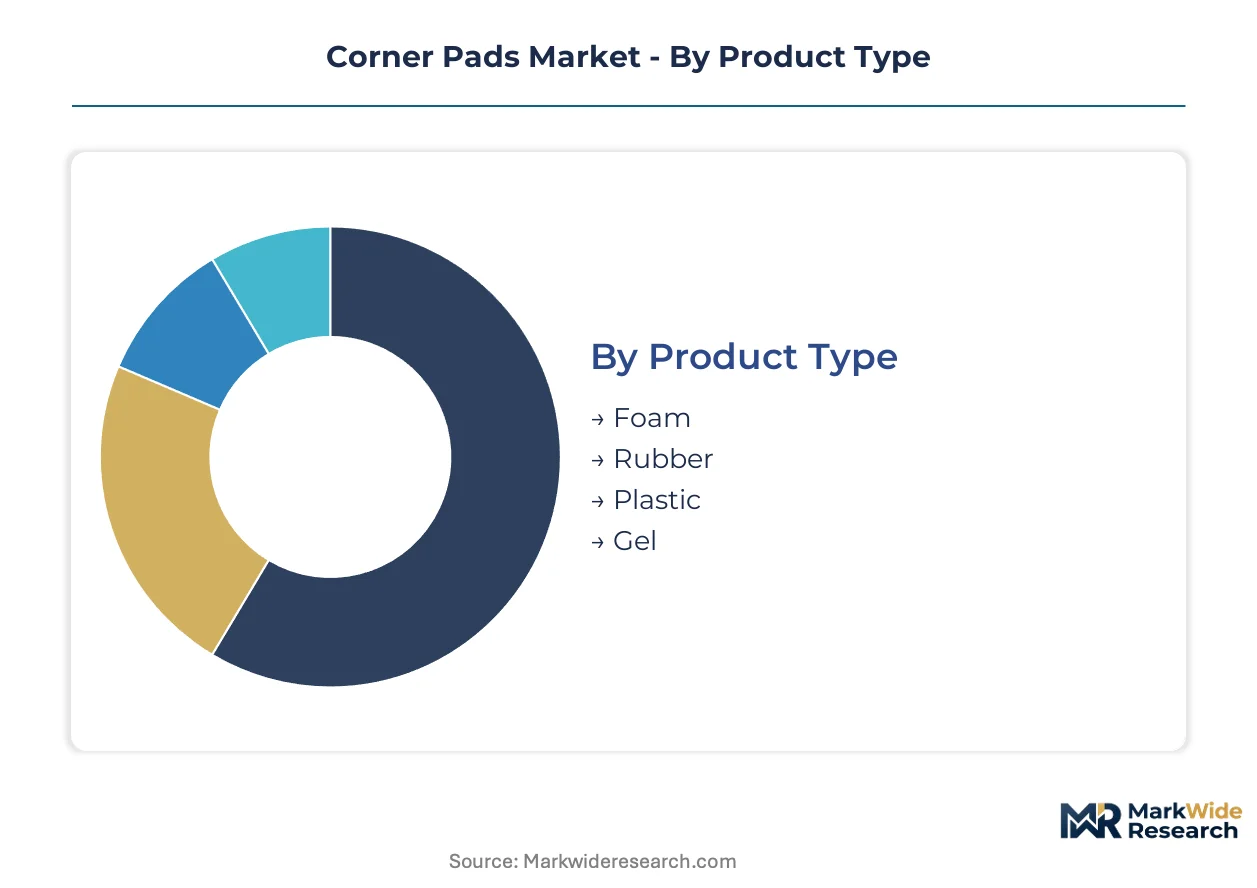
Corner pad segmentation reveals how material substitution pressures and installation efficiency demands are fragmenting procurement patterns across electronics, automotive, and furniture logistics. Specification consolidation among third-party logistics providers is compressing supplier diversity while creating tiered performance requirements by end-use.
Product Type:
Foam faces the most acute substitution threat as REACH phthalate restrictions and molded fiber advances erode its historical dominance in furniture and appliance shipping.
- Foam:Low-density polyethylene and polyurethane formulations deliver calibrated compression resistance for fragile electronics. German automotive glass logistics providers are mandating non-plasticizer foam formulations under REACH compliance timelines, compressing margin pools for conventional suppliers.
- Gel:Reusable, non-marking surface contact properties distinguish gel corner pads for high-value automotive glass shipments. Demand concentrates among German OEMs and tier-one suppliers standardizing protective packaging specifications for inbound windshield and sunroof deliveries.
- Rubber:Synthetic and natural rubber compounds serve heavy industrial machinery shipping where abrasion resistance exceeds cushioning priorities.
- Plastic:Injection-molded polypropylene and expanded polystyrene retain cost leadership in high-volume industrial logistics despite EU recyclability mandates pressuring material qualification.
Foam retains volume leadership; gel holds the steepest expansion curve.
Application:
Cost tier differentiation separates premium specification markets from commodity logistics procurement.
- Electronics:Smartphone, tablet, and semiconductor shipments require anti-static foam formulations with precise compression set specifications. Taiwan and South Korean contract manufacturers are accelerating bio-based polyol qualification, decomposing cost premiums between sustainable and conventional formulations.
- Automotive:Windshield, sunroof, and EV battery pack shipping demands non-marking, reusable cushioning with full material disclosure documentation. German OEM packaging engineering teams are consolidating approved supplier lists from twelve to four qualified converters.
- Furniture:Appliance and home furnishings logistics increasingly specify molded pulp alternatives, pressuring expanded polystyrene pricing power in Midwest US distribution corridors.
- Shipping:Third-party logistics standardization across multi-client fulfillment centers favors self-adhesive formats that reduce labor at packing stations.
Electronics commands premium pricing tiers; automotive is gaining share fastest.
Installation:
Volume concentration in e-commerce fulfillment is elevating labor efficiency as a primary specification driver.
- Self-Adhesive:Peel-and-stick backing eliminates secondary taping operations at high-velocity packing stations. Amazon and major third-party logistics providers in Germany and the US Midwest are mandating adhesive-backed formats for furniture and electronics fulfillment.
- Mechanical:Strap-secured and interlocking designs serve reusable container systems in closed-loop automotive component logistics.
- Embedded:Pre-installed corner protection in molded pulp trays and thermoformed dunnage integrates with automated packaging lines.
- Removable:Magnetic and clip-on formats support temporary protection during intra-facility material handling before final shipment.
Self-adhesive dominates new specifications; embedded is climbing the fastest in automated lines.
End User:
Customer type determines whether procurement emphasizes total cost of ownership or upfront material expense.
- Industrial:Automotive OEMs and tier-one electronics contract manufacturers specify certified recyclable portfolios under extended producer responsibility frameworks. EU Green Deal packaging targets are creating first-mover advantages for converters with compostable corner pad certifications.
- Commercial:Furniture retailers and appliance distributors balance damage reduction against labor efficiency in high-volume shipping operations.
- Residential:DIY moving and storage applications represent fragmented, price-sensitive demand served through retail hardware channels.
- Institutional:Government and healthcare logistics prioritize compliance documentation over material cost minimization.
Industrial end users drive specification innovation; commercial represents the largest addressable volume pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in protective cushioning track electronics and automotive manufacturing gravity, with Germany, the United States, China, and South Korea commanding disproportionate specification influence over cross-border packaging standards.
Germany
Automotive glass logistics and third-party fulfillment standardization drive specification consolidation. REACH phthalate restrictions enforced by ECHA mandate non-plasticizer foam documentation for inbound shipments. Stuttgart and Munich industrial corridors host OEM packaging engineering teams reducing approved supplier lists from twelve to four qualified converters.
United States
Midwest furniture manufacturing and e-commerce fulfillment automation elevate labor-efficient formats. EPA Clean Air Act standards regulate volatile organic compound emissions from foam curing operations across Ohio and Michigan production zones. Chicago distribution density enables same-day fulfillment capabilities for regional appliance manufacturers.
China
Electronics contract manufacturing clusters in the Yangtze River Delta and Pearl River Delta generate protective packaging demand at scale. GB standards and MIIT industrial policy shape material qualification timelines for export-oriented foam fabricators. Shenzhen and Dongguan semiconductor assembly facilities accelerate bio-based polyol qualification for smartphone shipments.
South Korea
Display panel and memory chip exports sustain premium cushioning specifications. MFDS and METI-aligned standards influence material disclosure requirements for automotive component shipments. Suwon and Pyeongtaek electronics corridors concentrate demand for anti-static foam formulations with precise compression set tolerances.
India
PLI scheme incentives for semiconductor and mobile device production expand protective packaging demand. BIS certification requirements and DGFT export protocols shape converter qualification processes. Noida and Sri City industrial corridors attract specification investment from multinational electronics contract manufacturers.
Corner Pads Market Competitive Environment
Concentration sits with integrated paperboard conglomerates controlling captive pulp networks and regional distribution density, while specialized foam fabricators compete on custom-engineered geometries and material formulation agility. Three archetypes dominate: vertically integrated paperboard producers with corrugation scale, specialized foam and gel compounders serving premium automotive specifications, and regional converters competing on fulfillment velocity. Competitive moves center on backward integration into bio-based raw material sourcing and strategic partnerships with third-party logistics providers to embed specifications.
Among Ireland-based integrated packaging conglomerates, Smurfit Kappa Group anchors the paperboard archetype with captive pulp supply control. Sonoco, a US-based multinational, exemplifies the diversified protective packaging specialist model spanning molded fiber and expanded foam alternatives. Packaging Corporation of America occupies a position within the regional density-focused tier, leveraging Midwest distribution proximity to furniture and appliance manufacturers.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| Sonoco |
| Packaging Corporation of America |
| ImpactSafe Solutions |
| CornerGuard Technologies |
| ProtectiveEdge Inc. |
| ImpactGuard Industries |
| SafeCorner Innovations |
| IPS |
| Others |
Value Chain & Pricing Dynamics
Captive pulp networks at integrated paperboard conglomerates compress cost floors for molded fiber corner pads while elevating entry barriers for independent foam fabricators competing on petroleum-derived formulations. Scale concentration in Germany and the US Midwest enables same-day fulfillment premiums that smaller regional converters cannot match, bifurcating price structures between density-anchored incumbents and formulation-specialist challengers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the corner pads market. Price differentiation rests on certification grade under EU Green Deal recyclability targets and volume scale commitments from automotive OEM packaging engineering teams. Cost compression in standard-grade foam tiers is intensifying because REACH phthalate restrictions force rapid material requalification. Commercial furniture retailers exhibit the highest price sensitivity due to thin logistics margins, while German automotive glass shippers prioritize non-marking surface contact properties over unit cost.
Supply Chain Analysis
Inventory cycles for bio-based polyol formulations stretch 12-18 months behind industrial compostability validation timelines, constraining converter responsiveness to specification shifts. Supply concentrates in Germany, the United States, and China, with automotive OEM corridors in Stuttgart and electronics clusters in Shenzhen commanding disproportionate specification influence. Raw material dependencies draw from low-density polyethylene resin, pulp feedstock, and specialized gel compounds. Single-source vulnerability sits with petrochemical feedstock exposure to crude oil indices. Distribution runs through third-party logistics provider procurement platforms that consolidate approved supplier lists from twelve to four qualified converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corner pads market represents a high-growth disruption as EU Packaging and Packaging Waste Regulation recyclability mandates force material portfolio requalification across European electronics and automotive supply chains.
For Market Incumbents: Secure backward integration into bio-based polyol sourcing to defend margin positions against petroleum feedstock volatility. Lock in long-term supply agreements with German automotive OEM packaging engineering teams before supplier list consolidation completes. Capacity addition in Noida and Sri City industrial corridors captures PLI scheme-driven electronics manufacturing expansion.
For New Entrants and Emerging Players: Self-adhesive installation format specialization offers a service-layer gap where incumbents under-serve high-velocity e-commerce fulfillment demand. Target India electronics manufacturing clusters with localized bio-based formulation production to bypass EN 13432 certification timeline disadvantages. Lead with peel-and-stick corner pad specifications through direct partnerships with Amazon and major third-party logistics providers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized foam and gel compounders with custom-engineered geometry capabilities over commodity paperboard converters. The five-to-ten year viability window rewards acquisition targets holding certified recyclable portfolios under extended producer responsibility frameworks. Watch for gel pad reusability adoption rates among German automotive glass shippers as the inflection indicator for durable cushioning format migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Material Certification Investment | EN 13432 compostability validation accelerates qualification for EU Green Deal procurement mandates. |
| Self-Adhesive Format Capacity Expansion | Peel-and-stick production lines capture labor-efficiency specifications from Amazon fulfillment centers. |
| Backward Integration into Polyol Sourcing | In-house bio-based feedstock production insulates margins from petroleum price volatility. |
| Third-Party Logistics Partnership Embedding | Direct collaboration with German automotive OEM packaging teams secures approved supplier list positions. |
| India Manufacturing Footprint Establishment | Noida and Sri City production sites leverage PLI scheme incentives for semiconductor protective packaging demand. |
Study Parameters
A standing panel of packaging engineering directors at automotive OEMs, procurement leads at third-party logistics providers, foam fabrication plant managers, and sustainability compliance officers provided ongoing calibration across primary research phases. Secondary validation drew from EU ECHA regulatory filings, EPA Clean Air Act enforcement records, customs trade data for protective cushioning imports, and SEC 10-K disclosures from integrated paperboard conglomerates. Bottom-up demand modeling across electronics, automotive, and furniture end uses triangulated against top-down market sizing from converter capacity assessments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by material substrate, installation format, application vertical, and end-user procurement archetype. CAGRs were derived from elasticity-adjusted demand curves incorporating REACH compliance timeline acceleration and bio-based polyol cost convergence assumptions. Forecast inputs included automotive OEM supplier consolidation rates and e-commerce fulfillment automation adoption patterns.
Material uncertainties — petrochemical input volatility, EN 13432 certification delays, and extended producer responsibility framework implementation timing — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and substitution elasticity between foam and molded fiber alternatives. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Europe Commercial Blinds and Shades Market
Homecare and Decor
India Wall Decor Market
Homecare and Decor
ASEAN UPVC Doors and Windows Market
Homecare and Decor
Hospital Bedsheet and Pillow Cover Market
Homecare and Decor
Vinyl Wallpaper Market
Homecare and Decor
Interior Design Market
Homecare and Decor
Smart Vase Market
Homecare and Decor
Builders and Cabinet Hardware Market
Homecare and Decor
Global Decorative Laminates Market
Homecare and Decor
Gas Fire Table Market
Homecare and Decor
United States Home Decor Market
Homecare and Decor
India Sustainable Home Decor Market
Homecare and Decor
Asia-Pacific Decor Paper Market
Homecare and Decor
Rift Sawn Lumber Market
Homecare and Decor
Fireplace and Stove Market
Homecare and Decor
Asia-Pacific Sustainable Home Decor Market