
 Vinyl Wallpaper Market | 2026-2036
Vinyl Wallpaper Market Size, Share, and Industry Trends Forecast 2026-2036
Vinyl Wallpaper Market Analytics
Digital color-matching and print-on-demand subscription services for interior designers is hardening as a revenue layer beyond physical rolls. Sangetsu Corporation leverages its integrated manufacturing base in Japan to sustain premium positioning across Asian hospitality projects. York Wall Coverings anchors North American distribution through dedicated contractor channels and specialized retail partnerships.
Vinyl wallpaper consists of a polyvinyl chloride or PVC-based surface layer bonded to paper or non-woven backing, typically manufactured through calendering or extrusion processes at thicknesses ranging from 0.15 to 0.40 millimeters, serving primarily as a durable, washable decorative wall finish for high-traffic interiors. Peel and Stick formats are capturing share among residential renovation segments where labor cost sensitivity and DIY installation dominate purchasing decisions. Hospitality end use commands the deepest margin pools due to custom color runs, fire-retardant specifications, and recurring refurbishment cycles in hotel portfolios.
EPA regulations on volatile organic compound emissions influence adhesive formulations and factory-level compliance investments for US-bound production. REACH restrictions on phthalate plasticizers and ECHA substance evaluations are redirecting European sourcing toward bio-based plasticizer alternatives. Stakeholders must monitor evolving chemical compliance thresholds across multiple jurisdictions to maintain product registration validity and avoid supply interruption.
Market Dynamics
China's updated GB standards for indoor air quality are forcing reformulation of PVC plasticizers across Asian manufacturing bases, while Vietnam's hotel construction corridor concentrates specification demand for moisture-resistant hospitality wallcoverings.
Growth Catalysts
- Hospitality Refurbishment Cycles:Hotel portfolios in Southeast Asia require recurring wallcovering replacement every 5-7 years, sustaining recurring demand for fire-retardant and custom color-matched vinyl specifications.
- REACH Plasticizer Restrictions:ECHA substance evaluations on phthalate alternatives are redirecting European sourcing toward bio-based plasticizer formulations, opening premium positioning for compliant manufacturers.
- Digital Print-on-Demand:Color-matching subscription services for interior designers are hardening as a revenue layer beyond physical roll sales, reducing inventory risk for distributors.
Market Restraints
- Petrochemical Input Volatility:PVC resin and plasticizer costs fluctuate with ethylene and chlorine feedstock prices, compressing margin predictability for calendering operations.
- Substitute Material Competition:Non-woven textile wallcoverings and paint systems capture residential renovation spend where labor cost sensitivity dominates purchasing decisions.
- Regulatory Fragmentation:Divergent VOC emission thresholds between EPA regulations for US-bound production and China's GB standards multiply compliance testing burdens.
Strategic Opportunities
- Peel-and-Stick Format Expansion:Self-adhesive vinyl wallpaper captures DIY residential renovation segments in North America where contractor labor availability constrains traditional paste-applied installation.
- EU Green Deal Alignment:Circular economy mandates and recycled content targets create specification preference for PVC products with verified post-consumer recycled backing layers.
- Fire-Rating Premium Tier:Hospitality procurement in Singapore and Dubai increasingly mandates NFPA 286 or EN 13501-1 Class B certification, supporting price differentiation for tested formulations.
Industry Challenges
- Skilled Installer Shortage:Commercial wallcovering application requires certified craftspeople capable of pattern matching and seam sealing, with training pipeline gaps in fast-growing construction markets.
- Multi-Jurisdiction Registration:Maintaining product registration validity across EPA, REACH, and GB compliance regimes demands dedicated regulatory affairs capacity and extended timeline-to-market for new formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinyl Wallpaper Market |
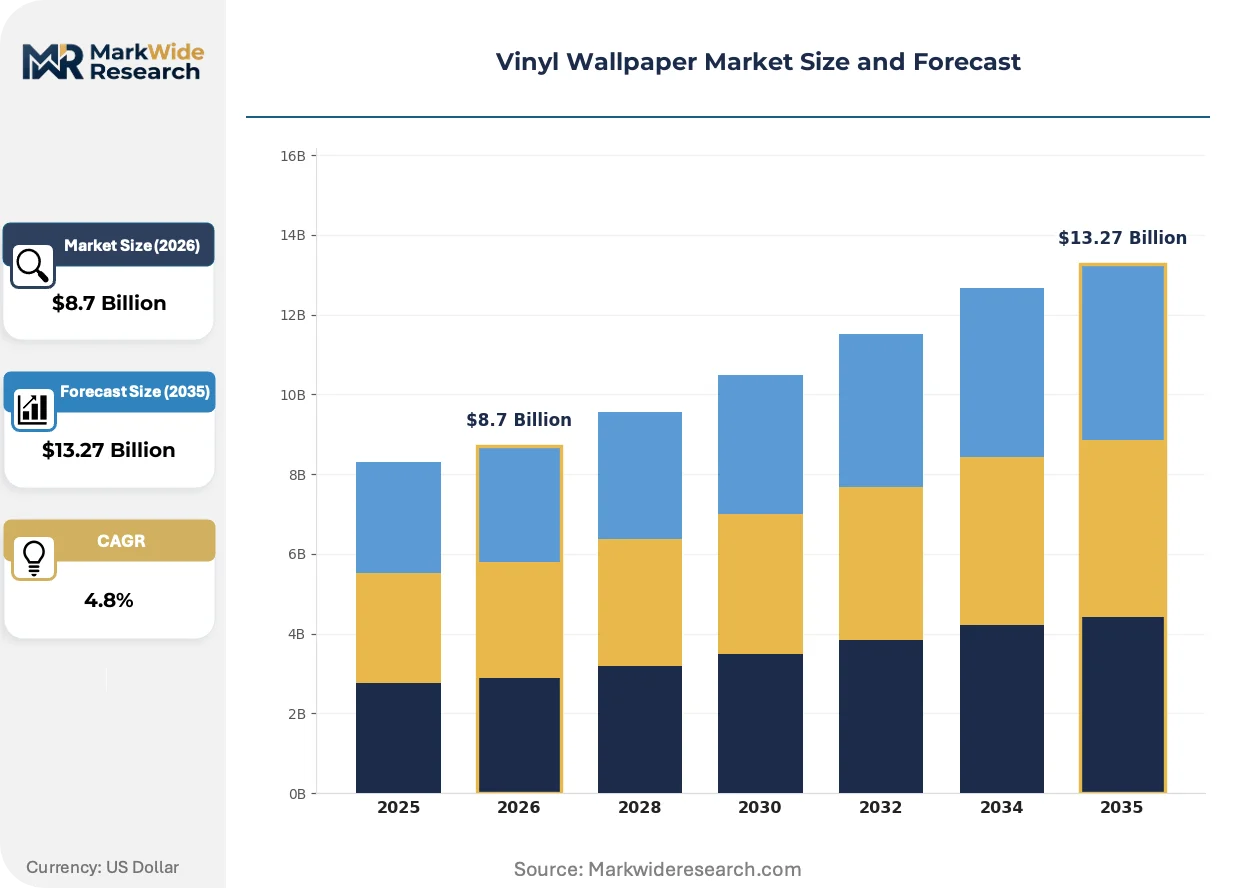
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peel and Stick, Traditional, Textured, Fiberglass End Use: Residential, Commercial, Institutional, Hospitality Material: Vinyl Coated, Vinyl Laminated, Non-Woven, Backed Paper Design Style: Floral, Geometric, Abstract, Striped |
| Companies Covered | Sangetsu Corporation, York Wall Coverings Inc., Brewster Wallpaper Corporation, F. Schumacher & Co., AS Creation Tapeten AG, Osborne & Little, The Romo Group, Grandeco, 4walls, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinyl Wallpaper Market Evolving Landscape
Digital manufacturing integration and chemical compliance evolution are compressing traditional specification cycles while opening new service-based revenue architectures for wallcovering suppliers.
Print-on-demand digital color-matching systems are unifying design visualization, sample production, and final roll manufacturing into single-workflow operations. Hospitality specifiers in Bangkok and Jakarta now expect 48-hour custom color proof turnaround, collapsing traditional 6-week sampling timelines. This compression is enabling project-specific color runs without minimum order quantity penalties, reshaping inventory economics for regional distributors.
REACH restrictions on phthalate plasticizers and ECHA substance evaluations are redirecting formulation chemistry toward bio-based alternatives derived from epoxidized soybean oil and citrate esters. European manufacturers face 2025 compliance deadlines for legacy plasticizer phase-out, accelerating R&D spend on migration-stable alternatives. Hospitality end-use in Germany and France shows early preference for certified bio-based formulations despite 15-20% cost premiums.
Interior designer procurement behavior is fragmenting across direct manufacturer portals, specialized distributor showrooms, and digital sample subscription services. Specification decisions increasingly originate from virtual rendering environments before physical material handling, displacing traditional rep-driven sampling workflows. This disintermediation is most pronounced in North American residential renovation, where designer-direct purchasing bypasses traditional wholesale channels.
Vinyl Wallpaper Market Segmentation
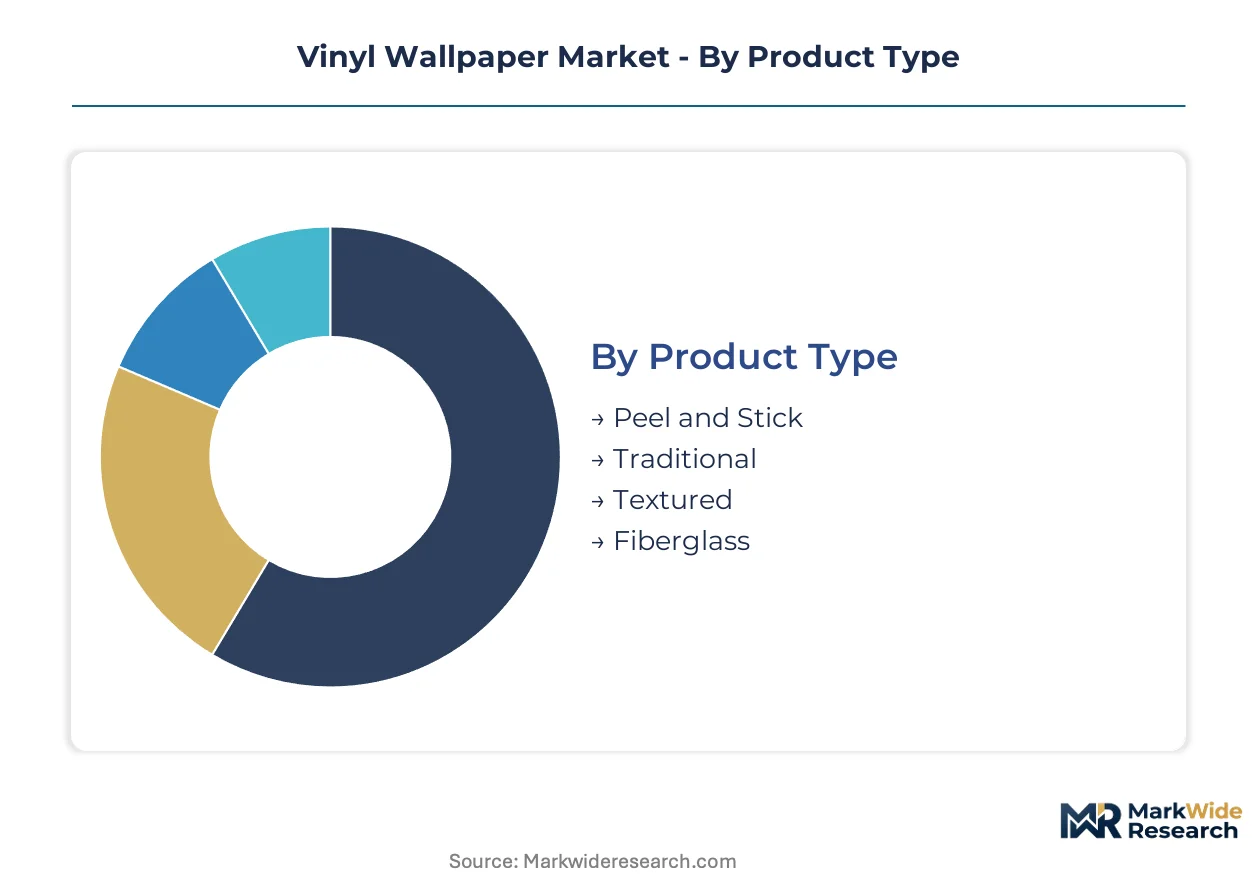
Vinyl wallpaper segmentation maps directly to specification complexity and installation labor requirements. Product format determines whether projects demand certified installers or permit DIY execution, while end-use classification shapes fire-rating and durability requirements.
Product Type:
Upgrade cycles vary dramatically by format, with self-adhesive solutions compressing replacement timelines versus traditional paste-applied specifications.
- Peel and Stick:Pressure-sensitive adhesive backing eliminates paste mixing and professional installation. Residential renovation demand concentrates in North American metro areas where contractor availability constrains project timelines.
- Traditional:Paste-applied vinyl requires skilled pattern matching and seam sealing, commanding premium labor rates. Hospitality portfolios in Singapore and Dubai specify this format for fire-retardant wallcovering cycles.
- Textured:Embossed surface patterns hide wall imperfections in older building stock.
- Fiberglass:Reinforced scrim backing withstands repeated cleaning in healthcare corridors.
Traditional sits at the top of the volume ranking, with Peel and Stick climbing the fastest.
End Use:
Cost tier stratification separates specification-grade procurement from retail-channel purchasing.
- Hospitality:Hotel portfolios demand custom color runs, NFPA 286 fire certification, and 5-7 year refurbishment cycles. Procurement concentrates in Vietnam's construction corridor and Southeast Asian resort developments.
- Residential:DIY renovation spend favors lower-unit-cost formats where labor cost sensitivity dominates purchasing decisions. Digital print-on-demand services are penetrating designer-direct channels.
- Commercial:Office and retail fit-outs balance durability requirements with speed-to-install.
- Institutional:Schools and government buildings prioritize scrubbability and vandal resistance.
Hospitality commands the deepest margin pools, with Residential gaining share fastest through self-adhesive format adoption.
Material:
Application environment dictates backing construction and surface layer composition.
- Vinyl Coated:PVC surface layer applied to paper backing balances cost with washability. China's updated GB standards for indoor air quality are forcing reformulation of plasticizer chemistry across Asian manufacturing bases.
- Vinyl Laminated:Separate PVC film bonded to substrate enables thicker, more durable specifications. REACH restrictions on phthalate plasticizers redirect European sourcing toward bio-based alternatives.
- Non-Woven:Synthetic fiber backing permits strippable removal without wall damage.
- Backed Paper:Entry-grade construction for price-sensitive residential applications.
Vinyl Laminated leads commercial specification volume, with Vinyl Coated expanding most quickly through Asian hospitality projects.
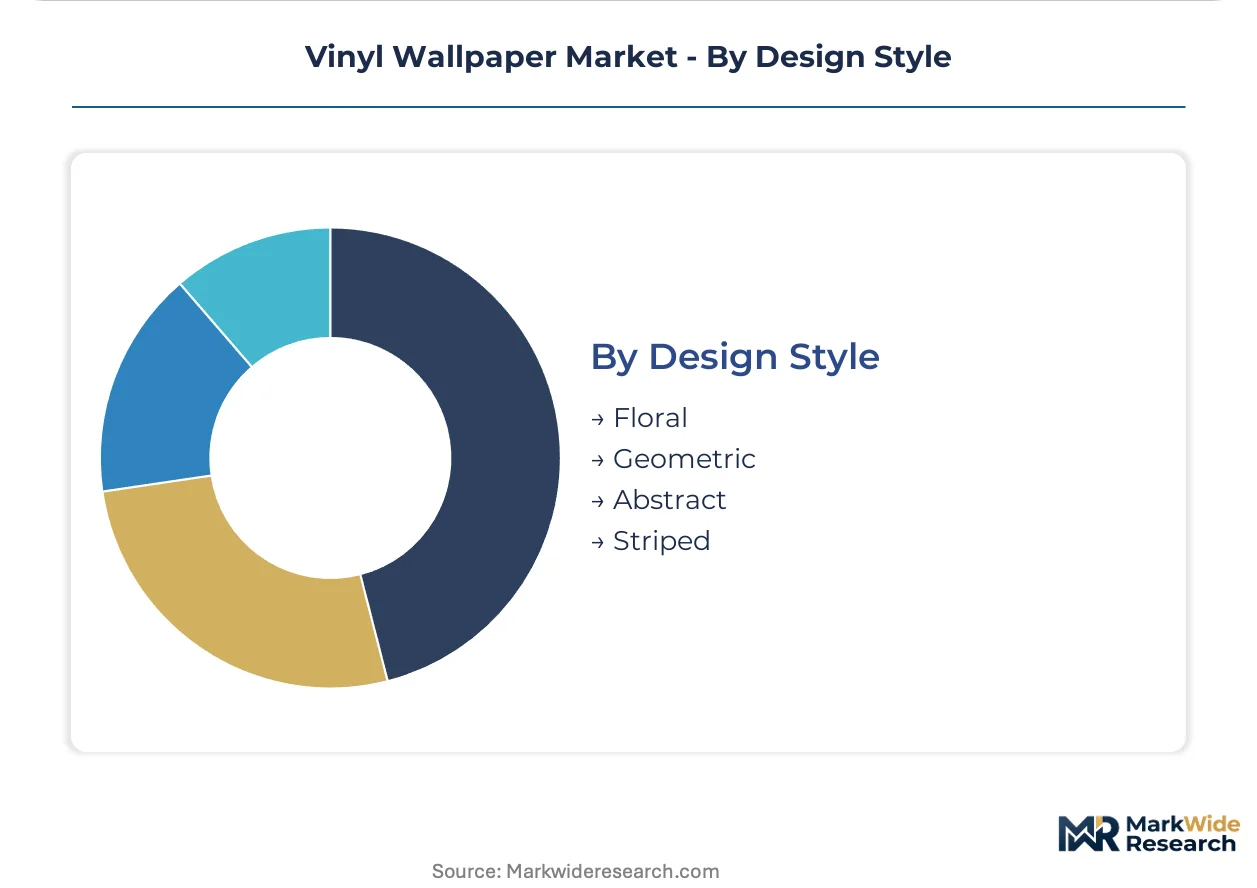
Design Style:
Customer type fragmentation separates trade-specified patterns from retail-consumer preferences.
- Geometric:Precise repeat patterns suit corporate and hospitality environments where visual consistency matters. Digital color-matching systems enable project-specific customization without minimum order penalties.
- Floral:Traditional motifs persist in residential renovation and boutique hotel segments. Regional preference variation drives inventory complexity for distributors.
- Abstract:Non-representational patterns accommodate contemporary commercial interiors.
- Striped:Classic linear designs serve as safe specifications for institutional procurement.
Geometric dominates specification volume, with Abstract showing the steepest expansion trajectory through designer-direct digital channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's hotel construction corridor concentrates specification demand for moisture-resistant wallcoverings, while China's updated GB standards for indoor air quality are forcing broader reformulation across Asian manufacturing bases.
China
GB standards for indoor air quality are reshaping material compliance requirements for imported vinyl products. The Ministry of Ecology and Environment enforces stricter VOC emission thresholds that cascade through PVC plasticizer supply chains. Manufacturing clusters in Guangdong and Zhejiang provinces are retooling calendering operations to meet certification deadlines for hospitality exports.
Vietnam
Fast-expanding hotel construction in Ho Chi Minh City and Da Nang drives specification volumes for fire-retardant and custom color-matched wallcoverings. The Ministry of Construction issues updated fire safety codes for commercial interiors that align with NFPA 286 standards. Procurement teams in the Central Highlands resort corridor now mandate 48-hour digital color proofing for refurbishment cycles.
United States
EPA regulations on volatile organic compound emissions influence adhesive formulations and factory-level compliance investments for domestic production. Residential renovation segments in Texas and Florida favor peel-and-stick formats where contractor labor availability constrains project timelines. York Wall Coverings anchors North American distribution through dedicated contractor channels in the Southeast and Southwest.
Germany
REACH restrictions on phthalate plasticizers and ECHA substance evaluations redirect sourcing toward bio-based plasticizer alternatives. The Federal Institute for Risk Assessment monitors migration stability in hospitality wallcoverings for hotel portfolios in Berlin and Munich. Manufacturers in North Rhine-Westphalia face 2025 compliance deadlines that accelerate R&D spend on epoxidized soybean oil formulations.
Japan
Sangetsu Corporation leverages its integrated manufacturing base to sustain premium positioning across Asian hospitality projects. METI guidelines on indoor air quality in commercial buildings reinforce demand for low-emission vinyl specifications. Tokyo and Osaka design studios increasingly specify digital print-on-demand services that compress traditional sampling timelines.
Vinyl Wallpaper Market Competitive Landscape
Top-tier vendors anchor premium hospitality specification, while mid-scale fabricators compete on format innovation and regional distribution density. The vendor base stratifies across integrated manufacturers with captive resin supply, specialized converters serving designer-direct channels, and private-label operators supplying retail home improvement chains. Strategic archetypes include: vertically integrated specialists controlling calendering through distribution; digital-first platforms collapsing sampling-to-installation timelines; and compliance-focused exporters navigating multi-jurisdiction registration. Competitive moves concentrate on M&A to secure regional distributor networks and capacity expansion in Southeast Asian manufacturing corridors.
Within the integrated manufacturing tier, Sangetsu Corporation and York Wall Coverings Inc. occupy positions that exemplify divergent geographic anchoring strategies. Sangetsu represents the Asia-Pacific hospitality specialist archetype, while York Wall Coverings exemplifies North American channel control through contractor-centric distribution. AS Creation Tapeten AG sits within the European compliance-focused exporter archetype, navigating REACH plasticizer restrictions while serving specification-grade procurement in Germany and adjacent markets.
| Leading Market Players |
|---|
| Sangetsu Corporation |
| York Wall Coverings Inc. |
| Brewster Wallpaper Corporation |
| F. Schumacher & Co. |
| AS Creation Tapeten AG |
| Osborne & Little |
| The Romo Group |
| Grandeco |
| 4walls |
| Others |
Value Network & Pricing Analysis
EU Green Deal circular economy mandates gate qualified supply and premium-tier pricing access for vinyl wallpaper manufacturers seeking specification-grade hospitality procurement. Compliance with verified post-consumer recycled content thresholds separates certified suppliers from commodity competitors, while non-compliant producers face exclusion from European project bidding.
Pricing Analysis
Capacity additions in Vietnam are reshaping price floors for moisture-resistant hospitality wallcoverings. Three-tier pricing structure across premium fire-rated, standard commercial, and economy residential levels dominates transaction structures. Price differentiation rests on NFPA 286 certification grade and custom color-matching capability. Cost compression in economy tiers is intensifying because of substitute material competition from non-woven textiles. Residential DIY segments exhibit highest price sensitivity, while hospitality procurement teams prioritize specification compliance over unit cost.
Supply Chain Analysis
Reverse logistics flows for sample returns and digital proofing waste are emerging as cost centers in print-on-demand subscription services. PVC resin supply concentrates in China, Japan, and South Korea, with calendering operations clustered in Guangdong and Zhejiang provinces. Manufacturing draws from ethylene feedstock, chlorine derivatives, and specialty plasticizer formulations. Single-source vulnerability in phthalate-alternative chemistry creates reformulation bottlenecks under REACH deadlines. Distribution runs through dedicated contractor channels in North America and specialized distributor showrooms in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vinyl wallpaper functions as a stable compounder anchored by recurring 5-7 year refurbishment cycles in Southeast Asian hotel portfolios. This predictable replacement demand sustains baseline volume regardless of new construction volatility.
For Market Incumbents: Anchor premium positioning through captive control of digital color-matching workflows and 48-hour proofing capabilities. Defend against disintermediation by interior designer-direct portals through exclusive subscription service partnerships. Invest in GB standards compliance certification for continued access to Chinese hospitality exports.
For New Entrants and Emerging Players: REACH plasticizer restrictions in Europe open a window for bio-based formulation specialists to capture specification share in German and French hospitality markets. Target North American residential renovation through peel-and-stick format innovation where contractor shortages constrain traditional installation. Pursue designer-direct digital channels as primary go-to-market path, bypassing established wholesale networks.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale fabricators lacking compliance certification depth but holding regional distributor relationships. Five-to-ten year viability favors converters with demonstrated multi-jurisdiction registration capacity. Monitor ECHA substance evaluation timelines as inflection indicator for accelerated consolidation among legacy plasticizer-dependent manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVC Resin Supply | Captive ethylene sourcing from Gulf Coast petrochemical clusters insulates margin from feedstock volatility. |
| Digital Print-on-Demand Platform Launch | Subscription services for interior designers compress sampling timelines and reduce distributor inventory risk. |
| Fire-Rating Certification Investment | NFPA 286 and EN 13501-1 Class B testing opens premium hospitality specification in Singapore and Dubai. |
| Regional Distributor Network Acquisition | Control over contractor channels in Texas and Florida secures peel-and-stick volume in labor-constrained markets. |
| Bio-Based Plasticizer Formulation Partnership | Epoxidized soybean oil chemistry collaboration with European suppliers ensures REACH compliance ahead of 2025 deadlines. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing demand-side validation. The research combines structured interviews with hospitality procurement directors, interior design studio principals, wallcovering distributor category managers, and calendering plant operations heads with secondary triangulation. Secondary sources include EPA emission compliance filings, ECHA substance evaluation databases, GB standards documentation, and customs trade records for PVC resin and finished wallcovering flows. Bottom-up project pipeline analysis and top-down construction spend estimates were cross-referenced to establish volume baselines.
Granularity extends to product format, end-use sector, material construction, and design style dimensions across the projection horizon. The analytical framework models replacement cycle timing, new construction absorption rates, and specification-grade procurement behavior by hospitality portfolio operators. CAGRs were derived from segment-level volume build-ups and value-per-unit trends informed by plasticizer cost trajectories and certification premium persistence. Industry-specific forecast inputs include hotel refurbishment scheduling patterns and designer subscription service adoption curves.
Revisions become necessary when regulatory compliance deadlines shift, petrochemical feedstock costs experience sustained dislocation, or substitute material technology achieves cost parity in residential applications. Forecasts reflect documented assumptions regarding continued hospitality construction momentum in Vietnam and Thailand. Practitioners should monitor ECHA substance evaluation outcomes and Chinese GB standards enforcement intensity for early signals of supply-side restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
India Home Furnishing Market
Homecare and Decor
Japan Sustainable Home Decor Market
Homecare and Decor
India Decorative Laminates Market
Homecare and Decor
Door Stopper Market
Homecare and Decor
France Steam Rooms Market
Homecare and Decor
Middle East and Africa Christmas Tree Market
Homecare and Decor
Europe Wall Coverings Market
Homecare and Decor
Gas Fire Table Market
Homecare and Decor
Asia-Pacific Decorative Laminates Market
Homecare and Decor
Hospital Bedsheet and Pillow Cover Market
Homecare and Decor
Wall Covering Market
Homecare and Decor
Global Wallpaper Market
Homecare and Decor
ASEAN UPVC Doors and Windows Market
Homecare and Decor
Bulletin Board Market
Homecare and Decor
Europe Commercial Blinds and Shades Market
Homecare and Decor
Mattress and Mattress Component Market