
 Balcony Accessories Market | 2026-2036
Balcony Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Balcony Accessories Market Analysis
REACH compliance is realigning the cost-of-entry calculus for balcony accessory manufacturers importing into European markets. Gloster leverages its teak sourcing networks to sustain premium positioning across Northern European markets. Brown Jordan anchors its competitive stance through specialized aluminum fabrication capabilities that reduce weight without sacrificing structural integrity. Dedon differentiates via proprietary synthetic fiber weaving technology that commands durability premiums in coastal hospitality applications.
Balcony accessories encompass functional and decorative elements designed for elevated outdoor platforms, typically manufactured from weather-resistant materials such as powder-coated aluminum, teak hardwood, or high-density polyethylene wicker rated for UV exposure and moisture cycling. These products serve to extend usable living space in dense urban environments while addressing safety, privacy, and aesthetic requirements. Furniture and railings represent mature volume categories where margin pools concentrate in premium hospitality specification, while planters and composite material segments capture faster growth as residential consumers prioritize low-maintenance greenery solutions and sustainable material credentials.
The EU Green Deal and F-Gas Regulation shape product standards for energy-efficient building envelopes, indirectly driving balcony enclosure and insulation accessory demand across member states. ECHA chemical restrictions on treated wood preservatives force material substitutions toward certified sustainable timber or engineered composites. The US EPA and state-level California Air Resources Board influence volatile organic compound limits on finishes and coatings, affecting cross-border supply configurations. Stakeholders must monitor evolving building code harmonization between national regulators and the EU AI Act's emerging implications for smart balcony systems integrating automated shading and climate control.
Market Dynamics
Urban densification across European capitals is compressing private outdoor space per capita, forcing manufacturers to engineer multi-functional balcony systems that satisfy EU Green Deal energy-efficiency mandates while serving as primary leisure zones for apartment dwellers.
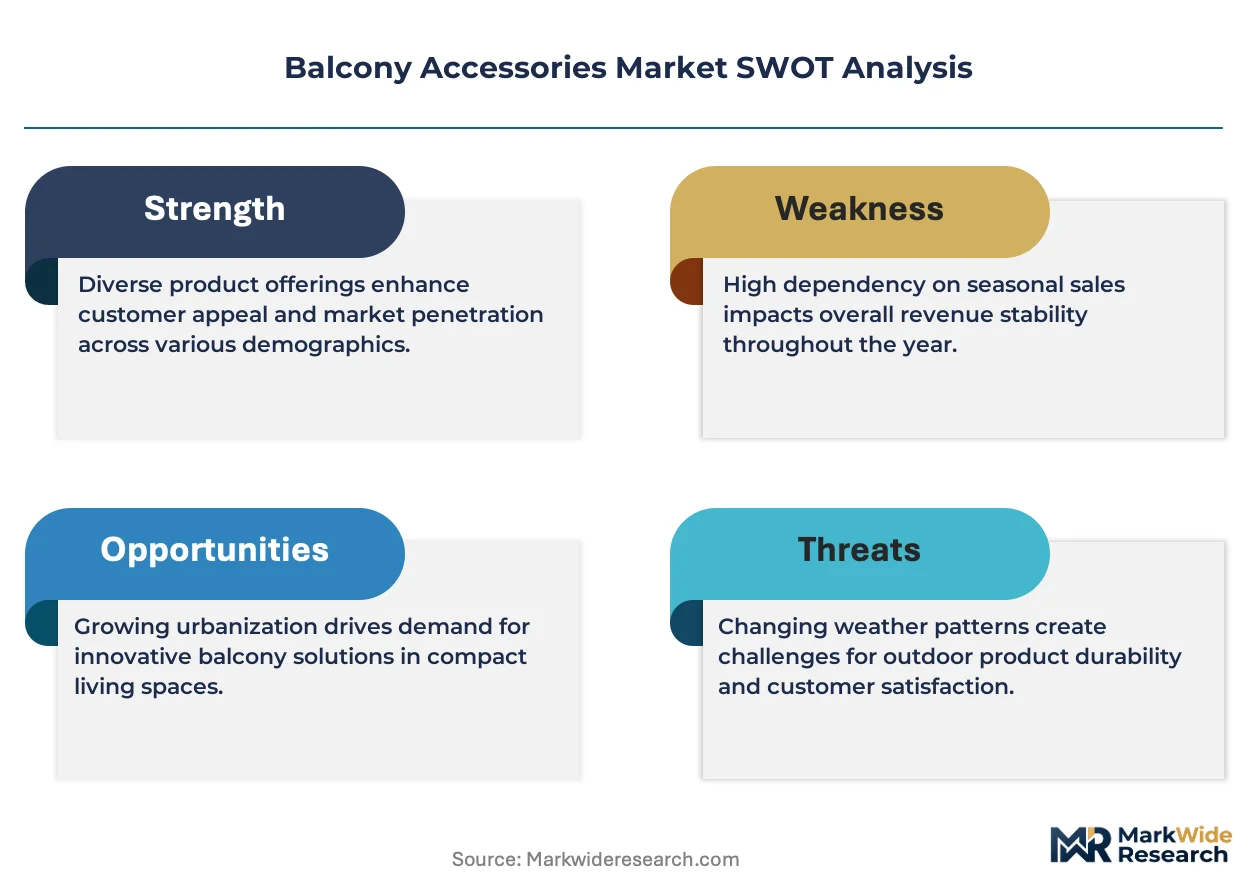
Growth Catalysts
- EU Green Deal renovation targets:Mandatory building envelope upgrades across member states are creating pull-through demand for thermally efficient balcony enclosures and integrated shading systems that reduce HVAC loads.
- High-density residential construction:Berlin, Barcelona, and Milan municipal zoning reforms are mandating minimum outdoor space quotas per unit, standardizing balcony inclusion in new-build permits.
- Coastal hospitality refurbishment cycles:Mediterranean resort operators are replacing weather-degraded metal fixtures with marine-grade synthetic wicker and powder-coated aluminum to extend replacement intervals.
Market Restraints
- Teak supply concentration:Myanmar and Laos export restrictions on unprocessed hardwood have concentrated certified sustainable teak sourcing with three Southeast Asian plantation consortia, elevating raw material price volatility.
- REACH compliance costs:ECHA substance restrictions on chromium-based wood preservatives and certain powder-coat formulations are forcing reformulation investments that disproportionately burden sub-scale European fabricators.
- Aluminum smelter energy intensity:European smelter curtailments during winter peak electricity demand periods are transmitting input cost spikes to extrusion-dependent railing and furniture manufacturers.
Strategic Opportunities
- Modular vertical gardening systems:Copenhagen and Amsterdam municipal greening subsidies are creating first-mover advantages for suppliers of irrigation-integrated planter systems designed for narrow balcony depths.
- Smart shading convergence:Integration of photovoltaic-embedded awnings with home energy management systems is opening specification pathways in German and Austrian passive-house construction segments.
- Direct-to-developer channels:Large residential developers in Madrid and Rome are consolidating procurement through specification partnerships, bypassing traditional retail distribution and capturing volume pricing leverage.
Industry Challenges
- Welding technician scarcity:Specialized aluminum TIG welding certification programs have contracted across Northern Italian industrial districts, constraining output expansion for premium railing fabricators.
- CE marking timeline compression:Revised Construction Products Regulation testing protocols are extending product certification cycles by four to six months, delaying new composite material introductions.
- Legacy ERP integration friction:Mid-tier manufacturers attempting to deploy automated order-to-production workflows face data migration bottlenecks with twenty-year-old inventory management architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Balcony Accessories Market |
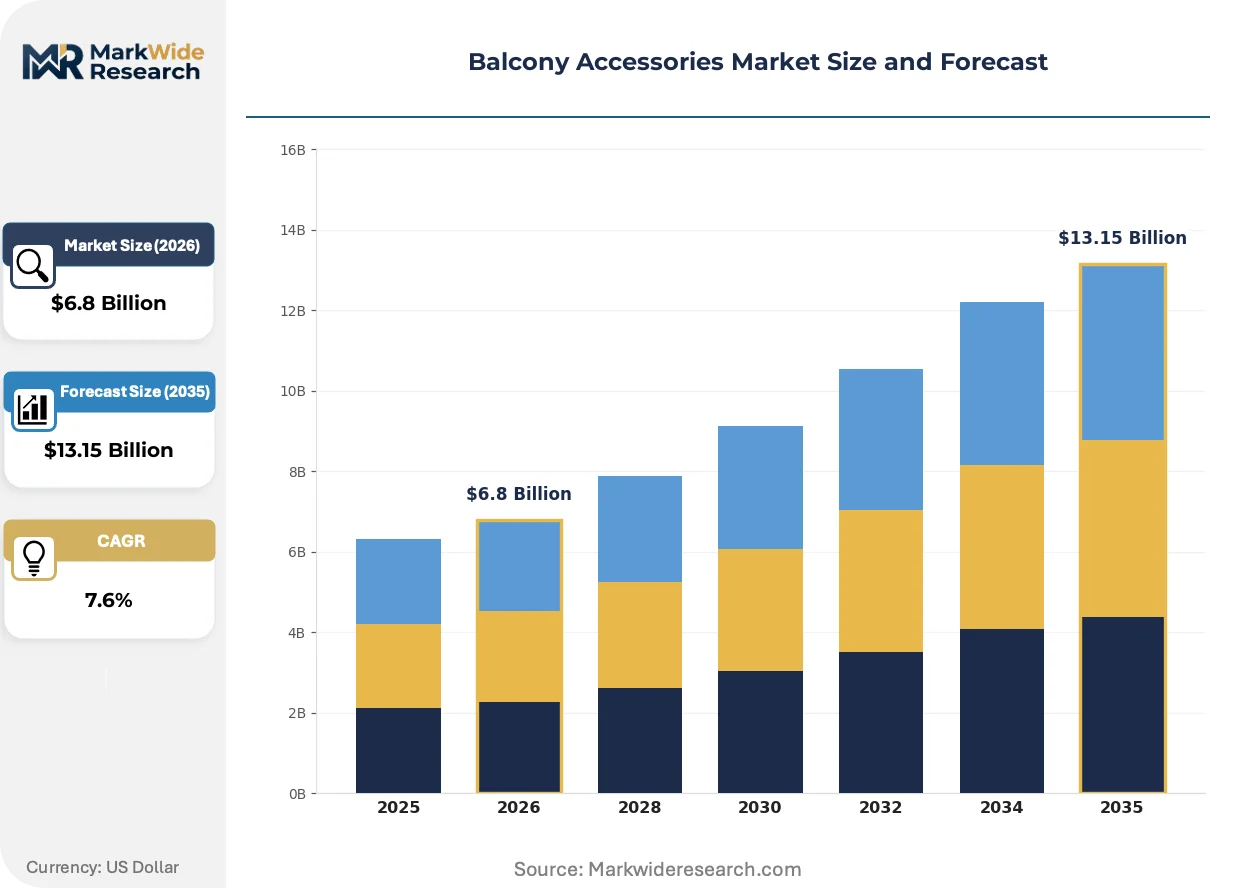
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Planters, Furniture, Railings, Decor Material: Wood, Metal, Plastic, Composite Application: Residential, Commercial, Public Spaces, Hospitality Design Style: Modern, Rustic, Minimalist, Vintage |
| Companies Covered | Gloster, Tribù, Brown Jordan, Barlow Tyrie, EMU Group, Dedon, Royal Botania, Manutti, Vondom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Balcony Accessories Market Emerging Trajectories
Material science breakthroughs and regulatory pressure on building energy performance are converging to redefine balcony accessory specifications, with durability and thermal integration now displacing pure aesthetics as primary purchase criteria.
Recycled ocean plastic composite decking is rewriting material substitution patterns in coastal markets. The proprietary extrusion process blends recovered fishing net polymers with mineral fillers to achieve slip resistance ratings matching tropical hardwood. Spanish and Portuguese hospitality developers are specifying these planks for pool-adjacent balcony renovations. The technology is compressing the addressable market for pressure-treated pine in salt-air environments.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in rubberized flooring are forcing compound reformulations across European supply chains. German testing laboratories report extended validation timelines for alternative elastomer blends. Residential retrofit contractors in Hamburg and Munich are experiencing project delays as certification documentation requirements tighten for recycled rubber tile imports.
Developer-led bulk procurement is consolidating specification authority away from individual unit owners. Large residential projects in Paris and Vienna now require balcony furniture and enclosure packages to meet unified design standards and warranty terms. This concentration is marginalizing independent retail showrooms and elevating contract negotiation leverage for volume-manufacturing specialists with dedicated project sales functions.
Balcony Accessories Market Segmentation
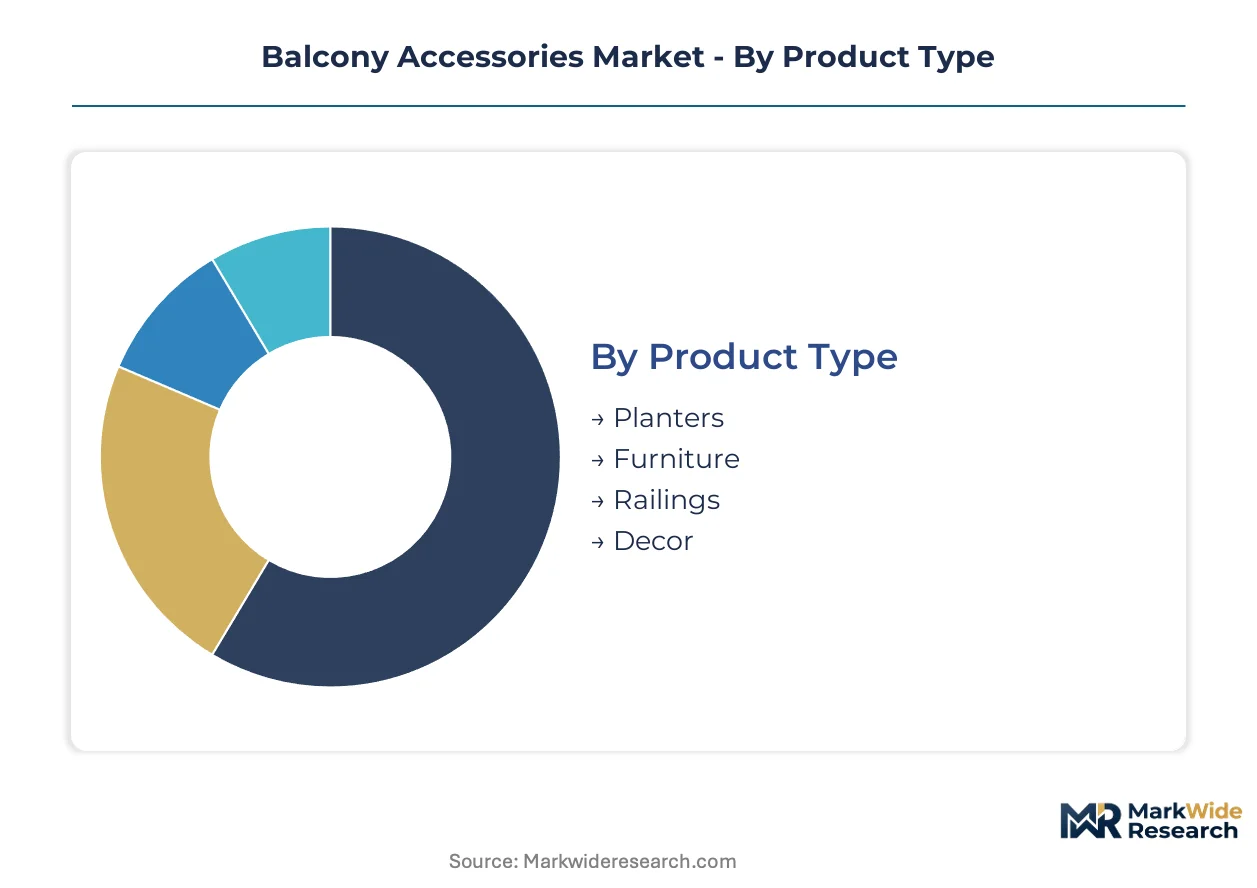
Balcony accessory purchasing decisions cascade through multiple filtering layers. Product type determines functional utility, material selection governs durability economics, and application context dictates regulatory compliance requirements.
Product Type:
Furniture and railings anchor volume procurement, while planters and decor command premium expansion trajectories.
- Furniture:Powder-coated aluminum frames and synthetic wicker seating systems dominate specification in German and Austrian passive-house developments. Berlin and Vienna developers now mandate modular configurations that adapt to narrow balcony depths under municipal outdoor space quotas.
- Railings:Extruded aluminum and stainless steel systems with integrated glass infill panels satisfy CE marking requirements under revised Construction Products Regulation. Italian fabricators in Veneto and Lombardy concentrate output for Mediterranean hospitality refurbishment cycles.
- Planters:Self-irrigating resin and composite containers with sub-surface water reservoirs address Copenhagen municipal greening subsidies.
- Decor:Weather-resistant textiles and lighting systems complete aesthetic packages for direct-to-developer procurement channels.
Today's leader: Furniture. Tomorrow's challenger: Planters.
Material:
Metal and wood split the market between structural permanence and aesthetic warmth, with composites gaining regulatory tailwind.
- Metal:Aluminum extrusions and powder-coated steel deliver weight-efficient structural performance for high-rise applications. European smelter curtailments during winter peak electricity periods transmit cost volatility to railing and furniture manufacturers.
- Wood:Teak and certified sustainable hardwoods retain specification in Northern European premium residential segments. Myanmar and Laos export restrictions on unprocessed timber have concentrated supply with Southeast Asian plantation consortia.
- Plastic:High-density polyethylene wicker and recycled polymer formulations serve cost-sensitive volume procurement in Spanish and Portuguese coastal hospitality.
- Composite:Mineral-filled recycled ocean plastic decking achieves slip resistance ratings matching tropical hardwood for salt-air environments.
Metal commands current specification authority. Composite materials are climbing the fastest as ECHA restrictions on treated wood preservatives accelerate substitution.
Application:
Residential density drives volume, while hospitality refurbishment concentrates margin pools.
- Residential:Apartment balcony outfitting in Berlin, Barcelona, and Milan expands with municipal zoning reforms mandating minimum outdoor space per unit. Multi-functional systems that integrate seating, storage, and greenery address compressed square footage.
- Commercial:Office building amenity balconies in Frankfurt and Amsterdam require durable low-maintenance specifications with unified warranty terms.
- Public Spaces:Municipal housing authority procurement in Paris and Vienna standardizes balcony packages across large residential developments.
- Hospitality:Mediterranean resort operators replace weather-degraded fixtures with marine-grade synthetic wicker and powder-coated aluminum to extend replacement intervals.
Residential anchors volume scale. Hospitality captures margin concentration.
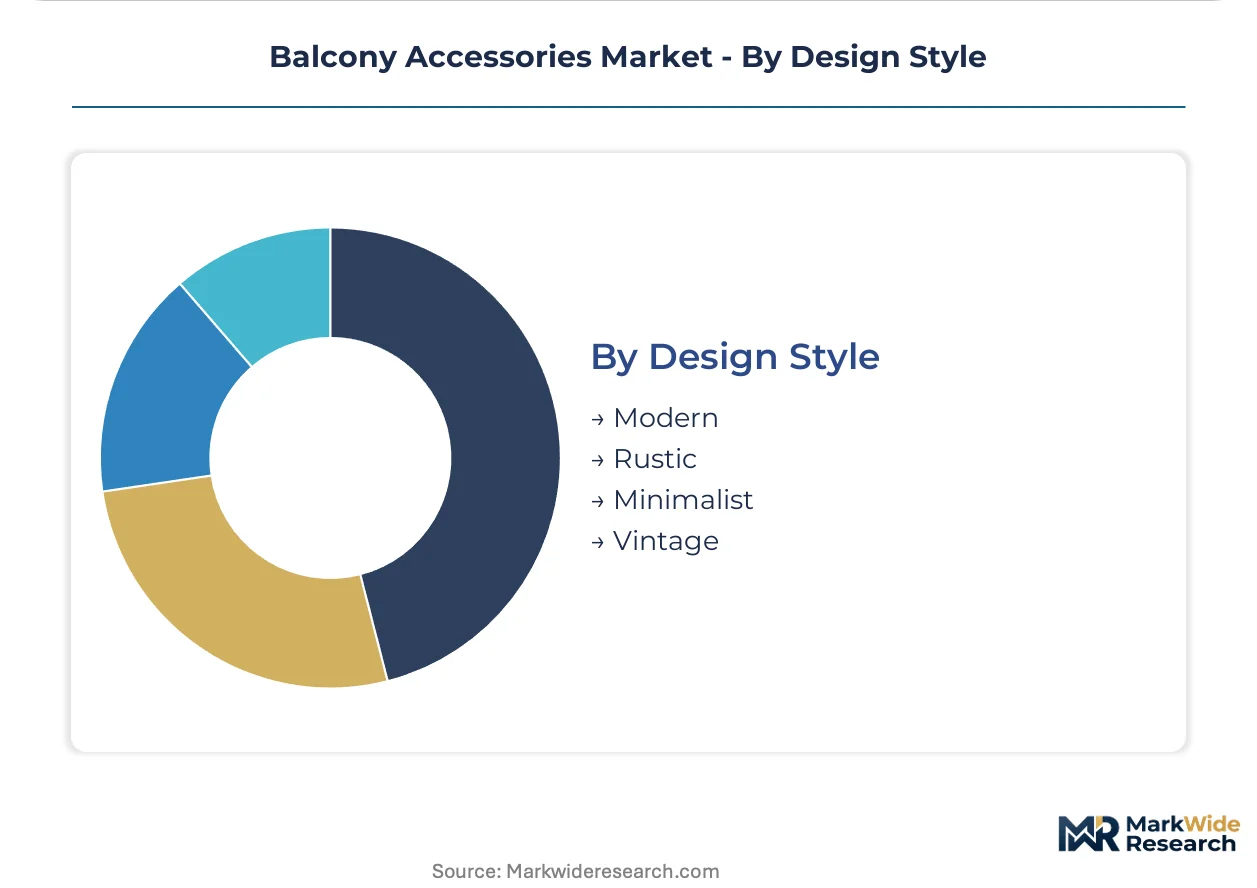
Design Style:
Developer-led bulk procurement is compressing style diversity toward unified project standards.
- Modern:Clean-lined aluminum and glass systems align with EU Green Deal energy-efficiency mandates for thermally integrated balcony enclosures.
- Rustic:Natural wood finishes and wrought-iron elements persist in heritage district renovations under strict municipal aesthetic codes.
- Minimalist:Reduced-material configurations address weight restrictions in high-rise structural engineering specifications.
- Vintage:Reclaimed and reproduction elements serve boutique hospitality differentiation in saturated Mediterranean markets.
Modern style dominates new-build specification. Minimalist is gaining share fastest as engineering constraints tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized aluminum fabricators and teak finishing craftsmen concentrate in Northern Italian industrial districts and Javanese plantation zones, anchoring supply-side capacity for premium balcony systems.
Germany
Passive-house construction standards in Berlin and Hamburg drive specification for thermally integrated balcony enclosures. The EU Green Deal mandates building envelope upgrades that reduce HVAC loads through automated shading systems. Bavarian fabricators supply powder-coated aluminum railing systems to Austrian and Swiss cross-border developments.
Italy
Veneto and Lombardy metalworking clusters concentrate extruded aluminum capacity for Mediterranean hospitality refurbishment cycles. REACH Annex XVII restrictions on chromium-based wood preservatives force material substitutions toward certified sustainable timber. Milan municipal zoning reforms mandate minimum outdoor space quotas per residential unit.
Spain
Barcelona and Madrid large residential developers consolidate procurement through direct specification partnerships. ECHA chemical restrictions on treated wood preservatives accelerate composite decking adoption for coastal applications. Valencia fabricators supply marine-grade synthetic wicker to Portuguese and French Riviera resort operators.
Netherlands
Amsterdam and Copenhagen municipal greening subsidies create demand for irrigation-integrated vertical gardening systems. The EU F-Gas Regulation shapes energy-efficient building envelope standards that indirectly drive balcony insulation accessory demand. Randstad engineering firms specialize in modular configurations for narrow balcony depths.
France
Paris municipal housing authorities standardize balcony packages across large residential developments under unified warranty terms. The EU AI Act's emerging implications affect smart balcony systems integrating automated shading and climate control. Île-de-France project sales teams negotiate directly with developers to bypass traditional retail distribution.
Balcony Accessories Market Vendor Landscape
The competitive structure tilts toward premium hospitality specialists with dedicated teak sourcing networks and aluminum fabrication capabilities. Three archetypes dominate: plantation-linked hardwood finishers, extrusion-dependent metalworkers, and synthetic fiber weaving technologists. Consolidation pressures intensify as REACH compliance costs disproportionately burden sub-scale European fabricators. Capacity expansion and direct-to-developer specification partnerships represent the dominant competitive moves reshaping distribution economics.
Among European-based specialists, Gloster, Brown Jordan, and Dedon exemplify contrasting strategic positions. Gloster anchors the plantation-linked hardwood finisher archetype through its teak sourcing networks. Brown Jordan occupies a position within the extrusion-dependent metalworker category, emphasizing aluminum fabrication capabilities. Dedon represents the synthetic fiber weaving technologist tier, commanding durability premiums in coastal hospitality applications through proprietary material processes.
| Leading Market Players |
|---|
| Gloster |
| Tribù |
| Brown Jordan |
| Barlow Tyrie |
| EMU Group |
| Dedon |
| Royal Botania |
| Manutti |
| Vondom |
| Others |
Supply Flow & Price Mechanics
Premium-to-commodity material divergence separates plantation-certified teak systems from powder-coated aluminum commodity rails, with that bifurcation manifesting in both procurement channel structures and margin capture across Northern European residential versus Mediterranean hospitality specifications. REACH compliance costs concentrate pricing power with scaled fabricators capable of absorbing reformulation investments, while sub-scale Italian metalworkers face margin compression from elevated certification documentation requirements.
Pricing Analysis
Bundled specification packages versus unbundled component procurement splits the market between direct-to-developer volume contracts and independent retail showroom transactions. Three-tier pricing structure across premium teak, standard aluminum, and economy composite levels reflects certification grade and after-sales warranty bundling. Cost compression in the mid-tier aluminum segment intensifies because European smelter curtailments transmit electricity price volatility to extrusion-dependent railing manufacturers. Residential apartment developers in Berlin and Vienna demonstrate highest price sensitivity through consolidated procurement leverage, while boutique hospitality operators in the French Riviera show lowest sensitivity when specifying marine-grade synthetic wicker for salt-air durability premiums.
Supply Chain Analysis
Workforce availability constraints in Northern Italian industrial districts and Javanese plantation zones anchor production bottlenecks for premium balcony systems. Supply concentrates in Italy for extruded aluminum fabrication, Indonesia for certified sustainable teak finishing, and Spain for marine-grade synthetic wicker weaving. Raw material flows draw from Southeast Asian plantation consortia for hardwood, European smelters for aluminum billet, and recycled fishing net polymers for composite decking formulations. Single-source vulnerability sits with the three plantation consortia controlling certified teak supply following Myanmar and Laos export restrictions. Distribution runs through specification partnerships with large residential developers in Madrid and Rome, bypassing traditional retail channels for volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where developer-led bulk procurement is concentrating specification authority toward unified warranty standards and premium material credentials. Demand is shifting toward thermally integrated balcony enclosures that satisfy EU Green Deal energy-efficiency mandates while serving as primary leisure zones in compressed urban outdoor spaces.
For Market Incumbents: To counter REACH compliance cost asymmetries that disproportionately burden sub-scale competitors, deepen backward integration into certified sustainable timber sourcing and captive aluminum extrusion capacity. Prioritize dedicated project sales functions that negotiate directly with large residential developers in Paris and Vienna, bypassing fragmented retail distribution. Anchor competitive position through proprietary synthetic fiber weaving technology or specialized TIG welding certification programs that constrain output expansion for rivals. For New Entrants and Emerging Players: Modular vertical gardening systems with irrigation integration offer a technology-first wedge into Copenhagen and Amsterdam municipal greening subsidy programs. Target narrow-depth balcony configurations in high-density Northern European residential construction where incumbent furniture systems fail to adapt. Pursue specification partnerships with Randstad engineering firms specializing in passive-house construction standards. Capture first-mover advantage in photovoltaic-embedded awning integration with home energy management systems for German and Austrian developer channels. For Investors and Strategic Acquirers: Asymmetric upside sits with plantation-linked hardwood finishers holding captive teak sourcing networks and extrusion-dependent metalworkers with specialized aluminum fabrication capabilities. Long-term viability favors scaled European fabricators capable of absorbing regulatory compliance investments while consolidating sub-scale competitors. Acquisition targets should demonstrate dedicated project sales functions and direct-to-developer channel control. Watch for inflection in CE marking timeline compression under revised Construction Products Regulation protocols, which could accelerate consolidation among mid-tier manufacturers facing extended certification cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Timber | Captive plantation sourcing in Indonesia insulates Gloster from Myanmar export restriction volatility. |
| Direct-to-Developer Channel Expansion | Bypassing retail distribution captures volume pricing leverage with Madrid and Rome residential consolidators. |
| Smart Shading Technology Integration | Photovoltaic-embedded awnings open specification pathways in German passive-house construction segments. |
| REACH Compliance Certification Investment | Reformulation capabilities disproportionately burden sub-scale Italian metalworkers, accelerating consolidation. |
| Modular Vertical Gardening Systems | Irrigation-integrated planters address Copenhagen municipal subsidies for narrow-depth balcony configurations. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with product development executives at Italian metalworking clusters, procurement leads at Mediterranean hospitality operators, regulatory affairs specialists navigating ECHA substance restrictions, and channel partners in Northern European distribution networks. Secondary validation drew from EU Green Deal implementation documents, ECHA REACH Annex XVII restriction updates, Construction Products Regulation CE marking protocols, and municipal zoning reform filings in Berlin, Barcelona, and Milan. Bottom-up demand modeling across product type, material grade, and application segments triangulated against top-down macroeconomic indicators for urban densification and building renovation expenditure.
Segment-weighting approaches distributed value and volume estimates across furniture, railing, planter, and decor categories, with further stratification by metal, wood, plastic, and composite material tiers. Residential, commercial, public space, and hospitality applications were modeled separately to capture divergent margin structures and procurement channel dynamics. CAGRs were derived from regression analysis of historical shipment data and forward projection of regulatory mandate implementation timelines. Industry-specific forecast inputs included EU Green Deal building envelope upgrade targets, municipal outdoor space quota enforcement schedules, and coastal hospitality refurbishment cycle patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA chemical restriction expansions, European aluminum smelter curtailment patterns, and Myanmar-Laos timber export policy shifts. Forecasts reflect documented assumptions regarding REACH compliance cost trajectories and developer procurement consolidation velocity. Material deviation in teak supply concentration, welding technician certification program availability, or CE marking timeline compression warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
US Bamboos Market
Homecare and Decor
Door Handles Market
Homecare and Decor
US Mattress Bases Market
Homecare and Decor
US Halloween Decorations Market
Homecare and Decor
Home Decor Market
Homecare and Decor
Vinyl Wallpaper Market
Homecare and Decor
Wall Covering Market
Homecare and Decor
France Steam Rooms Market
Homecare and Decor
Asia-Pacific Decorative Laminates Market
Homecare and Decor
India Furniture Hardware Market
Homecare and Decor
New Zealand Window Covering Market
Homecare and Decor
Gas Fire Table Market
Homecare and Decor
Frame for Painting Market
Homecare and Decor
United Arab Emirates Interior Design Market
Homecare and Decor
Garden Sheds Market
Homecare and Decor
Bamboo Panels Market