
 Middle East Revolving Doors Market | 2026-2036
Middle East Revolving Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Revolving Doors Market Insights
Aftermarket service revenue is tilting toward smart diagnostics and predictive maintenance contracts as building operators seek lifecycle cost control. Record leverages its electromechanical expertise to anchor long-term service agreements across Gulf hospitality portfolios. Dormakaba competes through integrated access-control bundling that extends beyond hardware into software-managed entry ecosystems.
Revolving doors are motorized or manually operated entrance systems with three or four wing configurations that create an airlock buffer to minimize HVAC energy loss while managing pedestrian throughput. These systems typically incorporate 6-12 mm tempered glass panels, stainless steel or aluminum framing, and electromechanical drive units rated for 500,000+ operational cycles in commercial settings. Automatic product types dominate current specification volumes across Middle East commercial buildings, while smart systems incorporating IoT sensors and building management integration represent the fastest-expanding technology segment. Energy saving variants command premium positioning as Gulf jurisdictions tighten thermal envelope requirements for new construction.
MOHAP in the UAE and Saudi Arabia's Saudi Building Code enforce fire safety and accessibility standards that directly shape revolving door installation specifications and certification requirements. The EU Green Deal's extraterritorial influence on Gulf developer ESG commitments is accelerating demand for energy-efficient entrance solutions that demonstrate measurable thermal performance. Stakeholders must monitor how evolving smart building mandates across Gulf jurisdictions redefine the competitive boundary between hardware suppliers and integrated building technology platforms.
Market Dynamics
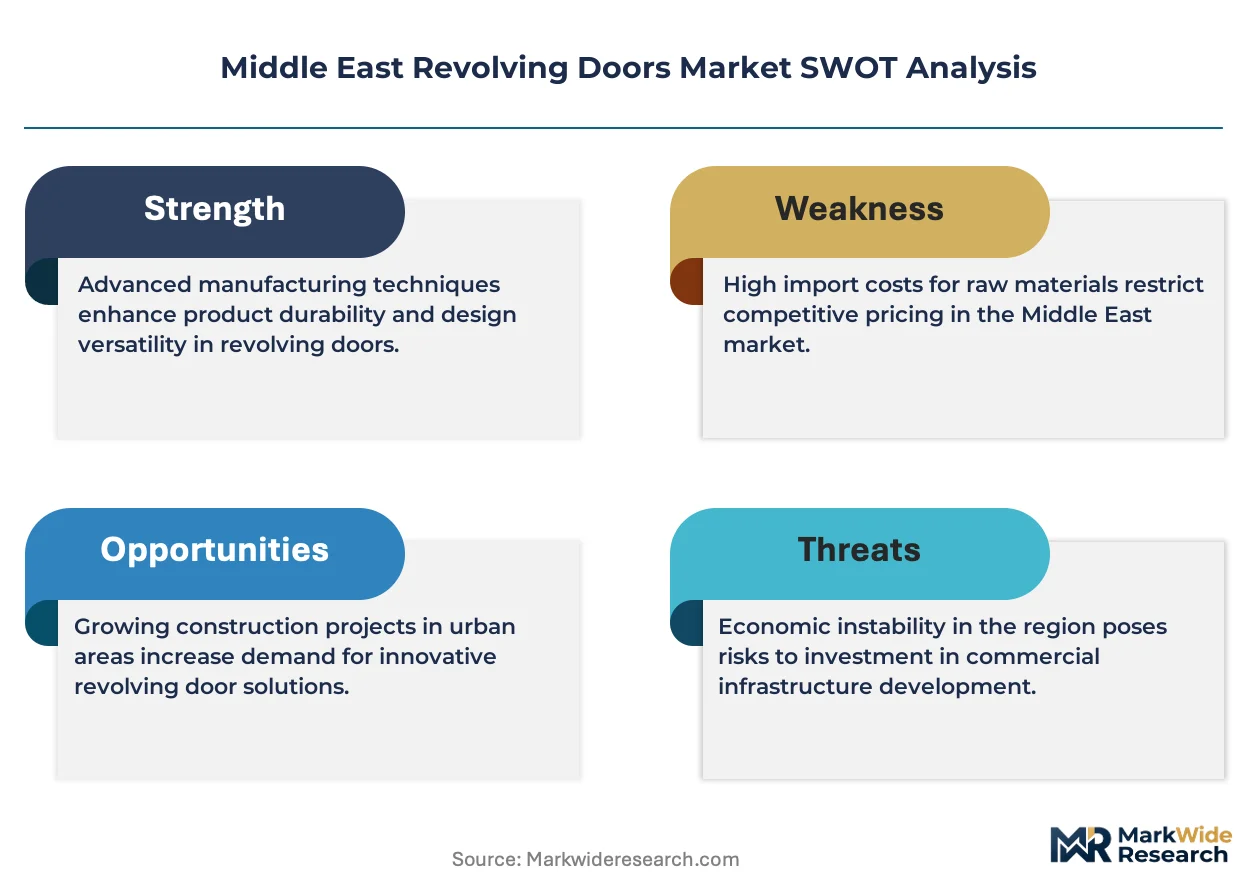
Thermal performance mandates across Gulf jurisdictions are compressing specification timelines and forcing building operators to prioritize entrance systems that demonstrably reduce HVAC load. Saudi Arabia's updated building energy codes and the UAE's green building frameworks now treat revolving doors as thermal envelope components rather than mere access hardware.
Growth Catalysts
- Saudi Building Code thermal mandates:Commercial entryways in new construction must meet specified thermal transmittance values, directly elevating specification rates for energy-efficient revolving door systems.
- Hospitality construction pipelines:Hotel developments across Dubai, Riyadh, and Doha are procuring automatic entrance systems at scale to manage high-volume pedestrian traffic while maintaining climate control.
- IoT sensor integration:Smart diagnostics embedded in drive units enable predictive maintenance contracts that extend vendor relationships beyond initial hardware sales.
Market Restraints
- Stainless steel input volatility:Framing material costs fluctuate with commodity markets, compressing margins for fixed-price installation contracts.
- European electromechanical component concentration:Drive unit and control system sourcing remains concentrated among specialized German and Swiss suppliers, creating lead time exposure.
- Sliding door substitution:Air curtain systems paired with linear automatic doors compete for retrofit projects where structural constraints limit revolving door installation.
Strategic Opportunities
- Qatar's hospitality expansion:Post-World Cup hotel and entertainment venue construction is generating specification volume for premium entrance systems.
- EU Green Deal extraterritorial influence:Gulf developer ESG commitments to European institutional investors are accelerating demand for certified energy-efficient entrance solutions.
- Software-managed entry ecosystems:Integration of access control, visitor management, and thermal monitoring into unified platforms creates service revenue expansion potential.
Industry Challenges
- Electromechanical technician scarcity:Specialized skills for servicing 500,000-cycle rated drive units are concentrated among a limited pool of certified field engineers across the Gulf.
- Multi-jurisdiction certification complexity:MOHAP fire safety requirements, Saudi Building Code accessibility standards, and project-specific developer ESG criteria create overlapping compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Revolving Doors Market |
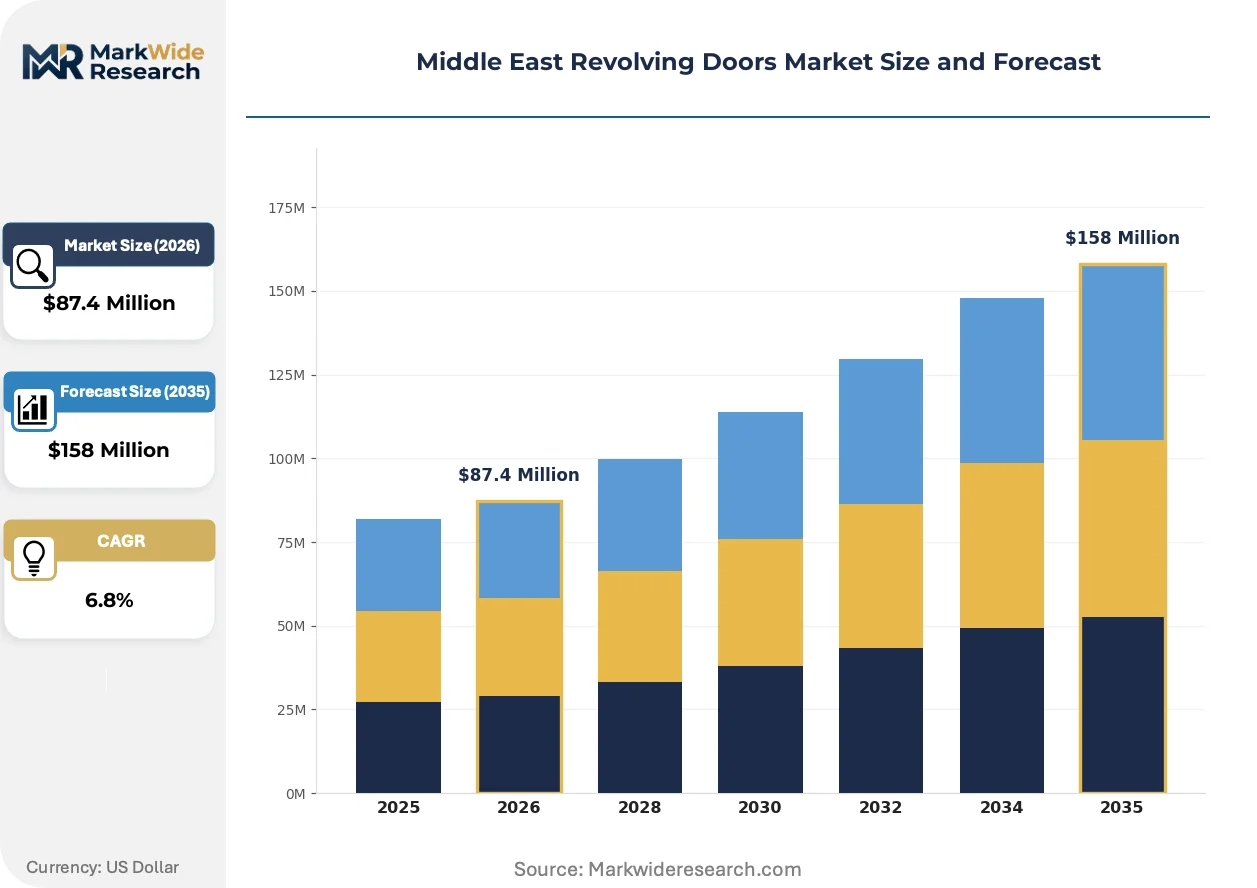
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, Security, Energy Saving Application: Commercial Buildings, Airports, Hotels, Retail Outlets End User: Architects, Contractors, Building Owners, Facility Managers Technology: Electromechanical, Hydraulic, Pneumatic, Smart Systems |
| Companies Covered | Record, Geze, Dormakaba, ERREKA, Horton Automatics, Boon Edam, Stanley, Portalp, Assa Abloy, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Revolving Doors Market Trends and Innovations
Building management system integration is redefining competitive boundaries as hardware suppliers compete with integrated technology platforms for long-term service relationships. Three developments are actively reshaping product development and procurement patterns.
Sensor-embedded drive units are virtualizing maintenance scheduling by transmitting operational cycle counts, torque anomalies, and thermal performance data to centralized monitoring platforms. Large hospitality operators in Dubai and Riyadh are adopting these systems to unbundle after-sales service from original equipment vendors. This virtualization is compressing the traditional reactive maintenance model into predictive intervention cycles that reduce downtime liability.
Saudi Arabia's Saudi Building Code and the UAE's green building frameworks now mandate documented thermal performance for commercial entryways, treating revolving doors as envelope components rather than access hardware. Developers must submit U-value calculations and air infiltration rates as part of permitting. Hospitality and healthcare verticals are responding fastest by specifying certified systems with third-party validated performance data.
Facility managers are consolidating vendor relationships around lifecycle cost guarantees rather than upfront capital expenditure minimization. Long-term service agreements covering predictive maintenance, component replacement, and energy performance monitoring are displacing traditional break-fix contracts. This consolidation is most visible in Dubai's airport and hotel portfolios where operational continuity carries premium value.
Middle East Revolving Doors Market Segmentation
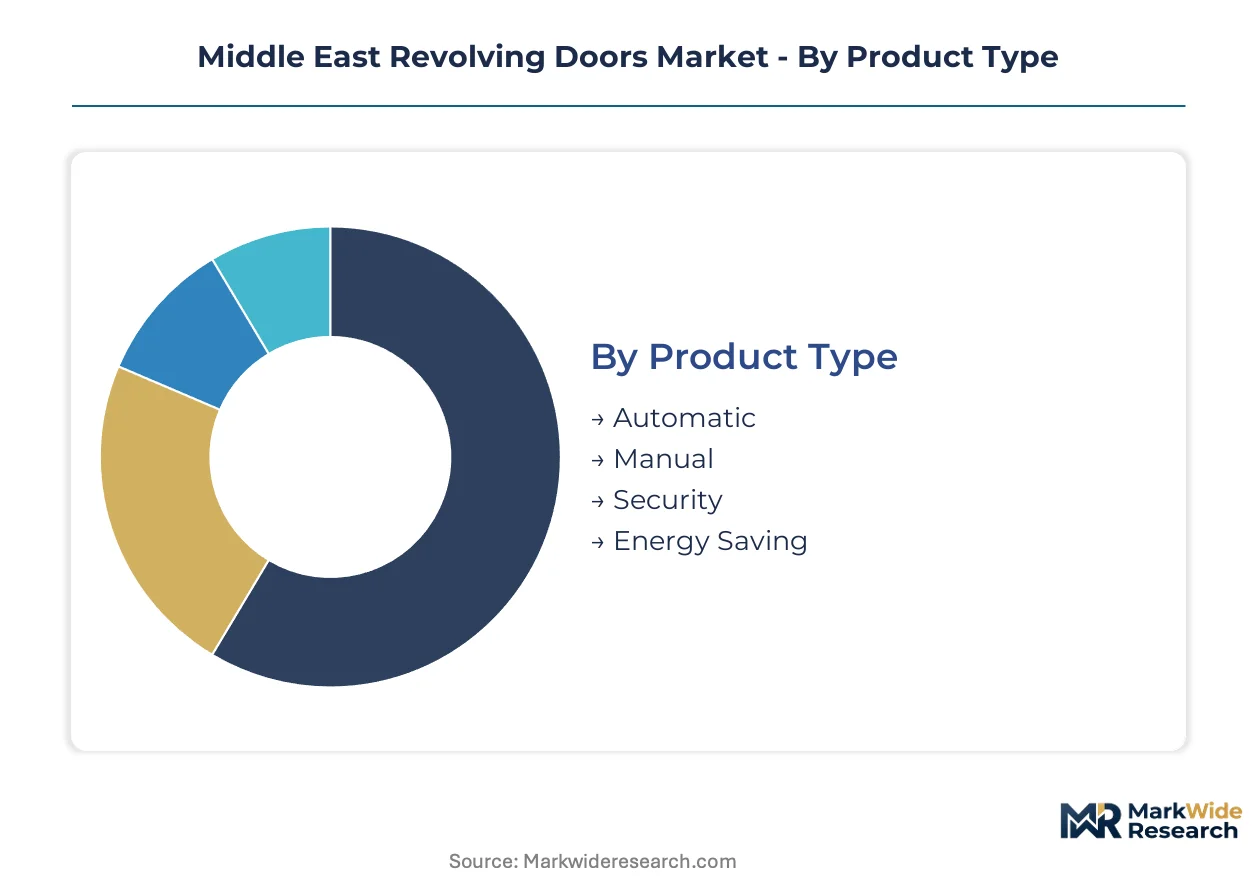
Segmentation reveals how procurement cycles and specification authority vary across the Middle East revolving doors market. Product type and application dimensions show the clearest divergence in replacement frequency and decision-making timelines.
Product Type:
Replacement cycles stretch from 15-20 years for manual systems down to 8-12 years for smart-enabled automatic units, creating distinct aftermarket revenue profiles.
- Automatic:Motorized drive units with sensor-activated wing rotation handle 500,000+ operational cycles. Dubai airport terminals and Riyadh hospitality complexes specify these for high-throughput pedestrian management with integrated access control.
- Energy Saving:Thermally broken frames and low-emissivity glazing assemblies meet Saudi Building Code U-value mandates. New commercial construction across the Gulf Cooperation Council treats these as envelope components rather than access hardware.
- Manual:Unpowered three-wing or four-wing configurations for low-traffic secondary entrances. Heritage building retrofits in older Dubai and Jeddah districts specify these where electrical infrastructure is constrained.
- Security:Reinforced framing with blast-resistant glazing and access-control integration. Government and diplomatic facilities in Abu Dhabi and Riyadh procure these for controlled entry protocols.
Automatic systems dominate installed base across Gulf commercial portfolios. Energy Saving variants are where expansion concentrates as thermal code enforcement tightens.
Application:
Specification complexity and decision-maker involvement intensify from standardized retail deployments to bespoke hospitality and aviation projects.
- Hotels:Grand entrance configurations with 3.6-4.2 meter diameter drums and premium finish requirements. Dubai and Doha hospitality pipelines specify automatic systems with building management integration to manage lobby climate control.
- Commercial Buildings:Mid-rise office towers and mixed-use developments with standardized 2.4-3.0 meter diameter specifications. Riyadh and Jeddah corporate construction drives volume procurement through contractor-led specifications.
- Airports:Extra-large diameter systems (4.5+ meters) with heavy-duty drive units rated for continuous operation. Dubai International and Hamad International expansion projects generate demand for certified fire-rated and accessibility-compliant configurations.
- Retail Outlets:Compact two-wing or three-wing units for shopping mall anchor tenants and flagship stores. Mall operators in Abu Dhabi and Kuwait City prioritize rapid installation and minimal structural modification.
Commercial Buildings anchor current specification volumes. Hotels are climbing the fastest as Gulf hospitality construction accelerates.
End User:
Decision authority and technical evaluation depth vary sharply between design-phase influencers and operational-phase purchasers.
- Building Owners:Hold capital expenditure authority on new construction and major renovations. Sovereign wealth-backed developers in Saudi Arabia and the UAE prioritize lifecycle cost guarantees and long-term service agreements.
- Architects:Drive aesthetic and performance specifications during schematic design. Leading firms in Dubai and Riyadh specify certified thermal performance data to satisfy green building permitting requirements.
- Facility Managers:Control aftermarket procurement and replacement decisions. Large hospitality operators in Dubai are unbundling service contracts from original equipment vendors to capture predictive maintenance value.
- Contractors:Execute value engineering and installation scheduling on fixed-price contracts. Gulf construction firms face margin pressure from stainless steel commodity volatility and European component lead times.
Building Owners control specification authority on new projects. Facility Managers are gaining influence fastest as service virtualization extends vendor relationships.
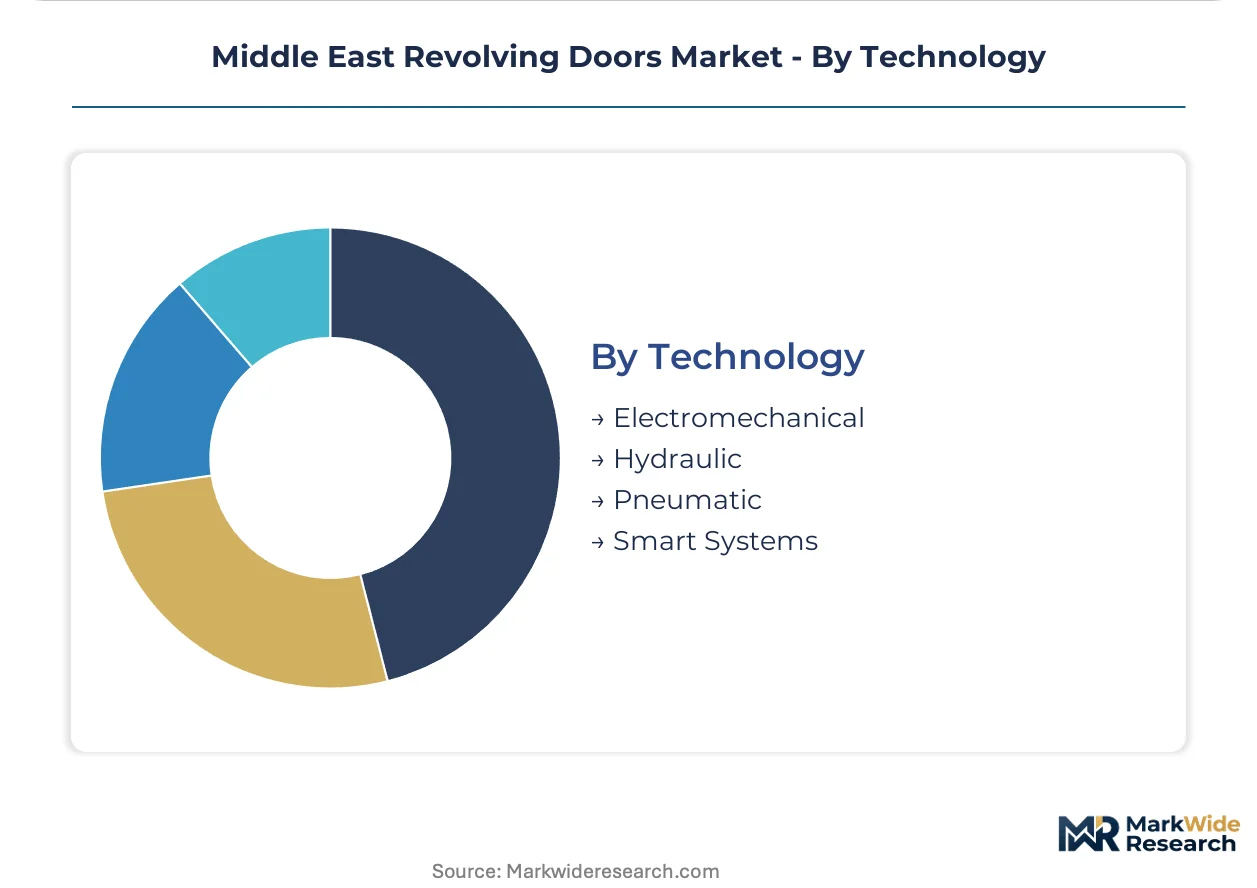
Technology:
Component sourcing geography and maintenance skill requirements create divergent supply chain risk profiles across technology categories.
- Smart Systems:IoT-enabled drive units with cloud-connected diagnostics and building management integration. Dubai airport and premium hotel portfolios specify these to enable predictive maintenance and operational cycle optimization.
- Electromechanical:AC or DC motor drives with gearbox transmission and programmable logic controllers. This technology anchors current specification volumes across Gulf commercial and hospitality applications.
- Hydraulic:Fluid-power drive systems for heavy-duty and security-rated installations. Specialized applications in government and diplomatic facilities specify these for smooth operation under load variation.
- Pneumatic:Compressed-air actuation for explosion-hazard environments and specific industrial settings. Limited deployment in Middle East commercial construction due to maintenance infrastructure requirements.
Electromechanical systems dominate current installed base. Smart Systems are gaining share fastest as building management integration becomes standard specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contractors in Saudi Arabia and Qatar demonstrate lowest price elasticity as thermal code enforcement tightens specification windows, while Kuwaiti retail developers retain higher sensitivity to upfront capital outlay.
United Arab Emirates
Dubai International Airport's terminal expansion and the Dubai South logistics corridor are procuring extra-large diameter systems rated for continuous operation. MOHAP fire safety standards mandate certified configurations for high-occupancy transit facilities. The Dubai Design District hospitality cluster is specifying smart-enabled units with building management integration.
Saudi Arabia
Riyadh's King Abdullah Financial District and Diriyah Gate developments are driving specification volume for premium entrance systems. The Saudi Building Code's updated thermal transmittance mandates for commercial entryways elevate procurement priority for energy-efficient variants. Jeddah's historic district retrofit projects are adapting manual configurations where electrical infrastructure constraints apply.
Qatar
Post-World Cup hospitality and entertainment venue construction in Lusail and West Bay is generating demand for grand entrance configurations. Qatar Civil Defence fire-rated certification requirements shape specification timelines for hotel and retail deployments. The Pearl-Qatar marina district is procuring corrosion-resistant framing for coastal exposure conditions.
Kuwait
Shopping mall anchor tenant fit-outs in Kuwait City prioritize rapid-install compact units with minimal structural modification. The Public Authority for Industry's building product conformity assessment procedures influence vendor qualification timelines. The Sabah Al-Salem residential corridor is seeing standardized office tower specifications through contractor-led procurement.
Oman
Muscat International Airport's capacity expansion and the Sultan Qaboos Port redevelopment are creating specification opportunities for heavy-duty drive systems. The Ministry of Regional Municipalities and Water Resources maintains accessibility standards that intersect with entrance system certification. The Duqm Special Economic Zone industrial construction is adopting mid-tier automatic configurations for administrative facilities.
Middle East Revolving Doors Market Competitive Landscape
Capability concentration sits with European electromechanical specialists; scale advantage sits with diversified building technology conglomerates. The vendor base separates into three functional tiers: heritage entrance system fabricators with century-long technical archives, diversified access control platforms integrating hardware with software-managed ecosystems, and regional installation contractors executing fixed-price deployment contracts. Competitive moves center on long-term service agreement anchoring and predictive maintenance capability bundling.
Within the heritage fabrication tier, Record and Boon Edam represent electromechanical expertise anchored in multi-decade operational archives. Dormakaba occupies a position exemplifying the access-control integration archetype, where hardware specification extends into software-managed entry ecosystems. These three entities illustrate how competitive boundary lines are shifting between pure-play entrance system suppliers and unified building technology platforms.
| Leading Market Players |
|---|
| Record |
| Geze |
| Dormakaba |
| ERREKA |
| Horton Automatics |
| Boon Edam |
| Stanley |
| Portalp |
| Assa Abloy |
| Others |
Pricing and Supply Chain Analysis
The Jebel Ali Port logistics corridor links European electromechanical component inflows to Gulf installation sites, with freight cost volatility amplifying margin pressure on fixed-price contracts while concentrating pricing power among suppliers with regional warehousing infrastructure.
Pricing Analysis
Long-term service agreements dominate procurement structures, with three-tier pricing separating premium smart-enabled systems from standard automatic configurations and economy manual units. Price differentiation hinges on thermal certification grade and predictive maintenance bundling, with Saudi Building Code compliance commanding measurable premiums. Pricing pressure stems from stainless steel commodity volatility compressing installation margins. Kuwaiti retail developers exhibit highest price sensitivity, while Saudi sovereign wealth-backed developers prioritize lifecycle guarantees over upfront capital minimization.
Supply Chain Analysis
Stainless steel feedstock draws from German, Italian, and Chinese metallurgical suppliers, creating tariff-exposed sourcing dependencies. Drive unit electromechanics rest on Swiss and German component specialists, while tempered glass panels source from regional float-glass facilities in the UAE and Saudi Arabia. Single-source vulnerability concentrates in precision gearbox and programmable logic controller supply. Distribution runs through Dubai-based regional stocking distributors serving contractor-led procurement across the Gulf Cooperation Council.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against air curtain and linear automatic door substitution threatening retrofit specifications, particularly where structural constraints limit revolving door deployment.
For Market Incumbents: Build predictive maintenance moats through sensor-embedded drive units and cloud-connected diagnostics platforms. Anchor long-term service agreements with Dubai hospitality portfolios and Riyadh financial district developments. Counter sliding door substitution by demonstrating lifecycle HVAC savings against air curtain alternatives. Deepen backward integration into regional glass fabrication to buffer stainless steel volatility.
For New Entrants and Emerging Players: Oman's Duqm Special Economic Zone offers underpenetrated white-space for mid-tier automatic configurations serving administrative and industrial facilities. Qatar's post-World Cup entertainment venue pipeline presents specification entry points for corrosion-resistant coastal variants. Target facility manager unbundling trends in Dubai by offering predictive maintenance SaaS independent of hardware procurement.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building technology conglomerates seeking to divest non-core entrance system divisions. Five-to-ten year viability favors vendors with electromechanical service archives and smart system integration capabilities. Monitor Saudi Building Code enforcement velocity as inflection indicator for energy-efficient variant demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Enables facility managers in Dubai to unbundle service from hardware vendors. |
| Backward Integration into Regional Glass Fabrication | Reduces tempered panel lead times and buffers stainless steel commodity exposure. |
| Thermal Certification Investment | Secures specification priority as Saudi Building Code mandates U-value documentation. |
| Smart System Partnership with Building Management Platforms | Extends vendor relationships from hardware into software-managed entry ecosystems. |
| Coastal Corrosion-Resistant Product Line | Captures Qatar marina and Red Sea hospitality construction specifications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Saudi Building Code documentation, UAE green building framework filings, and customs trade records for electromechanical component inflows. Interviews with facility managers at Dubai airport and hospitality portfolios, procurement leads at Saudi sovereign wealth developers, and aftermarket service heads at regional distributors informed demand-side dynamics. Secondary validation drew from MOHAP fire safety certification databases, Qatar Civil Defence product conformity registers, and EU Green Deal extraterritorial influence documentation on Gulf ESG commitments. Bottom-up specification volume estimates triangulated against top-down construction pipeline valuations.
Forecast inputs incorporate automatic versus manual product type substitution rates, smart system adoption curves tied to building management integration mandates, and thermal code enforcement timelines across Gulf jurisdictions. Segmentation modeling spans product type, application vertical, end-user decision authority, and technology category. CAGRs derive from installation base growth, replacement cycle compression for smart-enabled units, and premium pricing capture for energy-certified configurations. Electromechanical technician scarcity and European component lead time exposure inform supply-constrained scenario boundaries.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese electromechanical suppliers or air curtain technology platforms would shift outcomes. Material shifts in Saudi thermal code enforcement velocity, stainless steel commodity volatility, or European component export restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Europe Wall Coverings Market
Homecare and Decor
Bulletin Board Market
Homecare and Decor
Global Decorative Panels Market
Homecare and Decor
Wall Covering Market
Homecare and Decor
Curtains and Window Blinds Market
Homecare and Decor
Plantation Shutters Market
Homecare and Decor
Global Homeware Market
Homecare and Decor
Smart Curtain Market
Homecare and Decor
US Halloween Decorations Market
Homecare and Decor
Terracotta Pots Market
Homecare and Decor
Mattress Pads Market
Homecare and Decor
Europe Commercial Blinds and Shades Market
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
Garden Sheds Market
Homecare and Decor
US Wallcovering Market
Homecare and Decor
Flush Door Market