
 Global Semiconductor Etch Equipment Market | 2026-2036
Global Semiconductor Etch Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Etch Equipment Market Intelligence
China's dual carbon goals, which target energy efficiency in high-tech manufacturing, is realigning procurement criteria for semiconductor fabrication equipment. Lam Research Corporation leverages its expertise in plasma physics to develop lower-energy etch systems. Tokyo Electron Limited competes on process control and throughput efficiency for next-generation nodes. Applied Materials, Inc. differentiates through its integrated materials solutions that optimize etch and deposition steps for reduced environmental impact.
Semiconductor etch equipment uses plasma or wet chemical processes to selectively remove materials from a wafer, creating circuit patterns with nanometer precision. Its primary function is to transfer lithographically defined designs onto the silicon substrate to build transistors and interconnects. Logic Chips and Memory Chips constitute the largest application segments by volume. While Inductively Coupled Plasma remains a dominant technology, Atomic Layer Etch represents the fastest-growing product type, essential for advanced logic device fabrication.
Equipment design must comply with international standards like those from the IEC and SEMI for safety and interoperability. Regulations such as the EU's REACH and RoHS directives restrict the use of certain hazardous chemicals in the manufacturing process, influencing etchant gas selection. Foundries and Integrated Device Manufacturers must now evaluate equipment not just on process performance but also on its ability to adapt to evolving material and environmental compliance landscapes.
Market Dynamics
The industry-wide transition to Gate-All-Around transistor architectures is the central force shaping the semiconductor etch equipment market. This shift compels a fundamental redesign of etch systems to achieve unprecedented levels of precision and material selectivity for fabricating nanosheet-based devices.
Growth Catalysts
- Advanced Logic Demand:The expansion of AI accelerators and data centers requires complex logic chips, directly stimulating investment in high-precision etch equipment capable of fabricating sub-5nm nodes.
- Foundry Capital Expenditure:Massive government and private sector investment is expanding fabrication capacity, particularly in semiconductor hubs within Taiwan and South Korea, creating sustained demand for new etch tools.
- 3D Device Architectures:The move from planar transistors to complex 3D structures, including FinFET and Gate-All-Around, necessitates new etch capabilities for high-aspect-ratio and multi-material stack etching.
Market Restraints
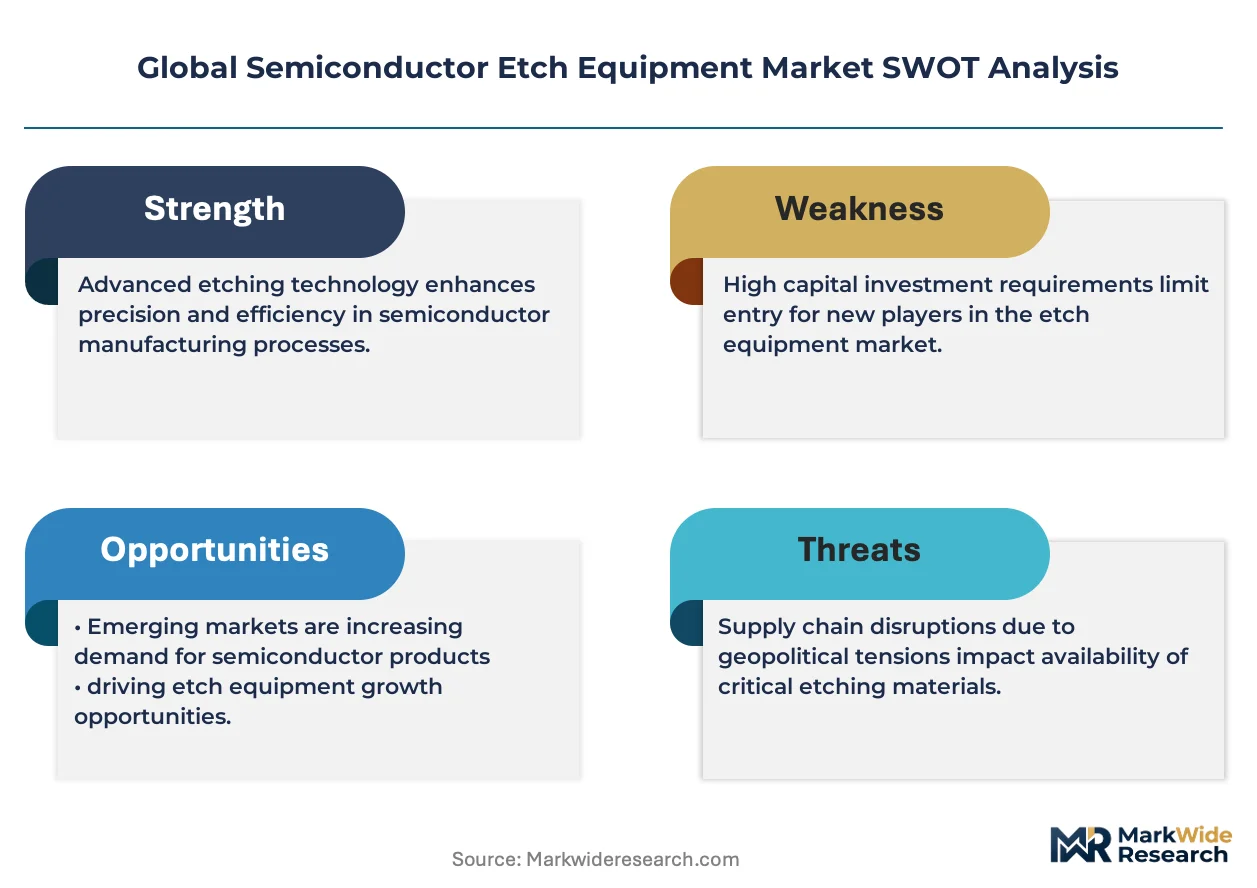
- Extreme Capital Intensity:The immense cost of developing and acquiring next-generation EUV-compatible etch systems creates a high barrier to entry, limiting adoption to the largest integrated device manufacturers and foundries.
- Component Supply Concentration:Critical subsystems, such as advanced radio-frequency generators and turbomolecular pumps, are sourced from a small number of specialized suppliers, creating potential bottlenecks and pricing pressures.
- Physical Process Limits:As feature sizes shrink, etch processes face fundamental challenges in managing plasma-induced damage, maintaining profile control, and achieving perfect selectivity between infinitesimally thin material layers.
Strategic Opportunities
- Atomic Layer Etch (ALE) Scale-Up:Developing higher-throughput ALE systems offers a significant opportunity to transition the technology from specialized applications to high-volume manufacturing for critical logic and memory layers.
- Sustainable Etching Solutions:Equipment designed to use alternative, low-GWP etchant gases or reduce energy consumption per wafer directly addresses compliance with China's dual carbon goals and the EU's REACH directive.
- Compound Semiconductor Processing:The growing market for GaN and SiC power devices and RF components creates a need for specialized etch equipment optimized for these harder-to-process materials.
Industry Challenges
- Talent Scarcity:A persistent shortage of plasma physicists and process engineers with expertise in next-generation etch technology constrains research and development cycles and limits operational support at customer sites.
- Material Qualification Timelines:Qualifying new etchant gases and chamber materials to meet both stringent process specifications and evolving environmental regulations like RoHS is a lengthy and expensive operational hurdle.
- System Integration Complexity:Integrating new, highly sophisticated etch modules into existing fab workflows alongside lithography and deposition tools presents a significant challenge, risking yield excursions and costly downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Etch Equipment Market |
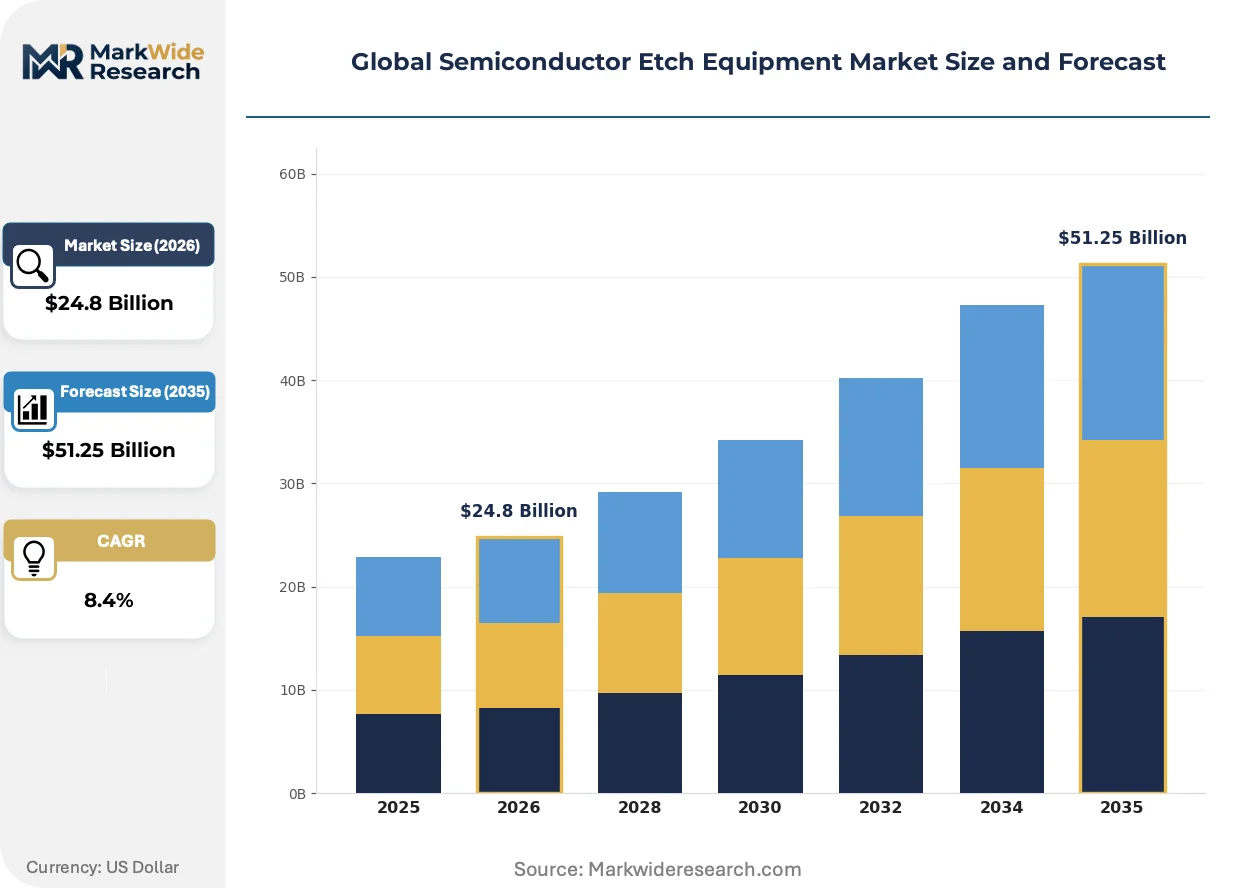
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactive Ion Etch, Plasma Etch, Ion Beam Etch, Wet Etch, Atomic Layer Etch Technology: Inductively Coupled Plasma, Capacitively Coupled Plasma, Deep Reactive Ion Etch, Cryogenic Etch, Magnetically Enhanced Reactive Ion Etch Application: Logic Chips, Memory Chips, Microelectromechanical Systems, Photonics Devices, Power Devices End User: Foundries, Integrated Device Manufacturers, Fabless Companies, Assembly & Test Service Providers |
| Companies Covered | Applied Materials, Inc., Lam Research Corporation, Tokyo Electron Limited, Hitachi High-Tech Corporation, Plasma-Therm, Oxford Instruments, NAURA Technology Group Co., Ltd., ULVAC, Inc., SPTS Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Etch Equipment Market Strategic Shifts & Innovations
Equipment design is now a dual optimization problem, balancing the nanometer-scale precision required for advanced devices with new mandates for energy and material efficiency. This convergence is driving innovation in both process control software and the underlying hardware and chemistry.
Machine learning software integrated into process control systems monitors plasma characteristics and wafer-state data in real time. Leading-edge foundries are rapidly adopting this for fabricating advanced memory and logic devices where process windows are exceptionally narrow. This intelligent oversight is automating the micro-adjustments of etch parameters like gas flow and RF power, reducing wafer-to-wafer variability and the need for constant manual engineering supervision.
The EU's F-Gas Regulation imposes strict controls on fluorinated gases with high global warming potential, which are common in plasma etching. This directive compels an industry-wide re-evaluation of process chemistries and investment in abatement systems for exhaust streams. The dry etch segment is most affected, with manufacturers responding by developing processes that use alternative gases or higher-efficiency plasma sources to reduce total gas consumption.
A clear shift in equipment acquisition favors integrated etch and deposition platforms sourced from a single vendor. This model displaces the traditional approach where fabs procured best-of-breed tools from multiple specialized suppliers for different process steps. The trend is most prominent in leading-edge fabrication plants in Taiwan and South Korea, where minimizing process variability between sequential steps is essential for achieving high yields.
Global Semiconductor Etch Equipment Market Segmentation
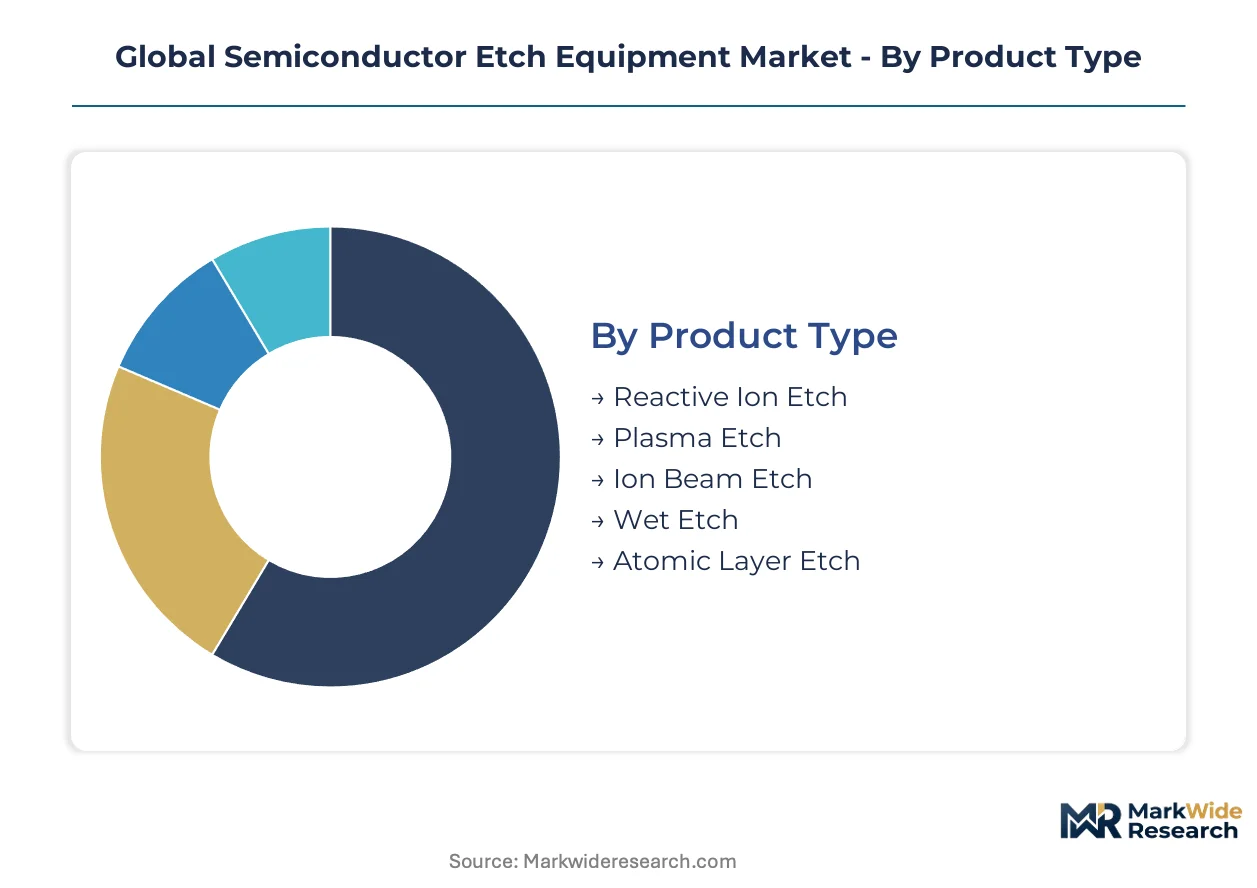
The semiconductor etch equipment market segmentations illuminate the intricate technological landscape and diverse operational demands driving industry growth. Understanding these distinctions is essential for tracking innovation, identifying specific investment areas, and tailoring solutions for advanced device manufacturing. These categories reflect how various fabrication techniques and end-user requirements shape equipment development.
Product Type:
The market's product type segmentation differentiates equipment based on the fundamental etching mechanism employed for material removal from semiconductor wafers.
- Atomic Layer Etch:This highly precise technique removes material one atomic layer at a time, essential for patterning advanced 3D structures and Gate-All-Around (GAA) transistors. Demand for ALE is intensifying in leading-edge logic and memory fabrication, particularly for sub-5nm nodes.
- Plasma Etch:Utilizing plasma to generate reactive species, this method offers anisotropic etching for creating vertical sidewalls and high aspect ratio features. Plasma etch systems are fundamental across various chip manufacturing processes, supporting both logic and memory production globally.
- Reactive Ion Etch:Combining chemical reactions with physical ion bombardment, RIE provides a balance of selectivity and anisotropy for a wide range of patterning tasks.
- Ion Beam Etch:This physical etching method uses a directed beam of ions to remove material, offering fine control for specific applications like magnetic devices and compound semiconductors.
- Wet Etch:Employing liquid chemicals to remove material, wet etch is typically used for bulk material removal, cleaning, or isotropic etching processes in less critical steps.
Mature deployment sits with Reactive Ion Etch. Newer deployment is concentrated in Atomic Layer Etch.
Technology:
This technology segmentation categorizes etch systems by their specific plasma generation and control methodologies, impacting precision and throughput for semiconductor fabrication.
- Inductively Coupled Plasma:ICP systems generate high-density plasma through inductive coils, offering excellent control over ion energy and radical flux for critical etching applications. This technology remains a dominant force in advanced manufacturing, supporting complex multi-layer device architectures.
- Deep Reactive Ion Etch:DRIE is a specialized plasma etching technique designed for creating high aspect ratio trenches and holes, crucial for MEMS devices and 3D packaging technologies. The push for 3D integration across various device types stimulates its adoption.
- Capacitively Coupled Plasma:CCP tools utilize RF power applied to parallel plates to create plasma, providing a cost-effective solution for less demanding etch processes and bulk material removal.
- Cryogenic Etch:This technique employs low temperatures during the etching process to achieve extremely high selectivity and reduced sidewall damage, particularly for silicon-based devices.
- Magnetically Enhanced Reactive Ion Etch:MERIE systems use magnetic fields to confine and increase plasma density, improving etch rates and uniformity for specific applications.
Inductively Coupled Plasma remains a foundational technology. Deep Reactive Ion Etch is gaining traction for complex 3D structures.
Application:
The application segments delineate equipment usage based on the type of semiconductor device being fabricated, reflecting diverse performance requirements and market demands.
- Logic Chips:These chips form the processing core of electronic devices, with demand driven by AI accelerators, data centers, and high-performance computing requiring sub-5nm nodes. Etch equipment for logic chips demands extreme precision for Gate-All-Around and FinFET architectures.
- Memory Chips:Including DRAM and NAND flash, memory chips are vital for data storage in consumer electronics and enterprise solutions, necessitating high-volume and cost-efficient etch processes. The transition to 3D NAND and advanced DRAM architectures drives innovation in multi-layer etching.
- Microelectromechanical Systems:MEMS devices integrate mechanical and electrical components on a chip, requiring specialized etch processes for creating intricate 3D microstructures.
- Photonics Devices:These devices manipulate light, used in fiber optics and sensors, and demand precise etching for waveguide structures and optical cavities.
- Power Devices:Utilizing materials like GaN and SiC, power devices require robust etch equipment optimized for these harder-to-process compound semiconductors used in electric vehicles and renewable energy.
Logic Chips and Memory Chips collectively drive the largest volume demand. Specialized applications like Power Devices are expanding rapidly.
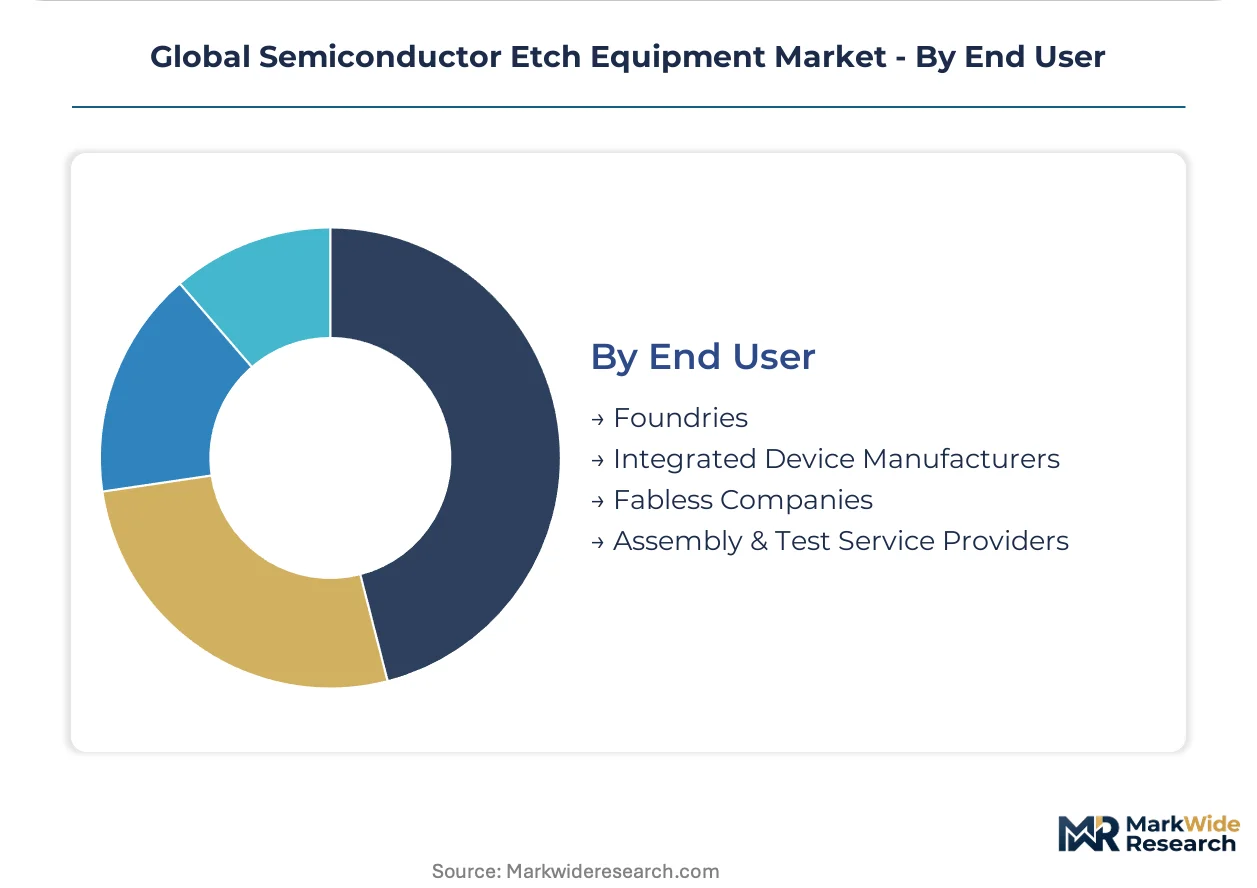
End User:
The end-user segmentation categorizes market participants by their operational model within the semiconductor manufacturing ecosystem, influencing procurement strategies and technology adoption rates.
- Foundries:These companies specialize in manufacturing chips for other firms (fabless companies), investing heavily in the latest etch equipment to offer cutting-edge process technologies. Massive capital expenditure in Taiwan and South Korea is concentrated in these facilities.
- Integrated Device Manufacturers:IDMs design, manufacture, and sell their own chips, maintaining significant in-house fabrication capabilities and requiring a broad range of etch solutions. These firms often drive early adoption of new etching technologies for competitive advantage.
- Fabless Companies:These firms design chips but outsource manufacturing to foundries, influencing etch equipment demand indirectly through their technology specifications.
- Assembly & Test Service Providers:These providers focus on the final stages of chip production, with minimal direct demand for etch equipment, but their requirements can influence packaging-related etch processes.
Foundries represent the largest purchasers of advanced etch equipment. Integrated Device Manufacturers maintain significant in-house fabrication capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park in Taiwan anchors a significant portion of global semiconductor manufacturing, driving substantial demand for advanced etch equipment. These fabrication hubs, supported by government investment, continuously upgrade their facilities to produce next-generation chips. Precision etching capabilities are critical for their leadership in logic and memory device production.
Taiwan
Taiwan's demand for etch equipment stems from its leadership in advanced logic and Gate-All-Around (GAA) transistor fabrication. Government investment incentives support continuous capital expenditure in leading-edge foundries. The Hsinchu Science Park remains a critical cluster, with major foundries expanding capacity for sub-5nm node production.
South Korea
South Korea's semiconductor industry drives demand for etch systems, particularly for advanced memory chips and next-generation logic architectures. National investment programs encourage research and development into high-throughput Atomic Layer Etch technologies. Gyeonggi Province, including Pyeongtaek, concentrates significant manufacturing facilities for global memory and logic chip supply.
United States
The United States sees demand for etch equipment from its robust R&D ecosystem and renewed domestic manufacturing initiatives. Federal initiatives like the CHIPS Act stimulate investment in new fabrication plants. Arizona and the Pacific Northwest are emerging as key hubs, attracting new foundries and expanding existing facilities.
China
China's drive for semiconductor self-sufficiency fuels substantial investment in etch equipment across various technology nodes. The country's dual carbon goals influence procurement decisions, favoring energy-efficient and environmentally compliant systems. The Yangtze River Delta region, particularly Shanghai, is a significant center for domestic chip production and equipment manufacturing.
Japan
Japan contributes to etch equipment demand through its specialized materials, advanced packaging, and renewed focus on domestic chip production. Government-backed initiatives promote collaboration between equipment makers and foundries. Kyushu, known as "Silicon Island," is witnessing revitalization with new fab projects and expanded research facilities.
Global Semiconductor Etch Equipment Market Key Industry Players
Premium-margin players sit above commodity-margin players across technological innovation and process precision. The market is structured with a few dominant technology leaders and several specialized niche players. Strategic archetypes include integrated solution providers, plasma physics specialists, and process control innovators. Dominant competitive moves involve significant research and development investment and strategic partnerships with leading foundries.
US-based Applied Materials, Inc. exemplifies integrated materials solutions, optimizing both etch and deposition steps for reduced environmental impact. Lam Research Corporation, also US-based, anchors the market with its expertise in plasma physics, developing lower-energy etch systems. Japan-based Tokyo Electron Limited occupies a strong position by competing on process control and throughput efficiency for next-generation nodes.
| Leading Market Players |
|---|
| Applied Materials, Inc. |
| Lam Research Corporation |
| Tokyo Electron Limited |
| Hitachi High-Tech Corporation |
| Plasma-Therm |
| Oxford Instruments |
| NAURA Technology Group Co., Ltd. |
| ULVAC, Inc. |
| SPTS Technologies |
| Others |
Cost & Logistics Intelligence
Precision versus commodity equipment defines the semiconductor etch market, where advanced atomic layer etch systems command premium pricing due to specialized component supply chains, while mature plasma etch tools face cost pressures. This bifurcation influences procurement strategies across foundries and integrated device manufacturers.
Pricing Analysis
Outcome-based pricing anchors semiconductor etch equipment, where value is directly linked to wafer throughput, process yield, and nanometer-scale precision. Price differentiation stems from customization levels for specific device architectures and comprehensive after-sales service packages. Pricing pressure intensifies for older-generation plasma etch systems due to increased supplier competition. Leading-edge foundries demonstrate lower price sensitivity for advanced Gate-All-Around tools, prioritizing performance, while integrated device manufacturers seek cost efficiencies for high-volume memory production.
Supply Chain Analysis
Refurbishment programs for high-value etch equipment components, alongside spare parts management, form a critical reverse logistics loop within the semiconductor industry. Supply for these complex systems concentrates heavily in Japan and the United States, sourcing specialized materials, RF generators, and turbomolecular pumps from a limited global vendor base. This component supply concentration creates a single-source vulnerability, impacting lead times for new equipment. Equipment distribution runs primarily through direct sales channels to major foundries and integrated device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The semiconductor etch equipment market navigates a fundamental technology transition, as Atomic Layer Etch (ALE) increasingly replaces traditional plasma etch for critical patterning steps. This shift reshapes competitive landscapes and investment priorities.
For Market Incumbents:Acquire specialized Atomic Layer Etch (ALE) IP portfolios to accelerate development of next-generation systems. Consolidate critical subsystem suppliers to mitigate component supply concentration, a persistent threat to production. Invest heavily in plasma physics R&D to overcome physical process limits at sub-3nm nodes, securing a long-term competitive lever. Forge strategic partnerships with leading foundries in Taiwan for early system integration and validation.
For New Entrants and Emerging Players:Capture market share in specialized applications like compound semiconductor processing, particularly for GaN and SiC power devices. Target the growing demand for sustainable etching solutions, emphasizing lower energy consumption per wafer. The MEMS segment offers a penetrable entry point due to diverse application requirements. A go-to-market strategy focusing on environmental compliance with EU's F-Gas Regulation can differentiate offerings.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized Atomic Layer Etch (ALE) technology providers given the industry's fundamental shift to Gate-All-Around architectures. Long-term viability for the next 5-10 years remains strong due to persistent demand for advanced logic chips. Acquisition targets should include plasma physics specialists with proven intellectual property in novel etch chemistries. Watch for increased capital expenditure announcements from leading foundries in Taiwan as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Atomic Layer Etch (ALE) Scale-Up | Scaling ALE for high-volume manufacturing is crucial for Gate-All-Around (GAA) transistor fabrication. |
| Sustainable Etching Solutions Development | Developing lower-GWP etchant gases addresses China's dual carbon goals and the EU's F-Gas Regulation. |
| Compound Semiconductor Equipment Optimization | Specialized etch tools are essential for the growing market of GaN and SiC power devices. |
| AI-driven Process Control Integration | Machine learning software enhances real-time process monitoring for advanced logic and memory devices. |
| Integrated Etch and Deposition Platforms | Single-vendor platforms minimize process variability between sequential steps for leading-edge fabrication. |
Research Approach
Industry reports, academic journals, and company financial filings formed the secondary backbone for this analysis. Primary interviews with plasma physicists, process engineers, and foundry procurement managers provided critical qualitative insights. This research combined both top-down market sizing and bottom-up validation, triangulating data points for robust conclusions. Secondary research was validated against primary stakeholder perspectives.
A bottom-up approach, complemented by top-down validation, structured the forecast framework across the analysis window. Segmentation dimensions modeled included product type, technology, application, end user, and device node complexity. Compound Annual Growth Rates were derived from historical growth patterns and projected technological shifts. Key industry-specific inputs included foundry capital expenditure and advanced logic chip demand for AI accelerators.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical tensions and rapid shifts in transistor architecture. Forecasts reflect assumptions concerning technological advancements and capital investment cycles. Practitioners should monitor major foundry expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
APAC Die Attach Equipment Market
Semiconductor Equipment
Chip Conveyors Market
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market
Semiconductor Equipment
Europe Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Semiconductor Wafer Fab Equipment (WFE) Market
Semiconductor Equipment
Plasma Etch System Market
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Wet Based Wafer Cleaning Equipment Market
Semiconductor Equipment
Vacuum Spin Coaters Market
Semiconductor Equipment
Global Wafer Cleaning Equipment Market
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Pulse Tube and Gifford-Mcmahon Cryocoolers Market
Semiconductor Equipment
Global Laser Dicing Systems Market
Semiconductor Equipment
Analog and Digital IC Development Tools Market
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
Dry Reactor Market