
 Semiconductor Bonding Equipment Market | 2026-2036
Semiconductor Bonding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Bonding Equipment Market Analytics
The EU Chips Act is realigning capital allocation rules for semiconductor fabrication equipment across European member states. Panasonic leverages its long-standing wire bonder installed base to sustain aftermarket service revenues in Japan and Southeast Asia. BE Semiconductor Industries N.V. specializes in high-accuracy die bonders for advanced packaging lines, while ASM Pacific Technology Ltd dominates thermocompression bonding platforms for flip chip applications. Kulicke & Soffa Industries anchors North American supply through its broad wire bonding portfolio serving legacy and leading-edge nodes.
Semiconductor bonding equipment comprises precision capital systems that mechanically and electrically attach dies, wires, or interposers to substrates using thermal, ultrasonic, or laser-induced metallurgical joining, typically achieving placement accuracy below five microns at throughputs exceeding ten thousand units per hour. The primary purpose is to create reliable electrical interconnects in packaged integrated circuits, from commodity microcontrollers to high-bandwidth memory stacks. Wire bonders occupy the largest installed base due to persistent demand from automotive and industrial microcontroller packaging, where gold and copper ball bonding remains cost-optimal. Flip chip bonders are expanding fastest as heterogeneous integration and 2.5D/3D packaging architectures displace wire bonding in high-performance computing. Die bonders capture concentrated margin pools in MEMS and photonics packaging, where epoxy dispensing precision and vacuum handling of fragile dies command premium pricing.
The US Department of Commerce export controls under the CHIPS and Science Act restrict bonding equipment sales to designated Chinese fabs, redirecting vendor focus toward allied Asian and European markets. Japan's METI coordinates domestic equipment makers through supply chain resilience programs that prioritize local content quotas in subsidized fabs. Taiwan's Industrial Development Bureau enforces cleanroom equipment certification standards that filter out non-compliant bonding system vendors. Stakeholders must monitor how subsidy localization requirements in the United States, European Union, Japan, and South Korea fragment procurement eligibility rules across otherwise integrated customer bases.
Market Dynamics
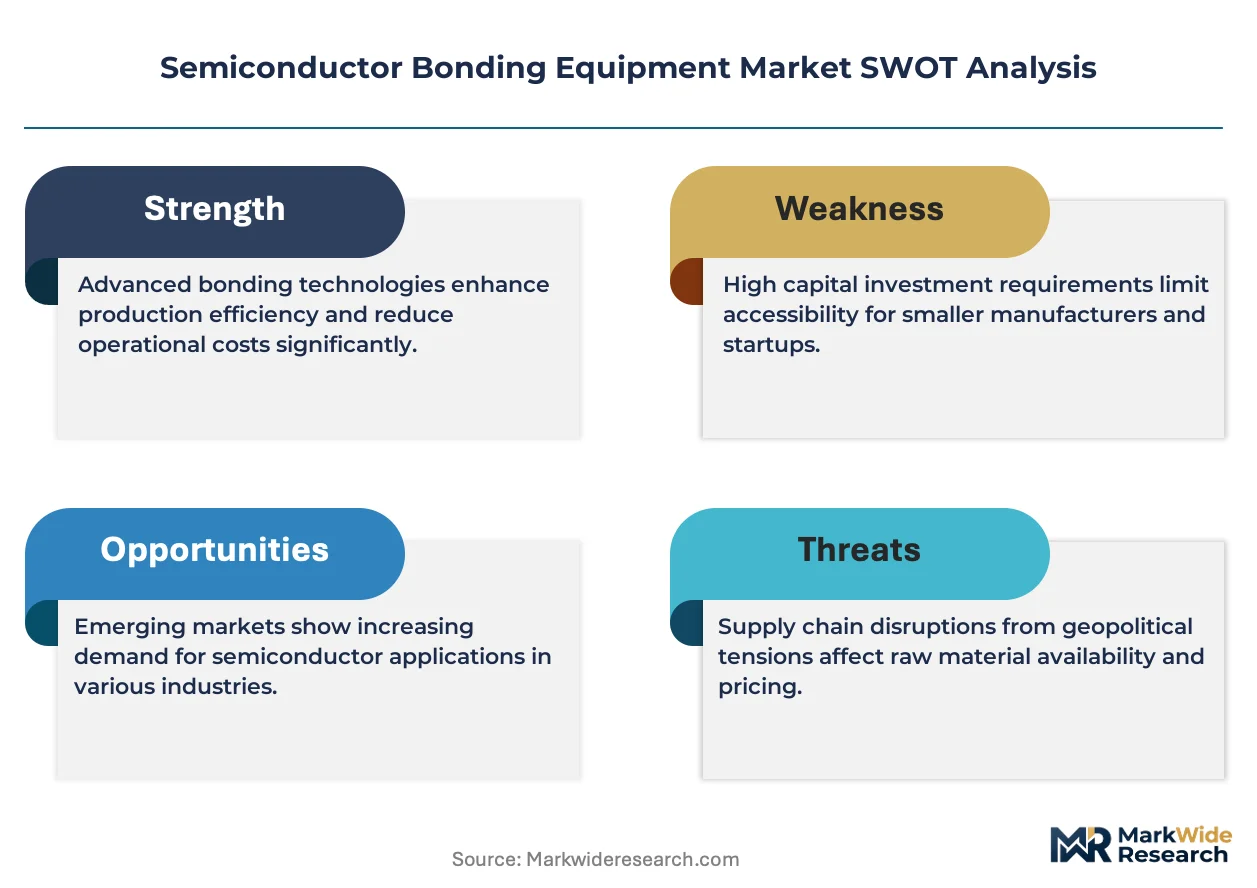
Advanced packaging architectures for AI accelerators and high-bandwidth memory stacks are compressing wire bonding's historical dominance while thermocompression and hybrid bonding platforms capture disproportionate capital allocation from foundry and OSAT procurement teams.
Growth Catalysts
- Heterogeneous Integration Mandates:Chiplet-based designs from AI chipmakers require die-to-wafer and die-to-die bonding precision below two microns, pulling orders toward thermocompression bonders.
- US CHIPS and Science Act:Domestic content requirements for subsidized fabs in Arizona and Texas redirect vendor sales teams toward captive memory and logic facilities.
- Copper Pillar and Microbump Proliferation:Flip chip interconnects for data center GPUs displace gold wire bonds in power delivery and signal routing layers.
Market Restraints
- Capital Intensity Concentration:Single advanced packaging line deployments exceed fifty million dollars, freezing out mid-tier OSATs in Malaysia and Vietnam.
- Specialized Component Scarcity:Ceramic heater blocks and ultrasonic transducers from Japanese suppliers face twelve-month lead times, throttling bondhead production.
- Export Control Friction:US Department of Commerce licensing requirements for fourteen-nanometer-and-below equipment block shipments to designated Chinese fabs, eliminating twenty percent of historical addressable demand.
Strategic Opportunities
- India Semiconductor Mission:Subsidized fab construction in Gujarat and Assam creates first-mover positioning for die bonder vendors before local supply chains mature.
- Glass Core Substrate Adoption:Intel and Samsung Foundry roadmaps for 2026-2027 panel-level packaging require new bonding toolsets for non-organic interposers.
- Equipment-as-a-Service Models:OSATs in Taiwan and South Korea favor throughput-based pricing over capital purchase, opening recurring revenue streams for bonding platform vendors.
Industry Challenges
- Metrology Integration Complexity:Real-time placement feedback systems must synchronize with third-party inspection tools from KLA and Onto Innovation, extending commissioning timelines.
- Process Engineer Talent Scarcity:Hybrid bonding recipes require expertise in surface activation chemistry and vacuum thermal compression that legacy wire bond technicians lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Bonding Equipment Market |
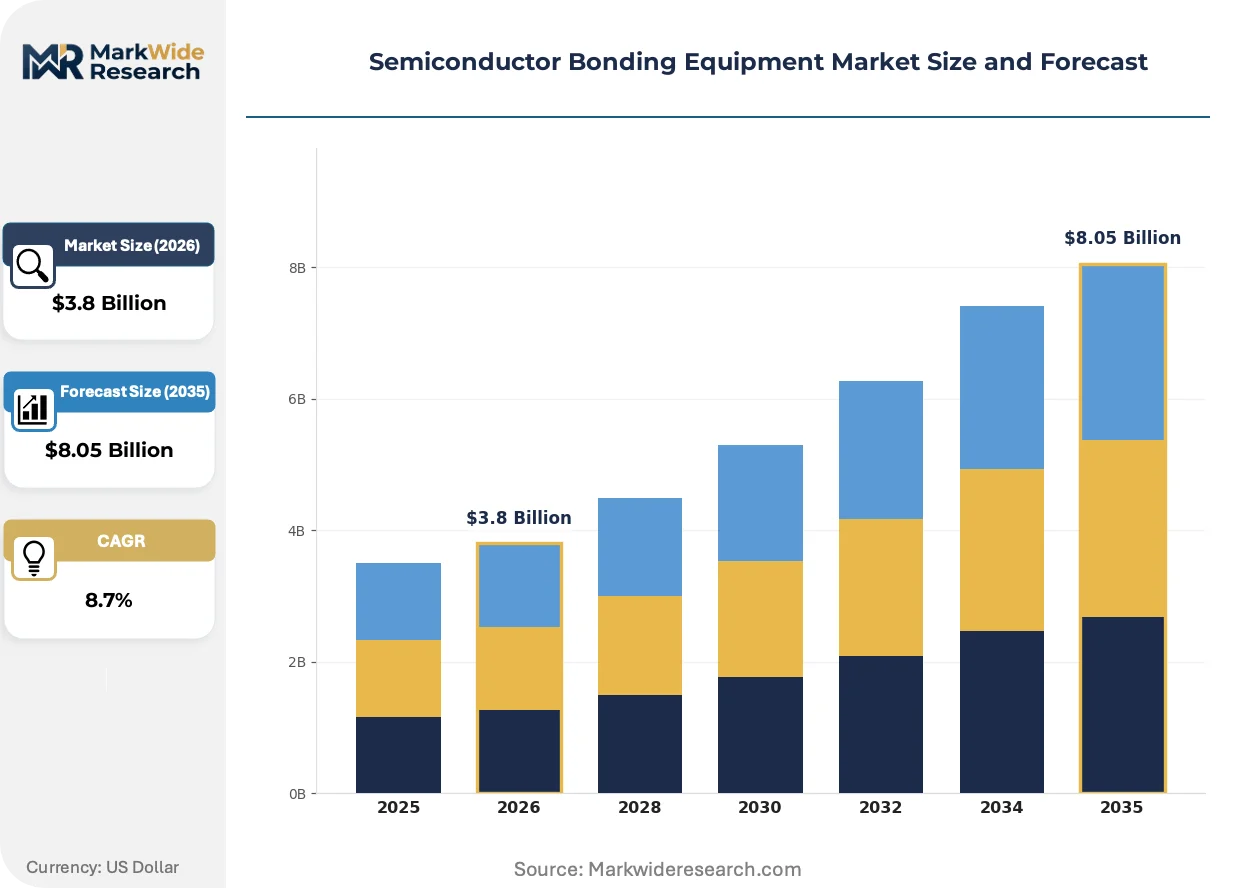
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Die Bonder, Wire Bonder, Flip Chip Bonder, Laser Bonder Technology: Thermal Bonding, Ultrasonic Bonding, Adhesive Bonding, Laser Bonding End User: Consumer Electronics, Automotive, Telecommunications, Aerospace Application: 3D Packaging, MEMS Packaging, IC Packaging, LED Packaging |
| Companies Covered | Panasonic, EV Group, ASM Pacific Technology Ltd, Shibaura Mechatronics Corporation, Nordson Corporation, Kulicke & Soffa Industries, SUSS MicroTec, Palomar Technologies, BE Semiconductor Industries N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Bonding Equipment Market Evolving Landscape
Thermocompression bonding is absorbing capital flows previously directed at wire bonders as heterogeneous integration architectures redefine interconnect hierarchy. Regulatory localization mandates and procurement model evolution are simultaneously fragmenting vendor access patterns.
Laser-assisted bonding is absorbing placement accuracy requirements for fine-pitch copper pillar applications in high-bandwidth memory stacks. Samsung and SK Hynix memory fabs in South Korea are deploying these platforms at scale for HBM3E production. The technology is absorbing market share from traditional thermocompression tools in applications below forty-micron pitch.
Japan's METI supply chain resilience programs now require local content quotas above sixty percent for subsidized equipment purchases in Kumamoto and Hokkaido fab clusters. This industrial policy redirects procurement eligibility toward domestic bonding tool vendors and their approved sub-tier suppliers. Die bonder lines for automotive MCU packaging face the tightest compliance timelines.
Outcome-based service contracts now dominate OSAT procurement in Taiwan, with vendors guaranteeing units-per-hour throughput rather than selling equipment outright. ASE Group and Powertech Technology are unbundling maintenance from capital leases, compressing vendor margin structures. This shift is most visible in Kaohsiung and Taichung packaging corridors where fleet utilization rates determine contract renewal.
Semiconductor Bonding Equipment Market Segmentation
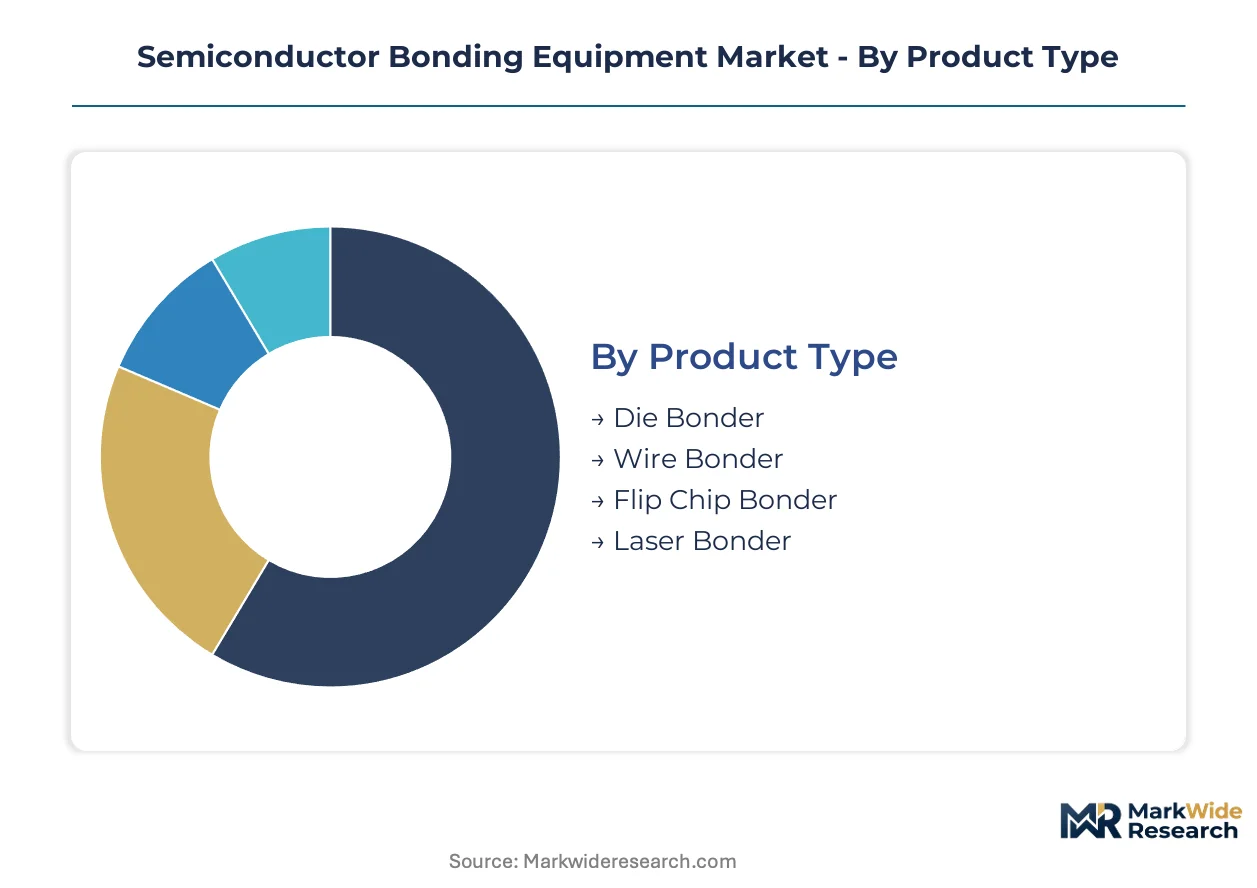
Equipment procurement patterns diverge sharply across bonding technologies and end-use applications. Die bonder buyers prioritize placement precision for fragile components, while wire bonder purchasers optimize throughput economics for high-volume microcontroller packaging.
Product Type:
Cost tier separates legacy wire bonding installations from advanced packaging capital commitments exceeding fifty million dollars per line.
- Die Bonder:Precision placement systems handle fragile dies using vacuum collets and epoxy dispensing at sub-five-micron accuracy. Memory fabs in South Korea deploy these for HBM3E stack assembly where die-to-wafer alignment tolerance compresses below two microns.
- Wire Bonder:Ball and wedge bonding platforms attach gold or copper wires between die pads and leadframes using thermal-sonic energy. Automotive MCU packaging in Germany and Japan sustains installed base demand where gold wire reliability outperforms flip chip for temperature cycling.
- Flip Chip Bonder:Thermocompression platforms align copper pillars and microbumps for heterogeneous integration.
- Laser Bonder:Non-contact joining systems address fine-pitch applications in photonics and advanced memory.
Volume sits with wire bonders; growth tilts toward die bonders.
Technology:
Application temperature requirements and substrate material compatibility drive technology selection across packaging workflows.
- Thermal Bonding:Heated bondheads apply controlled temperature profiles to achieve metallurgical joints in wire and die attach processes. OSATs in Taiwan favor these systems for copper wire conversion programs targeting cost reduction in commodity packaging.
- Ultrasonic Bonding:High-frequency mechanical vibration enables room-temperature wire attachment to temperature-sensitive substrates. MEMS packaging lines in the United States deploy these for accelerometer and gyroscope assembly where polymer substrate damage must be eliminated.
- Adhesive Bonding:Conductive and non-conductive epoxies attach dies without thermal stress for photonics and sensor applications.
- Laser Bonding:Localized heating through optical energy enables selective joining of dissimilar materials at fine pitch.
Ultrasonic bonding commands the broadest installed base; laser bonding is expanding most quickly.
End User:
Reliability certification requirements and production scale separate automotive qualification programs from consumer electronics volume procurement.
- Automotive:Zero-defect bonding protocols support AEC-Q100 qualification for engine control modules and advanced driver assistance systems. Tier-1 suppliers in Germany and Japan specify wire bonders with 100% visual inspection integration for safety-critical microcontroller packaging.
- Consumer Electronics:Smartphone and wearable OEMs drive flip chip and die bonder demand for application processors and camera modules. Assembly houses in Vietnam and Malaysia concentrate procurement for mid-range device packaging where cost-per-unit dominates equipment selection.
- Telecommunications:Base station and optical transceiver manufacturers require precision die attach for RF components and photonic integrated circuits.
- Aerospace:Hermetic sealing and extreme temperature qualification command premium bonding system specifications.
Consumer electronics absorbs the highest unit volumes; automotive commands the steepest expansion trajectory.
Application:
Packaging architecture complexity and interconnect density determine equipment specification tiers from commodity leadframe to advanced substrate systems.
- 3D Packaging:Through-silicon via and die stacking applications require hybrid bonding platforms with sub-micron alignment and surface activation capabilities. Intel and Samsung Foundry roadmaps for glass core substrates are pulling thermocompression tool development toward panel-level formats.
- IC Packaging:Traditional leadframe and laminate substrate assembly sustains wire bonder demand across microcontroller, power management, and analog device categories. Foundries in Taiwan and the United States maintain dual tool fleets serving both legacy node and advanced packaging requirements.
- MEMS Packaging:Vacuum cavity sealing and delicate die handling command specialized die bonder configurations for sensors and actuators.
- LED Packaging:High-throughput die attach for solid-state lighting applications prioritizes cost efficiency over placement precision.
IC packaging retains the largest equipment base; 3D packaging is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Taiwan, South Korea, and the United States concentrate bonding equipment procurement through tax-advantaged fab construction. Subsidy localization requirements fragment vendor access across otherwise integrated supply chains. Equipment certification standards in Taiwan and Japan filter non-compliant suppliers from qualified vendor lists.
United States
CHIPS Act subsidies for Arizona and Texas fabs redirect vendor sales teams toward captive memory and logic facilities. The Department of Commerce enforces export controls blocking fourteen-nanometer-and-below equipment shipments to designated Chinese fabs. Phoenix and Austin metro areas concentrate advanced packaging line deployments exceeding fifty million dollars per installation.
Taiwan
ASE Group and Powertech Technology drive outcome-based service contracts favoring throughput guarantees over capital purchase. The Industrial Development Bureau enforces cleanroom equipment certification standards that filter non-compliant bonding system vendors. Kaohsiung and Taichung packaging corridors determine contract renewal through fleet utilization rate metrics.
South Korea
Samsung and SK Hynix deploy laser-assisted bonding platforms at scale for HBM3E production. The Ministry of Trade, Industry and Energy coordinates supply chain resilience programs prioritizing local content quotas in subsidized fabs. Yongin and Pyeongtaek memory clusters absorb disproportionate capital allocation for thermocompression tool development.
Japan
Panasonic leverages its wire bonder installed base to sustain aftermarket service revenues across Japan and Southeast Asia. METI requires local content quotas above sixty percent for subsidized equipment purchases in Kumamoto and Hokkaido fab clusters. Automotive MCU packaging lines face the tightest compliance timelines for domestic bonding tool procurement.
China
Domestic fab construction continues despite US export controls restricting access to advanced bonding platforms. The Ministry of Industry and Information Technology coordinates indigenous equipment development through national technology programs. Shanghai and Beijing semiconductor clusters pivot toward mature-node wire bonder installations excluded from licensing restrictions.
Semiconductor Bonding Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers. Market structure consolidates around equipment vendors with captive installed bases and recurring service revenue streams. Three archetypes dominate: diversified electronics conglomerates with bonding divisions, precision capital equipment pure-plays, and semiconductor process tool specialists. Competitive moves center on geographic expansion into subsidized fab corridors and portfolio diversification toward advanced packaging platforms.
Within the precision equipment tier, BE Semiconductor Industries N.V. and ASM Pacific Technology Ltd exemplify focused specialists occupying positions in high-accuracy die bonding and thermocompression platforms respectively. Panasonic anchors the diversified conglomerate archetype through its long-standing wire bonder installed base. Kulicke & Soffa Industries sits within the North American supply anchor category. These three company structures illustrate how vendor origin and corporate form shape competitive positioning across fragmented procurement eligibility rules.
| Leading Market Players |
|---|
| Panasonic |
| EV Group |
| ASM Pacific Technology Ltd |
| Shibaura Mechatronics Corporation |
| Nordson Corporation |
| Kulicke & Soffa Industries |
| SUSS MicroTec |
| Palomar Technologies |
| BE Semiconductor Industries N.V. |
| Others |
Value Network & Pricing Analysis
Captive memory fabs in South Korea and Taiwan command contract-based pricing with throughput guarantees, while mid-tier OSATs in Vietnam and Malaysia face spot-market volatility for standard wire bonders. This buyer concentration tilts vendor negotiation leverage toward volume-commitment structures with penalty clauses for lead-time slippage.
Pricing Analysis
Short-lead-time premiums of fifteen to twenty percent apply to ceramic heater blocks and ultrasonic transducers sourced from Japanese suppliers, while spot inventory of legacy wire bonders trades at discounts in secondary markets. Three-tier pricing structure across premium, standard, and economy levels separates thermocompression platforms with sub-micron alignment from copper wire conversion systems and refurbished gold ball bonders. Price differentiation hinges on placement accuracy certification and geographic delivery cost from equipment hubs in Taiwan and Japan. Pricing pressure stems from outcome-based service contracts compressing vendor margins in Kaohsiung and Taichung packaging corridors. Mid-tier OSATs in Southeast Asia exhibit highest price sensitivity, whereas Samsung and SK Hynix absorb premium pricing for HBM3E assembly lines.
Supply Chain Analysis
Direct-to-captive-fab channels handle hyperscale demand from Samsung, SK Hynix, and Intel, while distributor networks serve tier-two OSATs in Malaysia and Vietnam. Manufacturing concentrates in Taiwan, South Korea, and Japan, with assembly of precision bondheads tethered to cleanroom clusters in Hsinchu and Yongin. Ceramic heater blocks, ultrasonic transducers, and vacuum collets draw from specialized Japanese and German component suppliers. Single-source vulnerability around ceramic heater blocks from Kyocera and NGK Insulators exposes bondhead production to twelve-month lead time extensions. Distribution runs through authorized service centers with certified technician pools, locking out unauthorized spare parts channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment availability lags demand by eight to twelve months due to ceramic heater block shortages, propping pricing power for vendors with captive component inventories.
For Market Incumbents: Cement aftermarket service revenue streams by unbundling maintenance from capital leases in Taiwan and South Korea, where ASE Group and Powertech Technology now demand throughput guarantees. Add bondhead refurbishment capacity in Arizona and Texas to capture CHIPS Act localization requirements. Vertical integration into ceramic heater block supply buffers against NGK Insulators lead-time volatility. Invest in laser-assisted bonding R&D to defend against thermocompression displacement in HBM4 roadmaps. For New Entrants and Emerging Players: The price-point gap between ASM Pacific thermocompression platforms and refurbished Kulicke wire bonders opens white-space targeting for mid-accuracy die bonders in India's Gujarat and Assam fab corridors. Target automotive MCU packaging lines in Kumamoto and Hokkaido where METI local content quotas above sixty percent filter out non-domestic vendors. Penetrate through equipment-as-a-service models with guaranteed uptime contracts rather than capital sale competition. Focus on glass core substrate bonding tool development ahead of Intel and Samsung Foundry 2026-2027 roadmaps. For Investors and Strategic Acquirers: The window for entry favors pure-play die bonder specialists with sub-five-micron placement patents and recurring service revenue above forty percent of total sales. Long-term viability rests on heterogeneous integration roadmaps from AI chipmakers requiring die-to-wafer bonding precision below two microns. Target acquisition archetypes include hybrid bonding technology holders with surface activation chemistry expertise and established cleanroom certification in Taiwan. Watch for inflection when ASE Group and Powertech Technology convert remaining capital lease fleets to pure service contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Technology Acquisition | Captures sub-micron alignment capabilities required for HBM4 and 3D logic stacking roadmaps. |
| India Market First-Mover Positioning | Secures qualified vendor status before Gujarat and Assam fab supply chains mature. |
| Ceramic Heater Block Backward Integration | Insulates bondhead production from NGK Insulators and Kyocera lead-time volatility. |
| Equipment-as-a-Service Model Rollout | Aligns with ASE Group and Powertech Technology procurement shifts in Taiwan. |
| Glass Core Substrate Tool Development | Addresses Intel and Samsung Foundry panel-level packaging requirements for 2026-2027. |
Research Methodology
Independent corroboration across equipment vendor sales executives, OSAT procurement directors, and captive fab engineering managers underwrites the qualitative findings in this study. Primary interviews with process engineers at Samsung, SK Hynix, ASE Group, and Powertech Technology supplied placement accuracy requirements and throughput specifications. Secondary validation drew from SEC 10-K filings of listed equipment vendors, Taiwan Industrial Development Bureau certification registries, and Japan METI supply chain resilience program disclosures. Bottom-up triangulation across individual tool procurement records and top-down reconciliation against fab capex announcements anchored market size estimates.
Comparable-period anchoring linked forward projections to historical wire bonder and die bonder shipment cycles across the analysis window. The modeling framework segmented by bonding technology type, end-use application, and regional regulatory cluster. CAGRs were derived from equipment procurement pipeline analysis and foundry capacity expansion schedules. Key forecast inputs included HBM3E and HBM4 die stacking layer counts, plus CHIPS Act and EU Chips Act subsidy disbursement timelines.
Inputs from Taiwan Industrial Development Bureau and Japan METI were available through the study window; gaps in Chinese indigenous equipment development progress introduce uncertainty bands around mature-node wire bonder demand forecasts. Forecasts reflect assumptions regarding ceramic heater block supply normalization and export control licensing continuity. Periodic stress-testing of base assumptions against foundry capex revision announcements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Semiconductor CVD Equipment Market
Semiconductor Equipment
Global Microelectronics Cleaning Equipment Market
Semiconductor Equipment
Global Capacitor Winding Machines Market
Semiconductor Equipment
Global Semiconductor Wafer Polishing and Grinding Equipment Market
Semiconductor Equipment
Global Semiconductor Back-End Equipment Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Plasma Etch System Market
Semiconductor Equipment
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Photoresist for Semiconductor Market
Semiconductor Equipment
Pulse Tube and Gifford-Mcmahon Cryocoolers Market
Semiconductor Equipment
Africa Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Wire Bonder Equipment Market
Semiconductor Equipment
Europe Semiconductor Etch Equipment Market
Semiconductor Equipment
Semiconductor Equipment Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market