
 Consumable Parts for Semiconductor Equipment Market | 2026-2036
Consumable Parts for Semiconductor Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Consumable Parts for Semiconductor Equipment Market Insights
A widening capability gap between vertically integrated incumbents and specialized material suppliers is reorganizing competitive tiers in consumable parts. Lam Research leverages captive ceramic manufacturing to control critical slit blade specifications, while Entegris sustains its position through advanced contamination control chemistry for fluid delivery systems. Kyocera anchors the Asia-Pacific supply base with precision-engineered chuck pads that compete on thermal uniformity metrics.
Consumable parts for semiconductor equipment encompass process-worn components—ceramic slit blades, polyimide chuck pads, quartz photo masks, polymer wafer carriers, and engineered cleaning cloths—fabricated to sub-micron tolerances and extreme purity grades to prevent particle contamination during wafer processing. These parts function as sacrificial interfaces between process tools and silicon substrates, requiring replacement at intervals dictated by film thickness deposition, plasma exposure cycles, or mechanical wear rates. Photo masks and wafer carriers command disproportionate margin pools due to EUV lithography's exacting flatness and defect specifications, while cleaning cloths represent the highest-volume, most price-sensitive category across CVD and etching tool platforms. Lithography consumables outpace deposition and CMP segments in value growth as leading-edge fabs extend multi-patterning cycles.
FDA oversight of fluoropolymer materials in semiconductor fluid systems, EPA emissions rules affecting perfluorinated compound usage in etch processes, and Japan's METI material security framework collectively elevate compliance costs and qualification timelines for consumable vendors. China's SAMR national standards and MIIT localization mandates further bifurcate supply chains between qualified import channels and domestic substitution programs. Stakeholders must monitor regulatory divergence between export control regimes and domestic content requirements as the primary determinant of vendor eligibility and pricing power across regional fab ecosystems.
Market Dynamics
Advanced logic foundries in Taiwan and South Korea are accelerating procurement cycles for EUV-grade consumables as sub-3nm nodes mature, compressing replacement intervals for ceramic slit blades and polyimide chuck pads while elevating purity specifications that disqualify second-tier suppliers.
Growth Catalysts
- EUV Lithography Maturation:Multi-patterning cycles at sub-3nm nodes extend photo mask utilization rates while demanding higher-grade quartz substrates and polymer carriers that resist thermal deformation during extended exposure sequences.
- China MIIT Localization Mandates:Domestic fab buildout under the 14th Five-Year Plan creates captive demand for etch chamber components and CMP pads from qualified local vendors, bypassing import qualification bottlenecks.
- Japan METI Material Security Framework:Strategic stockpiling directives for fluoropolymer resins and high-purity ceramics incentivize regional production capacity expansion and dual-source qualification protocols.
Market Restraints
- Yttria-Stabilized Zirconia Supply Concentration:Kyocera and CoorsTek control over 70% of precision ceramic feedstock for slit blades, creating single-source vulnerability for deposition tool operators.
- REACH Perfluorinated Compound Restrictions:ECHA phase-out timelines for PFOA and PFOS precursors force reformulation of etch chamber cleaning chemistries, extending qualification cycles by 18-24 months.
- Technical Ceiling in Polyimide Thermal Conductivity:Chuck pad materials face hard limits at 400°C continuous operation, constraining plasma etch tool throughput for high-aspect-ratio structures.
Strategic Opportunities
- Vietnam and Malaysia Backend Expansion:Advanced packaging facilities in Ho Chi Minh City and Penang generate incremental demand for wafer carriers and dicing tapes outside traditional front-end clusters.
- India PLI Scheme for Semiconductors:Subsidies for display and logic fabs in Gujarat and Karnataka create first-mover advantage for consumable vendors establishing local blending and finishing operations.
- SiC Power Device Manufacturing:Thermal processing steps for silicon carbide substrates at 1600°C+ require specialized quartzware and graphite susceptors with purity grades distinct from silicon CMOS requirements.
Industry Challenges
- Contamination Control Engineering Talent Scarcity:Fabs in Hsinchu and Pyeongtaek compete for specialists capable of correlating particle counts to consumable surface morphology at sub-50nm resolution.
- Dual-Qualification Burden for China Operations:Vendors must maintain parallel supply chains meeting SAMR GB standards and SEMI international specifications, doubling inventory carrying costs and audit frequencies.
- EUV Mask Blank Defect Metrology Integration:Cleaning cloth suppliers face retrofit requirements to align particle removal protocols with actinic inspection tools at mask shops in Dresden and Yokohama.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumable Parts for Semiconductor Equipment Market |
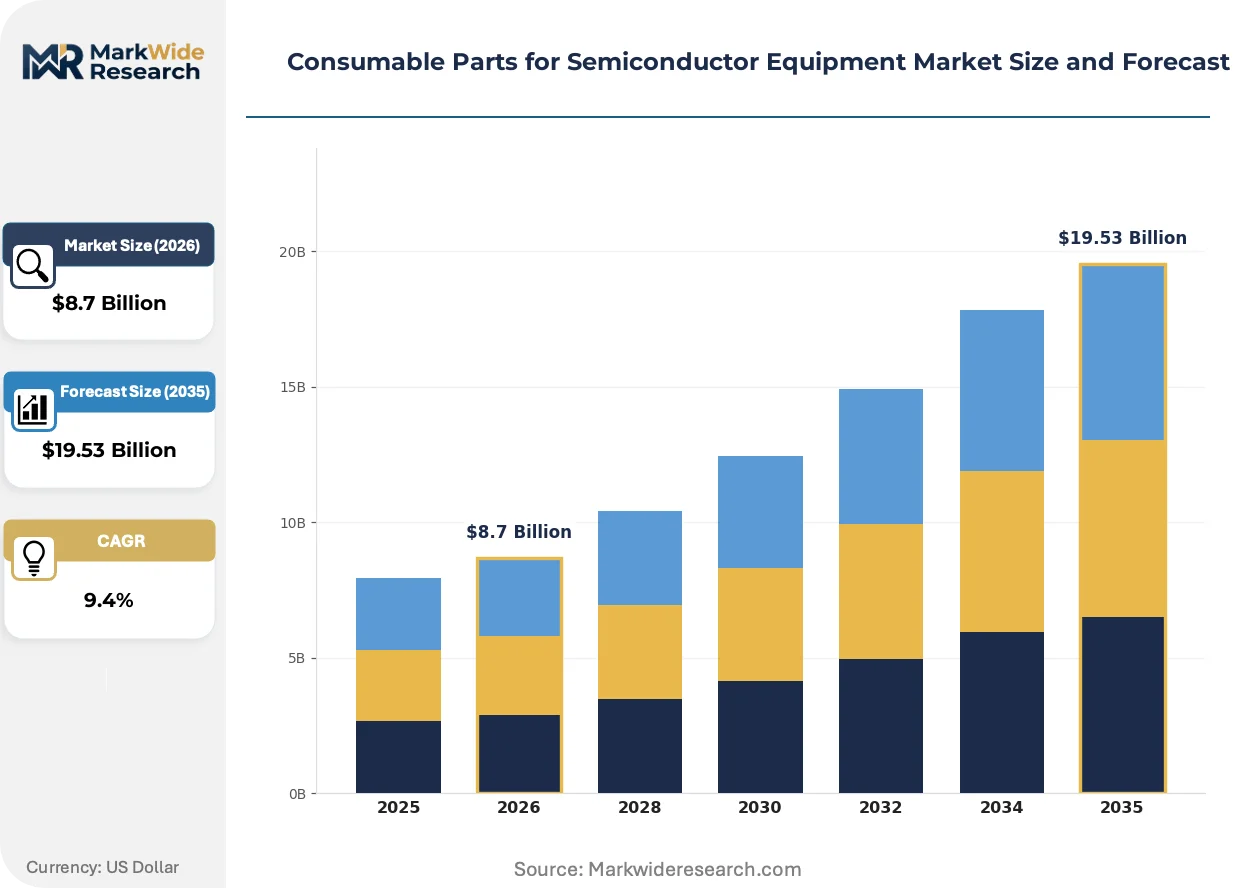
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SLIT BLADES, CHUCK PADS, PHOTO MASKS, WAFER CARIERS, CLEANING CLOTHS Technology: CVD, PVD, ETCHING, CHEMICAL MECHANICAL POLISHING, LITHOGRAPHY Application: Logic Chips, Memory Devices, Power Semiconductors, Sensors, RF Devices End User: Foundries, OSAT Providers, Semiconductor Fabs, Equipment OEMs, IDM Companies |
| Companies Covered | Lam Research, Applied Materials, Entegris, Tokyo Electron, ASML Holding, KLA, Mitsubishi Materials, Kyocera, Ferrotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumable Parts for Semiconductor Equipment Market Trends and Innovations
Process-worn component specifications are bifurcating between legacy node cost optimization and leading-edge purity escalation, forcing suppliers to maintain dual product architectures without cross-contamination.
Silicon carbide-coated graphite susceptors is supplanting pure graphite in CVD and epitaxy applications due to reduced particle generation during thermal cycling. Memory manufacturers in South Korea have adopted SiC-coated platforms for 200mm and 300mm wafer processing over the past 36 months. This material transition is supplanting incumbent graphite suppliers who lack chemical vapor infiltration capabilities, consolidating procurement among ceramic matrix composite specialists.
EPA fluoropolymer emissions rules under the Clean Air Act are tightening reporting thresholds for perfluorinated compound releases from etch and CVD tool exhaust streams. Equipment operators must now quantify consumable-derived emissions from chamber cleaning cycles and fluid delivery system components. Semiconductor facilities in Arizona and Texas are responding by qualifying fluorine-free plasma cleaning chemistries and closed-loop abatement systems that capture consumable degradation byproducts.
Consignment inventory arrangements are displacing traditional purchase-order models for high-volume consumables like CMP pads and cleaning cloths. Foundry operators in Taiwan now require vendors to maintain 4-6 weeks of buffer stock at fab sites, transferring working capital burden upstream while demanding real-time consumption tracking through automated dispensing systems. This inventory model shift is most pronounced at 300mm logic fabs where pad replacement intervals correlate directly to wafer starts rather than calendar time.
Consumable Parts for Semiconductor Equipment Market Segmentation
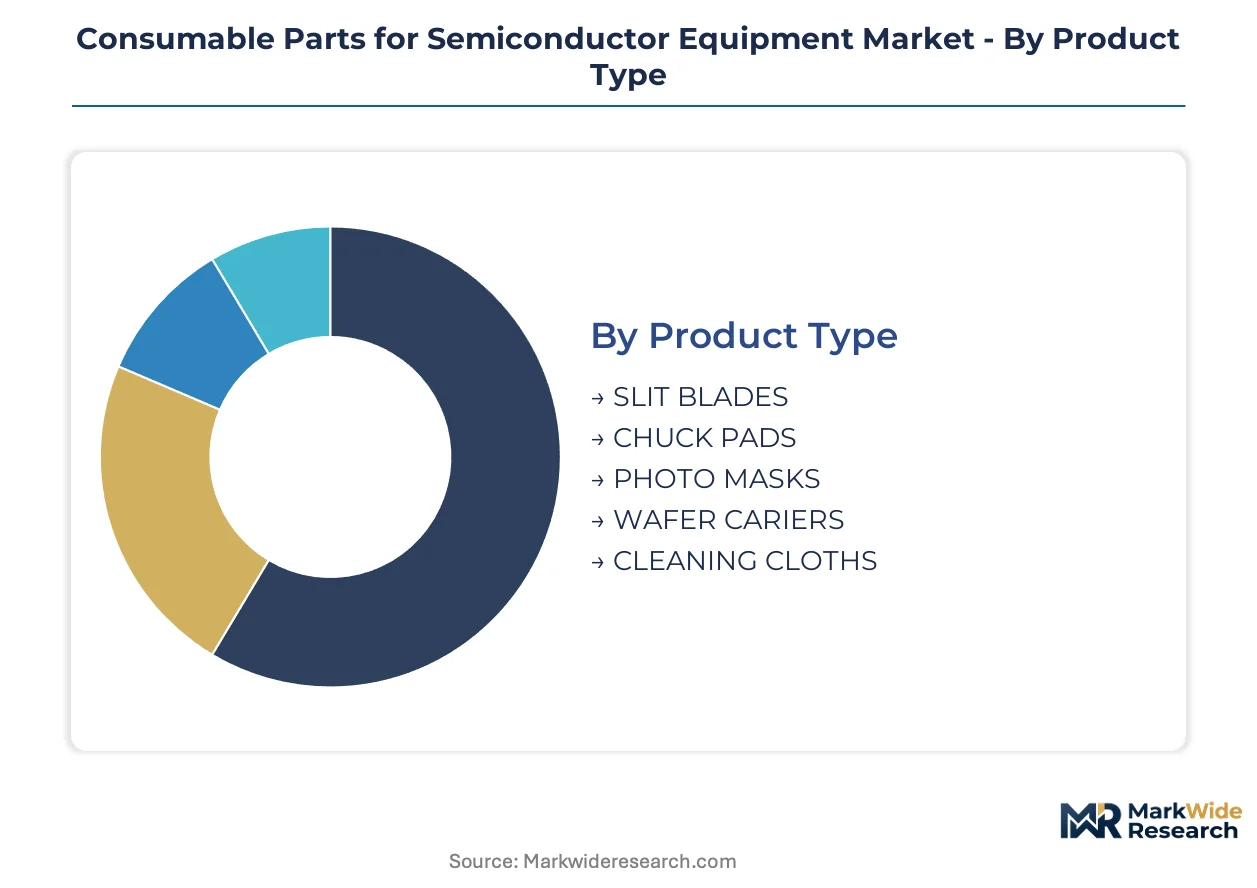
Consumable parts segmentation reveals how purity grades, replacement intervals, and process tool compatibility create distinct procurement categories. Each dimension—product form, deposition technology, chip application, and customer type—carries unique qualification protocols and margin structures that reshape vendor positioning.
Product Type:
Regulatory differentiation separates EUV-grade consumables from legacy node components, with REACH fluoropolymer restrictions and Japan METI material security frameworks imposing divergent purity documentation requirements across ceramic, polymer, and quartz-based product families.
- SLIT BLADES:Yttria-stabilized zirconia ceramic blades maintain precise gas flow boundaries in CVD and etch chambers. Taiwan advanced logic foundries now specify sub-50nm surface roughness for sub-3nm node production, compressing qualified supplier pools to captive ceramic manufacturers.
- CHUCK PADS:Polyimide and ceramic composite pads secure wafers during plasma processing through electrostatic or vacuum clamping mechanisms. South Korea memory fabs drive specifications toward 400°C thermal endurance limits as high-aspect-ratio etch cycles extend.
- PHOTO MASKS:EUV-grade quartz substrates with multilayer reflective coatings for extreme ultraviolet lithography patterning.
- WAFER CARRIERS:Polymer and ceramic transport cassettes engineered for automated material handling systems in 300mm fabs.
- CLEANING CLOTHS:Engineered microfiber and polymer wipes for chamber maintenance and mask blank surface preparation.
Established volume favors SLIT BLADES; emerging adoption favors PHOTO MASKS as EUV multi-patterning proliferates.
Technology:
Cost tier separation distinguishes consumable replacement economics, with lithography consumables commanding premium pricing against high-volume, price-sensitive categories in deposition and planarization processes.
- CVD:Consumables for chemical vapor deposition systems include gas distribution plates, liner tubes, and edge rings exposed to corrosive precursor chemistries. China domestic fab buildout under MIIT localization mandates is redirecting procurement toward qualified local ceramic and graphite suppliers.
- PVD:Sputtering target shields, collimators, and wafer lift pins face replacement cycles tied to film thickness accumulation. Taiwan foundries dominate consumption as advanced metallization layers multiply at sub-3nm nodes.
- ETCHING:Chamber components exposed to fluorinated plasma chemistries including focus rings, baffles, and slit valve doors.
- CHEMICAL MECHANICAL POLISHING:Polyurethane and non-woven polishing pads, conditioning disks, and slurry delivery components.
- LITHOGRAPHY:EUV pellicles, mask blanks, and illumination system optics requiring atomic-scale defect control.
Process maturity favors ETCHING consumables for volume scale; technology transition favors LITHOGRAPHY for margin expansion.
Application:
Customer type fragmentation splits procurement between captive fabs with consignment inventory models and merchant foundries demanding flexible supply terms.
- Logic Chips:Advanced node processors require the most stringent consumable purity grades, with EUV lithography and multi-patterning extending photo mask utilization while elevating defect specifications. Taiwan and South Korea foundries concentrate demand for ceramic slit blades and polyimide chuck pads at sub-3nm geometries.
- Memory Devices:3D NAND and DRAM fabrication drives high-throughput consumption of CMP pads and cleaning cloths. South Korea manufacturers have adopted silicon carbide-coated graphite susceptors for thermal processing steps over the past three years.
- Power Semiconductors:Silicon carbide and gallium nitride device manufacturing requires specialized quartzware and graphite components for 1600°C+ thermal processing.
- Sensors:Image sensor and MEMS fabrication utilizes mid-grade consumables with relaxed purity requirements versus leading-edge logic.
- RF Devices:Compound semiconductor processing for 5G infrastructure and defense applications.
Capacity expansion favors Memory Devices for near-term volume; node migration favors Logic Chips for specification escalation.
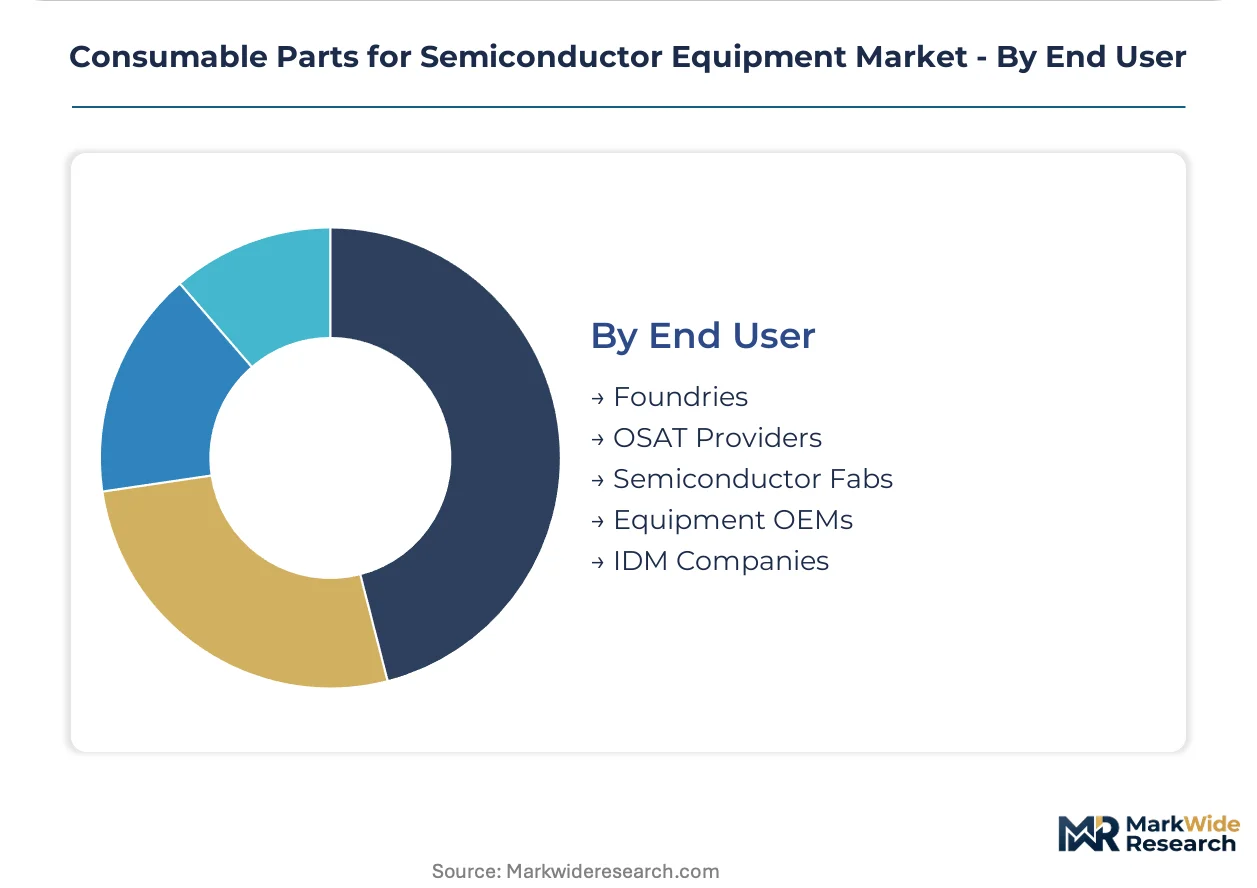
End User:
Supply concentration geometry clusters procurement authority among vertically integrated device manufacturers and dominant merchant foundries, with OSAT and equipment OEM channels serving fragmented secondary demand.
- Foundries:Merchant wafer manufacturers including TSMC, Samsung, and GlobalFoundries drive industry consumable specifications through consolidated procurement power. Taiwan-based operators now mandate 4-6 week consignment inventory buffers at fab sites, transferring working capital burden upstream.
- OSAT Providers:Outsourced semiconductor assembly and test facilities generate demand for wafer carriers, dicing tapes, and packaging-specific consumables. Vietnam and Malaysia backend expansion in Ho Chi Minh City and Penang is creating incremental demand outside traditional front-end clusters.
- Semiconductor Fabs:Captive manufacturing facilities of IDM companies with integrated design and production operations.
- Equipment OEMs:Original equipment manufacturers supplying process tools with initial consumable loads and spare parts packages.
- IDM Companies:Integrated device manufacturers maintaining in-house design and fabrication capabilities.
Procurement scale favors Foundries for specification leadership; geographic diversification favors OSAT Providers for emerging volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Taiwan and South Korea exhibit the lowest price sensitivity as EUV node migration accelerates, while Chinese fabs under localization mandates prioritize cost efficiency in domestic vendor qualification. This demand-elasticity contrast shapes divergent procurement strategies across major fabrication clusters.
United States
Advanced logic and memory fabs in Arizona and Texas drive specification escalation for fluoropolymer fluid system components. EPA Clean Air Act emissions rules tighten reporting thresholds for perfluorinated compound releases from etch and CVD tool exhaust streams. Intel's expansion in Chandler and Samsung's Taylor facility concentrate procurement authority for high-purity consumables.
China
Domestic fab buildout under MIIT localization mandates redirects procurement toward qualified local suppliers of etch chamber components and CMP pads. SAMR national standards and GB certification requirements bifurcate supply chains between import channels and domestic substitution programs. Yangtze Memory Technologies and SMIC in Shanghai and Wuhan anchor demand for ceramic slit blades and polymer wafer carriers.
Japan
Materials security directives from METI incentivize strategic stockpiling of fluoropolymer resins and high-purity ceramics for deposition tools. JIS standards and dual-source qualification protocols elevate compliance costs for consumable vendors serving Tokyo Electron and Shin-Etsu. Osaka and Kyoto industrial corridors concentrate precision ceramic manufacturing for chuck pads and slit blades.
South Korea
Memory manufacturers in Pyeongtaek and Yongin have adopted silicon carbide-coated graphite susceptors for thermal processing steps over the past three years. MFDS oversight of fluoropolymer materials aligns with METI frameworks for regional supply security. Samsung and SK Hynix dominate procurement for EUV-grade photo masks and polymer carriers at sub-3nm geometries.
Taiwan
TSMC's advanced logic foundries in Hsinchu and Tainan compress replacement intervals for ceramic slit blades and polyimide chuck pads while mandating 4-6 week consignment inventory buffers at fab sites. National Development Council initiatives support local consumable vendor qualification alongside SEMI international specifications. The Science Park clusters concentrate the world's most demanding purity specifications for EUV lithography consumables.
Consumable Parts for Semiconductor Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the consumable parts spectrum. Vertically integrated equipment OEMs control premium-tier specifications through captive ceramic manufacturing and contamination control chemistry, while specialized material suppliers compete on thermal uniformity metrics and regional qualification speed. The market structure tiers into three archetypes: integrated equipment vendors with backward integration into consumables, pure-play material specialists with precision engineering capabilities, and regional fabricators serving localization mandates. Dominant competitive moves include capacity expansion in Vietnam and Malaysia for backend packaging consumables, and strategic partnerships between Japanese ceramic manufacturers and Taiwan foundries for EUV-grade component qualification.
Among integrated equipment vendors, Lam Research, Entegris, and Applied Materials occupy positions spanning deposition tool consumables through fluid delivery systems. Lam Research exemplifies the captive manufacturing archetype through in-house ceramic production for critical slit blade specifications. Entegris anchors the contamination control tier with advanced chemistry for fluid delivery systems. Applied Materials represents the broad portfolio approach across CVD, PVD, and etch platform consumables. These three companies illustrate how equipment OEMs leverage installed base relationships to secure consumable replacement revenue streams.
| Leading Market Players |
|---|
| Lam Research |
| Applied Materials |
| Entegris |
| Tokyo Electron |
| ASML Holding |
| KLA |
| Mitsubishi Materials |
| Kyocera |
| Ferrotec |
| Others |
Pricing and Supply Chain Analysis
REACH fluoropolymer compliance and Japan METI material security protocols gate both supplier qualification and price differentiation simultaneously, bifurcating procurement pools between certified premium tiers and unqualified economy alternatives. Taiwan foundries absorb 40-60% price premiums for EUV-grade consumables while Chinese fabs under MIIT localization mandates prioritize cost efficiency in domestic vendor selection.
Pricing Analysis
After-sales consumable replacement revenue drives lifetime value for equipment OEMs, with Lam Research and Entegris capturing recurring revenue through captive ceramic manufacturing and contamination control chemistry. Three-tier pricing structure across EUV-certified, legacy-node, and unqualified economy levels separates Taiwan foundry procurement from Chinese domestic fab sourcing. Cost compression in standard-grade ceramic slit blades intensifies as Kyocera and CoorsTek expand capacity, while photo mask blanks command sustained premiums due to actinic defect metrology integration. Memory manufacturers in South Korea exhibit lowest price sensitivity for thermal processing components; OSAT providers in Vietnam and Malaysia drive hardest bargain on wafer carriers and dicing tapes.
Supply Chain Analysis
Inbound logistics costs through Kaohsiung and Busan ports constrain just-in-time delivery for yttria-stabilized zirconia feedstock, elevating safety stock requirements for deposition tool operators. Supply concentrates in Japan for precision ceramics, Taiwan for EUV-grade quartz substrates, and China for polymer wafer carriers under localization mandates. Raw material dependencies span high-purity alumina from Kyocera's Osaka facilities, fluoropolymer resins subject to METI stockpiling directives, and synthetic quartz for mask blank substrates. Single-source vulnerability in ceramic slit blade supply creates structural risk as Kyocera and CoorsTek control precision feedstock. Distribution runs through consignment inventory models at 300mm logic fabs, with vendors maintaining 4-6 week buffers at Hsinchu and Tainan sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in semiconductor consumables reaches inflection as EUV lithography tool interoperability standardizes qualification protocols across TSMC, Samsung, and Intel ecosystems. This interoperability shift consolidates procurement authority among foundries capable of dictating consumable specifications to captive supplier bases.
For Market Incumbents: Fortify position through backward integration into ceramic matrix composite manufacturing and dual-source qualification protocols under Japan METI frameworks. Entegris-style contamination control chemistry investments defend against emerging Korean material specialists. Capacity addition in Vietnam for backend packaging consumables secures geographic diversification beyond Taiwan and South Korea front-end clusters.
For New Entrants and Emerging Players: SAMR GB certification fast-track unlocks access to Yangtze Memory Technologies and SMIC procurement channels bypassing import qualification bottlenecks. White-space targets center on silicon carbide-coated graphite susceptors for power device manufacturing and fluorine-free plasma cleaning chemistries under EPA emissions rules. Foundry-direct technical partnership model accelerates qualification against distributor-dependent incumbents.
For Investors and Strategic Acquirers: EPA fluoropolymer emissions rulemaking reshapes the acquisition landscape toward abatement-integrated consumable suppliers and closed-loop chemistry platforms. Long-term viability favors ceramic matrix composite specialists with chemical vapor infiltration capabilities over pure graphite incumbents. Signal to monitor: dual-qualification burden metrics for China operations as SAMR and SEMI specification divergence widens.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Ceramic Manufacturing Expansion | Lam Research controls slit blade specifications through in-house yttria-stabilized zirconia production. |
| Consignment Inventory Model Adoption | TSMC transfers working capital burden upstream while demanding real-time consumption tracking. |
| SAMR GB Certification Fast-Track | Domestic Chinese vendors bypass import channels for etch chamber component qualification. |
| Silicon Carbide Coating Capability Buildout | Memory manufacturers in Pyeongtaek adopt SiC-coated platforms for thermal processing. |
| Fluorine-Free Chemistry Platform Launch | Arizona and Texas fabs qualify closed-loop abatement systems under EPA Clean Air Act rules. |
Research Methodology
Cross-validation between equipment OEM procurement disclosures and foundry technical specification documents anchors the qualitative findings in this study. Primary interviews with deposition tool engineers, ceramic manufacturing plant managers, contamination control specialists, and foundry supply chain directors combined with secondary validation through SEMI standards databases, EPA emissions filings, and Japan METI material security directives. Bottom-up consumable unit economics triangulate against top-down fab capacity expansion announcements across the analysis window.
Sensitivity analysis on EUV lithography adoption rates and China localization mandate enforcement intensity frames forecast uncertainty. The analytical framework segments by product type, deposition technology, chip application, and end-user procurement model across the projection horizon. CAGRs derive from replacement interval compression at sub-3nm nodes and consignment inventory penetration rates. Industry-specific inputs include actinic defect metrology integration timelines and fluoropolymer reformulation qualification cycles.
Decision-makers should treat outputs as directional under base assumptions of sustained EUV node migration and stable export control regimes; material deviation would warrant model refresh. Forecasts reflect assumptions regarding REACH phase-out timelines and MIIT localization enforcement. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
4-Inch SiC Laser Annealing Equipment Market
Semiconductor Equipment
Europe Semiconductor Etch Equipment Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
APAC Die Attach Equipment Market
Semiconductor Equipment
Solar Texturing Equipment Market
Semiconductor Equipment
Global Cleanroom Technologies Market
Semiconductor Equipment
OLED Vacuum Evaporation Machine Market
Semiconductor Equipment
Semiconductor Capital Equipment Market
Semiconductor Equipment
Vacuum Ovens Market
Semiconductor Equipment
Semiconductor Lithography Equipment Market
Semiconductor Equipment
150mm Probe Station Market
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Global Semiconductor Etch Equipment Market
Semiconductor Equipment
Semiconductor LPCVD Furnaces Market
Semiconductor Equipment
Global Semiconductor Front-End Equipment Market