
 VXI Test Equipment Market | 2026-2036
VXI Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
VXI Test Equipment Market Analytics
Leasing and project-based financing for automated test systems is rewriting competitive dynamics in the VXI test equipment landscape. National Instruments leverages its software-defined instrumentation platform to sustain recurring revenue from LabVIEW-integrated deployments. Keysight Technologies anchors its position through RF and millimeter-wave measurement specialization for 5G and satellite communications validation.
VXI test equipment comprises modular instrumentation based on the VMEbus Extensions for Instrumentation standard, typically operating with 13-slot mainframes and P1/P2/P3 connector backplanes that enable high-throughput data transfer between embedded controllers and measurement modules. The architecture serves automated test equipment environments requiring rapid reconfiguration for multi-parameter electronics validation. Modular Instrumentation occupies the largest value share as chassis-based systems allow users to mix signal generators, analyzers, and power meters within unified test stations. RF technology segments are expanding fastest as phased array radar and satellite payload testing drive demand for vector signal analysis above 40 GHz.
FCC Part 15 emissions standards and US DoD MOSA mandates shape product development priorities for domestic suppliers, while REACH and RoHS compliance requirements from ECHA constrain material selections for European-bound shipments. The IEEE 1155 VXI specification and ISO/IEC 17025 calibration traceability frameworks further govern interoperability and measurement integrity across international procurement. Stakeholders must evaluate whether to deepen software ecosystems around existing hardware platforms or migrate toward PXIe and LXI architectures that threaten VXI's installed base longevity.
Market Dynamics
The transition from legacy rack-and-stack instrumentation to modular VXI architectures is compressing platform refresh cycles across aerospace and defense test facilities. US DoD MOSA mandates are forcing prime contractors to retire proprietary interfaces in favor of open-standard backplanes.
Growth Catalysts
- US DoD MOSA Compliance Mandates:Defense procurement rules now require modular open systems architecture compatibility for all new automated test equipment, accelerating replacement of legacy GPIB-based systems.
- Millimeter-Wave Validation Demand:Phased array radar and satellite payload testing above 40 GHz requires VXI-based vector signal analysis modules with P3 connector high-speed data pathways.
- Automotive Electronics Clusters:Germany's precision instrumentation investment for electric powertrain and autonomous sensor validation sustains demand for mixed-signal VXI configurations.
Market Restraints
- PXIe Architecture Substitution:PXI Express platforms with PCIe Gen 3 backplanes offer higher data throughput than VXI P2/P3 connectors, capturing share in commercial electronics test.
- Specialized Controller Supply Concentration:Embedded VXI controller manufacturing concentrates among a limited supplier base, creating procurement vulnerability for multi-chassis deployments.
- REACH Material Constraints:ECHA restrictions on lead-based solders and specific flame retardants complicate backplane fabrication for European-bound shipments.
Strategic Opportunities
- Japan Telecommunications Infrastructure:METI investment in 5G-Advanced and 6G R&D creates demand for RF signal generation modules in VXI form factors for protocol validation.
- Software-Defined Instrumentation Convergence:FPGA-based measurement modules with LabVIEW runtime engines enable hardware reuse across multiple test programs without chassis reconfiguration.
- Leasing Model Expansion:Project-based financing for defense test programs allows contractors to access calibrated VXI systems without capital expenditure approval delays.
Industry Challenges
- Legacy System Integration Complexity:VXI chassis must bridge to existing GPIB and LXI instruments through translation modules, extending test station commissioning timelines.
- Calibration Technician Scarcity:ISO/IEC 17025 traceability requirements demand specialized metrology expertise that concentrates among aging workforce cohorts in precision instrumentation hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VXI Test Equipment Market |
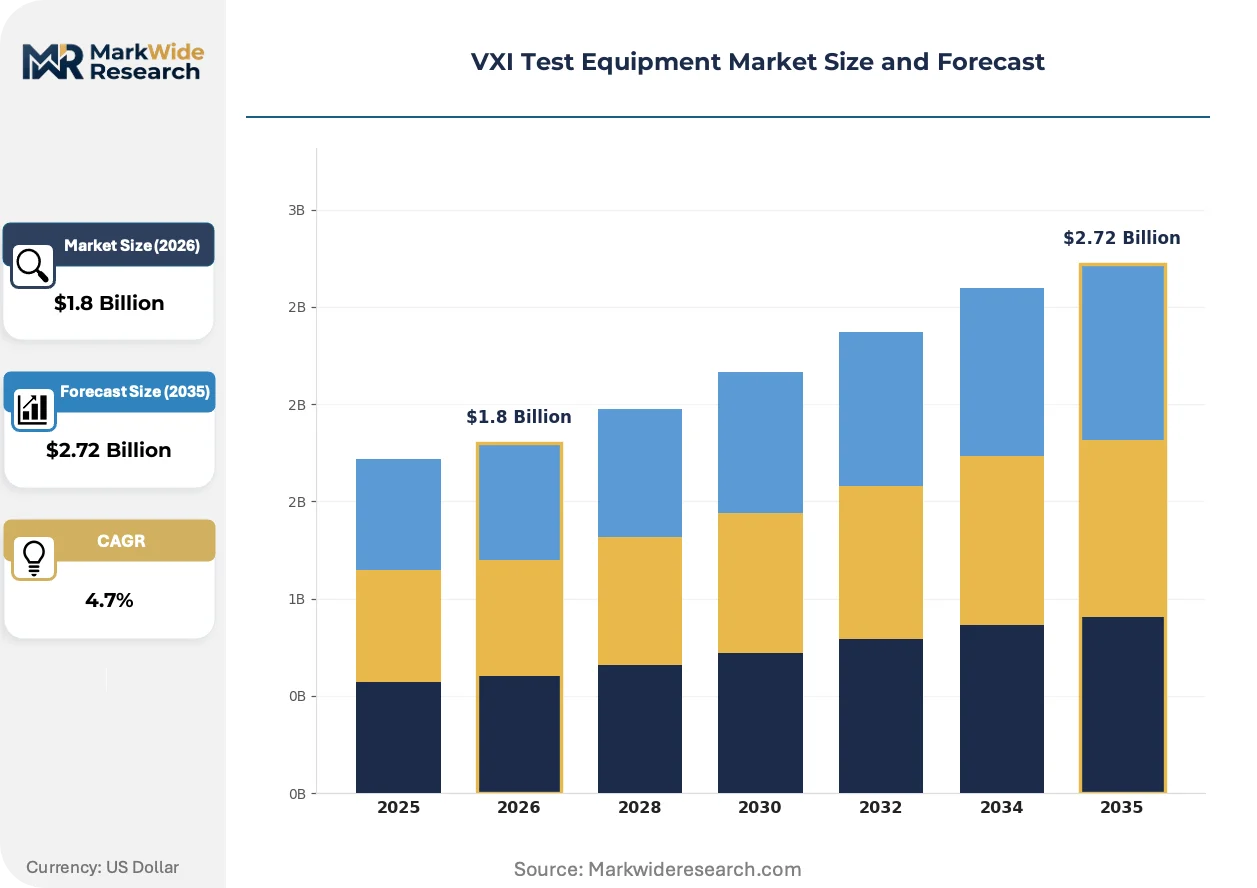
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Instrumentation, Signal Generators, Signal Analyzers, Power Meters End User: Aerospace, Telecommunications, Defense, Automotive Technology: Analog, Digital, RF, Mixed Signal Application: Testing, Measurement, Calibration, Research |
| Companies Covered | National Instruments, Agilent Technologies, C&H Technologies Inc., Giga-tronics Inc., Aeroflex Inc., Kinetic Systems, Interface Technology Inc., Keysight Technologies, Pickering Interfaces Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VXI Test Equipment Market Evolving Landscape
Test equipment architectures are converging around software-defined measurement cores that decouple hardware acquisition from analysis algorithms. This shift is fragmenting traditional vendor lock-in models and accelerating module interoperability standards.
FPGA-based digital signal processing engines embedded directly in VXI measurement modules are rendering obsolete external PC-based analysis workstations for real-time radar pulse characterization. Lockheed Martin and Northrop Grumman test facilities in Texas and California are deploying these configurations for active electronically scanned array validation. The compression of analysis latency from milliseconds to microseconds is eliminating the need for separate digitizer-and-PC architectures in time-critical defense applications.
ECHA REACH Annex XIV authorization requirements for specific phthalates and flame retardants are forcing backplane manufacturers to qualify alternative laminate materials. This regulatory pressure extends qualification timelines for European-market VXI chassis by 8-12 months. German automotive test houses are responding by consolidating procurement with suppliers holding pre-validated material declarations, concentrating supply relationships among RoHS-compliant specialists.
Defense contractors are unbundling hardware acquisition from calibration service contracts, treating measurement traceability as a separately procured subscription. This behavioral shift disrupts traditional bundled pricing models and transfers calibration scheduling risk to third-party metrology service providers. The pattern is most visible in California aerospace clusters, where prime contractors now specify ISO/IEC 17025-accredited calibration intervals independent of original equipment manufacturer service agreements.
VXI Test Equipment Market Segmentation
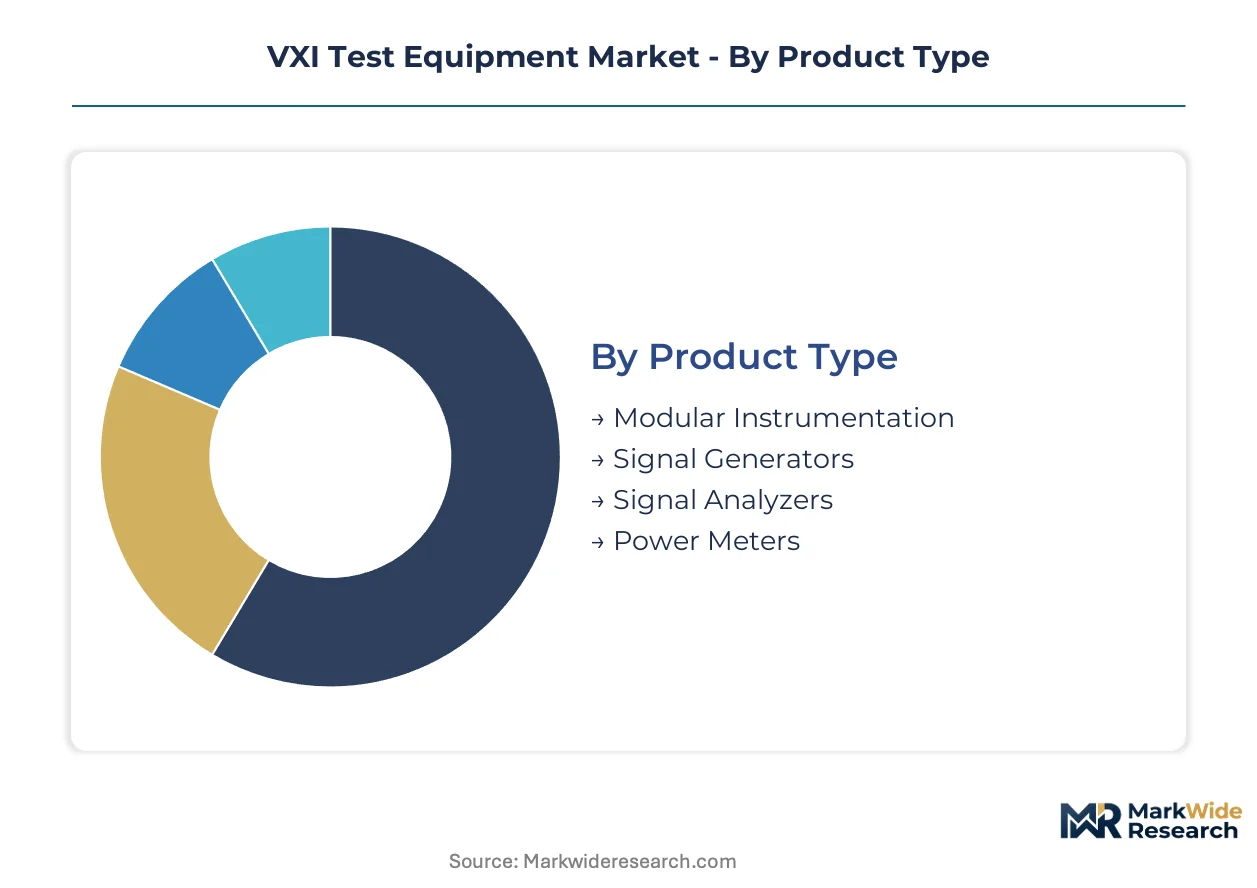
VXI test equipment segmentation reflects how procurement priorities diverge across defense, telecommunications, and automotive validation environments. Understanding these category boundaries clarifies why chassis configurations, module specifications, and software ecosystems vary dramatically by end-use requirements.
Product Type:
Mature chassis-based systems coexist with emerging specialized modules as test programs balance flexibility against measurement precision.
- Modular Instrumentation:Chassis-based systems with 13-slot mainframes and P1/P2/P3 backplanes enable rapid reconfiguration across multi-parameter test sequences. Aerospace contractors in California and Texas concentrate procurement here for automated test equipment supporting phased array radar validation.
- Signal Analyzers:Vector signal analysis modules with P3 connector high-speed data pathways handle millimeter-wave characterization above 40 GHz. Satellite payload testing programs drive concentrated demand for these configurations in defense electronics clusters.
- Signal Generators:RF and microwave sources for stimulus-response testing protocols.
- Power Meters:Precision RF power measurement modules for transmitter verification and amplifier linearity testing.
Modular Instrumentation handles the majority of throughput; Signal Analyzers are gaining share fastest on RF validation demand.
End User:
Cost tier differentiation separates capital-intensive defense programs from volume-sensitive commercial electronics testing.
- Defense:US Department of Defense MOSA compliance mandates drive replacement of legacy GPIB-based systems with open-standard VXI architectures. Prime contractors specify modular instrumentation for automated test equipment supporting platform refresh cycles.
- Aerospace:Lockheed Martin and Northrop Grumman facilities deploy FPGA-based measurement modules for real-time radar pulse characterization in active electronically scanned array validation.
- Automotive:Germany's precision instrumentation investment sustains demand for electric powertrain and autonomous sensor validation using mixed-signal VXI configurations.
- Telecommunications:METI-funded 5G-Advanced and 6G R&D programs in Japan create demand for protocol validation modules.
Defense commands the premium tier on MOSA-driven refresh cycles; Telecommunications shows the steepest expansion trajectory on next-generation infrastructure investment.
Technology:
Application requirements dictate whether analog precision, digital throughput, or RF bandwidth takes priority in module selection.
- RF:Phased array radar and satellite communications validation above 40 GHz demands vector signal analysis with high-speed P3 data pathways. This segment concentrates in defense electronics test facilities requiring real-time spectral characterization.
- Mixed Signal:Combined analog-digital measurement capability serves automotive power electronics and telecommunications baseband verification. German test houses favor these configurations for electric drivetrain validation.
- Analog:Precision voltage and current measurement for foundational electronics characterization.
- Digital:High-throughput logic analysis and protocol testing for digital subsystem verification.
RF technology carries the margin premium; Mixed Signal is climbing fastest on automotive electrification demand.
Application:
Customer type segmentation separates production-line testing from laboratory research and metrology-grade calibration workflows.
- Testing:Automated test equipment environments for production validation and incoming inspection. Defense contractors deploy these configurations for high-volume electronics screening in Texas and California facilities.
- Calibration:ISO/IEC 17025 traceability requirements drive demand for metrology-grade modules with accredited measurement uncertainty specifications. California aerospace clusters now unbundle calibration service contracts from hardware acquisition.
- Measurement:General-purpose instrumentation for R&D and engineering characterization.
- Research:Experimental configurations for next-generation technology development including 6G waveform prototyping.
Testing absorbs the largest equipment volume; Calibration is expanding most quickly on outcome-based service model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The VXI test equipment trade flows reflect concentrated defense electronics procurement in the United States against precision instrumentation exports from Germany and Japan. Import dependency for embedded controllers creates supply vulnerability for multi-chassis deployments in regions lacking domestic backplane fabrication.
United States
Defense electronics clusters in California and Texas drive automated test equipment procurement as prime contractors execute platform refresh cycles. FCC Part 15 emissions standards and US DoD MOSA mandates shape product development priorities for domestic suppliers. Lockheed Martin and Northrop Grumman facilities in Texas deploy FPGA-based measurement modules for real-time radar pulse characterization.
Germany
Precision instrumentation investment sustains demand for electric powertrain and autonomous sensor validation using mixed-signal VXI configurations. ECHA REACH and RoHS compliance requirements constrain material selections for backplane fabrication bound for European markets. Automotive test houses in Bavaria consolidate procurement with suppliers holding pre-validated material declarations.
Japan
METI-funded 5G-Advanced and 6G R&D programs create demand for RF signal generation modules in VXI form factors for protocol validation. JIS standards govern interoperability specifications for telecommunications infrastructure deployment. Tokyo-area electronics manufacturers concentrate procurement for next-generation wireless validation systems.
United Kingdom
Aerospace and defense electronics supply chains sustain demand for modular test architectures supporting satellite payload verification. UK Ministry of Defence procurement guidelines emphasize open systems architecture compatibility for automated test equipment. Southeast England defense electronics clusters source VXI chassis for phased array radar validation programs.
South Korea
Semiconductor and telecommunications equipment manufacturers invest in RF validation systems for 5G baseband and millimeter-wave component testing. MFDS regulatory frameworks influence calibration traceability requirements for precision instrumentation imports. Seoul Capital Area electronics clusters deploy mixed-signal configurations for consumer device production testing.
VXI Test Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain supplying measurement modules and backplane assemblies. The vendor base separates between chassis manufacturers with embedded controller capabilities and module specialists focused on RF, mixed-signal, or digital instrumentation. Three archetypes dominate: full-stack system integrators, RF measurement specialists, and modular interface providers. Competitive moves concentrate on software ecosystem deepening and strategic partnerships bridging legacy GPIB instrumentation to open-standard backplanes.
Among US-based instrumentation platforms, National Instruments and Keysight Technologies occupy positions spanning software-defined measurement ecosystems and RF specialization respectively. Pickering Interfaces Ltd. represents the modular switching and simulation archetype within European supply chains. These three anchors illustrate how competitive positioning fragments across software integration, millimeter-wave measurement, and signal routing domains.
| Leading Market Players |
|---|
| National Instruments |
| Agilent Technologies |
| C&H Technologies Inc. |
| Giga-tronics Inc. |
| Aeroflex Inc. |
| Kinetic Systems |
| Interface Technology Inc. |
| Keysight Technologies |
| Pickering Interfaces Ltd. |
| Others |
Value Network & Pricing Analysis
Undercapacity in embedded VXI controller fabrication across North American and European facilities is compressing supplier lead times and hardening pricing posture for multi-chassis defense deployments. This utilization squeeze simultaneously elevates procurement premiums for prime contractors and accelerates qualification timelines for alternative backplane suppliers seeking MOSA-compliant certification.
Pricing Analysis
Industrial OEM buyers anchor a contract-based pricing structure where chassis and module procurement bundles calibration service subscriptions as separately negotiated line items. Price differentiation rests on ISO/IEC 17025 certification tier and volume scale, with defense primes absorbing premium positioning against automotive test houses driving standard-tier negotiations. Pricing pressure stems from PXIe architecture substitution in commercial electronics validation, compressing margins in non-defense segments. Automotive OEMs in Germany exhibit highest price sensitivity due to REACH compliance cost pass-through, while US aerospace contractors demonstrate lowest sensitivity given MOSA mandate urgency and capital availability.
Supply Chain Analysis
Extended payment terms from prime contractors are forcing backplane manufacturers to utilize supply-chain finance facilities, tightening working capital for mid-tier module suppliers. Geographic concentration centers on the United States for embedded controller design, Germany for precision backplane fabrication, and Japan for high-frequency connector assemblies. Raw material dependencies include specialized laminate substrates, lead-free solder alloys, and RF-grade ceramic substrates. Single-source vulnerability concentrates in P3 connector supply for 40+ GHz applications. Distribution runs through authorized instrumentation distributors serving defense electronics clusters with value-added configuration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VXI test equipment market represents a compelling service-attach opportunity as calibration-as-a-subscription revenue layers expand faster than hardware replacement cycles, particularly among California aerospace clusters unbundling traceability contracts from original equipment procurement.
For Market Incumbents: Pre-empt PXIe substitution threat by deepening FPGA-based module ecosystems that enable hardware reuse across multiple test programs without chassis reconfiguration. Fortify position through backward integration into embedded controller design to reduce procurement vulnerability from concentrated supplier bases. Prioritize qualification of REACH-compliant laminate materials to defend European market access against regulatory displacement. For New Entrants and Emerging Players: South Korean semiconductor test facilities present underpenetrated white-space for mixed-signal VXI configurations serving 5G baseband validation. Japan's METI-funded 6G R&D programs offer secondary entry point for RF signal generation modules in protocol development applications. Pursue leasing-model partnerships with defense contractors to bypass capital expenditure approval barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among module specialists with pre-qualified material declarations and ISO/IEC 17025-accredited calibration service networks. Long-term viability favors acquisition targets holding MOSA-compliant certification and established relationships with Texas and California defense electronics clusters. Monitor embedded controller supply concentration as inflection indicator for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Instrumentation Convergence | FPGA-based measurement modules with LabVIEW runtime engines enable chassis reconfiguration elimination. |
| REACH-Compliant Material Qualification | Alternative laminate validation extends European market access for backplane manufacturers by 8-12 months. |
| Calibration-as-a-Subscription Unbundling | Third-party metrology service providers assume scheduling risk from prime contractors in California clusters. |
| Leasing Model Expansion | Project-based financing eliminates capital expenditure approval delays for defense test program access. |
| PXIe Bridge Module Development | Translation modules extend VXI chassis relevance against higher-throughput competing architectures. |
Research Methodology
Cross-validation between primary interviews with test engineering directors and secondary regulatory filings anchors the qualitative findings in this study. Stakeholder consultations spanned aerospace procurement managers, automotive validation engineers, metrology service providers, and embedded controller manufacturing leads. Secondary sources included US DoD procurement databases, ECHA REACH substance restriction updates, METI R&D program disclosures, and ISO/IEC 17025 accreditation registries. Bottom-up module shipment analysis triangulated against top-down defense electronics spending patterns.
Calibration against historical platform refresh cycles and MOSA mandate implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user, technology, and application with regional regulatory cluster overlays. CAGRs derived from weighted average of equipment replacement velocity and service revenue attachment rates. Industry-specific inputs encompassed phased array radar deployment schedules and automotive electrification test protocol evolution.
Practitioners should monitor embedded controller supply concentration and REACH authorization timeline extensions for early signals of forecast deviation. The analysis reflects assumptions regarding MOSA compliance adherence and defense electronics spending continuity. Macroeconomic contraction, regulatory acceleration, or architectural substitution breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Voltage Calibrator Market
Test and Measurement
Radiography Test Equipment Market
Test and Measurement
Tube Tester Market
Test and Measurement
Global Non-Destructive Testing and Inspection Market
Test and Measurement
Ground Resistance Testers Market
Test and Measurement
Asia-Pacific Semiconductor Metrology and Inspection Market
Test and Measurement
Semiconductor Metrology and Inspection Equipment Market
Test and Measurement
Global Laser Tracker Market
Test and Measurement
Power Electronics GaN and SiC Device Reliability Test Systems Market
Test and Measurement
Data Acquisition Equipment Market
Test and Measurement
Failure Analysis Market
Test and Measurement
Oscilloscope Market
Test and Measurement
Resonant Testing Machines Market
Test and Measurement
EMC Testing Market
Test and Measurement
Anechoic Chamber Market
Test and Measurement
Global Nondestructive Testing Equipment Market