

Power Electronics GaN and SiC Device Reliability Test Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Power Electronics GaN and SiC Device Reliability Test Systems Market Insights
The EU Green Deal is decoupling legacy silicon qualification timelines from next-generation power electronics roadmaps, forcing automotive and renewable energy buyers to retest GaN and SiC devices under accelerated stress protocols. Keysight Technologies leverages its RF and power semiconductor instrumentation heritage to anchor high-volume test cell deployments for EV power modules. Teradyne competes through system-level integration that extends from wafer-level probing to final module burn-in, sustaining margins across the qualification chain.
Power Electronics GaN and SiC Device Reliability Test Systems comprise specialized environmental and electrical stress equipment designed to validate device lifetimes under accelerated aging conditions, typically operating at junction temperatures exceeding 175°C for SiC and 200°C for GaN during high temperature operating life tests. These systems subject power semiconductors to thermal cycling, power cycling, and humidity bias to predict field failure modes in traction inverters and solar converters. Gallium Nitride test cells are capturing disproportionate capital allocation as RF and EV charger segments drive faster qualification cycles than established Silicon Carbide lines. Thermal Cycling and Power Cycling methods dominate the method mix, with Power Cycling specifically commanding premium pricing due to its direct correlation to automotive inverter reliability.
FDA medical device power supply regulations, EPA emissions-linked manufacturing standards, and NHTSA EV safety protocols collectively shape test stringency requirements for power modules entering regulated end markets. EMA and REACH frameworks in Europe add chemical substance compliance layers to test system materials and coolant chemistries. Stakeholders must monitor how automotive OEMs consolidate their approved supplier lists around test houses capable of dual GaN-SiC qualification under unified thermal modeling standards.
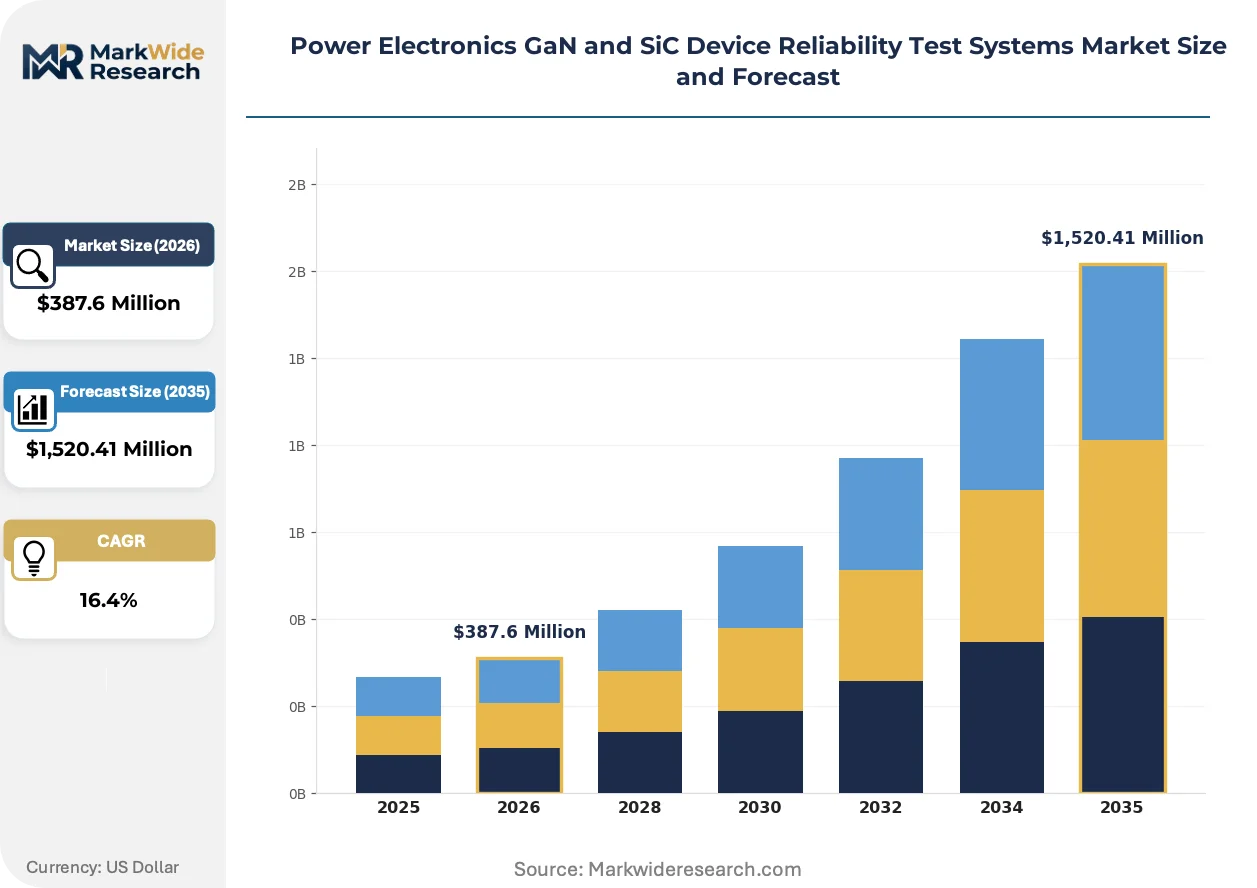
Market Dynamics
Automotive OEMs are consolidating their approved supplier lists around test houses capable of dual GaN-SiC qualification under unified thermal modeling standards, compressing the vendor landscape and raising capital barriers for new entrants.
Growth Catalysts
- EU Green Deal industrial emissions benchmarks:European semiconductor fabs must adopt stricter reliability verification protocols, expanding test system deployments across Germany, France, and the Netherlands.
- Traction inverter module validation clusters:Dense concentrations of automotive OEMs and tier-1 suppliers in southern Germany are driving concentrated demand for high-throughput power cycling equipment.
- Wide-bandgap semiconductor roadmaps:Electric vehicle powertrain programs are extending qualification protocols beyond legacy silicon timelines, creating sustained test capacity expansion.
Market Restraints
- Specialized thermal chamber supply concentration:Precision environmental simulation equipment relies on a limited base of German and Japanese component suppliers, creating input bottlenecks.
- REACH chemical substance compliance:Test system manufacturers face reformulation costs for coolants and thermal interface materials under ECHA restrictions.
- Accelerated stress protocol technical limitations:Junction temperature requirements exceeding 200°C for GaN HTOL testing exceed conventional silicon-based equipment design envelopes.
Strategic Opportunities
- RF and EV charger GaN segments:Faster qualification cycles in telecommunications infrastructure and DC fast charging create capacity expansion opportunities outside automotive.
- Unified thermal modeling standards:Test houses developing dual GaN-SiC qualification capabilities can capture consolidated procurement from automotive OEMs reducing vendor counts.
- India PLI scheme for semiconductor manufacturing:Domestic fab construction is creating demand for localized reliability verification infrastructure as the country builds compound semiconductor capacity.
Industry Challenges
- Power electronics reliability engineering talent scarcity:The intersection of wide-bandgap device physics and accelerated life test methodology requires specialists in short supply across Europe and North America.
- Multi-standard certification timeline compression:Simultaneous compliance with NHTSA EV safety protocols, EPA emissions-linked manufacturing standards, and FDA medical device power supply regulations strains test house scheduling.
- Legacy silicon test equipment retrofit complexity:Existing installed bases require substantial thermal and electrical subsystem reconfiguration to handle GaN's higher switching frequencies and SiC's elevated voltage ratings.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Electronics GaN and SiC Device Reliability Test Systems Market Trends and Innovations
Test system architecture is fragmenting between high-volume automotive production lines and flexible R&D validation cells, with equipment vendors pursuing divergent design philosophies to serve these distinct buyer segments.
Power cycling test hardware is modularizing around swappable thermal chuck and electrical load subsystems. Tier-1 automotive suppliers in Germany are deploying these reconfigurable cells to switch between SiC MOSFET and GaN HEMT qualification within single shift cycles. This architecture is compressing capital deployment timelines by allowing shared infrastructure across multiple device roadmaps rather than dedicated single-technology lines.
The EU Green Deal's F-Gas Regulation is phasing down fluorinated greenhouse gases used in conventional thermal chamber cooling systems. European test equipment manufacturers are retrofitting environmental simulation units with natural refrigerant alternatives or solid-state thermoelectric cooling. Automotive inverter module qualification facilities in Stuttgart and Munich are absorbing these upgrade costs ahead of mandated deadlines to maintain uninterrupted production schedules.
Buyer concentration among automotive OEMs is forcing test houses toward long-term capacity reservation contracts with penalty clauses for throughput shortfalls. Tier-1 suppliers are responding by unbundling after-sales calibration and maintenance services into separate multi-year agreements. This shift is most pronounced in Germany's Baden-Württemberg and Bavaria regions, where dense supplier clusters compete for validation contracts from Mercedes-Benz, BMW, and Volkswagen powertrain divisions.
Power Electronics GaN and SiC Device Reliability Test Systems Market Segmentation
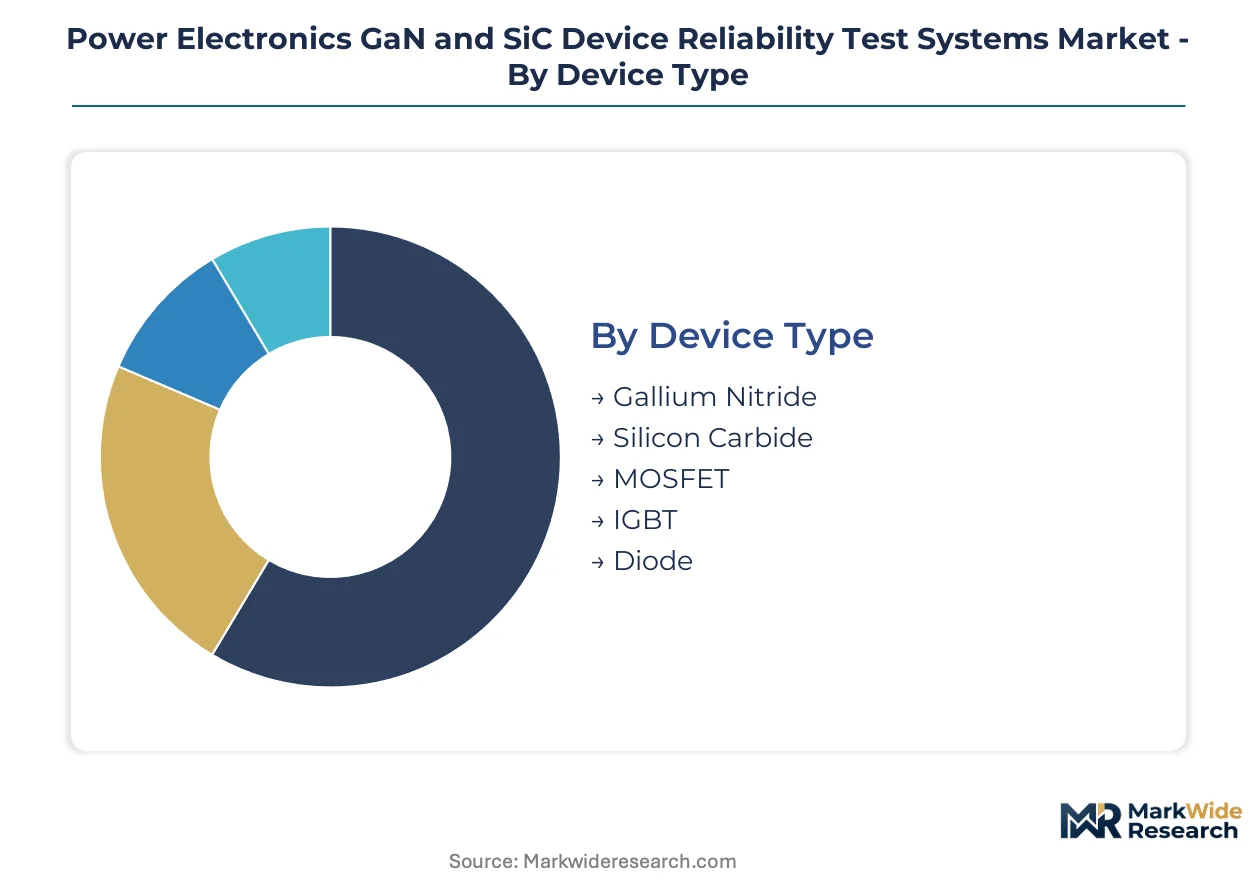
Segmentation in power electronics reliability testing reveals how capital deployment priorities diverge across device physics, stress methodologies, and end-market qualification requirements. Test houses configure their equipment portfolios around specific junction temperature thresholds and cycling profiles demanded by automotive and renewable energy buyers.
Device Type:
Capital intensity varies sharply across wide-bandgap technologies, with thermal chamber specifications and electrical load ratings driving equipment cost tiers.
- Gallium Nitride:GaN HEMT qualification demands test cells capable of sustaining junction temperatures above 200°C during HTOL protocols while managing MHz-range switching transient capture. RF infrastructure and EV charger manufacturers in Germany and Japan are absorbing premium pricing for accelerated cycling capacity.
- Silicon Carbide:SiC MOSFET testing requires elevated voltage ratings beyond 1.2kV and specialized thermal management for 175°C baseline operating life validation. Stuttgart-based automotive inverter module clusters are concentrating procurement for traction powertrain qualification.
- MOSFET:Legacy silicon MOSFET test infrastructure supports retrofit applications with moderate thermal envelope extensions.
- IGBT:Insulated gate bipolar transistor reliability verification maintains steady demand from industrial drive manufacturers.
- Diode:Freewheeling diode stress testing occupies lower capital tiers within mixed-technology qualification lines.
Silicon Carbide absorbs the bulk of installed capacity; Gallium Nitride is expanding most quickly.
Test Method:
Method selection tracks directly to field failure mode correlation, with automotive OEMs prioritizing stress protocols that replicate inverter operating conditions.
- Power Cycling:Active power injection creates thermal gradients mimicking electric vehicle acceleration-deceleration profiles, with cycle counts exceeding 100,000 for automotive qualification. German tier-1 suppliers command premium pricing for high-throughput cells capable of parallel multi-device testing.
- Thermal Cycling:Passive temperature ramping between -40°C and 175°C validates package integrity and solder joint reliability under climatic stress. Renewable energy inverter manufacturers specify extended dwell periods for solar converter applications.
- High Temperature Operating Life:Sustained bias at maximum rated junction temperature accelerates intrinsic degradation mechanisms.
- Electrical Overstress:Surge and transient injection tests boundary conditions for avalanche and short-circuit ruggedness.
- Temperature Humidity Bias:Combined environmental stress exposes moisture ingress vulnerabilities in power module encapsulation.
Power Cycling claims the dominant share of automotive-directed capital; Thermal Cycling maintains broadest cross-industry deployment.
Application:
End-market qualification timelines compress procurement decisions, with EV powertrain validation demanding fastest throughput expansion.
- Electric Vehicles:Traction inverter module testing dominates volume allocation, with 800V architecture migration requiring recalibrated stress profiles. Southern Germany's OEM supplier clusters are consolidating dual GaN-SiC qualification capacity.
- Renewable Energy Systems:Solar and wind converter reliability programs emphasize 25-year lifetime prediction through extended thermal cycling protocols.
- Aerospace:Radiation-hardened and high-altitude specifications add environmental simulation complexity.
- Telecom Infrastructure:5G base station power supply qualification drives GaN-specific HTOL capacity.
- Industrial Drives:Motor control module testing maintains steady replacement demand for aging silicon IGBT lines.
Electric Vehicles command the steepest capital allocation trajectory; Renewable Energy Systems sustain the most predictable long-term capacity planning.
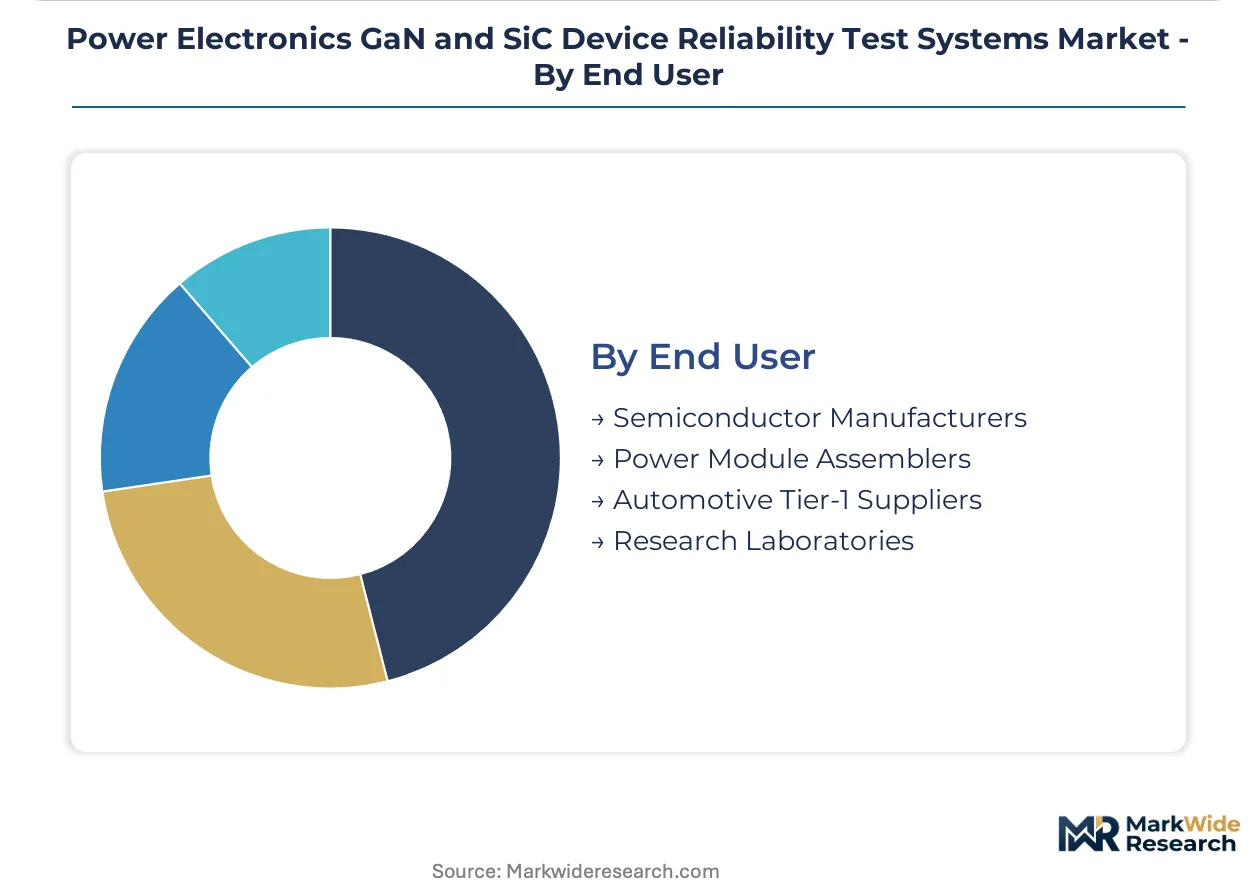
End User:
Buyer sophistication determines service bundling preferences, with integrated suppliers seeking unified thermal modeling across device technologies.
- Automotive Tier-1 Suppliers:Continental, Bosch, and ZF-grade powertrain divisions require test houses capable of dual GaN-SiC qualification under consolidated procurement contracts with throughput penalty clauses.
- Semiconductor Manufacturers:Foundry and IDM reliability engineering groups maintain captive test capacity for process development feedback.
- Power Module Assemblers:Packaging specialists concentrate on solder fatigue and wire bond lift validation.
- Research Laboratories:Fraunhofer and university-affiliated centers access public funding for next-generation stress methodology development.
Automotive Tier-1 Suppliers concentrate procurement volume; Semiconductor Manufacturers retain highest captive capacity ratios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment production clusters in Germany and Japan supply test systems to consumption centers concentrated in automotive manufacturing corridors across southern Germany, Detroit, and Seoul. The geographic mismatch between fabrication and qualification demand shapes capital deployment timelines and service network density.
Germany
Automotive OEM powertrain divisions at Mercedes-Benz, BMW, and Volkswagen drive concentrated demand for dual GaN-SiC qualification capacity. The EU Green Deal's F-Gas Regulation mandates thermal chamber cooling retrofits by 2030, accelerating equipment upgrade cycles. Stuttgart and Munich host dense validation clusters where tier-1 suppliers compete for traction inverter module contracts.
United States
NHTSA EV safety protocols and EPA emissions-linked manufacturing standards impose multi-layered compliance burdens on power module suppliers. The Inflation Reduction Act's domestic content provisions incentivize localized test infrastructure for battery and inverter supply chains. Michigan and Tennessee automotive corridors are absorbing capital for 800V architecture qualification programs.
China
MIIT industrial policy targets compound semiconductor self-sufficiency, expanding captive reliability verification capacity at state-backed foundries. Dual carbon goals accelerate SiC deployment in renewable energy inverters and rail traction systems. Yangtze River Delta fabs in Shanghai and Wuxi are commissioning high-throughput power cycling cells for EV powertrain exports.
Japan
METI's semiconductor strategy prioritizes wide-bandgap device commercialization through public-private R&D consortia. JIS standards for automotive power modules exceed baseline IEC requirements, creating premium test specifications. Nagoya and Kyoto industrial zones concentrate equipment vendors serving Toyota and Honda electrification roadmaps.
South Korea
Hyundai-Kia's vertical integration into power semiconductor packaging drives captive test capacity expansion. The national semiconductor regulator enforces reliability benchmarks aligned with AEC-Q101 automotive standards. Seoul Capital Area and Busan-Ulsan corridors are consolidating GaN qualification for 5G telecom infrastructure exports.
Power Electronics GaN and SiC Device Reliability Test Systems Market Competitive Landscape
The competitive structure tilts toward diversified instrumentation conglomerates with RF and power semiconductor heritage. Tier-1 automotive suppliers compress vendor lists around test houses capable of unified thermal modeling across device technologies. Three archetypes dominate: integrated test system manufacturers, specialized environmental simulation equipment builders, and third-party validation service providers. Consolidation pressure manifests through long-term capacity reservation contracts and bundled after-sales service agreements.
Among diversified test equipment manufacturers, Advantest, Teradyne, and Keysight Technologies exemplify scale-driven positions anchored in semiconductor instrumentation heritage. These Japanese and US-based entities occupy positions spanning wafer-level probing through final module burn-in. Their geographic distribution reflects historical concentrations in Aichi Prefecture industrial corridors and Silicon Valley instrumentation clusters. Each represents an archetype of system-level integration rather than point-solution specialization.
| Leading Market Players |
|---|
| Advantest |
| Teradyne |
| Keysight Technologies |
| National Instruments |
| Cohu |
| Chroma ATE |
| DEKRA |
| SGS |
| UL Solutions |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's F-Gas Regulation gates qualified supply and premium-tier pricing access for thermal chamber cooling systems, forcing test equipment manufacturers toward natural refrigerant retrofits or solid-state alternatives that command 15-25% capital premiums over conventional fluorinated gas units.
Pricing Analysis
Throughput-based pricing anchors test system valuation, with automotive tier-1 suppliers contracting for guaranteed cycle counts and uptime penalties rather than capital purchase. Pricing stratifies across automotive-grade AEC-Q101 certification tiers, RF infrastructure qualification levels, and industrial drive validation standards, with cost compression in legacy silicon retrofit lines intensifying due to surplus equipment availability. Semiconductor foundries exhibit lowest price sensitivity given captive reliability engineering requirements, while third-party test houses face margin pressure from consolidated procurement contracts.
Supply Chain Analysis
Freight costs for precision thermal chambers and high-voltage electrical load subsystems amplify total landed costs by 8-12% for cross-continental shipments from Germany and Japan to North American automotive corridors. Component sourcing draws from specialized German and Japanese suppliers for environmental simulation equipment, with silicon carbide substrate availability and precision thermocouple arrays representing critical input dependencies. Single-source vulnerability concentrates in cryogenic cooling compressor units. Distribution runs through direct OEM relationships for high-volume automotive qualification lines and regional equipment distributors serving R&D validation cells.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wide-bandgap semiconductor qualification is displacing legacy silicon test infrastructure, with GaN HEMT and SiC MOSFET roadmaps forcing equipment architecture redesigns that favor vendors with RF and power semiconductor instrumentation heritage.
For Market Incumbents: Deepen backward integration into thermal chuck and electrical load subsystem manufacturing to defend margins against modular equipment competitors. Secure long-term capacity reservation contracts with penalty structures from automotive OEMs consolidating approved supplier lists. Invest in dual GaN-SiC qualification capability under unified thermal modeling standards to capture procurement consolidation.
For New Entrants and Emerging Players: Third-party validation service providers represent the most penetrable channel for equipment placement, as test houses unbundle after-sales calibration and maintenance into separate multi-year agreements. Target India's PLI scheme for semiconductor manufacturing, where domestic fab construction creates demand for localized reliability verification infrastructure without entrenched incumbent relationships. Position around flexible R&D validation cell architectures rather than high-volume automotive production lines.
For Investors and Strategic Acquirers: Automotive OEM dual GaN-SiC supplier list consolidation is the leading indicator that captive test capacity ratios will shift toward outsourced validation, extending the third-party test house growth window. Focus acquisition screening on environmental simulation equipment builders with natural refrigerant thermal chamber portfolios aligned with EU F-Gas Regulation deadlines. Monitor REACH chemical substance compliance costs as a margin inflection signal for coolant and thermal interface material reformulation.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual GaN-SiC Qualification Capability | Captures consolidated procurement from automotive OEMs reducing vendor counts under unified thermal modeling standards. |
| Natural Refrigerant Thermal Chamber Retrofit | Maintains EU market access ahead of F-Gas Regulation mandated deadlines without production schedule interruption. |
| Modular Power Cycling Cell Architecture | Enables tier-1 suppliers to switch between SiC MOSFET and GaN HEMT qualification within single shift cycles. |
| Long-term Capacity Reservation Contracts | Locks in throughput commitments with penalty clauses from Mercedes-Benz, BMW, and Volkswagen powertrain divisions. |
| India PLI Scheme Localization | Positions equipment vendors for domestic fab reliability verification infrastructure as compound semiconductor capacity builds. |
Research Methodology
Multi-period observation of automotive powertrain electrification roadmaps, wide-bandgap semiconductor foundry capex cycles, and thermal chamber equipment order backlogs anchored the trend analysis, supplemented by interviews with reliability engineering directors at tier-1 automotive suppliers, test house operations managers, semiconductor foundry process integration leads, and thermal simulation software specialists. Secondary validation drew from SEC equipment manufacturer filings, EU ECHA regulatory databases, MIIT semiconductor policy announcements, and automotive OEM supplier quality manuals. Bottom-up test cell deployment counts triangulated against top-down wide-bandgap device market projections.
Segment-weighting across device type, test method, application, and end user dimensions informed value allocation modeling throughout the projection horizon. Power cycling and thermal cycling method shares were calibrated against automotive inverter module validation cluster density in southern Germany. Electric vehicle traction powertrain application weights tracked 800V architecture migration timelines. CAGRs derived from equipment replacement cycles for legacy silicon retrofit limitations and greenfield wide-bandgap capacity expansion rates.
Caveats apply where REACH chemical substance compliance timelines, NHTSA EV safety protocol revisions, or MIIT industrial policy shifts could materially shift the outlook for test system demand. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.