
 Tube Tester Market | 2026-2036
Tube Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Tube Tester Market Analytics
Hobbyist collectors of vintage audio equipment is redrawing demand patterns that manufacturers once dominated. Curtiss-Wright leverages its aerospace pedigree to sustain defense-sector contracts for high-reliability tube testing systems. Vacuum Instrument Corp anchors the vacuum tube technology segment through specialized equipment for scientific instrumentation applications. USA Industries competes aggressively on aftermarket service coverage across power generation maintenance channels.
A tube tester is an electronic instrument designed to measure vacuum tube parameters including transconductance, plate current, and emission characteristics under controlled operating conditions. The device applies precise voltages to tube elements and quantifies electrical response to determine functional status, primarily serving equipment maintenance, restoration, and quality assurance workflows. Digital tester platforms are capturing margin pools from aging analog units as calibration precision and data logging capabilities become decisive procurement criteria. Multifunction testers are expanding fastest among professional end users who require consolidated testing of diverse tube architectures across radio restoration and industrial testing applications. Portable tester demand remains structurally constrained by trade-offs between measurement accuracy and field-deployable form factors.
The U.S. FAA mandates tube integrity verification for certain avionics pressure systems, while OSHA standards govern industrial testing equipment electrical safety certification. Germany's KBA enforces component reliability protocols that extend to vacuum-based systems in automotive applications, and REACH compliance affects material composition in tester manufacturing. Stakeholders must weigh calibration traceability requirements against total cost of ownership when selecting between established analog platforms and emerging digital architectures.
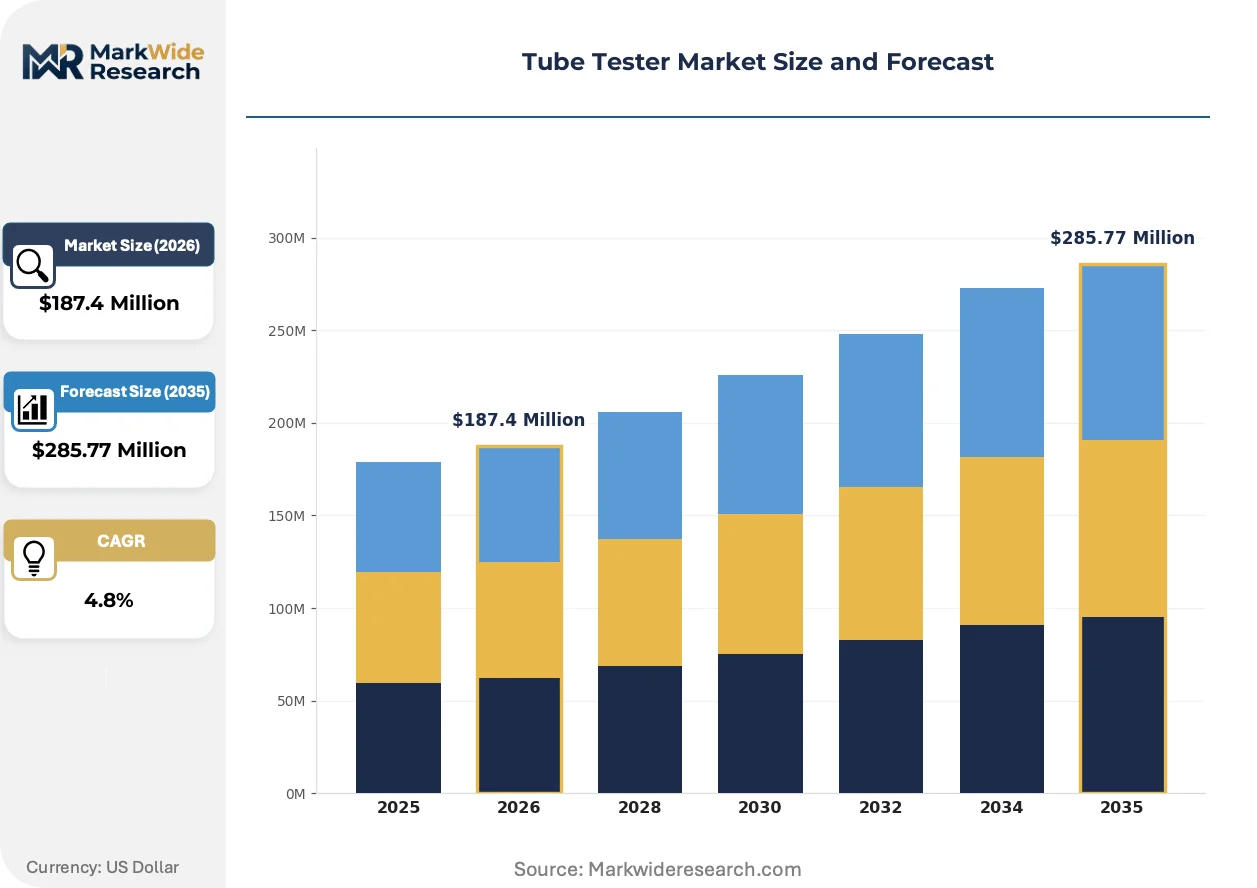
Market Dynamics
Digital tube tester platforms are compressing calibration cycles and displacing analog architectures across aerospace maintenance workflows, forcing incumbent suppliers to reconfigure hardware-software integration roadmaps.
Growth Catalysts
- FAA Airworthiness Directives:Updated pressure vessel integrity mandates in the United States are mandating tube integrity verification protocols, expanding procurement of precision testing equipment among avionics maintenance providers.
- Automotive Component Reliability:Germany's KBA enforces vacuum-based system protocols that extend to industrial testing applications, driving laboratory adoption of advanced digital platforms.
- Non-Destructive Inspection Workflows:Aerospace maintenance providers are consolidating testing equipment procurement around multifunction units capable of diverse tube architecture validation.
Market Restraints
- Calibration Traceability Costs:Digital platforms require continuous metrological verification against NIST-traceable standards, elevating total cost of ownership versus legacy analog units.
- Component Supply Concentration:Precision voltage reference modules and specialized analog-to-digital converters concentrate among East Asian semiconductor foundries, exposing tester manufacturers to input volatility.
- Form Factor Limitations:Portable tester designs face fundamental trade-offs between measurement accuracy and field-deployable weight specifications, constraining mobile inspection adoption.
Strategic Opportunities
- Scientific Instrumentation Applications:Research laboratories require specialized equipment for vacuum tube characterization in particle detection and spectroscopy systems, creating premium pricing potential.
- Power Generation Aftermarket Channels:Maintenance service providers seek consolidated testing capabilities across diverse tube inventories, favoring suppliers with broad service coverage networks.
- REACH Compliance Differentiation:European material composition standards are elevating procurement scrutiny around tester manufacturing processes, rewarding early compliance investments.
Industry Challenges
- Vacuum Tube Expertise Scarcity:The technician workforce proficient in thermionic emission physics and vintage tube architectures is aging without sufficient knowledge transfer mechanisms.
- Legacy System Integration Complexity:Digital tester platforms must interface with existing analog calibration records and maintenance databases, complicating deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tube Tester Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Tester, Digital Tester, Multifunction Tester, Portable Tester End User: Manufacturers, Distributors, Retailers, Hobbyists Application: Audio Equipment, Television Repair, Radio Restoration, Industrial Testing Technology: Vacuum Tube, Solid-State, Hybrid, Bipolar |
| Companies Covered | Apex Tool Group, Curtiss-Wright, EST Group, Vacuum Instrument Corp, Thermographics, USA Industries, Magnetic Analysis Corp, Thomas C. Wilson, Foerster Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tube Tester Market Evolving Landscape
Cloud-connected diagnostic capabilities and automated parameter logging are redefining how maintenance organizations document tube performance histories and demonstrate regulatory compliance.
Multifunction digital architectures are decomposing the traditional segmentation between emission testers, transconductance analyzers, and leakage detection units. Professional restoration workshops and industrial laboratories are consolidating procurement around consolidated platforms that execute diverse test sequences through software configuration rather than hardware swapping. This convergence is decomplicating inventory management for maintenance providers while compressing capital expenditure requirements across multiple tube categories.
REACH regulations governing substance restrictions in electrical equipment manufacturing are elevating material disclosure requirements throughout European supply chains. Tester manufacturers must document compliance across solder compositions, chassis coatings, and internal wiring insulation. German industrial testing laboratories are prioritizing suppliers with verified environmental product declarations, shifting competitive advantage toward transparent supply chain governance.
Certification-driven procurement preferences are displacing price-centric selection criteria among institutional buyers. Aerospace maintenance divisions now require documented calibration traceability to national standards bodies as a threshold qualification, filtering out uncertified equipment regardless of functional capability. This behavioral shift concentrates contract awards among established metrology suppliers with accredited laboratory networks, particularly visible in United States defense-sector procurement channels.
Tube Tester Market Segmentation
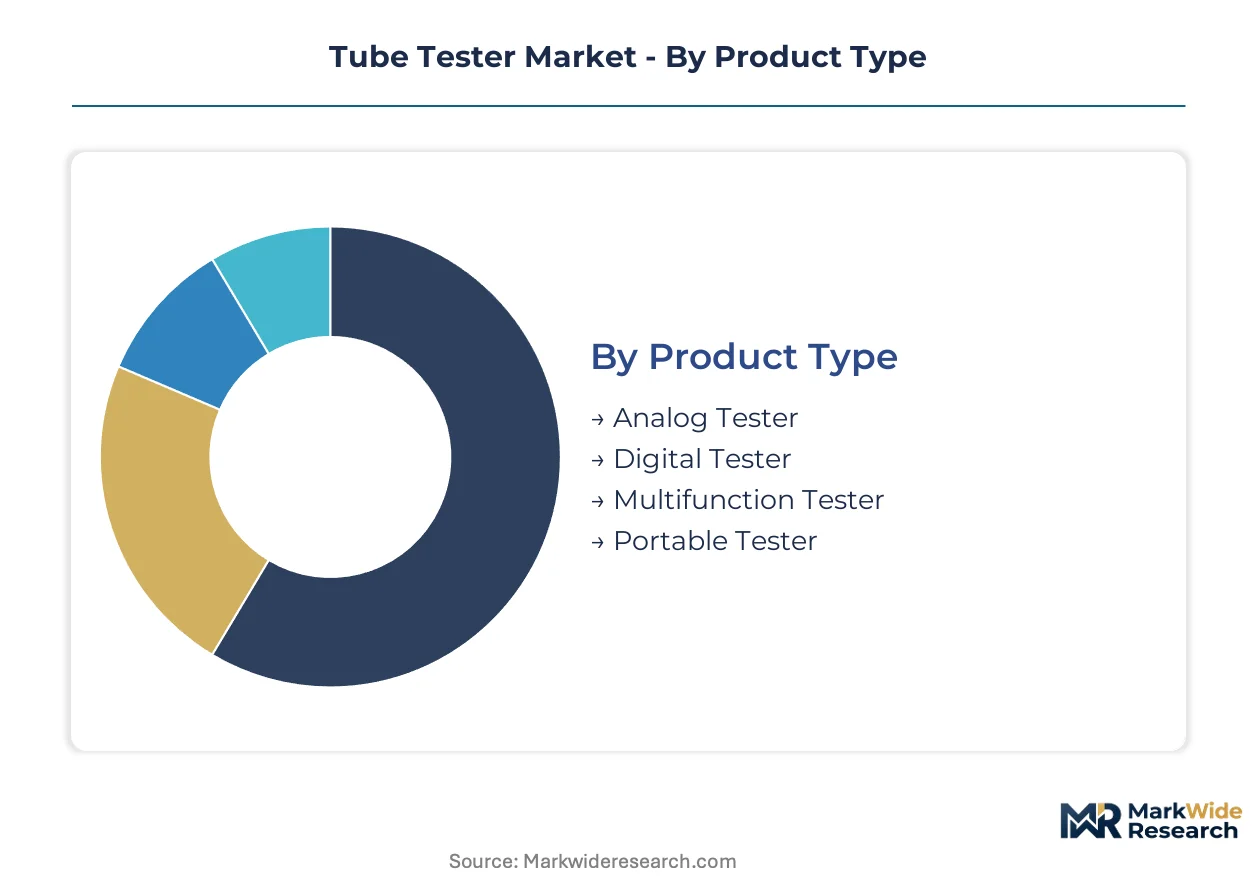
Tube tester procurement patterns diverge sharply across professional and consumer channels, with aerospace maintenance providers demanding calibration-traceable digital platforms while hobbyist collectors sustain analog equipment markets through restoration supply chains. Understanding these segment boundaries reveals where margin pools concentrate and which technology transitions threaten incumbent positioning.
Product Type:
Channel flows split between industrial procurement through authorized distributors and consumer acquisition via specialty retailers and direct-to-hobbyist ecommerce platforms.
- Digital Tester:These platforms apply precision voltage references and NIST-traceable calibration cycles to quantify transconductance and emission characteristics. Aerospace maintenance divisions in the United States concentrate procurement here, driven by FAA airworthiness directives mandating documented tube integrity verification for avionics pressure systems. Digital architectures compress calibration intervals while expanding data logging capabilities for regulatory compliance demonstration.
- Multifunction Tester:Consolidated hardware-software systems execute diverse test sequences across emission, transconductance, and leakage detection through configuration rather than hardware swapping. German industrial testing laboratories anchor demand, with KBA-enforced vacuum system protocols extending from automotive component reliability programs. Professional restoration workshops favor these units for inventory simplification across diverse tube architectures.
- Analog Tester:Legacy electromechanical instruments with manual calibration procedures and visual meter displays. Hobbyist collectors and vintage audio restoration specialists sustain residual demand through specialty supply channels.
- Portable Tester:Battery-powered or lightweight AC units designed for field deployment. Form factor constraints limit measurement precision, constraining adoption to preliminary screening applications rather than certification-grade verification.
Multifunction tester platforms dominate installed base among professional end users. Digital tester architectures are where expansion concentrates, climbing the fastest as calibration traceability becomes a threshold procurement qualification.
End User:
Cost tier stratification separates capital-intensive institutional procurement from price-sensitive individual acquisition patterns.
- Manufacturers:Original equipment producers integrating tube testing into quality assurance workflows for vacuum tube production lines. Demand concentrates in scientific instrumentation and specialized industrial applications requiring emission consistency verification.
- Distributors:Wholesale channels stocking testers for resale to maintenance organizations and restoration professionals. Inventory breadth and aftermarket service coverage determine competitive positioning in this tier.
- Retailers:Specialty electronics vendors serving hobbyist and small-scale repair shop demand. These channels favor lower-price-point analog and entry-level digital units with simplified operation.
- Hobbyists:Individual collectors and vintage audio enthusiasts acquiring testers for personal restoration projects. This segment sustains analog equipment markets and drives demand for educational documentation and community support resources.
Manufacturers and distributors dominate transaction volume. Hobbyists represent the fastest-expanding demand source as vintage audio collecting broadens beyond traditional demographic boundaries.
Application:
Application-specific requirements determine whether procurement prioritizes precision metrology or operational simplicity.
- Industrial Testing:Non-destructive inspection workflows in aerospace, power generation, and automotive manufacturing. German laboratories and United States defense maintenance channels concentrate demand here, with REACH compliance and OSHA electrical safety certification governing equipment selection.
- Radio Restoration:Vintage communications equipment refurbishment for amateur radio operators and museum collections. Multifunction digital platforms gain preference for handling diverse tube architectures spanning multiple eras.
- Audio Equipment:High-fidelity vacuum tube amplifier maintenance and boutique manufacturing. Precision matching of tube pairs drives demand for emission consistency measurement capabilities.
- Television Repair:Declining application segment limited to specialty repair shops servicing vintage CRT displays and industrial monitoring equipment.
Industrial testing commands premium pricing tiers. Radio restoration is where technology transition accelerates most quickly, with digital displacement of analog workflows.
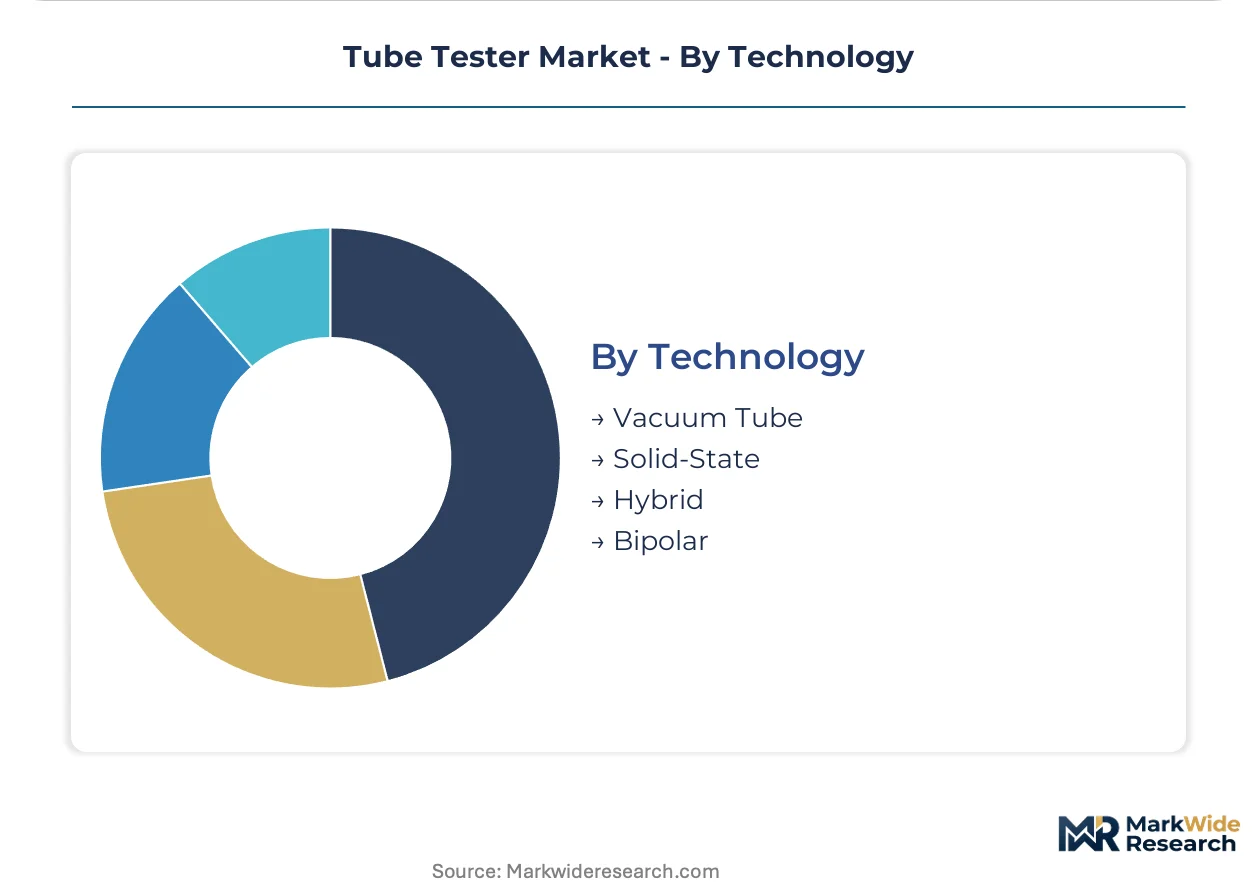
Technology:
Supply concentration in precision voltage reference modules and specialized analog-to-digital converters shapes which technology architectures manufacturers can reliably source.
- Vacuum Tube:Traditional thermionic emission technology using heated cathodes and electron flow through vacuum envelopes. Scientific instrumentation applications in particle detection and spectroscopy sustain specialized demand for characterization equipment.
- Solid-State:Semiconductor-based testing circuitry with digital control and automated parameter logging. Cloud-connected diagnostic capabilities redefine compliance documentation for institutional buyers.
- Hybrid:Combined vacuum tube and solid-state architectures in testing equipment design. These configurations balance measurement fidelity with operational efficiency in mid-tier product positioning.
- Bipolar:Bipolar junction transistor-based signal processing in portable and cost-optimized tester designs. Limited to screening applications where absolute precision is secondary to field deployability.
Solid-state architectures dominate new equipment shipments. Vacuum tube technology persists in specialized scientific channels where thermionic emission physics expertise creates capability scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's central role in European industrial equipment distribution, while the Trans-Alaska Pipeline System anchors North American energy infrastructure maintenance demand for precision testing instruments.
United States
Aerospace maintenance providers in Oklahoma City and Wichita concentrate procurement of digital tube testers for avionics pressure system verification. The FAA's updated airworthiness directives mandate documented tube integrity protocols, tightening compliance requirements for MRO facilities. Dallas-Fort Worth hosts defense-sector maintenance clusters where Curtiss-Wright sustains high-reliability equipment contracts.
Germany
Industrial testing laboratories in Stuttgart and Munich drive adoption of multifunction digital platforms across automotive and energy applications. The KBA enforces vacuum-based system reliability protocols that extend component verification requirements to tube architectures. Bavaria's precision engineering clusters prioritize REACH-compliant equipment with verified environmental product declarations.
Japan
Scientific instrumentation manufacturers in Osaka and Nagoya sustain specialized demand for vacuum tube characterization equipment. METI standards govern measurement device calibration traceability for research laboratory procurement. The Kansai region's particle detection and spectroscopy systems sector requires thermionic emission physics expertise that creates capability scarcity.
United Kingdom
Vintage audio restoration workshops in London and Birmingham sustain analog tester demand through specialty supply channels. CE marking requirements affect electrical safety certification for imported testing equipment. The Midlands manufacturing belt hosts radio refurbishment specialists consolidating procurement around multifunction digital units.
China
Power generation maintenance providers in Shanghai and Shenzhen seek consolidated testing capabilities across diverse tube inventories. GB standards govern industrial testing equipment electrical safety specifications. The Yangtze River Delta's semiconductor foundry concentration exposes tester manufacturers to precision voltage reference module supply volatility.
Tube Tester Market Competitive Landscape
Listed leaders compete with private specialists across calibration-traceable digital architectures, creating a tiered structure where aerospace-grade metrology suppliers command premium positioning against cost-optimized aftermarket providers. The vendor base separates into three strategic archetypes: heritage defense contractors leveraging aerospace pedigrees, scientific instrumentation specialists serving research laboratories, and industrial service providers competing on geographic coverage networks. Dominant competitive moves include portfolio diversification into cloud-connected diagnostic capabilities and strategic partnerships with semiconductor foundries to secure precision component supply.
Within the defense-contractor archetype, Curtiss-Wright occupies a position exemplifying high-reliability system supply to military aviation maintenance channels. Vacuum Instrument Corp represents the scientific instrumentation specialist tier, anchoring demand from research laboratories requiring vacuum tube characterization. USA Industries sits within the industrial service provider category, competing on aftermarket coverage breadth across power generation maintenance networks.
| Leading Market Players |
|---|
| Apex Tool Group |
| Curtiss-Wright |
| EST Group |
| Vacuum Instrument Corp |
| Thermographics |
| USA Industries |
| Magnetic Analysis Corp |
| Thomas C. Wilson |
| Foerster Instruments |
| Others |
Value Network & Pricing Analysis
FAA calibration-traceability mandates gate both supplier qualification and price differentiation simultaneously, compressing procurement options to accredited metrology providers while elevating certification-grade equipment premiums above uncertified alternatives. Buyers face threshold requirements that filter out lower-cost analog platforms regardless of functional capability.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with aerospace maintenance divisions commanding standard-economy splits based on calibration documentation depth. Price differentiation rests on NIST-traceable certification tiers and aftermarket service bundling rather than hardware specifications alone. Cost compression in entry-level digital segments intensifies as East Asian manufacturers push specification-matched units through unauthorized distribution channels. Hobbyist collectors exhibit highest price sensitivity, while defense-sector maintenance channels prioritize qualification over unit economics.
Supply Chain Analysis
Strategic stockpiling of precision voltage reference modules and specialized analog-to-digital converters characterizes inventory management as semiconductor foundry concentration in Taiwan, South Korea, and China exposes tester manufacturers to input volatility. Raw material dependencies center on high-precision resistors, ceramic capacitors, and vacuum-grade socket assemblies. Single-source vulnerability in East Asian semiconductor fabrication creates supply interruption risk. Distribution runs through authorized industrial equipment distributors serving aerospace and power generation maintenance channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among institutional procurement consortia, with aerospace maintenance divisions and German industrial testing laboratories consolidating equipment purchasing through multi-year framework agreements that compress supplier margins.
For Market Incumbents: Secure calibration-laboratory accreditation networks against emerging digital-platform entrants by expanding NIST-traceable service footprints into Oklahoma City and Stuttgart maintenance clusters. Deepen backward integration into precision voltage reference module sourcing to offset East Asian foundry concentration risk. Prioritize cloud-connected diagnostic capability development to defend against software-native competitors. For New Entrants and Emerging Players: Aftermarket calibration service gaps in vintage audio restoration channels present white-space entry points where established metrology suppliers under-invest. Hobbyist collectors and small-scale repair workshops represent the most penetrable segment given price sensitivity and simplified documentation requirements. Direct-to-hobbyist ecommerce platforms offer lower-friction go-to-market positioning versus authorized distributor networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state digital architectures as cloud-connected diagnostic capabilities require sustained software development investment. Long-term viability favors acquisition targets with established calibration-laboratory networks and defense-sector contract visibility. Watch for FAA airworthiness directive expansion scope as inflection signal indicating addressable market enlargement.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Accreditation Expansion | NIST-traceable certification opens FAA-mandated aerospace procurement channels. |
| Cloud-Connected Diagnostic Platform Launch | Automated parameter logging addresses regulatory compliance documentation requirements. |
| Backward Integration into Precision Components | In-house voltage reference production reduces East Asian foundry dependency exposure. |
| REACH Compliance Certification Program | Environmental product declarations unlock German industrial laboratory procurement preferences. |
| Aftermarket Service Network Expansion | Geographic coverage breadth determines competitive positioning in power generation channels. |
Research Methodology
A standing panel of aerospace maintenance directors, industrial testing laboratory managers, vintage audio restoration specialists, and semiconductor procurement leads provided ongoing calibration against market dynamics. Primary interview data combined with secondary validation from FAA airworthiness directive filings, OSHA electrical safety certification records, KBA component reliability protocols, and customs trade data. Bottom-up equipment shipment analysis triangulated against top-down maintenance expenditure estimates.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation modeling incorporated product architecture, end-user procurement authority, application-specific precision requirements, and regional regulatory cluster variations. CAGRs derived from equipment replacement cycle analysis and institutional procurement budget trajectories. Industry-specific forecast inputs included avionics pressure system maintenance schedules and scientific instrumentation capital expenditure patterns.
Forecasts assume regulatory continuity in FAA airworthiness directives, KBA vacuum system protocols, and REACH substance restrictions; material policy shifts would require re-modeling. Semiconductor supply concentration and technician workforce demographics represent specific risk factors. Revision becomes warranted when calibration-traceability mandate expansion or foundry disruption crosses operational thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Permeation Testing Machines Market
Test and Measurement
Ultrasonic Flaw Detector Market
Test and Measurement
Inline Metrology Market
Test and Measurement
Digital Inspection Market
Test and Measurement
Bursting Strength Tester Market
Test and Measurement
Fiber Optic Test Equipment (FOTE) Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
Simulation and Test Data Management Market
Test and Measurement
Digital Inspection Tools Market
Test and Measurement
5G Testing Devices Market
Test and Measurement
Silicon Photonics and Optical I/O Test and Measurement Systems Market
Test and Measurement
Non-Destructive Testing (NDT) Service Market
Test and Measurement
High-Aspect-Ratio 3D NAND Metrology Equipment Market
Test and Measurement
Data Center Testing Market
Test and Measurement
RFID Tester Market
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market