
 EMC Testing Market | 2026-2036
EMC Testing Market Size, Share, and Industry Trends Forecast 2026-2036
EMC Testing Market Analysis
EMC engineering talent availability is collapsing across North America and Western Europe, forcing laboratories to automate workflows or expand recruitment into Eastern European and Asian technical institutes. SGS SA leverages its global laboratory network to sustain multi-site certification programs for automotive tier-one suppliers. Bureau Veritas anchors its EMC portfolio with marine and industrial equipment specializations that demand harsh-environment immunity validation. Intertek Group plc competes on turnaround speed for consumer electronics pre-compliance, differentiating through dedicated anechoic chamber capacity in Shenzhen and Fremont.
Electromagnetic compatibility testing encompasses the measurement and verification that electrical and electronic equipment neither emits excessive electromagnetic interference nor suffers performance degradation under defined immunity stress levels, typically conducted in shielded anechoic chambers or open-area test sites with calibrated antennas and spectrum analyzers per CISPR and IEC standards. Its primary industrial purpose is to ensure regulatory conformity, functional safety, and coexistence of densely packed electronics in vehicles, medical devices, and wireless infrastructure. Testing Services commands the largest revenue share within Service Type due to recurring mandatory certification cycles, while Certification Services captures disproportionate margin pools from automotive and aerospace OEM approvals. Emission Testing dominates Product Type volume as baseline regulatory entry requirements, though Immunity Testing is expanding fastest from electric vehicle powertrain and autonomous sensor validation needs.
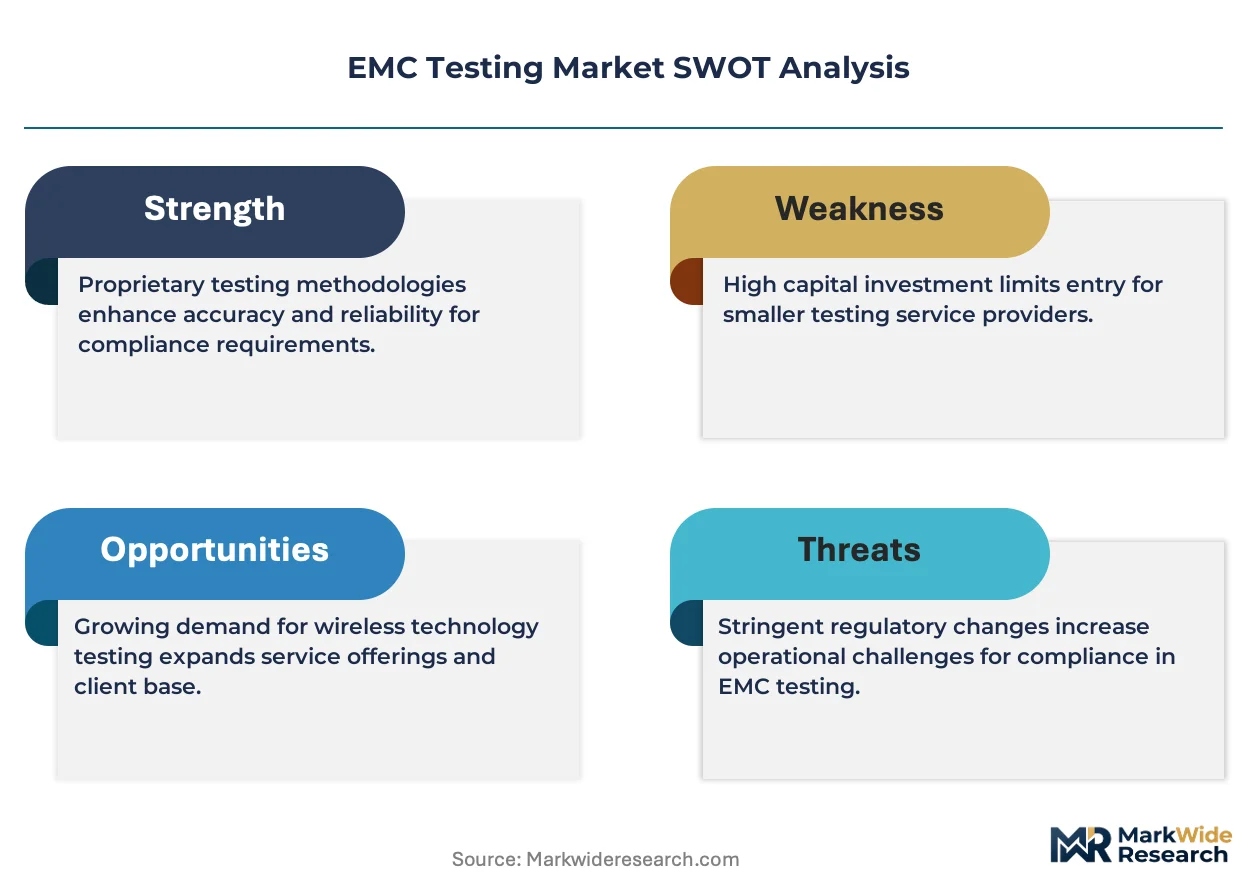
The U.S. FCC Part 15 and Part 18 rules, the EU EMC Directive with CE marking obligations, and China's GB/T standards enforced by SAMR collectively define the regulatory perimeter that laboratories must navigate for market access. These frameworks mandate third-party testing for intentional radiators, industrial equipment, and automotive electronics, directly translating compliance scope into laboratory revenue pipelines. Stakeholders should monitor divergence between EU and U.S. immunity test levels for 5G base stations and industrial IoT gateways, as regulatory misalignment threatens to fragment certification strategies and duplicate testing expenditure.
Market Dynamics
Automotive electrification is forcing a wholesale reconfiguration of EMC validation protocols as 800V architectures and multi-domain controllers multiply interference pathways beyond legacy 12V test matrices.
Growth Catalysts
- EU Radio Equipment Directive:Tightened conformity assessment obligations for 5G and IoT devices are expanding mandatory third-party testing volumes across telecommunications supply chains.
- Electric vehicle powertrains:Silicon carbide inverters and wireless charging coils introduce high-frequency switching noise that exceeds legacy emission limits, requiring redesigned immunity validation.
- Germany's automotive cluster:Concentrated OEM and tier-one supplier engineering centers in Stuttgart, Munich, and Wolfsburg sustain dense demand for pre-compliance and homologation services.
Market Restraints
- Chamber construction costs:Ferrite-tile and hybrid anechoic installations require specialized RF-absorbing materials and precision shielding that inflate fixed asset intensity.
- Engineer supply concentration:EMC design and measurement expertise pools narrowly in specific technical universities across Poland, Hungary, and select Indian institutes, creating recruitment bottlenecks.
- Regulatory divergence friction:Misalignment between FCC Part 15 emission limits and EU EMC Directive immunity test levels for industrial IoT gateways forces redundant certification cycles.
Strategic Opportunities
- India's automotive testing corridor:Chennai and Pune emerging as EMC validation hubs for export-oriented component manufacturers serving ASEAN and Middle Eastern markets.
- Over-the-air (OTA) test automation:Software-defined spectrum analyzers and robotic antenna positioning are compressing test cycle times for mass-market consumer electronics.
- EU Battery Regulation:Electromagnetic safety mandates for traction batteries and battery management systems open specialized validation revenue streams beyond traditional automotive electronics.
Industry Challenges
- RF engineer scarcity:North American and Western European laboratories face acute shortages of professionals skilled in CISPR 25 automotive chamber calibration and antenna factor derivation.
- Multi-standard integration complexity:Simultaneous compliance with UNECE R10, ISO 11452, and OEM-specific test plans strains laboratory scheduling and equipment allocation.
- Legacy equipment write-downs:Transition from 3-meter to 10-meter chamber configurations for heavy-duty vehicle testing accelerates depreciation of existing semi-anechoic assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMC Testing Market |
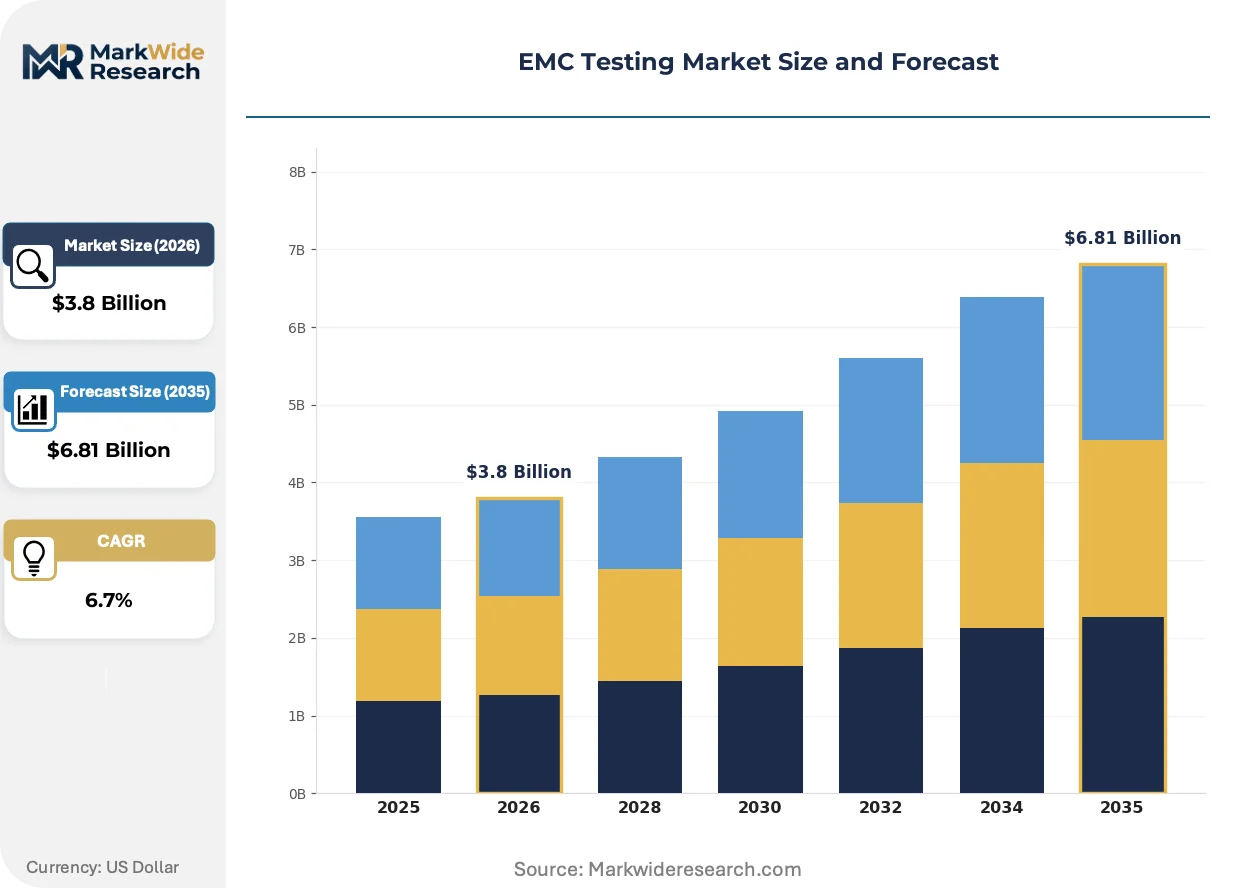
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emission Testing, Immunity Testing, Standards Compliance, Pre-compliance Testing End User: Telecommunications, Automotive Industry, Aerospace & Defense, Consumer Electronics Service Type: Consulting Services, Testing Services, Certification Services, Training Services Technology: Automated Testing, Manual Testing, Software Solutions, Measurement Equipment |
| Companies Covered | TÜV SÜD, Eurofins Scientific, Intertek Group plc, UL LLC, TÜV NORD GROUP, SGS SA, Keysight Technologies, Dekra SE, Bureau Veritas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMC Testing Market Emerging Trajectories
Test methodology automation and predictive modeling are compressing traditional validation timelines while regulatory scope expansion into new product categories reshapes laboratory capability requirements.
Software-defined test instrumentation is decomposing the traditional hardware-centric EMC laboratory model. Automotive tier-one suppliers in Stuttgart and Detroit are adopting modular spectrum analyzers and programmable switching matrices that slash chamber occupancy hours. This technology shift is compressing the revenue-per-test-hour model that has sustained legacy laboratories for decades.
REACH restrictions on hexavalent chromium and cadmium in RF-absorbing foams are forcing chamber refurbishment cycles across European test houses. Manufacturers in Germany and France must now source alternative ferrite composites or absorb compliance-driven cost premiums. The directive most acutely affects marine and industrial equipment specialists requiring large-volume semi-anechoic configurations.
Certification-driven supplier consolidation is altering procurement patterns among automotive OEMs. Tier-one electronics vendors in China and the United States are bundling EMC validation into multi-year engineering service contracts rather than transactional test orders. This behavioral shift is most pronounced in electric vehicle programs where design iteration frequency demands embedded laboratory partnerships rather than spot-market testing.
EMC Testing Market Segmentation
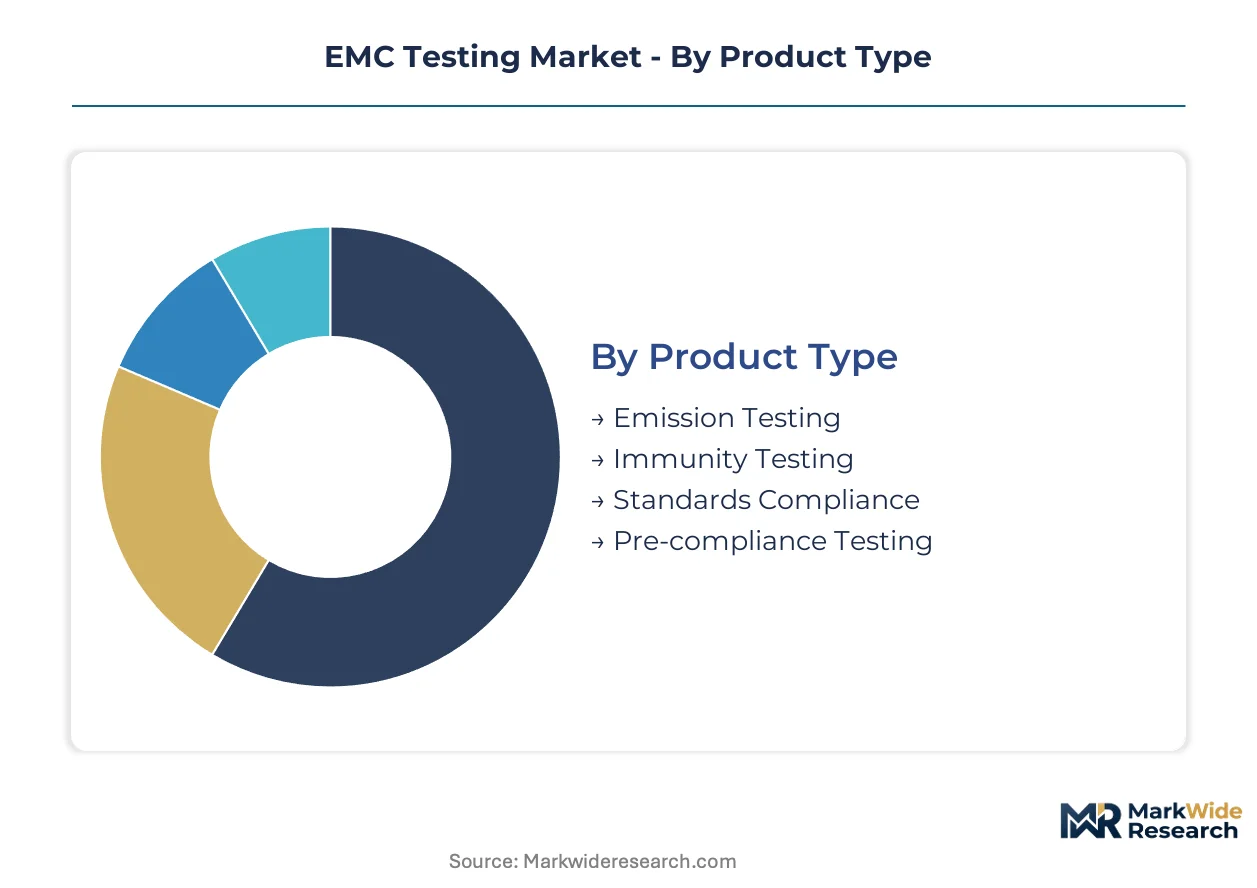
EMC testing segmentation reflects divergent regulatory stringency across product categories and end-use applications. Laboratories configure specialized capabilities around emission limits versus immunity stress levels, with service delivery models adapting to certification urgency and customer engineering maturity.
Product Type:
FCC Part 15 emission limits for unintentional radiators diverge sharply from EU EMC Directive immunity test levels, creating distinct capability requirements across testing protocols.
- Emission Testing:Measures conducted and radiated electromagnetic interference against CISPR and IEC baseline limits using calibrated antennas and spectrum analyzers in shielded chambers. Automotive OEMs in Stuttgart and Detroit concentrate validation demand here for powertrain electronics and infotainment systems facing strict regulatory entry requirements.
- Immunity Testing:Subjecting equipment to defined electromagnetic stress levels including electrostatic discharge, radiated fields, and transient bursts to verify functional performance under interference. Electric vehicle programs with silicon carbide inverters and autonomous sensor arrays in Germany and China are accelerating validation volumes as 800V architectures exceed legacy test matrices.
- Standards Compliance:Formal verification against harmonized standards for CE marking, FCC certification, or GB/T conformity assessment.
- Pre-compliance Testing:Early-stage diagnostic screening to identify design flaws before full certification cycles.
Emission Testing handles the majority of throughput; Immunity Testing is expanding most quickly on share.
End User:
Customer concentration varies by engineering sophistication, with aerospace and defense contractors demanding embedded laboratory partnerships while consumer electronics vendors prioritize turnaround velocity.
- Automotive Industry:Tier-one suppliers and OEMs require multi-domain controller validation across 12V and 800V architectures, with homologation cycles tied to UNECE R10 and ISO 11452 compliance. Engineering centers in Wolfsburg, Munich, and Detroit sustain dense demand for pre-compliance and production validation services.
- Telecommunications:5G base station and IoT gateway manufacturers face tightened EU Radio Equipment Directive conformity assessment obligations. Equipment vendors in Shenzhen and Fremont drive chamber occupancy for intentional radiator certification under FCC Part 15 rules.
- Consumer Electronics:High-volume, short-lifecycle products requiring rapid pre-compliance turnaround.
- Aerospace & Defense:Harsh-environment immunity validation for avionics and military systems with extended certification timelines.
Automotive Industry captures the largest revenue concentration; Telecommunications is climbing the fastest on validation volume.
Service Type:
Margin structures diverge between transactional test execution and multi-year engineering partnerships with embedded laboratory access.
- Testing Services:Recurring mandatory certification cycles for regulatory conformity, conducted in semi-anechoic chambers or open-area test sites. Laboratories in Germany, China, and the United States concentrate capacity here to serve automotive and telecommunications supply chains with high repeat volumes.
- Certification Services:Formal approval documentation for market access, capturing disproportionate margin pools from automotive and aerospace OEM approvals. SGS SA and Bureau Veritas leverage global accreditation networks to sustain multi-site certification programs.
- Consulting Services:Design-stage EMC engineering support for product development teams.
- Training Services:Capability building for customer engineering staff on CISPR and IEC test methodologies.
Testing Services dominates absolute throughput; Certification Services delivers the steepest margin expansion.
Technology:
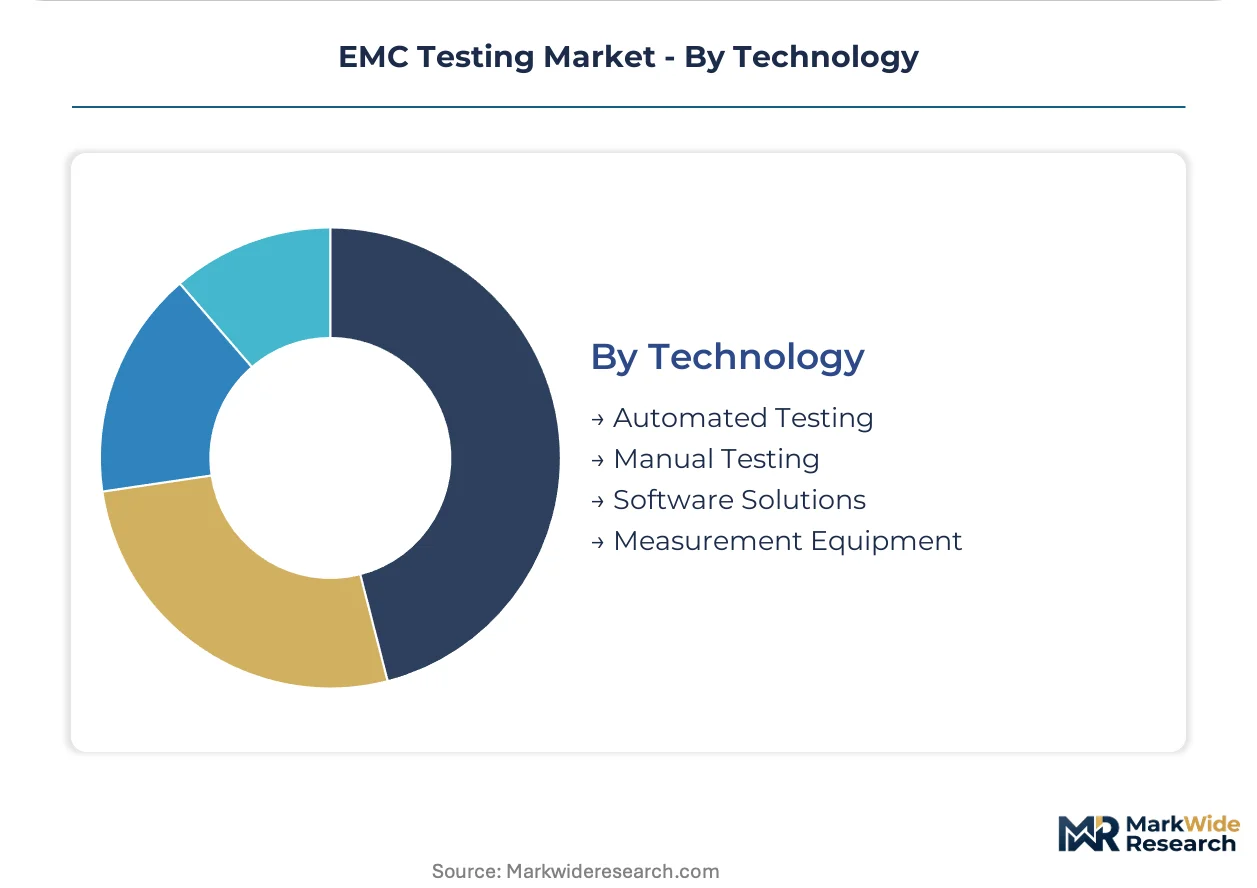
Capital intensity and labor substitution potential separate automated from manual testing approaches, with software-defined instrumentation decomposing legacy hardware-centric laboratory models.
- Automated Testing:Software-defined spectrum analyzers, programmable switching matrices, and robotic antenna positioning compress chamber occupancy hours. Tier-one suppliers in Stuttgart and Detroit are adopting modular instrumentation to slash test cycle times for mass-market consumer electronics.
- Measurement Equipment:Calibrated antennas, receivers, and signal generators forming the fixed asset base of EMC laboratories. REACH restrictions on hexavalent chromium and cadmium in RF-absorbing foams are forcing chamber refurbishment cycles across European test houses in Germany and France.
- Manual Testing:Engineer-intensive protocols for complex or non-standard product configurations.
- Software Solutions:Test automation platforms and data management systems for regulatory documentation.
Automated Testing is gaining adoption fastest; Measurement Equipment represents the largest fixed capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China deploy EMC testing for automotive electrification validation, while the United States concentrates on telecommunications infrastructure certification and consumer electronics pre-compliance screening.
Germany
Automotive OEMs and tier-one suppliers in Stuttgart, Munich, and Wolfsburg sustain dense demand for 800V powertrain validation. The KBA enforces UNECE R10 homologation requirements that mandate third-party electromagnetic compatibility assessment. Engineering centers across Baden-Württemberg and Bavaria are embedding laboratory partnerships into multi-year supplier contracts.
China
Shenzhen and Shanghai host concentrated 5G base station manufacturing that drives intentional radiator certification under MIIT-administered GB/T standards. SAMR conformity assessment obligations are tightening for industrial IoT gateway exports to European markets. The Yangtze River Delta and Pearl River Delta clusters are expanding semi-anechoic chamber capacity for electric vehicle controller validation.
United States
FCC Part 15 and Part 18 rules govern emission limits for unintentional radiators and industrial equipment across telecommunications and medical device supply chains. Fremont and Austin engineering centers are automating test workflows to compress turnaround times for high-volume consumer electronics. The FCC's updated equipment authorization procedures are expanding mandatory third-party testing scope for modular transmitter approvals.
India
Chennai and Pune are emerging as EMC validation hubs for export-oriented automotive component manufacturers serving ASEAN markets. BIS certification requirements under the Compulsory Registration Order are expanding mandatory testing for electronic goods. The Tamil Nadu and Maharashtra industrial corridors are attracting laboratory investments from European certification bodies seeking regional coverage.
Japan
METI-administered technical standards for radio equipment are tightening conformity assessment for 5G infrastructure and automotive radar systems. Nagoya and Tokyo engineering centers concentrate validation demand for hybrid vehicle power electronics. The Chubu and Kanto regions sustain specialized immunity testing capacity for harsh-environment industrial automation equipment.
EMC Testing Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with global certification networks separating scale-driven players from regional laboratory operators. The structure rewards multi-site accreditation capabilities that sustain automotive OEM homologation programs across jurisdictions. Three archetypes dominate: diversified testing conglomerates with cross-industry portfolios, automotive-focused validation specialists with embedded OEM partnerships, and equipment manufacturers extending into calibration services. Competitive positioning hinges on chamber capacity expansion in high-demand clusters and strategic partnerships with tier-one suppliers for embedded test programs.
Within the diversified certification tier, SGS SA, Bureau Veritas, and Intertek Group plc exemplify global network operators leveraging multi-site accreditation to sustain multi-year automotive supplier contracts. These entities occupy positions that span marine, industrial, and consumer electronics validation, with geographic coverage anchored in European and Asian manufacturing clusters. Their market presence reflects the premium placed on regulatory breadth rather than single-industry depth.
| Leading Market Players |
|---|
| TÜV SÜD |
| Eurofins Scientific |
| Intertek Group plc |
| UL LLC |
| TÜV NORD GROUP |
| SGS SA |
| Keysight Technologies |
| Dekra SE |
| Bureau Veritas |
| Others |
Supply Flow & Price Mechanics
Chamber construction lead times stretching 18-24 months for ferrite-tile installations concentrate pricing power with established laboratory operators in Germany and China, while automotive OEMs absorb premium rates to secure embedded validation partnerships for 800V powertrain programs.
Pricing Analysis
Long-term engineering service contracts dominate procurement for automotive tier-one suppliers, displacing transactional test orders as electric vehicle programs demand embedded laboratory partnerships. Pricing stratifies across automotive OEM homologation tiers, consumer electronics pre-compliance screening, and marine certification grades, with cost compression in consumer electronics intensifying as Shenzhen laboratories automate workflows. Tier-one automotive buyers show lowest price sensitivity due to regulatory liability exposure, while mass-market consumer electronics vendors negotiate aggressively on per-test rates.
Supply Chain Analysis
Germany and China anchor anechoic chamber manufacturing and RF-absorbing material production, with specialized ferrite composite fabrication concentrated in Baden-Württemberg and the Yangtze River Delta. Laboratory equipment supply draws from calibrated antenna producers in the United States, spectrum analyzer manufacturers in Japan, and precision shielding fabricators in South Korea. REACH restrictions on hexavalent chromium in RF-absorbing foams create regulatory-driven supply risk for European test house refurbishment cycles. Distribution runs through direct sales to automotive OEM engineering centers and certification body networks serving telecommunications infrastructure deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined test instrumentation is collapsing the traditional hardware-centric laboratory model into a platform ecosystem where modular spectrum analyzers and programmable switching matrices interoperate across supplier networks, reconfiguring value capture toward automation vendors and away from fixed-asset operators.
For Market Incumbents: Shield accreditation portfolios against modular instrumentation disruption by embedding multi-site certification networks into automotive OEM homologation programs. Prioritize chamber capacity expansion in Chennai and Pune to capture export-oriented automotive component validation demand from ASEAN markets. Defensive consolidation around silicon carbide inverter immunity testing protocols preserves margin pools as 800V architectures exceed legacy test matrices. For New Entrants and Emerging Players: Differentiate on over-the-air test automation for 5G base station intentional radiator certification, targeting Shenzhen and Fremont engineering centers with robotic antenna positioning and software-defined spectrum analyzer offerings. White-space concentration sits with EU Battery Regulation electromagnetic safety mandates for traction battery management systems, where specialized validation protocols remain undersupplied. Go-to-market leverage rests on partnerships with European certification bodies seeking regional coverage in India's Tamil Nadu corridor. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because automotive electrification and telecommunications infrastructure deployment are structurally expanding mandatory third-party testing scope across jurisdictions. Acquisition targets should concentrate on laboratories with UNECE R10 and ISO 11452 accreditation depth serving Stuttgart, Munich, and Wolfsburg automotive clusters. The signal to watch is divergence between FCC Part 15 and EU EMC Directive immunity test levels for industrial IoT gateways, which would fragment certification strategies and favor multi-site network operators.| Strategic Initiative | Industry Significance |
|---|---|
| Chamber Capacity Expansion | Semi-anechoic installations in Chennai and Pune capture ASEAN export validation demand from automotive component manufacturers. |
| Software-Defined Test Automation | Modular spectrum analyzers and robotic antenna positioning compress cycle times for Shenzhen consumer electronics pre-compliance screening. |
| Multi-Site Accreditation Investment | UNECE R10 and ISO 11452 certification depth sustains embedded partnerships with Stuttgart and Wolfsburg OEM engineering centers. |
| EU Battery Regulation Specialization | Electromagnetic safety validation for traction batteries opens revenue streams beyond traditional automotive electronics testing. |
| Strategic Partnership with Tier-One Suppliers | Long-term engineering service contracts displace transactional orders as electric vehicle programs demand embedded laboratory access. |
Methodological Framework
Initial hypotheses were tested against primary input from EMC laboratory directors, automotive tier-one supplier procurement leads, telecommunications equipment validation managers, and certification body accreditation officers, and refined through secondary validation against FCC equipment authorization databases, EU harmonized standards publications, SAMR conformity assessment disclosures, and automotive OEM homologation filings. Bottom-up segmentation modeling triangulated with top-down market sizing across service type, product type, and end-user dimensions.
Variance decomposition across the projection horizon isolated volume drivers from pricing dynamics, with analytical framework segmentation spanning testing services versus certification services, emission versus immunity protocols, and automotive versus telecommunications end-use concentration. CAGRs were derived from regression analysis of historical certification cycle frequency and forward projections of electric vehicle powertrain validation demand, with chamber capacity utilization rates and engineer supply concentration serving as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained automotive electrification investment and stable regulatory alignment between FCC and EU EMC Directive frameworks; material divergence in immunity test levels or REACH restriction expansion would warrant model refresh. Recalibration cycles align with material shifts in 5G infrastructure deployment timelines and silicon carbide inverter adoption trajectories across OEM supply chains.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Video Test Equipment Market
Test and Measurement
Fluorometers Market
Test and Measurement
Tribometer Market
Test and Measurement
Noise Dosimeter Market
Test and Measurement
Noise Vibration Harshness (NVH) Testing Market
Test and Measurement
Global Electromagnetic Flow Meter Market
Test and Measurement
Non-Destructive Testing Market
Test and Measurement
Test and Measurement Sensors Market
Test and Measurement
Drop Weight Testers Market
Test and Measurement
Battery Test Equipment Market
Test and Measurement
In-Line Overlay and Critical Dimension Metrology for Sub-3nm Nodes Market
Test and Measurement
Battery Drop Tester Market
Test and Measurement
Rohs Tester Market
Test and Measurement
Wireless Network Test Equipment Market
Test and Measurement
LCR Meter Market
Test and Measurement
Brightness Meter Market