
 Global Casino and Gaming Market | 2026-2036
Global Casino and Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Global Casino and Gaming Market Foresight
Digital payment infrastructure is broadening access to real-money gaming across underbanked populations in emerging economies. MGM Resorts International leverages its integrated resort footprint to anchor premium hospitality-gaming bundles in Las Vegas and regional US markets. Caesars Entertainment competes through its omnichannel loyalty architecture that bridges physical casino floors with digital sportsbook platforms. Galaxy Entertainment Group dominates Macau's Cotai Strip with concentrated mass-table and non-gaming revenue diversification.
Casino and gaming encompasses physical and digital wagering environments where chance-based and skill-based contests generate revenue through house-edge mechanics, commission structures, or subscription fees. The industry relies on random number generation certification, server-based gaming networks, and geolocation verification to ensure regulatory compliance and operational integrity. Slot machines and electronic gaming machines capture the largest installed base across land-based casinos, though sports betting terminals are expanding fastest as jurisdictions liberalize live-event wagering. Online casinos and mobile gaming command superior margin profiles due to lower physical overhead, while social gaming serves as a regulated-adjacent acquisition funnel in restrictive markets.
The US Federal Trade Commission monitors sweepstakes and promotional gaming mechanics for consumer deception, while state gaming commissions enforce territorial licensing exclusivity. The European Gaming and Betting Association coordinates self-exclusion standards across EU member regulators, and Macau's Gaming Inspection and Coordination Bureau sets table allocation and capital reserve requirements. China's Ministry of Culture and Tourism restricts cross-border marketing of gambling services, constraining operator expansion tactics. Stakeholders must monitor regulatory divergence between permissive licensing regimes and prohibitionist enforcement corridors when allocating platform development resources.
Market Dynamics
Regulatory divergence between permissive digital licensing regimes and prohibitionist enforcement corridors is fragmenting operator capital allocation strategies across the Global Casino and Gaming Market. Jurisdictions with mature online frameworks attract platform development investment while restrictive markets force reliance on physical integrated resort expansion or social-gaming acquisition funnels.
Growth Catalysts
- Digital wallet penetration:Mobile payment infrastructure across Southeast Asian markets is broadening access to real-money gaming for underbanked populations previously excluded from formal banking channels.
- EGBA coordination:The European Gaming and Betting Association's harmonized self-exclusion standards reduce compliance fragmentation costs for operators seeking multi-jurisdiction licenses within the European Union.
- Mass-market pivot:Macau's Cotai Strip operators are diversifying revenue streams toward non-gaming hospitality and mass-table gaming, reducing reliance on volatile VIP junket volumes.
Market Restraints
- AML compliance costs:The European Union's tightening anti-money laundering protocols for remote gaming operators impose substantial transaction monitoring infrastructure expenditures.
- Cross-border marketing restrictions:China's Ministry of Culture and Tourism constraints on gambling service promotion limit operator expansion tactics in the world's largest outbound tourism market.
- Server-based gaming capital intensity:Land-based casinos face replacement cycles for electronic gaming machine networks requiring certified random number generation hardware and geolocation verification systems.
Strategic Opportunities
- Live-event wagering liberalization:Sports betting terminals represent the fastest-expanding installed base as US state commissions and European regulators authorize real-time in-play markets.
- Social gaming acquisition funnels:Free-to-play mobile casino mechanics serve as regulated-adjacent player development channels in prohibitionist enforcement corridors.
- Integrated resort bundling:Premium hospitality-gaming packages anchored by destination entertainment and convention infrastructure capture extended-stay visitor spend.
Industry Challenges
- Geolocation verification precision:Remote gaming operators must deploy multi-source location authentication to satisfy territorial licensing exclusivity requirements enforced by state gaming commissions.
- Random number generation certification timelines:Third-party laboratory testing for slot machine and electronic gaming machine algorithm integrity creates product launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Casino and Gaming Market |
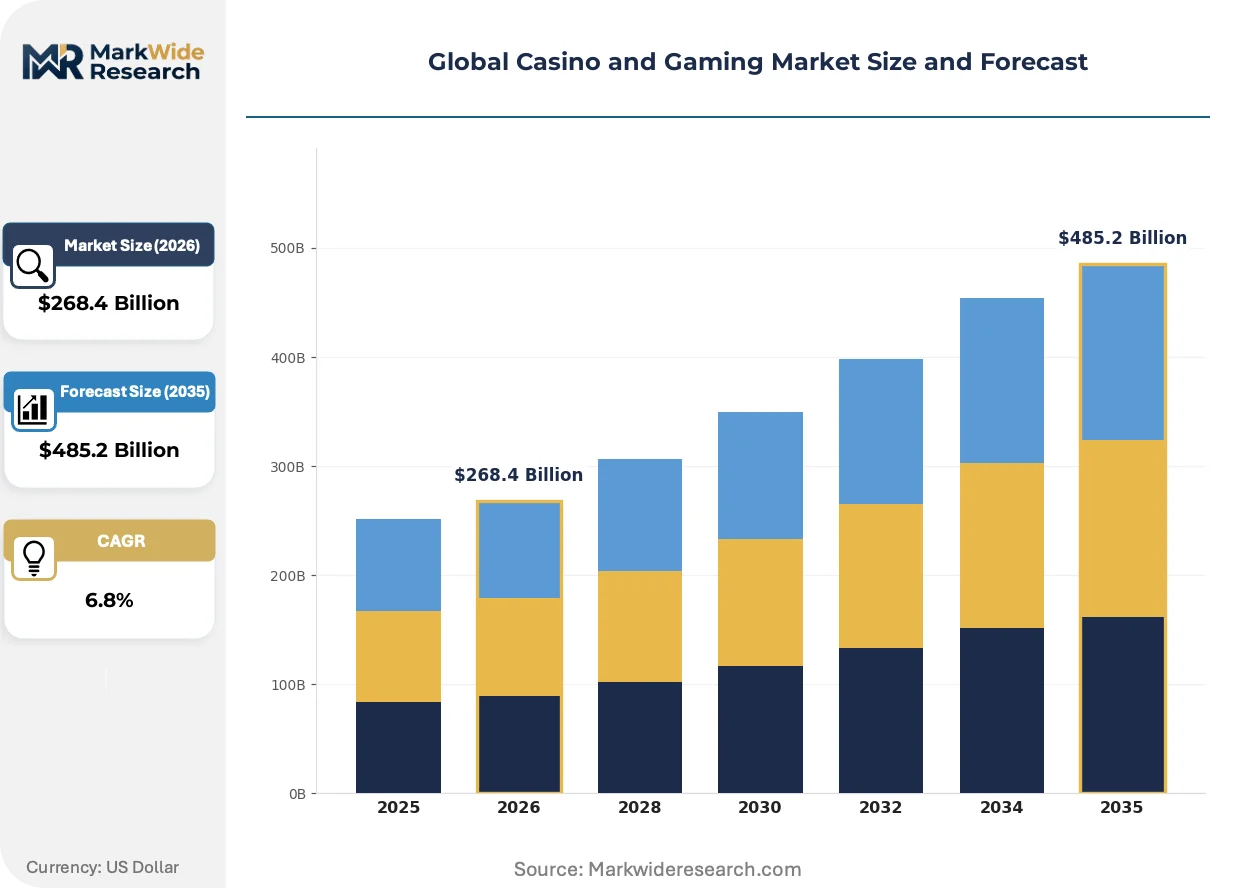
| Market Size in 2026 | $268.4 Billion |
| Market Size in 2035 | $485.2 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slot Machines, Table Games, Electronic Gaming Machines, Sports Betting Terminals Application: Land-Based Casinos, Online Casinos, Mobile Gaming, Social Gaming End User: Casinos, Gaming Lounges, Betting Shops, Private Clubs Technology: Virtual Reality, Blockchain, Cloud Computing, Artificial Intelligence, Skill-Based Gaming |
| Companies Covered | MGM Resorts International, Las Vegas Sands Corporation, Wynn Resorts, Caesars Entertainment, Galaxy Entertainment Group, Melco Resorts & Entertainment, SJM Holdings Limited, Genting Berhad, Crown Resorts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Casino and Gaming Market Shifts & Advancements
Platform architecture convergence is compressing the boundary between physical casino floors and digital wagering environments. Operators now compete through unified player account systems that synchronize loyalty currencies, wagering histories, and responsible gaming controls across channel silos.
Blockchain-based provable fairness mechanisms are unifying trust architectures for online casino operators seeking differentiation in saturated European and Latin American markets. Mid-tier platforms adopting these verification layers report accelerated player acquisition velocity. The technology is unifying previously separate random number generation certification, payout transparency, and dispute resolution functions into single technical stacks.
The EU AI Act's risk classification framework for automated decision-making systems is reshaping operator investment in player behavior analytics. Remote gaming platforms must now document algorithmic logic for deposit limit interventions and self-exclusion triggers. European-licensed operators are responding by segregating AI-driven personalization engines from responsible gaming automation to maintain regulatory defensibility.
Subscription-based social casino models are displacing traditional advertising-dependent free-to-play monetization in restrictive Asian markets. Japanese and South Korean mobile publishers now bundle virtual currency allotments with exclusive content access rather than relying on intermittent in-app purchases. This behavioral pivot is most visible in markets where real-money gaming prohibition elevates skill-based tournament formats and collectible meta-layer engagement.
Global Casino and Gaming Market Segmentation
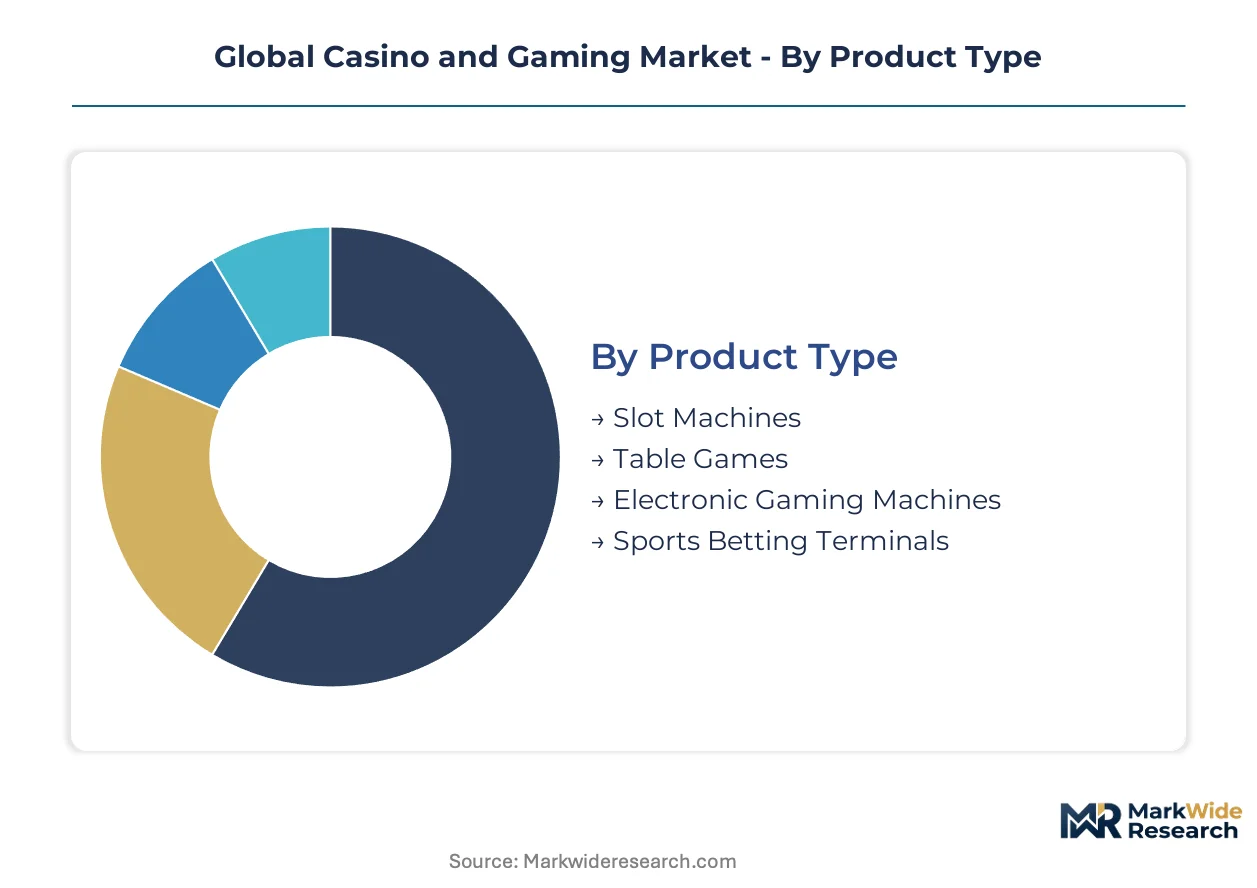
Segmentation in casino and gaming reveals how regulatory boundaries and technology deployment costs fragment addressable markets. Operators must align platform architecture with channel-specific compliance requirements rather than pursuing universal product designs.
Product Type:
Hardware standardization dominates mass-market segments while bespoke configurations persist in premium tiers.
- Slot Machines:Mechanical and video reel configurations with certified random number generation hardware. Demand concentrates in Las Vegas and regional US markets as tribal gaming compacts expand machine allocation entitlements.
- Table Games:Physical felt-based contests including blackjack, baccarat, and roulette with house-edge mathematics. Macau's Cotai Strip operators deploy these for mass-market floor space optimization amid VIP junket decline.
- Electronic Gaming Machines:Server-based terminals with centralized game libraries and remote content management.
- Sports Betting Terminals:In-venue kiosks with real-time odds integration and cashless wallet connectivity.
Leading the category by volume: Slot Machines. Growing fastest: Sports Betting Terminals.
Application:
Channel economics diverge sharply between physical overhead absorption and digital marginal cost structures.
- Land-Based Casinos:Integrated resort and standalone venues with territorial licensing exclusivity. Nevada and New Jersey gaming commissions enforce geofenced operational boundaries with substantial compliance infrastructure requirements.
- Online Casinos:Browser and native application platforms with remote verification protocols. European Union member states through EGBA-coordinated frameworks concentrate demand where multi-jurisdiction licensing reduces fragmentation costs.
- Mobile Gaming:Smartphone-optimized wagering interfaces with biometric authentication layers.
- Social Gaming:Free-to-play mechanics with virtual currency monetization serving regulated-adjacent acquisition.
Land-Based Casinos retain volume leadership. Online Casinos gain share fastest as US state liberalization accelerates.
End User:
Facility type determines capital intensity thresholds and regulatory scrutiny depth.
- Casinos:Full-service integrated resorts and standalone gaming venues with comprehensive amenity bundles. Macau's Gaming Inspection and Coordination Bureau mandates minimum capital reserves and table allocation formulas for these operators.
- Gaming Lounges:Limited-machine venues with restricted game type authorization and shorter operating hours.
- Betting Shops:High-street retail terminals focused on sports wagering with over-the-counter service models.
- Private Clubs:Membership-restricted venues with bespoke table minimums and personalized host services.
Casinos dominate category volume. Gaming Lounges expand most quickly in Southeast Asian markets with emerging digital wallet penetration.
Technology:
Adoption timelines separate proven infrastructure investments from experimental platform layers.
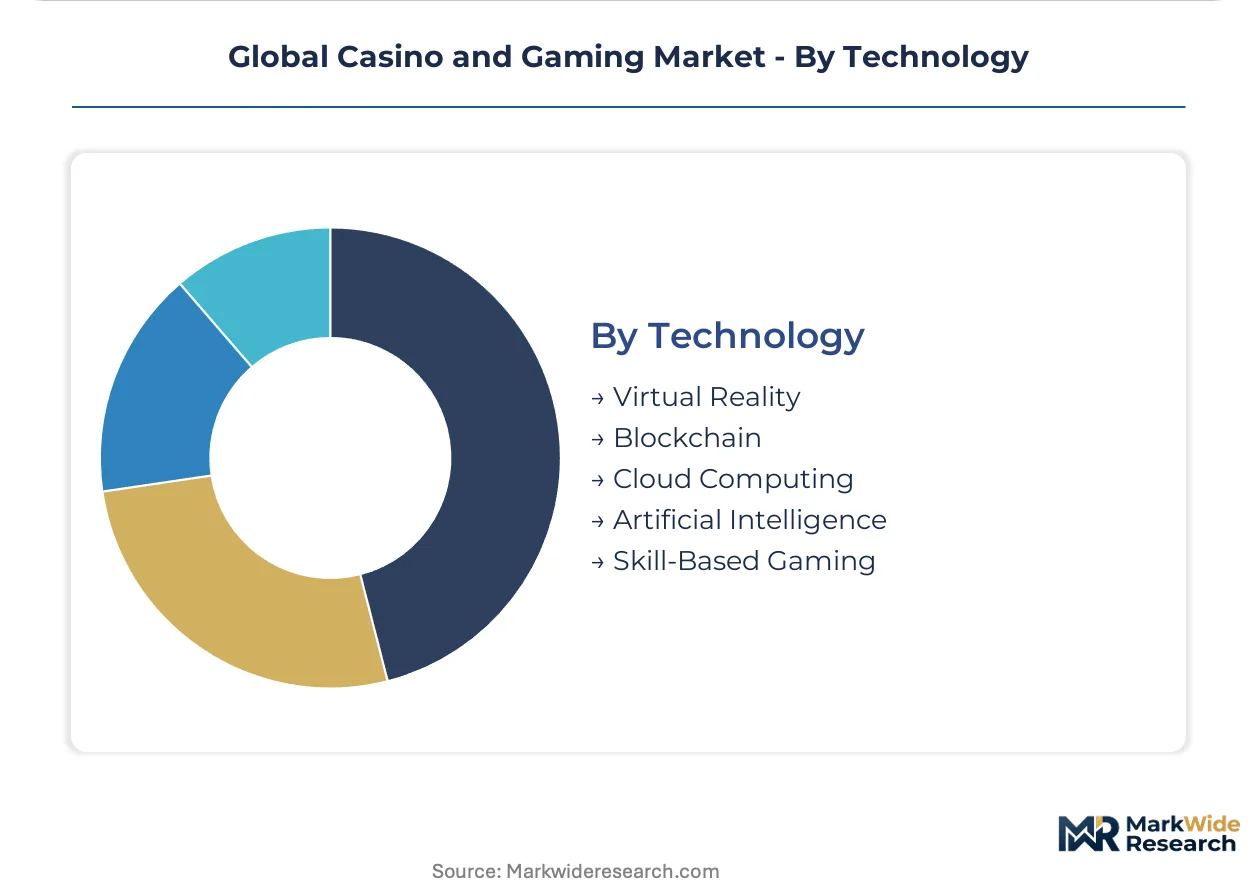
- Virtual Reality:Immersive headset-based casino environments with spatial wagering interfaces. Early deployment concentrates in social gaming as real-money regulators await responsible gaming control validation.
- Blockchain:Distributed ledger systems for provable fairness verification and cryptocurrency settlement. Latin American and European mid-tier platforms adopt these for player acquisition differentiation in saturated markets.
- Cloud Computing:Elastic infrastructure for traffic spike absorption and geographic content distribution.
- Artificial Intelligence:Player behavior analytics with deposit limit automation and self-exclusion triggering.
- Skill-Based Gaming:Outcome-contest hybrids blending chance mechanics with player proficiency elements.
Cloud Computing leads category deployment. Blockchain climbs fastest as regulatory frameworks mature for cryptocurrency settlement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Macau concentrates the highest gaming revenue per capita globally, while Las Vegas anchors North American integrated resort development. European digital licensing frameworks attract platform investment. Southeast Asian mobile payment expansion unlocks underbanked player populations.
United States
State-by-state sports betting liberalization drives terminal deployment across Nevada, New Jersey, and emerging Midwest markets. The FTC monitors sweepstakes mechanics for consumer deception while state gaming commissions enforce territorial licensing exclusivity. Las Vegas Strip operators anchor premium hospitality-gaming bundles with destination entertainment infrastructure.
China
Macau's Cotai Strip operators pivot toward mass-table gaming and non-gaming hospitality as VIP junket volumes decline. The Ministry of Culture and Tourism restricts cross-border marketing of gambling services, constraining operator expansion tactics. The Gaming Inspection and Coordination Bureau mandates minimum capital reserves and table allocation formulas for concessionaires.
United Kingdom
Mature online casino frameworks concentrate platform development investment from remote gaming operators. The Gambling Commission enforces affordability checks and source-of-funds verification under tightening consumer protection mandates. London serves as headquarters for several pan-European digital wagering platforms seeking multi-jurisdiction licenses.
Singapore
Integrated resort operators diversify revenue toward convention infrastructure and premium hospitality as gaming volumes normalize. The Casino Regulatory Authority enforces entry levies for local residents and mandatory exclusion programs. Marina Bay and Sentosa anchor the city-state's concentrated gaming supply with non-gaming amenity expansion.
Australia
Electronic gaming machine networks dominate regional and metropolitan venue revenue across New South Wales and Victoria. State-level regulators impose harm minimization mandates including pre-commitment systems and mandatory closure periods. Crown Resorts and competitor operators face intensified compliance scrutiny in Melbourne and Sydney cluster markets.
Global Casino and Gaming Market Competitive Landscape
Portfolio diversification dominates the current landscape as operators bridge physical casino floors with digital wagering platforms. The vendor base organizes around three strategic archetypes: integrated resort developers with hospitality-gaming bundles, omnichannel platform operators synchronizing loyalty across channels, and regional specialists concentrated in single jurisdictions. M&A activity and technology licensing partnerships represent the dominant competitive vectors as firms acquire digital capabilities and geolocation verification assets.
Within the integrated resort tier, MGM Resorts International and Las Vegas Sands Corporation exemplify scale-driven hospitality-gaming bundling across Las Vegas and Asian markets. Caesars Entertainment occupies a position bridging physical casino floors with digital sportsbook platforms through unified loyalty architecture. Galaxy Entertainment Group anchors the Macau-centric specialist archetype with concentrated Cotai Strip presence and mass-market diversification.
| Leading Market Players |
|---|
| MGM Resorts International |
| Las Vegas Sands Corporation |
| Wynn Resorts |
| Caesars Entertainment |
| Galaxy Entertainment Group |
| Melco Resorts & Entertainment |
| SJM Holdings Limited |
| Genting Berhad |
| Crown Resorts |
| Others |
Supply & Pricing Matrix
Captive server-based gaming networks anchor supply positions for integrated resort operators while simultaneously determining pricing power across hardware procurement and digital platform licensing tiers. This backward integration into certified random number generation hardware and geolocation verification systems concentrates cost control among Macau concessionaires and Las Vegas Strip anchors, insulating premium hospitality-gaming bundles from commodity volatility in electronic gaming machine replacement cycles.
Pricing Analysis
Volume leadership in slot machines compresses per-unit margins while sports betting terminals command premium pricing through real-time odds integration and cashless wallet connectivity. Three-tier pricing structure across premium hospitality bundles, standard electronic gaming machine configurations, and economy-tier social gaming platforms differentiates operator revenue streams. Pricing pressure stems from AML compliance infrastructure expenditures mandated by EU remote gaming protocols. Mass-market gaming segments exhibit highest price sensitivity; VIP and premium hospitality tiers retain pricing inelasticity through destination entertainment anchoring.
Supply Chain Analysis
Regional distribution centers in Nevada, Macau, and Singapore coordinate hub-and-spoke patterns for electronic gaming machine deployment and spare parts logistics. Manufacturing concentration in Taiwan, South Korea, and Japan supplies certified random number generation chipsets and display panel assemblies. Raw material dependencies include semiconductor wafers, specialized gaming cabinet alloys, and secure biometric authentication modules. Single-source vulnerability in geolocation verification firmware creates exposure to regulatory recertification delays. Distribution runs through authorized service integrators with territorial licensing exclusivity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory licensing scarcity constrains platform development capacity, propping pricing power for authorized operators across EU member states and US tribal gaming jurisdictions. This supply bottleneck intensifies returns for incumbents holding multi-jurisdiction certifications while elevating barriers for unlicensed market participation.
For Market Incumbents: Anticipate platform consolidation pressure from omnichannel loyalty architectures bridging physical casino floors with digital sportsbook environments. Defensive priorities center on deepening backward integration into geolocation verification assets and securing EGBA-coordinated multi-jurisdiction licenses before regulatory fragmentation accelerates. Capacity additions in Southeast Asian digital wallet corridors anchor next-generation player acquisition infrastructure. For New Entrants and Emerging Players: Enter via social gaming acquisition funnels in prohibitionist enforcement corridors where real-money gaming prohibition elevates skill-based tournament formats. White-space concentration appears in blockchain-based provable fairness verification for mid-tier European and Latin American platforms. Subscription-based virtual currency bundling in Japanese and South Korean mobile markets offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in platform technology licensing to integrated resort operators seeking omnichannel synchronization capabilities. Long-term viability favors acquisition targets with segregated AI-driven personalization engines and responsible gaming automation architectures compliant with EU AI Act risk classifications. The signal to watch is regulatory liberalization velocity in US state commissions authorizing real-time in-play sports wagering markets.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies player account systems across physical casino floors and digital wagering environments under EGBA-coordinated frameworks. |
| Blockchain Verification Deployment | Accelerates player acquisition velocity in saturated European markets through provable fairness differentiation. |
| Geographic Expansion | Captures underbanked player populations via digital wallet penetration across Southeast Asian mobile corridors. |
| Regulatory Certification Investment | Secures multi-jurisdiction licensing under tightening EU anti-money laundering protocols for remote gaming operators. |
| Strategic Partnership | Anchors premium hospitality-gaming bundles through destination entertainment infrastructure in Las Vegas and Macau Cotai Strip clusters. |
Research Methodology
Multi-period observation of regulatory licensing velocity, electronic gaming machine replacement cycles, and digital wallet penetration rates anchored the trend analysis, supplemented by interviews with integrated resort operations executives, state gaming commission administrators, platform technology architects, and digital payment infrastructure specialists. Secondary validation drew from EGBA coordination bulletins, Macau Gaming Inspection and Coordination Bureau concessionaire filings, US state gaming commission regulatory dockets, and SEC 10-K disclosures from listed operators. Bottom-up segment sizing triangulated against top-down market aggregation across the analysis window.
Segment-weighting approaches distributed value and volume projections across product type, application channel, end-user facility tier, and technology adoption trajectory dimensions. CAGRs derived from regression analysis of historical licensing liberalization patterns and installed base expansion rates. Forecast inputs incorporated server-based gaming network deployment schedules and geolocation verification system certification timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory reversal conditions or accelerated prohibitionist enforcement in key outbound tourism markets. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
VR Racing Gaming Market
Gaming
India Gaming Market
Gaming
SLG Game Market
Gaming
Europe Serious Gaming Market
Gaming
Gaming Gadgets Market
Gaming
RPG Games Market
Gaming
Board Games Market
Gaming
Metaverse in Gaming Market
Gaming
Mobile MOBA Games Market
Gaming
Europe Video Game Software Market
Gaming
Shooter Game Market
Gaming
Global Game Testing Service Market
Gaming
Global Gaming Market
Gaming
Global Online Simulation Games Market
Gaming
Lottery Market
Gaming
PC Games Market