
 Australia Casino Tourism Market | 2026-2036
Australia Casino Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Casino Tourism Market Outlook
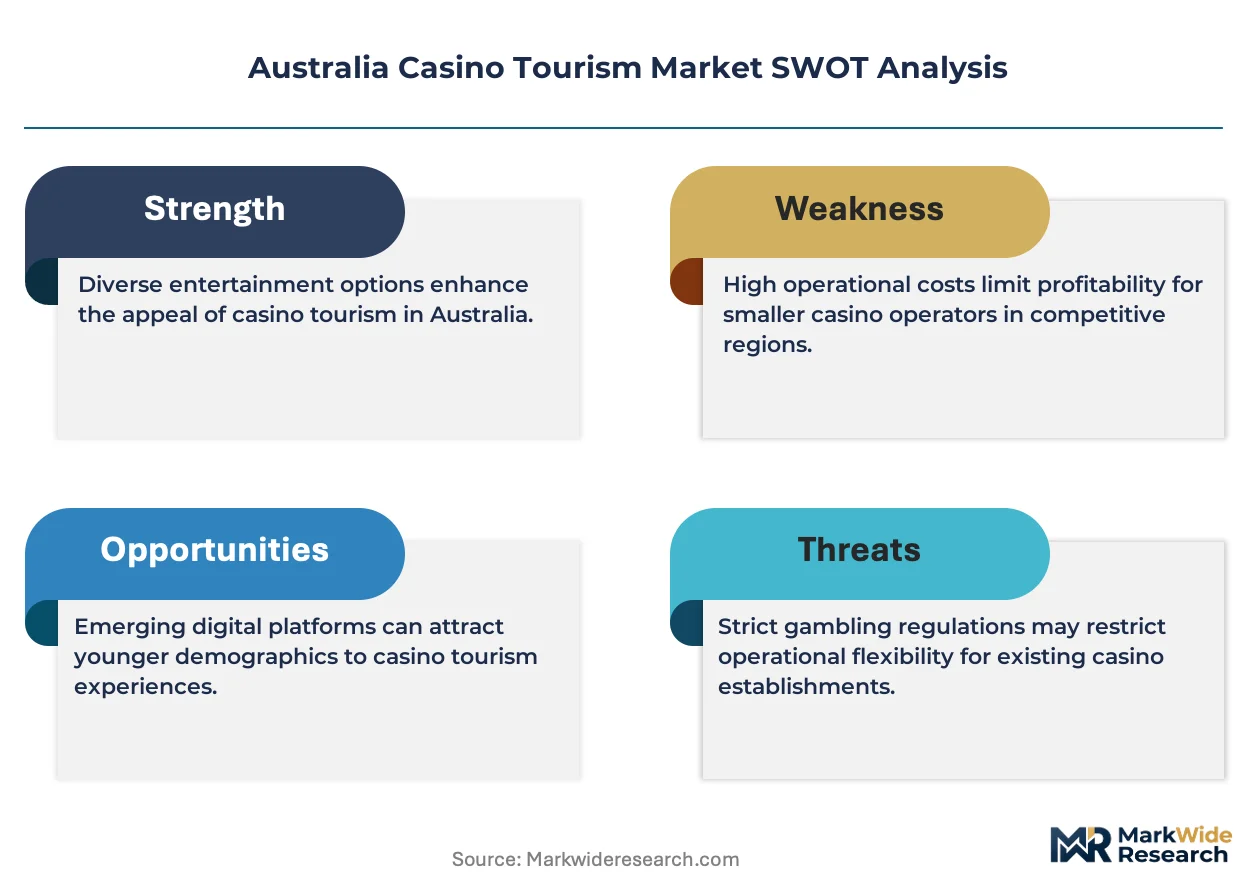
Digital wagering platforms are rebalancing spend away from physical gaming floors toward hybrid experiences that blend on-property hospitality with remote engagement. Crown Resorts Limited leverages its vertically integrated entertainment precincts to sustain premium yield per visitor across Melbourne, Perth, and Sydney. The Star Entertainment Group Ltd anchors its competitive position through harbour-front real estate and convention-linked visitation. SkyCity Entertainment Group differentiates via its Adelaide and Auckland cross-Tasman network, capturing transit-oriented leisure demand.
Australia casino tourism denotes the structured travel segment where visitors journey specifically to participate in legal gambling activities at licensed venues, encompassing integrated resorts with hotel, retail, and entertainment functions alongside standalone gaming houses. Properties typically operate under state-specific Casino Control Acts with mandated responsible gambling protocols, surveillance standards, and taxation schedules calibrated to gross gaming revenue. International tourists represent the fastest-expanding visitor category, drawn by visa-accessible entertainment visas and direct aviation links from Singapore, China, and India. Integrated resorts command the dominant share of capital investment and regulatory attention, while standalone casinos occupy mature, lower-growth positions in regional markets. Service offerings cluster around gaming revenue, though accommodation and dining margins expand as operators diversify from pure wagering dependence.
The Australian Communications and Media Authority enforces Interactive Gambling Act provisions that constrain online casino advertising and offshore operator access, directly shaping domestic platform economics. State casino regulators in Victoria, New South Wales, and Queensland impose fit-and-proper person tests, mandatory pre-commitment systems, and anti-money laundering protocols that elevate compliance costs for license holders. The National Consumer Protection Framework for Online Wagering harmonizes cross-border standards without displacing state-level enforcement primacy. Stakeholders must monitor regulatory divergence between states as licensing renewal timelines approach and responsible gambling mandates tighten.
Market Dynamics
Interactive Gambling Act amendments are compressing advertising margins while state-level casino licensing reforms force capital reallocation toward compliance infrastructure and surveillance upgrades across Queensland and New South Wales.
Growth Catalysts
- Entertainment Visa Accessibility:Streamlined visa pathways from Singapore, China, and India are pulling high-yield international visitation toward integrated resort precincts in Melbourne and Sydney.
- Integrated Resort Capital Deployment:Mixed-use developments combining gaming floors with convention centers and luxury accommodation are extending visitor dwell time and per-capita spend.
- Cross-Tasman Aviation Links:Expanded direct routes between Adelaide, Auckland, and Asian hubs are capturing transit-oriented leisure demand for SkyCity's dual-venue network.
Market Restraints
- Compliance Cost Escalation:Victoria's Casino Control Act mandates and New South Wales fit-and-proper person tests are elevating licensing renewal expenditures.
- Digital Wagering Substitution:Remote betting platforms constrained by ACMA enforcement still capture discretionary gaming spend away from physical floors.
- AML Protocol Burden:Anti-money laundering surveillance standards require continuous technology refresh cycles that strain regional operator balance sheets.
Strategic Opportunities
- Queensland Expansion Corridors:Gold Coast and Brisbane integrated resort zones offer underdeveloped positions relative to saturated southern markets.
- Convention-Linked Visitation:Hybrid business-leisure travel formats are opening revenue streams beyond pure gaming dependence at harbour-front precincts.
- Responsible Gambling Technology:Pre-commitment system mandates are creating procurement demand for biometric player-tracking and real-time intervention platforms.
Industry Challenges
- Surveillance Technology Integration:Legacy analog camera networks at mature regional properties require complete replacement to meet state regulator real-time monitoring standards.
- Specialized Compliance Talent Scarcity:Shortages of AML analysts and responsible gambling program managers are extending recruitment timelines and inflating compensation packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Casino Tourism Market |
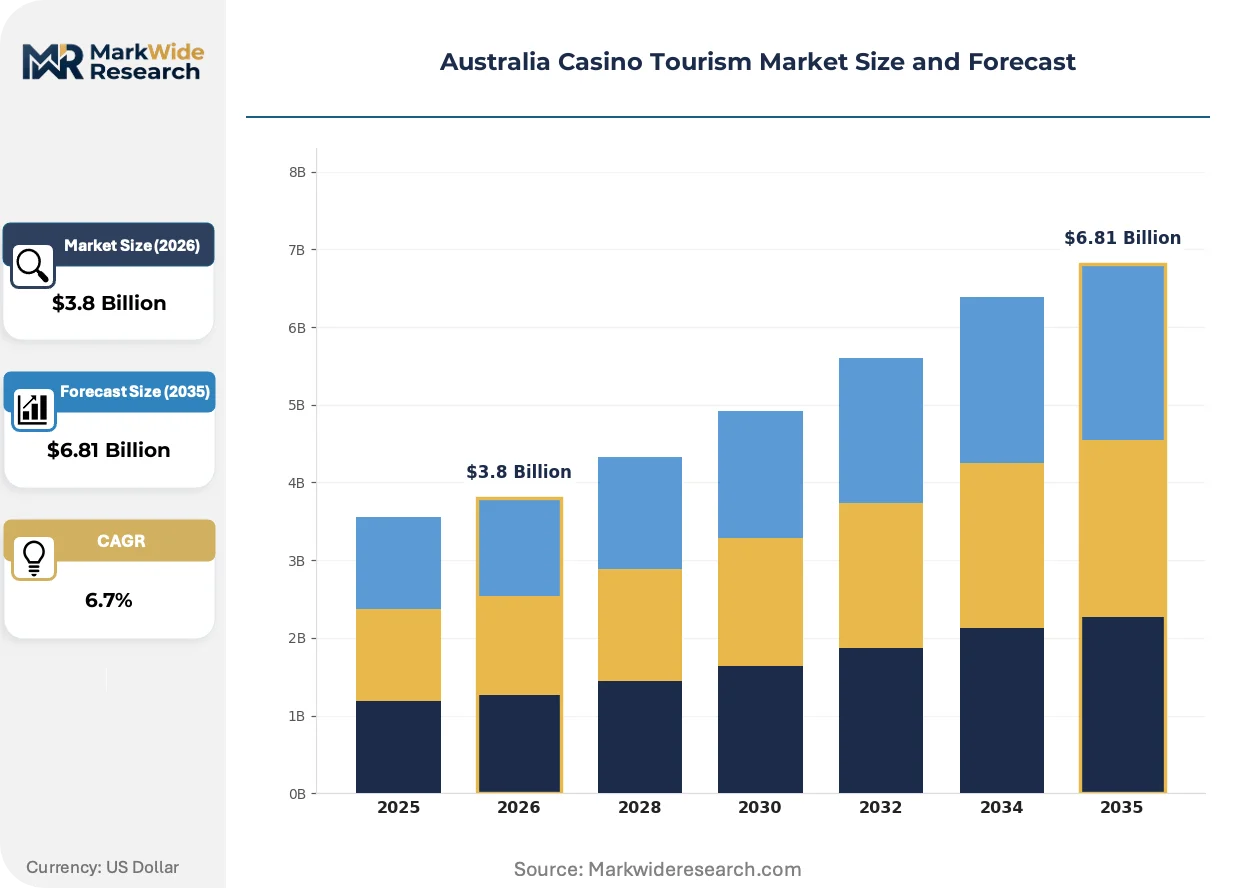
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tourist Type: Domestic Visitors, International Tourists, VIP Players, Group Travelers Casino Type: Integrated Resorts, Standalone Casinos, Riverboat Casinos, Online Casinos Service Offering: Gaming, Accommodation, Dining, Entertainment Customer Experience: Loyalty Programs, Personalization, Onsite Amenities, Event Packages |
| Companies Covered | Crown Resorts Limited, The Star Entertainment Group Ltd, Aristocrat Leisure Ltd, The Lottery Corporation Ltd, Tabcorp Holdings Limited, SkyCity Entertainment Group, Treasury Brisbane, Reef Casino Trust, Crown Perth, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Casino Tourism Market Strategic Shifts
Digital wagering platforms are compressing traditional gaming floor economics while forcing integrated resorts to reconceptualize on-property experiences as hospitality-first destinations with wagering as one component among many.
Biometric player identification is electrifying responsible gambling enforcement across Australian casino floors. The technology authenticates patrons at entry points and gaming tables while linking behavior to pre-commitment limits in real time. State regulators in Victoria and New South Wales are mandating phased deployment, compressing vendor selection timelines for resort operators.
The National Consumer Protection Framework for Online Wagering is harmonizing cross-border standards without displacing state-level enforcement primacy. This creates dual compliance obligations where operators must satisfy both federal advertising constraints and state-specific harm minimization protocols. Queensland properties face the steepest adaptation curve given recent licensing framework overhauls.
Visitation patterns are pivoting toward experience-stacking where travelers bundle gaming with dining, entertainment, and accommodation in single itineraries. Integrated resorts in Sydney's Barangaroo precinct and Melbourne's Southbank are responding by unbundling and rebundling packages through direct booking channels. This behavioral shift is most pronounced among inbound tourists from Singapore and India seeking multi-day entertainment itineraries.
Australia Casino Tourism Market Segmentation
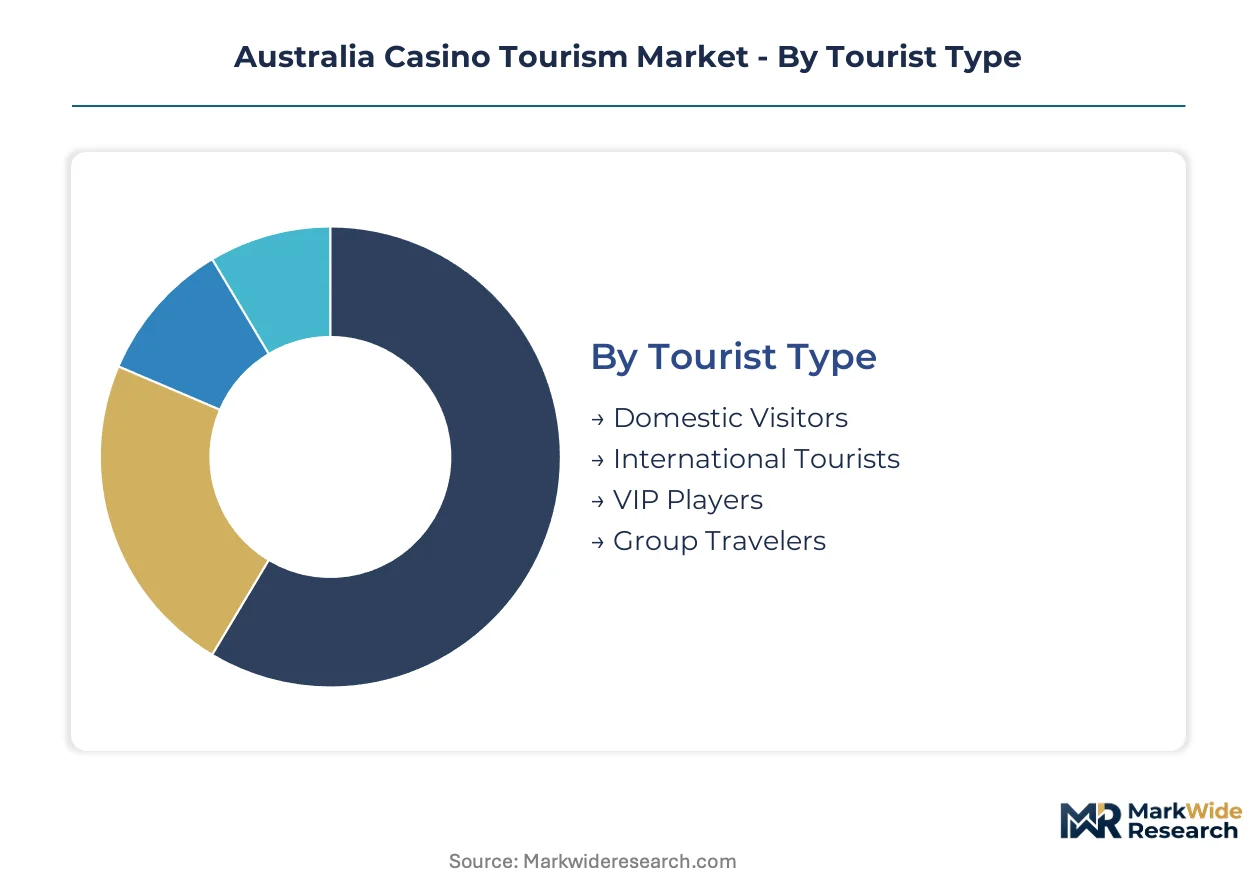
Segmentation in Australia's casino tourism market reveals distinct spending patterns, regulatory exposure, and yield profiles across visitor categories and venue formats. Understanding these divisions enables operators to calibrate capital deployment, compliance infrastructure, and service bundling to capture high-value visitation while managing state-level licensing obligations.
Tourist Type:
Visitor origin and travel format determine yield per capita, visa requirements, and length of stay across Queensland and New South Wales properties.
- Domestic Visitors:Australian residents from interstate markets drive weekend and holiday-period visitation. Melbourne and Sydney properties capture recurring spend from drive-in markets across Victoria and New South Wales, though regulatory scrutiny on responsible gambling protocols intensifies for repeat local patrons.
- International Tourists:Visa-accessible travelers from Singapore, China, and India sustain the fastest-expanding visitor category. Streamlined entertainment visa pathways pull high-yield multi-day itineraries toward integrated resorts in Barangaroo and Southbank precincts.
- VIP Players:High-net-worth individuals command premium yield through private gaming salons and dedicated concierge services. State fit-and-proper person tests and anti-money laundering surveillance elevate compliance costs for operators serving this segment.
- Group Travelers:Packaged tour cohorts from Asian source markets deliver volume throughput at lower per-capita margins. Convention-linked itineraries at harbour-front precincts extend dwell time through bundled hospitality offerings.
Domestic visitors lead volumes today; international tourists are gaining share fastest.
Casino Type:
Venue format dictates capital intensity, regulatory tier, and diversification potential across state licensing frameworks.
- Integrated Resorts:Mixed-use developments combining gaming floors with hotels, retail, and convention facilities dominate capital deployment. Melbourne's Crown complex and Sydney's Barangaroo precinct concentrate regulatory attention and premium yield extraction through extended visitor dwell time.
- Standalone Casinos:Gaming-focused venues in mature regional markets occupy lower-growth positions with reduced compliance burdens. These properties face substitution pressure from digital wagering platforms constrained by ACMA enforcement.
- Riverboat Casinos:Water-based gaming operations operate under restricted state licensing regimes with limited geographic distribution. Regulatory novelty and tourism positioning differentiate these venues in specific Queensland corridors.
- Online Casinos:Remote platforms fall under Interactive Gambling Act provisions that constrain advertising and offshore operator access. Domestic platform economics remain compressed despite state-level harm minimization mandates.
Integrated resorts command investment focus; online platforms face the steepest regulatory headwinds.
Service Offering:
Revenue stream composition determines margin stability and gaming revenue dependence across operator portfolios.
- Gaming:Table games and electronic gaming machines generate core revenue subject to state taxation schedules calibrated to gross gaming revenue. Pre-commitment system mandates and biometric player-tracking requirements reshape floor economics.
- Accommodation:Luxury hotel inventory extends visitor length of stay and cross-sells dining and entertainment. Sydney and Melbourne properties leverage harbour-front and Southbank real estate to capture premium rate premiums.
- Dining:Restaurant and beverage operations expand margins as operators diversify from pure wagering dependence. Celebrity chef partnerships and integrated resort precinct positioning drive destination dining demand.
- Entertainment:Theatres, nightclubs, and event spaces complete experience-stacking itineraries for inbound tourists. Direct booking channel unbundling and rebundling responds to Singapore and India source market preferences.
Gaming remains the revenue anchor; accommodation and dining margins are expanding most quickly.
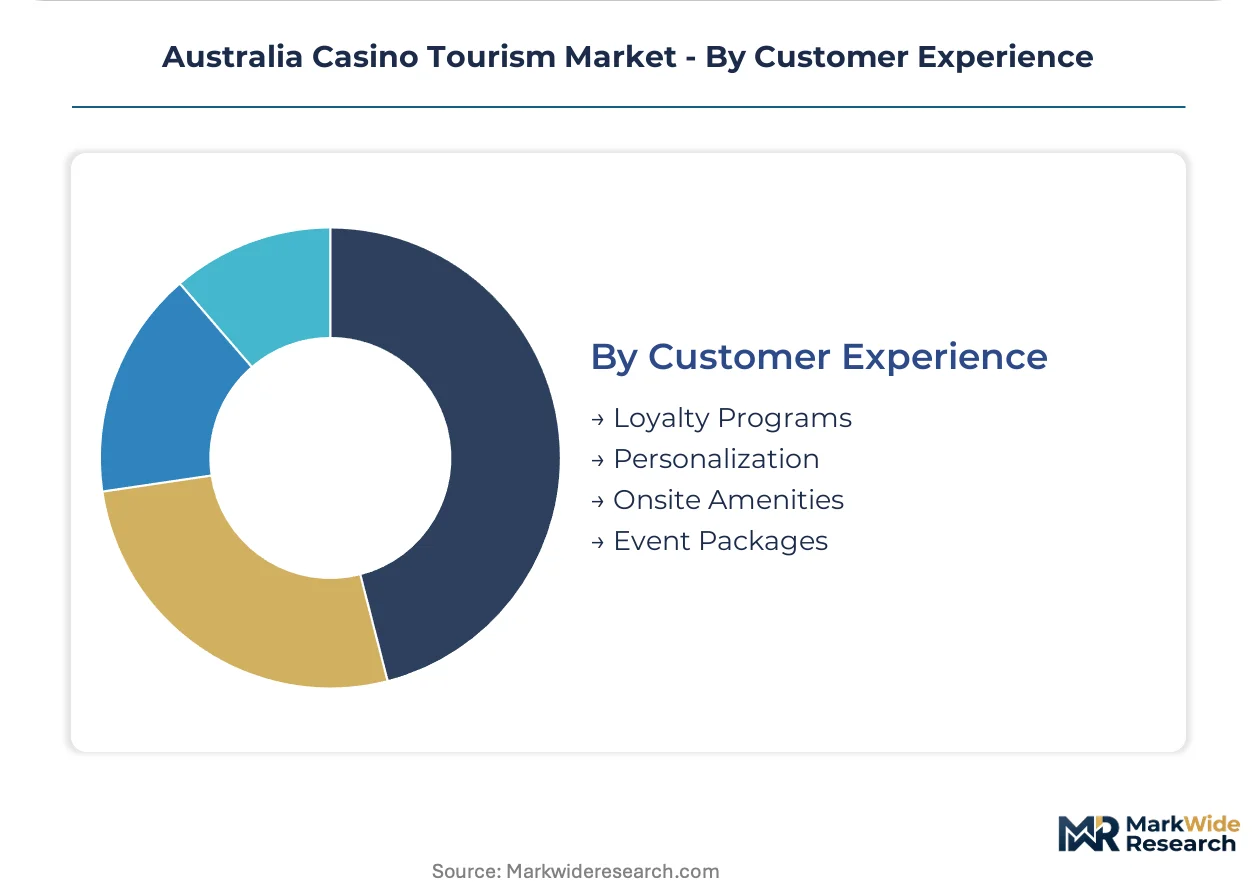
Customer Experience:
Engagement architecture separates premium yield extraction from commodity visitation across competitive precincts.
- Loyalty Programs:Tiered membership systems track wagering behavior and reward frequency with complimentary services. Biometric identification integration links program benefits to real-time pre-commitment limit enforcement.
- Personalization:Data-driven service customization targets high-value patrons with tailored hospitality offerings. AML surveillance protocols and responsible gambling mandates constrain data utilization scope.
- Onsite Amenities:Spa, retail, and recreational facilities extend property dwell time beyond gaming floor engagement. Adelaide and Auckland cross-Tasman networks capture transit-oriented leisure demand through amenity differentiation.
- Event Packages:Bundled hospitality for sporting fixtures, concerts, and conventions attracts non-gaming expenditure. Queensland Gold Coast and Brisbane zones offer underdeveloped positions relative to saturated southern markets.
Loyalty programs retain the largest installed base; personalization features are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Melbourne's Crown complex anchors capital deployment and regulatory scrutiny across Australia's casino tourism landscape. State-level licensing reforms and integrated resort expansions are redistributing visitation patterns toward Queensland corridors. The analysis examines five sub-regional markets where operator compliance burdens and infrastructure investments concentrate competitive positioning.
New South Wales
Sydney's Barangaroo precinct concentrates premium yield extraction through harbour-front real estate and convention-linked visitation. The state's fit-and-proper person tests and Casino Control Act mandates elevate compliance costs for license holders. Operators deploy capital toward surveillance technology upgrades to satisfy real-time monitoring standards imposed by the state regulator.
Victoria
Melbourne's Southbank entertainment district sustains recurring spend from drive-in interstate markets across Victoria and adjacent states. The Victorian Commission for Gambling and Liquor Regulation enforces mandatory pre-commitment systems and biometric player-tracking requirements. Crown Melbourne anchors this sub-region with vertically integrated hospitality precincts extending visitor dwell time beyond gaming floors.
Queensland
Gold Coast and Brisbane integrated resort zones capture underdeveloped positions relative to saturated southern markets. Recent licensing framework overhauls create the steepest adaptation curve for operators harmonizing federal and state compliance obligations. Treasury Brisbane and transit-oriented leisure demand anchor competitive positioning in this expansion corridor.
Western Australia
Perth's isolated geographic position sustains captive domestic visitation with limited substitution from interstate competitors. The state's casino regulator imposes surveillance standards and responsible gambling protocols calibrated to gross gaming revenue taxation schedules. Crown Perth dominates this sub-region with integrated resort amenities targeting fly-in leisure demand from Asian source markets.
South Australia
Adelaide's casino precinct leverages cross-Tasman aviation links to capture transit-oriented leisure demand between Australia and New Zealand. SkyCity Entertainment Group operates the dominant venue with dual-venue network advantages across the Adelaide-Auckland corridor. The state's regulatory environment maintains lower compliance burdens relative to eastern seaboard jurisdictions.
Australia Casino Tourism Market Competitive Environment
Compliance infrastructure investment dominates the current landscape as operators reallocate capital toward surveillance upgrades and biometric player-tracking systems. The vendor base concentrates around three integrated resort operators controlling premium yield extraction across Melbourne, Sydney, and Perth. Two strategic archetypes define competitive positioning: vertically integrated entertainment precincts with hospitality-first diversification, and regional standalone venues facing digital wagering substitution pressure. M&A consolidation and responsible gambling technology procurement represent the dominant competitive moves reshaping operator balance sheets.
Among Australia-based integrated resort operators, Crown Resorts Limited and The Star Entertainment Group Ltd exemplify the premium-tier archetype through harbour-front and Southbank real estate concentration. SkyCity Entertainment Group occupies a position within the cross-Tasman network specialist tier, leveraging Adelaide and Auckland dual-venue presence to capture transit-oriented demand. Aristocrat Leisure Ltd represents the gaming technology supply segment, anchoring electronic gaming machine and platform provision to venue operators without direct casino property ownership. These three company structures illustrate the bifurcation between property-owning resort operators and technology-enabling suppliers.
| Leading Market Players |
|---|
| Crown Resorts Limited |
| The Star Entertainment Group Ltd |
| Aristocrat Leisure Ltd |
| The Lottery Corporation Ltd |
| Tabcorp Holdings Limited |
| SkyCity Entertainment Group |
| Treasury Brisbane |
| Reef Casino Trust |
| Crown Perth |
| Others |
Value Chain & Pricing Dynamics
Construction cost indices for integrated resort developments in Australia cascade through operator procurement decisions into tiered hospitality pricing across Melbourne, Sydney, and Brisbane. Labor and materials inflation in Queensland and New South Wales compresses margins on mid-market accommodation packages while premium suites at harbour-front properties absorb cost pass-through through yield management systems.
Pricing Analysis
Input-cost pass-through dominates casino tourism pricing as construction materials and specialized compliance technology inflate capital deployment budgets. Three-tier pricing structure across premium, standard, and economy levels separates VIP gaming salon access from convention-linked group packages and domestic drive-in visitation. Pricing pressure stems from biometric surveillance mandates and AML system refresh cycles mandated by Victoria's Casino Control Act and New South Wales fit-and-proper protocols. Domestic weekend visitors exhibit highest price sensitivity while international entertainment visa holders from Singapore and India demonstrate lowest elasticity.
Supply Chain Analysis
Warehouse-distribution layers for casino hospitality procurement concentrate through Sydney and Melbourne regional distribution centers serving integrated resort precincts. Supply concentration draws from China for electronic gaming machine components, Malaysia for luxury hotel furnishings, and New Zealand for cross-Tasman food and beverage inputs. Single-source vulnerability in biometric player-tracking technology creates procurement risk as state regulators mandate phased deployment timelines. Distribution runs through hub-and-spoke patterns anchored by Crown Melbourne and Sydney Barangaroo procurement consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia casino tourism represents a late-cycle quality story where visitation yield depends on premium hospitality specifications rather than pure gaming floor expansion. Inbound tourists from Asian markets increasingly demand integrated entertainment experiences over standalone wagering venues.
For Market Incumbents: Lock in compliance infrastructure advantages through accelerated biometric surveillance deployment ahead of Queensland licensing renewal timelines. Crown Resorts Limited and The Star Entertainment Group Ltd should consolidate procurement scale across Melbourne, Sydney, and Perth to offset AML analyst talent scarcity. Vertical integration into responsible gambling technology platforms creates defensive moats against regulatory escalation. For New Entrants and Emerging Players: Launch via underdeveloped Queensland expansion corridors where Gold Coast and Brisbane integrated resort zones offer lower competitive density than saturated southern markets. Target convention-linked hybrid business-leisure formats that extend visitor dwell time beyond pure gaming dependence. White-space exists in transit-oriented leisure capture between Adelaide and Auckland where SkyCity Entertainment Group maintains incumbent position. For Investors and Strategic Acquirers: Consolidation pressure builds where regional standalone casinos face digital wagering substitution and cannot fund surveillance technology refresh cycles. Acquisition targets include mature properties with harbour-front real estate optionality and underutilized convention infrastructure. Monitor Queensland licensing framework implementation as inflection indicator for regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Surveillance Deployment | Victoria and New South Wales mandates accelerate procurement demand for real-time player-tracking platforms. |
| Queensland Integrated Resort Expansion | Gold Coast and Brisbane zones capture underdeveloped positions relative to saturated Melbourne and Sydney markets. |
| Cross-Tasman Network Consolidation | Adelaide-Auckland aviation links enable SkyCity Entertainment Group to capture transit-oriented leisure demand. |
| Convention Infrastructure Investment | Harbour-front precincts in Sydney extend visitor dwell time through hybrid business-leisure bundling. |
| Responsible Gambling Technology Procurement | Pre-commitment system mandates create vendor opportunity for real-time intervention and biometric authentication. |
Study Parameters
Multiple input streams — regulatory filings with state casino control authorities, operator capital expenditure disclosures, and aviation route data — were reconciled through bottom-up and top-down triangulation. Primary interviews with integrated resort operations directors, compliance officers, state gambling regulators, and tourism board executives informed qualitative assessment. Secondary validation drew from Australian Communications and Media Authority enforcement records, state Casino Control Act amendments, convention bureau visitation statistics, and hospitality industry procurement databases.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning tourist origin, venue format, service offering mix, and customer experience architecture. Modeled CAGRs derived from historical gross gaming revenue taxation schedules, capital deployment timelines for integrated resort expansions, and inbound aviation capacity growth from Singapore, China, and India. Forecast inputs incorporated regulatory compliance cost trajectories and biometric technology procurement curves mandated by state-level responsible gambling frameworks.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Interactive Gambling Act amendment severity and Queensland licensing framework implementation delays. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Mobile Game Controller Market
Gaming
Gaming Chair Market
Gaming
Latin America Gaming Headsets Market
Gaming
Asia-Pacific in-Game Advertising Market
Gaming
LAMEA Gaming Posters Market
Gaming
RPG Games Market
Gaming
United States Virtual Reality Gaming Market
Gaming
Middle East and Africa Gaming Headsets Market
Gaming
Metaverse in Gaming Market
Gaming
Global Electronic Table Games (ETG) Market
Gaming
Europe Video Game Software Market
Gaming
Mobile Game Software Market
Gaming
VR Racing Gaming Market
Gaming
Global Trading Card Games Market
Gaming
Global Game Testing Service Market
Gaming
Game Applications Market