
 Gaming Console Market | 2026-2036
Gaming Console Market Size, Share, and Industry Trends Forecast 2026-2036
Gaming Console Market Analysis
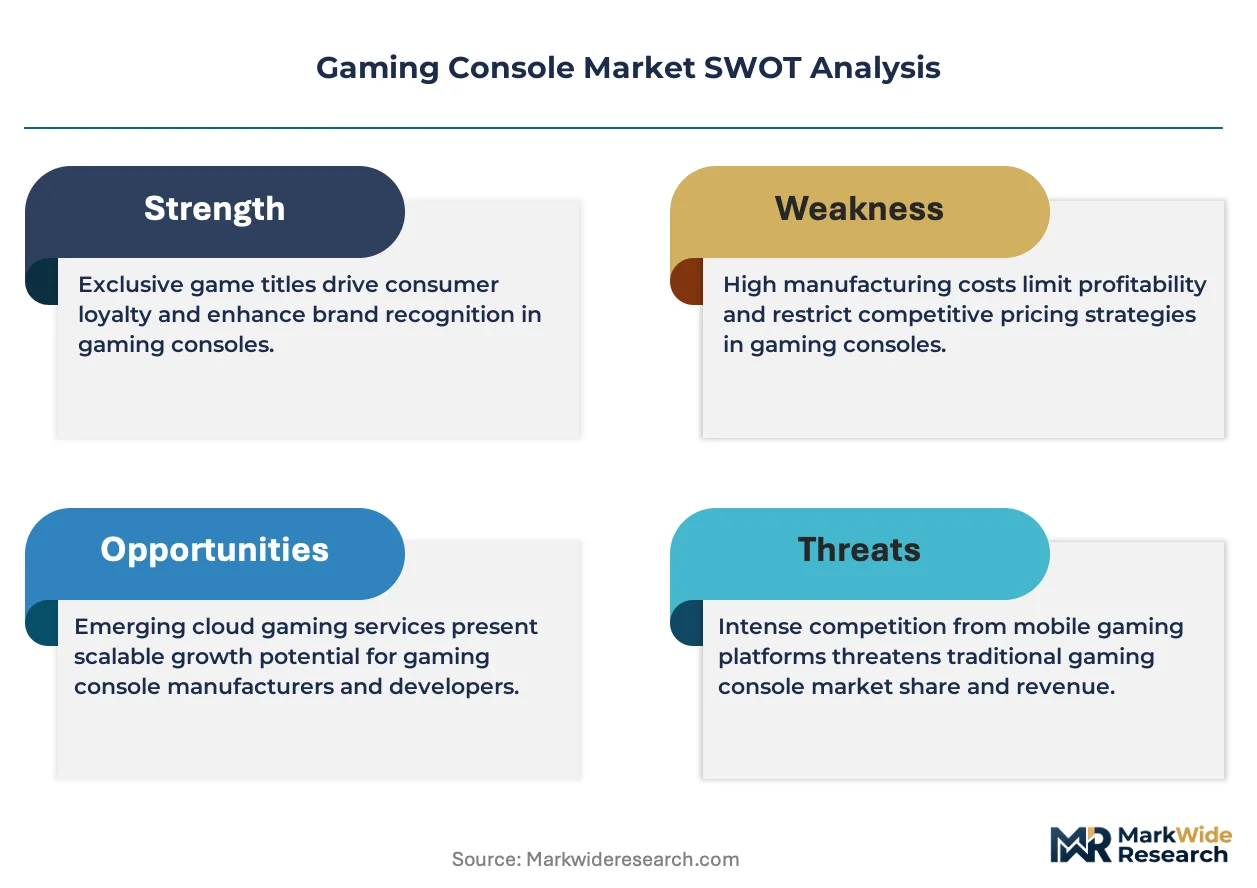
Subscription-to-hardware bundling is realigning how consumers evaluate total cost of ownership against standalone device purchases. Sony Group Corporation leverages its PlayStation Plus ecosystem to anchor recurring revenue alongside cyclical hardware refreshes. Nintendo Co., Ltd. differentiates through hybrid portability that sustains premium pricing across home and mobile contexts. Microsoft Corporation competes via Game Pass integration, extending software reach across PC and cloud endpoints beyond proprietary hardware.
A gaming console is a specialized computing device built around custom accelerated processing units, high-bandwidth memory architectures, and proprietary operating systems engineered for real-time interactive entertainment rendering. These systems integrate thermal management solutions, solid-state storage subsystems, and wireless connectivity protocols to deliver sub-20 millisecond input latency for commercial consumer entertainment. Home consoles occupy the dominant revenue position within product type segmentation due to higher average selling prices and accessory attach rates. Hybrid systems represent the fastest structural growth vector as consumers prioritize single-device flexibility across stationary and portable use cases. Subscription services concentrate margin pools through recurring billing models that reduce cyclical revenue volatility inherent to hardware launch windows.
The Federal Communications Commission governs wireless spectrum allocation for controller and online connectivity features in the United States, while the EPA administers energy efficiency standards affecting power supply design and standby consumption profiles. The EU Green Deal and F-Gas Regulation constrain refrigerant choices in thermal management systems and mandate recyclable packaging percentages for electronics sold across European member states. Japan's Ministry of Economy, Trade and Industry oversees domestic content rating frameworks and semiconductor supply chain security protocols that influence regional production decisions. Stakeholders must monitor how evolving right-to-repair legislation across multiple jurisdictions reshapes aftermarket service economics and hardware modularity requirements.
Market Dynamics
Cloud streaming architectures are decoupling software distribution from proprietary hardware ownership, forcing incumbents to rebuild margin structures around recurring subscription pools rather than cyclical console launches.
Growth Catalysts
- Subscription bundling models:Recurring revenue frameworks reduce purchase-friction for software libraries. Hardcore gamers commit to annual billing cycles that stabilize platform cash flows.
- EU Green Deal packaging mandates:Recyclable materials requirements accelerate design-for-disassembly protocols. Manufacturers capture sustainability premiums in environmentally conscious European markets.
- Hybrid portability engineering:Single-device flexibility across home and mobile contexts commands pricing power. Nintendo's form-factor innovation validates premium positioning for versatile hardware.
Market Restraints
- Advanced node semiconductor scarcity:TSMC and Samsung Foundry capacity constraints throttle custom APU production. Launch volumes face hard ceilings regardless of demand signals.
- F-Gas Regulation thermal limits:EU refrigerant restrictions complicate liquid cooling implementations for high-TDP consoles. Thermal design power budgets compress performance headroom.
- Smartphone gaming substitution:Mobile processors now render console-comparable visuals at fraction of hardware cost. Casual player migration threatens addressable market expansion.
Strategic Opportunities
- India untapped install base:Localized payment integration and regional content licensing unlock middle-class discretionary spending. Price-sensitive segments respond to entry-tier hardware SKUs.
- Right-to-repair legislative tailwinds:US state-level repair access mandates create aftermarket service revenue pools. Modular component designs extend hardware lifecycles and parts sales.
- AI-driven upscaling convergence:Machine learning inference engines reduce native rendering loads while preserving visual fidelity. Cloud-edge hybrid architectures lower bandwidth requirements for streaming subscribers.
Industry Challenges
- Real-time systems programming talent scarcity:Low-latency graphics pipeline optimization requires specialized engineering expertise. Compensation inflation in semiconductor design functions compresses R&D margins.
- Cross-platform certification complexity:Multi-territory content rating approvals delay simultaneous global launches. Age verification systems must satisfy Japan's METI frameworks alongside ESRB and PEGI requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaming Console Market |
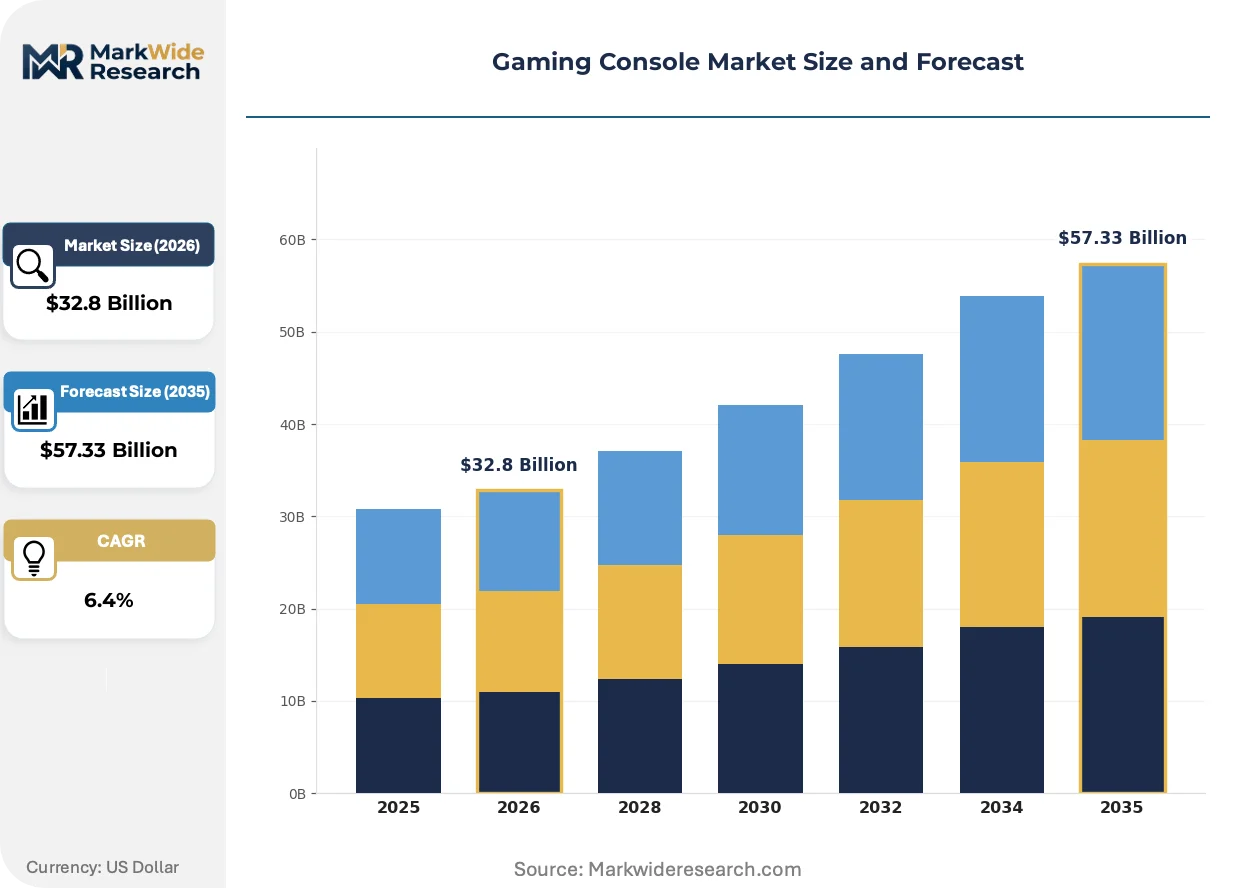
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Home Console, Hybrid, Streaming End User: Casual Gamers, Hardcore Gamers, Families, Professionals Distribution Channel: Retail Stores, Online Marketplaces, Direct Sales, Distributors Service Type: Subscription Services, Game Bundles, Technical Support, Accessories |
| Companies Covered | Sony Group Corporation, Nintendo Co., Ltd., Microsoft Corporation, Advanced Micro Devices, Bandai Namco Entertainment, Atari Inc., Bandai Namco Studios, Electronic Arts, Activision Blizzard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaming Console Market Emerging Trajectories
Generative inference workloads and edge-compute distribution are redistributing computational gravity away from centralized data centers toward localized rendering clusters.
Ray-traced global illumination is expanding into mid-tier hardware configurations through AMD and NVIDIA upscaling technologies. Indie developers now ship titles with path-traced lighting that previously required flagship GPU investments. This capability compression erodes the visual differentiation historically commanded by premium console SKUs.
Japan's METI semiconductor supply chain security protocols are mandating domestic buffer stock requirements for critical gaming components. Console manufacturers must maintain 90-day inventory coverage of custom processors and high-bandwidth memory modules. This policy is accelerating near-shoring discussions for final assembly operations previously concentrated in Chinese manufacturing zones.
Hardcore gamers now evaluate total cost of ownership through subscription-library depth rather than hardware specifications alone. PlayStation Plus and Game Pass catalogs drive platform switching decisions more than teraflop benchmarks. This behavioral pivot concentrates purchasing power among service-aggregated households in Japan, the United States, and United Kingdom markets.
Gaming Console Market Segmentation
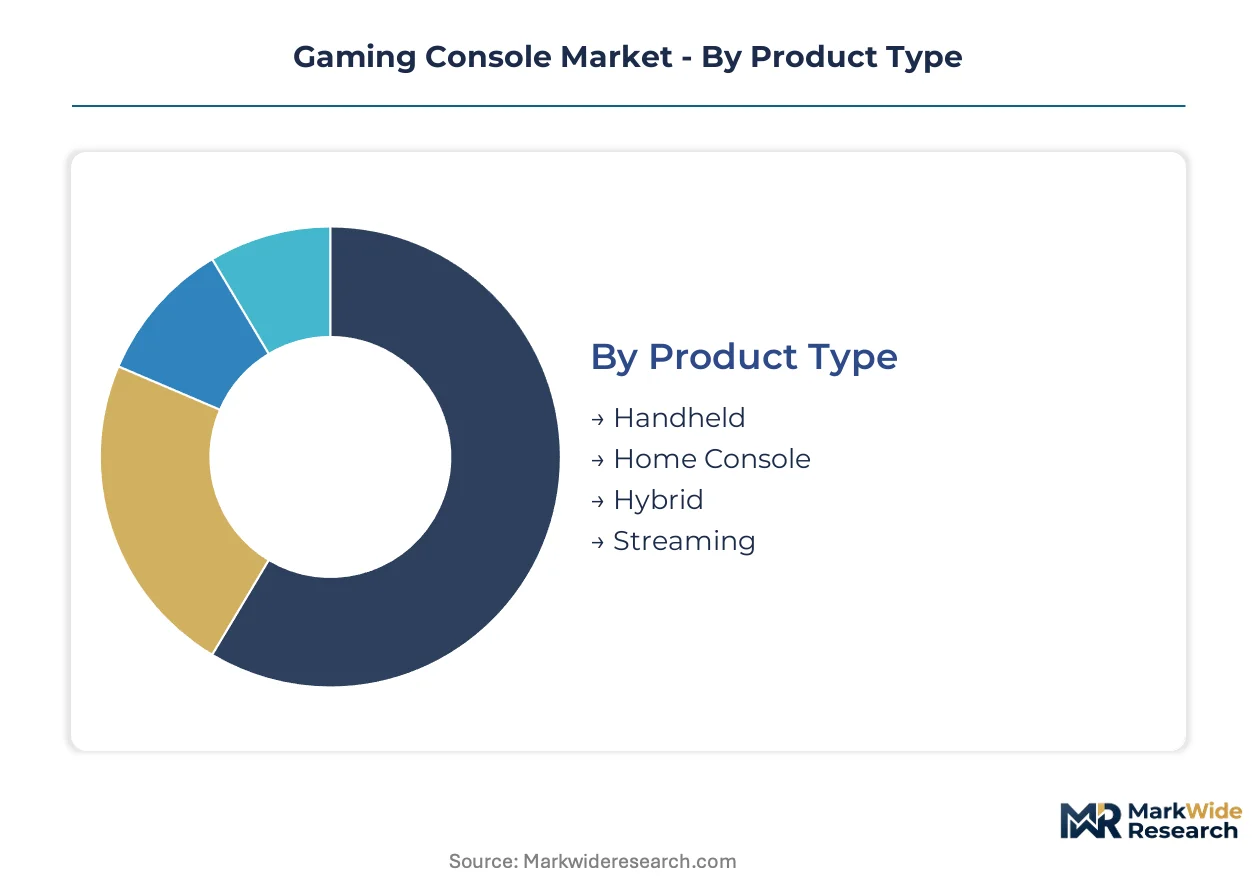
Segmentation in gaming consoles reveals how hardware form factors, user commitment levels, and monetization architectures compete for margin allocation. Distinct purchasing behaviors across these dimensions determine platform strategy and ecosystem lock-in effectiveness.
Product Type:
Integration depth varies sharply: home consoles anchor stationary entertainment systems while handheld and hybrid formats embed computing into portable form factors.
- Handheld:Self-contained mobile devices with integrated displays, battery subsystems, and thermal envelopes optimized for 5-15 watt TDP budgets. Demand clusters in Japan's dense transit corridors where commute gaming sustains daily engagement. Battery chemistry constraints limit sustained performance versus docked alternatives.
- Home Console:Stationary units engineered for 150-350 watt thermal designs, leveraging active cooling and external power bricks to drive 4K rendering pipelines. North American living room installations prioritize accessory attach rates and media center integration. Component sourcing concentrates around TSMC advanced nodes for custom accelerated processing units.
- Hybrid:Nintendo's detachable dock architecture validates single-device flexibility across portable and television contexts. The form factor commands pricing premiums by collapsing two hardware purchases into one ecosystem commitment.
- Streaming:Thin-client hardware decoding cloud-rendered frames with sub-20 millisecond latency requirements. Google's Stadia discontinuation demonstrated margin compression when content libraries fail to match technical infrastructure.
Volume placements concentrate in Home Console; the faster expansion belongs to Hybrid.
End User:
Customer archetypes stratify by session length, content spending velocity, and multiplayer engagement depth.
- Casual Gamers:Intermittent players prioritizing accessible mechanics and low time commitment. Mobile substitution threats concentrate in this segment as smartphone processors deliver comparable visual fidelity at lower hardware cost.
- Hardcore Gamers:Daily high-session users driving premium hardware adoption and subscription stacking. This cohort evaluates total cost of ownership through library depth rather than specification benchmarks. Japan's concentrated urban demographics sustain the highest per-capita hardcore penetration globally.
- Families:Multi-user households prioritizing content rating controls and local multiplayer capabilities. Purchasing decisions emphasize durability and parental governance features over raw performance metrics.
- Professionals:Streamers and esports competitors requiring broadcast-grade output and tournament-standard input latency. Peripheral ecosystems and sponsorship integrations drive hardware refresh cycles independent of consumer replacement patterns.
Revenue concentration sits with Hardcore Gamers; Families represent the most price-elastic expansion vector.
Distribution Channel:
Channel selection determines inventory risk allocation, margin capture, and customer data ownership.
- Retail Stores:Physical locations enabling hands-on demonstration and immediate fulfillment. Japan's electronics retail culture sustains higher brick-and-mortar attach rates than Western markets.
- Online Marketplaces:Platform-agnostic aggregators competing on price transparency and bundled financing. Scalper arbitrage during supply-constrained launch windows exposed inventory allocation vulnerabilities.
- Direct Sales:Manufacturer-controlled storefronts capturing full margin and first-party customer relationships. Microsoft's Xbox Design Lab exemplifies customization premiums unavailable through wholesale channels.
- Distributors:Regional intermediaries managing logistics complexity across fragmented retail networks. Emerging market penetration relies on distributor credit terms and localized payment integration.
Margin capture favors Direct Sales; volume scaling depends on Distributor relationships.
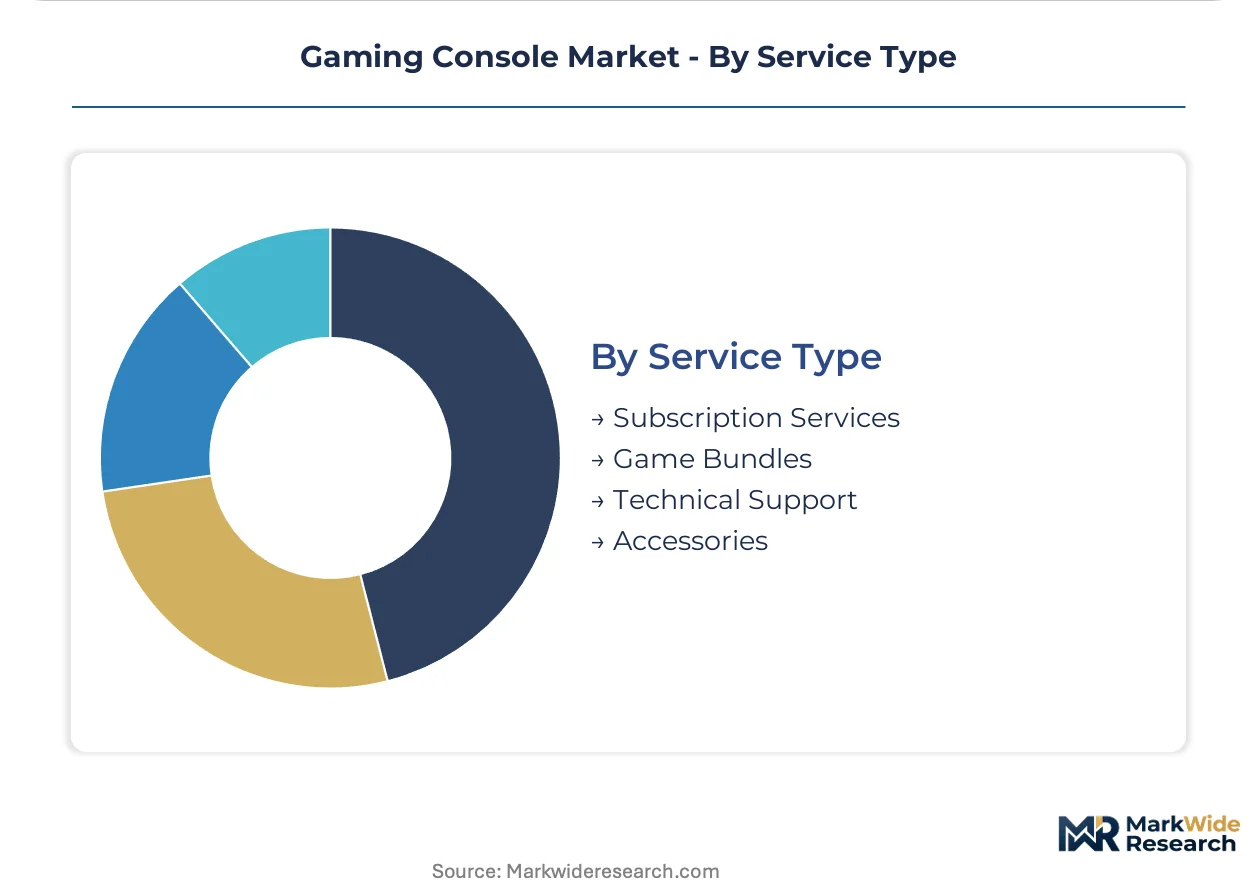
Service Type:
Post-hardware monetization architectures transform one-time transactions into recurring revenue streams.
- Subscription Services:Monthly billing for library access, multiplayer infrastructure, and cloud storage. Sony's PlayStation Plus and Microsoft's Game Pass have redefined platform switching costs around accumulated digital entitlements.
- Game Bundles:Packaged software inclusion at hardware purchase to accelerate install base content depth. Bundle economics compress per-unit software margins while driving accessory and subscription conversion.
- Technical Support:Extended warranty and repair services addressing joystick drift, thermal degradation, and storage expansion. Right-to-repair legislative momentum threatens captive service revenue pools.
- Accessories:Controllers, headsets, and storage peripherals generating margin multiples exceeding hardware units. Haptic feedback and adaptive trigger technologies differentiate premium controller tiers.
Recurring stability concentrates in Subscription Services; margin rate leadership belongs to Accessories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in East Asian semiconductor clusters while consumption distributes across high-income markets with established gaming cultures. Japan and China anchor component fabrication and final assembly operations. North American and European markets absorb premium hardware volumes despite limited domestic production capacity.
Japan
Tokyo and Osaka metropolitan corridors sustain the densest hardcore gamer populations globally, with per-capita console ownership exceeding all other major markets. METI semiconductor supply chain security protocols mandate 90-day inventory buffers for custom processors and high-bandwidth memory, accelerating near-shoring discussions for assembly operations. Kyoto anchors Nintendo's integrated hardware-software development campus, while Tokyo's Shinagawa district concentrates Sony's platform engineering headquarters and third-party publisher ecosystems.
United States
Seattle and Redmond, Washington, host Microsoft's Xbox division and cloud infrastructure engineering for Game Pass streaming architectures. FCC spectrum allocation governs wireless controller protocols and online connectivity standards across all imported hardware. California's Bay Area clusters independent game studios whose titles drive platform-exclusive purchasing decisions, while Austin, Texas, anchors growing esports tournament infrastructure that sustains professional-grade peripheral demand.
China
Shanghai and Shenzhen manufacturing zones assemble the majority of global console hardware despite historical software licensing restrictions. MIIT certification requirements and GB standards compliance create multi-month approval delays for official market entry. Guangdong province's Pearl River Delta ecosystem supplies thermal management components, power supply units, and controller assemblies to Japanese and American platform holders.
Germany
Bavaria and North Rhine-Westphalia distribute the highest console penetration rates in continental Europe, driven by discretionary household spending on entertainment hardware. EU Green Deal packaging mandates and F-Gas Regulation thermal constraints force design-for-disassembly protocols and refrigerant selection changes. Berlin's indie development scene generates critically acclaimed titles that influence platform library evaluations across German-speaking markets.
South Korea
Seoul Capital Area gamers demonstrate highest subscription stacking rates globally, with multiple platform memberships per household. MFDS content rating frameworks operate alongside international ESRB and PEGI standards for imported software. Suwon and Gyeonggi province host Samsung and SK Hynix memory fabrication facilities supplying high-bandwidth components for next-generation console architectures.
Gaming Console Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and service layers. Platform holders capture recurring revenue through subscription ecosystems while semiconductor suppliers command pricing power during advanced node capacity constraints. Strategic archetypes include integrated hardware-software platforms, component technology licensors, and third-party content publishers. Competitive moves concentrate on exclusive content acquisition and cloud infrastructure deployment rather than hardware specification escalation.
Within the integrated platform tier, Sony Group Corporation, Nintendo Co., Ltd., and Microsoft Corporation occupy positions defined by distinct ecosystem architectures. Sony leverages PlayStation Plus subscription depth to anchor hardware refresh cycles. Nintendo's hybrid form-factor specialization commands pricing premiums through single-device portability. Microsoft's cross-platform Game Pass distribution extends software reach beyond proprietary console hardware. Each represents a divergent bet on where value capture migrates in decoupled hardware-software relationships.
| Leading Market Players |
|---|
| Sony Group Corporation |
| Nintendo Co., Ltd. |
| Microsoft Corporation |
| Advanced Micro Devices |
| Bandai Namco Entertainment |
| Atari Inc. |
| Bandai Namco Studios |
| Electronic Arts |
| Activision Blizzard |
| Others |
Supply Flow & Price Mechanics
Custom accelerated processing unit wafer costs cascade through three-tier pricing structure across premium, standard, and economy levels as TSMC advanced node capacity constraints concentrate bargaining power with semiconductor foundries serving Sony, Nintendo, and Microsoft procurement teams.
Pricing Analysis
Margin tightening in entry-tier hardware reflects smartphone gaming substitution eroding casual segment willingness to pay for dedicated devices. Three-tier pricing structure across premium, standard, and economy levels segments buyers by subscription commitment depth and accessory attach rates. Hardcore gamers demonstrate lowest price elasticity as library entitlements accumulate switching costs. Families exhibit highest sensitivity, delaying purchases until bundle promotions or hardware refresh cycles.
Supply Chain Analysis
Reverse logistics flows for controller refurbishment and trade-in credit programs recover rare earth magnets and lithium-ion cells from end-of-life units. Component sourcing draws from Taiwan for custom APUs, South Korea for high-bandwidth memory, and Japan for precision thermal management subassemblies. Single-source vulnerability concentrates in TSMC N4/N3 node allocation for console-specific processor designs. Distribution runs through direct-to-consumer storefronts capturing full margin alongside distributor networks managing emerging market credit terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced node semiconductor scarcity is forcing consolidation as capital-intensive foundry relationships and exclusive content acquisition costs marginalize undercapitalized platform aspirants.
For Market Incumbents: Lock in captive APU allocation through multi-year foundry offtake agreements with TSMC and Samsung Foundry. Deepen exclusive content pipelines by acquiring mid-tier studios before cloud-streaming entrants can aggregate library depth. Threat substitution from Netflix and Amazon Luna cloud gaming services demands preemptive ecosystem fortification. For New Entrants and Emerging Players: Capture India untapped install base through localized payment integration and regional content licensing partnerships with domestic publishers. White-space concentration in middle-class discretionary spending responds to entry-tier hardware SKUs below incumbent flagship pricing. Go-to-market leverage rests on distributor credit terms enabling installment purchase structures. For Investors and Strategic Acquirers: METI semiconductor supply chain security protocol implementation is the leading indicator that near-shoring assembly operations will reshape capital deployment toward Japanese manufacturing zones. Long-term viability favors vertically integrated hardware-software platforms with recurring subscription revenue exceeding cyclical hardware dependency. Acquisition target archetype: regional distributors with established emerging market logistics networks and localized payment integration capabilities. Monitor right-to-repair legislative momentum across US statehouses for aftermarket service revenue inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Content Acquisition | Library depth drives platform switching decisions more than hardware specifications in hardcore gamer segments. |
| Cloud Infrastructure Deployment | Game Pass and PlayStation Plus streaming architectures extend software reach beyond proprietary hardware endpoints. |
| Hybrid Form Factor Engineering | Nintendo's detachable dock architecture validates single-device flexibility commanding pricing premiums across use cases. |
| Foundry Capacity Reservation | TSMC advanced node allocation agreements determine launch volume ceilings regardless of demand signals. |
| Regional Content Localization | India market penetration requires domestic publisher partnerships and payment system integration for price-sensitive segments. |
Methodological Framework
SEC 10-K filings, customs trade databases, and platform holder earnings disclosures formed the secondary backbone for revenue and shipment volume estimation. Primary interviews with console platform engineering directors, semiconductor procurement leads at OEMs, third-party publisher business development executives, and regional distributor operations heads validated secondary assumptions. Bottom-up hardware shipment modeling and top-down subscription revenue aggregation triangulated market sizing across product type, end user, and regional dimensions.
Bottom-up volume builds aggregated unit economics across home console, handheld, hybrid, and streaming hardware categories. Top-down validation cross-referenced aggregate platform holder disclosed revenues against modeled average selling prices and attach rates. Segmentation dimensions spanned product type, end user archetype, distribution channel, and service monetization architecture. CAGRs derived from regression analysis of historical shipment trajectories and subscription penetration curves. Forecast inputs incorporated foundry capacity expansion schedules and content licensing pipeline visibility.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cloud streaming substitution rates and right-to-repair legislative implementation timelines. Forecasts reflect documented assumptions regarding semiconductor supply normalization and subscription stacking saturation thresholds. Practitioners should monitor TSMC advanced node allocation announcements and India payment infrastructure regulatory developments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Gaming As a Service Market
Gaming
Global Subscription-Based Gaming Market
Gaming
VR Melee Games Market
Gaming
Connected Game Console Market
Gaming
South Korea Subscription-Based Gaming Market
Gaming
VR Gaming Market
Gaming
Global NFT Gaming Market
Gaming
Gaming Gadgets Market
Gaming
Game API Market
Gaming
Puzzle Video Game Market
Gaming
Europe Serious Gaming Market
Gaming
Africa Gaming Market
Gaming
Gaming Software Market
Gaming
Serious Games Market
Gaming
Mobile MOBA Games Market
Gaming
Online Strategy Games Market