
 North America Gaming Market | 2026-2036
North America Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gaming Market Outlook
Multi-source content pipelines is consolidating as the dominant production strategy across major North American studios. Electronic Arts Inc. sustains its competitive edge through proprietary Frostbite engine development and sports licensing control. Microsoft Corporation leverages its Azure cloud backbone to anchor Xbox Game Pass distribution across console and PC ecosystems. Sony Interactive Entertainment LLC dominates premium hardware cycles with PlayStation exclusives that lock in ecosystem loyalty.
North America gaming encompasses interactive software and hardware systems designed for entertainment, competition, and social engagement, typically requiring real-time rendering at frame rates exceeding 60 FPS and sub-50ms latency for competitive integrity. The industry serves commercial purposes spanning consumer entertainment, professional esports broadcasting, and brand advertising integration. Mobile platforms command the largest addressable user base through free-to-play monetization models supported by in-game purchases, while console segments retain the highest per-user revenue concentration through premium software pricing and subscription services. Cloud gaming represents the fastest-expanding structural category as infrastructure investments reduce latency barriers to streaming high-fidelity titles without dedicated hardware.
The FCC governs broadband infrastructure standards that determine cloud gaming service quality thresholds across the United States, while Canada's CRTC oversees comparable telecommunications frameworks affecting cross-border platform delivery. ESRB content ratings and COPPA children's privacy rules shape product design requirements and marketing access for demographic-targeted releases. Stakeholders must monitor evolving antitrust scrutiny of platform exclusivity arrangements and app store fee structures as these regulatory pressures redefine distribution economics and developer revenue shares.
Market Dynamics
Cloud gaming infrastructure deployment is compressing hardware ownership cycles across the United States and Canada, as latency-sensitive streaming protocols displace dedicated console purchases among casual user segments.
Growth Catalysts
- 5G network densification:FCC spectrum auctions have accelerated millimeter-wave rollout in urban corridors, reducing cloud gaming latency below competitive thresholds in Los Angeles, San Francisco, and Toronto metropolitan zones.
- Cross-platform progression systems:Persistent player profiles spanning mobile, console, and PC endpoints are extending session duration and monetization depth across free-to-play ecosystems.
- Esports broadcasting rights:Traditional sports networks in the United States and Canada are acquiring exclusive tournament distribution agreements, funneling advertiser budgets into gaming content production.
Market Restraints
- Input cost volatility:Semiconductor fabrication capacity constraints in East Asian foundries are inflating GPU and custom APU pricing for console manufacturers.
- Supply concentration risk:Cloud gaming server infrastructure depends on hyperscaler concentration in Virginia, Oregon, and Quebec data center clusters, creating single-point-of-failure exposure.
- Regulatory friction:Ongoing FCC net neutrality proceedings generate uncertainty around traffic prioritization agreements essential for sub-20ms streaming performance guarantees.
Strategic Opportunities
- Underpenetrated rural broadband:USDA Rural Development grants and Canadian Universal Broadband Fund allocations are extending fiber-to-the-home infrastructure into Montana, Wyoming, and northern Canadian territories previously excluded from cloud gaming service maps.
- Regulatory tailwind:Canadian CRTC wholesale broadband rate reforms are reducing independent ISP operational costs, enabling regional price competition that expands addressable cloud gaming households.
- Technology convergence:Edge computing nodes are converging with AI-driven upscaling algorithms to deliver console-equivalent fidelity on mid-tier mobile chipsets without dedicated hardware.
Industry Challenges
- Live service engineering talent scarcity:Server architecture, anti-cheat systems, and real-time economy balancing expertise commands premium compensation in the Los Angeles-San Francisco corridor, constraining mid-size studio expansion.
- Certification timeline compression:ESRB rating processes and platform-holder technical compliance reviews for simultaneous multi-platform launches are extending pre-release development cycles.
- IP licensing complexity:Sports league exclusive agreements, music synchronization rights, and actor likeness permissions are fragmenting content availability across competing subscription services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gaming Market |
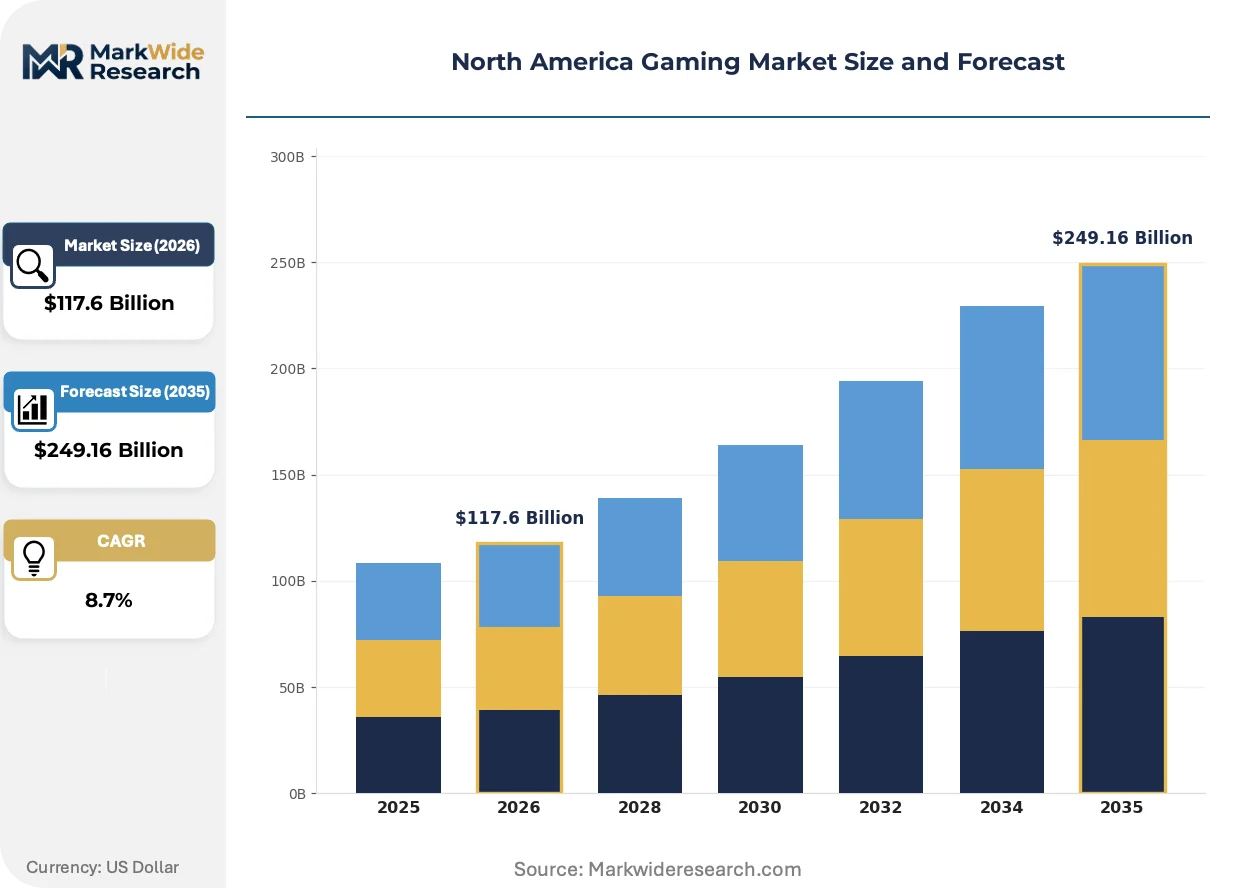
| Market Size in 2026 | $117.6 Billion |
| Market Size in 2035 | $249.16 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: PC, Mobile, Console, Cloud Game Type: Action, RPG, Simulation, Sports Monetization Model: In-Game Purchases, Subscription, Free-to-Play, Premium Demographic: Teens, Adults, Casual Gamers, Hardcore Gamers |
| Companies Covered | Activision Blizzard, Inc., Electronic Arts Inc., Microsoft Corporation, Sony Interactive Entertainment LLC, Nintendo Co., Ltd., Take-Two Interactive Software, Inc., Ubisoft Entertainment SA, Epic Games, Inc., Valve Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gaming Market Strategic Shifts
Real-time rendering pipelines and AI-assisted content generation are compressing production timelines for AAA releases, while regulatory scrutiny of platform economics is forcing distribution model experimentation.
Generative AI tooling for asset creation, voice synthesis, and localization is converging with traditional motion-capture workflows. Mid-size studios in Austin and Montreal are adopting these hybrid pipelines to reduce per-title headcount requirements. This convergence is compressing the cost barrier between indie and AAA visual fidelity tiers.
The FCC's ongoing net neutrality rulemaking is creating uncertainty around paid peering agreements between cloud gaming services and last-mile ISPs. Platform operators are responding by negotiating direct server colocation contracts with regional broadband providers. This regulatory friction most acutely affects multi-tenant cloud services competing against vertically integrated distribution networks.
Subscription fatigue among core gamers is fragmenting library access across multiple paid services, driving demand for account-linking APIs and unified progression systems. Platform holders are responding with cross-purchase entitlements and social graph portability features. This behavioral shift is most visible in the United States, where average household gaming subscription expenditure has plateaued against discretionary entertainment budgets.
North America Gaming Market Segmentation
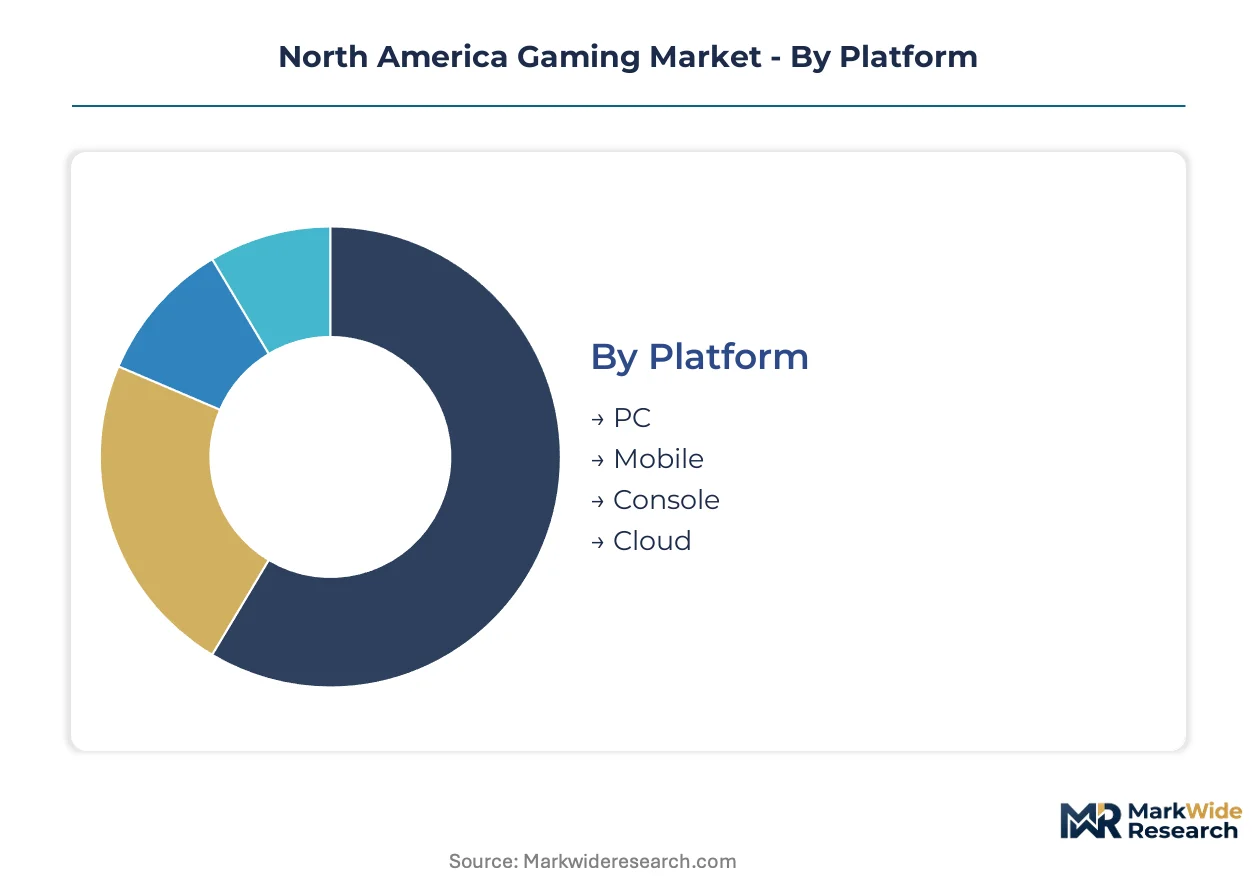
Platform diversity across North America gaming creates distinct infrastructure requirements and monetization ceilings. Each segment demands specialized server architecture, content certification pipelines, and distribution partnerships that shape competitive positioning.
Platform:
Standardization dominates hardware interfaces while software customization proliferates across operating environments.
- PC:Open architecture enables direct-to-consumer distribution and modding ecosystems. Demand concentrates among competitive multiplayer titles in Texas and Washington state server corridors, driven by esports tournament prize pools and streaming sponsorships.
- Mobile:ARM-based chipsets and touch-optimized UX define technical specifications. California and Ontario developers prioritize this segment for free-to-play monetization scale, constrained by iOS App Store and Google Play commission structures.
- Console:Proprietary SDKs and certification gates enforce hardware-software integration standards.
- Cloud:Latency-sensitive streaming protocols require edge node proximity to end users.
Most installed capacity flows through Console. Expansion is steepest in Cloud.
Game Type:
Development cost tiers separate blockbuster production from mid-budget releases across this category.
- Action:Real-time combat systems demand 60+ FPS rendering and sub-50ms input response. Los Angeles studios dominate this segment for AAA releases, leveraging motion-capture stages and Hollywood stunt coordination pipelines.
- RPG:Narrative branching and persistent world states require live service engineering expertise. Montreal and Austin development clusters specialize here, supported by Canadian tax credit incentives and Texas relocation subsidies.
- Simulation:Physics engines and emergent gameplay systems attract niche enthusiast audiences.
- Sports:League licensing agreements concentrate content control among established publishers.
Action titles command the largest production budgets. RPGs are gaining share fastest through subscription catalog depth.
Monetization Model:
Customer lifetime value calculations vary dramatically across payment structure archetypes.
- In-Game Purchases:Microtransaction systems power cosmetic and progression economies. Mobile platforms in the United States generate disproportionate revenue here, though regulatory scrutiny of loot box mechanics constrains design freedom.
- Subscription:Recurring revenue models prioritize library breadth over individual title investment. Microsoft's Xbox Game Pass and Sony's PlayStation Plus anchor this segment, with Canadian households showing higher per-capita subscription penetration than US averages.
- Free-to-Play:Zero-entry pricing maximizes user acquisition funnel width.
- Premium:Upfront purchase models retain importance for narrative-driven single-player experiences.
Free-to-Play captures the widest user base. Subscription models show the steepest revenue trajectory.
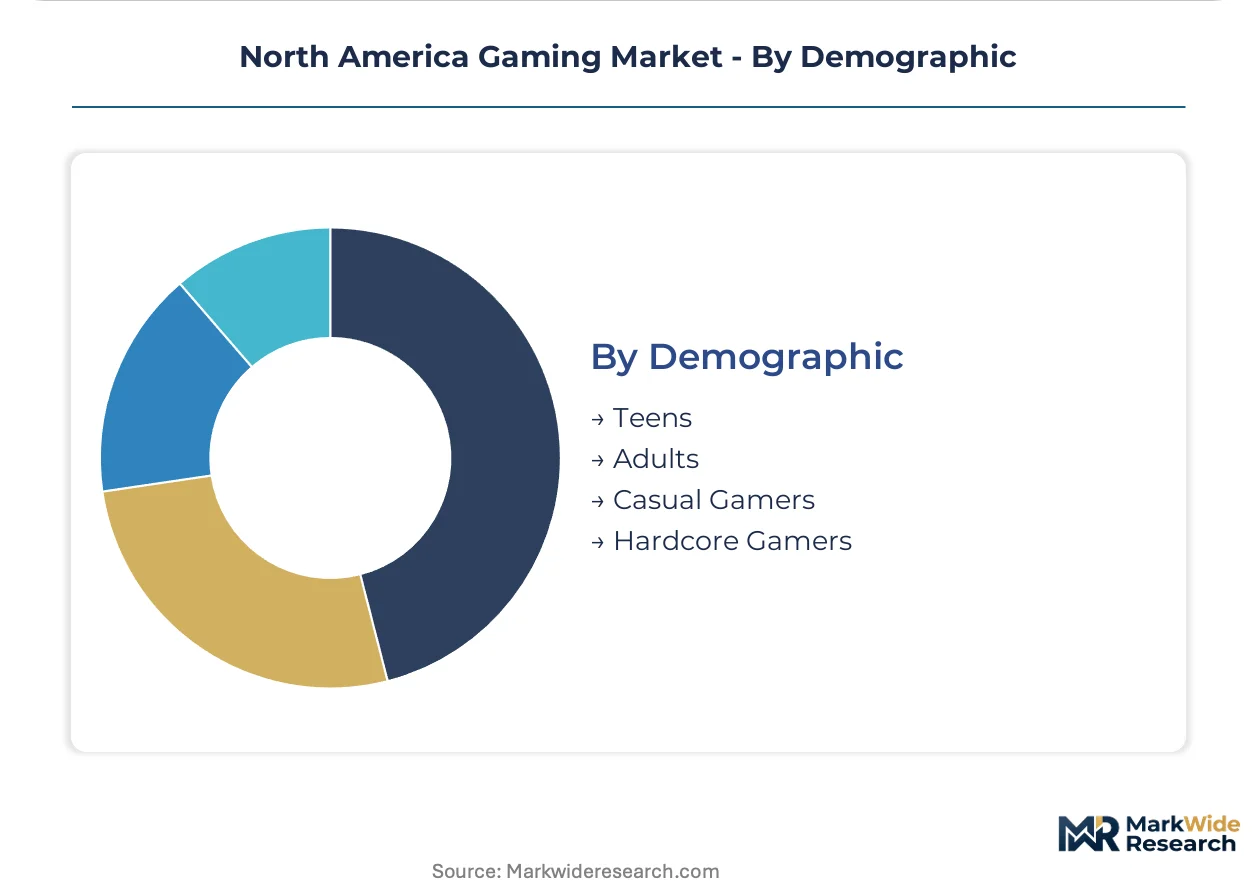
Demographic:
Session length and spending patterns diverge sharply across player commitment levels.
- Hardcore Gamers:Daily 3+ hour sessions and hardware upgrade cycles define this cohort. Demand clusters in metropolitan corridors with fiber infrastructure and esports venue density, particularly Seattle and Toronto.
- Casual Gamers:Intermittent play patterns favor mobile touch interfaces and cloud streaming convenience. Rural broadband expansion in Montana and Saskatchewan is unlocking this segment previously excluded by latency barriers.
- Adults:Discretionary income enables premium hardware and subscription stacking.
- Teens:COPPA compliance requirements and parental control systems shape product design constraints.
Adults represent the largest spending base. Hardcore Gamers drive the fastest platform adoption cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Los Angeles-San Francisco corridor concentrates North American gaming studio density, venture capital deployment, and cloud infrastructure investment. This concentration shapes content production scale and technology adoption velocity across the continent.
United States
Esports tournament prize pools and streaming sponsorships drive competitive multiplayer demand in Texas and Washington state server corridors. FCC spectrum auctions accelerate millimeter-wave rollout, reducing cloud gaming latency below competitive thresholds in urban zones. Seattle anchors hardcore gamer hardware upgrade cycles through fiber infrastructure density and esports venue concentration.
Canada
Canadian households show higher per-capita subscription penetration than US averages for gaming services. CRTC wholesale broadband rate reforms reduce independent ISP operational costs, enabling regional price competition. Montreal development clusters specialize in RPG production, supported by Canadian tax credit incentives and live service engineering expertise.
Mexico
Mobile free-to-play monetization scales through expanding smartphone penetration and young demographic concentration. The country's federal telecommunications regulator oversees spectrum allocation affecting cloud gaming service quality. Mexico City Metro serves as the primary hub for Latin American-localized content production and regional publisher operations.
North America Gaming Market Competitive Environment
Global majors compete with regional champions across platform exclusivity and content licensing dimensions. The market structure consolidates around vertically integrated platform holders, mid-size studios with specialized genre expertise, and independent developers leveraging digital distribution. Three archetypes dominate: ecosystem-locked hardware-software integrators, live service specialists with persistent world engineering capabilities, and IP licensors controlling sports league and entertainment franchise rights. Competitive moves concentrate on exclusive content acquisition and cloud infrastructure partnerships.
Among US-based platform holders, Microsoft Corporation and Sony Interactive Entertainment LLC exemplify ecosystem-locked competitive positioning through cloud backbone integration and exclusive content pipelines. Electronic Arts Inc. represents the IP licensing archetype, leveraging proprietary engine development and sports licensing control to sustain competitive differentiation.
| Leading Market Players |
|---|
| Activision Blizzard, Inc. |
| Electronic Arts Inc. |
| Microsoft Corporation |
| Sony Interactive Entertainment LLC |
| Nintendo Co., Ltd. |
| Take-Two Interactive Software, Inc. |
| Ubisoft Entertainment SA |
| Epic Games, Inc. |
| Valve Corporation |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up cloud infrastructure specialists anchor supply behavior and pricing discipline across North American gaming, as concentrated hyperscaler ownership in Virginia and Oregon data center clusters limits competitive pressure on server leasing rates while subscription pricing power concentrates among platform holders with exclusive content pipelines.
Pricing Analysis
Input-cost pass-through from semiconductor fabrication constraints in East Asian foundries is compressing console hardware margins and accelerating subscription service bundling. Premium-mid-economy pricing differentiation separates Xbox Game Pass Ultimate from standard tiers based on cloud streaming access and day-one release entitlements. Pricing pressure stems from GPU and custom APU cost inflation rather than demand erosion. Casual mobile gamers exhibit highest price sensitivity to in-game purchase friction, while hardcore console subscribers demonstrate lowest sensitivity due to ecosystem lock-in effects.
Supply Chain Analysis
ESRB certification and platform-holder technical compliance gates filter upstream component suppliers, restricting console APU sourcing to TSMC-fabricated designs and custom AMD silicon. Taiwan, South Korea, and Japan anchor semiconductor supply for gaming hardware, while Mexico and China feed peripheral manufacturing. Raw material dependencies span advanced packaging substrates, high-bandwidth memory stacks, and rare earth magnets for controller haptics. Single-source vulnerability concentrates in East Asian foundry capacity for 7nm and below process nodes. Distribution runs through direct-to-consumer digital storefronts and big-box retail partnerships for physical hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by hardcore gamer demand-shift toward sub-20ms latency specifications and premium subscription stacking tolerance.
For Market Incumbents: Anticipate regulatory scrutiny of platform exclusivity arrangements by diversifying content licensing across multi-platform releases. Secure backward integration into cloud edge node infrastructure through direct colocation contracts with regional ISPs, reducing exposure to FCC net neutrality uncertainty around traffic prioritization agreements.
For New Entrants and Emerging Players: Direct-to-consumer PC distribution channels bypass platform-holder certification gates and 30% commission structures. Target underpenetrated rural broadband expansion zones in Montana and Saskatchewan where USDA and Canadian Universal Broadband Fund infrastructure investments are unlocking previously excluded casual gamer segments. Prioritize free-to-play mobile titles with cross-progression systems as the most penetrable entry vector.
For Investors and Strategic Acquirers: Cloud hyperscalers represent the most active acquirer in this space, seeking live service engineering talent and proprietary engine technology. Long-term viability favors studios with persistent world expertise and anti-cheat system IP. Watch CRTC wholesale broadband rate reform implementation as the signal indicating inflection in Canadian cloud gaming household penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Partnership | Direct server colocation with regional ISPs reduces FCC net neutrality exposure. |
| Cross-Platform Progression System | Persistent player profiles extend session duration across mobile, console, and PC endpoints. |
| Live Service Engineering Acquisition | Server architecture and real-time economy expertise commands premium compensation in Los Angeles-San Francisco corridor. |
| Rural Broadband Expansion Targeting | USDA Rural Development grants unlock Montana and Wyoming households previously excluded by latency barriers. |
| Generative AI Pipeline Integration | Asset creation and voice synthesis tooling compresses per-title headcount requirements for mid-size Austin and Montreal studios. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with platform engineering directors, live service operations leads, esports tournament organizers, and cloud infrastructure procurement officers with secondary validation against FCC spectrum auction records, CRTC regulatory filings, SEC 10-K disclosures from listed publishers, and hyperscaler capex announcements. Bottom-up title-level revenue modeling and top-down subscription penetration analysis triangulated segment sizing.
Segment-weighting approaches distributed value across platform type, monetization model, and demographic commitment tier, with cloud gaming expansion rates calibrated against fiber-to-the-home deployment data and 5G millimeter-wave rollout timelines across the analysis window. CAGRs derived from installed base projections, average revenue per user trajectories, and content production cost inflation assumptions. Forecast inputs incorporated ESRB rating pipeline volumes and platform-holder SDK release cycles.
The model assumes a particular technology adoption path; alternative pathways for edge computing node density would alter the outlook. Forecasts reflect assumptions around FCC net neutrality resolution timing and East Asian foundry capacity expansion. A model refresh is warranted upon material change in CRTC wholesale broadband rate implementation or hyperscaler data center clustering patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Mobile Gaming Market
Gaming
Mobile Shooter Market
Gaming
Metaverse in Gaming Market
Gaming
Virtual Reality (VR) in Gaming Market
Gaming
VR Gaming Controller Market
Gaming
Video Game Software Market
Gaming
3D Gaming Technology Market
Gaming
Global Subscription-Based Gaming Market
Gaming
North America Casino Gambling Market
Gaming
South Korea Virtual Reality Gaming Market
Gaming
Online Strategy Games Market
Gaming
China in-Game Advertising Market
Gaming
Board Games Market
Gaming
Germany Gaming Headset Market
Gaming
Global Gaming Market
Gaming
Global Casino Market