
 VR Gaming Controller Market | 2026-2036
VR Gaming Controller Market Size, Share, and Industry Trends Forecast 2026-2036
VR Gaming Controller Market Insights
Asset-light leasing models for VR hardware bundles are rewriting competitive entry barriers for smaller venue operators and independent arcade chains. Sony Group Corporation leverages its PlayStation VR ecosystem to sustain controller sales through exclusive title compatibility. Meta Platforms anchors its position through backward integration into headset-controller software stacks. Valve Corporation differentiates via SteamVR's open tracking standards that attract third-party peripheral makers.
A VR gaming controller is a handheld human interface device incorporating inertial measurement units, capacitive sensors, and haptic actuators to translate physical gestures into spatial inputs within virtual environments. These devices typically operate at sub-20ms latency thresholds and rely on either inside-out optical tracking or external base station triangulation to maintain positional accuracy. Motion controllers currently lead volume shipments due to their deployment across mainstream consumer headsets, while haptic feedback technology commands premium pricing through force-feedback mechanisms that enhance immersion in professional training simulations. Optical tracking systems dominate installed base metrics but face displacement risk from ultrasonic alternatives that reduce occlusion failures in multi-user warehouse-scale setups.
FCC Part 15 emissions rules in the United States constrain radio-frequency transmission power in wireless controller designs, while CE marking under the EU Radio Equipment Directive mandates interoperability testing for devices operating in shared spectrum bands. Japan's METI enforces electrical appliance safety standards that affect battery thermal management specifications in controller designs. Stakeholders must monitor whether emerging national cybersecurity frameworks for connected gaming peripherals will impose firmware attestation requirements that fragment certification pathways across export destinations.
Market Dynamics
Location-based entertainment venues are consolidating procurement around standardized controller ecosystems to reduce training overhead and simplify spare parts logistics across multi-site deployments.
Growth Catalysts
- EU CE marking directives:Harmonized electromagnetic compatibility standards reduce retesting burdens for manufacturers exporting across European markets, accelerating cross-border shipments.
- VR arcade networks:Dense clustering of immersive entertainment venues in China, Japan, and South Korea generates recurring hardware refresh cycles and bulk replacement demand.
- Ultrasonic tracking modules:Warehouse-scale multiplayer facilities adopt occlusion-resistant positioning systems to eliminate line-of-sight failures in free-roam configurations.
Market Restraints
- Base station supply concentration:External optical tracking hardware relies on specialized laser diode arrays sourced from limited East Asian component suppliers, creating single-source vulnerability.
- FCC Part 15 power ceilings:United States radio-frequency emission limits constrain wireless transmission range, forcing either battery-heavy amplification or tethered fallback designs.
- LiDAR hand-tracking substitution:Camera-based gesture recognition built into next-generation headsets threatens standalone controller attach rates in consumer segments.
Strategic Opportunities
- Professional training simulations:Force-feedback haptic controllers command premium pricing in aviation maintenance and surgical rehearsal applications where tactile fidelity reduces error rates.
- Asset-light leasing models:Hardware-as-a-service contracts lower capital barriers for independent arcade operators, converting upfront purchases into recurring revenue streams for distributors.
- India's electronics manufacturing incentives:Production-linked incentive schemes attract controller assembly investments serving domestic demand and Middle East export corridors.
Industry Challenges
- Embedded firmware attestation:Emerging national cybersecurity frameworks for connected peripherals impose cryptographic verification requirements that fragment certification pathways across export destinations.
- Multi-protocol integration:Venue operators face complexity stitching together proprietary tracking stacks from competing headset ecosystems within single attraction footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR Gaming Controller Market |
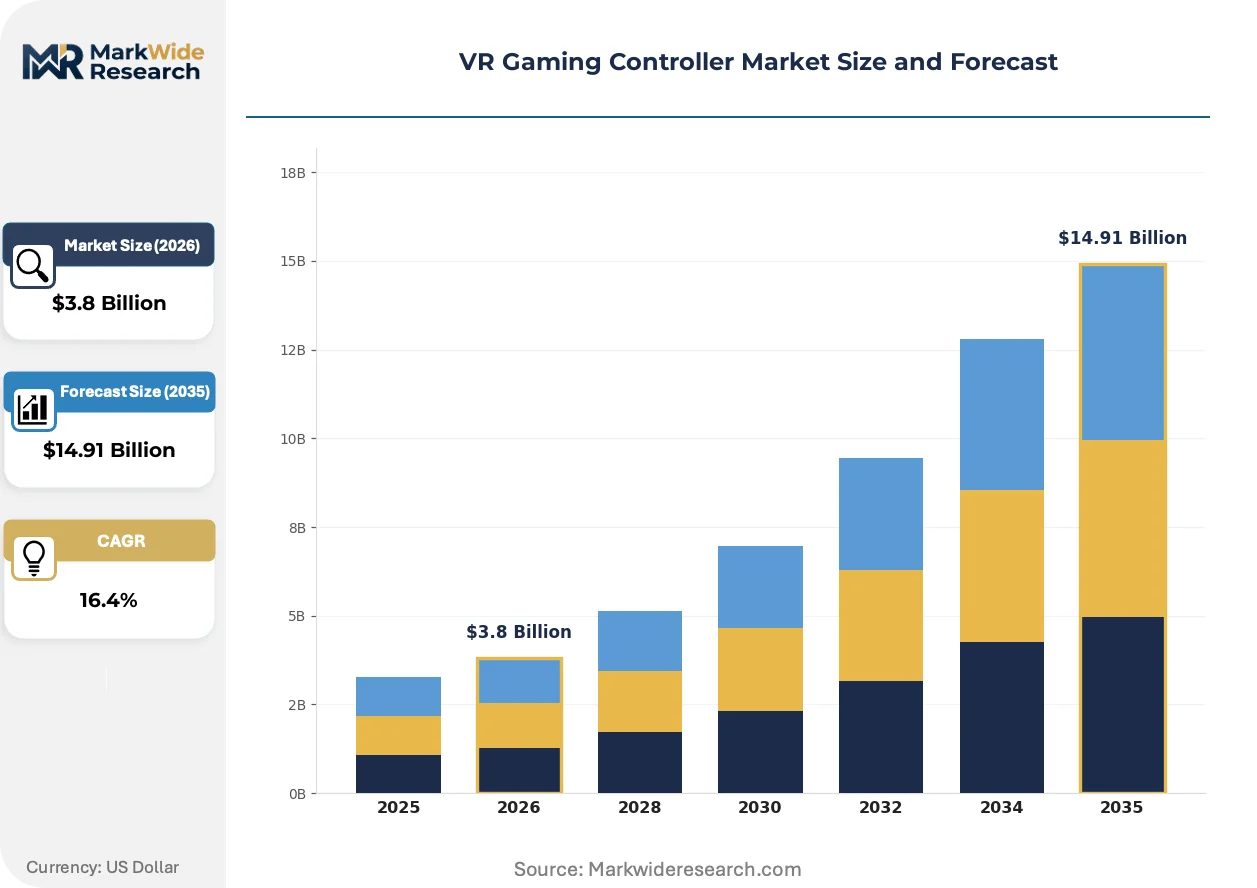
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Controllers, Hybrid Controllers, Attached Controllers, Motion Controllers Technology: Optical Tracking, Inertial Tracking, Ultrasonic Tracking, Haptic Feedback End User: Casual Gamers, Professional Gamers, Gaming Developers, Educational Institutions Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Sony Group Corporation, Meta Platforms, Valve Corporation, HTC Corporation, Microsoft Corporation, Razer Inc., Logitech International S.A., Nintendo Co., Ltd., SteelSeries ApS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR Gaming Controller Market Trends and Innovations
Controller architectures are fragmenting along use-case lines as consumer, enterprise training, and location-based entertainment segments diverge in performance requirements and durability specifications.
Capacitive finger-tracking sensors are migrating from high-end enterprise gloves into mainstream motion controllers, enabling natural grasp gestures without mechanical buttons. Training simulation buyers at aviation maintenance schools and surgical centers now specify sub-millimeter finger pose accuracy in procurement tenders. This migration is compressing the feature gap between premium haptic gloves and standard handheld controllers, forcing mid-tier manufacturers to accelerate R&D timelines or retreat to pure price competition.
Japan's METI electrical appliance safety standards are tightening battery thermal management specifications following incidents of lithium-ion cell swelling in high-utilization arcade environments. Manufacturers must now submit extended cycle-life test data and thermal runaway containment documentation before obtaining market clearance. Arcade operators in Tokyo and Osaka are responding by specifying controllers with detachable battery modules to simplify field replacement without full hardware swaps.
After-sales service unbundling is disrupting traditional distribution channels as venue operators negotiate direct technical support contracts with controller manufacturers, bypassing regional distributors. Large location-based entertainment chains in South Korea now require 24-hour replacement guarantees and on-site technician dispatch as standard contract terms. This shift is most visible in Seoul's Hongdae district, where dense clustering of VR cafes has created localized service infrastructure that smaller regional markets struggle to replicate.
VR Gaming Controller Market Segmentation
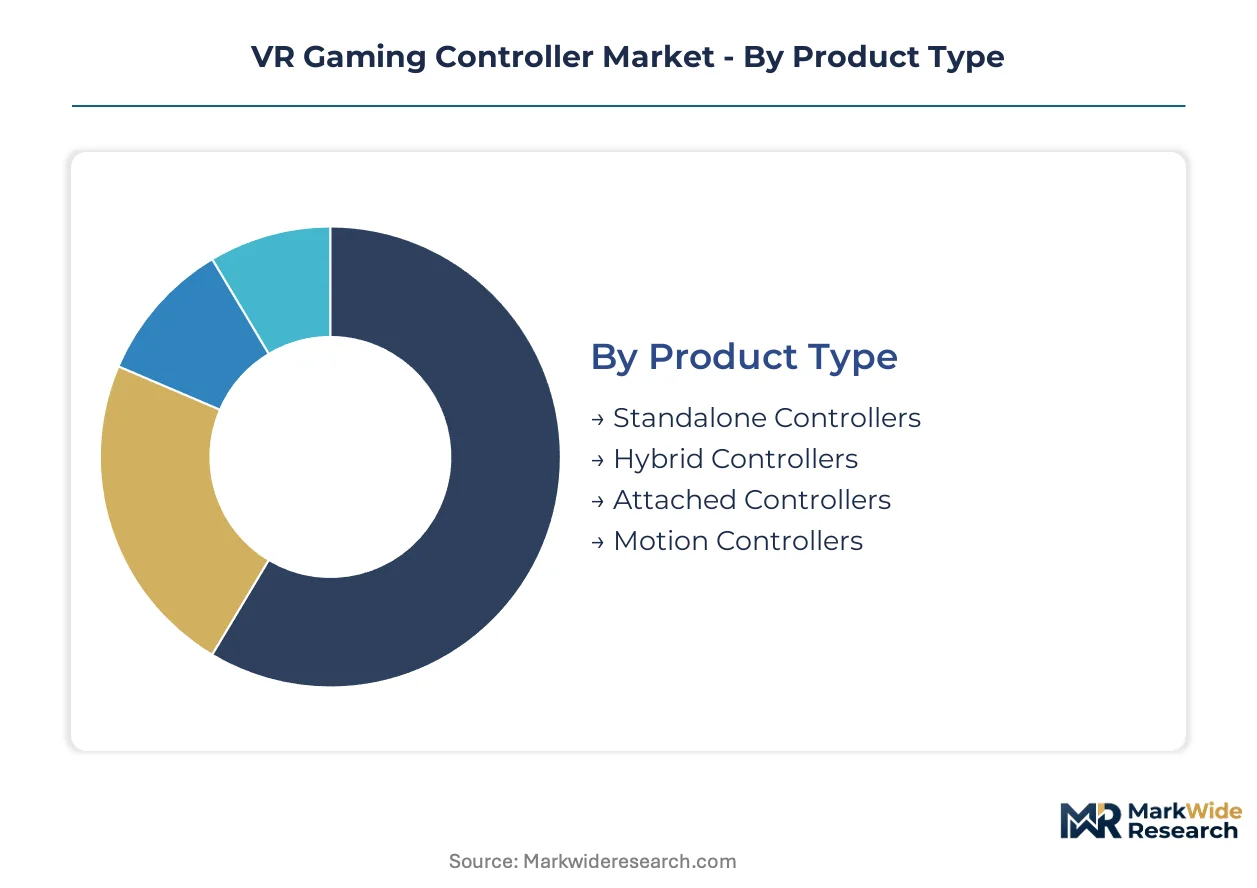
Controller architectures diverge sharply across use cases as consumer, enterprise training, and location-based entertainment segments impose incompatible durability and latency specifications. Procurement patterns consolidate around standardized ecosystems to simplify spare parts logistics and reduce training overhead across multi-site deployments.
Product Type:
Volume concentration across controller form factors reflects divergent attachment strategies to headset ecosystems and varying degrees of hardware independence.
- Motion Controllers:Handheld devices incorporating inertial measurement units and capacitive sensors to translate physical gestures into spatial inputs. Demand concentrates in China, Japan, and South Korea through dense VR arcade networks that require standardized peripherals for free-roam multiplayer configurations.
- Standalone Controllers:Self-contained units with onboard processing and wireless connectivity, eliminating tethering to host headsets. Professional training simulations in aviation maintenance and surgical rehearsal specify these for untethered mobility in warehouse-scale facilities.
- Hybrid Controllers:Modular designs supporting both attached and detached operation modes.
- Attached Controllers:Fixed peripherals integrated into headset bundles through proprietary mounting systems.
Motion controllers command the established base. The steepest expansion runs through standalone controllers.
Technology:
Tracking modality selection determines occlusion resilience, positional accuracy, and infrastructure cost for venue operators scaling immersive attractions.
- Optical Tracking:Camera-based or laser base station triangulation achieving sub-millimeter accuracy in controlled lighting environments. Location-based entertainment venues in Seoul and Tokyo specify these for high-fidelity consumer experiences despite line-of-sight vulnerability.
- Haptic Feedback:Force-feedback actuators and vibrotactile arrays delivering tactile immersion through variable resistance and texture simulation. Premium procurement from surgical centers and aviation schools commands pricing multiples over standard vibration motors.
- Ultrasonic Tracking:Emitter-receiver arrays using time-of-flight calculations for occlusion-resistant positioning.
- Inertial Tracking:Accelerometer and gyroscope fusion for orientation data without external infrastructure.
Optical tracking dominates current installed base metrics. Ultrasonic alternatives are gaining share fastest in warehouse-scale multiplayer deployments.
End User:
Customer type segmentation captures divergent performance requirements, price sensitivity, and replacement cycle patterns across consumer and institutional buyers.
- Casual Gamers:Price-sensitive consumers purchasing controllers as accessories to mainstream headsets. Volume concentrates through retail channels in consumer electronics markets with attach rates tied to exclusive title releases.
- Professional Gamers:Competitive players demanding sub-20ms latency and customizable control mappings. Esports venues in South Korea drive refresh cycles through intensive utilization rates that accelerate hardware degradation.
- Gaming Developers:Studios requiring reference controllers for software optimization and QA testing.
- Educational Institutions:Schools and universities deploying controllers for STEM visualization and vocational training.
Casual gamers represent the volume anchor. Professional gamers drive the steepest technology upgrade trajectory.
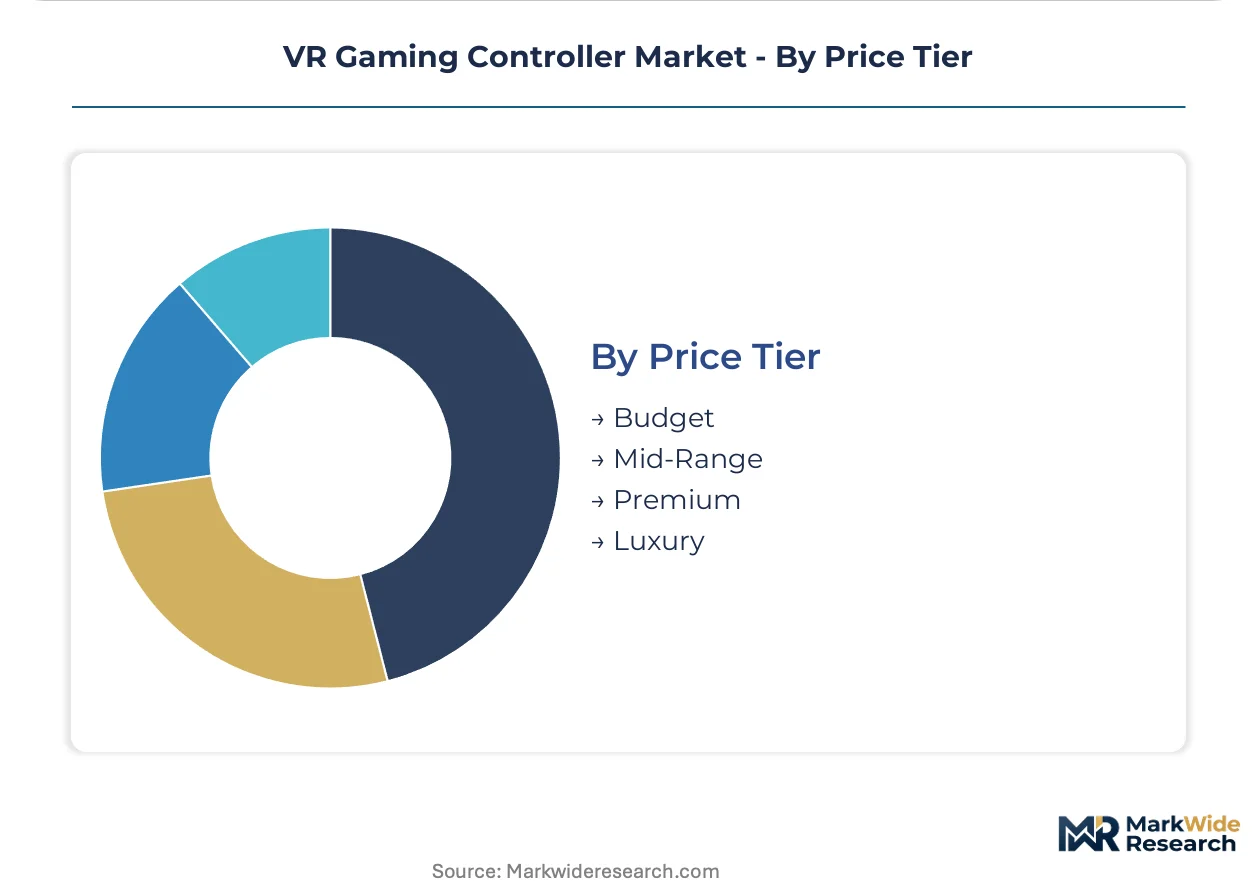
Price Tier:
Cost stratification aligns controller specifications with buyer willingness to pay for durability, precision, and ecosystem exclusivity.
- Premium:Force-feedback haptics, sub-millimeter tracking accuracy, and aerospace-grade materials. Professional training simulations in surgical rehearsal and aviation maintenance specify these despite five-figure unit pricing.
- Mid-Range:Balanced feature sets targeting enthusiast consumers and independent arcade operators. Seoul's Hongdae district VR cafes standardize procurement here to balance immersion quality against capital recovery timelines.
- Budget:Basic motion sensing without haptic actuation or advanced tracking.
- Luxury:Limited edition finishes, concierge support, and exclusive software bundles.
Mid-range controllers anchor volume shipments. Premium tier devices are expanding most quickly through enterprise training adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Controller trade flows skew toward net-import positions in Western markets against concentrated East Asian export capacity. Currency volatility and logistics costs are prompting regional assembly investments to shorten fulfillment cycles for venue operators.
United States
Location-based entertainment chains in Los Angeles and Orlando drive bulk procurement of haptic-enabled controllers for immersive attractions. FCC Part 15 emissions rules constrain wireless transmission power, forcing manufacturers to optimize antenna designs for range without amplification. Texas-based distributors now stock modular controller inventory to support 24-hour replacement guarantees demanded by large venue operators.
China
Dense VR arcade networks in Shenzhen and Shanghai generate recurring hardware refresh cycles and bulk replacement demand. GB standards administered by MIIT govern electromagnetic compatibility and electrical safety for domestic sales and re-export assembly. The Yangtze River Delta concentration of laser diode suppliers creates single-source vulnerability for base station components used in optical tracking systems.
Japan
Tokyo and Osaka arcade clusters specify controllers with detachable battery modules to simplify field replacement under high-utilization conditions. METI electrical appliance safety standards require extended cycle-life test data and thermal runaway containment documentation before market clearance. Kanto region venues are consolidating procurement around standardized ecosystems to reduce training overhead across multi-site deployments.
South Korea
Seoul's Hongdae district VR cafes have created localized service infrastructure with 24-hour replacement guarantees and on-site technician dispatch as standard contract terms. The national radio regulator enforces spectrum coordination for wireless controller operation in dense urban deployments. Daegu-Gyeongbuk manufacturing zones are attracting assembly investments to serve domestic demand and Southeast Asian export corridors.
Germany
Industrial training centers in Bavaria and North Rhine-Westphalia procure force-feedback controllers for aviation maintenance and surgical rehearsal applications. CE marking under the EU Radio Equipment Directive mandates interoperability testing for devices operating in shared spectrum bands. Stuttgart-area automotive suppliers are piloting VR controller integration into assembly line training protocols, creating adjacent demand beyond entertainment.
VR Gaming Controller Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in tracking hardware and haptic actuator supply. Market structure exhibits tiered consolidation with three to four ecosystem anchors controlling attach rates through exclusive title compatibility and proprietary tracking stacks. Dominant archetypes include headset-integrated platform owners, third-party peripheral specialists, and venue-focused durability manufacturers. Competitive moves center on backward integration into controller-headset software stacks and asset-light leasing models that convert upfront purchases into recurring revenue.
Within the platform-integrated tier, Sony Group Corporation and Meta Platforms exemplify ecosystem anchoring strategies that sustain controller sales through exclusive content libraries and proprietary tracking protocols. Valve Corporation occupies a distinct position through open-standard advocacy that attracts third-party peripheral makers to its tracking architecture. These three companies collectively represent the competitive fault lines between closed and open controller ecosystems.
| Leading Market Players |
|---|
| Sony Group Corporation |
| Meta Platforms |
| Valve Corporation |
| HTC Corporation |
| Microsoft Corporation |
| Razer Inc. |
| Logitech International S.A. |
| Nintendo Co., Ltd. |
| SteelSeries ApS |
| Others |
Pricing and Supply Chain Analysis
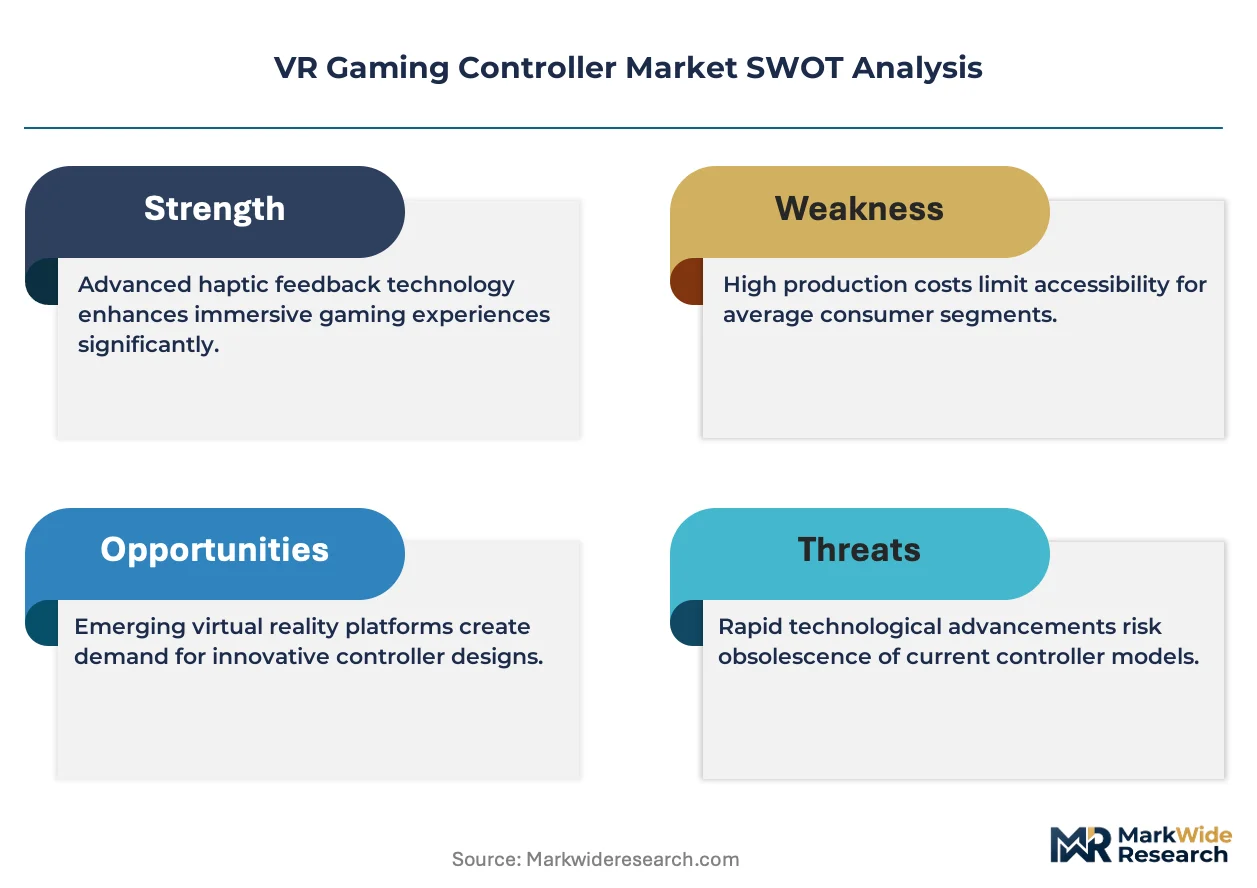
Laser diode array sourcing concentration in the Yangtze River Delta determines both premium tier spreads and supply chain configuration for optical tracking systems. Venue operators face pricing volatility when single-source component dependencies intersect with FCC Part 15 power constraints that force costlier antenna redesigns.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium controllers with force-feedback haptics command multiples over standard vibration units due to aerospace-grade materials and sub-millimeter tracking certification. Cost compression in the budget tier intensifies because LiDAR hand-tracking substitution threatens standalone controller attach rates. Casual gamers exhibit highest price sensitivity while professional training simulations show inelastic demand for tactile fidelity.
Supply Chain Analysis
Upstream feedstock for haptic actuators and inertial measurement units draws from China, South Korea, and Japan manufacturing clusters. Controller assembly rests on laser diode arrays, lithium-ion battery cells, and capacitive sensor substrates. Single-source vulnerability concentrates in base station optical components. Distribution runs through Texas-based inventory hubs serving location-based entertainment chains with 24-hour replacement guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LiDAR hand-tracking substitution threatens standalone controller attach rates, forcing incumbents to defend ecosystem lock-in through software-hardware integration.
For Market Incumbents: Entrench platform exclusivity through backward integration into headset-controller software stacks. Secure laser diode supply via long-term contracts with Yangtze River Delta suppliers to mitigate single-source exposure. Counter ultrasonic tracking displacement by embedding proprietary protocols in location-based entertainment reference designs. For New Entrants and Emerging Players: Pursue asset-light leasing models for independent arcade operators in India's emerging VR cafe networks. White-space concentrates in professional training simulations where force-feedback specifications outrun incumbent R&D cycles. Go-to-market leverage rests on direct technical support contracts bypassing regional distributors. For Investors and Strategic Acquirers: EU CE marking cybersecurity attestation requirements reshape the acquisition landscape by fragmenting certification pathways. Five-to-ten year viability favors targets with embedded firmware cryptographic verification capabilities. Watch for national cybersecurity framework announcements as inflection signals for regulatory compliance premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tracking Hardware | Captive laser diode supply from Yangtze River Delta suppliers insulates against base station component shortages. |
| Asset-Light Leasing Model Deployment | Hardware-as-a-service contracts convert upfront purchases into recurring revenue from Seoul VR cafe operators. |
| CE Marking Cybersecurity Certification | Firmware attestation compliance opens European location-based entertainment procurement channels. |
| Ultrasonic Tracking Module Adoption | Occlusion-resistant positioning eliminates line-of-sight failures in warehouse-scale multiplayer facilities. |
| Detachable Battery Module Specification | Field replacement capability satisfies Tokyo arcade operator demands under METI thermal management standards. |
Research Methodology
Initial hypotheses were tested against primary input from VR arcade operators, headset platform engineers, location-based entertainment procurement managers, and haptic actuator R&D directors and refined through secondary validation against FCC Part 15 filings, CE marking directive databases, METI electrical safety standards, and customs trade records. Bottom-up venue deployment counts triangulated against top-down headset shipment estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include controller form factor, tracking modality, end-user archetype, and price tier. CAGRs derived from hardware refresh cycle analysis and venue expansion trajectories. Forecast inputs incorporated laser diode supply constraints and regulatory attestation timeline assumptions.
Sensitivities concentrate around LiDAR hand-tracking substitution velocity and national cybersecurity framework rollout schedules. Forecasts reflect assumptions on arcade network densification and component supply concentration. Cross-checking against headset manufacturer disclosed attach rate data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Lottery Market
Gaming
Global Casino Market
Gaming
Animation, VFX & Game Market
Gaming
Online Strategy Games Market
Gaming
Global Trading Card Games Market
Gaming
Simulation Video Game Market
Gaming
Mobile and Handheld Gaming Market
Gaming
LAMEA Gaming Posters Market
Gaming
Slot Machine Market
Gaming
Global Casino and Gaming Market
Gaming
South Korea Subscription-Based Gaming Market
Gaming
Australia Casino Tourism Market
Gaming
North America Casino Gambling Market
Gaming
Game Applications Market
Gaming
Latin America Mobile Gaming Market
Gaming
GCC Gaming Headsets Market