
 Puzzle Video Game Market | 2026-2036
Puzzle Video Game Market Size, Share, and Industry Trends Forecast 2026-2036
Puzzle Video Game Market Insights
Mobile app store commission structures are rewriting how puzzle studios monetize their player bases. Tencent Games leverages its WeChat ecosystem to anchor distribution across China's super-app environment. Playtika specializes in live-ops mechanics that sustain engagement across its social casino-puzzle hybrid portfolio. Nexon dominates premium PC puzzle releases in South Korea through its long-running MapleStory IP extensions.
Puzzle video games constitute interactive software built on deterministic or stochastic rule systems requiring pattern recognition, spatial reasoning, or logical deduction to progress through discrete challenge states; engines typically run at 30-60 frames per second with input latencies below 100 milliseconds to preserve tactile satisfaction in tile-matching and physics-based mechanics. Match-3 titles occupy the largest revenue pool due to their low cognitive load and high session frequency among casual demographics. Mobile platform distribution leads volume but faces margin compression from store fees, while ad-supported monetization grows fastest in emerging markets where credit card penetration lags. Subscription models concentrate among puzzle enthusiasts seeking ad-free experiences with expanded level libraries.
The ESRB and PEGI rating frameworks govern content classification and age-gating for puzzle titles distributed in North America and Europe, directly affecting marketing channels and storefront visibility. China's SAMR enforces real-name registration and playtime limits for minors, forcing developers to architect separate progression systems for underage accounts. South Korea's GRAC mandates probability disclosures for gacha-style puzzle mechanics, reshaping monetization design across East Asian releases. Stakeholders must monitor how platform holders like Apple and Google adjust store policies around alternative payment systems, as these rulings will determine whether studios can reclaim the fifteen to thirty percent commissions that currently flow to distributors.
Market Dynamics
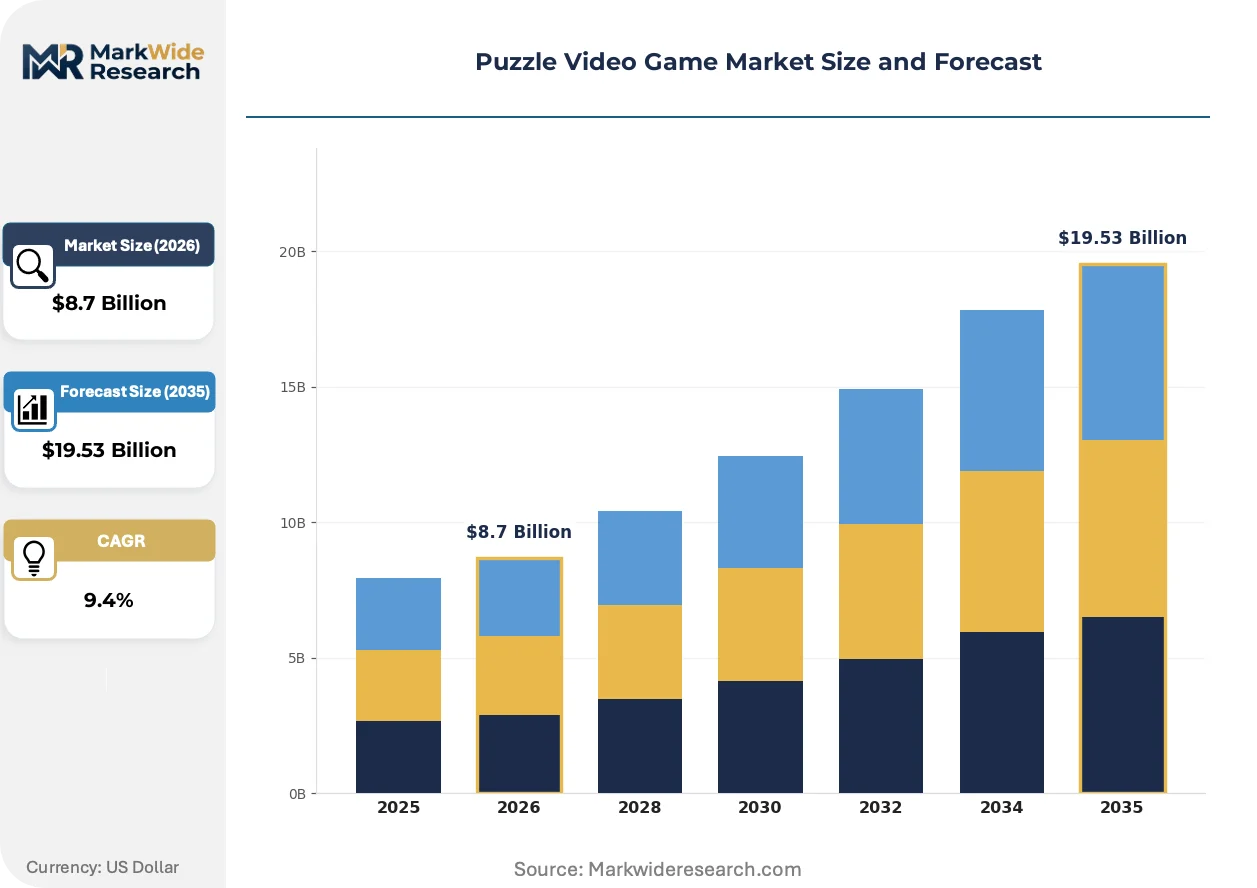
Mobile platform commission structures are compressing studio margins while simultaneously forcing monetization innovation toward direct-to-consumer channels and hybrid ad-subscription models.
Growth Catalysts
- WeChat ecosystem penetration:China's super-app environment enables frictionless distribution and social viral mechanics that reduce user acquisition costs for puzzle developers targeting casual demographics.
- Probability disclosure mandates:South Korea's GRAC regulations on gacha mechanics are legitimizing transparent monetization designs that build longer player lifecycles and reduce regulatory risk across East Asian releases.
- Esports-integrated formats:Competitive puzzle variants in South Korea's metropolitan gaming corridors are attracting sponsorship capital and extending session depth beyond traditional casual play patterns.
Market Restraints
- Store fee compression:Apple and Google app store commissions of fifteen to thirty percent structurally cap net revenue per user across mobile-first puzzle portfolios.
- Credit infrastructure gaps:Emerging market monetization remains constrained by low credit card penetration, forcing reliance on ad-supported models with inferior unit economics.
- Content review timelines:China's SAMR framework imposes unpredictable localization delays that extend time-to-revenue for foreign-developed titles entering the domestic market.
Strategic Opportunities
- Alternative payment channels:Platform policy shifts around external billing systems in the European Union and United States could restore margin capture currently flowing to distributors.
- Subscription tier expansion:Ad-free experience bundles with expanded level libraries represent underpenetrated white space among puzzle enthusiasts seeking uninterrupted play sessions.
- Cloud-streaming convergence:Integration of puzzle mechanics with low-latency streaming infrastructure enables browser-based distribution that bypasses native app store gatekeeping entirely.
Industry Challenges
- Live-ops talent scarcity:Sustained engagement mechanics require specialized data science and event design capabilities that outpace current educational pipeline output.
- Multi-territory compliance architecture:Simultaneous adherence to ESRB, PEGI, GRAC, and SAMR frameworks demands redundant content versioning systems that inflate operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Puzzle Video Game Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Match-3, Sudoku, Jigsaw, Logic Puzzles Platform: Mobile, PC, Console, Web-based Monetization Model: In-app Purchases, Premium Purchase, Subscription, Ad-supported Target Audience: Casual Gamers, Puzzle Enthusiasts, Competitive Players, Family-Friendly |
| Companies Covered | Nexon, Bandai Namco Entertainment, Tencent Games, Koei Tecmo, Niantic, 37Games, Square Enix, Neowiz, Playtika, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Puzzle Video Game Market Trends and Innovations
Generative tooling and procedural content systems are compressing production timelines while regulatory fragmentation across major territories is forcing modular compliance architectures.
Procedural level generation is digitizing content pipeline economics for mid-tier puzzle studios. Teams adopting these systems reduce manual design hours per release by half while maintaining output velocity. The structural consequence is compressing development cycles from months to weeks for seasonal event content.
REACH chemical safety extensions and emerging EU AI Act provisions are imposing documentation burdens on puzzle titles incorporating machine-generated assets. Studios must now maintain provenance records for algorithmically created visual elements. European releases face the steepest compliance cost inflation as these frameworks mature.
Buyer concentration around subscription bundling is consolidating player spending into platform-agnostic services like Apple Arcade and Google Play Pass. Traditional premium download sales are contracting as these channels capture puzzle enthusiasts seeking catalog breadth. This pattern is most pronounced in North American and Western European markets where credit infrastructure supports recurring billing adoption.
Puzzle Video Game Market Segmentation
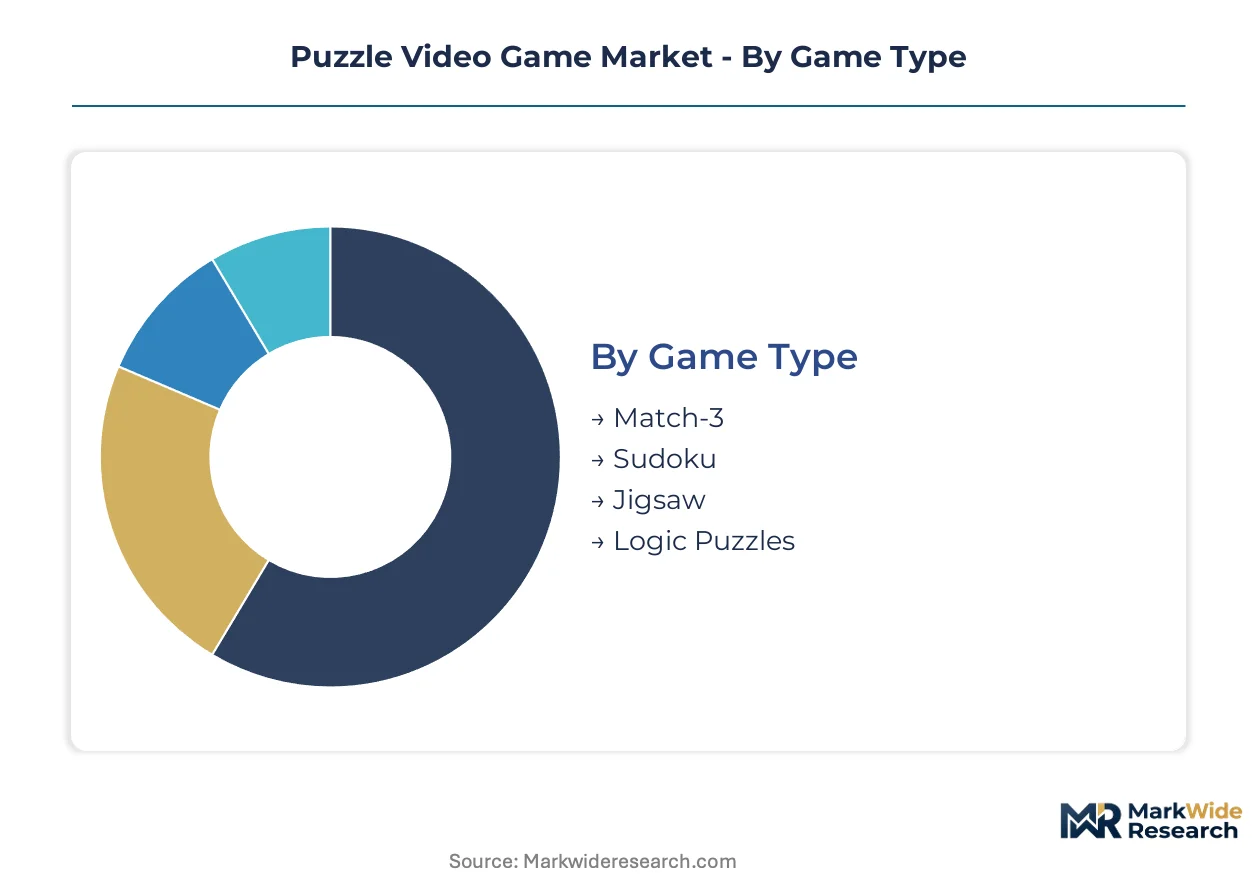
Puzzle video games fragment across gameplay mechanics, distribution infrastructure, revenue architecture, and player psychographics. Understanding these intersecting dimensions reveals where studios can defend margin position and where new entrants face structural barriers.
Game Type:
The use-case spectrum spans rapid session entertainment to deep cognitive engagement, with each format commanding distinct production economics and player lifetime value profiles.
- Match-3:Tile-swapping mechanics built on deterministic pattern recognition algorithms sustain the highest session frequency among casual demographics. South Korea's metropolitan gaming corridors concentrate demand for competitive variants, where esports-integrated formats attract sponsorship capital and extend monetization depth beyond traditional casual play patterns.
- Sudoku:Number-placement logic built on Latin square mathematics appeals to puzzle enthusiasts seeking algorithmic purity without monetization friction. China's SAMR age-rating requirements shape product localization timelines for numeric puzzle titles targeting family demographics, forcing separate progression architectures for underage accounts.
- Jigsaw:Spatial assembly mechanics leverage image segmentation algorithms with variable piece counts scaling difficulty curves. Digital adaptations capture analog puzzle enthusiasts migrating from physical formats.
- Logic Puzzles:Deductive reasoning systems spanning nonograms, sliding blocks, and physics-based challenges serve niche enthusiast segments with higher willingness-to-pay for premium content libraries.
The dominant share belongs to Match-3, while Logic Puzzles are closing the gap fastest through subscription bundling into platform-agnostic services.
Platform:
Distribution economics vary sharply across hardware ecosystems, with margin structures and addressable audiences diverging by territory.
- Mobile:Touch-native input systems running at 30-60 frames per second with sub-100 millisecond latency requirements dominate volume distribution. Southeast Asia concentrates adoption among casual gamers where credit card penetration constraints force hybrid ad-subscription monetization innovation.
- PC:Mouse-precision and keyboard-modifier inputs enable complex puzzle mechanics with higher cognitive load thresholds. Nexon anchors premium releases in South Korea through long-running IP extensions with expanded level libraries.
- Console:Controller-optimized haptic feedback and achievement integration serve family-friendly demographics in North American and Western European living room contexts.
- Web-based:Browser-based distribution bypasses native app store gatekeeping through low-latency streaming infrastructure, emerging as an alternative channel where platform policy disputes create margin recovery opportunities.
Mobile captures the largest addressable audience, yet Web-based distribution is expanding most quickly as studios seek commission relief from Apple and Google store fees.
Monetization Model:
Revenue architecture selection directly determines customer acquisition economics and regulatory exposure across territorial frameworks.
- In-app Purchases:Microtransaction systems for power-ups, cosmetic assets, and progression acceleration dominate mobile monetization. South Korea's GRAC mandates probability disclosures for gacha-style mechanics, reshaping design transparency requirements across East Asian releases.
- Premium Purchase:Upfront download fees with complete content unlocks concentrate among PC and console puzzle enthusiasts seeking uninterrupted experiences without live-ops dependency.
- Subscription:Recurring billing for ad-free catalog access with expanded level libraries consolidates player spending into Apple Arcade and Google Play Pass bundles. North American and Western European markets show strongest credit infrastructure support for this model.
- Ad-supported:Rewarded video and interstitial placements sustain emerging market participation where payment friction limits conversion. Unit economics remain inferior to direct monetization but enable scale without credit card penetration.
In-app Purchases retain the dominant revenue position, though Subscription is gaining share fastest through platform bundling and enthusiast demand for uninterrupted play sessions.
Target Audience:
Psychographic segmentation aligns content complexity, social features, and monetization pressure with player motivation profiles.
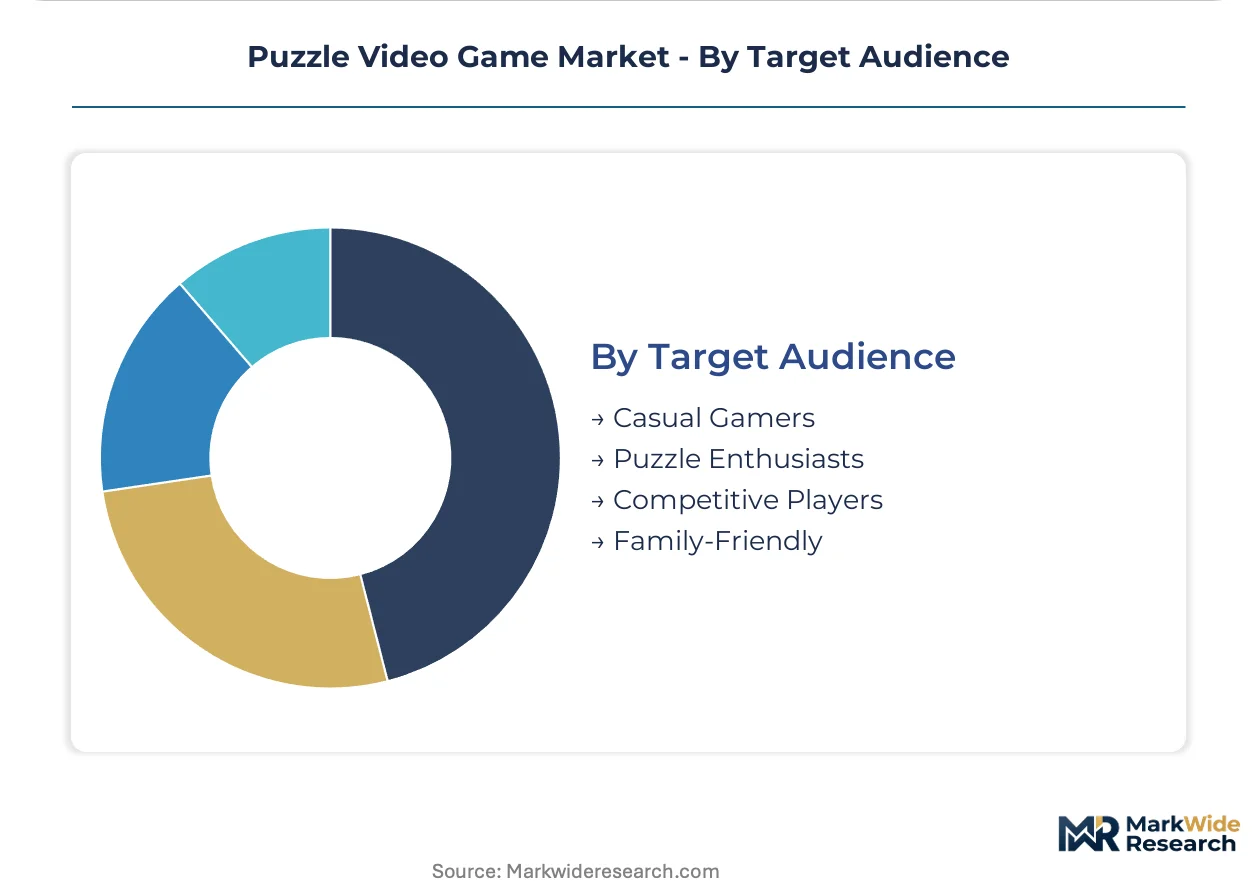
- Casual Gamers:Low-cognitive-load preference with high session frequency and tolerance for ad-supported or light in-app purchase models. Tencent Games leverages WeChat ecosystem penetration to reduce acquisition costs for this segment across China's super-app environment.
- Puzzle Enthusiasts:Depth-seeking players with high willingness-to-pay for premium content, ad-free experiences, and expanded level libraries. Playtika specializes in live-ops mechanics sustaining engagement across social casino-puzzle hybrid portfolios targeting this demographic.
- Competitive Players:Ranking-system and tournament-motivated users driving esports-integrated format development in South Korea's metropolitan gaming corridors.
- Family-Friendly:Multi-generational accessibility requirements with strict content rating adherence to ESRB, PEGI, and SAMR frameworks governing age-gating and storefront visibility.
Casual Gamers command the largest population share, while Competitive Players are climbing the fastest through esports sponsorship capital and extended session depth mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The subsea cable networks linking Singapore to Los Angeles and Tokyo underpin digital distribution velocity across the Asia-Pacific rim. Data center clusters in Seoul, Tokyo, and Singapore process match-3 session telemetry with sub-50 millisecond latency. Regulatory divergence across SAMR, GRAC, and ESRB frameworks forces modular compliance architectures.
China
Tencent Games anchors distribution through WeChat's super-app ecosystem, reducing user acquisition costs for match-3 titles targeting casual demographics. SAMR enforces real-name registration and playtime limits for minors, forcing separate progression architectures for underage accounts. Shanghai and Beijing concentrate development studios navigating unpredictable content review timelines that extend time-to-revenue for foreign-developed titles.
South Korea
Esports-integrated puzzle formats attract sponsorship capital in Seoul's metropolitan gaming corridors, extending session depth beyond traditional casual play patterns. GRAC mandates probability disclosures for gacha-style mechanics, legitimizing transparent monetization designs that reduce regulatory risk. Busan-Ulsan and Daegu-Gyeongbuk host live-ops talent clusters sustaining engagement mechanics for social casino-puzzle hybrids.
United States
Apple and Google app store commissions of fifteen to thirty percent structurally cap net revenue per user across mobile-first puzzle portfolios. ESRB rating frameworks govern content classification and age-gating, directly affecting marketing channels and storefront visibility. California's Bay Area and Seattle-Tacoma corridor concentrate platform policy lobbying efforts around alternative payment system litigation.
Japan
Puzzle enthusiasts demonstrate high willingness-to-pay for premium content libraries and ad-free subscription experiences. METI guidelines on consumer protection influence gacha mechanic transparency expectations across mobile releases. Tokyo and Osaka anchor development studios specializing in IP-extended puzzle franchises with expanded level libraries.
Germany
PEGI rating frameworks enforce strict age-gating requirements that shape storefront visibility and marketing channel selection for family-friendly puzzle titles. REACH chemical safety extensions impose documentation burdens on titles incorporating machine-generated visual assets. Berlin-Brandenburg and Bavaria host mid-tier studios adopting procedural level generation to compress seasonal content production cycles.
Puzzle Video Game Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The market fragments across super-app ecosystem operators, live-ops mechanics specialists, and premium IP extension houses. Three archetypes dominate: super-app distributors leveraging social viral mechanics, live-ops studios sustaining engagement through data-driven event design, and IP holders monetizing legacy franchises through puzzle format adaptations. Competitive moves concentrate on alternative payment channel litigation and subscription tier bundling into platform-agnostic services.
Within the super-app distributor tier, Tencent Games exemplifies ecosystem-anchored distribution. Among live-ops specialists, Playtika occupies a position representing sustained engagement mechanics for social casino-puzzle hybrids. Nexon sits within the IP extension archetype, anchoring premium PC puzzle releases through long-running franchise adaptations. These three entities collectively illustrate the strategic divergence between platform-captive distribution and direct-to-consumer monetization recovery.
| Leading Market Players |
|---|
| Nexon |
| Bandai Namco Entertainment |
| Tencent Games |
| Koei Tecmo |
| Niantic |
| 37Games |
| Square Enix |
| Neowiz |
| Playtika |
| Others |
Pricing and Supply Chain Analysis
Live-ops talent clusters in South Korea's Busan-Ulsan corridor anchor premium monetization design, concentrating margin capture with studios that sustain engagement mechanics for social casino-puzzle hybrids while commodifying execution layers elsewhere.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs puzzle video game monetization. Price differentiation rests on ad-free subscription depth, expanded level library access, and live-ops event intensity. Cost compression in ad-supported tiers is intensifying because emerging market credit infrastructure gaps force reliance on inferior unit economics. Casual gamers in Southeast Asia exhibit highest price sensitivity; puzzle enthusiasts in Japan and South Korea demonstrate least sensitivity due to willingness-to-pay for uninterrupted premium experiences.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for puzzle video game distribution. Development talent concentrates in South Korea, China, and Japan, with art production and QA services drawing from Vietnam and the Philippines. Raw material dependencies span game engine licensing, cloud infrastructure provisioning, and user acquisition platform access. Single-source vulnerability sits with Apple and Google app store gatekeeping, which controls downstream distribution through mobile-native commission structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized data science and event design capabilities for sustained engagement mechanics outpace educational pipeline output, creating acute talent scarcity that reshapes competitive dynamics across live-ops-dependent studios.
For Market Incumbents: Harden live-ops architecture through captive talent acquisition in Seoul's metropolitan gaming corridors, insulating against poaching from emerging social casino entrants. Deepen vertical integration into cloud-streaming infrastructure to bypass Apple and Google store commission extraction. Threat substitution from web-based distribution alternatives demands preemptive channel control investment. For New Entrants and Emerging Players: Establish a beachhead in browser-based puzzle distribution where platform policy disputes create margin recovery opportunities for commission-free monetization. Target South Korea's esports-integrated competitive puzzle segment, the most penetrable white space attracting sponsorship capital. Go-to-market leverage rests on low-latency streaming partnerships that circumvent native app store gatekeeping entirely. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed live-ops specialists holding proprietary engagement mechanics but facing succession and platform dependency risks. Long-term viability favors studios with modular compliance architectures spanning SAMR, GRAC, and ESRB frameworks. Watch Apple and Google alternative payment system litigation outcomes as the decisive inflection signal for margin structure recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Live-Ops Talent Acquisition | Captive data science and event design teams in Seoul-Busan clusters secure engagement mechanics differentiation. |
| Cloud-Streaming Infrastructure Investment | Low-latency browser distribution bypasses Apple and Google commission structures entirely. |
| Alternative Payment Channel Litigation | European Union and United States policy shifts could restore fifteen to thirty percent margin capture. |
| Modular Compliance Architecture | Simultaneous SAMR, GRAC, and ESRB adherence reduces time-to-revenue for multi-territory releases. |
| Esports Format Integration | Competitive puzzle variants in South Korea attract sponsorship capital and extend session depth. |
Research Methodology
A standing panel of live-ops directors, monetization designers, platform policy counsel, and user acquisition specialists provided ongoing calibration for primary interview protocols. Secondary validation drew from SEC filings, App Annie/Sensor Tower mobile intelligence, hyperscaler capex disclosures, and GRAC probability disclosure enforcement records. Bottom-up studio revenue modeling and top-down platform commission flow analysis were triangulated to constrain estimate variance.
Scenario-bracketing framed projections across the analysis window, with CAGRs derived from segment-level adoption curves and territory-specific regulatory lag assumptions. Segmentation dimensions spanned game type mechanics, platform distribution infrastructure, monetization architecture, and player psychographic profiles. Forecast inputs incorporated SAMR content review timeline distributions and emerging market credit infrastructure penetration trajectories.
Stress conditions across platform policy litigation outcomes, live-ops talent availability, and alternative payment system adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions around regulatory enforcement consistency and cloud infrastructure cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Latin America Gaming Headsets Market
Gaming
Gaming Gadgets Market
Gaming
Mobile Shooter Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
Lottery Market
Gaming
India Gaming Market
Gaming
VR Gaming Accessories Market
Gaming
GCC Gaming Headsets Market
Gaming
Traditional Casual Games Market
Gaming
Asia-Pacific Video Game Software Market
Gaming
United States Virtual Reality Gaming Market
Gaming
Latin America Mobile Gaming Market
Gaming
Europe Casino Gambling Market
Gaming
Global Subscription-Based Gaming Market
Gaming
Asia-Pacific in-Game Advertising Market
Gaming
South Korea Subscription-Based Gaming Market