
 3D Gaming Technology Market | 2026-2036
3D Gaming Technology Market Size, Share, and Industry Trends Forecast 2026-2036
3D Gaming Technology Market Intelligence
Cloud-based rendering, which substitutes remote server power for local GPU hardware, is restructuring the cost-to-performance ratio for end-users. Epic Games leverages its Unreal Engine to dominate the high-fidelity development tool market. Electronic Arts sustains its market position through a vast portfolio of established gaming franchises. Service providers like Keywords Studios specialize in co-development and quality assurance for major publishers, supporting the complex production pipelines required for modern 3D titles.
3D gaming technology encompasses software and hardware systems that render three-dimensional graphics in real time by processing polygonal models, textures, and lighting. Its primary commercial purpose is to build immersive and interactive entertainment experiences for consumers. Within the technology segment, augmented reality represents a high-growth frontier compared to the mature stereoscopic 3D category. Virtual reality gaming applications are a significant source of demand for innovations in rendering performance and haptic feedback.
Regulatory frameworks like Europe's GDPR govern player data, while content rating systems such as PEGI and the ESRB dictate market access. In China, MEE policies on data center energy efficiency impact the economics of cloud gaming platforms. The key strategic decision for developers involves balancing investments in graphical fidelity against rising computational costs. Stakeholders must monitor the evolution of intellectual property law concerning AI-generated game assets.
Market Dynamics
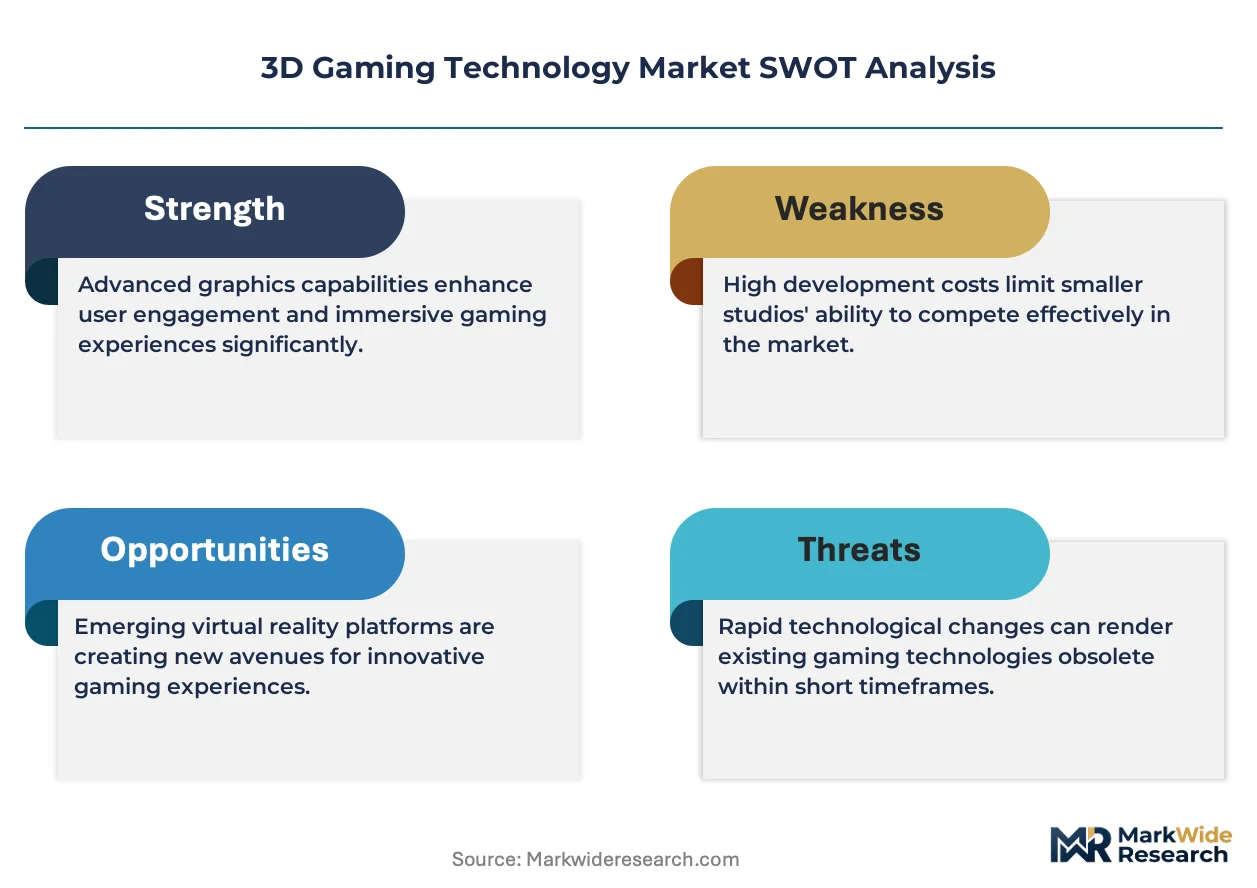
The central tension shaping the 3D gaming technology market is the developer's need to balance escalating consumer demand for photorealistic graphical fidelity against the sharply rising computational and financial costs required to produce and run such experiences.
Growth Catalysts
- AI-Powered Development:The integration of artificial intelligence into development tools, particularly for real-time rendering and asset generation, is significantly reducing production timelines and enabling smaller studios to create higher-fidelity content.
- Esports Spectatorship:Demand from professional Esports organizations for more immersive and visually compelling spectator experiences is driving investment in advanced real-time rendering, camera systems, and augmented reality overlays for live broadcasts.
- Advanced Digital Infrastructure:The high-density connectivity and sophisticated gaming infrastructure in markets like South Korea create a concentrated demand hub for technologies supporting large-scale competitive and social gaming platforms.
Market Restraints
- High Hardware Costs:The substantial cost of high-end GPUs and professional-grade development workstations acts as a significant financial barrier, particularly for independent developers and smaller studios, limiting market entry and experimentation.
- Data Privacy Compliance:Regulatory frameworks such as Europe's GDPR impose strict rules on the collection and processing of player data, complicating the development of personalized experiences and increasing compliance overhead for global publishers.
- Persistent Technical Hurdles:The challenge of overcoming the "uncanny valley" in digital human rendering remains a key technical restraint, limiting the achievement of full photorealism and emotional believability in character-driven games.
Strategic Opportunities
- Technology Convergence:Combining 3D gaming engines with advanced haptic feedback systems and next-generation VR headsets presents an opportunity to create deeply immersive experiences that go beyond visual rendering into tactile sensation.
- Industrial Simulation:Gaming engines represent a high-growth frontier for enterprise applications, including architectural visualization, automotive design, and factory-floor simulations, offering a new revenue stream for technology providers.
- Optimized Mobile Experiences:Developing 3D gaming technologies optimized for the mobile chipset capabilities in emerging markets across Southeast Asia and Latin America opens access to a massive and growing player base.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of specialized talent, including real-time rendering engineers and technical artists with deep expertise in platforms like Unreal Engine, creates production bottlenecks and drives up labor costs.
- Intellectual Property Ambiguity:Stakeholders face uncertainty regarding the evolving landscape of intellectual property law as it pertains to AI-generated game assets, creating legal and financial risks for developers using these new tools.
- Production Pipeline Complexity:The immense scale and complexity of modern AAA game development require sophisticated project management and quality assurance processes, posing a significant operational challenge to delivering titles on time and on budget.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Gaming Technology Market |
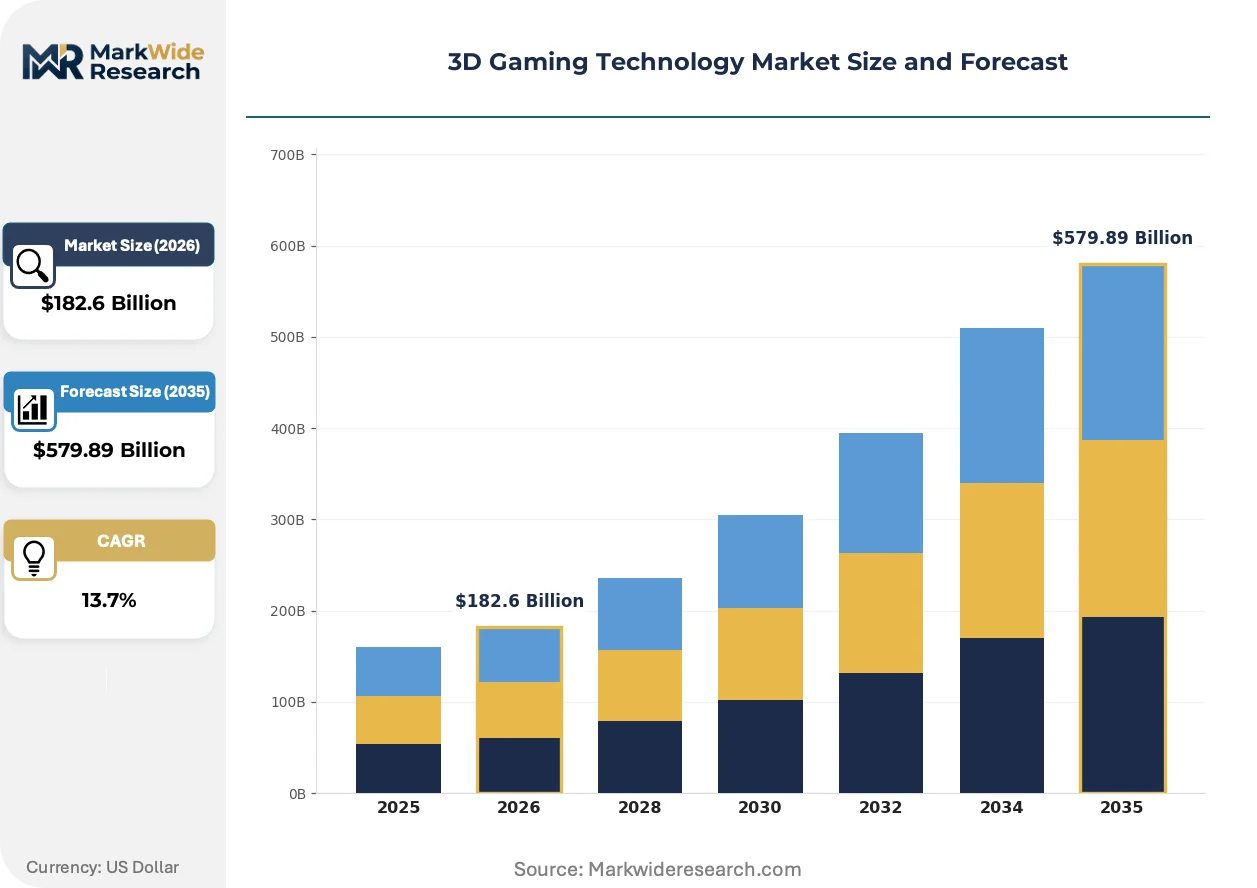
| Market Size in 2026 | $182.6 Billion |
| Market Size in 2035 | $579.89 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Volumetric Displays, Holography, Stereoscopic 3D, Augmented Reality, Light Field Technology Application: Virtual Reality Gaming, Mobile 3D Games, Simulation Training, Location-Based Entertainment, Social Gaming End User: Game Developers, Content Creators, Theme Parks, Esports Organizations, Educational Institutions Deployment: Console, PC, Handheld Devices, Cloud Gaming Platforms, Arcade Systems |
| Companies Covered | Keywords Studios, Cubix, Electronic Arts, Room 8 Studio, Stepico, Epic Games, Kevuru Games, Pingle Studio, Virtuos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Gaming Technology Market Strategic Shifts & Innovations
The democratization of high-fidelity development tools is occurring alongside a fundamental shift in computing paradigms, with cloud-based rendering and subscription models altering the industry's economic and technical foundations. These forces are reshaping how 3D gaming experiences are created, distributed, and consumed.
Real-time ray tracing is a rendering technique that simulates the physical behavior of light to generate highly realistic lighting, shadows, and reflections. This technology is being rapidly adopted by AAA game studios for premium PC and console titles. The rendering technique is expanding into cloud streaming services and mid-range hardware, resetting consumer performance expectations and making photorealism a more accessible standard across different market tiers.
The European Union’s AI Act introduces a risk-based framework for regulating artificial intelligence systems, which has direct implications for game development. This policy imposes new transparency and compliance duties on developers using AI for procedural content generation or dynamic difficulty adjustment. Game publishers targeting the EU are now auditing their AI pipelines to ensure alignment with the act's requirements on fairness and oversight.
A notable behavioral shift sees consumers moving away from one-time game purchases toward subscription-based access and live-service content models. This trend disrupts traditional retail distribution and elevates the importance of digital platforms that offer extensive content libraries. This consumption pattern is most prominent within the PC and console gaming segments in North America and Western Europe.
3D Gaming Technology Market Segmentation
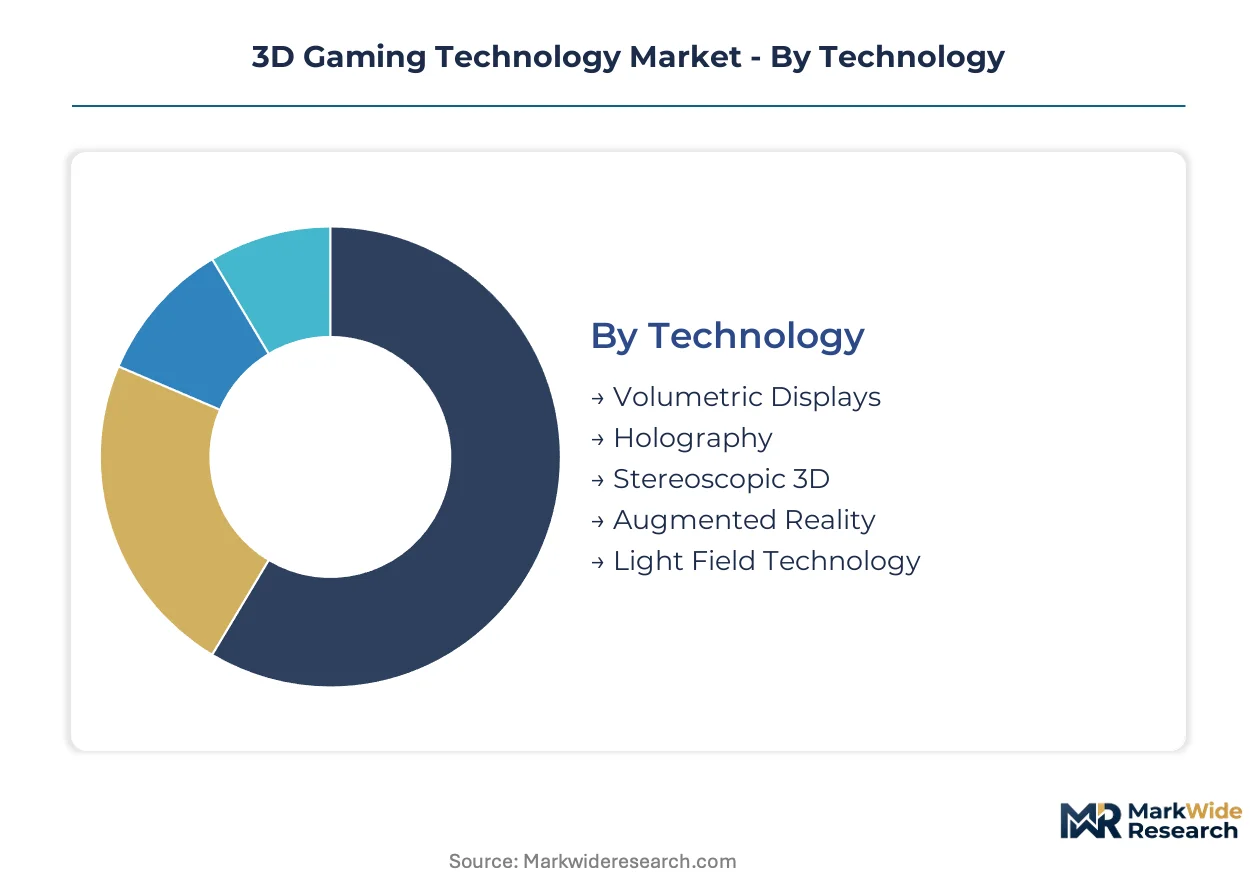
The 3D gaming technology market segments across distinct categories, reflecting diverse technological capabilities, application areas, end-user profiles, and deployment methods. Understanding these segments helps stakeholders identify specific growth vectors and target strategic investments. Each category reveals unique demand patterns and competitive dynamics.
Technology:
Developers prioritize specific technologies based on the immersive quality and interactivity they aim to deliver to consumers.
- Augmented Reality:This technology overlays digital information onto the real world, enhancing user perception with interactive 3D elements. Demand concentrates in mobile gaming and live event spectator experiences due to accessible hardware and immersive potential.
- Light Field Technology:This advanced rendering technique captures and reproduces light rays from multiple angles, enabling true 3D perception without special glasses. Demand is concentrating in high-end simulation and professional visualization for its unparalleled depth perception.
- Volumetric Displays:These displays create 3D images that occupy physical space, allowing viewing from any angle without external aids.
- Holography:Holographic systems project three-dimensional images into space, offering realistic visual depth and interaction.
- Stereoscopic 3D:This traditional method uses two slightly offset images to create a perception of depth, primarily through specialized glasses.
Volume sits with Stereoscopic 3D due to its established presence; growth tilts toward Augmented Reality.
Application:
Applications for 3D gaming technology span a wide spectrum, each addressing distinct user needs and commercial objectives.
- Virtual Reality Gaming:These applications immerse users in fully simulated digital environments, requiring head-mounted displays and haptic feedback. Demand for VR gaming is concentrating in PC and console platforms, driven by advancements in rendering performance and sensory immersion.
- Mobile 3D Games:These games are designed for smartphones and tablets, leveraging device-specific capabilities for 3D graphics and touch interfaces. Demand is concentrating in emerging markets across Southeast Asia and Latin America due to widespread smartphone penetration and accessible content.
- Simulation Training:This segment uses 3D environments to replicate real-world scenarios for professional training in industries like aviation and healthcare.
- Location-Based Entertainment:These experiences utilize 3D technology in physical venues, offering interactive attractions such as VR arcades and themed rides.
- Social Gaming:This category integrates 3D graphics into online platforms where players interact and engage in shared virtual spaces.
Mobile 3D Games command the largest user base, while Virtual Reality Gaming is expanding most quickly.
End User:
End users drive innovation and adoption, with their specific requirements shaping the development of 3D gaming technologies.
- Esports Organizations:These entities require advanced 3D technology for immersive spectator experiences, including real-time rendering and AR overlays for broadcasts. Demand concentrates in South Korea and North America, fueled by high-stakes competitive gaming and fan engagement.
- Game Developers:This segment comprises studios and individuals who create 3D games, demanding robust engines, asset creation tools, and rendering solutions. Demand concentrates on tools that accelerate development cycles and reduce computational costs, like AI-powered asset generation.
- Content Creators:Individual artists and small teams leverage 3D tools for virtual production, digital art, and interactive media beyond traditional games.
- Theme Parks:These entertainment venues utilize 3D technology for attractions, rides, and interactive exhibits to enhance visitor immersion.
- Educational Institutions:Schools and universities employ 3D gaming technology for interactive learning modules, virtual labs, and skill development simulations.
Game Developers represent the foundational demand, with Esports Organizations driving significant innovation in real-time rendering.
Deployment:
Deployment platforms dictate accessibility and performance, influencing how 3D gaming experiences reach consumers.
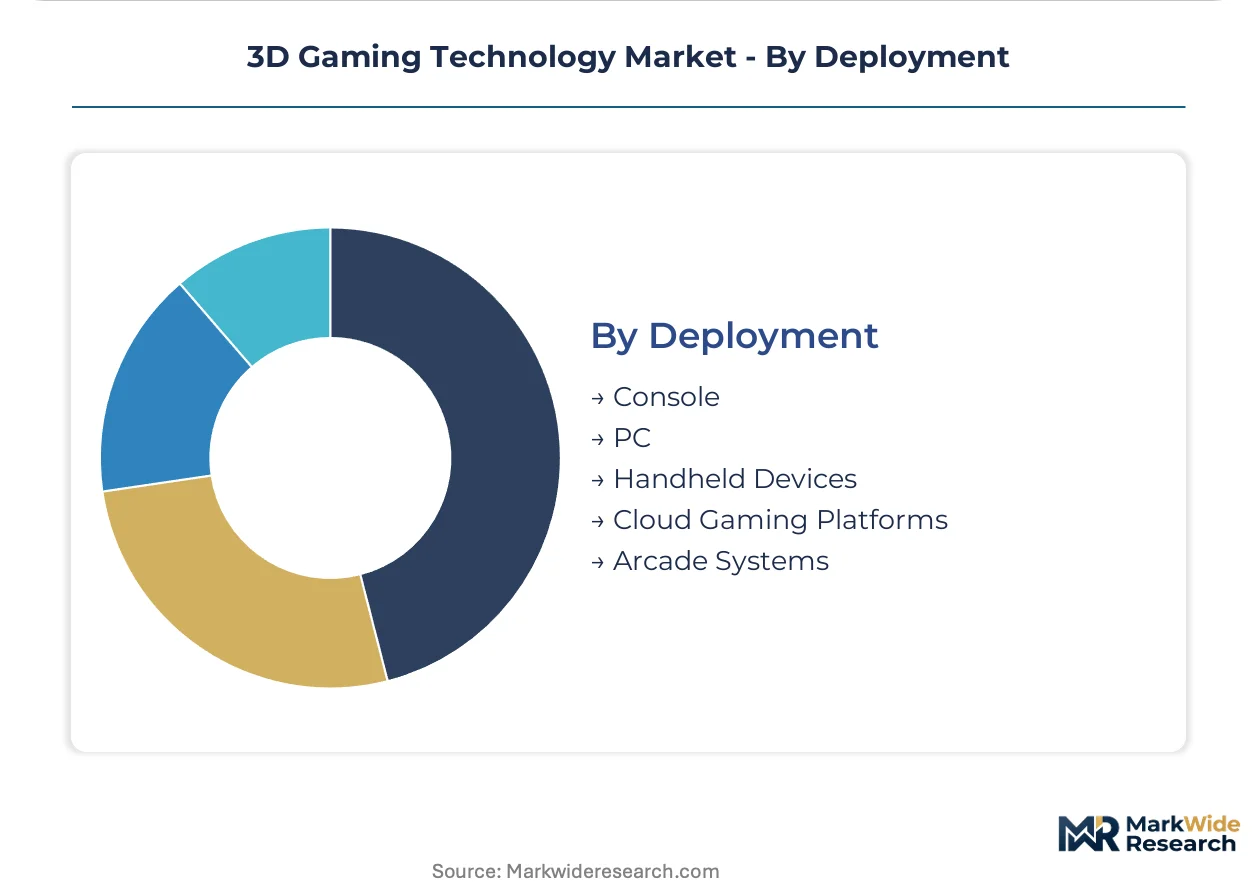
- Cloud Gaming Platforms:These services stream 3D games from remote servers, reducing local hardware requirements for end-users. Demand concentrates in markets with high-density connectivity and robust digital infrastructure, enabling seamless, high-fidelity streaming.
- PC:Personal computers remain a primary deployment method for high-fidelity 3D games, offering extensive customization and performance capabilities. Demand concentrates among enthusiasts and professional gamers in established markets due to powerful hardware and diverse software ecosystems.
- Console:Dedicated gaming consoles provide optimized hardware and curated game libraries, offering a streamlined 3D gaming experience.
- Handheld Devices:Portable gaming devices and smartphones enable on-the-go 3D gaming, prioritizing accessibility and battery efficiency.
- Arcade Systems:Traditional arcade machines offer unique, often large-scale, interactive 3D experiences in public entertainment venues.
PC deployment maintains strong market share, while Cloud Gaming Platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Incentive programs within South Korea's Gyeonggi Province are driving concentrated demand for 3D gaming technology. These regional initiatives foster an ecosystem conducive to advanced game development and competitive esports. The global market exhibits varied regional adoption patterns influenced by infrastructure, regulatory frameworks, and consumer preferences.
South Korea
Demand for advanced real-time rendering and immersive spectator experiences from esports organizations is high. Government support for digital content industries, including favorable policies for game development studios, underpins market expansion. Seoul's Gangnam district, a hub for IT and entertainment, concentrates numerous gaming studios and esports facilities.
United States
The United States exhibits strong demand for high-fidelity PC and console gaming, alongside significant investment in virtual reality applications. The ESRB content rating system dictates market access for game titles, influencing content development. Los Angeles, California, serves as a major cluster for game development studios and entertainment technology firms.
Germany
German consumers show strong engagement with PC and console gaming, while industrial applications like simulation training are also expanding. The EU AI Act introduces a risk-based framework for AI systems, directly impacting game development practices. Berlin, with its vibrant tech scene, hosts numerous independent game developers and incubators.
China
Demand for mobile 3D games and cloud gaming platforms is substantial, driven by widespread smartphone penetration. MEE policies on data center energy efficiency significantly impact the operational economics of cloud gaming services. Shanghai's Yangtze River Delta region is a key development and publishing hub for both domestic and international gaming companies.
3D Gaming Technology Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, defining the competitive dynamics within the 3D gaming technology market. The market structure is tiered, with distinct players focusing on engine development, content publishing, or specialized production services. Key strategic archetypes include technology providers, large-scale publishers, and co-development/QA specialists. Technology licensing and strategic partnerships represent dominant competitive moves for market participants.
Specialists in development tools and services represent distinct market positions. Epic Games, for instance, anchors the engine development segment with its Unreal Engine, providing foundational technology for numerous titles. Electronic Arts exemplifies the large publisher archetype, leveraging an extensive portfolio of established gaming franchises. Keywords Studios occupies a position within the specialized co-development and quality assurance segment, supporting complex production pipelines for major publishers globally.
| Leading Market Players |
|---|
| Keywords Studios |
| Cubix |
| Electronic Arts |
| Room 8 Studio |
| Stepico |
| Epic Games |
| Kevuru Games |
| Pingle Studio |
| Virtuos |
| Others |
Cost & Logistics Intelligence
The clear performance gap between high-fidelity AAA titles and accessible mobile 3D games manifests in divergent pricing models and specialized supply chain configurations for each segment. This bifurcation reflects distinct consumer expectations and hardware requirements.
Pricing Analysis
The volume-vs-margin split dictates pricing strategies. Licensing and royalty models dominate for foundational technologies like game engines, while project-based fees apply to co-development services. Price differentiation stems from graphical fidelity and the level of AI integration in development tools. Pricing pressure stems from intense competition within the mobile 3D gaming segment, driving down per-unit costs. Mobile 3D game players in emerging markets represent the most price-sensitive buyer segment, while Esports organizations exhibit lower price sensitivity for premium rendering solutions.
Supply Chain Analysis
Certification requirements for software and hardware components gate entry into certain segments. Geographic supply concentration for high-end GPUs centers on Taiwan, while specialized software development talent is often found in the United States and Europe. Raw material dependencies include advanced semiconductors and specialized software libraries. A structural supply chain risk is the scarcity of specialized talent like real-time rendering engineers. Distribution runs through digital platforms for games and cloud streaming services for remote rendering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 3D gaming technology market is increasingly a vertical-integration race, with major players pursuing end-to-end control over engine development, content creation, and distribution channels.
For Market Incumbents: Deepen proprietary engine capabilities to maintain a technological lead against rising development costs. Acquire specialized AI studios to mitigate intellectual property ambiguity surrounding AI-generated assets. Invest in cloud-native rendering solutions to counter the threat of hardware-agnostic platforms. Focus R&D on real-time ray tracing and advanced haptic feedback systems to differentiate premium offerings.
For New Entrants and Emerging Players: A price-point gap exists between premium console experiences and accessible mobile gaming. Target underpenetrated mobile 3D game markets in Southeast Asia and Latin America with optimized experiences. Leverage subscription-based access models to lower entry barriers for consumers. Focus on niche augmented reality applications with accessible hardware requirements. Develop specialized AI tools for asset generation to reduce production timelines for smaller studios.
For Investors and Strategic Acquirers: Re-rating potential sits with technology providers offering foundational rendering engines given the sustained demand for immersive content. Long-term viability is strong for firms enabling scalable content creation and distribution. Target specialized AI rendering studios or haptic feedback innovators for their unique technological capabilities. A signal to watch is the widespread adoption of next-generation VR headsets, indicating a market inflection point for immersive experiences.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Next-gen VR headset | Expands immersive experience frontier, drives hardware demand for consumers. |
| Strategic Partnership: Engine developer with cloud provider | Optimizes real-time rendering performance for cloud streaming services. |
| Acquisition of Specialist Firm: AI asset generation studio | Reduces content creation costs, accelerates development cycles for publishers. |
| Technology Licensing: Haptic feedback IP to game publishers | Enhances sensory immersion, differentiates gaming experiences for players. |
| Geographic Expansion: Mobile 3D game studio into Southeast Asia | Taps into large, accessible consumer base with high smartphone penetration. |
Research Approach
Independent corroboration across primary interviews, secondary industry reports, and financial filings underwrites the qualitative findings. This study involved in-depth discussions with game developers, esports organization managers, rendering engineers, and cloud platform architects. Secondary validation drew from industry association reports, technology whitepapers, and academic studies on real-time graphics.
The forecast framework was anchored to historical performance across comparable periods, establishing a baseline for future projections. This analytical framework modeled segmentation dimensions including technology, application, end-user, deployment, and regional adoption across the analysis window. Compound annual growth rates were derived from historical growth rates, market saturation points, and technological innovation cycles. Key forecast inputs included GPU performance trends and smartphone penetration rates.
Inputs from major game publishers, engine developers, and cloud service providers were available through the study window; gaps in emerging market infrastructure data introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements and regulatory stability. A model refresh is warranted upon material change in global digital infrastructure investment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Game API Market
Gaming
Global Gaming Market
Gaming
Advanced Digital Gaming Market
Gaming
RPG Games Market
Gaming
Europe Serious Gaming Market
Gaming
SLG Game Market
Gaming
Mobile Gaming Market
Gaming
Global Game Testing Service Market
Gaming
Board Games Market
Gaming
Animation, VFX & Game Market
Gaming
South Asia Mobile Gaming Market
Gaming
Global Tarot Cards Market
Gaming
FPS Game Market
Gaming
Shooter Game Market
Gaming
Asia-Pacific Casino Gambling Market
Gaming
Racing Games Market