
 VR Gaming Market | 2026-2036
VR Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
VR Gaming Market Outlook
Standalone six-degrees-of-freedom tracking is collapsing the price-performance barrier that once confined quality VR to tethered PC setups. Meta leverages its vertically integrated headset and content ecosystem to dominate consumer-facing hardware distribution. Epic Games anchors high-fidelity rendering pipelines through its Unreal Engine licensing, which sustains developer loyalty across premium console and PC VR titles. Schell Games specializes in location-based educational experiences that occupy a defensible niche outside the crowded consumer gaming fray.
VR gaming encompasses interactive software and hardware systems that generate immersive three-dimensional environments through stereoscopic displays, sub-20ms motion-to-photon latency, and six-axis positional tracking for real-time user embodiment. The technology serves commercial purposes spanning entertainment consumption, skills acquisition, and spatial design validation. Standalone platforms are recording the fastest hardware growth as wireless all-in-one headsets displace PC-tethered configurations in volume terms. Subscription services within the distribution channel dimension are accumulating recurring revenue pools faster than transactional digital stores, while professional end users generate per-seat economics that casual gamers cannot match.
FCC equipment authorization rules govern radio-frequency emissions for VR headsets sold in the United States, while the EU AI Act imposes transparency obligations on adaptive difficulty algorithms embedded in European-distributed titles. China's SAMR enforces content review protocols that shape which experiences reach its domestic digital stores. Stakeholders must monitor whether emerging biometric data collection in head-mounted displays triggers HIPAA-level health privacy scrutiny or GDPR-class consent frameworks before embedding physiological sensors into next-generation hardware.
Market Dynamics
Standalone six-degrees-of-freedom headsets are collapsing the price-performance barrier that once confined quality VR to tethered PC configurations, redistributing volume toward wireless all-in-one hardware and compressing margins for legacy peripheral-dependent systems.
Growth Catalysts
- Enterprise Training Mandates:Boeing and Walmart procurement programs are expanding headset volumes for skills acquisition and safety simulation, creating institutional demand pools that consumer gaming cannot match.
- China MIIT Near-Eye Display Standards:Tightened optical performance requirements are accelerating domestic manufacturer R&D investment and filtering substandard hardware from official distribution channels.
- Seoul Metropolitan Gaming Cluster:Concentrated developer talent and government-backed incubator infrastructure in South Korea are generating location-based entertainment concepts that export to Asian and North American markets.
Market Restraints
- Display Panel Supply Concentration:Premium OLED and fast-LCD substrates for VR headsets concentrate among Korean and Taiwanese suppliers, creating input cost volatility during semiconductor cycle downturns.
- Motion Sickness Technical Limitation:Sub-20ms motion-to-photon latency requirements demand specialized ASIC design that generic mobile chipsets cannot satisfy, constraining budget hardware performance.
- China SAMR Content Review Protocols:Extended approval timelines for interactive entertainment software create regulatory friction that delays international title launches in the largest addressable hardware market.
Strategic Opportunities
- Biometric Sensor Integration:Embedding physiological monitoring into next-generation headsets opens health-adjacent applications where HIPAA-level privacy frameworks create defensible competitive moats.
- Subscription Distribution Models:Recurring revenue pools within hardware-agnostic content services are accumulating faster than transactional digital stores, shifting value capture toward platform operators.
- EU AI Act Adaptive Difficulty Mandates:Transparency obligations for algorithmic game systems create compliance service opportunities and favor European developers with established algorithmic audit capabilities.
Industry Challenges
- Spatial Computing Talent Scarcity:Six-axis positional tracking optimization and stereoscopic rendering pipeline engineering require specialized skill sets that generalist game studios lack.
- FCC Equipment Authorization Timelines:Radio-frequency emission certification for new headset models creates capex intensity in hardware development cycles that software-only competitors avoid.
- GDPR Biometric Consent Complexity:Embedding eye-tracking or galvanic skin response sensors triggers cross-border data governance obligations that fragment product architecture across regulatory zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR Gaming Market |
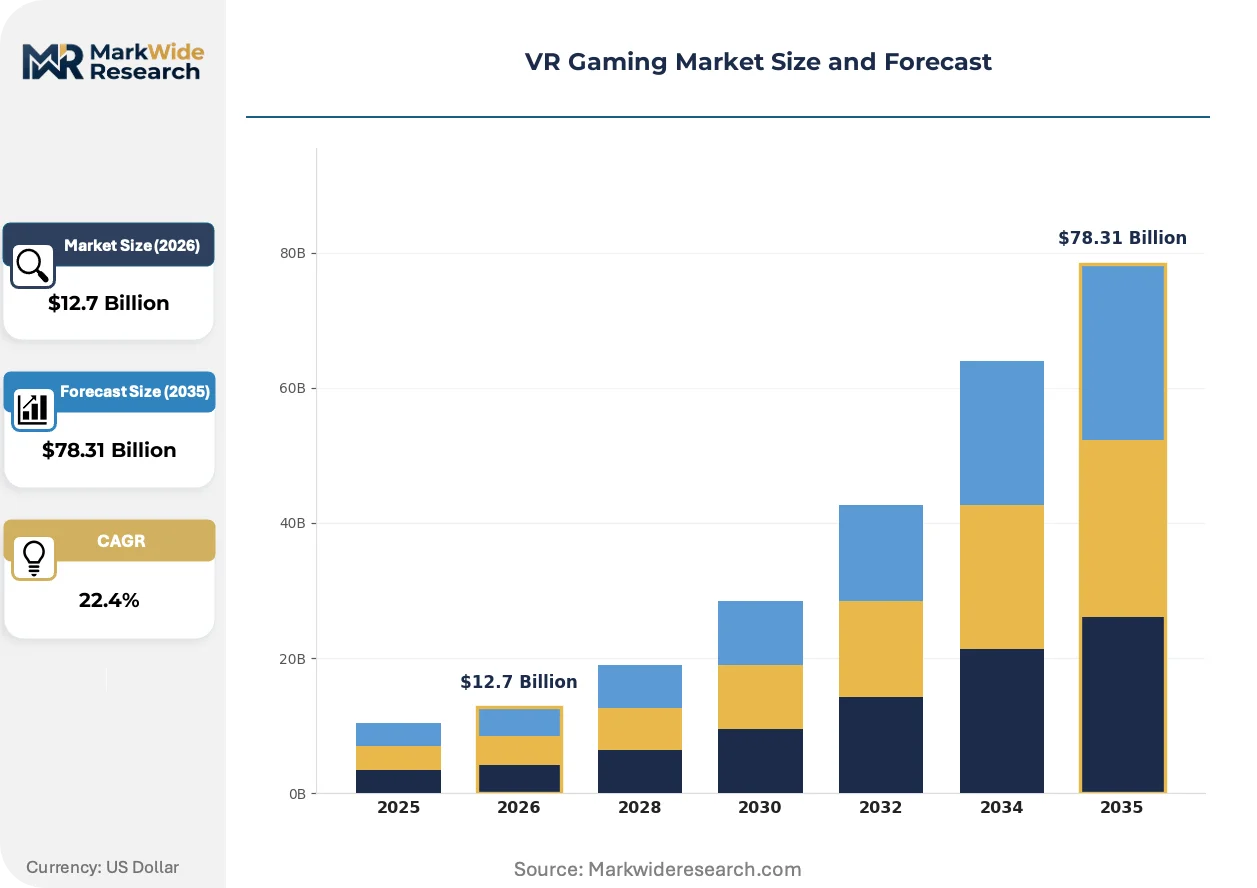
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $78.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: PC, Console, Mobile, Standalone Content Type: Games, Experiences, Education, Training Distribution Channel: Digital Stores, Retail, Subscription Services, Direct Sales End User: Casual Gamers, Professionals, Educators, Developers |
| Companies Covered | Schell Games, Wildnet Edge, Meta, Invogame, Groove Jones, Unity Technologies, Beat Games, Varwin, Epic Games, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR Gaming Market Strategic Shifts
Rendering pipelines and distribution architectures are fragmenting as cloud streaming, edge computing, and standalone silicon paths diverge, forcing developers to place multiple hardware bets simultaneously.
Pancake optics is decomposing the bulk and weight constraints that limited session duration in legacy Fresnel-lens headsets. Fitness-oriented VR applications at Meta and ByteDance are adopting folded optical path designs at accelerated refresh cycles. This technology is decomposing the tether between immersive fidelity and physical comfort that previously forced trade-offs in hardware positioning.
The EU AI Act imposes documentation obligations on machine-learning-driven adaptive difficulty and NPC behavior systems distributed in European markets. Developers must now maintain algorithmic audit trails and explainability layers that increase production overhead. Premium narrative VR studios targeting German and French markets are responding by hiring compliance engineers earlier in production cycles.
Hardware-agnostic subscription services are capturing user attention that device-exclusive storefronts previously monopolized. Cloud-rendered VR experiences streamed to thin-client headsets are displacing native application purchases in price-sensitive segments. This pattern is most visible in South Korea's PC bang culture, where hourly access models for high-fidelity VR are normalizing before home hardware penetration reaches mass-market thresholds.
VR Gaming Market Segmentation
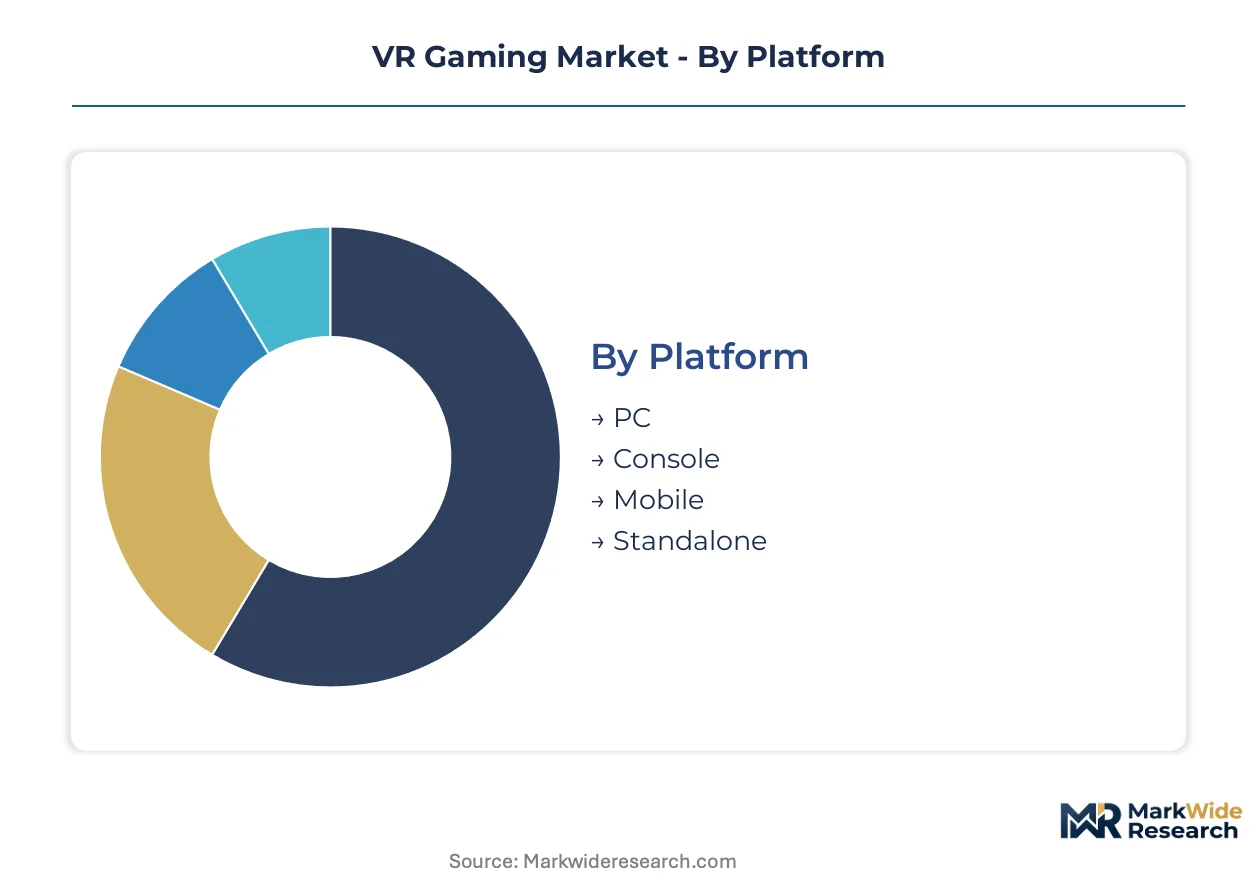
Platform architecture determines hardware procurement cycles, content development pipelines, and margin structures across the VR gaming value chain. Each segmentation dimension reveals distinct competitive dynamics between tethered performance systems and wireless convenience-oriented alternatives.
Platform:
Standalone headsets face the strongest substitution pressure as wireless all-in-one systems displace PC-tethered configurations that once dominated quality-demanding segments.
- PC:High-fidelity rendering pipelines powered by discrete GPUs deliver uncompromised visual fidelity for simulation-heavy applications. Demand concentrates in enterprise training programs at Boeing and Walmart where per-seat economics justify hardware investment. FCC equipment authorization rules for radio-frequency peripherals add compliance overhead that consumer segments avoid.
- Standalone:Integrated SoC architectures with six-degrees-of-freedom tracking collapse the price-performance barrier that previously confined quality VR to external computing. Seoul Metropolitan Gaming cluster developers prioritize these systems for location-based entertainment exports. China's MIIT near-eye display standards filter substandard hardware from official distribution channels.
- Console:Closed-ecosystem distribution through proprietary storefronts limits hardware choice but guarantees optimization targets. Sony's PlayStation VR anchors this segment with exclusive first-party content libraries.
- Mobile:Smartphone-dependent viewers leverage existing device penetration for lowest-barrier entry. Samsung Gear VR and Google Cardboard legacy established price-elastic demand patterns in emerging markets.
Standalone retains volume leadership; Standalone holds the steepest expansion curve.
Content Type:
Commercial maturity varies sharply across application types, with enterprise-facing categories commanding premium pricing power absent from consumer entertainment.
- Training:Safety simulation and skills acquisition modules generate per-seat economics that casual gaming cannot match. Boeing and Walmart procurement programs institutionalize demand independent of consumer hardware cycles. HIPAA-level privacy frameworks create defensible moats when biometric sensors embed physiological monitoring.
- Games:Interactive entertainment software drives hardware adoption through network effects and exclusive content libraries. Epic Games' Unreal Engine licensing sustains developer loyalty across premium PC and console VR titles. EU AI Act transparency obligations for adaptive difficulty algorithms increase production overhead for European-distributed titles.
- Experiences:Passive and lightly interactive content occupies marketing and brand activation use cases. Location-based entertainment venues in South Korea normalize hourly access models before home hardware penetration reaches mass-market thresholds.
- Education:Curriculum-aligned spatial learning tools target institutional procurement cycles with extended sales timelines. Schell Games specializes in this niche outside crowded consumer gaming competition.
Games captures the largest addressable user base; Training delivers the highest revenue per seat.
Distribution Channel:
Revenue capture is shifting from transactional ownership toward recurring access models that reduce consumer upfront commitment.
- Subscription Services:Hardware-agnostic content libraries accumulate recurring revenue pools faster than digital storefronts. Cloud-rendered experiences streamed to thin-client headsets displace native application purchases in price-sensitive segments. GDPR biometric consent complexity fragments product architecture when eye-tracking sensors trigger cross-border data governance obligations.
- Digital Stores:Platform-exclusive marketplaces monetize through transaction fees and discovery placement. Meta's vertically integrated headset and content ecosystem dominates consumer-facing hardware distribution through captive storefront control.
- Direct Sales:Enterprise procurement bypasses retail intermediaries for volume pricing and support customization. Extended sales cycles match institutional budgeting timelines.
- Retail:Physical channel presence drives awareness among hardware-first purchasers. Big-box electronics chains anchor consumer education in North American and European markets.
Digital Stores maintain transaction volume dominance; Subscription Services gains share fastest through recurring revenue accumulation.
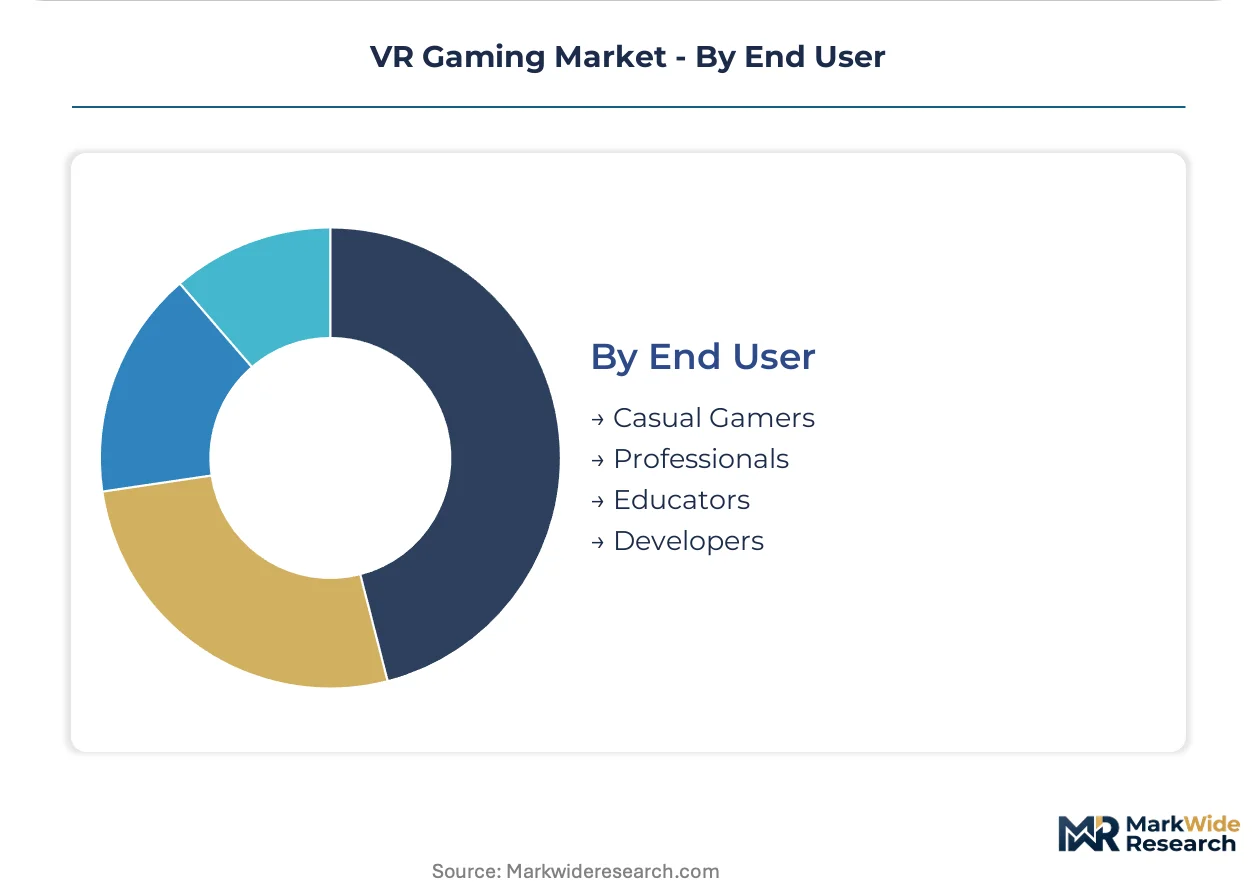
End User:
Professional and institutional users generate economics that subsidize consumer segment development through cross-subsidization patterns.
- Professionals:Enterprise training, architectural visualization, and healthcare simulation demand justifies premium hardware procurement. Per-seat licensing models exceed casual gamer lifetime value multiples. China's SAMR content review protocols create regulatory friction delaying international title launches in the largest addressable hardware market.
- Developers:Content creation tools and early hardware access programs anchor platform ecosystem investment. Spatial computing talent scarcity in six-axis positional tracking optimization limits generalist studio participation.
- Casual Gamers:Price-elastic demand responds to hardware cost reductions and content library breadth. Meta and ByteDance fitness-oriented applications adopt pancake optics at accelerated refresh cycles.
- Educators:Curriculum integration requirements extend sales cycles but reduce churn through institutional commitment. Government-backed incubator infrastructure in South Korea generates location-based concepts that export to Asian and North American markets.
Professionals command the highest revenue per user; Casual Gamers represents the largest addressable population.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in VR hardware and content services reflect divergent regulatory environments and domestic demand patterns. South Korea and China export location-based entertainment concepts while importing specialized optical components from Taiwan and Japan. The United States maintains a deficit in headset assembly but dominates cloud-rendered content licensing.
United States
Enterprise training procurement at Boeing and Walmart institutionalizes demand independent of consumer cycles. FCC equipment authorization rules for radio-frequency headsets add compliance overhead that filters smaller hardware entrants. Seattle and Austin anchor development clusters where spatial computing talent concentrates for six-axis positional tracking optimization.
China
Domestic headset manufacturers face tightened MIIT near-eye display standards that accelerate R&D investment in pancake optics. SAMR content review protocols create regulatory friction delaying international title launches in official digital stores. Shenzhen's hardware ecosystem supplies folded optical path components to ByteDance and Meta at accelerated refresh cycles.
South Korea
Seoul Metropolitan Gaming cluster generates location-based entertainment concepts that export to Asian and North American markets. Government-backed incubator infrastructure concentrates developer talent for hourly access VR models. Samsung Display and LG Display supply premium OLED substrates that Korean and Taiwanese headset assemblers depend upon.
Germany
EU AI Act transparency obligations for adaptive difficulty algorithms increase production overhead for studios targeting German and French markets. Premium narrative VR developers respond by hiring compliance engineers earlier in production cycles. Munich and Frankfurt anchor automotive visualization applications where per-seat enterprise licensing exceeds casual gamer economics.
Japan
METI standards for near-eye display optical performance align with domestic manufacturer quality positioning. Sony's PlayStation VR anchors console-tethered distribution through exclusive first-party content libraries. Tokyo and Osaka development studios specialize in high-fidelity rendering pipelines that sustain developer loyalty across premium titles.
VR Gaming Market Competitive Environment
Concentration sits with vertically integrated platform operators and specialized engine licensors that control distribution and rendering infrastructure. The market structure splits between hardware-software bundlers, middleware enablers, and niche content specialists. Three archetypes dominate: ecosystem gatekeepers with captive storefronts, engine providers licensing rendering pipelines, and location-based experience developers. Competitive moves center on optical technology licensing and subscription service expansion into hardware-agnostic distribution.
Among ecosystem gatekeepers, Meta exemplifies vertical control over headset manufacturing and content distribution. Epic Games and Unity Technologies occupy positions as engine providers whose licensing sustains developer loyalty across premium PC and console VR titles. Schell Games represents the location-based education specialist archetype outside crowded consumer gaming competition.
| Leading Market Players |
|---|
| Schell Games |
| Wildnet Edge |
| Meta |
| Invogame |
| Groove Jones |
| Unity Technologies |
| Beat Games |
| Varwin |
| Epic Games |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with Korean and Taiwanese display panel suppliers lock in both optical component access and unit cost visibility for headset manufacturers navigating semiconductor cycle volatility. These arrangements insulate procurement teams from spot-market price spikes while committing volume thresholds that shape factory utilization planning across the upstream substrate ecosystem.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in enterprise training deployments. Boeing and Walmart procurement programs command volume discounts that casual gamer segments cannot match, while FCC equipment authorization compliance costs embed into premium tier pricing. Cost compression in standalone hardware intensifies because integrated SoC designs displace discrete component architectures. Casual gamers exhibit highest price sensitivity; enterprise trainers show lowest.
Supply Chain Analysis
Strategic stockpiling of fast-LCD and OLED substrates dominates inventory strategy as manufacturers buffer against Korean and Taiwanese supplier concentration. Pancake optics components draw from China's Shenzhen ecosystem; specialized ASICs for sub-20ms latency rest on Taiwanese foundry capacity. Single-source vulnerability in premium display substrates creates disruption risk. Distribution runs through hardware-agnostic subscription platforms and captive digital storefronts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where Meta's vertically integrated headset-content ecosystem generates network effects that compound user lock-in and developer loyalty.
For Market Incumbents: Compound ecosystem control by deepening backward integration into pancake optics manufacturing and expanding capacity reservation contracts with Samsung Display and LG Display. Cloud-rendered VR streaming from emerging platform operators threatens hardware-exclusive revenue streams; prioritize R&D in biometric sensor architectures that trigger HIPAA-level compliance moats. For New Entrants and Emerging Players: Lead with location-based entertainment concepts targeting South Korea's Seoul Metropolitan Gaming cluster for proof-of-concept validation before North American expansion. Enterprise training modules at Boeing-scale procurement programs represent the most penetrable white-space; adopt direct sales channels with extended implementation support. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hardware-agnostic subscription service operators with cloud rendering infrastructure. Five-to-ten year viability favors platform-agnostic content libraries over device-captive storefronts. Monitor ByteDance fitness-oriented VR application traction as inflection signal for pancake optics adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Pancake Optics Manufacturing Scale-Up | Reduces headset weight and extends session duration for Meta and ByteDance fitness applications. |
| Biometric Sensor Integration | Opens health-adjacent applications where HIPAA frameworks create defensible competitive moats. |
| Cloud Rendering Infrastructure Partnership | Enables hardware-agnostic subscription services that displace native application purchases. |
| EU AI Act Compliance Engineering | Positions European developers with algorithmic audit capabilities for transparency mandates. |
| Enterprise Training Content Library Expansion | Captures Boeing and Walmart procurement cycles with per-seat economics exceeding consumer segments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with VR hardware procurement managers at enterprise training programs, content studio technical directors, optical component sourcing leads, and platform ecosystem engineers. Secondary validation drew from FCC equipment authorization filings, MIIT near-eye display standard disclosures, EU AI Act regulatory texts, and hyperscaler VR capex disclosures. Bottom-up volume modeling triangulated against top-down addressable market sizing.
Across the analysis window, forecasts employed segmented modeling across platform architecture, content type, distribution channel, and end-user professionalization tier. CAGRs derived from hardware shipment trajectory analysis and content monetization pattern regression. Industry-specific inputs included Seoul Metropolitan Gaming cluster developer surveys and SAMR content approval timeline tracking.
The analysis sits within stated boundaries; outcomes outside sustained enterprise training procurement or loosened China content review protocols would require recalibration. Forecasts reflect documented assumptions around optical component supply continuity and biometric privacy regulatory evolution. Revision becomes warranted when FCC equipment authorization timelines or GDPR biometric consent complexity crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
South Korea Subscription-Based Gaming Market
Gaming
Game Applications Market
Gaming
H5 Games Market
Gaming
Global Gaming Market
Gaming
Videogames Market
Gaming
Africa Gaming Market
Gaming
United States Virtual Reality Gaming Market
Gaming
LAMEA in-Game Advertising Market
Gaming
Serious Games Market
Gaming
Australia Gaming Gadgets Market
Gaming
Galgames Market
Gaming
China Casino Tourism Market
Gaming
Simulation Video Game Market
Gaming
Game API Market
Gaming
Traditional Casual Games Market
Gaming
Gaming Software Market