
 Slot Machine Market | 2026-2036
Slot Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Slot Machine Market Intelligence
Server-based gaming architecture is narrowing the gap between hardware refresh cycles and software update timelines across casino floors. Aristocrat Leisure Limited leverages its North American installed base to sustain recurring revenue from game content subscriptions. Light and Wonder, Inc. anchors its position through vertical integration into casino management systems. International Game Technology PLC competes on regulatory compliance breadth, operating certified platforms across multiple state jurisdictions.
A slot machine constitutes an electromechanical or fully electronic gambling device utilizing a random number generator to determine game outcomes, typically featuring three or more reels displayed on physical mechanisms or high-definition video screens with touch interfaces. The apparatus serves commercial gaming establishments by generating house-banked wagers regulated by jurisdictional gaming commissions. Video Slots dominate installed base value due to higher per-unit pricing and multimedia content flexibility, while Progressive Slots concentrate jackpot-driven player engagement and yield management optimization for casino operators. Mobile-Compatible technology represents the fastest-expanding segment as operators deploy tethered companion applications extending floor gameplay to on-property mobile devices.
The Nevada Gaming Commission, state tribal gaming compacts, and the National Indian Gaming Commission collectively shape product certification requirements, technical standards, and market access protocols for equipment manufacturers serving US jurisdictions. Compliance with GLI-19 and GLI-11 testing standards determines product eligibility across most regulated North American markets. Stakeholders must monitor evolving cashless wagering mandates and responsible gaming algorithm requirements as regulatory technology expectations intensify.
Market Dynamics
Server-based gaming architecture compresses hardware replacement cycles while extending software monetization horizons across casino floors, forcing equipment suppliers to restructure revenue models around recurring content licensing rather than unit sales.
Growth Catalysts
- GLI-19 Certification Standards:Unified technical testing protocols across US state jurisdictions accelerate product approval timelines and reduce manufacturer compliance duplication costs.
- Tribal Gaming Compact Expansions:Renegotiated agreements between tribal authorities and state governments authorize expanded electronic gaming machine allocations on sovereign lands.
- Cashless Wagering Mandates:Regulatory directives from Nevada Gaming Commission and peer bodies drive replacement demand for systems supporting digital payment rails.
Market Restraints
- Semiconductor Supply Concentration:GPU and specialized processor sourcing depends on Taiwan-based foundry capacity, exposing production schedules to geopolitical disruption risks.
- Extended Certification Timelines:Multi-state GLI-11 testing requirements add 8-14 months to product launch schedules, compressing effective revenue windows.
- Mobile Gaming Substitution:Off-property real-money iGaming applications capture player wagering volume that previously flowed to physical slot floors.
Strategic Opportunities
- Companion Application Ecosystems:Tethered mobile apps extending floor gameplay to on-property devices create new revenue streams while complying with jurisdictional proximity requirements.
- Responsible Gaming Algorithm Mandates:Regulatory requirements for player-behavior monitoring systems open consulting and software licensing opportunities for analytics providers.
- Japan Integrated Resort Development:Casino legalization in designated metropolitan zones creates demand for certified equipment from operators entering newly regulated Asian markets.
Industry Challenges
- Embedded Systems Engineering Talent Scarcity:Shortage of developers skilled in real-time gaming firmware and random number generator architecture constrains product pipeline velocity.
- Legacy Protocol Integration Complexity:New server-based platforms must maintain backward compatibility with decade-old casino management systems, fragmenting engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slot Machine Market |
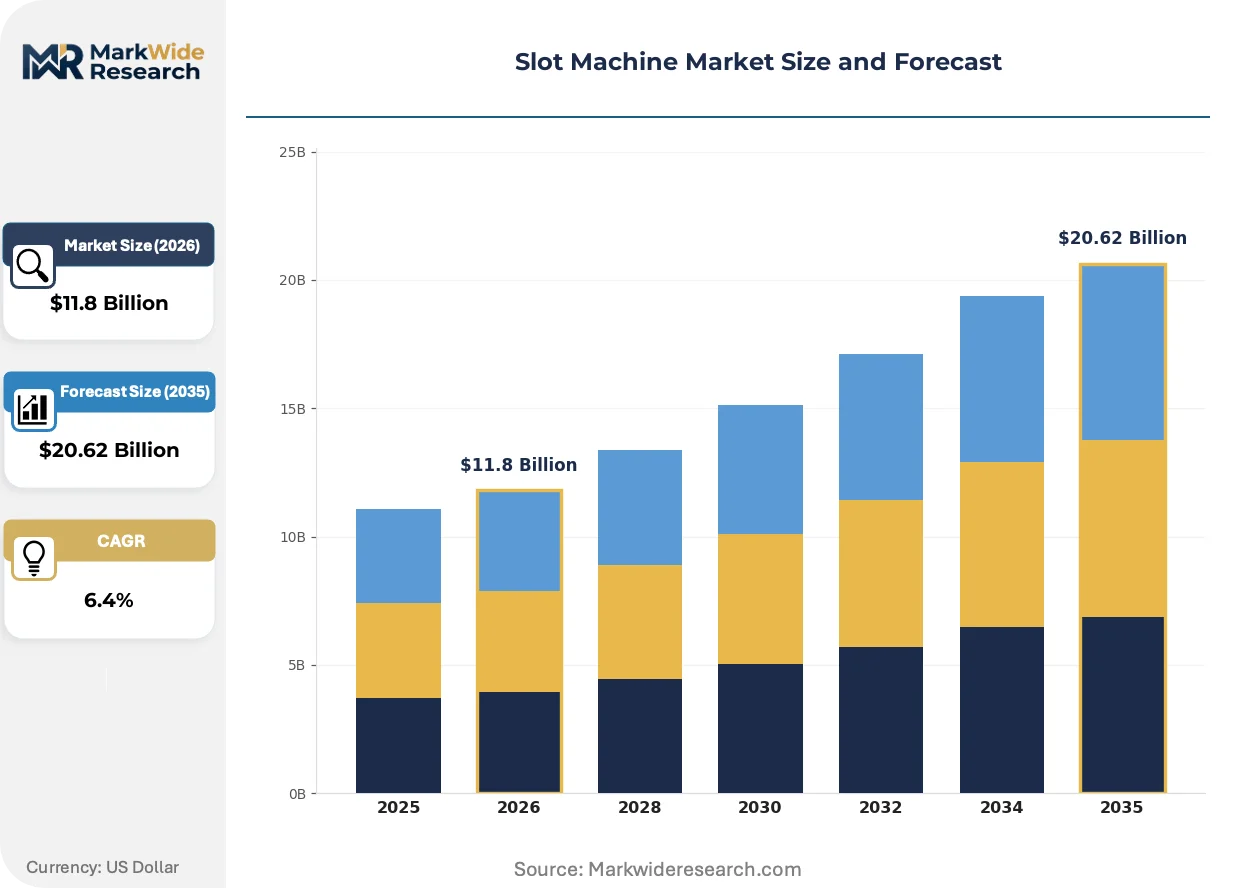
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Slots, Classic Slots, Progressive Slots, 3D Slots Technology: Random Number Generator, Touchscreen Interface, Virtual Reality, Mobile-Compatible End User: Casinos, Online Gaming Platforms, Arcades, Cruise Ships Distribution Channel: Retail, Online, Direct Sales, Trade Shows |
| Companies Covered | International Game Technology PLC, Aristocrat Leisure Limited, Light and Wonder, Inc., Scientific Games Corporation, Konami Holdings Corporation, Novomatic AG, Everi Holdings Inc., Incredible Technologies, Inc., PlayAGS, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slot Machine Market Strategic Shifts & Innovations
Digital convergence between physical gaming hardware and cloud-connected content delivery is dissolving traditional boundaries between slot machine manufacturing and software publishing.
Virtualized reel-mapping technology is virtualizing the random number generator-to-display pipeline, replacing fixed mechanical configurations with software-defined symbol distributions. Tribal casino operators in Oklahoma and California are deploying these systems fastest, drawn by reduced maintenance overhead and instant game library swaps. This compression of hardware-software coupling is virtualizing the traditional seven-year replacement cycle into continuous incremental upgrades.
EU AI Act algorithmic transparency requirements are mandating explicable decision logic for machine learning components in player-tracking and game-adaptation systems. Equipment manufacturers serving European cruise ship casinos must now document training data provenance and model drift monitoring protocols. Video slot suppliers with embedded recommendation engines face the steepest compliance recalibration.
Outcome-based floor performance contracts are displacing traditional equipment lease arrangements, with casino operators paying suppliers based on actual player time-on-device metrics. This shift transfers volatility risk from capital-constrained tribal gaming authorities to manufacturers with stronger balance sheets. The model is penetrating fastest in Arizona and Florida, where compact renegotiations have enabled revenue-sharing experimentation.
Slot Machine Market Segmentation

Slot machine segmentation reveals how hardware form factors, software architectures, and venue requirements fragment procurement patterns across tribal gaming authorities, commercial casino operators, and emerging digital platforms. Understanding these divides exposes where replacement cycles concentrate and where regulatory compliance costs vary most steeply.
Product Type:
Cost tier differentiation separates high-ASP video systems from mechanical legacy units, with pricing spreads reflecting display technology, content licensing depth, and jackpot liability structures.
- Video Slots:High-definition display arrays and multimedia content pipelines dominate casino floor allocations. Tribal gaming authorities in Oklahoma and California prioritize these systems for reduced maintenance overhead and instant game library swaps.
- Progressive Slots:Networked jackpot pools linking multiple machines create concentrated yield management optimization for operators. Nevada commercial casinos deploy these most aggressively to drive player time-on-device metrics and cross-floor traffic patterns.
- Classic Slots:Electromechanical three-reel configurations retain presence in regional markets with conservative player demographics.
- 3D Slots:Stereoscopic display technology and immersive visual rendering target younger player cohorts in destination resort properties.
Video Slots hold installed capacity. Progressive Slots is rotating up the share rankings.
Technology:
Application functionality determines regulatory certification pathways, with random number generator architecture and payment rail integration commanding distinct compliance timelines across jurisdictions.
- Random Number Generator:Cryptographic seeding algorithms and entropy sourcing define core game integrity standards. GLI-19 certification requirements in Nevada, New Jersey, and Michigan mandate independent testing of these subsystems before market deployment.
- Mobile-Compatible:Tethered companion applications extending floor gameplay to on-property devices represent the steepest expansion trajectory. Arizona and Florida compact renegotiations enable revenue-sharing experimentation with these systems.
- Touchscreen Interface:Capacitive multi-touch panels replace mechanical button arrays for simplified maintenance and dynamic interface reconfiguration.
- Virtual Reality:Headset-integrated immersive environments remain pre-commercial pending motion sickness mitigation and regulatory comfort assessments.
Random Number Generator systems anchor regulatory compliance spend. Mobile-Compatible platforms are climbing the fastest in new installation permits.
End User:
Customer type dictates equipment specifications, with sovereign tribal authorities, state-licensed commercial operators, and maritime venues each imposing distinct technical standards and procurement financing structures.
- Casinos:Tribal gaming authorities and commercial operators drive replacement cycles for server-based gaming systems. Floor space expansion for electronic gaming machines concentrates demand in jurisdictions with modernized compliance frameworks.
- Cruise Ships:EU AI Act algorithmic transparency requirements mandate explicable decision logic for player-tracking systems in European waters. Equipment manufacturers must document training data provenance and model drift monitoring protocols.
- Online Gaming Platforms:Browser-based and native application delivery extends slot mechanics beyond physical hardware constraints.
- Arcades:Amusement-with-prize configurations operate under reduced regulatory scrutiny in select jurisdictions.
Casinos command the dominant share of hardware shipments. Cruise Ships are gaining permit velocity as maritime regulatory clarity improves.
Distribution Channel:
Volume concentration varies by procurement sophistication, with large casino operators consolidating through direct manufacturer relationships while smaller venues depend on intermediary networks.
- Direct Sales:Aristocrat Leisure Limited leverages its North American installed base through manufacturer-direct content subscription models. Large tribal gaming authorities negotiate outcome-based floor performance contracts transferring volatility risk to suppliers.
- Trade Shows:Global Gaming Expo and ICE London serve as concentrated venues for product launches and multi-state regulatory pre-certification discussions. These events compress 8-14 month GLI-11 testing timelines through coordinated agency engagement.
- Retail:Distributor networks serve mid-market casino operators with standardized lease arrangements.
- Online:Digital procurement portals facilitate spare parts and software update transactions.
Direct Sales captures the highest-value contracts. Trade Shows are expanding their role in regulatory pre-clearance workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tribal gaming authorities and commercial casino operators concentrate procurement power in the United States, with secondary demand emerging from integrated resort developments in Asia-Pacific jurisdictions. Regulatory modernization across multiple countries is compressing equipment certification timelines and reshaping supplier market access.
United States
Tribal gaming compacts in Oklahoma and California authorize expanded electronic gaming machine allocations on sovereign lands. The Nevada Gaming Commission mandates GLI-19 certification standards for all new floor deployments. Server-based gaming systems dominate replacement cycles in Las Vegas and Atlantic City commercial corridors.
Japan
Integrated resort legalization in designated metropolitan zones creates demand for certified equipment from operators entering newly regulated markets. METI establishes technical standards for casino equipment imports. Osaka and Yokohama cluster developments concentrate procurement planning for foreign equipment suppliers.
Australia
State-level gaming authorities in New South Wales and Victoria drive replacement demand for video slot systems with enhanced responsible gaming features. The Victorian Commission for Gambling and Liquor Regulation mandates player-behavior monitoring algorithm compliance. Sydney and Melbourne casino floors anchor equipment upgrade cycles.
United Kingdom
UK Gambling Commission licensing requirements shape product certification for equipment serving British cruise ship and land-based venues. EU AI Act transparency mandates extend to algorithmic player-tracking systems in European waters. London serves as the regional headquarters concentration for multinational suppliers.
Canada
Provincial lottery corporations in Ontario and British Columbia consolidate procurement for First Nations gaming partnerships. Health Canada and provincial regulators coordinate technical standards for electronic gaming equipment. Toronto and Vancouver metropolitan areas concentrate casino floor expansion projects.
Slot Machine Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base consolidates around three strategic groupings: integrated platform suppliers with casino management system capabilities, content-focused developers with recurring licensing models, and regional equipment fabricators serving jurisdictional niches. Dominant competitive moves include outcome-based floor performance contracts transferring volatility risk to manufacturers, and vertical integration into adjacent casino operations software.
Within the integrated platform tier, International Game Technology PLC and Aristocrat Leisure Limited exemplify archetypes competing on regulatory compliance breadth and North American installed base leverage respectively. Light and Wonder, Inc. occupies a position emphasizing systems integration capabilities. These three entities anchor the competitive structure through distinct strategic positioning around content licensing, platform integration, and jurisdictional certification coverage.
| Leading Market Players |
|---|
| International Game Technology PLC |
| Aristocrat Leisure Limited |
| Light and Wonder, Inc. |
| Scientific Games Corporation |
| Konami Holdings Corporation |
| Novomatic AG |
| Everi Holdings Inc. |
| Incredible Technologies, Inc. |
| PlayAGS, Inc. |
| Others |
Cost & Logistics Intelligence
Taiwan-based GPU foundry capacity anchors upstream semiconductor sourcing, concentrating margin capture with specialized processor suppliers while casino operators downstream negotiate outcome-based floor performance contracts that transfer volatility risk to equipment manufacturers.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate server-based gaming system procurement. Three-tier pricing structure across premium video slots, standard progressive systems, and economy classic configurations reflects display technology grade and GLI-19 certification tier. Pricing pressure stems from extended GLI-11 certification timelines compressing effective revenue windows. Tribal gaming authorities exhibit highest price sensitivity due to capital constraints, while Las Vegas commercial operators prioritize content flexibility over unit cost.
Supply Chain Analysis
Export-control regimes restricting advanced GPU technology flows to Chinese equipment fabricators fragment supplier access for casino management system integrators. Manufacturing concentrates in Taiwan, South Korea, and Japan for specialized processors, with Mexico and Vietnam hosting final assembly for North American market access. Critical dependencies include high-brightness LED display panels, cryptographic random number generator chips, and cashless payment rail modules. Single-source vulnerability in Taiwan foundry capacity exposes production schedules to geopolitical disruption. Distribution runs through direct manufacturer relationships for large tribal authorities, with distributor networks serving mid-market operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Server-based gaming architecture fragments procurement patterns across tribal compacts, commercial casino operators, and maritime venues, creating specialization niches as regulatory technology expectations diverge across jurisdictions.
For Market Incumbents: Pre-empt mobile gaming substitution by accelerating companion application ecosystem deployment in Arizona and Florida where compact renegotiations enable revenue-sharing experimentation. Consolidate regulatory compliance breadth across multi-state GLI-19 certifications to raise barriers against emerging platform specialists lacking jurisdictional coverage.
For New Entrants and Emerging Players: Japan integrated resort development represents the most penetrable entry point for foreign equipment suppliers lacking established North American installed bases. Target cruise ship operators in European waters facing EU AI Act algorithmic transparency mandates as consulting and software licensing opportunities. Pursue outcome-based floor performance contracts to differentiate from incumbent capital-sale models.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional equipment fabricators serving Oklahoma and California tribal gaming niches. Five-to-ten year viability hinges on server-based platform transition completion rather than legacy mechanical unit maintenance. Monitor Japan METI technical standard finalization as inflection indicator for Asian market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Application Ecosystem Development | Tethered mobile platforms extend floor gameplay to on-property devices while satisfying Nevada Gaming Commission proximity requirements. |
| GLI-19 Certification Pre-Clearance Investment | Multi-state testing coordination through Global Gaming Expo compresses approval timelines and accelerates product launch velocity. |
| Outcome-Based Floor Performance Contracts | Revenue-sharing arrangements transfer volatility risk from tribal gaming authorities to manufacturers with stronger balance sheets. |
| Responsible Gaming Algorithm Integration | Player-behavior monitoring systems address Victorian Commission for Gambling and Liquor Regulation mandates in Australian markets. |
| Japan Integrated Resort Equipment Certification | METI technical standard compliance positions suppliers for Osaka and Yokohama cluster development procurement cycles. |
Research Approach
Initial hypotheses were tested against primary input from casino operations executives, tribal gaming authority procurement directors, GLI certification engineers, and slot floor managers and refined through secondary validation against Nevada Gaming Commission regulatory filings, National Indian Gaming Commission compact databases, SEC 10-K disclosures from listed equipment suppliers, and Global Gaming Expo product launch records. Bottom-up unit shipment estimates triangulated with top-down casino floor space expansion projections.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by video, progressive, and classic configurations; technology tier by random number generator architecture and mobile compatibility; end user category by tribal, commercial, and maritime venues; and distribution channel by direct sales and intermediary networks. CAGRs derived from replacement cycle analysis, floor space expansion permits, and regulatory mandate timing. Industry-specific inputs included GLI-11 certification timeline distributions and tribal compact renegotiation schedules.
Macroeconomic conditions sit as an overlay; deviation in casino operator capital expenditure cycles and semiconductor foundry capacity allocation would shift the trajectory. Forecasts reflect assumptions regarding regulatory technology mandate adoption rates and server-based platform transition velocity. Material shifts in Japan integrated resort legalization timelines or Taiwan export control enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
MMORPG Gaming Market
Gaming
Gaming Controller Market
Gaming
Global Casino Market
Gaming
South Asia Mobile Gaming Market
Gaming
Online Strategy Games Market
Gaming
Australia Gaming Accessories Market
Gaming
Global Casino and Gaming Market
Gaming
Online Casino Market
Gaming
India Gaming Market
Gaming
Shooter Game Market
Gaming
United States Gaming Market
Gaming
Game Applications Market
Gaming
Gaming Accessories Market
Gaming
Mobile Gaming Market
Gaming
France Online Gambling Market
Gaming
Mobile and Handheld Gaming Market