
 Saudi Arabia Entertainment and Amusement Market | 2026-2036
Saudi Arabia Entertainment and Amusement Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Entertainment and Amusement Market Analytics
Ticket bundling with dining and retail is expanding across Saudi entertainment venues, reshaping how families and corporate groups allocate leisure spending. SEVEN leverages its Qiddiya and city-center development pipeline to anchor multi-asset entertainment districts. Abdul Mohsen Al Hokair Group sustains decades of regional operational expertise across its indoor family entertainment centers. MDLBEAST Records differentiates through music festival IP and youth-oriented experiential programming that competes with traditional amusement formats.
Saudi Arabia entertainment and amusement encompasses purpose-built venues delivering scripted leisure experiences through mechanical rides, immersive media systems, and live performance infrastructure designed for four- to eight-hour visitor dwell times. Facilities typically integrate HVAC-engineered indoor environments, redundant power systems, and crowd-flow architecture supporting throughput rates above two thousand guests per hour. Theme Parks and Amusement Centers command the dominant share of installed capital, reflecting heavy fixed-asset investment in ride systems and themed environments. Virtual Reality and Augmented Reality deployments within the Technology dimension are capturing disproportionate operator attention as hardware costs decline and localization content pipelines mature.
The General Entertainment Authority and Saudi Standards, Metrology and Quality Organization shape venue safety certification, content approval timelines, and foreign operator joint-venture requirements. GEA licensing frameworks directly determine market access speed for international brands seeking to establish permanent Saudi facilities. MOHAP health and safety protocols govern food service, crowd density, and emergency response standards across enclosed entertainment sites. Stakeholders must track regulatory clarity on cinema content classification, esports betting prohibitions, and women-targeted venue programming as these domains evolve under social transformation mandates.
Market Dynamics
Vision 2030 cultural mandates are compressing venue approval timelines from years to months, while Qiddiya and Red Sea Project megadevelopments concentrate capital deployment into purpose-built entertainment districts with integrated ride systems and immersive media infrastructure.
Growth Catalysts
- GEA Licensing Reforms:The General Entertainment Authority's streamlined permitting frameworks are accelerating foreign operator joint-venture formations and reducing time-to-revenue for new indoor family entertainment centers.
- Secondary City Expansion:Dammam and Abha are drawing targeted capital as anchor cities reach saturation, with municipal authorities offering land concessions for multi-asset entertainment districts.
- Immersive Media Hardware:Declining costs for VR headsets and motion-platform systems are enabling mid-scale operators to deploy experiential attractions previously limited to flagship venues.
Market Restraints
- Import Dependency for Ride Systems:Heavy mechanical attractions and themed steel fabrication rely on European and East Asian suppliers, exposing operators to currency volatility and extended lead times.
- MOHAP Crowd Density Protocols:Health ministry mandates on enclosed venue occupancy caps constrain throughput optimization and revenue per square meter during peak demand windows.
- Skilled Technician Scarcity:Maintenance and safety certification for complex electromechanical ride systems depends on expatriate specialists, with limited domestic training pipeline capacity.
Strategic Opportunities
- Esports and Competitive Gaming Venues:The prohibition on betting creates demand for pure-experience gaming arenas, with youth-oriented operators building dedicated tournament infrastructure in Riyadh and Jeddah.
- Women-Targeted Programming:Social transformation mandates are opening segmented venue hours and female-staffed entertainment complexes, an underdeveloped category with dedicated GEA licensing pathways.
- AR-Enhanced Heritage Attractions:Convergence of location-based augmented reality and cultural tourism is creating white space for operators to anchor experiences at UNESCO sites and historical districts.
Industry Challenges
- Localization Content Pipeline:Theatrical productions, character IP, and narrative-driven attractions require Arabic-language scripting and culturally adapted theming, stretching creative development timelines.
- Power Redundancy Standards:SAMR-influenced electrical safety certifications and GEA emergency response mandates demand redundant generator systems and specialized electrical engineering, elevating capex thresholds for indoor venues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Entertainment and Amusement Market |
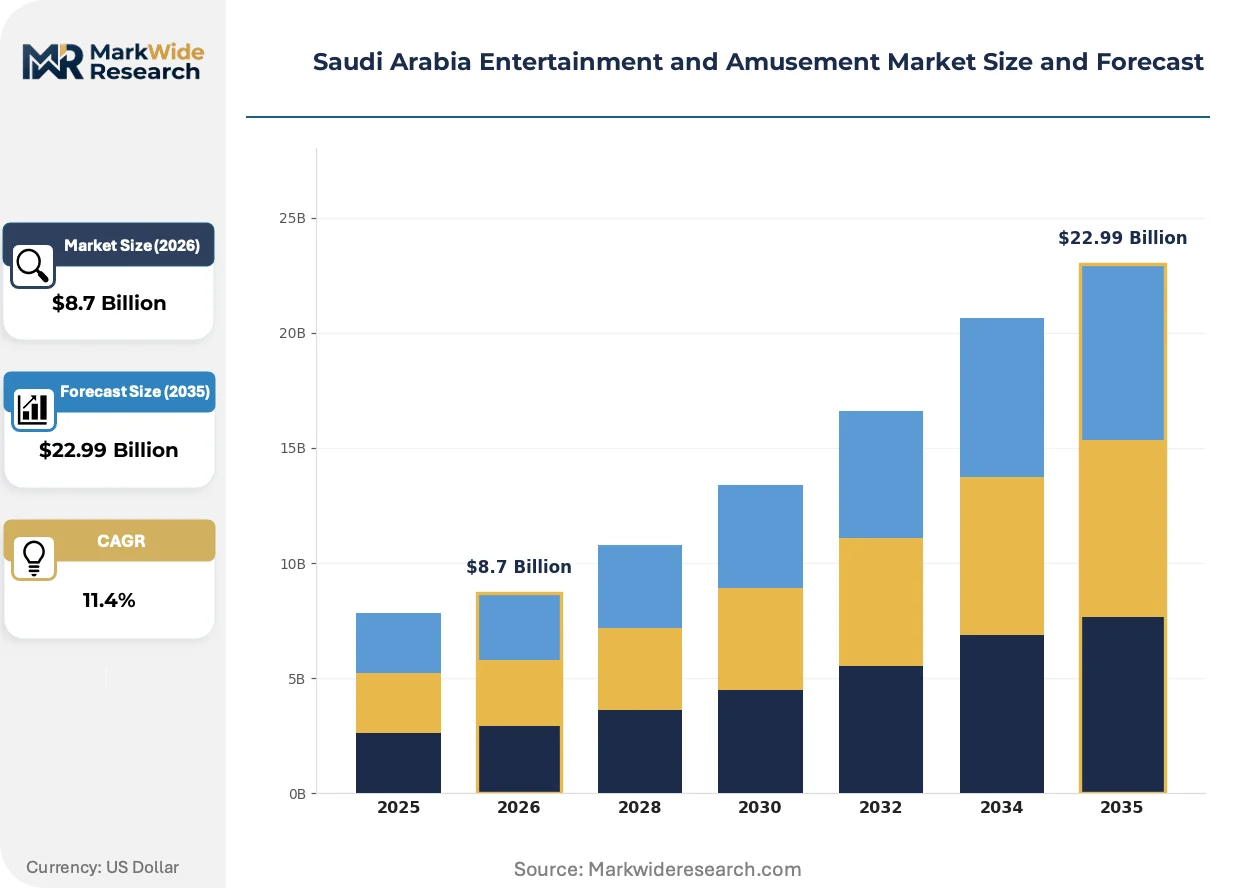
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Theme Parks, Water Parks, Amusement Centers, Arcade Games Service Type: Vendor Services, Event Planning, Maintenance, Technical Support Customer Type: Families, Tourists, Local Residents, Corporate Groups Technology: Virtual Reality, Augmented Reality, Interactive Displays, Mobile Applications |
| Companies Covered | AMC Cinemas KSA, MBC Group, Qiddiya Investment Company, Abdul Mohsen Al Hokair Group, Rotana Group, SEVEN (Saudi Entertainment Ventures), MDLBEAST Records, Al Othaim Leisure & Tourism, VOX Cinemas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Entertainment and Amusement Market Evolving Landscape
Experiential programming is displacing passive consumption across Saudi entertainment venues, with operators investing in extended dwell-time architectures and integrated food-retail-attraction bundling to capture family leisure budgets.
Virtual reality motion platforms are expanding into mid-scale family entertainment centers as hardware costs decline and localization content matures. Regional operators in Riyadh and Jeddah are deploying these systems at accelerated pace to differentiate against traditional mechanical rides. The technology is expanding into secondary city markets previously priced out of immersive attraction categories.
GEA content classification frameworks are tightening approval timelines for live performance scripting and cinema exhibition standards. The regulation is compressing pre-opening marketing windows and forcing operators to front-load creative development. Indoor theatrical venues and cinema-integrated entertainment complexes are responding by building in-house content review capabilities.
Corporate group procurement of packaged entertainment experiences is displacing individual ticket purchasing for team-building and client entertainment. Hospitality channels and direct B2B sales teams are capturing volume commitments that bypass traditional retail distribution. This shift concentrates revenue visibility in Riyadh's corporate headquarters cluster and Jeddah's commercial district.
Saudi Arabia Entertainment and Amusement Market Segmentation
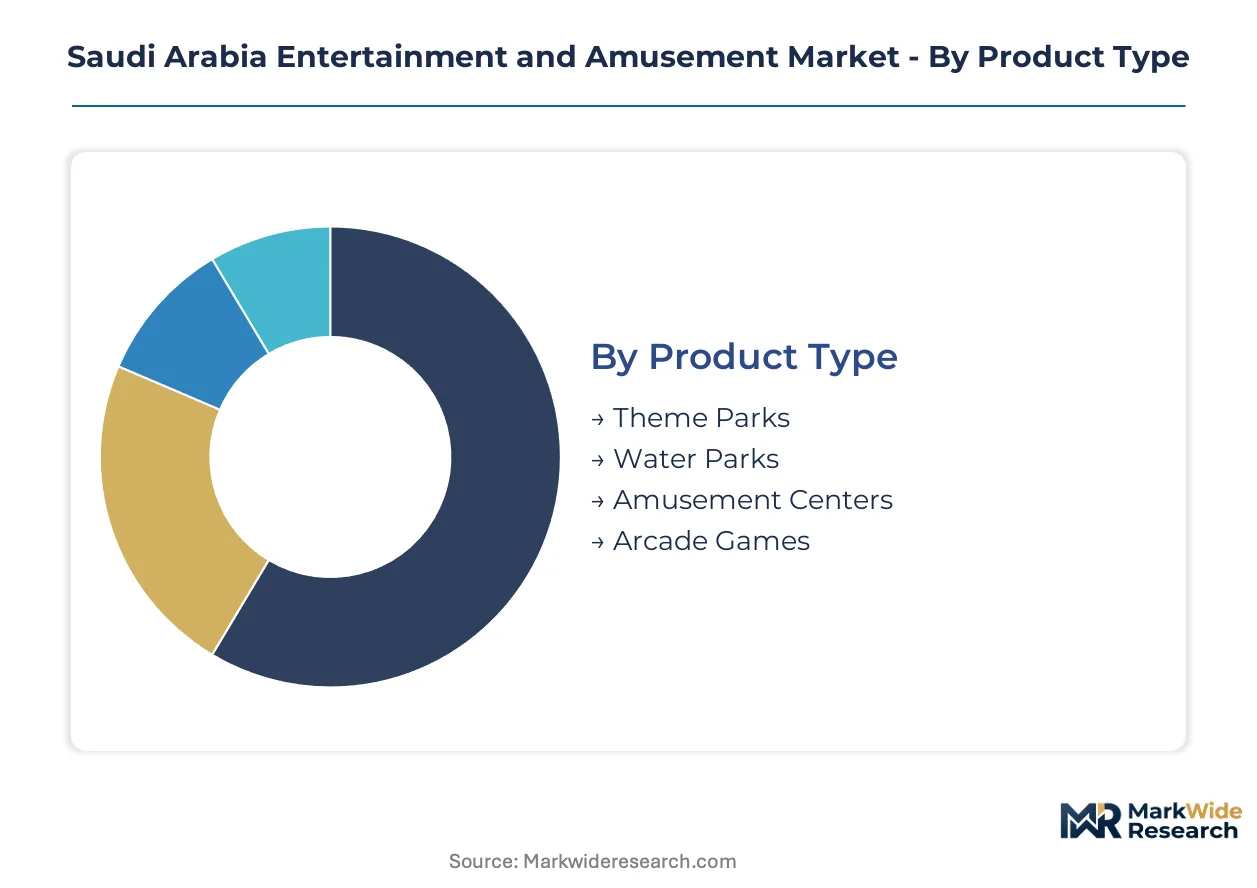
Segmentation in Saudi Arabia's entertainment and amusement market reveals distinct capital deployment patterns and operational requirements across venue formats and service layers. Each category carries specific GEA licensing pathways and MOHAP compliance obligations that shape operator business models.
Product Type:
The customization-standardization spectrum spans from bespoke themed environments to repeatable arcade formats, with capital intensity and content localization demands varying dramatically across this range.
- Theme Parks:Heavy fixed-asset installations integrating mechanical ride systems, immersive narrative architecture, and HVAC-engineered indoor environments. Demand concentrates in Riyadh and Jeddah as anchor cities for SEVEN's Qiddiya pipeline and city-center developments, constrained by import dependency for European and East Asian steel fabrication.
- Water Parks:Seasonal outdoor facilities and climate-controlled indoor aquatic complexes requiring redundant power systems and specialized filtration engineering. Secondary cities including Dammam and Abha are drawing targeted capital as municipal authorities offer land concessions for multi-asset entertainment districts.
- Amusement Centers:Mid-scale indoor venues deploying motion-platform systems and redemption gaming hardware.
- Arcade Games:Standardized electronic gaming cabinets with shorter GEA approval timelines and lower capex thresholds.
Leading the category by volume: Theme Parks. Expanding most quickly: Water Parks.
Service Type:
Margin concentration shifts upstream from execution-heavy event logistics to specialized technical competencies with certification barriers.
- Vendor Services:Equipment procurement, installation supervision, and supply chain coordination for ride system imports. European and East Asian OEM relationships dominate this layer, with currency volatility exposing operators to margin compression during extended lead times.
- Event Planning:Corporate group packaging and hospitality channel coordination for B2B entertainment procurement. Riyadh's corporate headquarters cluster and Jeddah's commercial district concentrate revenue visibility as team-building displaces individual ticket purchasing.
- Maintenance:Electromechanical safety certification and preventive servicing for complex ride systems.
- Technical Support:VR headset calibration, motion-platform diagnostics, and immersive media hardware troubleshooting.
Highest margin capture: Vendor Services. Steepest expansion trajectory: Event Planning.
Customer Type:
Volume distribution reflects Saudi demographic structure and Vision 2030 tourism targets, with corporate procurement emerging as a distinct channel.
- Families:Multi-generational leisure spending driving four- to eight-hour dwell times across integrated food-retail-attraction venues. Domestic operators including Abdul Mohsen Al Hokair Group sustain decades of regional expertise in indoor family entertainment center formats.
- Tourists:International visitors attracted to purpose-built entertainment districts at Qiddiya and Red Sea Project megadevelopments. GEA licensing reforms compressing venue approval timelines from years to months accelerate foreign operator joint-venture formations.
- Local Residents:Repeat visitation patterns supporting membership and loyalty programming at city-center locations.
- Corporate Groups:Packaged experiences for client entertainment and team-building with direct B2B sales bypassing retail distribution.
Dominant spend base: Families. Gaining share fastest: Corporate Groups.
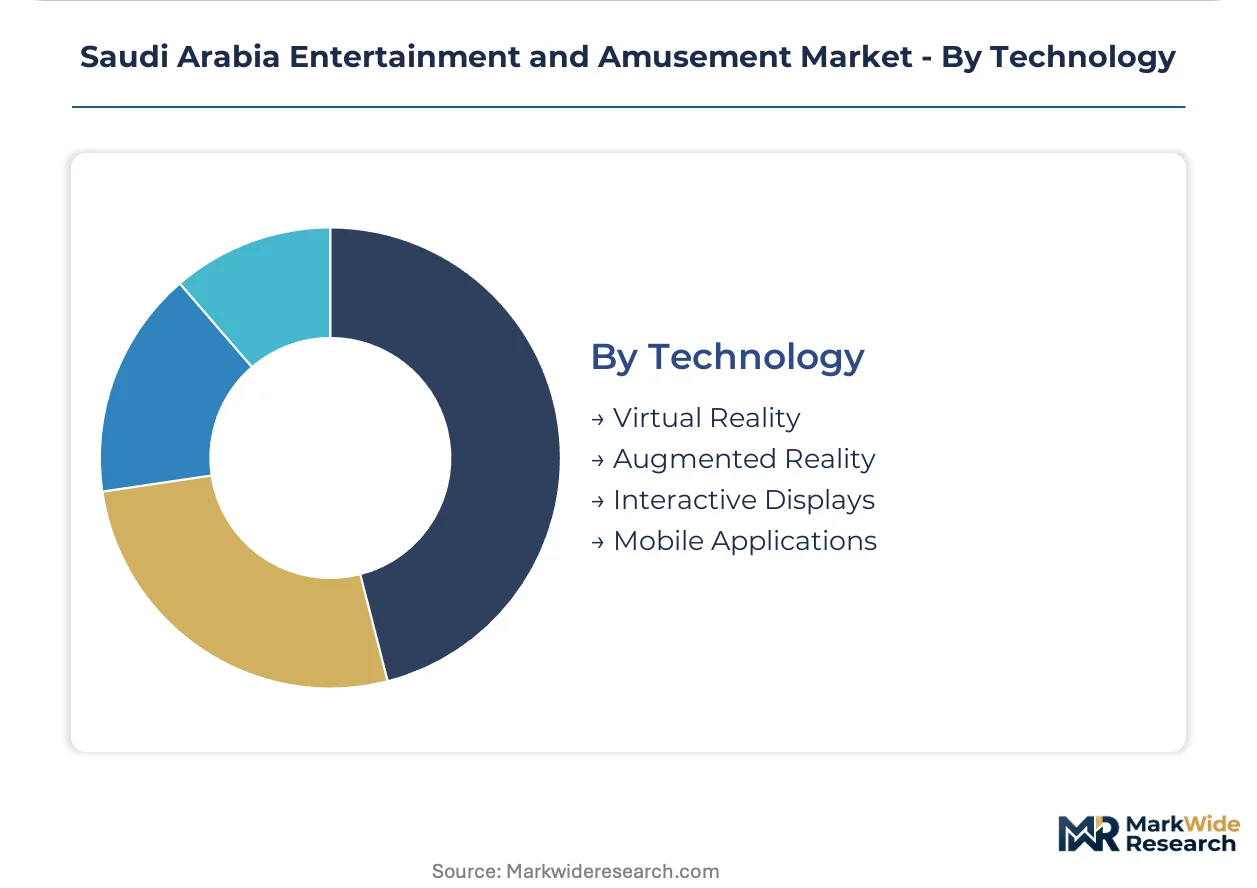
Technology:
Hardware cost curves and content localization maturity determine deployment feasibility across immersive media categories.
- Virtual Reality:Headset-based immersive experiences and motion-platform systems declining in hardware cost, enabling mid-scale operator deployment previously limited to flagship venues. Riyadh and Jeddah operators are deploying these systems at accelerated pace to differentiate against traditional mechanical rides.
- Augmented Reality:Location-based overlays converging with cultural tourism at UNESCO sites and historical districts, creating white space for heritage-anchored experiences with Arabic-language content pipelines.
- Interactive Displays:Touchscreen and gesture-based interfaces for queue management and pre-show entertainment.
- Mobile Applications:Ticketing, wayfinding, and loyalty integration with venue operational systems.
Widest installed base: Virtual Reality. Climbing the fastest: Augmented Reality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Abdullah Economic City and other special economic zones are channeling foreign direct investment into purpose-built entertainment districts, compressing project timelines and concentrating operator licensing activity.
Riyadh
Corporate headquarters migration and population growth are driving demand for indoor family entertainment centers and integrated dining-retail venues. GEA licensing reforms have reduced venue approval timelines from years to months, accelerating SEVEN's city-center development pipeline and Qiddiya megaproject construction.
Eastern Province
Dammam's industrial base and expatriate population are supporting water park and seasonal outdoor facility investment. Municipal authorities are offering land concessions for multi-asset entertainment districts as the region diversifies beyond oil-dependent economic activity.
Western Region
Jeddah's commercial district and Red Sea Project tourism infrastructure are anchoring immersive media and live performance venue deployment. MOHAP health and safety protocols govern enclosed site occupancy caps, constraining throughput optimization during peak pilgrimage and holiday windows.
Asir Region
Abha's temperate climate and domestic tourism positioning are attracting targeted capital for outdoor adventure and heritage-anchored attractions. The General Entertainment Authority is streamlining permits for operators developing Arabic-language content pipelines at UNESCO-recognized historical sites.
NEOM Northwest
The linear city development is integrating augmented reality and location-based entertainment into its tourism and residential zone planning. Regulatory sandboxes are testing novel venue formats ahead of nationwide GEA framework adoption.
Saudi Arabia Entertainment and Amusement Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across venue development, content production, and technical services layers. The market structure tilts toward asset-heavy operators with government joint-venture relationships, though mid-scale specialists are gaining share through immersive media differentiation. Two strategic archetypes dominate: integrated district developers with megaproject pipelines, and niche operators with youth-oriented experiential programming. Competitive moves concentrate on foreign operator licensing partnerships and in-house content localization capabilities.
Among Saudi-based entertainment developers, Qiddiya Investment Company and SEVEN anchor the integrated district tier, while MDLBEAST Records occupies a position within youth-focused experiential programming. Abdul Mohsen Al Hokair Group exemplifies the multi-decade regional operator archetype with indoor family entertainment center expertise. These entities represent distinct capital deployment strategies: sovereign-linked megaproject development, private equity-backed experiential formats, and generational family-owned operational platforms.
| Leading Market Players |
|---|
| AMC Cinemas KSA |
| MBC Group |
| Qiddiya Investment Company |
| Abdul Mohsen Al Hokair Group |
| Rotana Group |
| SEVEN (Saudi Entertainment Ventures) |
| MDLBEAST Records |
| Al Othaim Leisure & Tourism |
| VOX Cinemas |
| Others |
Value Network & Pricing Analysis
Sovereign-backed entertainment developers and family-owned operational platforms anchor capital deployment across Saudi Arabia's venue construction pipeline, concentrating procurement leverage with European and East Asian OEMs while compressing margin structures for mid-scale operators competing on immersive media differentiation.
Pricing Analysis
Margin tightening in mid-scale indoor entertainment centers reflects hardware cost deflation for VR motion-platform systems as Riyadh and Jeddah operators accelerate deployment. Three-tier pricing structure across flagship, city-center, and secondary-city venue levels separates SEVEN's Qiddiya developments from Abdul Mohsen Al Hokair Group's established FEC network and emerging Abha operators. Pricing pressure stems from import dependency for themed steel fabrication and electromechanical ride systems. Corporate group procurement demonstrates lowest price sensitivity, while individual family ticket purchasers exhibit highest elasticity during off-peak windows.
Supply Chain Analysis
SAMR-influenced electrical safety certifications and GEA emergency response mandates gate supplier qualification, elevating capex thresholds for redundant generator systems and specialized electrical engineering. European and East Asian suppliers dominate heavy mechanical attraction fabrication, with German and Italian OEMs anchoring themed steel production and Chinese and South Korean manufacturers feeding motion-platform hardware. Supply chain risk concentrates in single-source vulnerability for electromechanical safety certification components. Distribution runs through sovereign-linked megaproject procurement channels and direct vendor relationships with established domestic operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled technician scarcity for complex ride system maintenance props venue operating costs, constraining supply expansion and sustaining pricing power for certified service providers across the analysis window.
For Market Incumbents: Lock in expatriate specialist employment contracts and accelerate domestic training pipeline partnerships with GEA-licensed technical institutes. Threat from immersive media entrants with lower fixed-asset intensity demands backward integration into content localization capabilities. Priority lever rests on exclusive supplier agreements with European OEMs for ride system spare parts. For New Entrants and Emerging Players: Enter via women-targeted entertainment complexes in secondary cities, where GEA licensing pathways remain underdeveloped and municipal land concessions reduce entry capex. Most penetrable segment is female-staffed FEC formats in Dammam and Abha. Go-to-market angle emphasizes Arabic-language character IP and culturally adapted theming pipelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale immersive media specialists with established SAMR certification records in Jeddah's commercial district. Long-term viability hinges on operators' ability to pivot from hardware-dependent models toward recurring-content-revenue formats. Signal to watch is MOHAP protocol relaxation on enclosed venue occupancy caps.| Strategic Initiative | Industry Significance |
|---|---|
| Immersive Media Hardware Deployment | VR motion-platform expansion enables mid-scale operators to differentiate against traditional mechanical rides in Riyadh. |
| Domestic Technician Training Pipeline | GEA-licensed certification programs reduce expatriate dependency and compress maintenance cost structures. |
| Women-Targeted Venue Licensing | Segmented programming hours open white space for female-staffed entertainment complexes under social transformation mandates. |
| Arabic-Language Content Localization | In-house scripting capabilities accelerate GEA approval timelines for theatrical productions and narrative attractions. |
| Corporate Group B2B Procurement | Direct hospitality channel sales bypass retail distribution and concentrate revenue visibility in Riyadh headquarters cluster. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews across venue development executives, GEA licensing officers, MOHAP compliance leads, and electromechanical maintenance specialists. GEA permit databases, SAMR safety certification registries, SEVEN and Qiddiya procurement disclosures, and European OEM export records supplied quantitative foundations. Bottom-up venue capacity modeling and top-down entertainment spending flow analysis cross-validated market sizing.
Granularity-level modeling distinguished theme park, water park, amusement center, and arcade game formats across Riyadh, Jeddah, Dammam, and Abha metro clusters. Technology segmentation captured VR, AR, interactive display, and mobile application deployment intensity. Customer type splits incorporated family, tourist, local resident, and corporate group spending patterns. CAGRs derived from regression against population migration, corporate headquarters expansion, and GEA licensing velocity. Forecast inputs included Qiddiya construction timelines and secondary city land concession pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MOHAP protocol stringency shifts or currency volatility in European OEM contracts. Model refresh is warranted upon material change in GEA content classification frameworks or SAMR electrical safety certification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Game Applications Market
Gaming
North America Gaming Hardware and Accessories Market
Gaming
China Gaming Headsets Market
Gaming
Mobile Game Controller Market
Gaming
GCC Gaming Headsets Market
Gaming
VR Gaming Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
Mobile Game Software Market
Gaming
United States Gaming Market
Gaming
Gaming Simulation Market
Gaming
VR Melee Games Market
Gaming
Europe Serious Gaming Market
Gaming
Galgames Market
Gaming
LAMEA in-Game Advertising Market
Gaming
Global Subscription-Based Gaming Market
Gaming
Africa Gaming Market