
 Australia Gaming Gadgets Market | 2026-2036
Australia Gaming Gadgets Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Gaming Gadgets Market Insights
Buyer concentration across Australia's gaming population is realigning as casual gamers fragment into specialized sub-communities while professional and streaming segments consolidate purchasing power. Dell Australia Pty Limited leverages its Alienware brand strength in high-performance gaming laptops to anchor premium positioning in Melbourne and Sydney. Razer Inc. competes through peripheral specialization, sustaining channel control across specialty electronics retailers nationwide. Corsair Gaming, Inc. differentiates via component ecosystems that extend from memory modules to complete system builds.
Gaming gadgets encompass dedicated electronic hardware engineered for interactive entertainment, including input devices with sub-1ms polling rates, thermal-dissipation systems maintaining sub-85°C junction temperatures, and display panels achieving sub-5ms grey-to-grey response times. These specifications serve competitive advantage where millisecond latency differentiates performance outcomes. Gaming laptops and VR headsets capture margin concentration as professional gamers and streamers prioritize immersive fidelity, while cloud gaming infrastructure shifts hardware demand toward thin-client peripherals. Wireless connectivity adoption accelerates as low-latency protocols displace tethered configurations among eSports teams.
ACMA enforces radiofrequency emission standards under the Radiocommunications Act, compelling manufacturers to certify wireless gaming peripherals before market entry. EESS registration through state electrical safety offices mandates compliance testing for mains-powered devices. TGA oversight intersects where VR headsets incorporate biometric monitoring capabilities. Stakeholders must monitor evolving electromagnetic compatibility thresholds and streaming platform partnership requirements that reshape hardware specification priorities.
Market Dynamics
Professional eSports infrastructure investment across New South Wales and Victoria is compressing hardware replacement cycles, forcing manufacturers to align product roadmaps with tournament schedules and streaming platform technical specifications rather than traditional consumer upgrade patterns.
Growth Catalysts
- ACMA radiofrequency certification:Standardized wireless protocol approval is accelerating peripheral interoperability across Australian retail channels, reducing vendor-specific ecosystem lock-in for competitive gamers.
- Cloud gaming infrastructure:Edge server deployment by telecommunications providers is shifting hardware demand toward low-latency input devices and thin-display configurations in Melbourne and Sydney metro clusters.
- Thermal management engineering:Sub-85°C junction temperature requirements in high-refresh displays are driving heat-dissipation component upgrades among professional streaming setups.
Market Restraints
- EESS registration timelines:State electrical safety office certification delays for mains-powered gaming laptops create 8-12 week market entry friction for new product launches.
- Semiconductor input concentration:GPU and memory module supply dependence on East Asian foundries exposes Australian distributors to allocation volatility during global capacity constraints.
- TGA biometric oversight:VR headset heart-rate monitoring capabilities trigger medical device classification uncertainty, complicating import documentation for immersive hardware vendors.
Strategic Opportunities
- Queensland regional expansion:Underdeveloped competitive gaming infrastructure in Brisbane and Gold Coast corridors offers first-mover positioning for peripheral brands establishing eSports venue partnerships.
- Indigenous content streaming:Emerging broadcaster requirements for culturally specific gaming content are creating demand for localized capture hardware and audio processing equipment.
- Wireless protocol convergence:Low-latency Bluetooth LE Audio and proprietary 2.4GHz standard unification is enabling single-headset deployment across mobile, console, and PC gaming environments.
Industry Challenges
- Firmware integration complexity:Synchronizing peripheral polling rates with diverse game engine architectures requires specialized embedded systems engineering talent scarce in Australian labor markets.
- Electromagnetic compatibility retesting:TGA threshold adjustments for radiated emissions necessitate costly redesign cycles for wireless mouse and keyboard manufacturers targeting hospital-adjacent gaming rehabilitation programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Gaming Gadgets Market |
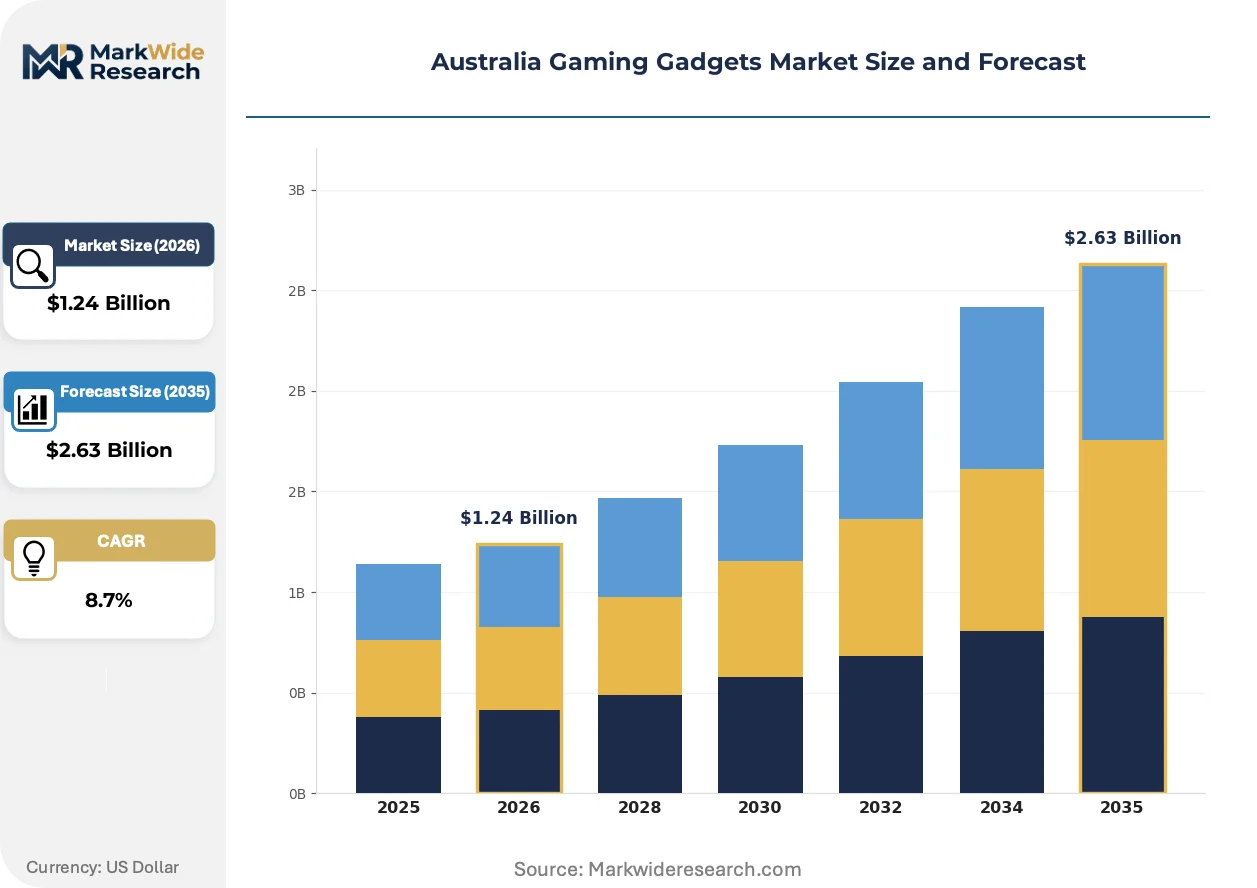
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $2.63 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consoles, Game Controllers, VR Headsets, Gaming Laptops End User: Casual Gamers, Professional Gamers, Streamers, eSports Teams Technology: Cloud Gaming, Augmented Reality, 4K Graphics, Wireless Connectivity Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Electronics Retailers |
| Companies Covered | Dell Australia Pty Limited, Logitech Europe S.A, Voyetra Turtle Beach, Inc., NZXT Australia Pty Ltd, HP PPS Australia Pty Ltd, Razer Inc., Corsair Gaming, Inc., SteelSeries ApS, AsusTek Computer Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Gaming Gadgets Market Trends and Innovations
Hardware specification convergence between professional competitive and broadcast streaming use cases is collapsing previously distinct product categories, forcing manufacturers to engineer multi-purpose devices that satisfy latency-sensitive tournament play and high-fidelity content production simultaneously.
Unified sensor fusion architectures combining optical tracking, inertial measurement, and haptic feedback is unifying input device design across mouse, controller, and VR motion controller form factors. eSports teams in Sydney are adopting these hybrid peripherals at 18-month replacement cycles. This convergence is compressing vendor SKU proliferation into modular platform strategies that reduce inventory carrying costs for specialty retailers.
TGA electromagnetic compatibility standard revisions under the Therapeutic Goods Act are tightening radiated emission thresholds for biometric-enabled VR headsets. Manufacturers must now submit supplementary testing documentation for devices incorporating pupil tracking or galvanic skin response sensors. Rehabilitation gaming programs in Victorian healthcare networks face procurement delays as vendors recertify existing hardware against updated thresholds.
Subscription-based hardware refresh programs are displacing outright purchase models among Melbourne-based professional streamers and eSports organizations. Dell Australia's Alienware division and specialty retailers now offer 24-month device rotation contracts bundling laptops, peripherals, and priority technical support. This shift concentrates buyer power with fewer procurement decision-makers while transferring obsolescence risk to vendors and their financing partners.
Australia Gaming Gadgets Market Segmentation
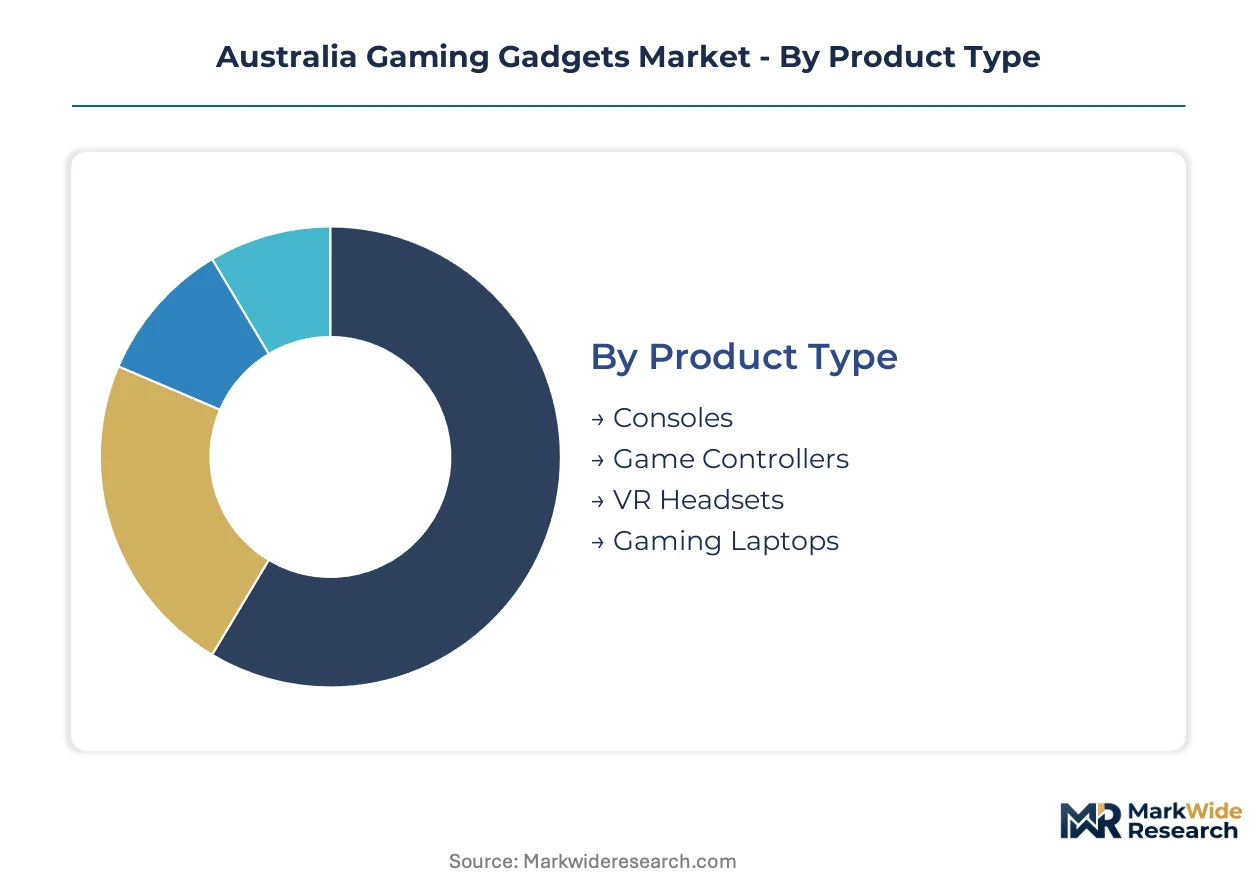
Hardware specification divergence between casual and professional user bases creates distinct procurement patterns across Australia's gaming gadget landscape. Segmentation reveals how thermal performance thresholds, latency tolerances, and content production requirements reshape vendor product roadmaps and channel strategies.
Product Type:
Price-to-performance ratios separate enthusiast buyers from mainstream consumers across Australia's metropolitan gaming clusters.
- Gaming Laptops:Mobile workstations with discrete GPUs and vapor-chamber cooling dominate professional eSports team deployments in Melbourne and Sydney. Dell Australia's Alienware configurations anchor premium positioning where sub-85°C thermal management justifies replacement cycles compressed to 18-24 months.
- VR Headsets:Biometric-enabled immersive displays incorporating pupil tracking and galvanic skin response sensors face TGA electromagnetic compatibility recertification requirements. Victorian healthcare rehabilitation programs drive procurement for hospital-adjacent gaming therapy installations.
- Consoles:Fixed-hardware entertainment systems serve casual household gaming across Australian suburbs with standardized content libraries.
- Game Controllers:Haptic-feedback input devices with unified sensor fusion architectures unify design across PC and console environments.
Volume sits with Gaming Laptops; growth tilts toward VR Headsets.
End User:
Hardware investment intensity correlates directly with monetization capability from gaming activities.
- Professional Gamers:Tournament-competing individuals demand sub-1ms polling rate peripherals and high-refresh displays where millisecond latency differentiates competitive outcomes. New South Wales and Victoria infrastructure investments compress their hardware replacement cycles below consumer norms.
- eSports Teams:Organized competitive organizations in Sydney and Melbourne metropolitan clusters procure through subscription-based refresh programs that bundle laptops, peripherals, and priority technical support into 24-month rotation contracts.
- Streamers:Content producers require simultaneous low-latency gameplay and high-fidelity capture hardware for broadcast output.
- Casual Gamers:Fragmenting sub-communities with intermittent upgrade patterns and price-sensitive procurement behaviors.
Procurement concentrates with eSports Teams; margin expansion favors Professional Gamers.
Technology:
Connectivity architecture choices determine ecosystem lock-in versus interoperability flexibility.
- Wireless Connectivity:Low-latency 2.4GHz proprietary protocols and Bluetooth LE Audio unification enable single-headset deployment across mobile, console, and PC environments. ACMA radiofrequency certification standardization accelerates peripheral interoperability across Australian retail channels.
- 4K Graphics:High-resolution rendering pipelines demand GPU allocation from East Asian foundries, exposing Australian distributors to semiconductor supply volatility during global capacity constraints.
- Cloud Gaming:Edge server deployment by telecommunications providers shifts hardware demand toward thin-client peripherals and low-latency input devices in metro clusters.
- Augmented Reality:Overlay display technologies with nascent gaming application development and uncertain content library scaling.
Adoption runs deepest with Wireless Connectivity; capability investment centers on 4K Graphics.
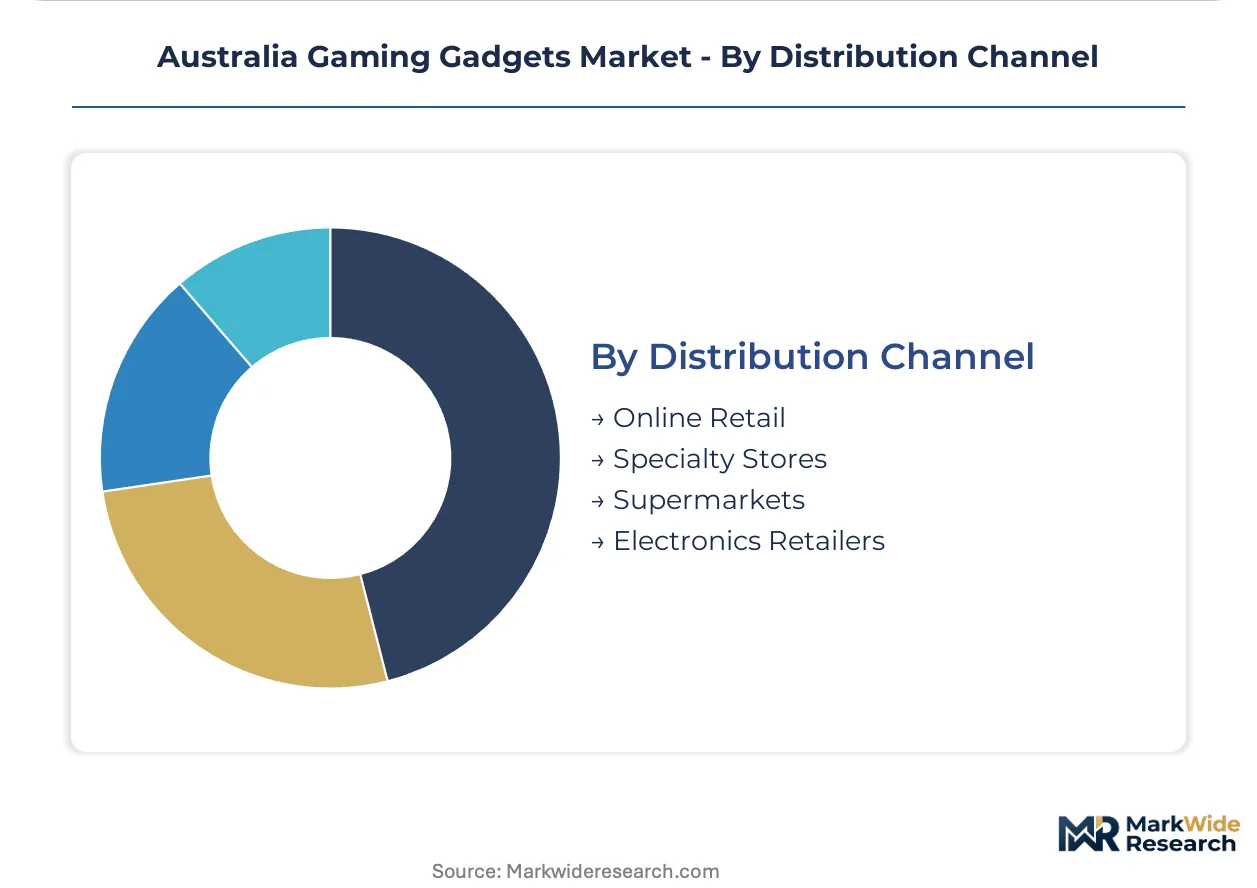
Distribution Channel:
Customer education requirements and technical support intensity shape channel profitability.
- Specialty Stores:Staff-equipped retailers with demonstration capabilities and technical consultation services capture premium peripheral sales. Razer Inc. sustains channel control across this nationwide network through dedicated brand positioning.
- Online Retail:Direct-to-consumer platforms with subscription-based hardware refresh programs displace outright purchase models among Melbourne-based professional streamers and eSports organizations.
- Electronics Retailers:Broad-assortment chains with standardized warranty processing for mainstream gaming laptop volumes.
- Supermarkets:Mass-market outlets with limited SKU depth targeting casual gamer impulse purchases.
Transaction volume flows through Online Retail; margin protection rests with Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication capacity in East Asian foundries anchors hardware supply chains serving Australian gaming gadget demand. New South Wales and Victoria metropolitan clusters concentrate procurement power among professional eSports organizations and streaming content producers. State-level electrical safety registrations and federal radiofrequency certifications shape distribution logistics across Australian territories.
New South Wales
Sydney anchors Australia's largest eSports venue infrastructure with dedicated tournament facilities compressing peripheral replacement cycles below 18 months. ACMA radiofrequency certification requirements for wireless gaming headsets add 6-8 week pre-market approval timelines for importers. The Parramatta-Rhodes corridor hosts specialty retailer concentration where Alienware and Razer maintain flagship demonstration spaces.
Victoria
Melbourne's streaming content producer density drives demand for simultaneous low-latency gameplay and broadcast capture hardware. TGA electromagnetic compatibility oversight intersects with VR headset procurement for hospital-adjacent rehabilitation gaming programs in Victorian healthcare networks. The Docklands-Southbank precinct concentrates subscription-based hardware refresh contract negotiations among professional eSports teams.
Queensland
Brisbane and Gold Coast corridors present underdeveloped competitive gaming infrastructure with first-mover positioning available for peripheral brands establishing venue partnerships. EESS registration through state electrical safety offices creates identical certification friction for mains-powered laptops as other Australian states. The Fortitude Valley entertainment district shows emerging demand for cloud-gaming-optimized thin-client peripherals.
Western Australia
Perth's geographic isolation from eastern seaboard distribution hubs elevates freight costs for GPU and memory module imports from East Asian foundries. The state's mining sector wage structures spill over into discretionary gaming hardware purchasing power among casual consumer segments. Fremantle-Canning Vale logistics corridors handle consolidated container shipments before eastern redistribution.
South Australia
Adelaide's smaller metropolitan scale limits dedicated eSports venue investment, channeling professional gamer demand toward online retail procurement. Local electrical safety office processing capacity creates comparable EESS registration timelines without the volume prioritization seen in Sydney and Melbourne. The Tonsley innovation precinct hosts nascent game development studios with indirect peripheral demand through employment concentration.
Australia Gaming Gadgets Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-gaming peripheral specialization and biometric-enabled VR form factors. The vendor base stratifies across three concentration levels: multinational electronics conglomerates with captive gaming divisions, dedicated gaming peripheral specialists with ecosystem lock-in strategies, and component-aggregating system builders. Three archetypes dominate: premium-brand laptop fabricators, peripheral-ecosystem orchestrators, and modular component suppliers. Competitive intensity manifests through subscription-based hardware refresh program expansion and specialty retail channel control contests.
Among multinational electronics conglomerates, Dell Australia Pty Limited and HP PPS Australia Pty Ltd represent the integrated laptop-and-peripheral tier, leveraging enterprise service infrastructure for gaming segment crossover. Razer Inc. and Corsair Gaming, Inc. exemplify dedicated gaming specialists with pronounced ecosystem strategies. These four anchors demonstrate how vendor positioning splits between scale-driven platform breadth and focused peripheral depth.
| Leading Market Players |
|---|
| Dell Australia Pty Limited |
| Logitech Europe S.A |
| Voyetra Turtle Beach, Inc. |
| NZXT Australia Pty Ltd |
| HP PPS Australia Pty Ltd |
| Razer Inc. |
| Corsair Gaming, Inc. |
| SteelSeries ApS |
| AsusTek Computer Inc. |
| Others |
Pricing and Supply Chain Analysis
TGA electromagnetic compatibility standard revisions under the Therapeutic Goods Act gate qualified supply access for biometric-enabled VR headsets and anchor premium-tier pricing power for vendors holding current certifications. ACMA radiofrequency certification requirements simultaneously filter peripheral market entry, concentrating margin capture among incumbents with established compliance infrastructure.
Pricing Analysis
Volume flows through standard-tier gaming laptops and consoles while margin concentrates in premium peripherals and subscription-based hardware refresh programs. Three-tier pricing structure across premium, standard, and economy levels separates Alienware configurations with vapor-chamber cooling from mainstream electronics retailer SKUs. Pricing pressure stems from semiconductor input volatility exposing distributors to GPU allocation constraints during East Asian foundry capacity tightness. Casual gamers in Western Australia mining sector spillover markets exhibit highest price sensitivity, while Melbourne-based eSports teams show lowest sensitivity through bundled procurement contracts.
Supply Chain Analysis
Domestic-content mandates remain minimal in Australian gaming gadget markets, though EESS state-level electrical safety registrations functionally reshape sourcing timelines for mains-powered devices. GPU and memory module supply draws from Taiwan, South Korea, and China, with semiconductor fabrication concentration creating single-source vulnerability during geopolitical trade disruptions. Thermal management components, display panels, and haptic feedback modules constitute critical input dependencies. Distribution runs through Sydney and Melbourne specialty retail flagships for premium peripherals, with online retail platforms capturing volume through direct-to-consumer subscription programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ACMA radiofrequency certification and TGA electromagnetic compliance create a cost-of-compliance barrier-to-entry moat that favors incumbents with dedicated regulatory affairs infrastructure and punishes opportunistic importers.
For Market Incumbents: Deploy subscription-based hardware refresh programs as the primary retention lever against cloud gaming infrastructure shifts that threaten peripheral replacement cycles. Dell Australia's Alienware division and Razer Inc. should deepen channel control across specialty retailers in Queensland's underdeveloped Brisbane-Gold Coast corridors before emerging entrants establish venue partnerships. Firmware integration engineering talent scarcity in Australian labor markets presents a secondary defensive investment priority. For New Entrants and Emerging Players: Specialty eSports venue operators represent the most viable channel partner type for bypassing incumbent retail lock-in. Queensland regional expansion offers white-space positioning with first-mover advantage in peripheral-venue partnerships, while Indigenous content streaming requirements create demand for localized capture hardware with limited incumbent supply. Direct-to-eSports-team subscription pitches with 24-month rotation terms provide the strongest go-to-market angle against established distributor relationships. For Investors and Strategic Acquirers: TGA electromagnetic compatibility recertification announcements for biometric-enabled VR headsets are the leading indicator that regulatory moat depth is expanding and acquisition premiums for compliant assets will widen. Long-term viability favors vendors with diversified input sourcing beyond East Asian semiconductor concentration and established cloud-gaming peripheral portfolios. Acquisition target archetypes include modular component suppliers with thermal management IP and wireless protocol convergence capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| ACMA Certification Pre-Investment | Front-loaded regulatory compliance accelerates market entry timelines for wireless peripherals. |
| Queensland Venue Partnership | First-mover positioning in Brisbane-Gold Coast corridors captures underdeveloped competitive infrastructure. |
| Subscription Program Expansion | 24-month hardware rotation contracts transfer obsolescence risk from Melbourne eSports teams to vendors. |
| Thermal Engineering Talent Acquisition | Embedded systems specialists enable firmware synchronization with diverse game engine architectures. |
| Indigenous Content Hardware Localization | Culturally specific capture equipment addresses emerging broadcaster procurement requirements. |
Research Methodology
Multi-period observation of ACMA certification timelines, TGA electromagnetic threshold adjustments, and eSports venue investment patterns anchored the trend analysis, supplemented by interviews with gaming hardware procurement managers at Sydney and Melbourne eSports organizations, specialty retail category buyers, Dell Australia and Razer Inc. channel directors, and Victorian healthcare rehabilitation program administrators. Secondary validation drew from ACMA radiofrequency device registers, EESS state electrical safety filings, TGA therapeutic goods determinations, and semiconductor trade flow data. Bottom-up SKU-level demand modeling triangulated against top-down metropolitan cluster spending estimates.
Input-output matrix framing connected GPU allocation volatility from East Asian foundries to Australian distributor pricing power, thermal management component demand to vapor-chamber cooling adoption curves, and wireless protocol standardization to peripheral interoperability across the projection horizon. Segmentation dimensions modeled include product type, end-user monetization capability, connectivity architecture, and distribution channel technical support intensity. CAGRs derived from hardware replacement cycle compression rates and subscription program penetration assumptions, with cloud gaming infrastructure deployment and biometric VR recertification timelines as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced TGA electromagnetic threshold revisions, ACMA protocol standardization changes, and geopolitical disruptions to East Asian semiconductor supply. Forecasts reflect documented assumptions about eSports infrastructure investment continuity and streaming platform technical specification stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Mobile and Handheld Gaming Market
Gaming
Global Game Testing Service Market
Gaming
China in-Game Advertising Market
Gaming
Mobile Game Software Market
Gaming
Mobile Gaming Market
Gaming
Slot Machine Market
Gaming
Global Casino and Gaming Market
Gaming
PC Games Market
Gaming
Game API Market
Gaming
Global Tarot Cards Market
Gaming
Virtual Reality (VR) in Gaming Market
Gaming
VR Gaming Controller Market
Gaming
North America Gaming Market
Gaming
Gaming Console Market
Gaming
Global Electronic Table Games (ETG) Market
Gaming
Gaming As a Service Market