
 North America in-Game Advertising Market | 2026-2036
North America in-Game Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
North America in-Game Advertising Market Analytics
Ad inventory allocation within live-service titles is tilting toward programmatic and rewarded formats as publishers seek recurring revenue beyond initial purchases. Unity Technologies leverages its engine dominance to embed advertising infrastructure directly into development workflows. Electronic Arts Inc. sustains brand integration partnerships across its sports and battle royale portfolios. Activision Blizzard, Inc. competes through exclusive sponsorship deals tied to seasonal content drops in flagship franchises.
North America in-game advertising comprises promotional content rendered within interactive entertainment software through banners, video interstitials, sponsored environments, and native brand placements, typically served via SDK integrations or server-side ad insertion with latency targets under 150 milliseconds. Its primary commercial purpose connects advertisers with engaged, captive audiences during leisure intervals when conventional media consumption fragments. Mobile platforms generate the largest volume base due to freemium monetization models, while video ads command premium rates because completion metrics exceed those of static display. Brand integration captures the highest margin pools as custom creative development requires direct publisher collaboration and extended campaign timelines.
The Federal Trade Commission monitors native advertising disclosure requirements across interactive media, while state attorneys general in California and Virginia enforce privacy statutes that restrict behavioral targeting without explicit consent. The Federal Communications Commission maintains oversight of broadband infrastructure that underpins cloud gaming ad delivery. Stakeholders must track how fragmented state privacy legislation complicates cross-border campaign deployment and whether federal preemption emerges as a legislative priority.
Market Dynamics
Programmatic ad insertion infrastructure is compressing latency windows below 150 milliseconds, forcing publishers to rebuild server-side rendering stacks around real-time bidding protocols or surrender inventory control to platform intermediaries.
Growth Catalysts
- Rewarded Video Formats:Freemium mobile titles in the United States now derive majority ad revenue from opt-in video placements that exchange virtual currency for completed views, driving higher engagement metrics than interstitial alternatives.
- COPPA Compliance Frameworks:The Children's Online Privacy Protection Act creates competitive moats for publishers investing in age-gating infrastructure, as advertisers prefer verified brand-safe inventory over unvetted alternatives.
- Cloud Gaming Infrastructure:Microsoft Azure and Amazon Web Services data center expansion across Texas and Virginia reduces stream latency for interactive ad overlays in browser-based titles.
Market Restraints
- Identifier Deprecation:Apple's App Tracking Transparency framework and Google's Privacy Sandbox eliminate deterministic device-level targeting, forcing reliance on contextual signals with lower conversion precision.
- Supply Concentration:Mobile ad mediation layers concentrate through Unity Technologies and ironSource consolidation, extracting 30-50% revenue shares from independent publishers.
- Creative Production Costs:Native brand integrations requiring 3D asset development and physics-engine compatibility carry 4-6 week production timelines versus 48-hour turnaround for standard video.
Strategic Opportunities
- Mexican Mobile Expansion:Smartphone penetration in Mexico City and Guadalajara lags US benchmarks by 40 percentage points, creating first-mover advantage for localized Spanish-language ad networks.
- Audio-First Placements:Voice-activated smart speaker integration with console ecosystems enables screen-off advertising during idle gameplay intervals.
- California Privacy Dividend:The California Privacy Rights Act mandates opt-in consent frameworks that premium publishers leverage to command CPM premiums over non-compliant competitors.
Industry Challenges
- Ad Fraud Detection:Bot farms simulating video completion metrics in Android emulators drain 15-20% of programmatic budgets, requiring server-side verification SDKs with fingerprinting capabilities.
- Cross-Platform Measurement:Fragmented attribution across console, PC, and mobile identifiers prevents unified frequency capping, exposing brands to overexposure liability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America in-Game Advertising Market |
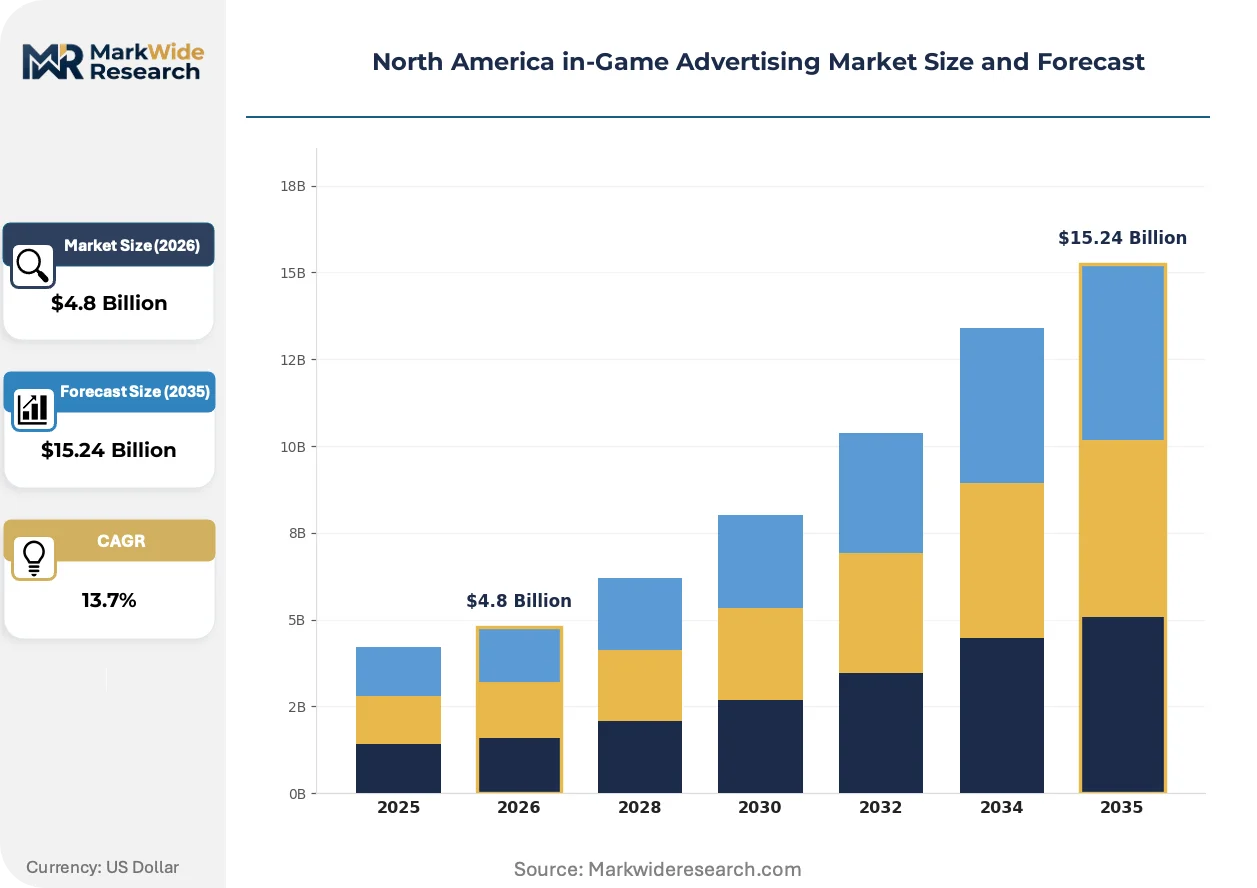
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: PC, Mobile, Console, Cloud Gaming Format: Banner Ads, Video Ads, Sponsored Content, Brand Integration Advertiser Type: Gaming Companies, Consumer Brands, Entertainment, Retail Target Audience: Casual Gamers, Hardcore Gamers, Teenagers, Adults |
| Companies Covered | Unity Technologies, Electronic Arts Inc., Activision Blizzard, Inc., Playwire LLC, AdColony, Chartboost, Inc., Vungle, Frameplay Corporation, AppsFlyer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America in-Game Advertising Market Evolving Landscape
Real-time rendering pipelines are collapsing the distinction between game environment and commercial message, enabling dynamic product placement that responds to player behavior without interrupting flow states.
Programmatic guaranteed deals are digitizing premium inventory allocation for live-service titles, allowing Electronic Arts and Activision Blizzard to pre-sell sponsorship slots in seasonal content calendars while retaining creative veto rights over brand adjacencies.
The FTC's updated endorsement guidelines now explicitly cover influencer-hosted gameplay streams, requiring disclosure overlays for sponsored segments within Twitch and YouTube Gaming broadcasts; sports simulation publishers face highest compliance exposure given athlete influencer dependencies.
Agency trading desks are consolidating media buys through consolidated demand-side platforms, displacing direct publisher relationships that previously dominated console advertising; this concentration is most visible in Los Angeles and New York metropolitan planning organizations where entertainment and media buyers cluster.
North America in-Game Advertising Market Segmentation
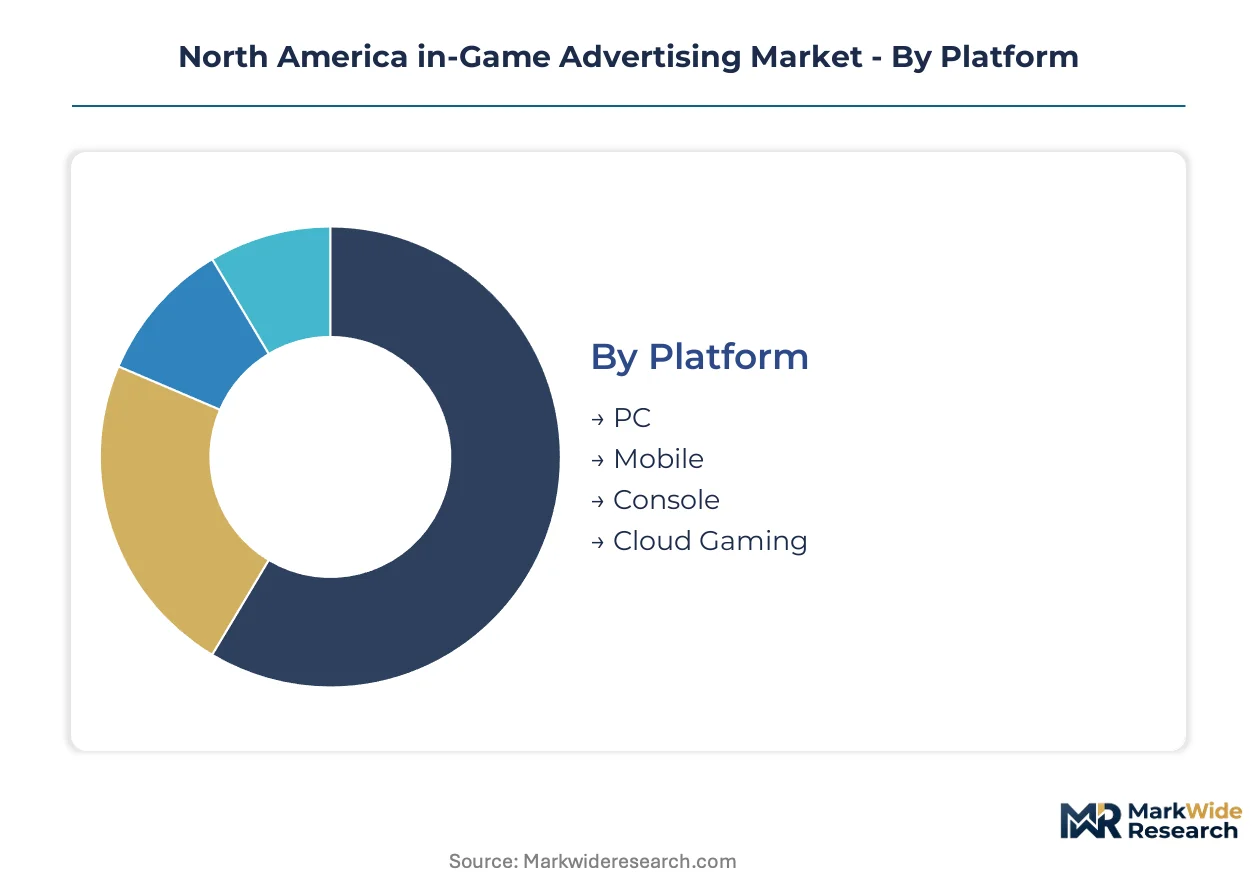
Platform diversity across North American gaming ecosystems fragments inventory valuation, while format complexity demands specialized creative production pipelines. Advertiser type and audience granularity determine campaign architecture, from broad-reach mobile video to precision-targeted console sponsorships.
Platform:
Live-service titles span smartphone handsets, dedicated gaming hardware, personal computing rigs, and browser-based streaming infrastructure, each imposing distinct latency and rendering constraints on ad delivery.
- Mobile:Freemium titles on iOS and Android generate the highest impression volumes through rewarded video and interstitial placements. United States smartphone penetration above 85% concentrates demand in urban coastal corridors, though identifier deprecation under Apple's App Tracking Transparency compresses targeting precision.
- Console:PlayStation and Xbox ecosystems command premium CPMs through immersive sponsored environments and native billboards within sports simulations. Brand safety verification through Entertainment Software Rating Board age-gating attracts automotive and beverage advertisers seeking verified adult demographics.
- PC:Steam and Epic Games Store distribution enables mod-supported ad integrations and overlay technologies, particularly within battle royale and massively multiplayer online titles where session lengths exceed 90 minutes.
- Cloud Gaming:Microsoft Azure and Amazon Web Services infrastructure in Texas and Virginia reduces stream latency below 50 milliseconds, enabling interactive ad overlays without local rendering hardware.
The dominant share belongs to Mobile, while Cloud Gaming is closing the gap fastest.
Format:
Creative production timelines and technical integration depth separate commodity inventory from bespoke partnerships, with margin structures diverging by an order of magnitude.
- Video Ads:Completion rates for rewarded opt-in placements surpass 80% in mobile puzzle and strategy titles. 15-30 second spots require SDK integration with Unity or ironSource mediation layers, compressing publisher margins through revenue share extraction.
- Brand Integration:Custom 3D asset development and physics-engine compatibility demand 4-6 week production cycles, limiting deployment to flagship franchises with predictable seasonal content calendars. Sports simulation publishers command the highest sponsorship premiums through exclusive apparel and equipment placements.
- Banner Ads:Static and rich media units persist in legacy mobile titles and loading-screen real estate, though viewability concerns and banner blindness depress effective CPMs below video alternatives.
- Sponsored Content:Native environmental placements—virtual billboards, branded in-game items, and narrative-integrated storylines—blur advertising and gameplay boundaries, requiring direct publisher-creative agency collaboration.
Video Ads capture the largest revenue pool, while Brand Integration is expanding most quickly.
Advertiser Type:
Budget allocation patterns reflect sector-specific regulatory exposure and audience alignment with gaming demographics.
- Consumer Brands:Automotive, beverage, and personal care verticals prioritize verified adult audiences through console and PC placements, with COPPA compliance frameworks filtering inventory for family-friendly mobile alternatives.
- Gaming Companies:Cross-promotional campaigns for upcoming releases dominate mobile ad networks, leveraging first-party data from existing player bases to drive pre-registration and launch conversion.
- Entertainment:Film studios and streaming services synchronize theatrical and series releases with in-game trailer placements, particularly within open-world titles where narrative immersion aligns with content marketing objectives.
- Retail:E-commerce platforms deploy dynamic product placement responding to real-time inventory availability, enabled by server-side rendering pipelines that collapse distinction between game environment and commercial message.
Consumer Brands hold the dominant position, while Retail is gaining share fastest.
Target Audience:
Age verification infrastructure and gameplay intensity segment addressable inventory across regulatory and engagement spectrums.
- Adults:Verified 18+ demographics command the highest CPM premiums through age-gated console and PC titles, particularly within mature-rated first-person shooters and sports simulations where disposable income correlates with in-game purchase behavior.
- Casual Gamers:Mobile puzzle and hyper-casual titles attract broad-reach campaigns from packaged goods advertisers, with session lengths under 10 minutes favoring interstitial over immersive formats.
- Hardcore Gamers:Daily engagement exceeding 3 hours in live-service titles enables deep brand integration and sponsored competitive events, though audience saturation risks overexposure without cross-platform frequency capping.
- Teenagers:COPPA and state-level privacy statutes restrict behavioral targeting, forcing reliance on contextual signals and content-based placement within age-appropriate titles.
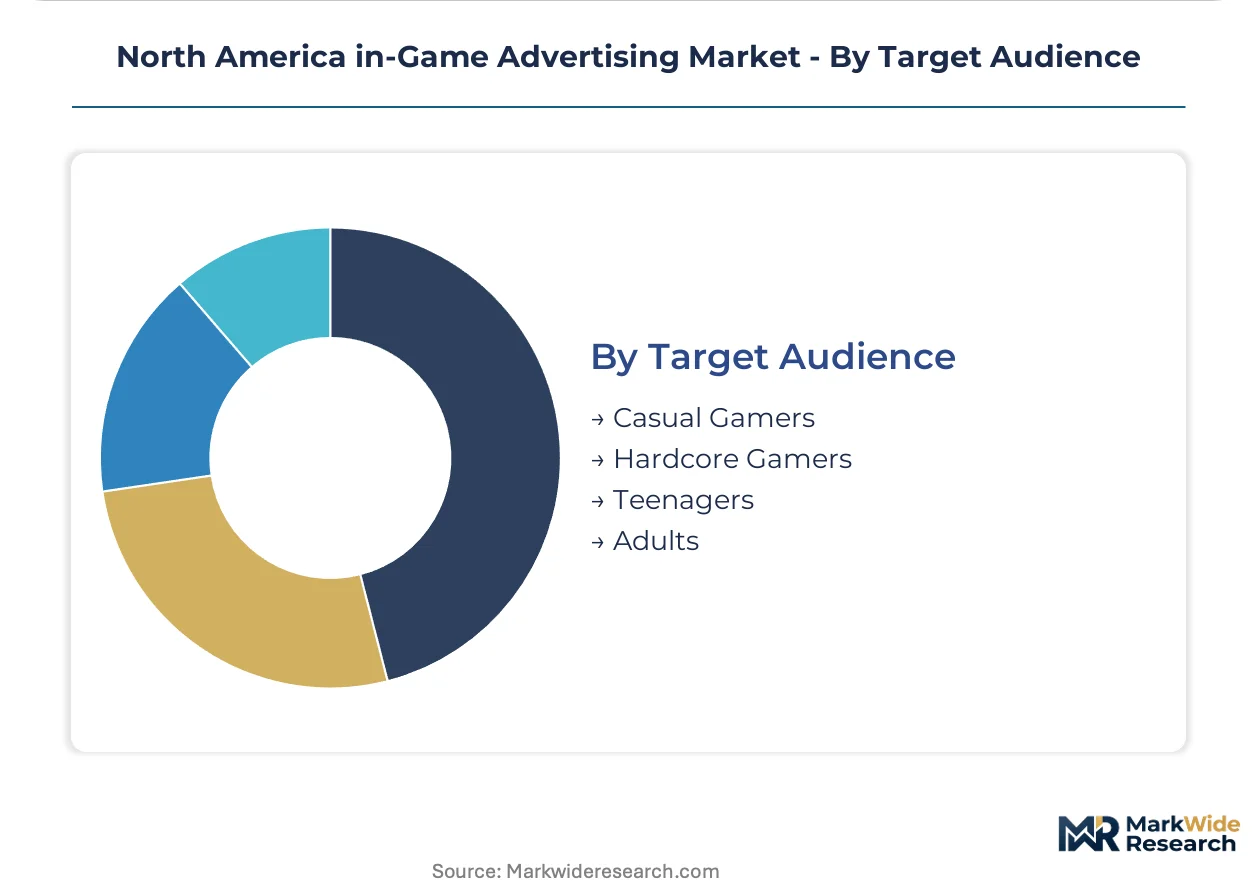
Adults represent the most valuable segment, while Casual Gamers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level privacy statutes across the United States and federal frameworks in Canada and Mexico are reshaping how advertisers deploy player data and allocate inventory spend across North American markets.
United States
Mobile gaming penetration above 85 percent drives impression volume through rewarded video formats in freemium titles. The Federal Trade Commission enforces native advertising disclosure requirements across interactive media, with particular scrutiny on influencer-hosted gameplay streams. Los Angeles and New York metropolitan planning organizations concentrate agency trading desks and entertainment media buyers who consolidate programmatic guaranteed deals for live-service titles.
Canada
Console ecosystem maturity in Ontario and Quebec attracts automotive and beverage advertisers seeking verified adult demographics through age-gated sports simulations. Health Canada maintains oversight of digital advertising standards that align with federal privacy legislation, creating compliance frameworks for cross-border campaign deployment. Toronto and Vancouver anchor development studios producing flagship franchises with predictable seasonal content calendars suitable for brand integration partnerships.
Mexico
Smartphone penetration in Mexico City and Guadalajara lags United States benchmarks by 40 percentage points, creating first-mover positioning for localized Spanish-language ad networks. The country's federal consumer protection agency enforces advertising transparency rules that intersect with emerging data localization requirements. Monterrey and Guadalajara industrial corridors host cloud gaming infrastructure investments from Microsoft Azure and Amazon Web Services that reduce stream latency for interactive ad overlays.
North America in-Game Advertising Market Competitive Landscape
On the supply side, the industry is consolidating around engine-integrated advertising infrastructure and independent mediation layers that extract substantial revenue shares from publishers. Three strategic archetypes dominate: development platform owners embedding SDKs directly into production workflows, specialized ad networks optimizing fill rates across mobile portfolios, and measurement providers verifying attribution across fragmented identifiers. Dominant competitive moves include vertical integration of rendering technology with programmatic stacks and exclusive sponsorship pre-sales tied to seasonal content calendars.
Within the engine-platform tier, Unity Technologies exemplifies supply-side consolidation through embedded advertising infrastructure, while Electronic Arts Inc. and Activision Blizzard, Inc. occupy positions as premium publishers leveraging direct brand integration partnerships across sports and battle royale portfolios.
| Leading Market Players |
|---|
| Unity Technologies |
| Electronic Arts Inc. |
| Activision Blizzard, Inc. |
| Playwire LLC |
| AdColony |
| Chartboost, Inc. |
| Vungle |
| Frameplay Corporation |
| AppsFlyer Inc. |
| Others |
Value Network & Pricing Analysis
Ad mediation layer consolidation through Unity Technologies and ironSource extracts 30-50% revenue shares from independent publishers, concentrating margin pools with platform intermediaries rather than content creators. This upstream concentration forces publishers toward programmatic guaranteed deals or exclusive sponsorship pre-sales to retain pricing power.
Pricing Analysis
Three-tier pricing structure across premium brand integrations, standard video placements, and economy banner inventory governs North American in-game advertising. Premium tiers command 4-6 week production timelines for custom 3D assets, while economy banners suffer viewability concerns and depressed CPMs. Price differentiation rests on creative complexity and age-verification infrastructure, with COPPA-compliant inventory earning premiums. Cost compression in standard video tiers is intensifying because identifier deprecation under Apple's App Tracking Transparency eliminates deterministic targeting precision. Casual mobile publishers exhibit highest price sensitivity, while console sports simulation franchises demonstrate lowest sensitivity due to exclusive sponsorship scarcity.
Supply Chain Analysis
Upstream feedstock for ad-serving infrastructure draws from cloud computing capacity concentrated in United States data centers across Texas and Virginia, plus rendering engine technology anchored in Denmark and San Francisco. Raw material dependencies include server-side rendering stacks, real-time bidding protocols, and SDK mediation layers. Supply chain risk centers on single-source vulnerability within Unity Technologies' engine-platform dominance, which embeds advertising infrastructure directly into development workflows. Distribution runs through programmatic demand-side platforms consolidating media buys in Los Angeles and New York metropolitan planning organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American in-game advertising represents a service-attach opportunity where recurring revenue from ad mediation and measurement layers expands faster than one-time creative production. Programmatic infrastructure and first-party data services now outpace growth in standard video inventory.
For Market Incumbents: Pre-empt platform disintermediation by building direct advertiser relationships outside programmatic layers. Publishers should invest in age-gating infrastructure to capture COPPA-compliant inventory premiums before regulatory fragmentation accelerates. Threat of supply concentration through Unity-ironSource consolidation demands exclusive sponsorship pre-sales and seasonal content calendar control as defensive levers.
For New Entrants and Emerging Players: Mexican smartphone penetration lagging United States benchmarks by 40 percentage points offers first-mover positioning for localized Spanish-language ad networks. Guadalajara and Mexico City present the most penetrable geography, with cloud gaming infrastructure investments from Microsoft Azure and Amazon Web Services reducing latency barriers. Go-to-market angle should emphasize contextual targeting solutions that bypass identifier deprecation limitations.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ad mediation layers seeking exit liquidity before platform consolidation completes. Long-term viability across the next decade hinges on measurement providers verifying attribution across fragmented console, PC, and mobile identifiers. Signal to watch is federal preemption of state privacy legislation as inflection indicator for cross-border campaign deployment economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Programmatic Infrastructure Investment | Real-time bidding protocols under 150-millisecond latency targets compress publisher margins but secure inventory control. |
| Age-Gating Compliance Certification | COPPA frameworks create competitive moats as advertisers prefer verified brand-safe inventory over unvetted alternatives. |
| Cloud Gaming Ad Overlay Development | Microsoft Azure and Amazon Web Services infrastructure enables interactive advertising without local rendering hardware. |
| Direct Publisher-Advertiser Partnerships | Exclusive sponsorship pre-sales tied to seasonal content calendars bypass platform intermediary revenue extraction. |
| Cross-Platform Measurement Integration | Unified frequency capping across console, PC, and mobile identifiers reduces brand overexposure liability exposure. |
Research Methodology
A standing panel of mobile game publishers, console platform executives, programmatic traders at agency trading desks, and measurement technology engineers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from SEC filings, App Annie mobile intelligence data, hyperscaler capex disclosures, and FTC enforcement action records. Bottom-up triangulation across platform-specific impression volumes and top-down reconciliation against advertiser budget allocation surveys anchored value estimates.
Scenario-bracketing around identifier deprecation timelines, federal privacy preemption probabilities, and cloud gaming adoption curves bounded projection uncertainty. Segmentation dimensions modeled include platform type, format complexity, advertiser vertical, and audience verification tier across the analysis window. CAGRs derived from regression analysis against historical mobile gaming penetration curves and console hardware lifecycle patterns, with inputs from server-side rendering pipeline deployment rates and programmatic guaranteed deal digitization trends.
Practitioners should monitor state attorney general enforcement patterns and App Tracking Transparency opt-in rate trajectories for early signals of forecast revision. Assumptions underlying projections reflect current regulatory frameworks and technology deployment schedules. Quarterly review of latency benchmark improvements and bot farm detection efficacy is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
VR Gaming Market
Gaming
Mobile and Handheld Gaming Market
Gaming
Arcade Games Market
Gaming
India Gaming Market
Gaming
Arcade Cabinet Market
Gaming
Video Game Software Market
Gaming
Gaming Simulation Market
Gaming
Puzzle Video Game Market
Gaming
Gaming Software Market
Gaming
Global Online Simulation Games Market
Gaming
Gaming As a Service Market
Gaming
Serious Games Market
Gaming
Mobile Shooter Market
Gaming
FPS Game Market
Gaming
Online Strategy Games Market
Gaming
Gaming Simulator Market